
 Artificial Intelligence for IT Operations (Aiops) Market | 2026-2036
Artificial Intelligence for IT Operations (Aiops) Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence for IT Operations (Aiops) Market Outlook
Enterprise buyer concentration is restructuring as Fortune 500 technology departments consolidate vendor relationships around full-stack observability platforms. IBM leverages its Watson AIOps suite to anchor hybrid cloud deployments across regulated industries. Broadcom differentiates through embedded telemetry within its semiconductor-to-software stack. Datadog sustains developer-centric growth by occupying the application performance monitoring layer with native machine learning capabilities.
Artificial Intelligence for IT Operations constitutes an algorithmic systems management discipline that ingests multi-source telemetry, applies machine learning correlation across distributed infrastructure, and automates incident response workflows to maintain service-level objectives. The technology processes log streams, metrics, and traces through neural architectures that detect anomaly patterns below human perceptual thresholds. Cloud deployment configurations now lead solution type demand as enterprises migrate from static on-premises toolchains, while security analytics represents the fastest-expanding solution category due to converged SecOps requirements. Machine learning remains the dominant technology foundation, though predictive analytics is gaining share as organizations prioritize proactive capacity planning over reactive alerting.
FCC guidelines on communications infrastructure reliability intersect with NIST cybersecurity frameworks to shape AIOps procurement specifications for US federal contractors. The EU AI Act's risk classification system is forcing platform vendors to document automated decision logic within IT operations workflows. HIPAA audit requirements for healthcare IT systems are accelerating demand for explainable anomaly detection. Stakeholders must evaluate how emerging algorithmic accountability standards will reshape vendor certification requirements and customer due diligence processes.
Market Dynamics
The convergence of EU AI Act compliance mandates with cloud-native observability requirements is compressing vendor consolidation timelines. Federal IT modernization programs in the United States are rewiring procurement specifications toward explainable automation platforms.
Growth Catalysts
- EU AI Act risk classification:Mandatory documentation of automated decision logic in IT operations workflows is accelerating platform upgrades across European financial services and healthcare sectors.
- Real-time fraud detection:Financial institutions deploy neural architectures for anomaly detection below human perceptual thresholds, embedding AIOps into payment infrastructure resilience.
- FCC infrastructure reliability guidelines:Intersection with NIST cybersecurity frameworks shapes procurement specifications for US federal contractors, mandating algorithmic accountability in communications systems.
Market Restraints
- Specialized talent scarcity:Shortage of ML-operations engineers capable of tuning neural architectures for distributed infrastructure telemetry limits deployment velocity.
- Legacy toolchain entrenchment:Static on-premises monitoring investments create technical debt friction during cloud migration, particularly in regulated industries with HIPAA audit requirements.
- Input cost concentration:GPU compute for training anomaly detection models concentrates procurement leverage with hyperscaler cloud providers, compressing margin structures.
Strategic Opportunities
- SecOps convergence:Security analytics represents the fastest-expanding solution category as organizations merge IT operations with threat detection workflows.
- Explainable anomaly detection:HIPAA audit requirements for healthcare IT systems create demand for interpretable ML models that document decision pathways.
- Predictive capacity planning:Organizations prioritize proactive infrastructure scaling over reactive alerting, expanding predictive analytics adoption beyond traditional machine learning foundations.
Industry Challenges
- Integration complexity:Multi-source telemetry ingestion across hybrid cloud environments requires reconfiguration of existing observability pipelines.
- Certification timeline compression:EU AI Act documentation requirements and NIST framework alignment demand accelerated vendor certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence for IT Operations (Aiops) Market |
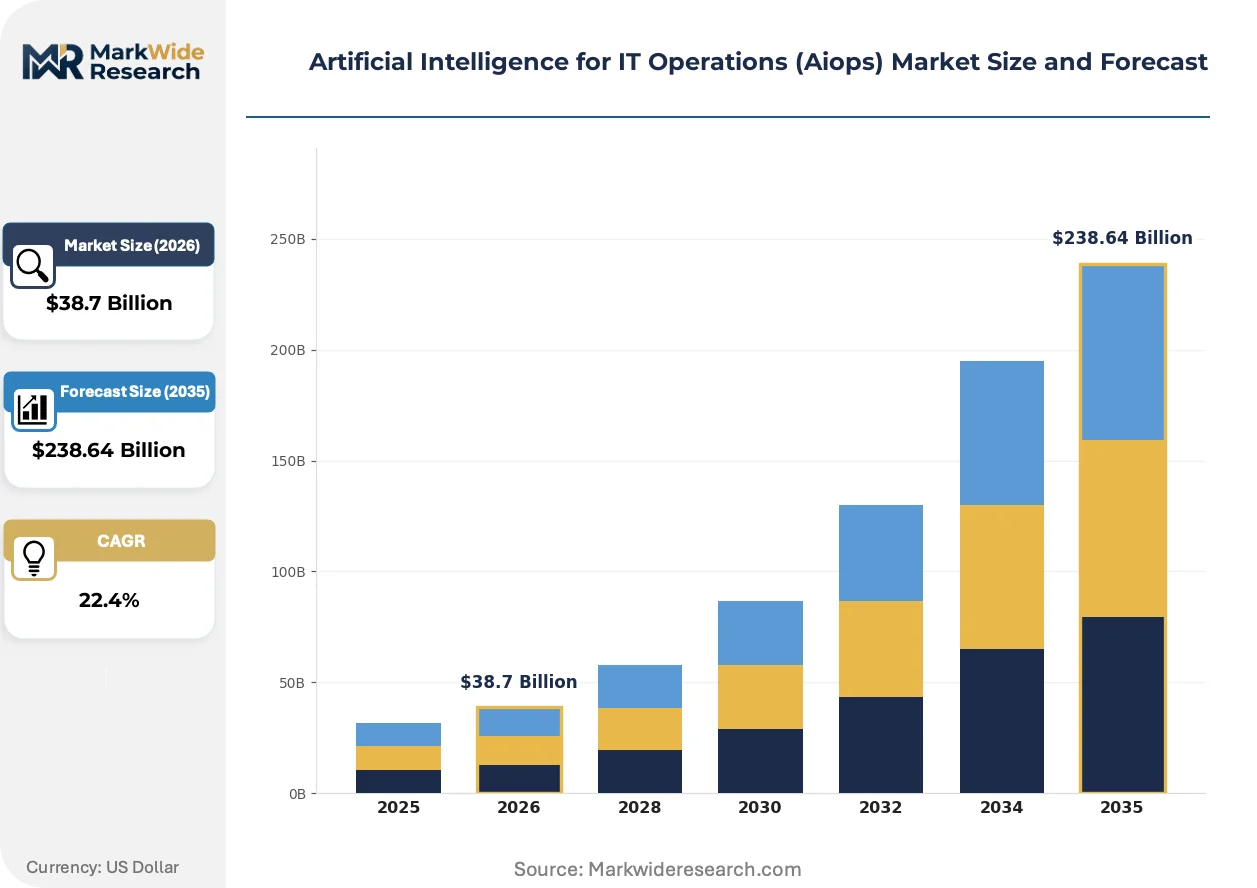
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $238.64 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premises, Hybrid, Multi-Cloud Solution Type: Network Management, Performance Monitoring, Incident Management, Security Analytics End User: IT Service Providers, Enterprises, Managed Service Providers, Telecom Operators Technology: Machine Learning, Natural Language Processing, Automation Tools, Predictive Analytics |
| Companies Covered | IBM, Broadcom, OpenText, Dynatrace, ServiceNow, Splunk, BigPanda, Aisera, Datadog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence for IT Operations (Aiops) Market Strategic Shifts
Observability platforms are absorbing adjacent functionality as buyers consolidate vendor relationships. Algorithmic accountability standards are rewriting technical specifications across regulated industries.
Neural architectures for log correlation and metric analysis are unifying previously siloed monitoring domains. DevOps teams in financial services and telecommunications deploy these systems at accelerated cadences. The technology is unifying application performance monitoring with infrastructure health assessment, collapsing procurement decisions into full-stack platform selections.
The EU AI Act's risk classification system mandates documented audit trails for automated IT operations decisions. Platform vendors must retrofit explainability layers into existing ML pipelines. Healthcare and financial services verticals in Europe face the steepest compliance curves, forcing architectural redesigns before 2025 enforcement deadlines.
Enterprise technology departments now consolidate vendor relationships around integrated observability suites rather than point solutions. Traditional application performance monitoring contracts face compression as buyers demand embedded machine learning capabilities. United States federal contractors exhibit this pattern most acutely, where IT modernization programs bundle AIOps into broader infrastructure awards.
Artificial Intelligence for IT Operations (Aiops) Market Segmentation
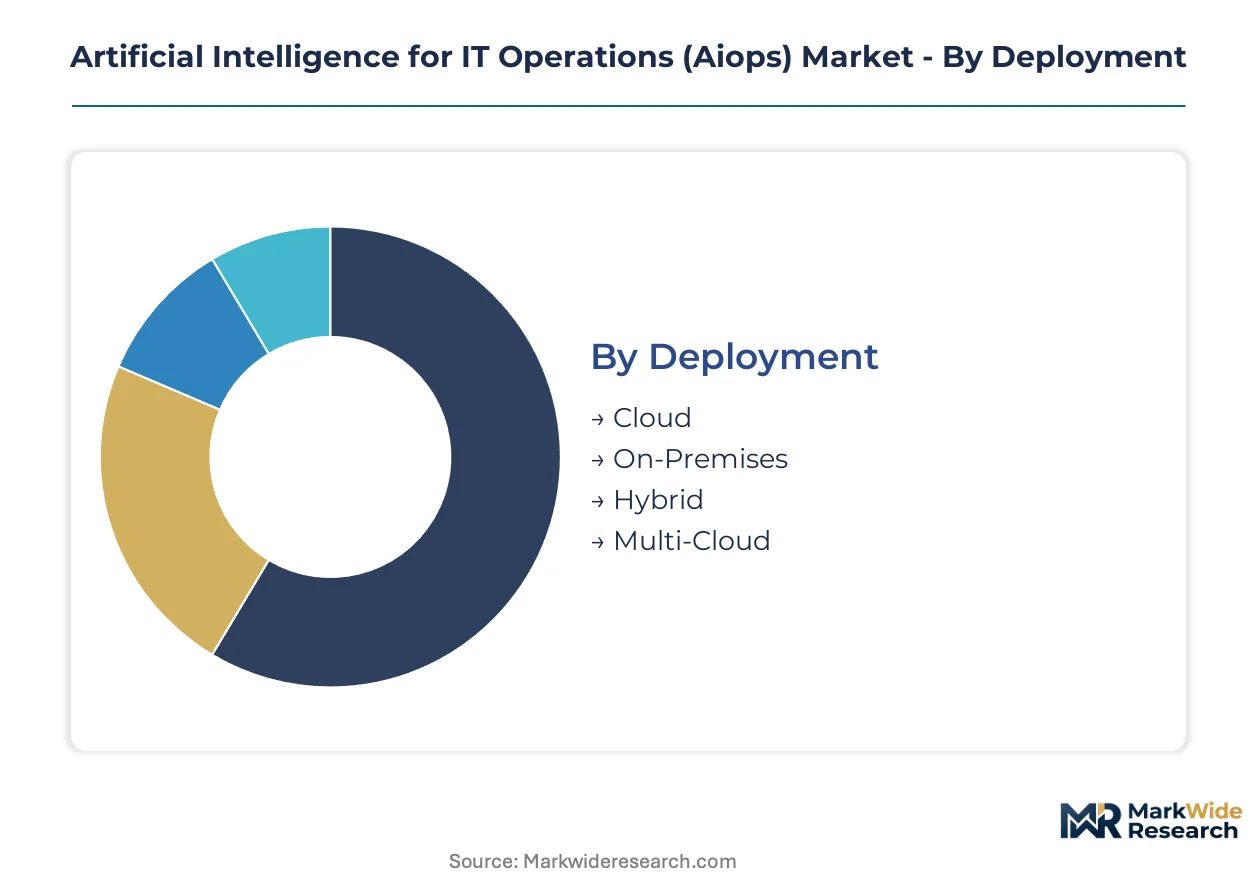
Segmentation in AIOps reflects divergent infrastructure maturity levels across buyer organizations. Procurement patterns split sharply between cloud-native adopters seeking elastic observability and regulated entities preserving on-premises control for compliance.
Deployment:
Deployment architecture determines data sovereignty posture and integration complexity for telemetry pipelines.
- Cloud:Elastic compute resources enable real-time neural processing of distributed log streams without capital infrastructure commitment. Demand concentrates among fintech startups in Singapore and digital-native enterprises migrating from static monitoring toolchains, driven by hyperscaler partnership incentives and consumption-based pricing models.
- On-Premises:Air-gapped infrastructure preserves telemetry within organizational boundaries, satisfying HIPAA audit requirements and classified federal workloads. German automotive manufacturers and US defense contractors anchor this segment, constrained by GPU procurement bottlenecks and specialized ML-operations talent scarcity.
- Hybrid:Split telemetry processing keeps sensitive anomaly detection on-premises while pushing non-critical metrics to cloud aggregation layers.
- Multi-Cloud:Abstraction layers normalize telemetry across AWS, Azure, and GCP environments to prevent vendor lock-in.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud.
Solution Type:
Functional modules align with operational workflows from infrastructure health through threat response.
- Security Analytics:Converged SecOps platforms embed anomaly detection within threat detection workflows, unifying SIEM telemetry with infrastructure metrics. European financial services under EU AI Act documentation mandates and US federal contractors meeting NIST framework specifications drive steepest expansion trajectory.
- Performance Monitoring:Application-layer telemetry ingestion with embedded machine learning capabilities collapses previously siloed domain monitoring. Developer-centric technology departments in telecommunications and e-commerce prioritize this layer for service-level objective maintenance.
- Network Management:Topology-aware correlation of flow data with infrastructure health metrics.
- Incident Management:Automated runbook execution and root-cause analysis workflows.
Procurement concentration favors Performance Monitoring. Security Analytics exhibits the steepest expansion trajectory.
End User:
Organizational buyer type shapes platform complexity requirements and integration depth.
- Enterprises:Fortune 500 technology departments consolidate vendor relationships around full-stack observability suites with explainable automation layers. US federal IT modernization programs and EU AI Act compliance deadlines compress procurement timelines for hybrid cloud deployments.
- Managed Service Providers:Multi-tenant architectures demand scalable telemetry ingestion with customer-isolated ML model training. MSPs serving mid-market healthcare verticals face HIPAA audit requirements for interpretable anomaly detection pathways.
- IT Service Providers:Project-based deployment models with standardized toolchains.
- Telecom Operators:FCC infrastructure reliability guidelines mandate algorithmic accountability in communications systems.
Revenue concentration rests with Enterprises. MSPs are gaining share fastest through vertical specialization.
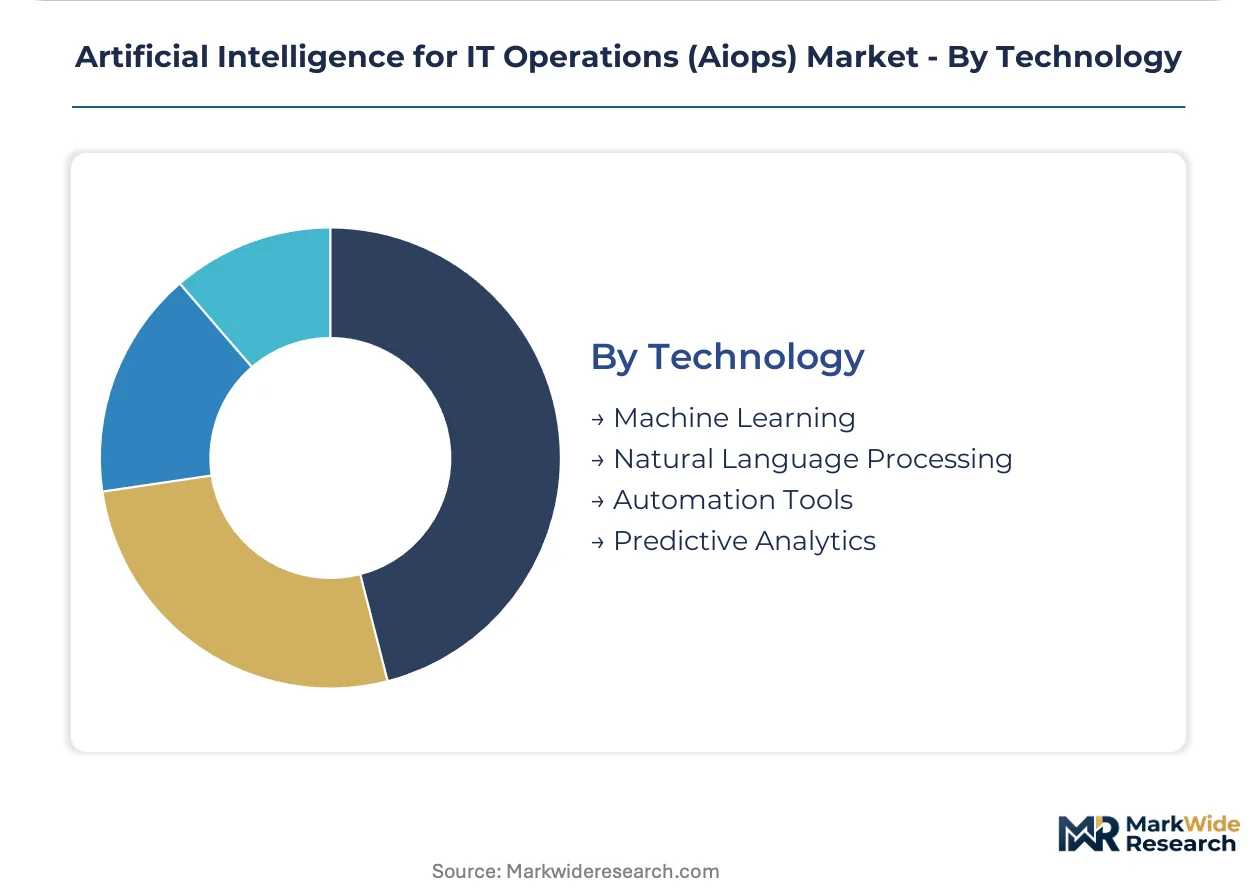
Technology:
Algorithmic foundation determines detection latency, interpretability, and training data requirements.
- Machine Learning:Neural architectures for log correlation and metric analysis constitute the dominant technology foundation, processing multi-source telemetry below human perceptual thresholds. Financial services fraud detection and telecommunications infrastructure monitoring anchor primary demand.
- Predictive Analytics:Time-series forecasting for capacity planning shifts operational focus from reactive alerting to proactive infrastructure scaling. Organizations with mature observability pipelines in manufacturing and cloud services prioritize this capability.
- Natural Language Processing:Unstructured log parsing and incident narrative analysis.
- Automation Tools:Runbook execution and remediation workflow orchestration.
Technology maturity clusters around Machine Learning. Predictive Analytics is climbing the fastest as organizations prioritize proactive capacity planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GPU fabrication clusters in Taiwan and South Korea supply the neural processing hardware anchoring AIOps deployment density across major economies.
United States
Hyperscaler cloud partnerships and federal IT modernization programs compress procurement timelines for explainable automation platforms. FCC infrastructure reliability guidelines intersect with NIST cybersecurity frameworks to mandate algorithmic accountability in communications systems procurement. Silicon Valley and Seattle technology corridors concentrate vendor headquarters and enterprise pilot deployments.
Germany
Automotive manufacturers and industrial conglomerates demand air-gapped anomaly detection for classified production telemetry. EU AI Act risk classification mandates documentation of automated decision logic within IT operations workflows. Bavarian automotive clusters and Baden-Württemberg industrial zones anchor on-premises deployment concentration.
Singapore
Fintech startups and digital-native enterprises migrate from static monitoring toolchains to elastic observability architectures. Monetary Authority of Singapore operational resilience guidelines shape procurement specifications for financial infrastructure. The city-state's data center hub status attracts hyperscaler partnership investments for regional AIOps service delivery.
United Kingdom
Financial services regulators emphasize operational resilience mandates for payment infrastructure anomaly detection. Bank of England and Financial Conduct Authority frameworks intersect with emerging EU AI Act documentation requirements post-Brexit adjustment. London's concentrated banking sector drives demand for real-time fraud detection neural architectures.
India
IT service providers and managed service operators scale multi-tenant telemetry ingestion for mid-market healthcare verticals. Reserve Bank of India cybersecurity guidelines and data localization requirements shape hybrid deployment architectures. Bengaluru and Hyderabad technology corridors concentrate ML-operations engineering talent for platform implementation.
Artificial Intelligence for IT Operations (Aiops) Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue vertical specialization and cloud-native observability adjacencies. The vendor structure concentrates around full-stack platform providers with embedded machine learning capabilities, while point-solution specialists face contract compression. Three archetypes dominate: hyperscaler-integrated suites, semiconductor-to-software stacks, and developer-centric monitoring layers. Consolidation momentum favors strategic partnerships over standalone expansion, with certification acceleration and explainability retrofitting as dominant competitive moves.
Within the full-stack observability tier, IBM, Broadcom, and Datadog exemplify divergent anchoring strategies. IBM leverages its Watson AIOps suite to anchor hybrid cloud deployments across regulated industries. Broadcom occupies a position within semiconductor-to-software integration, embedding telemetry capabilities across hardware layers. Datadog represents the developer-centric monitoring archetype, sustaining growth through application performance management with native machine learning capabilities.
| Leading Market Players |
|---|
| IBM |
| Broadcom |
| OpenText |
| Dynatrace |
| ServiceNow |
| Splunk |
| BigPanda |
| Aisera |
| Datadog |
| Others |
Value Chain & Pricing Dynamics
Neural processing hardware commoditization simultaneously compresses training cost curves and concentrates procurement leverage among hyperscaler cloud providers. GPU-as-a-service consumption models reshape vendor margin structures while telemetry pipeline complexity drives premium pricing for integrated observability suites.
Pricing Analysis
Warranty and service-bundling differentiation separates full-stack platform providers from point-solution vendors, with embedded ML-operations support commanding substantial premiums over unbundled licensing. Three-tier pricing structure across premium, standard, and economy levels stratifies by explainability certification depth and SLA guarantees. Cost compression in mid-market tiers intensifies because hyperscaler marketplace listings commoditize baseline anomaly detection. Fortune 500 enterprises exhibit lowest price sensitivity due to EU AI Act compliance penalties, while mid-market healthcare verticals face acute budget constraints for HIPAA-auditable deployments.
Supply Chain Analysis
GPU compute supply rests on Taiwanese and South Korean fabrication clusters, with NVIDIA and AMD silicon anchoring neural processing hardware procurement. Telemetry ingestion pipelines draw from open-source streaming platforms, proprietary observability agents, and third-party SIEM connectors. Single-source vulnerability concentrates in advanced node semiconductor supply, where geopolitical export controls threaten training infrastructure availability. Distribution runs through hyperscaler marketplaces, direct enterprise sales forces, and managed service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU AI Act certification timelines and explainability retrofitting costs force weaker point-solution vendors toward strategic exit.
For Market Incumbents: Cement hybrid cloud anchoring through embedded Watson-style explainability layers that preempt regulatory audit requirements. Deepen upstream control over GPU allocation partnerships with hyperscalers to defend margin position against cloud-native entrants. Threat displacement comes from developer-centric monitoring layers absorbing adjacent SecOps functionality. For New Entrants and Emerging Players: Capture mid-market healthcare verticals where HIPAA audit requirements for interpretable anomaly detection outpace incumbent platform retrofitting cycles. Penetrate Singapore fintech clusters through consumption-based pricing models that bypass enterprise procurement friction. Go-to-market leverage rests on vertical-specific compliance pre-certification. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler tuck-in acquisitions seeking explainability capabilities for regulated verticals. Long-term viability favors platforms with documented EU AI Act risk classification workflows and federal contractor certification history. Watch hyperscaler capex allocation shifts toward AI infrastructure as inflection indicator for training cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Explainability Layer Retrofit | EU AI Act documentation mandates force architectural redesigns for existing ML pipelines. |
| Hyperscaler Partnership | AWS, Azure, and GCP marketplace listings accelerate procurement velocity for cloud-native entrants. |
| Vertical Compliance Pre-Certification | HIPAA-auditable anomaly detection pathways unlock healthcare procurement cycles ahead of competitors. |
| SecOps Platform Integration | SIEM telemetry unification captures fastest-expanding solution category demand. |
| Federal Contractor Certification | NIST framework alignment opens US government IT modernization program awards. |
Study Parameters
Document review covered hyperscaler capex disclosures, SEC 10-K infrastructure software filings, and EU regulatory submissions, complemented by interviews with CTOs, IT procurement officers, platform engineers, and channel partners. Secondary validation drew from NIST cybersecurity framework documentation, FCC infrastructure reliability guidelines, and healthcare GPO contract databases. Bottom-up telemetry pipeline deployment estimates triangulated against top-down enterprise software spending analysis.
Market size outputs reflect segment-level modeling across deployment architecture, solution type, end-user organization scale, and algorithmic technology foundation. CAGRs derive from neural processing hardware cost curve trajectories and observability platform adoption velocity across the analysis window. Forecast inputs incorporate EU AI Act enforcement timeline assumptions and federal IT modernization program budget allocations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hyperscaler GPU pricing volatility and export control regime shifts. Projections reflect assumptions about regulatory compliance cost trajectories and legacy toolchain replacement cycles. A small set of triggers—EU AI Act penalty enforcement, federal contractor certification acceleration, and hyperscaler vertical partnership announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Agentic AI Market
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
Global Citizen Services AI Market
Artificial Intelligence (AI)
Supermarket AI-Powered Checkout Market
Artificial Intelligence (AI)
Europe Generative AI Market
Artificial Intelligence (AI)
Global Augmented Intelligence Market
Artificial Intelligence (AI)
Edge AI Software Market
Artificial Intelligence (AI)
Cognitive Systems Market
Artificial Intelligence (AI)
Generative AI in Coding Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Security Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
Synthetic Data Generation Market
Artificial Intelligence (AI)
Federated Learning Market