
 North America Chatbot Market | 2026-2036
North America Chatbot Market Size, Share, and Industry Trends Forecast 2026-2036
North America Chatbot Market Analytics
The North America chatbot landscape is rebalancing between premium enterprise-grade solutions with deep CRM integration and commodity rule-based bots serving small businesses. Microsoft Corporation leverages its Azure cloud infrastructure to anchor large-scale enterprise deployments across Fortune 500 accounts. Google LLC competes through advanced natural language processing capabilities embedded within its contact center AI suite. Amazon Web Services, Inc. differentiates by extending conversational interfaces into logistics and retail operations where it controls end-to-end data flows.
A chatbot is a software application that simulates human conversation through text or voice interfaces, typically employing natural language processing engines, intent classification models, and dialogue management systems to interpret user inputs and generate contextually relevant responses. Its primary commercial purpose is automating customer interactions, reducing operational expenditure, and capturing structured data from conversational exchanges. AI-driven deployments command disproportionate investment as enterprises replace legacy rule-based systems with large language model architectures that improve resolution accuracy. Customer Support applications dominate current revenue pools, though Healthcare segments show the steepest adoption trajectory as HIPAA-compliant architectures mature.
The US FDA and Health Canada scrutinize clinical decision-support chatbots under evolving software-as-medical-device frameworks, compelling vendors to document algorithmic transparency and risk mitigation protocols. The FCC monitors voice-based bot deployments for compliance with telemarketing restrictions and consumer consent requirements. Stakeholders must monitor how state-level biometric privacy laws in Illinois, Texas, and Washington reshape voice authentication strategies and data retention policies.
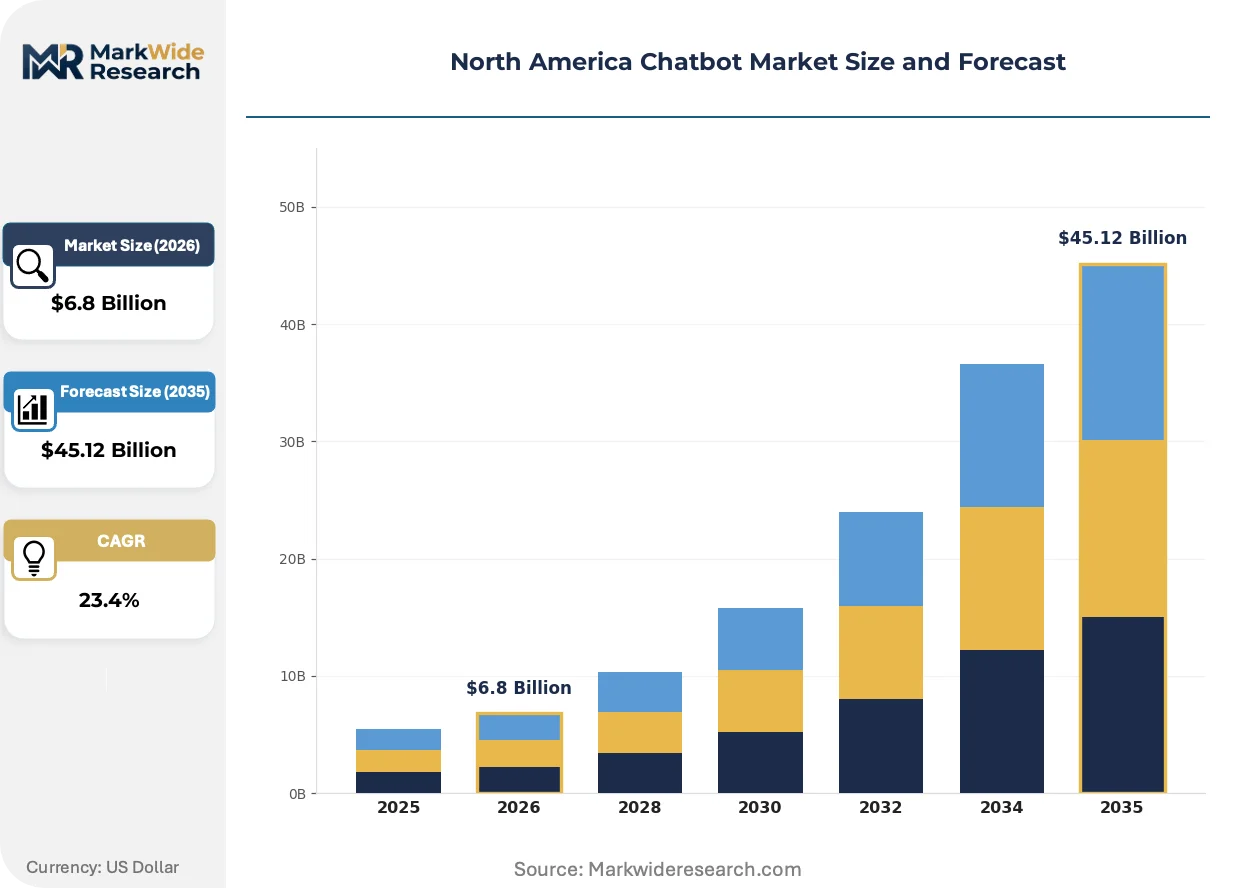
Market Dynamics
Large language model architectures are compressing development cycles for conversational AI, forcing vendors to reprice legacy rule-based offerings and rebuild engineering stacks around transformer-based inference engines.
Growth Catalysts
- FDA Software-as-Medical-Device Framework:Health Canada and the US FDA are clarifying validation pathways for clinical decision-support chatbots, reducing regulatory ambiguity that previously stalled hospital procurement.
- HIPAA-Compliant Cloud Infrastructure:Healthcare providers in California and New York are deploying patient-facing triage bots as major cloud platforms certify business associate agreements for protected health information processing.
- Contact Center Labor Costs:Financial services firms in Manhattan and Toronto are automating tier-one support queries to offset wage inflation in customer service operations.
Market Restraints
- GPU Compute Pricing Volatility:Training and inference costs for large language models fluctuate with NVIDIA data center supply constraints, compressing margins for mid-tier SaaS vendors.
- Washington State Biometric Privacy Law:Voice authentication deployments face consent and retention restrictions that increase compliance overhead for cross-border customer service operations.
- Rule-Based Bot Substitution:Small businesses in the US Midwest continue purchasing cheaper scripted chatbots for basic FAQ handling, delaying AI upgrade cycles.
Strategic Opportunities
- Canadian Healthcare Provincial Networks:Ontario and Quebec hospital systems are consolidating vendor relationships, creating openings for enterprise-grade triage platforms with French-English bilingual capabilities.
- Texas Energy Sector Field Operations:Oil and gas producers are piloting voice-enabled maintenance bots for remote equipment diagnostics where cellular connectivity is intermittent.
- Retrieval-Augmented Generation Convergence:Combining vector database architectures with LLM inference is enabling domain-specific bots that cite source documentation, critical for regulated industries.
Industry Challenges
- Conversational AI Engineer Scarcity:Enterprises in the US Southeast struggle to hire prompt engineering specialists and dialogue designers capable of optimizing retrieval pipelines.
- Legacy CRM Integration Complexity:Fortune 500 accounts demand bidirectional synchronization with decades-old customer databases, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Chatbot Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $45.12 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Text-based, Voice-based, Hybrid, AI-driven Application: Customer Support, E-commerce, Healthcare, Education Deployment: Cloud, On-premise, Hybrid Solution, Open-source End User: Retail, BFSI, Telecom, Travel |
| Companies Covered | International Business Machines Corporation, Microsoft Corporation, Google LLC, Amazon Web Services, Inc., OpenAI, Oracle Corporation, Nuance Communications, Verint Systems Inc, Kore.ai, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Chatbot Market Evolving Landscape
Transformer-based architectures are fragmenting the vendor landscape into inference-optimized specialists and full-stack platform providers, with buyer preferences splitting between customization depth and deployment speed.
Retrieval-augmented generation is modularizing how knowledge bases connect to conversational interfaces. Healthcare systems in Boston and San Francisco are deploying RAG pipelines that ground patient-facing bots in institutional clinical guidelines. This architecture is modularizing the traditional monolithic chatbot stack, allowing providers to swap embedding models and vector stores without retraining entire dialogue systems.
The US FDA's evolving guidance on AI-enabled medical devices is forcing clinical chatbot vendors to document algorithmic transparency and risk mitigation protocols. Health Canada is aligning its software-as-medical-device framework with FDA precedents, creating a harmonized North American compliance pathway. Healthcare IT procurement teams in both countries are now requiring pre-market submission documentation that was previously unnecessary for administrative automation tools.
Buyer concentration among Fortune 500 accounts is consolidating vendor relationships around platforms with pre-built CRM connectors. Mid-market enterprises in Chicago and Dallas are abandoning point solutions for suites that bundle chatbot capabilities with existing cloud productivity licenses. This preference shift is most visible in financial services, where procurement teams prioritize single-vendor support contracts over best-of-breed conversational AI specialists.
North America Chatbot Market Segmentation
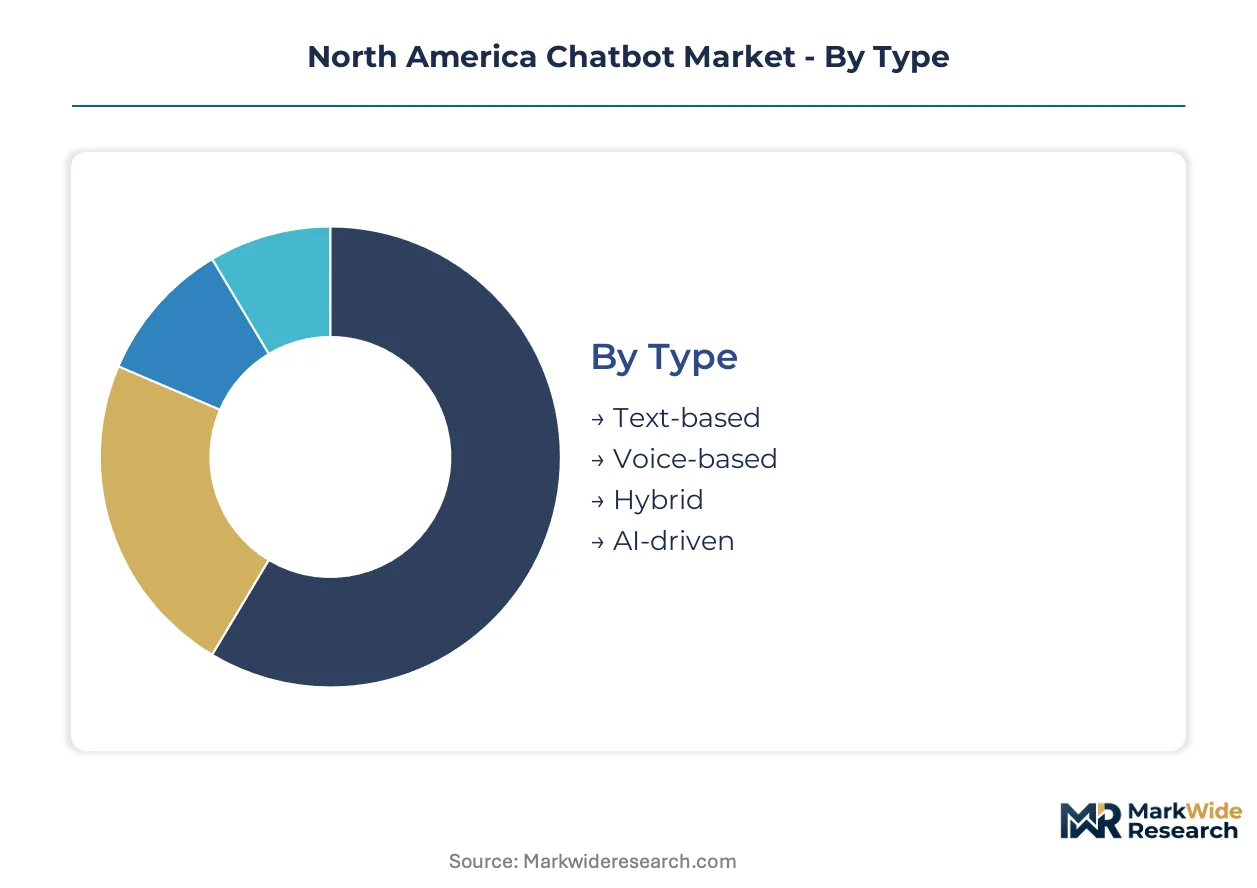
Chatbot segmentation in North America tracks how enterprises replace legacy rule-based systems with AI-native architectures. Deployment choices and application priorities diverge sharply between HIPAA-constrained healthcare providers and cost-sensitive retail operators.
Type:
Upgrade cycles favor AI-driven architectures over scripted alternatives as enterprises reprice vendor relationships around transformer-based inference capabilities.
- AI-driven:Large language model architectures process unstructured queries through retrieval-augmented generation pipelines. Hospital systems in California and Massachusetts demand these for clinical decision-support after FDA validation pathways clarified. Healthcare procurement teams now require algorithmic transparency documentation that rule-based systems never triggered.
- Voice-based:Natural language processing engines convert speech to intent classifications for hands-free operations. Oil and gas producers in Texas deploy these for remote equipment diagnostics where cellular connectivity is intermittent and field technicians need hands-free interfaces.
- Hybrid:Combines text and voice modalities within unified dialogue management systems.
- Text-based:Rule-based or simple NLP systems handling typed queries through scripted response trees.
Volume placements concentrate in Text-based systems serving small business FAQ automation; the faster expansion belongs to AI-driven deployments replacing legacy stacks in Fortune 500 accounts.
Application:
Cost tier separation shapes procurement patterns as premium healthcare deployments absorb compliance overhead that commodity customer support bots avoid.
- Healthcare:HIPAA-compliant architectures with business associate agreements for protected health information processing. Hospital networks in Ontario and Quebec consolidate vendor relationships around bilingual triage platforms. Health Canada and FDA software-as-medical-device frameworks now require pre-market submission documentation.
- Customer Support:Tier-one query automation for financial services firms in Manhattan and Toronto offsetting wage inflation. These deployments prioritize CRM bidirectional synchronization over conversational sophistication.
- E-commerce:Product recommendation and cart recovery through conversational interfaces.
- Education:Administrative automation and student inquiry handling for institutional deployment.
Revenue concentration sits with Customer Support across financial services and telecom; Healthcare applications are climbing the fastest as provincial networks consolidate procurement.
Deployment:
Customer type dictates infrastructure preferences as regulated industries demand data residency that cloud-native vendors must architect around.
- Cloud:Scalable inference through certified healthcare cloud platforms with business associate agreements. Major platforms compete for hospital procurement in California's enterprise software corridor and New York's financial services hub.
- Hybrid Solution:Sensitive data processing on-premise with model inference in cloud environments. Banks in Toronto and Chicago favor this architecture for customer authentication workflows subject to cross-border data restrictions.
- On-premise:Complete data residency for classified or highly regulated operations.
- Open-source:Self-managed deployments with community-supported model weights.
Procurement volume clusters in Cloud deployments leveraging existing productivity suite licenses; Hybrid Solution architectures are gaining share fastest among regulated BFSI accounts.
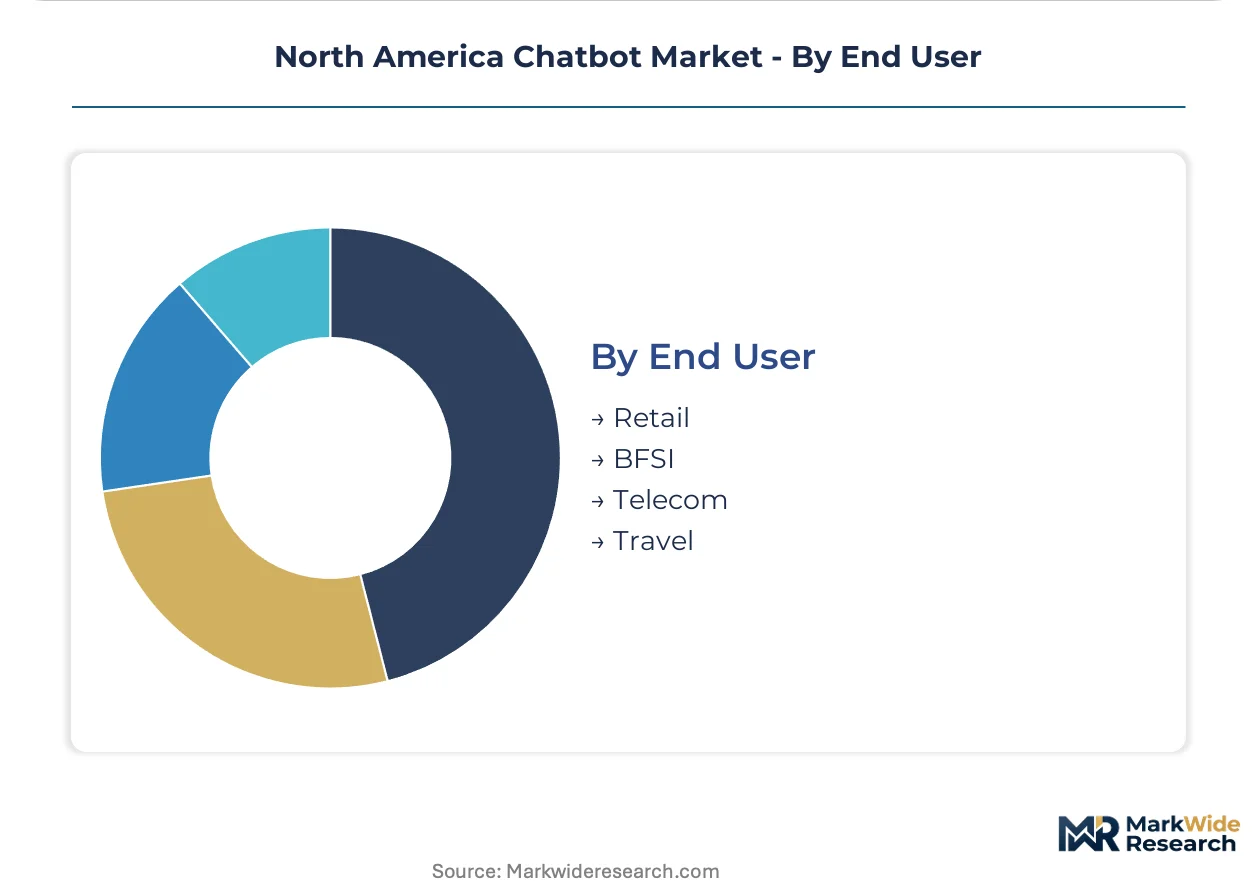
End User:
Margin structures vary by vertical as BFSI tolerates premium pricing for compliance certification while retail squeezes vendor margins.
- BFSI:Fraud detection, account servicing, and wealth management conversations requiring audit trails. Manhattan and Toronto financial services firms prioritize single-vendor support contracts over best-of-breed specialists.
- Retail:High-volume, low-complexity interactions where scripted bots suffice for basic FAQ handling. Midwest retailers continue purchasing cheaper rule-based systems, delaying AI upgrade cycles.
- Telecom:Technical support and billing inquiry automation with IVR replacement.
- Travel:Booking modification and real-time itinerary assistance across multimodal transport.
Contract value concentrates in BFSI deployments with compliance overhead; Retail represents the steepest expansion trajectory as mid-market enterprises abandon point solutions for bundled suites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's enterprise software corridor anchors North American chatbot deployment, with San Francisco and San Jose hosting dense concentrations of AI-native vendors and Fortune 500 pilot programs. New York's financial services hub and Toronto's banking sector drive parallel demand for compliance-heavy conversational automation.
United States
Healthcare providers in California and Massachusetts accelerate patient-facing triage bot deployments as the FDA clarifies software-as-medical-device validation pathways. The FCC monitors voice-based deployments for telemarketing consent compliance. Manhattan financial services firms consolidate vendor relationships around platforms with pre-built CRM connectors.
Canada
Ontario and Quebec hospital networks consolidate procurement around bilingual triage platforms with French-English capabilities. Health Canada aligns its software-as-medical-device framework with FDA precedents, creating harmonized compliance requirements. Toronto's banking sector drives demand for hybrid cloud architectures addressing cross-border data restrictions.
Mexico
Manufacturing clusters in Nuevo León and the Bajío Region pilot Spanish-language customer support automation for export-oriented operations. The country's federal data protection authority imposes localization requirements on customer-facing conversational systems. Mexico City Metro hosts growing contact center outsourcing operations adopting tier-one query automation.
North America Chatbot Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance certification depth and enterprise CRM integration capability. The vendor base stratifies between hyperscale cloud platforms with full-stack AI infrastructure and specialized conversational AI vendors with vertical-specific compliance expertise. Three archetypes dominate: hyperscale cloud providers anchoring enterprise-wide deployments, healthcare-focused specialists with FDA validation experience, and mid-tier SaaS vendors serving cost-sensitive mid-market accounts. M&A activity concentrates on acquiring retrieval-augmented generation capabilities, while strategic partnerships focus on embedding conversational interfaces within legacy enterprise software suites.
Within the hyperscale tier, Microsoft Corporation and Amazon Web Services, Inc. occupy positions defined by cloud infrastructure control and enterprise distribution reach. Microsoft leverages Azure's existing Fortune 500 footprint to anchor large-scale deployments, while AWS extends conversational interfaces into logistics and retail operations where it commands end-to-end data flows. Google LLC exemplifies the NLP-specialist archetype through advanced language processing capabilities embedded within contact center suites. These three hyperscale anchors represent the consolidation pressure forcing mid-tier vendors toward vertical specialization or niche compliance expertise.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| Microsoft Corporation |
| Google LLC |
| Amazon Web Services, Inc. |
| OpenAI |
| Oracle Corporation |
| Nuance Communications |
| Verint Systems Inc |
| Kore.ai, Inc. |
| Others |
Value Network & Pricing Analysis
Prompt engineering specialists concentrated in California's Bay Area and Seattle metropolitan corridors command compensation premiums that widen pricing spreads between enterprise-grade AI deployments and commodity rule-based alternatives. Labor-cost differentials between these talent clusters and secondary US markets feed directly into vendor pricing tiers, with HIPAA-compliant healthcare deployments absorbing the steepest premiums.
Pricing Analysis
Value-based pricing anchored to resolution accuracy rates and patient outcome metrics dominates healthcare deployments, where FDA-validated clinical decision-support bots command premium positioning against administrative automation tools. Price differentiation rests on certification depth—FDA software-as-medical-device documentation versus basic business associate agreements—and integration complexity with legacy CRM systems. Cost compression in mid-market SaaS tiers intensifies as NVIDIA GPU supply constraints inflate inference overhead. Retail and small business segments exhibit the sharpest price sensitivity, while hospital networks in California and Massachusetts tolerate premium positioning for validated clinical architectures.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure compel enterprise buyers to qualify both Microsoft Azure and Amazon Web Services for critical deployments, mitigating single-platform dependency risks. Supply concentration centers on the United States for hyperscale cloud platforms, Taiwan for NVIDIA GPU fabrication, and Ireland plus Singapore for European and Asia-Pacific data residency compliance. Raw material dependencies span advanced silicon wafers, high-bandwidth memory modules, and specialized optical interconnects. Tariff exposure on Chinese-manufactured server components presents structural vulnerability. Distribution runs through direct enterprise sales organizations supplemented by systems integrators in healthcare and financial services verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America chatbot market is consolidating around a vertical-integration race, with hyperscale platforms pursuing in-house production of retrieval-augmented generation pipelines and specialized embedding models to capture margin pools previously ceded to component vendors.
For Market Incumbents: Acquire retrieval-augmented generation engineering teams to fortify differentiation against open-source model commoditization. Consolidate hospital procurement relationships in Ontario and Quebec by embedding French-English bilingual capabilities as standard features, not premium add-ons. Deepen backward integration into vector database architectures to reduce dependency on Pinecone and Weaviate licensing.
For New Entrants and Emerging Players: Transformer-based fine-tuning for Texas energy sector field operations offers a technology-first wedge into an underserved vertical with intermittent connectivity requirements and limited incumbent penetration. Target provincial healthcare networks consolidating vendor relationships around bilingual triage platforms. Pursue channel partnerships with industrial IoT hardware vendors rather than direct enterprise sales to minimize customer acquisition costs.
For Investors and Strategic Acquirers: Re-rating potential sits with healthcare-focused specialists possessing FDA software-as-medical-device submission experience given Health Canada's harmonization with US validation pathways. Long-term viability over the next decade favors vendors with pre-built CRM connectors to Salesforce and Microsoft Dynamics ecosystems. Monitor Ontario Health and Quebec Santé procurement consolidation announcements as inflection indicators for enterprise-grade platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-built Salesforce and Microsoft Dynamics connectors accelerate hospital procurement cycles in California and Massachusetts. |
| Acquisition of Specialist Firm | Retrieval-augmented generation engineering teams command premium valuations as vector database expertise scarcity intensifies. |
| Strategic Partnership | French-English bilingual capability alliances with Quebec language technology providers secure provincial healthcare procurement. |
| Geographic Expansion | Ontario and Quebec hospital network consolidation creates concentrated demand for enterprise-grade triage platforms. |
| Product Launch | FDA-validated clinical decision-support modules differentiate offerings in Health Canada harmonized compliance frameworks. |
Research Methodology
Independent corroboration across primary interviews with hospital CIOs, contact center operations directors, conversational AI engineering leads, and healthcare GPO contracts managers underwrites the qualitative findings. Secondary validation draws from FDA software-as-medical-device guidance documents, Health Canada regulatory filings, hyperscaler capex disclosures, and hospital procurement database aggregators. Bottom-up deployment estimates triangulate against top-down market sizing derived from cloud infrastructure spending patterns and enterprise software license trajectories.
Rate-of-change decomposition across the analysis window isolates volume effects from pricing migration as enterprises shift from rule-based to AI-native architectures. Segmentation dimensions modeled span deployment model, organization size, vertical application, integration complexity, and regional regulatory cluster. CAGRs derive from logistic adoption curves fitted to historical enterprise software upgrade cycles, with healthcare penetration rates and GPU compute cost trajectories as primary forecast inputs.
Several conditions sit outside the modeled scope, including unanticipated FDA regulatory reversals on clinical decision-support classification, catastrophic supply disruptions in NVIDIA data center GPU availability, and state-level biometric privacy law expansions beyond Illinois, Texas, and Washington. Deviation in Health Canada software-as-medical-device framework alignment with FDA precedents would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Asia-Pacific Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Supermarket AI-Powered Checkout Market
Artificial Intelligence (AI)
Emotion AI Software Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
AI Code Assistant Market
Artificial Intelligence (AI)
Global Artificial Intelligence-Emotion Recognition Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Law Market
Artificial Intelligence (AI)
AI-Ready Enterprise Knowledge Graph Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
Robotic Vision Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Hardware Market
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
Global Cognitive Services Market