
 AI Data Labeling Market | 2026-2036
AI Data Labeling Market Size, Share, and Industry Trends Forecast 2026-2036
AI Data Labeling Market Insights
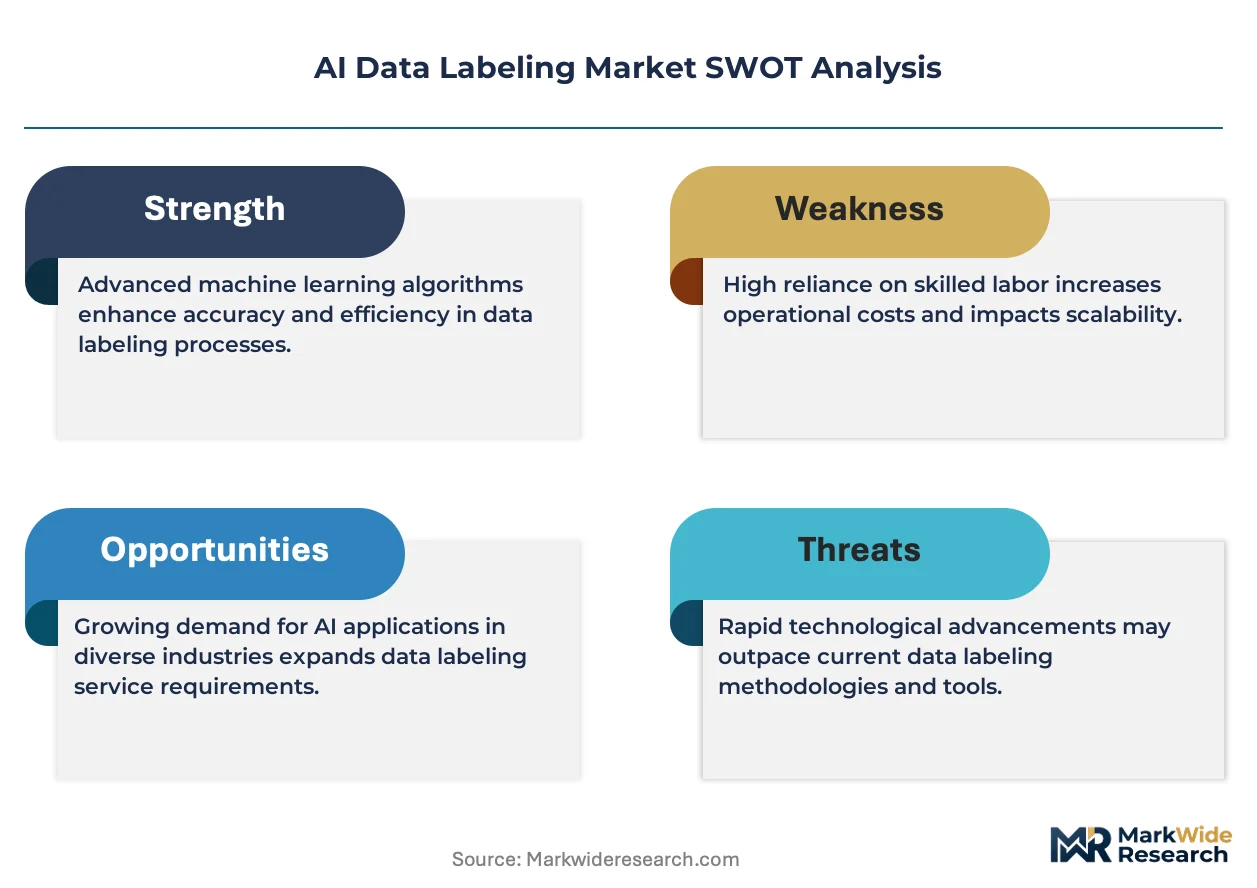
Enterprise demand for training data is consolidating around a shrinking pool of technology firms and automotive OEMs that internalize quality requirements. Scale AI dominates high-complexity annotation for defense and autonomous mobility clients. Appen Limited sustains broad linguistic coverage across its contributor network for natural language processing workloads. Amazon Web Services leverages cloud infrastructure integration to bundle labeling with compute and storage services.
AI data labeling encompasses the systematic assignment of descriptive tags, bounding coordinates, semantic masks, or transcription metadata to raw unstructured data, enabling supervised machine learning algorithms to recognize patterns and make predictions. The process relies on human annotators, algorithm-assisted pre-labeling, and quality assurance pipelines to achieve precision thresholds typically exceeding 95 percent for production-grade computer vision models. Image annotation leads current revenue contribution as autonomous vehicle perception systems require pixel-accurate object detection across millions of frames. Text annotation represents the fastest-expanding category as large language model developers procure instruction-following datasets and reinforcement learning from human feedback corpora. Cloud-based deployment captures the dominant share of new contracts by eliminating capital expenditure for annotation infrastructure and enabling elastic workforce scaling.
The European Union AI Act imposes documentation and traceability mandates on training data used in high-risk applications, directly elevating compliance costs for providers serving healthcare analytics and autonomous systems. The FDA maintains evolving guidance on machine learning-enabled medical devices, requiring structured validation datasets that drive demand for clinically annotated imaging. ISO standards for AI quality management are gaining contractual weight in procurement specifications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid fragmented compliance architectures that inflate operational overhead.
Market Dynamics
Enterprise procurement of labeled datasets is consolidating around vertically integrated technology platforms that bundle annotation with model training infrastructure, compressing margins for standalone service providers.
Growth Catalysts
- EU AI Act documentation mandates:The regulation's risk-classification framework requires auditable data provenance for high-stakes AI systems, forcing healthcare analytics and autonomous vehicle developers to upgrade labeling infrastructure.
- Reinforcement learning from human feedback (RLHF):Large language model developers are procuring instruction-following corpora at scale, expanding text annotation faster than any other data modality.
- San Francisco-Seattle annotation hub concentration:Federal AI procurement guidelines and venture capital flows are clustering specialized workforce pools on the United States West Coast.
Market Restraints
- Pixel-accurate quality thresholds:Autonomous vehicle perception models demand annotation precision exceeding 95 percent, requiring multi-pass human review that inflates unit economics.
- Cloud infrastructure vendor lock-in:Amazon Web Services and Microsoft Azure bundle labeling tools with compute contracts, raising switching costs for enterprise buyers.
- Clinical validation dataset requirements:FDA guidance on machine learning-enabled medical devices mandates structured imaging corpora that extend sales cycles by 12-18 months.
Strategic Opportunities
- India contributor network expansion:Linguistic diversity and cost arbitrage position the country as an alternative to United States-based annotation pools for natural language processing workloads.
- Algorithm-assisted pre-labeling convergence:Computer vision models are accelerating human annotator throughput by generating draft bounding boxes and semantic masks for refinement.
- ISO 42001 AI management system certification:Early adoption of quality management standards creates procurement preference in enterprise and defense segments.
Industry Challenges
- Annotator workforce retention:Repetitive task design and wage compression in offshore delivery centers drive annual turnover exceeding 40 percent in tier-2 Indian cities.
- Multi-jurisdiction compliance architecture:Divergent documentation requirements between EU AI Act, FDA guidance, and ISO standards fragment operational workflows for global providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Data Labeling Market |
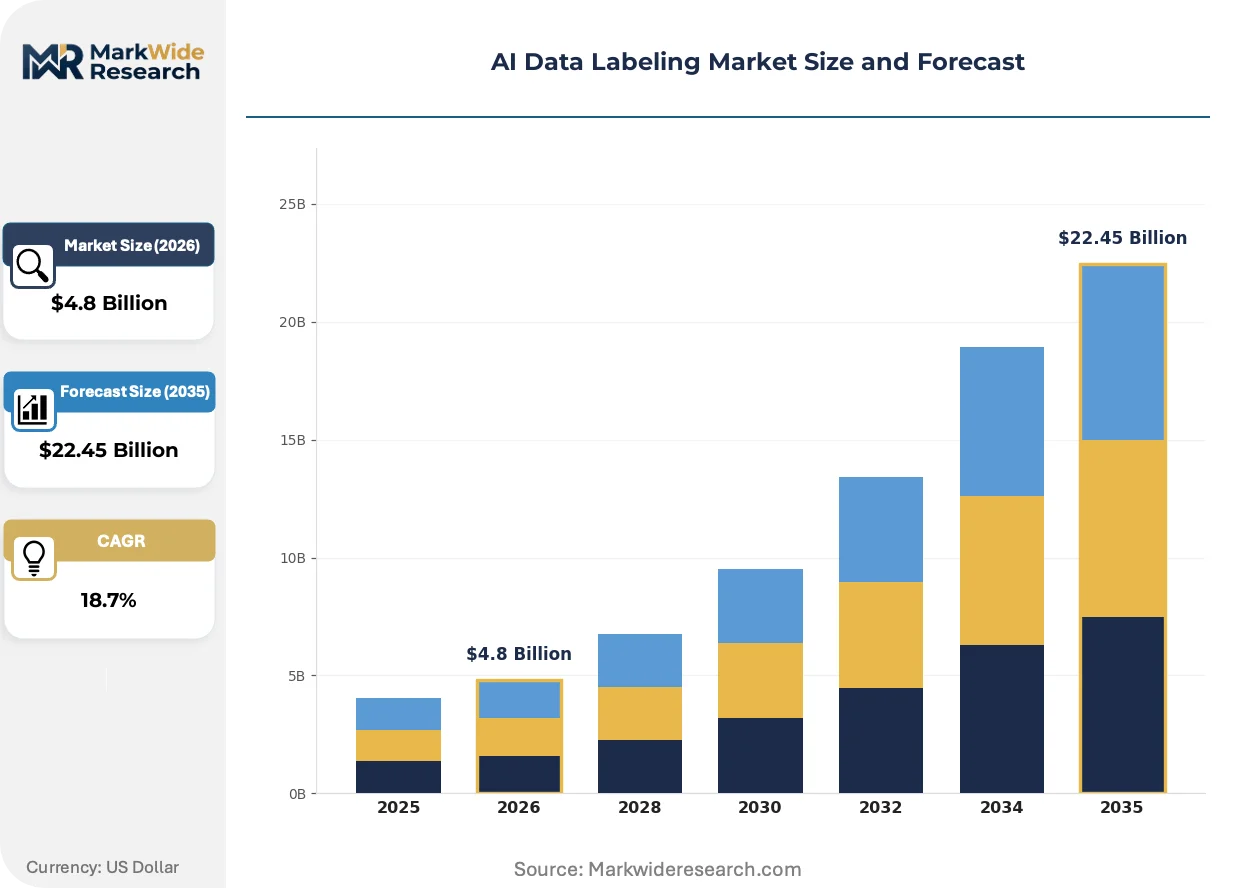
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Image Annotation, Video Annotation, Text Annotation, Audio Annotation Application: Autonomous Vehicles, Healthcare Analytics, E-commerce, Customer Service End User: Manufacturers, Technology Firms, Research Institutions, Startups Deployment Model: On-Premises, Cloud-Based, Hybrid, Others |
| Companies Covered | Scale AI, Appen Limited, Amazon Web Services, iMerit Technology Services, CloudFactory Limited, TELUS International AI Data Solutions, Labelbox, Encord, Sama, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Data Labeling Market Trends and Innovations
Federated learning architectures and synthetic data generation are redistributing annotation workloads away from centralized facilities toward edge-deployed contributor networks and algorithmic pipelines.
Synthetic data generation is decentralizing the economics of training data production. Generative adversarial networks and neural radiance fields now render photorealistic scenarios for rare edge cases in autonomous driving. Automotive OEMs are adopting these pipelines to supplement real-world capture for pedestrian-in-jam scenarios and adverse weather conditions. The technology is decentralizing geographic dependency on physical test fleets and localized camera rigs.
The EU AI Act's risk-tier documentation requirements are reshaping contractual specifications for high-stakes applications. Providers serving medical imaging and autonomous systems must now maintain immutable audit trails linking individual annotations to final model outputs. Healthcare analytics vendors are responding by investing in blockchain-verified provenance systems and dedicated compliance engineering functions.
Buyers are unbundling annotation from model development to secure multi-source data provenance. Defense contractors and autonomous vehicle manufacturers now split workloads across three or more providers to mitigate concentration risk and satisfy procurement diversity mandates. This pattern is most visible in United States federal AI contracts, where vendor fragmentation requirements intersect with security clearance constraints.
AI Data Labeling Market Segmentation
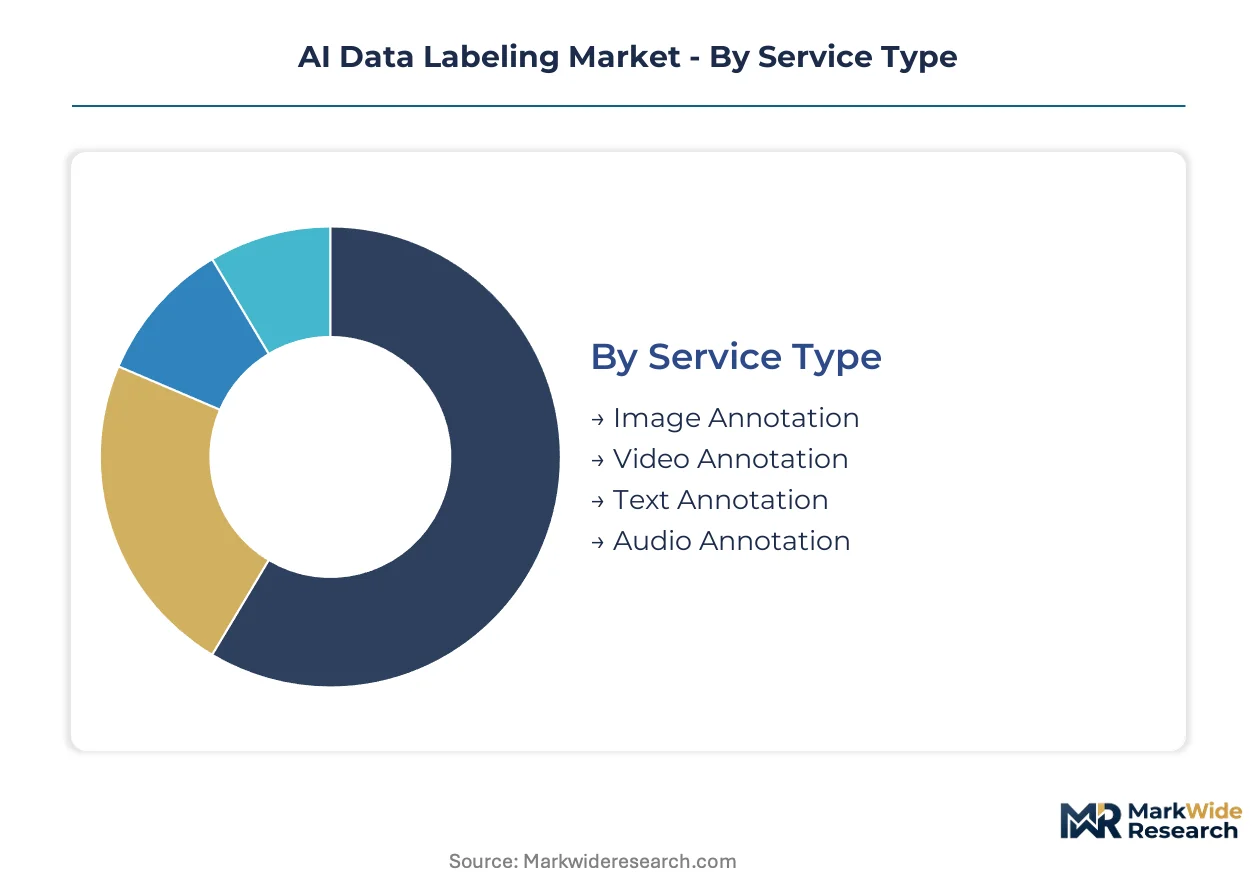
Segmentation reveals how annotation workloads fragment across technical modalities, end-use applications, and procurement models. Understanding these divisions exposes where margin pressure concentrates and where specialized providers can defend pricing power.
Service Type:
Supply concentration varies sharply across annotation modalities, with computer vision tasks commanding premium rates while text annotation scales through distributed contributor networks.
- Image Annotation:Pixel-accurate bounding boxes, semantic masks, and keypoint labeling for perception models. Autonomous vehicle manufacturers in the United States consume the largest volumes, with multi-pass human review pushing unit costs higher than other modalities.
- Text Annotation:Named entity recognition, sentiment classification, and instruction-following corpus development. Large language model developers are expanding procurement fastest, with reinforcement learning from human feedback driving demand for specialized linguist pools.
- Video Annotation:Temporal object tracking and action recognition across frame sequences. Autonomous mobility and surveillance analytics represent primary demand concentrations.
- Audio Annotation:Speech-to-text transcription, speaker diarization, and acoustic event detection. Voice assistant developers and call center analytics platforms sustain volume.
Today's leader: Image Annotation. Tomorrow's challenger: Text Annotation.
Application:
End-use applications stratify by regulatory intensity, with healthcare and autonomous systems facing documentation mandates that standalone providers struggle to satisfy.
- Autonomous Vehicles:Perception dataset development for object detection, lane segmentation, and rare edge-case capture. United States federal procurement guidelines and NHTSA safety expectations drive demand for traceable annotation provenance.
- Healthcare Analytics:Medical imaging annotation for radiology and pathology AI. FDA guidance on machine learning-enabled devices mandates structured validation datasets that extend sales cycles and favor established compliance infrastructure.
- E-commerce:Product categorization, visual search training, and recommendation system optimization. Retail platform operators internalize simpler annotation tasks while outsourcing specialized visual taxonomy development.
- Customer Service:Chatbot training data, intent classification, and sentiment analysis corpora. Technology firms deploy algorithm-assisted pre-labeling to compress costs for high-volume conversational AI workloads.
Healthcare Analytics commands the steepest compliance premium. E-commerce offers the most scalable volume pathway.
End User:
Customer type determines contract structure, with manufacturers and technology firms consolidating procurement around vertically integrated platforms while research institutions fragment spend across specialized providers.
- Manufacturers:Automotive OEMs and industrial automation developers procuring perception training data. These buyers internalize quality assurance functions and demand ISO 42001-certified annotation partners.
- Technology Firms:Cloud providers and AI developers bundling labeling with compute infrastructure. Amazon Web Services and Microsoft Azure leverage existing contracts to capture annotation spend.
- Research Institutions:Academic labs and government research centers with constrained budgets and specialized domain requirements. These buyers tolerate longer turnaround times in exchange for cost efficiency.
- Startups:Early-stage AI companies with sporadic, project-based annotation needs. Price sensitivity drives these buyers toward offshore delivery centers and algorithm-assisted workflows.
Technology Firms consolidate spend fastest. Research Institutions sustain the most fragmented supplier relationships.
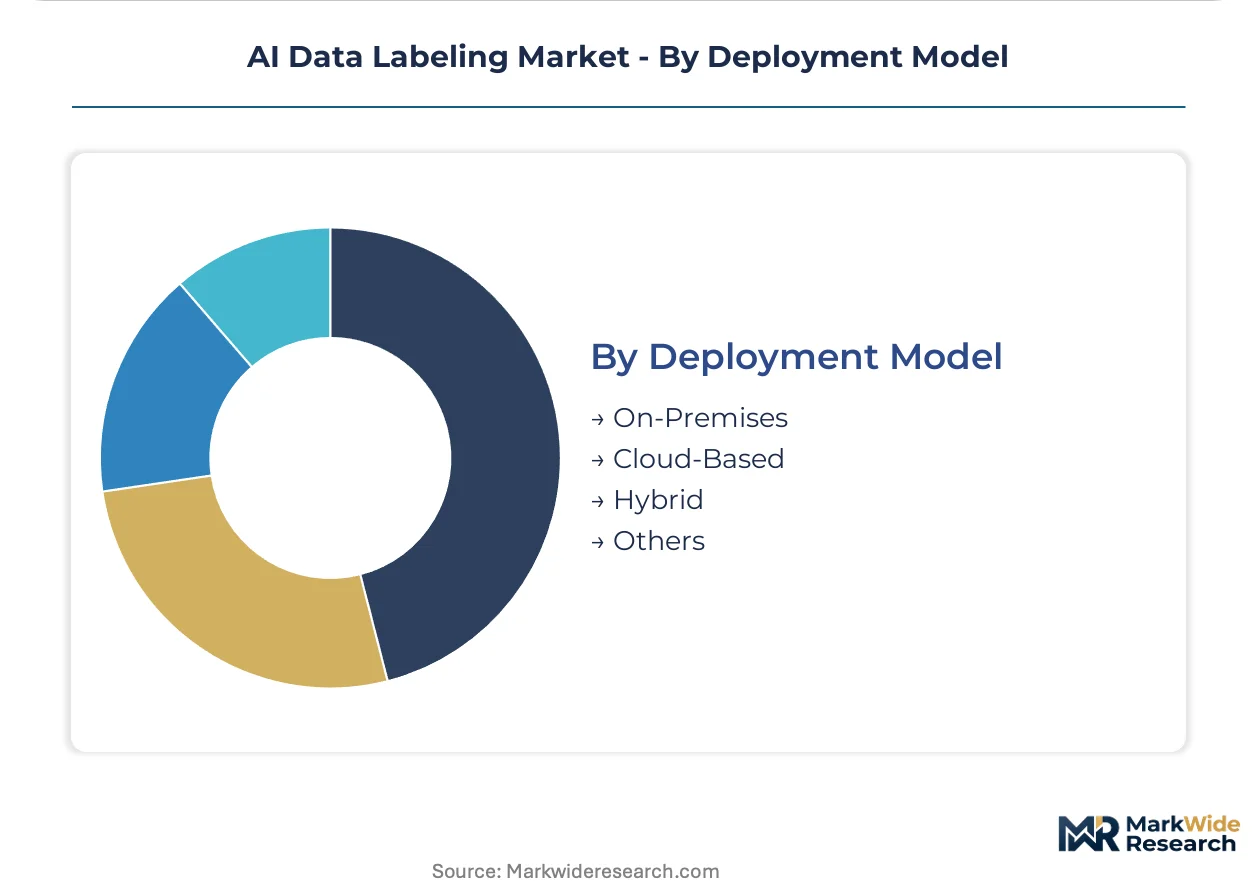
Deployment Model:
Infrastructure choices reflect data sensitivity trade-offs, with defense and healthcare buyers accepting capital expenditure for on-premises control while commercial AI developers optimize for elastic cloud scaling.
- Cloud-Based:Fully managed annotation platforms with elastic workforce scaling and zero capital expenditure. This model dominates new contract signings among technology firms and e-commerce operators.
- On-Premises:Air-gapped annotation infrastructure for classified or regulated data. Defense contractors and healthcare systems accept higher fixed costs to satisfy security clearance and HIPAA requirements.
- Hybrid:Sensitive data processed on-premises with crowdsourced overflow during peak demand. This architecture appeals to autonomous vehicle developers balancing IP protection with annotation velocity.
- Others:Edge-deployed contributor networks and federated learning architectures. These emerging models decentralize annotation away from centralized facilities toward distributed workforce pools.
Cloud-Based deployment captures current volume leadership. Hybrid architectures are gaining procurement preference among security-conscious buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized annotation workforces cluster around venture capital nodes and federal procurement centers, with talent density determining regional competitive advantage in high-precision data services.
United States
San Francisco and Seattle anchor the densest concentration of annotation specialists serving autonomous vehicle developers and defense contractors. Federal AI procurement guidelines from the Department of Defense mandate security-cleared labeling infrastructure, concentrating classified workloads around Washington state and Northern Virginia. Pittsburgh's robotics cluster and Austin's emerging AI corridor absorb secondary annotation demand from industrial automation startups.
India
Linguistic diversity across 22 scheduled languages positions Indian contributor networks as the primary alternative for natural language processing annotation. Cost arbitrage drives large language model developers to Bangalore and Hyderabad delivery centers for instruction-following corpus development. Annual annotator turnover exceeds 40 percent in tier-2 cities, forcing providers to invest in workforce retention programs.
Germany
Automotive OEMs in Stuttgart and Munich procure pixel-accurate perception datasets for advanced driver assistance systems. The KBA enforces documentation standards for training data used in safety-critical vehicle functions, elevating compliance requirements for annotation partners. Berlin's AI startup ecosystem generates secondary demand for multilingual text annotation serving European market expansion.
China
Domestic autonomous vehicle developers in Shenzhen and Beijing operate captive annotation facilities to protect perception model intellectual property. MIIT guidelines on intelligent connected vehicles mandate data localization, restricting cross-border labeling contracts for sensitive mobility datasets. Shanghai's computer vision research institutes supply algorithm-assisted pre-labeling tools that accelerate human annotator throughput.
United Kingdom
London-based AI consultancies procure specialized annotation for financial services and legal technology applications. The Information Commissioner's Office enforces GDPR-aligned data processing agreements that extend vendor qualification timelines for healthcare analytics workloads. Cambridge's machine learning research cluster generates demand for academic-quality ground-truth datasets in scientific computing domains.
AI Data Labeling Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. Cloud infrastructure providers leverage existing compute contracts to bundle annotation services, compressing margins for standalone vendors. Three strategic archetypes dominate: vertically integrated platforms serving defense and automotive OEMs, linguistically diversified contributor networks for NLP workloads, and algorithm-assisted workflow vendors optimizing unit economics. Consolidation pressures favor M&A activity targeting ISO 42001-certified operations and strategic partnerships bridging on-premises security requirements with elastic cloud scaling.
Within the vertically integrated tier, Scale AI exemplifies the defense-automotive specialist archetype through its concentration on high-complexity perception datasets. Appen Limited anchors the linguistic coverage segment with distributed contributor infrastructure spanning multiple continents. Amazon Web Services occupies the cloud-bundling position, leveraging existing enterprise contracts to capture annotation spend through infrastructure integration. These three represent the dominant competitive vectors shaping procurement patterns across enterprise and government segments.
| Leading Market Players |
|---|
| Scale AI |
| Appen Limited |
| Amazon Web Services |
| iMerit Technology Services |
| CloudFactory Limited |
| TELUS International AI Data Solutions |
| Labelbox |
| Encord |
| Sama |
| Others |
Pricing and Supply Chain Analysis
EU AI Act documentation mandates gate both qualified supply and premium-tier pricing access, restricting high-stakes annotation contracts to providers with immutable audit trails and ISO 42001 certification while compressing margins for uncertified competitors serving lower-risk applications.
Pricing Analysis
The bundled-vs-unbundled service split separates cloud-integrated platforms from standalone annotation vendors. Pricing stratifies across premium, standard, and economy tiers based on ISO 42001 certification status and multi-pass quality review depth. Cost compression in the standard tier is intensifying because Amazon Web Services and Microsoft Azure bundle labeling with compute contracts. Startups exhibit the highest price sensitivity, while defense contractors accept substantial premiums for security-cleared infrastructure.
Supply Chain Analysis
Regional distribution centers in San Francisco, Seattle, and Bangalore anchor hub-and-spoke workforce deployment for high-complexity perception datasets. Raw material dependencies include specialized linguist pools for NLP workloads, algorithm-assisted pre-labeling software licenses, and HIPAA-compliant data infrastructure. Single-source vulnerability concentrates in cloud infrastructure provisioning, where AWS and Azure control annotation platform delivery. Distribution runs through direct enterprise contracts with automotive OEMs and federal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as autonomous vehicle manufacturers and healthcare analytics vendors consolidate procurement around ISO 42001-certified providers capable of satisfying EU AI Act traceability requirements.
For Market Incumbents: Anticipate margin compression from algorithm-assisted pre-labeling tools by accelerating in-house development of computer vision automation and securing exclusive contracts with security-cleared annotation facilities in Washington state. Prioritize backward integration into synthetic data generation pipelines to defend against generative AI substitution for rare edge-case capture.
For New Entrants and Emerging Players: Cloud hyperscaler partnership programs offer the most penetrable channel for mid-market technology firms seeking to bundle annotation with existing infrastructure spend. Target academic research institutions with fragmented supplier relationships and extended turnaround tolerance. Deploy federated learning architectures as a differentiated go-to-market angle for privacy-sensitive healthcare workloads.
For Investors and Strategic Acquirers: Valuations sit cheapest among linguistically diversified contributor networks with established India delivery infrastructure and subscale compliance engineering functions. Long-term viability hinges on regulatory divergence between jurisdictions creating persistent demand for multi-territory operational expertise. Monitor FDA guidance evolution on machine learning-enabled medical devices as the critical inflection signal for healthcare annotation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 42001 Certification Investment | Creates procurement preference among automotive OEMs and defense contractors subject to EU AI Act documentation mandates. |
| Synthetic Data Generation Pipeline | Reduces geographic dependency on physical test fleets for autonomous vehicle perception training. |
| India Contributor Network Expansion | Captures cost arbitrage for natural language processing workloads while mitigating San Francisco-Seattle talent concentration. |
| Algorithm-Assisted Pre-Labeling Development | Accelerates human annotator throughput through computer vision draft bounding box generation. |
| Blockchain-Verified Provenance System | Satisfies EU AI Act immutable audit trail requirements for high-risk healthcare and autonomous system applications. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with data labeling platform executives, automotive OEM procurement leads, healthcare AI regulatory affairs specialists, and cloud infrastructure partnership managers alongside secondary validation from SEC filings, EU AI Act implementation guidance, FDA machine learning device guidance documents, and hyperscaler capex disclosures. Bottom-up annotation volume estimates triangulate against top-down enterprise AI training spend projections.
Granularity-level framing models service type, application, end user, and deployment mode dimensions at the segment level with regional production cluster differentiation. CAGRs derive from fitted growth curves across the projection horizon incorporating autonomous vehicle fleet deployment schedules, large language model developer headcount expansion, and regulatory compliance cost pass-through assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to algorithmic substitution rates for human annotation and jurisdictional regulatory divergence. Forecasts reflect documented assumptions around workforce retention in Indian delivery centers and cloud infrastructure vendor concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
Artificial Intelligence Platform Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Security Market
Artificial Intelligence (AI)
Global Ambient Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
Industrial Artificial Intelligence [AI] Market
Artificial Intelligence (AI)
AI in Retail Market
Artificial Intelligence (AI)
AI in Fashion Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
AI Mirror Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market
Artificial Intelligence (AI)
Egypt Artificial Intelligence Market