
 Artificial Intelligence (AI) in BFSI Market | 2026-2036
Artificial Intelligence (AI) in BFSI Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) in BFSI Market Analysis
Cloud-native model deployment is tilting the technology stack away from on-premise legacy systems toward elastic, API-first architectures. IBM Corporation leverages its Watson platform to anchor institutional trust in explainable credit scoring. Microsoft Corporation sustains competitive pressure through deep Azure integration with existing enterprise banking infrastructure. NVIDIA dominates the training-layer supply chain with specialized GPU clusters optimized for high-frequency trading algorithms.
Artificial Intelligence in BFSI encompasses machine learning, natural language processing, computer vision, and robotic process automation applied to financial services workflows, typically operating through cloud-based inference engines that process structured and unstructured data at sub-second latency for decision automation. The primary commercial purpose is to reduce operational cost, enhance predictive accuracy, and enable personalized customer engagement at scale. Fraud Detection leads product-type deployment as regulatory scrutiny intensifies and real-time payment rails expand. Natural Language Processing is the fastest-growing technology segment as conversational banking interfaces displace traditional call-center volumes. Machine Learning occupies the mature core of the stack, where margin pools have compressed and differentiation shifts toward proprietary data moats rather than algorithmic novelty.
The EU AI Act, the US SEC's predictive-data analytics rules, and the UK's Financial Conduct Authority guidance on algorithmic decision-making collectively reshape product standards and market access by mandating human oversight, bias auditing, and transparency documentation for high-risk financial AI applications. HIPAA and GDPR intersect where health-insurance underwriting models process protected information, creating dual-compliance architecture requirements. Stakeholders must monitor emerging jurisdictional fragmentation in algorithmic accountability standards to avoid costly retrofitting of governance frameworks across operating regions.
Market Dynamics
The EU AI Act's risk-based classification framework is compressing deployment timelines for automated lending systems while forcing institutions to rebuild governance architectures around explainability mandates.
Growth Catalysts
- Real-time payment infrastructure:Instant settlement rails in the United States and United Kingdom are generating transaction volumes that exceed human monitoring capacity, necessitating machine learning deployment for fraud detection.
- GDPR Article 22 enforcement:European data protection authorities are compelling banks to document algorithmic decision logic, creating procurement pull for explainable AI tooling.
- Conversational interfaces:Natural language processing capabilities are displacing tier-one call center volumes as retail banks automate customer service workflows.
Market Restraints
- GPU supply concentration:Training-layer hardware dependency on specialized semiconductor foundries in Taiwan creates procurement bottlenecks and cost volatility for model development.
- Dual compliance architecture:Intersection of HIPAA and GDPR requirements for health-insurance underwriting models forces redundant data governance systems.
- Human oversight mandates:The EU AI Act's requirement for meaningful human review of high-risk credit decisions adds operational friction to fully automated workflows.
Strategic Opportunities
- India's regulatory sandbox:The Reserve Bank of India's controlled testing environment permits experimental AI deployment in credit scoring without full licensing requirements.
- Embedded finance convergence:Integration of machine learning models into non-banking platforms creates distribution channels beyond traditional branch networks.
- Climate risk modeling:Stress-testing algorithms for physical asset exposure represent an emerging application as insurers face regulatory pressure from the EU Green Deal.
Industry Challenges
- Model risk management talent:Scarcity of professionals capable of validating machine learning systems against SR 11-7 standards constrains deployment velocity.
- Legacy core integration:API connectivity between cloud-native inference engines and mainframe-based transaction processing systems requires expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) in BFSI Market |
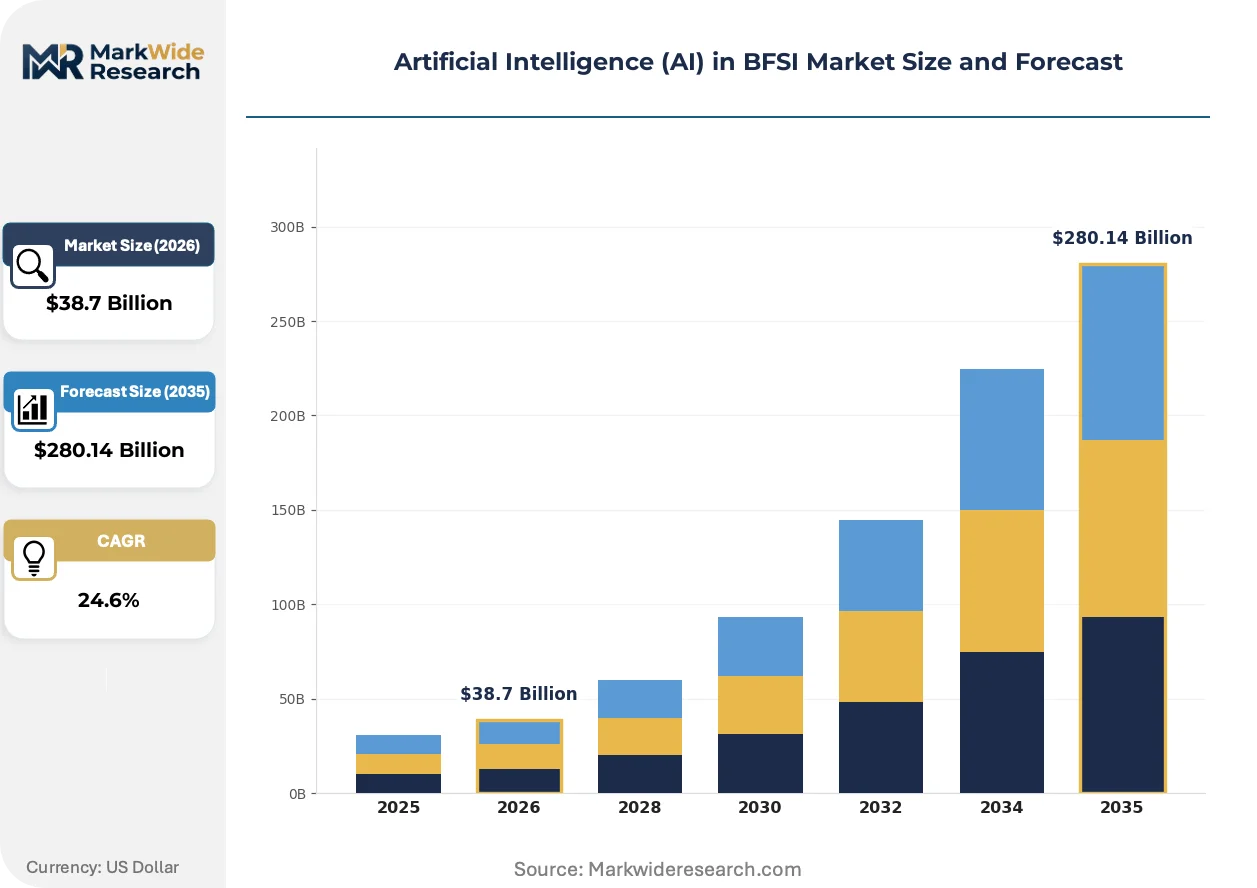
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fraud Detection, Risk Management, Customer Insights, Chatbots Application: Loan Approval, Insurance Underwriting, Investment Analysis, Personalized Banking End User: Retail Banks, Investment Firms, Insurance Providers, Credit Unions Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotic Process Automation |
| Companies Covered | IBM Corporation, Microsoft Corporation, Google, Amazon Web Services, Salesforce, Oracle, SAP, NVIDIA, Baidu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) in BFSI Market Emerging Trajectories
Competitive advantage is migrating from proprietary algorithm development toward exclusive data access and real-time feature engineering capabilities that improve model performance.
Federated learning architectures are migrating from experimental pilots to production deployment, allowing banks to train models on distributed datasets without centralizing sensitive customer information. European institutions facing GDPR constraints are adopting this approach fastest. The structural consequence is that data network effects are compressing competitive moats for institutions with limited cross-border data access.
The EU AI Act's conformity assessment requirements are mandating bias auditing documentation and human oversight protocols for automated credit decisions. Banks must now maintain technical files demonstrating risk management systems. Retail lending divisions in France and Germany are responding by restructuring product approval workflows to embed compliance checkpoints before model deployment.
Subscription-based model governance platforms are displacing perpetual-license software procurement in enterprise AI operations. Chief risk officers are prioritizing vendors offering continuous monitoring and automated retraining pipelines. This shift is most visible in United States money-center banks where operational technology budgets face heightened scrutiny from federal banking regulators.
Artificial Intelligence (AI) in BFSI Market Segmentation
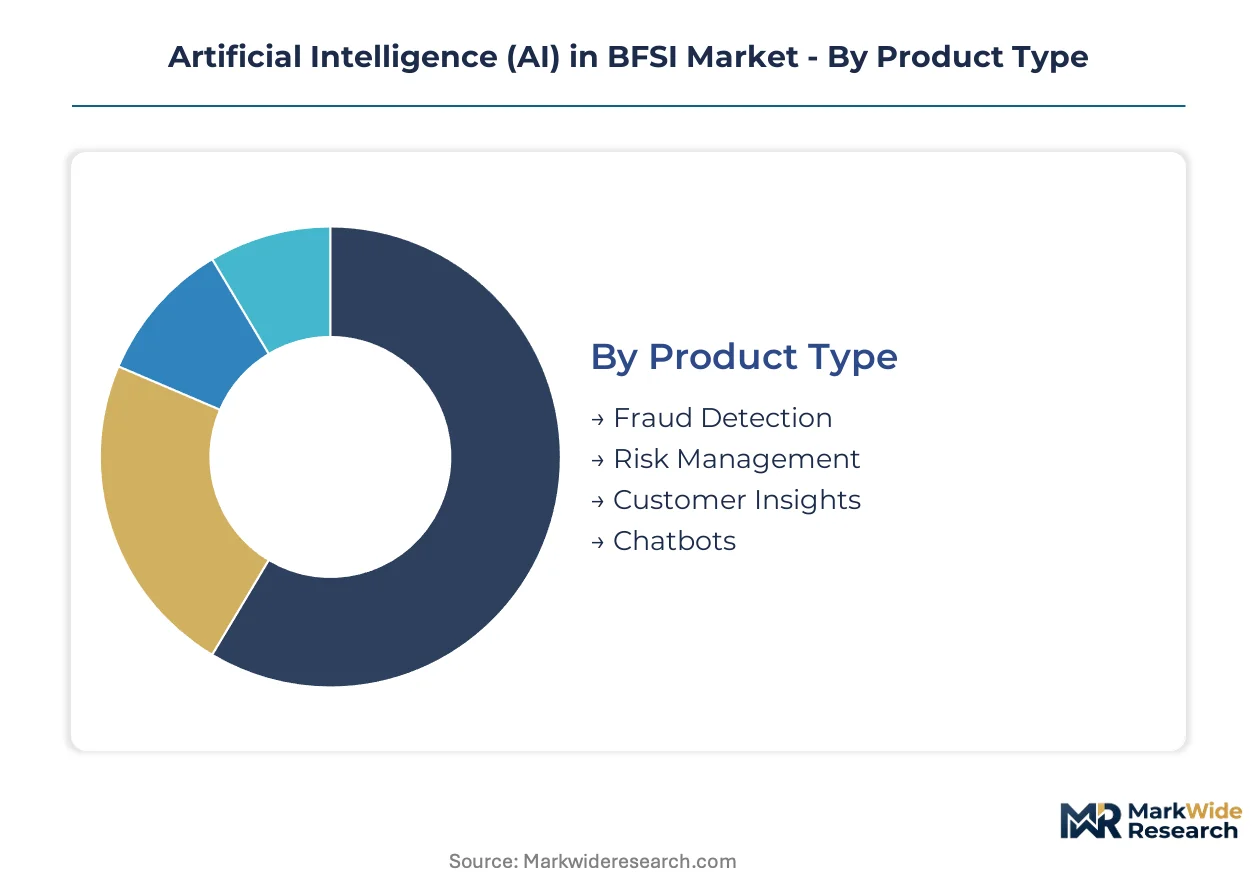
Segmentation in AI-driven financial services reveals how technology deployment varies sharply by institutional risk appetite, regulatory exposure, and data infrastructure maturity. Each dimension exposes distinct procurement patterns and vendor selection criteria that shape competitive outcomes across banking, insurance, and capital markets.
Product Type:
Use-case spectrum spans from defensive compliance applications to offensive revenue-generation tools, with deployment priority shifting based on institutional size and regulatory jurisdiction.
- Fraud Detection:Real-time transaction monitoring systems employing anomaly detection algorithms to flag suspicious patterns across payment rails. Demand concentrates among United States retail banks facing SEC scrutiny on consumer protection, driven by instant settlement infrastructure expansion that outpaces human review capacity. The dominant share belongs to Fraud Detection, while Customer Insights is closing the gap fastest.
- Risk Management:Predictive models for credit default probability, market volatility forecasting, and operational risk quantification. Investment firms in London deploy these for stress-testing portfolios against climate scenarios mandated by the EU Green Deal.
- Customer Insights:Behavioral analytics platforms segmenting depositors and borrowers for targeted product recommendations. German retail lenders use these to comply with GDPR Article 22 documentation requirements while preserving cross-sell efficiency.
- Chatbots:Conversational interfaces handling routine account inquiries and service requests. French banks deploy these to reduce call-center headcount while maintaining EU AI Act human oversight protocols for escalations.
Product mix tilts toward defensive applications in regulated European markets versus customer-facing automation in competitive North American retail banking.
Application:
Revenue impact varies from cost-avoidance in back-office functions to direct margin expansion in front-line distribution.
- Loan Approval:Automated credit scoring pipelines evaluating borrower risk through alternative data integration. United States regional banks deploy these to compete with fintech lenders, constrained by fair-lending audit requirements from the Consumer Financial Protection Bureau.
- Insurance Underwriting:Machine learning models processing medical records, telematics, and satellite imagery for premium pricing. Health insurers face dual HIPAA-GDPR compliance architecture when cross-border data flows intersect with protected health information.
- Investment Analysis:Algorithmic parsing of earnings transcripts, regulatory filings, and alternative data for alpha generation. Quantitative hedge funds in Connecticut and London dominate procurement of natural language processing tools for sentiment extraction.
- Personalized Banking:Recommendation engines tailoring product bundles to individual cash-flow patterns. Indian banks leverage the Reserve Bank of India's regulatory sandbox to test experimental personalization without full licensing overhead.
Loan Approval commands the largest implementation base, though Personalized Banking exhibits the steepest expansion trajectory among digitally native retail institutions.
End User:
Procurement sophistication correlates with balance-sheet scale and in-house data science headcount.
- Retail Banks:Full-stack deployment spanning fraud detection through conversational interfaces, constrained by legacy core system integration costs. Major United States money-center banks lead in cloud-native inference engine adoption.
- Investment Firms:Specialized demand for high-frequency trading algorithms and alternative data processing. GPU cluster procurement concentrates among quantitative funds with direct exchange connectivity.
- Insurance Providers:Climate risk modeling and automated claims processing represent emerging priorities under EU Green Deal disclosure requirements.
- Credit Unions:Limited deployment focused on member service automation and basic fraud monitoring, constrained by technology budgets and vendor management capacity.
Retail Banks absorb the dominant technology investment volume, while Investment Firms achieve the highest per-employee AI spending intensity.
Technology:
Maturity gradient runs from commoditized infrastructure to experimental capabilities with unproven governance frameworks.
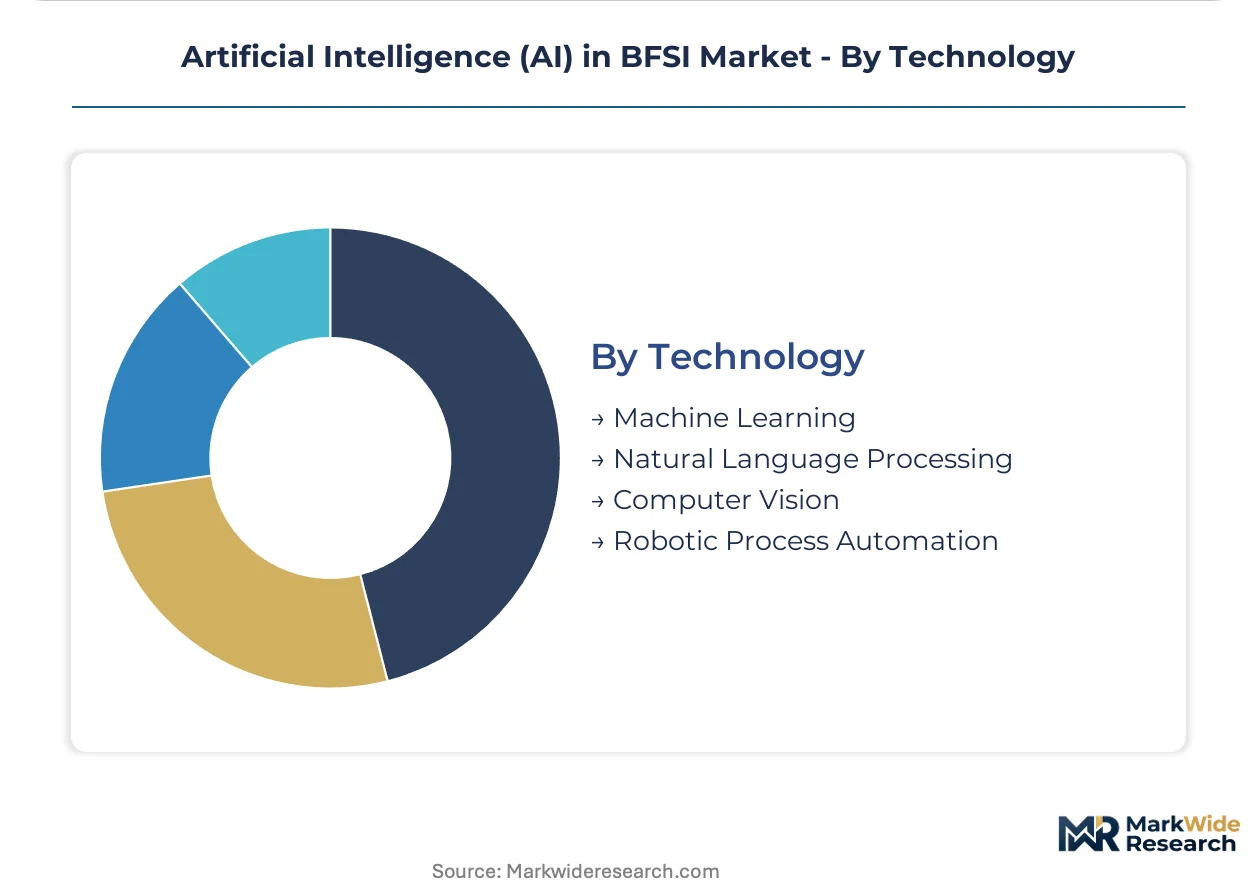
- Machine Learning:Supervised and unsupervised statistical models forming the operational core of credit scoring, fraud detection, and portfolio optimization. Margin compression has shifted competitive differentiation toward proprietary training data rather than algorithmic architecture.
- Natural Language Processing:Text and speech analysis enabling document extraction, sentiment analysis, and conversational interfaces. European institutions facing GDPR constraints adopt federated learning architectures fastest to preserve cross-border model training without data centralization.
- Computer Vision:Image recognition for check processing, identity verification, and property damage assessment. Insurance providers deploy these for automated claims triage.
- Robotic Process Automation:Rule-based workflow automation handling repetitive data entry and reconciliation tasks. Credit unions leverage these for cost reduction without complex model governance overhead.
Machine Learning retains the deepest installed base, though Natural Language Processing is gaining share fastest as conversational banking displaces traditional service channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in AI-enabled financial software exports, while India and China remain net importers of core training infrastructure and specialized GPU clusters. European institutions face the steepest compliance cost escalation under the EU AI Act's conformity assessment regime.
United States
Real-time payment infrastructure expansion through FedNow drives machine learning procurement for fraud detection at money-center banks. The SEC's predictive-data analytics rules mandate algorithmic transparency documentation for broker-dealers. New York City anchors quantitative hedge fund concentration, where natural language processing tools parse earnings transcripts for alpha generation.
Germany
Retail lending divisions restructure product approval workflows to embed EU AI Act compliance checkpoints before model deployment. BaFin guidance on algorithmic decision-making requires explainable credit scoring documentation for automated loan decisions. Frankfurt's banking cluster leads federated learning adoption to preserve cross-border model training without centralizing sensitive customer data.
United Kingdom
Instant settlement rails generate transaction volumes exceeding human monitoring capacity, necessitating real-time anomaly detection systems. FCA guidance on algorithmic decision-making shapes governance standards for automated underwriting. London's quantitative finance sector dominates procurement of GPU-optimized high-frequency trading infrastructure.
India
The Reserve Bank of India's regulatory sandbox permits experimental AI deployment in credit scoring without full licensing requirements. SEBI mandates algorithmic audit trails for systematic trading platforms. Mumbai's fintech corridor attracts cloud-native inference engine deployment for personalized banking recommendation systems.
China
Domestic banks accelerate computer vision adoption for identity verification and property damage assessment in insurance claims. SAMR algorithmic recommendation regulations impose transparency requirements on automated lending platforms. Shenzhen's technology cluster concentrates development of conversational banking interfaces displacing traditional call-center operations.
Artificial Intelligence (AI) in BFSI Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability layers: cloud infrastructure providers, specialized AI platform vendors, and semiconductor hardware suppliers. Strategic archetypes include full-stack enterprise platforms, vertical-specific SaaS providers, and training-layer hardware specialists. Competitive moves center on API-first architecture partnerships and federated learning consortium formations to bypass data localization constraints.
Within the enterprise platform tier, IBM Corporation and Microsoft Corporation exemplify divergent approaches to institutional trust-building—Watson anchors explainable credit scoring positioning while Azure leverages deep enterprise banking infrastructure integration. NVIDIA occupies the training-layer supply chain position with GPU clusters optimized for high-frequency trading algorithm development. Google and Amazon Web Services represent the cloud-native deployment vector, competing through elastic inference engine pricing and pre-trained model marketplaces.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Amazon Web Services |
| Salesforce |
| Oracle |
| SAP |
| NVIDIA |
| Baidu |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Taiwan-based semiconductor foundries compresses pricing tiers across training-layer hardware while forcing cloud-native inference engine providers toward multi-sourcing strategies. GPU supply concentration determines both the premium commanded by NVIDIA for high-frequency trading clusters and the cost pass-through structure facing United States money-center banks deploying real-time fraud detection.
Pricing Analysis
Enterprise banking buyers anchor subscription-based model governance platforms as the dominant pricing structure, displacing perpetual-license software procurement. Pricing stratifies across premium explainable AI tiers with full EU AI Act documentation, standard cloud-native inference packages, and economy robotic process automation modules with limited governance overhead. Cost compression in standard tiers intensifies as Microsoft Azure and Google Cloud Services compete on elastic compute pricing. Credit unions exhibit highest price sensitivity due to constrained technology budgets, while quantitative hedge funds in London show lowest sensitivity given alpha-generation returns from GPU-optimized infrastructure.
Supply Chain Analysis
Advanced GPU architectures feed from Taiwan, South Korea, and United States fabrication facilities, with NVIDIA's training-layer clusters resting on TSMC's specialized foundry capacity. Cloud infrastructure components draw from Chinese manufacturing for server assembly, United States for software layer development, and Ireland for European data residency compliance. Single-source vulnerability concentrates in Taiwan's semiconductor ecosystem, exposing procurement timelines to geopolitical disruption. Distribution runs through API-first vendor partnerships and federated learning consortiums that bypass data localization constraints across European jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics dynamics in AI-enabled financial services hinge on API-first architecture partnerships that embed machine learning models into non-banking distribution channels. Interoperability shifts toward explainable AI tooling that satisfies EU AI Act conformity assessments while preserving model performance.
For Market Incumbents: Pre-empt regulatory fragmentation by consolidating federated learning consortiums that preserve cross-border data access without centralization. Invest in proprietary training data moats as algorithmic novelty compresses margins across commoditized machine learning infrastructure. Defend against cloud-native entrants through deep core banking system integration that legacy mainframe connectivity reinforces. For New Entrants and Emerging Players: India's regulatory sandbox under the Reserve Bank of India offers the most penetrable entry point for experimental credit scoring without full licensing overhead. Target climate risk modeling for EU Green Deal compliance as established insurers face capability gaps in physical asset stress-testing. Pursue embedded finance convergence through conversational banking interfaces that displace traditional call-center volumes. For Investors and Strategic Acquirers: The EU AI Act's conformity assessment deadline reshapes the acquisition landscape toward explainable AI tooling vendors with pre-built documentation frameworks. Long-term viability centers on data network effects rather than algorithmic differentiation as federated learning architectures democratize model training. Monitor SEBI algorithmic audit trail enforcement in India as the signal indicating regulatory maturity for systematic trading platform investments.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Consortium Formation | European banks preserve cross-border model training without GDPR centralization penalties through distributed architectures. |
| Explainable AI Platform Integration | BaFin and FCA documentation requirements drive procurement for credit scoring with embedded compliance checkpoints. |
| Embedded Finance Partnership | Non-banking platforms in India distribute personalized banking recommendation engines through RBI sandbox permissions. |
| GPU Cluster Diversification | Money-center banks reduce Taiwan foundry exposure through multi-sourcing agreements with Samsung and Intel. |
| Climate Risk Model Development | EU Green Deal disclosure mandates create procurement pull for physical asset exposure algorithms among insurers. |
Methodological Framework
A spread of perspectives from chief risk officers at United States money-center banks, platform engineers at cloud infrastructure providers, regulatory affairs leads navigating EU AI Act implementation, and procurement managers at quantitative hedge funds converged on the working assumptions. Primary interviews combined with secondary validation against SEC predictive-data analytics rule filings, BaFin algorithmic decision-making guidance, RBI sandbox application records, and hyperscaler capex disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the BFSI technology stack.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with deployment velocity constrained by model risk management talent scarcity and legacy core integration costs. Segmentation dimensions modeled encompassed product type, application workflow, end-user institution category, and technology maturity tier alongside regional regulatory cluster intensity. CAGRs derived from installed base expansion rates adjusted for compliance-driven procurement acceleration. Forecast inputs incorporated FedNow real-time payment infrastructure rollout timelines and GDPR Article 22 enforcement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native fintech challengers or accelerated EU AI Act penalty enforcement would shift outcomes. Cross-checking against SEBI algorithmic trading audit disclosure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Cognitive Services Platform Market
Artificial Intelligence (AI)
Artificial Intelligence Based Personalization Market
Artificial Intelligence (AI)
AI Document Generator Market
Artificial Intelligence (AI)
Asia-Pacific Synthetic Data Generation Market
Artificial Intelligence (AI)
Decision Intelligence Market
Artificial Intelligence (AI)
Global Cloud Telecommunication AI Market
Artificial Intelligence (AI)
Brain Machine Interface Market
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market
Artificial Intelligence (AI)
Global Mobile Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Supply Chain Market
Artificial Intelligence (AI)
Computer Vision Market
Artificial Intelligence (AI)
AI in Project Management Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market