
 Synthetic Data Generation Market | 2026-2036
Synthetic Data Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Data Generation Market Intelligence
Enterprise-grade fidelity is bifurcating the competitive landscape into premium and standard tiers. Syntho leverages differential privacy architectures to anchor European healthcare deployments. Mostly AI sustains leadership in banking-grade tabular synthesis through deep statistical fidelity. Parallel Domain dominates autonomous vehicle simulation with photorealistic sensor data generation.
Synthetic data generation produces algorithmically constructed datasets that mirror statistical properties of real-world information without containing identifiable records, typically employing generative adversarial networks, variational autoencoders, or diffusion models to achieve distributional accuracy within epsilon-differential privacy bounds. Its primary purpose enables AI model training, software validation, and privacy-compliant analytics in jurisdictions where raw personal data faces legal restriction. Image and video synthesis claims the fastest expansion trajectory, fueled by autonomous driving and computer vision R&D pipelines, while text synthesis retains mature margin pools in financial services compliance testing. Cloud-based deployment is displacing on-premises infrastructure among mid-market adopters seeking elastic compute for episodic model retraining workloads.
The EU AI Act imposes conformity requirements on high-risk AI systems that synthetic data can satisfy through auditable provenance trails, while HIPAA limits real patient record circulation in the United States and drives healthcare entities toward de-identification alternatives. ISO standards for AI risk management and data quality provide emerging benchmarks that procurement teams increasingly embed in vendor evaluations. Stakeholders must monitor regulatory divergence between privacy regimes to determine where synthetic data substitutes for anonymization and where it merely supplements existing compliance toolkits.
Market Dynamics
The EU AI Act's conformity requirements for high-risk systems are compressing real-world data pipelines and redirecting procurement budgets toward auditable synthetic alternatives with provenance documentation.
Growth Catalysts
- GDPR Article 25 compliance:Organizations across Germany, France, and the Netherlands deploy synthetic patient records to satisfy data minimization mandates without sacrificing model training throughput.
- Generative adversarial networks:Healthcare AI developers in the United States leverage GAN architectures to generate statistically faithful clinical trial simulations that bypass HIPAA circulation restrictions.
- Autonomous vehicle R&D:Sensor data synthesis for LiDAR and camera fusion training claims the fastest expansion trajectory as OEMs confront real-world data collection bottlenecks.
Market Restraints
- GPU compute cost volatility:Foundation model training for high-fidelity synthesis requires NVIDIA H100 clusters whose spot pricing fluctuates with cryptocurrency mining demand cycles.
- Statistical fidelity ceiling:Tabular synthesis for banking-grade risk models struggles to preserve rare-event tail distributions below epsilon-differential privacy thresholds of 0.1.
- Regulatory fragmentation:Divergent de-identification standards between HIPAA Safe Harbor methods and GDPR anonymization case law create compliance engineering overhead for multinational deployments.
Strategic Opportunities
- Japan's METI AI governance framework:The country's emphasis on trustworthy AI creates procurement pull for synthetic data with embedded fairness auditing capabilities.
- Climate simulation:Earth system modelers in the United Kingdom and Australia adopt synthetic meteorological datasets to augment sparse observational records for extreme weather prediction.
- Diffusion model convergence:Text-to-image architectures from computer vision migrate into structured data generation, enabling photorealistic medical imaging synthesis with pathology labels.
Industry Challenges
- Differential privacy engineering talent:The scarcity of practitioners capable of tuning epsilon parameters against utility loss constraints delays enterprise deployment timelines.
- ISO/IEC 42001 alignment:AI management system certification requirements demand documentation workflows that legacy data science teams lack infrastructure to automate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Data Generation Market |
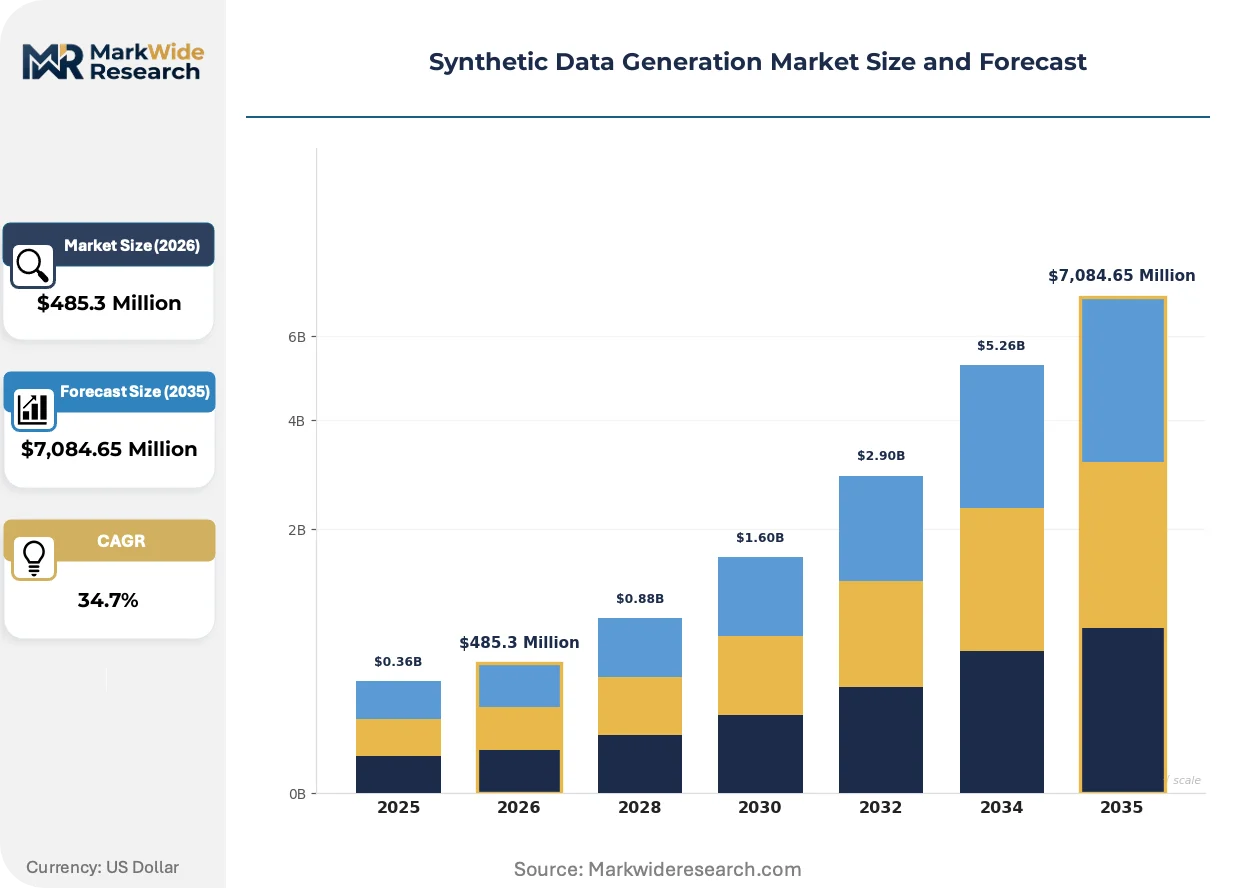
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $7,084.65 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Text, Image, Video, Audio Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Application: Machine Learning, AI Training, Software Testing, Data Privacy End User: Retail, Healthcare, Automotive, Finance |
| Companies Covered | Syntho, Dedomena.AI, K2View, Parallel Domain, Tonic AI, Mostly AI, GenRocket, Syntegra, Hazy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Data Generation Market Strategic Shifts & Innovations
Generative architectures are fragmenting the vendor landscape into fidelity-optimized specialists while regulatory pressure compresses acceptable data sourcing channels across healthcare and financial services.
Diffusion-based synthesis is bifurcating the medical imaging segment. Radiology AI developers at academic medical centers adopt Stable Diffusion derivatives for chest X-ray generation with controlled pathology prevalence. The technology compresses reliance on hospital data sharing agreements while enabling rare disease augmentation that real-world collections cannot support.
The EU AI Act's conformity assessment obligations for high-risk systems are restructuring procurement specifications. Healthcare providers in Sweden and Denmark now require synthetic data vendors to submit algorithmic impact documentation alongside statistical validation reports. This regulatory friction favors European suppliers with embedded legal engineering capabilities over generalist platforms.
Consumption patterns among mid-market enterprises are rotating toward managed synthetic data services. Organizations with episodic model retraining needs reject perpetual licensing in favor of usage-based contracts that bundle generation, validation, and compliance documentation. This shift is most visible in the United States, where HIPAA Business Associate Agreement complexity drives buyers toward vendors assuming liability for downstream privacy failures.
Synthetic Data Generation Market Segmentation
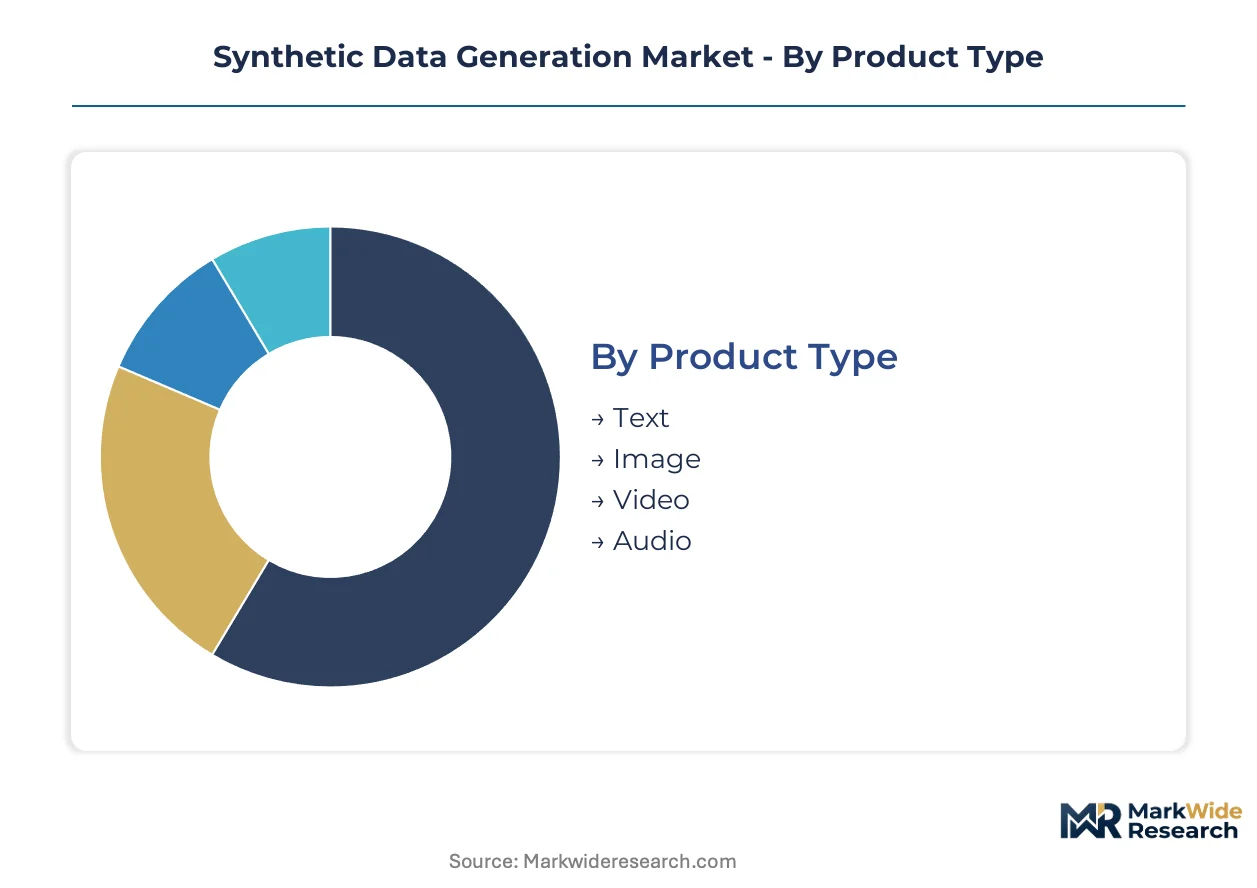
Synthetic data generation vendors compete across four distinct category axes where substitution threats vary sharply. Product type determines fidelity thresholds, deployment mode shapes compliance postures, application use cases dictate validation rigor, and end-user industries impose sector-specific regulatory burdens.
Product Type:
Video synthesis faces the most acute substitution pressure from real-world capture alternatives, while text and tabular formats enjoy stronger structural moats against raw data sourcing.
- Image:Generative architectures produce photorealistic medical scans, satellite imagery, and manufacturing defect simulations with controlled pathology labels. Radiology AI developers at academic medical centers deploy chest X-ray synthesis to bypass hospital data sharing agreements while enabling rare disease augmentation.
- Video:LiDAR and camera fusion sequences for autonomous vehicle training claim the steepest expansion trajectory as OEMs confront real-world data collection bottlenecks and edge-case scarcity. Sensor simulation pipelines compress physical test fleet requirements by orders of magnitude.
- Text:Structured narrative generation serves financial services compliance testing and conversational AI training with embedded fairness auditing capabilities.
- Audio:Speech synthesis with speaker anonymization supports call center analytics and voice biometric system development under GDPR voice data restrictions.
Image synthesis anchors the volume base while video gains share at the steepest rate.
Deployment:
Cost tier stratification separates enterprise buyers with perpetual infrastructure investments from mid-market adopters seeking elastic consumption models.
- Cloud-Based:Usage-based contracts bundle generation, validation, and compliance documentation for episodic model retraining workloads. HIPAA Business Associate Agreement complexity drives United States healthcare buyers toward vendors assuming liability for downstream privacy failures.
- On-Premises:Air-gapped installations serve defense contractors and classified research facilities requiring sovereign data control with zero external transmission.
- Hybrid:Tiered architectures route sensitive preprocessing on-premises while pushing scalable generation to elastic cloud compute during peak training cycles.
- Multi-Cloud:Vendor-agnostic orchestration mitigates NVIDIA H100 cluster spot pricing volatility by distributing workloads across AWS, Azure, and Google Cloud infrastructure.
Cloud-based deployment commands the revenue concentration while multi-cloud configurations expand most quickly among risk-averse enterprises.
Application:
Customer type divergence splits procurement between research-intensive model developers and compliance-driven data privacy officers with distinct validation requirements.
- AI Training:Foundation model developers consume synthetic datasets for pre-training corpus expansion where real-world licensing proves prohibitively expensive or legally restricted.
- Machine Learning:Tabular synthesis for credit risk and fraud detection models struggles to preserve rare-event tail distributions below epsilon-differential privacy thresholds of 0.1.
- Data Privacy:GDPR Article 25 compliance drives German, French, and Dutch organizations toward synthetic patient records that satisfy data minimization mandates without sacrificing model training throughput.
- Software Testing:Production-like environment replication enables CI/CD pipeline validation without exposing live customer records to development teams.
AI training captures the largest budget allocation while data privacy applications climb the fastest on regulatory enforcement tailwinds.
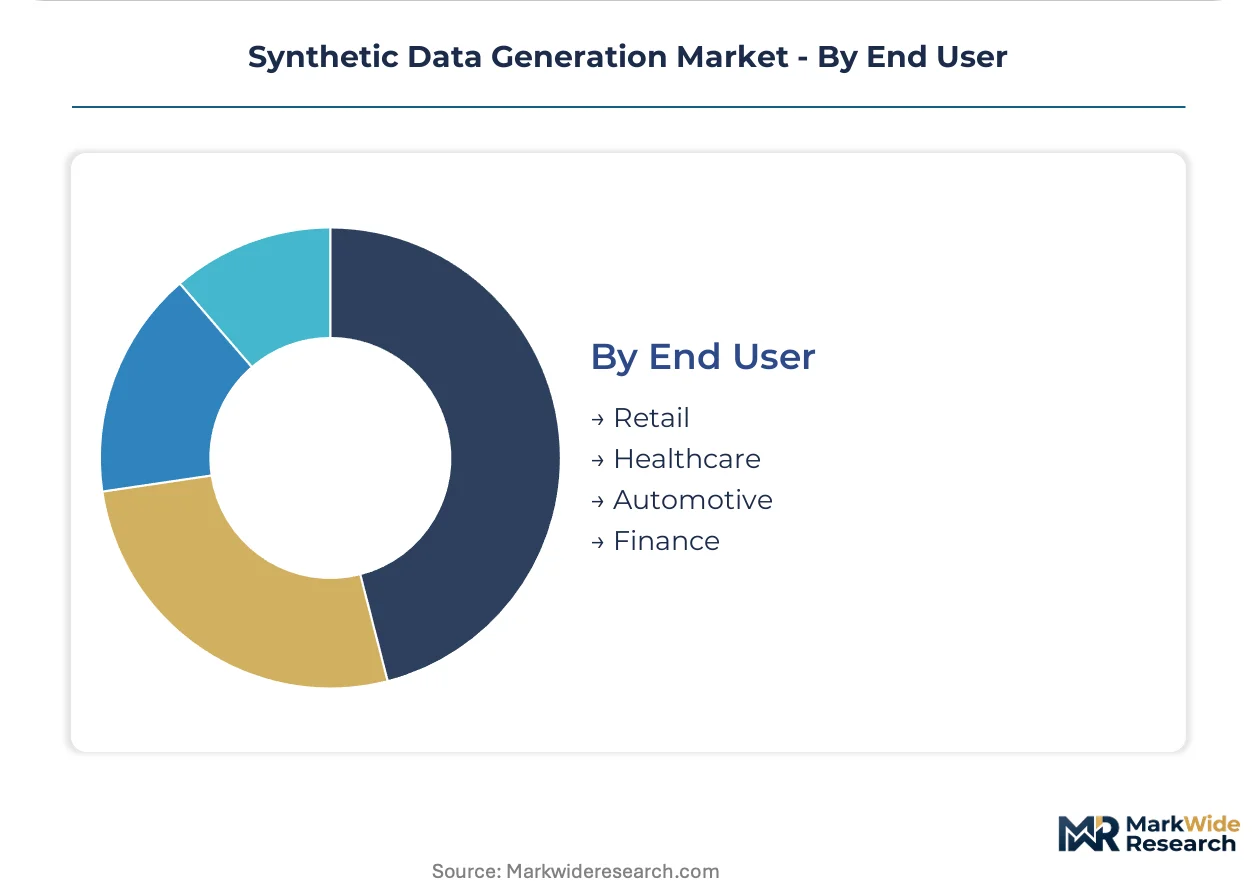
End User:
Geographic concentration of regulatory stringency concentrates demand in jurisdictions with strictest real-data constraints.
- Healthcare:HIPAA limits real patient record circulation in the United States, pushing providers toward de-identification alternatives with auditable provenance trails for EU AI Act conformity assessments.
- Automotive:German and Swedish OEMs dominate sensor data synthesis procurement as NHTSA and KBA safety validation requirements intensify simulation fidelity demands.
- Finance:Banking-grade tabular synthesis requires deep statistical fidelity for risk model validation under ECB and Federal Reserve stress testing frameworks.
- Retail:Customer behavior simulation supports demand forecasting and personalization algorithm development with synthetic transaction histories.
Healthcare anchors the volume base while automotive gains share at the steepest rate on autonomous vehicle R&D acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports synthetic data compliance solutions to Nordic healthcare systems facing GDPR Article 25 enforcement. The United States ships banking-grade tabular synthesis platforms to Canadian fintech clusters navigating provincial privacy fragmentation.
United States
Federal AI investment and HIPAA complexity pull healthcare providers toward compliant synthetic data pipelines. The FDA's guidance on AI/ML-based medical devices encourages simulation-based validation for clinical algorithm development. Academic medical centers in Boston and the San Francisco Bay Area deploy chest X-ray synthesis to bypass hospital data sharing agreements.
Germany
Automotive OEMs confront NHTSA and KBA safety validation requirements that intensify sensor simulation fidelity demands. The EU AI Act's conformity assessment obligations restructure procurement specifications for high-risk AI systems. Stuttgart and Munich anchor LiDAR and camera fusion sequence development for autonomous vehicle training datasets.
United Kingdom
Earth system modelers adopt synthetic meteorological datasets to augment sparse observational records for extreme weather prediction. The Information Commissioner's Office enforces GDPR anonymization case law that diverges from HIPAA Safe Harbor methods. Oxford and Cambridge research clusters pioneer diffusion-based medical imaging synthesis with controlled pathology labels.
Japan
METI's AI governance framework creates procurement pull for synthetic data with embedded fairness auditing capabilities. The Pharmaceuticals and Medical Devices Agency evaluates simulation-based clinical trial designs for regulatory acceptance. Tokyo and Osaka house financial services compliance testing operations using structured narrative generation.
Netherlands
Healthcare providers require synthetic data vendors to submit algorithmic impact documentation alongside statistical validation reports. The Dutch Data Protection Authority enforces data minimization mandates under GDPR Article 25. Amsterdam and Eindhoven concentrate differential privacy engineering talent for European healthcare deployments.
Synthetic Data Generation Market Key Industry Players
Listed leaders compete with private specialists across differential privacy architectures and statistical fidelity tiers. The vendor base stratifies into fidelity-optimized specialists rather than consolidating around generalist platforms. Three archetypes dominate: healthcare-focused compliance vendors, automotive sensor simulation specialists, and banking-grade tabular synthesis providers. M&A activity concentrates on acquiring differential privacy engineering teams, while strategic partnerships target cloud infrastructure integration for elastic compute provisioning.
Within the privacy-preserving healthcare tier, Syntho and Syntegra occupy positions anchored in European regulatory engineering capabilities. Parallel Domain exemplifies the automotive sensor simulation archetype with photorealistic LiDAR and camera fusion expertise. Mostly AI represents banking-grade tabular synthesis specialists competing on deep statistical fidelity for risk model validation.
| Leading Market Players |
|---|
| Syntho |
| Dedomena.AI |
| K2View |
| Parallel Domain |
| Tonic AI |
| Mostly AI |
| GenRocket |
| Syntegra |
| Hazy |
| Others |
Cost & Logistics Intelligence
Cloud-native GPU clusters displacing on-premises NVIDIA infrastructure are redrawing procurement geography and compressing pricing power toward hyperscaler-dominated compute markets. Healthcare buyers in the United States and automotive OEMs in Germany now face divergent cost structures as spot pricing volatility feeds back into long-term contract negotiation strategies.
Pricing Analysis
Generation-based pricing gaps separate H100-class foundation model training from prior-generation A100 inference workloads and emerging Blackwell architectures. Three-tier pricing structure across premium healthcare compliance, standard enterprise SaaS, and economy developer API tiers dominates procurement. Price differentiation rests on epsilon-differential privacy certification grade and HIPAA Business Associate Agreement liability assumption. Pricing pressure stems from cryptocurrency mining demand cycles eroding GPU spot market stability. Mid-market episodic retraining buyers exhibit highest price sensitivity; defense contractors with air-gapped requirements show lowest.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing chokepoints in advanced node fabrication tether synthetic data platform performance to geopolitical transit risks. NVIDIA H100 and Blackwell GPU supply concentrates in Taiwan and South Korea with final assembly in China and Mexico. Raw material dependencies span advanced packaging substrates, high-bandwidth memory stacks, and liquid cooling infrastructure. Single-source vulnerability in CoWoS advanced packaging creates bottleneck exposure. Distribution runs through hyperscaler marketplaces, direct OEM procurement, and specialized AI infrastructure resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic data generation markets are recovering from GPU supply cyclicality as hyperscaler capex expansion normalizes compute availability. Federal AI investment waves in the United States and EU AI Act enforcement cycles in Europe provide alternating demand pulses.
For Market Incumbents: Secure differential privacy engineering talent pools in Amsterdam and Eindhoven before GDPR Article 25 enforcement intensifies vendor consolidation. Anchor long-term contracts with United States academic medical centers facing HIPAA complexity escalation. Defend against diffusion model startups by embedding algorithmic impact documentation workflows that satisfy Swedish and Danish procurement specifications. For New Entrants and Emerging Players: Managed synthetic data services for mid-market episodic retraining workloads represent the most penetrable white-space segment. Target United States healthcare providers rejecting perpetual licensing in favor of usage-based compliance-bundled contracts. Deploy fairness auditing capabilities aligned with Japan METI governance frameworks as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed banking-grade tabular synthesis specialists holding Federal Reserve stress testing relationships. Five-to-ten year viability hinges on regulatory divergence between HIPAA Safe Harbor and GDPR anonymization case law creating persistent compliance engineering demand. Monitor EU AI Act conformity assessment obligation rollout velocity as inflection signal for healthcare procurement budget reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Differential Privacy Certification Investment | ISO/IEC 42001 alignment satisfies Swedish and Danish healthcare procurement requirements. |
| Hyperscaler Marketplace Integration | AWS and Azure distribution channels capture mid-market episodic retraining demand. |
| Automotive Sensor Simulation Partnership | LiDAR and camera fusion expertise locks in German and Swedish OEM procurement. |
| Fairness Auditing Capability Development | METI-aligned features penetrate Japan financial services compliance testing markets. |
| Multi-Cloud Orchestration Buildout | Vendor-agnostic GPU provisioning mitigates NVIDIA H100 spot pricing volatility exposure. |
Research Approach
Cross-validation between synthetic data platform engineering leads and healthcare AI procurement officers anchors the qualitative findings. Primary interviews with differential privacy architects, hospital purchasing committees, automotive sensor simulation directors, and banking risk model validators combined with secondary validation. Secondary sources include FDA AI/ML-based medical device guidance documents, EU AI Act conformity assessment frameworks, HIPAA Business Associate Agreement templates, and hyperscaler capex disclosure filings. Bottom-up deployment mode segmentation triangulates against top-down end-user industry demand modeling.
Sensitivity analysis across epsilon-differential privacy threshold assumptions and GPU spot pricing volatility bands stress-tests projection robustness. The analytical framework segments by product type, deployment mode, application use case, and end-user industry across the analysis window. CAGRs derive from statistical fidelity tier adoption curves and regulatory enforcement timeline probabilities. Forecast inputs incorporate EU AI Act implementation velocity and autonomous vehicle R&D pipeline acceleration.
Material uncertainties — GPU supply chain geopolitical disruption, regulatory divergence between HIPAA and GDPR anonymization standards, and foundation model architecture shifts — sit outside the modeled envelope. Forecasts reflect assumptions about differential privacy engineering talent availability and hyperscaler pricing power consolidation. Practitioners should keep alternative scenarios live as EU AI Act enforcement intensity and federal AI investment appropriation cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Saudi Arabia Big Data and Artificial Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Security Market
Artificial Intelligence (AI)
Automotive Predictive Diagnostic System Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Global Call Center AI Market
Artificial Intelligence (AI)
AI Image Recognition Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market
Artificial Intelligence (AI)
Self-Supervised Learning Market
Artificial Intelligence (AI)
Robotic Vision Market
Artificial Intelligence (AI)
AI in Robotics Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market
Artificial Intelligence (AI)
Autonomous AI and Autonomous Agents Market
Artificial Intelligence (AI)
North America Conversational AI Market