
 Artificial Intelligence (AI) Market | 2026-2036
Artificial Intelligence (AI) Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) Market Outlook
Healthcare is realigning from administrative automation toward clinical decision-support and radiology AI, pulling compute budgets from legacy IT into inference-heavy workloads. NVIDIA Corporation dominates datacenter GPU supply for training and inference pipelines. Microsoft leverages its Azure cloud footprint to embed copilots across enterprise software stacks. Google LLC anchors research-to-production pathways through its DeepMind and Google Cloud AI divisions.
Artificial Intelligence denotes computational systems that learn patterns from structured and unstructured data, then generate predictions, classifications, or synthetic outputs without explicit rule-based programming; these systems rely on neural network architectures, tensor processing units, and large-scale training clusters consuming megawatts of power. Cloud-based deployment captures the bulk of enterprise spending as organizations shift capital expenditure to operational models, while edge computing segments grow fastest in manufacturing quality inspection and autonomous vehicle perception loops where millisecond latency governs utility. Machine learning remains the revenue core, though computer vision applications in semiconductor defect detection and agricultural monitoring are carving out dedicated margin pools.
The FDA regulates AI-enabled medical devices through premarket submission pathways requiring algorithm change control plans, while the EU AI Act imposes risk-tiered conformity obligations on high-stakes applications. China's SAMR and MIIT enforce algorithmic recommendation and deep synthesis provisions that shape product architecture for vendors serving that market. Stakeholders must monitor divergence between Brussels' ex-ante compliance mandates and Washington's post-market surveillance approach, as this regulatory fragmentation will determine which AI architectures achieve cross-border deployability.
Market Dynamics
Healthcare providers are redirecting capital from legacy IT infrastructure toward inference-heavy GPU clusters, compressing procurement cycles from 18-month refresh schedules to quarterly capacity expansions. This compute reallocation is tightening supply chains for NVIDIA H100 and AMD MI300 accelerators while elevating power density requirements in California and Washington datacenter clusters.
Growth Catalysts
- EU AI Act risk-tiered obligations:High-stakes medical device applications face mandatory conformity assessments, accelerating vendor investment in algorithmic audit trails and clinical validation pipelines.
- Semiconductor defect detection:Taiwan and South Korea foundries are deploying computer vision systems for sub-3nm wafer inspection, pulling edge AI hardware into cleanroom environments.
- Cloud operational expenditure models:Enterprise buyers are abandoning capital-intensive on-premise AI infrastructure for Azure and Google Cloud consumption-based contracts.
Market Restraints
- GPU supply concentration:TSMC's CoWoS advanced packaging capacity in Taiwan constrains output of training-optimized accelerators, creating 6-9 month order backlogs.
- FDA algorithm change control requirements:Pre-market submission pathways mandate locked model architectures, freezing vendor ability to deploy continuous learning updates.
- Megawatt-scale power consumption:Training clusters exceeding 100MW draw face permitting delays and grid interconnection bottlenecks in Northern Virginia and Phoenix.
Strategic Opportunities
- India's CDSCO medical device pathway:Streamlined approval timelines for AI-enabled diagnostics are attracting radiology AI vendors to establish local clinical trial infrastructure.
- Federated learning architectures:Privacy-preserving model training across hospital networks without centralizing patient data is opening pharmaceutical discovery partnerships.
- Edge manufacturing quality inspection:Millisecond-latency defect detection in German automotive plants is driving specialized inference chip design.
Industry Challenges
- Transformer architecture specialization:The narrow talent pool for large language model optimization commands compensation premiums exceeding 40% above conventional software engineering roles.
- Cross-border model deployment:Divergent FDA post-market surveillance and EU AI Act ex-ante compliance mandates force vendors to maintain parallel validation datasets and governance frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) Market |
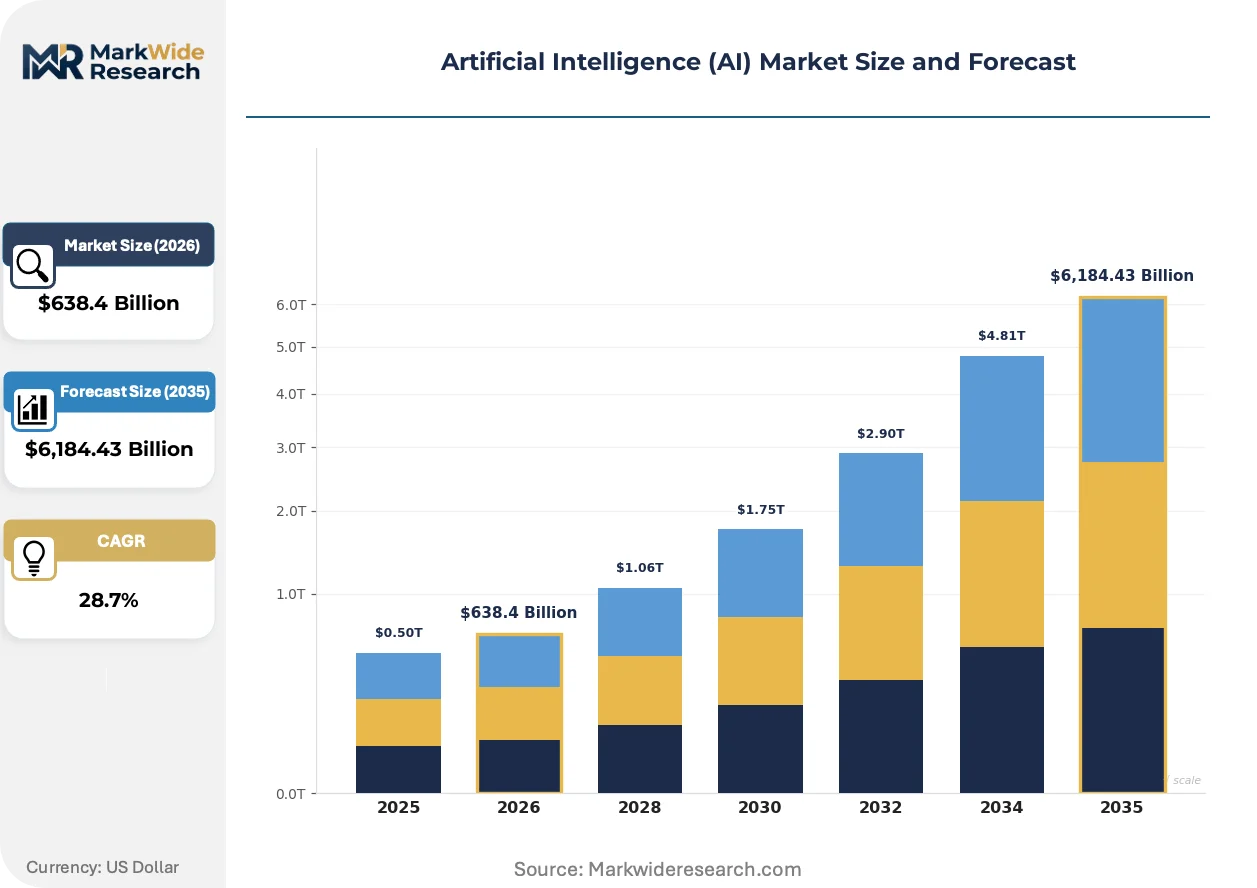
| Market Size in 2026 | $638.4 Billion |
| Market Size in 2035 | $6,184.43 Billion |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics End User: Healthcare, BFSI, Manufacturing, Retail Application: Fraud Detection, Predictive Analytics, Customer Service, Autonomous Vehicles |
| Companies Covered | NVIDIA Corporation, Microsoft, Google LLC, Amazon Web Services, International Business Machines Corporation, Intel Corporation, Advanced Micro Devices, OpenAI, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) Market Strategic Shifts
Foundation model architectures are fragmenting into specialized vertical variants, compressing the dominance of general-purpose systems. This specialization is redrawing competitive boundaries between horizontal platform vendors and domain-trained challengers.
Retrieval-augmented generation is modularizing enterprise knowledge management by decoupling inference from proprietary data stores. Financial services compliance teams in New York and London are deploying these architectures for real-time regulatory query resolution. The separation of parametric memory from contextual retrieval is modularizing cost structures, allowing buyers to scale compute independently from data infrastructure.
The EU AI Act's high-risk system designation is forcing medical device manufacturers to reconstruct development workflows around conformity assessment precedents. Algorithmic transparency requirements are embedding technical documentation teams alongside product engineering. European radiology AI vendors are responding by pre-certifying locked model versions rather than deploying continuous learning pipelines.
Hospital procurement committees are consolidating AI vendor relationships from point-solution fragmentation to platform-standardization contracts. Radiology departments in Texas and Florida are demanding unified inference infrastructure spanning imaging, pathology, and clinical decision support. This concentration is compressing sales cycles for niche diagnostic algorithms while elevating procurement leverage for integrated platform vendors.
Artificial Intelligence (AI) Market Segmentation
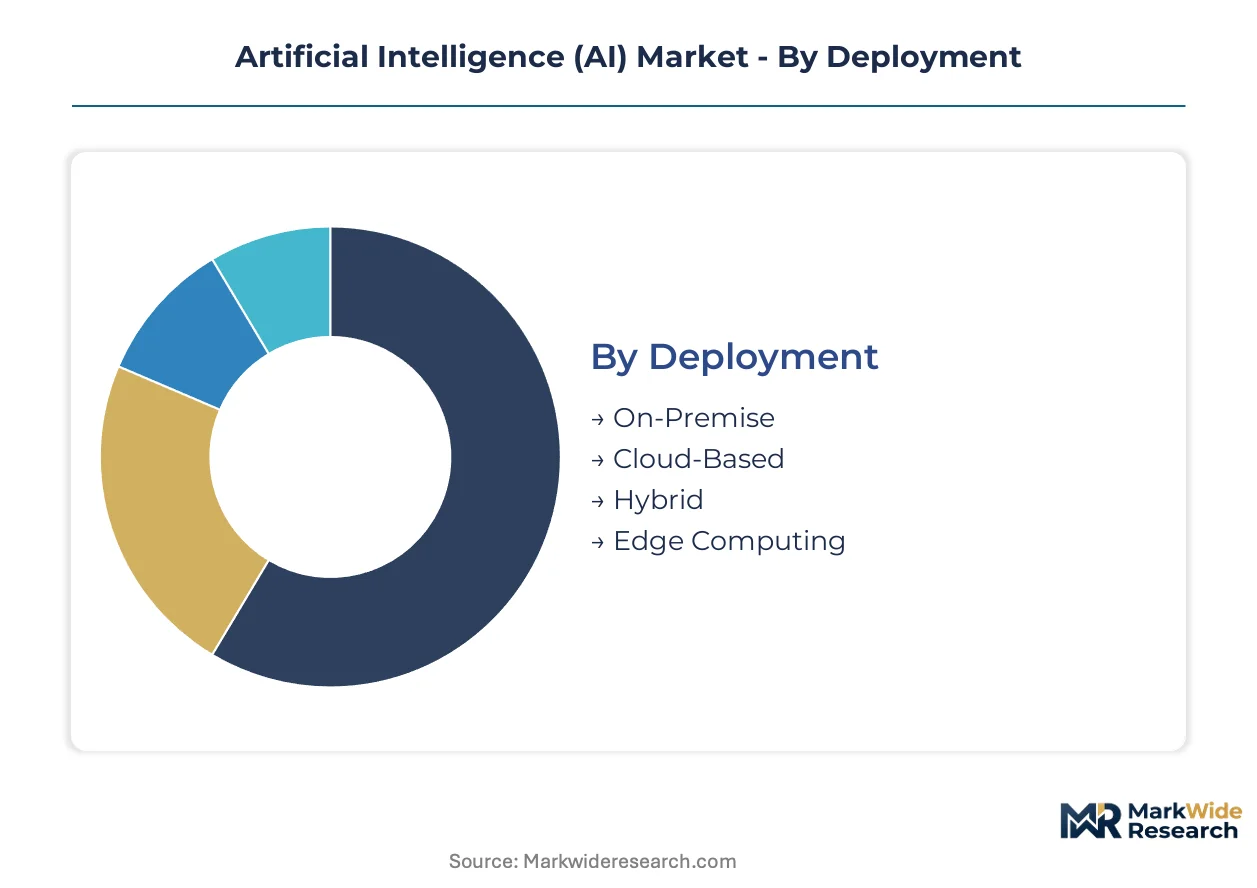
Segmentation in the AI market reveals how regulatory burdens, infrastructure costs, and latency requirements split procurement patterns across buyer types. Understanding these fault lines exposes where compliance investments concentrate and which deployment modes command premium pricing.
Deployment:
FDA premarket submission pathways impose algorithm change control plans on On-Premise medical AI, while EU AI Act conformity assessments fall heaviest on Cloud-Based deployments handling high-risk personal data. Edge Computing in manufacturing escapes direct FDA jurisdiction but faces OSHA safety system validation where AI controls physical machinery.
- On-Premise:Locked infrastructure within hospital datacenters satisfies FDA algorithm change control requirements for diagnostic imaging systems. Texas Medical Center and Mayo Clinic campuses in Minnesota favor this model to maintain direct custody of patient data while running NVIDIA DGX clusters for radiology inference.
- Cloud-Based:Consumption-based contracts through Azure and Google Cloud shift capital expenditure to operational models, though EU AI Act risk-tiered obligations force vendors to maintain EU-sovereign data residency zones. Financial services compliance teams in New York and London deploy retrieval-augmented generation architectures here for regulatory query resolution.
- Hybrid:Split architectures training in cloud while inferencing locally balance cost against latency for pharmaceutical discovery pipelines.
- Edge Computing:Millisecond-latency inference chips in German automotive plants and Taiwanese semiconductor cleanrooms bypass cloud round-trips for defect detection.
Cloud-Based deployments sit at the top of the volume ranking, with Edge Computing climbing the fastest as manufacturing quality inspection demands sub-10ms response times.
Technology:
Cost tiers separate commodity toolkits from proprietary architectures, with foundation model development consuming 100x the compute budget of narrow computer vision systems. Natural Language Processing commands the steepest talent premiums, while Robotics integration faces the longest validation cycles.
- Machine Learning:Statistical pattern recognition from structured data underpins credit scoring and demand forecasting. BFSI risk departments in London and Singapore rely on gradient-boosted frameworks for fraud detection, with model interpretability mandates from the UK's FCA driving investment in SHAP-based explanation layers.
- Natural Language Processing:Transformer architectures process unstructured text for contract analysis and clinical documentation. The narrow talent pool for large language model optimization commands compensation premiums exceeding 40% above conventional software engineering roles, concentrating development in Seattle and San Francisco Bay Area clusters.
- Computer Vision:Convolutional neural networks inspect sub-3nm wafers in Taiwan and South Korea foundries.
- Robotics:Physical actuation combined with perception stacks faces extended safety certification timelines in automotive assembly.
Machine Learning captures the largest installed base, with Natural Language Processing gaining share fastest as enterprise copilot deployments scale.
End User:
Application maturity varies sharply by sector, with Healthcare and BFSI operating under formal regulatory frameworks while Manufacturing and Retail self-certify against operational KPIs. Procurement committee sophistication determines whether buyers demand algorithmic audit trails or accept vendor attestations.
- Healthcare:Diagnostic imaging and drug discovery applications pull compute budgets from legacy IT into inference-heavy GPU clusters. EU AI Act high-risk system designations and FDA premarket pathways force algorithmic transparency investments, embedding technical documentation teams alongside product engineering at European radiology AI vendors.
- BFSI:Real-time transaction monitoring and regulatory reporting consume the bulk of operational AI spending. Federated learning architectures enable model training across bank networks without centralizing sensitive transaction data, opening partnerships between pharmaceutical discovery platforms and hospital networks.
- Manufacturing:Predictive maintenance and quality inspection drive edge AI hardware into production environments.
- Retail:Demand forecasting and personalization engines operate with lighter compliance burdens than regulated sectors.
Healthcare leads in compliance-driven procurement value, with Manufacturing expanding most quickly as computer vision penetrates automotive and electronics assembly lines.
Application:
Customer-facing deployments face stricter oversight than internal analytics, with Autonomous Vehicles subject to NHTSA reporting obligations and Customer Service chatbots triggering EU AI Act transparency requirements. Predictive Analytics in supply chain escapes direct regulation but faces internal governance scrutiny.
- Fraud Detection:Real-time pattern recognition in payment networks combines anomaly detection with rule-based thresholds. BFSI operations in Singapore and London deploy ensemble models flagging transactions for human review, with false positive rates directly impacting customer churn.
- Predictive Analytics:Time-series forecasting for inventory and maintenance scheduling dominates internal enterprise use cases. German automotive plants integrate these systems with millisecond-latency edge infrastructure for just-in-sequence production adjustments.
- Customer Service:Conversational agents handle tier-1 support queries, with EU AI Act disclosure mandates requiring bot identity revelation.
- Autonomous Vehicles:Perception and planning stacks face NHTSA incident reporting and state-level testing permits in California and Arizona.
Fraud Detection holds the largest current deployment base, with Autonomous Vehicles tracing the steepest expansion trajectory as lidar and camera fusion costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between Brussels and Washington is creating compliance-cost arbitrage, pushing AI development investment toward jurisdictions with clearer pre-market pathways. Vendors are fragmenting their architectures to satisfy both EU AI Act conformity assessments and FDA post-market surveillance without cross-border deployment conflicts.
United States
Enterprise software clusters in California and Washington are absorbing inference-heavy GPU capacity for clinical decision-support systems. FDA premarket submission pathways mandate algorithm change control plans that freeze continuous learning updates. The Texas Medical Center in Houston and Mayo Clinic campuses in Minnesota favor on-premise NVIDIA DGX clusters to maintain direct custody of patient data.
China
Domestic cloud providers are scaling foundation model training under SAMR algorithmic recommendation and MIIT deep synthesis provisions. The country's national technology regulators enforce data localization requirements that shape product architecture for vendors serving this market. Yangtze River Delta compute clusters in Shanghai and Hangzhou are expanding training capacity despite CoWoS packaging constraints.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg are deploying millisecond-latency edge AI for quality inspection in cleanroom environments. The EU AI Act's high-risk system designation forces algorithmic audit trail investments alongside product engineering. Stuttgart and Munich industrial zones are driving specialized inference chip design for just-in-sequence production adjustments.
India
Radiology AI vendors are establishing local clinical trial infrastructure under CDSCO streamlined approval timelines for AI-enabled diagnostics. The country's national pharmaceutical regulator offers faster pathways than FDA or EMA processes for algorithmic medical devices. Bangalore and Hyderabad software clusters are attracting federated learning partnerships for pharmaceutical discovery platforms.
United Kingdom
Financial services compliance teams in London are deploying retrieval-augmented generation architectures for real-time regulatory query resolution. The FCA's model interpretability mandates drive investment in SHAP-based explanation layers for fraud detection systems. The Square Mile and Canary Wharf banking clusters are consolidating vendor relationships from point-solution fragmentation to platform-standardization contracts.
Artificial Intelligence (AI) Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with horizontal platform vendors commanding procurement leverage against domain-trained challengers. The vendor base concentrates around three strategic archetypes: GPU-accelerated infrastructure suppliers, cloud-embedded software platforms, and research-to-production pathway integrators. Competitive positioning hardens through M&A activity targeting vertical AI capabilities and strategic partnerships locking exclusive training data access.
Within the infrastructure tier, NVIDIA Corporation anchors GPU supply for training and inference pipelines, while Microsoft exemplifies cloud-embedded platform expansion through Azure consumption-based contracts. Google LLC occupies a research-to-production position bridging DeepMind capabilities with enterprise deployment pathways.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Microsoft |
| Google LLC |
| Amazon Web Services |
| International Business Machines Corporation |
| Intel Corporation |
| Advanced Micro Devices |
| OpenAI |
| Apple |
| Others |
Value Chain & Pricing Dynamics
EU AI Act high-risk system designations gate qualified supply for medical AI vendors, reserving premium-tier pricing access to those bearing algorithmic audit trail investments and locked-model certification costs. This sustainability-linked compliance architecture concentrates margin capture among incumbents with pre-certified architectures while compressing pricing power for continuous-learning challengers.
Pricing Analysis
Distributor margins for enterprise AI software compress at 15-25% for cloud-based consumption contracts versus 30-40% for on-premise perpetual licenses. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic algorithms from uncertified analytical tools and open-source frameworks. Cost compression in the standard tier intensifies because hyperscaler marketplace listings bypass traditional channel markups. Hospital procurement committees in Texas and Florida demonstrate highest price sensitivity, while pharmaceutical discovery platforms in Boston and Basel accept premium positioning for federated learning architectures.
Supply Chain Analysis
India's PLI scheme for semiconductor packaging and China's MIIT domestic-content mandates are reshaping sourcing for AI accelerator assembly, pulling advanced packaging capacity toward Bangalore and Shanghai. Geographic supply concentration centers on Taiwan for TSMC CoWoS advanced packaging, South Korea for HBM memory stacks, and the United States for NVIDIA and AMD chip design. Raw material dependencies draw from neon gas extraction in Ukraine, palladium refining in Russia, and high-purity silicon from Germany. Single-source vulnerability in CoWoS capacity creates 6-9 month order backlogs for training-optimized accelerators. Distribution runs through direct hyperscaler contracts for cloud deployment and systems integrators for on-premise hospital installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU AI Act compliance costs in Brussels run 40-60% above FDA premarket pathway investments in Washington, creating divergent vendor economics across Atlantic deployment strategies.
For Market Incumbents: Hedge against regulatory fragmentation by maintaining parallel validation datasets for EU AI Act conformity assessments and FDA post-market surveillance. Lock exclusive training data partnerships with hospital networks in Texas Medical Center and Mayo Clinic campuses to defend against foundation model challengers. Build backward integration into edge inference chip design for manufacturing quality inspection to capture margin pools escaping cloud commoditization.
For New Entrants and Emerging Players: CDSCO streamlined approval timelines in India open a window for radiology AI vendors to establish clinical trial infrastructure ahead of FDA or EMA processes. Target federated learning architectures for pharmaceutical discovery partnerships as the most penetrable white space, exploiting privacy-preserving demand from hospital networks unwilling to centralize patient data. Pursue go-to-market angles through German automotive OEMs seeking millisecond-latency defect detection for just-in-sequence production adjustments.
For Investors and Strategic Acquirers: Roll-up economics work for vertical AI specialists because horizontal platform vendors lack domain-trained model architectures for semiconductor defect detection and agricultural monitoring. Over a 5-10 year viability window, acquire targets with locked-model FDA clearances or EU AI Act pre-certifications rather than continuous-learning pipelines. Watch TSMC CoWoS capacity expansion announcements as the signal indicating whether training accelerator supply constraints ease or intensify.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Change Control Investment | Locked-model architectures satisfy FDA premarket requirements for diagnostic imaging systems. |
| Federated Learning Partnership | Privacy-preserving training opens pharmaceutical discovery contracts without centralizing hospital data. |
| Edge Inference Chip Design | Specialized hardware captures German automotive demand for sub-10ms quality inspection response. |
| EU Sovereign Data Residency | Cloud deployments handling high-risk personal data require localized infrastructure under EU AI Act. |
| Retrieval-Augmented Generation Deployment | Financial services compliance teams in London deploy modular architectures for regulatory query resolution. |
Study Parameters
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts managers, and pharmaceutical discovery platform executives grounded qualitative assessment of AI deployment patterns. Secondary validation drew from FDA 510(k) filings, EU AI Act implementation guidance, hospital procurement databases, and hyperscaler capex disclosures. Bottom-up triangulation against top-down regulatory impact modeling ensured segmentation integrity across deployment modes and end-user verticals.
Bottom-up volume builds aggregated installed base estimates for NVIDIA DGX clusters, Azure AI consumption contracts, and edge inference chip shipments across German automotive plants and Taiwanese foundries. Segmentation dimensions spanned deployment model, technology tier, end-user vertical, application type, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating EU AI Act compliance cost trajectories and FDA premarket submission velocity across the analysis window.
Revisions become necessary when TSMC CoWoS capacity expansion accelerates, EU AI Act enforcement intensity shifts, or transformer architecture optimization talent pools expand beyond current Seattle and San Francisco Bay Area concentration. Forecasts reflect documented assumptions about regulatory pathway durations and hospital procurement committee consolidation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
AI Dubbing Software Market
Artificial Intelligence (AI)
Artificial Intelligence in Big Data Analysis Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
AI in Life Sciences Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
Global AI in Telecommunication Market
Artificial Intelligence (AI)
Industrial Artificial Intelligence [AI] Market
Artificial Intelligence (AI)
AI Document Generator Market
Artificial Intelligence (AI)
Global Artificial Intelligence-Emotion Recognition Market