
 Artificial Intelligence (AI) Assisted Robots Market | 2026-2036
Artificial Intelligence (AI) Assisted Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) Assisted Robots Market Analysis
Direct-to-factory distribution channels is reshaping how AI-assisted robot vendors reach end users, bypassing traditional systems integrators in automotive and electronics plants. NVIDIA Corporation leverages its GPU-accelerated compute platforms to dominate edge AI inference for robotic perception. ABB anchors its position through integrated controller-software stacks that tighten hardware-software coupling. FANUC Corporation sustains manufacturing scale advantages across its Japanese production bases, competing on unit economics for high-volume industrial deployments.
Artificial intelligence assisted robots integrate neural network-based perception, motion planning algorithms, and adaptive control systems operating at sub-millisecond latencies for real-time decision-making in unstructured environments. Their primary purpose centers on augmenting or replacing human judgment in tasks requiring visual recognition, force-sensitive manipulation, or autonomous navigation across variable conditions. Industrial robots occupy the largest installed base, though collaborative robots represent the fastest-expanding category as safety-certified force-limiting designs penetrate smaller manufacturing footprints. Machine learning underpins most functional advances, while computer vision commands the steepest R&D allocation due to its centrality in pick-and-place, inspection, and surgical guidance applications.
FDA device classifications for surgical and diagnostic robots shape product development timelines and clinical trial requirements in the United States. The EU AI Act imposes risk-tiered conformity obligations on autonomous systems deployed in European manufacturing and healthcare settings, while ISO 10218 and ISO/TS 15066 define collaborative robot safety benchmarks that gate market access across industrialized economies. Stakeholders must track divergence between emerging national AI governance frameworks and existing machinery safety directives to anticipate compliance cost trajectories.
Market Dynamics
Direct-to-factory distribution is compressing traditional systems integrator margins while GPU-accelerated edge inference redefines hardware procurement priorities across automotive and electronics manufacturing corridors.
Growth Catalysts
- EU AI Act Risk-Tiered Obligations:Manufacturers deploying autonomous systems in European healthcare and industrial settings face mandated conformity assessments that accelerate vendor consolidation around certified platform providers.
- Automotive Manufacturing Corridors:Germany, Japan, and the United States drive concentrated demand for adaptive control systems in battery assembly and precision component handling operations.
- Neural Network Perception:Sub-millisecond latency visual recognition capabilities expand addressable tasks from structured pick-and-place to unstructured bin picking and surgical guidance applications.
Market Restraints
- GPU Supply Concentration:NVIDIA's dominance in accelerated compute silicon creates single-source dependency risk for robot perception hardware stacks.
- FDA Device Classification Friction:Surgical robot developers face extended clinical trial timelines and 510(k) or PMA pathway uncertainties that compress commercialization windows.
- ISO/TS 15066 Compliance Costs:Force-limiting collaborative robot certification requires specialized safety engineering that elevates unit economics for smaller manufacturing footprints.
Strategic Opportunities
- Japanese Healthcare Expansion:PMDA regulatory streamlining and METI procurement incentives create favorable conditions for surgical robot vendors targeting aging demographic care automation.
- Computer Vision Convergence:Integration of depth sensing with transformer-based architectures enables zero-shot object recognition that reduces deployment engineering for variable production lines.
- Electronics Plant Channel Disintermediation:Direct vendor-to-factory relationships bypass traditional integrator markups in South Korean and Taiwanese semiconductor packaging facilities.
Industry Challenges
- Motion Planning Talent Scarcity:Shortage of robotics engineers proficient in trajectory optimization and real-time control theory constrains product development velocity.
- Legacy Controller Integration:Retrofitting adaptive AI layers onto installed ABB, FANUC, and KUKA industrial bases requires custom middleware development that extends deployment cycles.
- Multi-Jurisdictional Certification Parallelism:Simultaneous FDA, PMDA, and CE marking pursuit demands redundant testing protocols that strain R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) Assisted Robots Market |
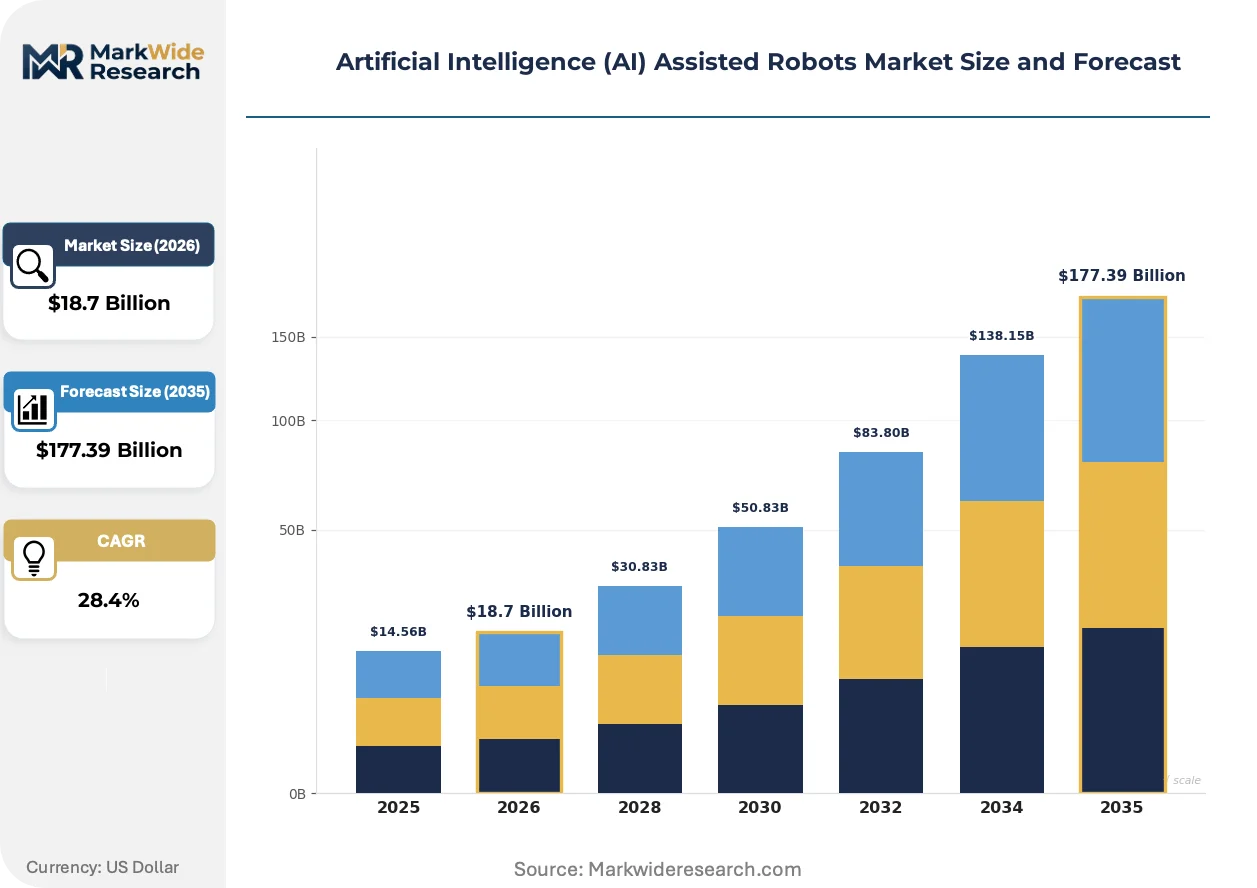
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $177.39 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Industrial Robots, Service Robots, Collaborative Robots, Medical Robots Application: Manufacturing, Healthcare, Logistics, Hospitality End User: Automotive, Electronics, Retail, Aerospace Technology: Machine Learning, Computer Vision, Natural Language Processing, Sensor Fusion |
| Companies Covered | NVIDIA Corporation, ABB, Intel Corporation, Boston Dynamics, Hanson Robotics, FANUC Corporation, KUKA AG, Yaskawa Electric Corporation, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) Assisted Robots Market Emerging Trajectories
Edge AI inference architectures are displacing cloud-dependent processing models while regulatory fragmentation across major economies forces modular compliance engineering into product roadmaps.
Transformer-based visual perception is digitizing robotic scene understanding by enabling real-time segmentation and pose estimation without task-specific training datasets. Automotive battery module manufacturers in Germany and the United States deploy these systems for defect detection at conveyor speeds exceeding human inspection capacity. The technology is digitizing quality assurance workflows by collapsing the engineering time required for new product introduction from weeks to hours.
The EU AI Act's risk-based conformity framework imposes documentation and human oversight mandates on autonomous manufacturing systems deployed in European Union member states. High-risk categorization for collaborative robots in healthcare settings triggers third-party assessment requirements that extend time-to-market by six to eighteen months. German surgical robot developers are responding by front-loading clinical validation and establishing dedicated regulatory affairs functions that parallel engineering teams.
Factory-level technical buyers are consolidating vendor relationships around integrated controller-software stacks that reduce interoperability engineering burden. Traditional systems integrators in Japanese automotive plants lose margin to direct procurement contracts as end-users internalize deployment expertise. This pattern concentrates most visibly in German Mittelstand manufacturing where in-house automation teams now specify complete perception-to-actuation solutions rather than component sourcing.
Artificial Intelligence (AI) Assisted Robots Market Segmentation
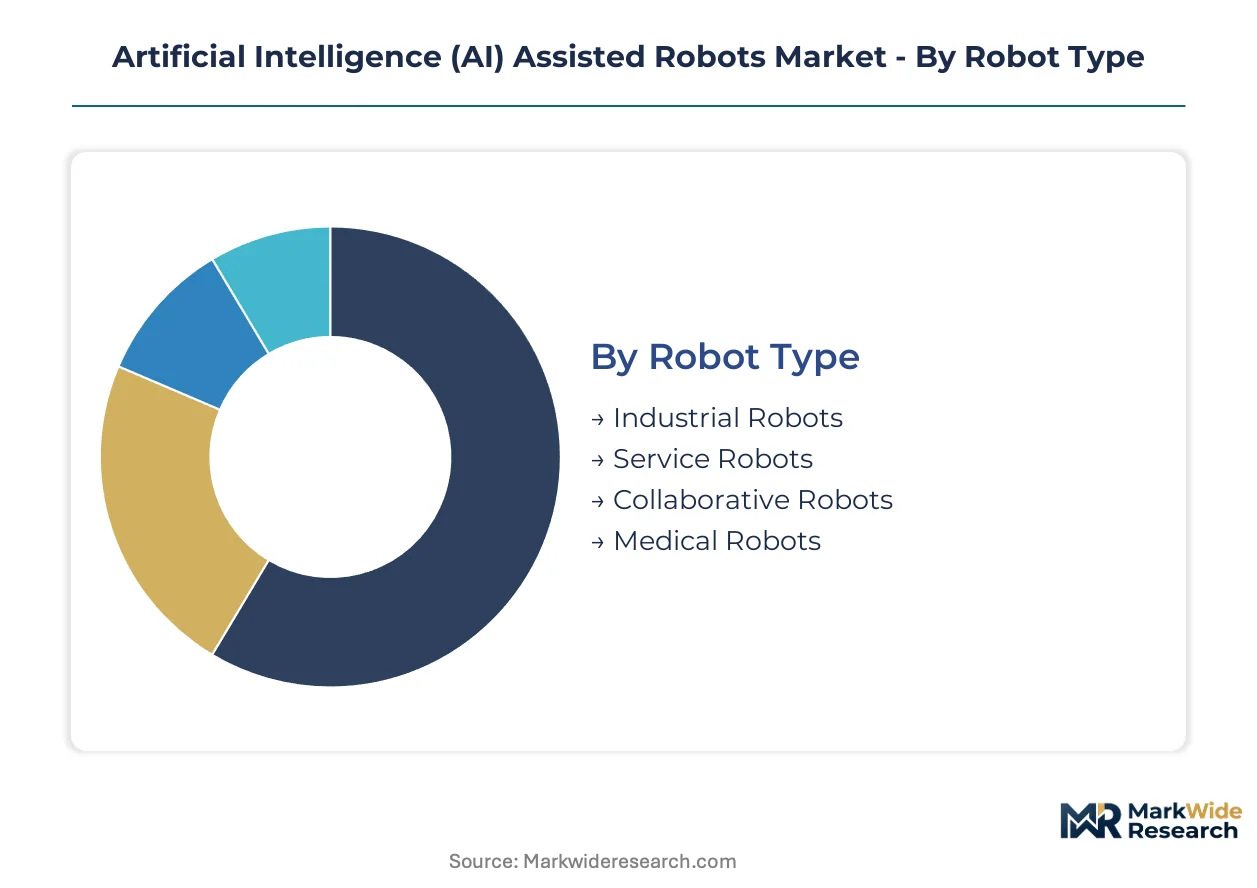
Segmentation in AI-assisted robotics reveals how hardware form factors, deployment environments, and technical architectures shape procurement patterns. Buyers prioritize different capability bundles depending on whether they operate regulated surgical suites or high-throughput automotive lines.
Robot Type:
Cost tier determines how safety certification investments amortize across unit volumes and deployment scales.
- Industrial Robots:Fixed-base articulated arms with sub-millimeter repeatability dominate high-volume welding and painting operations. German automotive OEMs in Bavaria and Baden-Württemberg specify these for battery module assembly where cycle time consistency gates line economics.
- Collaborative Robots:Force-limiting designs with ISO/TS 15066 certification enable fenceless human-robot workflows. Japanese electronics plants in Nagoya and Osaka prefectures deploy these for precision component handling where retooling frequency favors reprogrammable platforms.
- Service Robots:Mobile platforms with SLAM navigation target facility maintenance and security patrolling.
- Medical Robots:FDA Class II and PMDA-regulated systems integrate haptic feedback for surgical teleoperation.
Industrial robots hold installed capacity. Collaborative robots are rotating up the share rankings.
Application:
Application context dictates sensor payload requirements and regulatory exposure severity.
- Manufacturing:Vision-guided pick-and-place and adaptive grinding absorb the majority of GPU-accelerated edge inference deployments. United States battery gigafactories in Nevada and Texas concentrate demand for defect detection at conveyor speeds exceeding human inspection capacity.
- Healthcare:Surgical navigation and diagnostic imaging robots face FDA 510(k) and EU MDR conformity timelines that extend commercialization windows by twelve to twenty-four months.
- Logistics:Autonomous mobile robots with pallet-scale manipulation traverse warehouse aisles for e-commerce fulfillment.
- Hospitality:Guest-facing service robots with natural language interfaces target concierge and delivery functions.
Manufacturing commands current deployment volume. Healthcare is climbing the fastest on revenue per unit metrics.
End User:
Customer type concentration shapes how vendors structure field service networks and spare parts logistics.
- Automotive:Tier-1 suppliers in Germany's Stuttgart region and Japan's Toyota City corridor specify integrated controller-software stacks that reduce interoperability engineering burden.
- Electronics:Semiconductor packaging facilities in South Korea and Taiwan bypass traditional systems integrators through direct vendor procurement contracts.
- Retail:Warehouse automation and in-store inventory scanning drive mobile robot deployments.
- Aerospace:Precision drilling and composite layup applications demand force-sensitive manipulation with real-time adaptive control.
Automotive maintains procurement leadership. Electronics is gaining share fastest through channel disintermediation.
Technology:
Technical architecture selection determines compute hardware procurement priorities and development talent requirements.
- Computer Vision:Transformer-based architectures enable zero-shot object recognition that collapses new product introduction engineering from weeks to hours. Depth-sensing convergence with neural radiance fields expands addressable tasks from structured pick-and-place to unstructured bin picking.
- Machine Learning:Trajectory optimization and predictive maintenance models train on operational data from installed ABB, FANUC, and KUKA bases.
- Natural Language Processing:Voice command interfaces reduce training burden for collaborative robot redeployment.
- Sensor Fusion:Lidar, tactile, and visual input integration enables robust perception in variable lighting conditions.
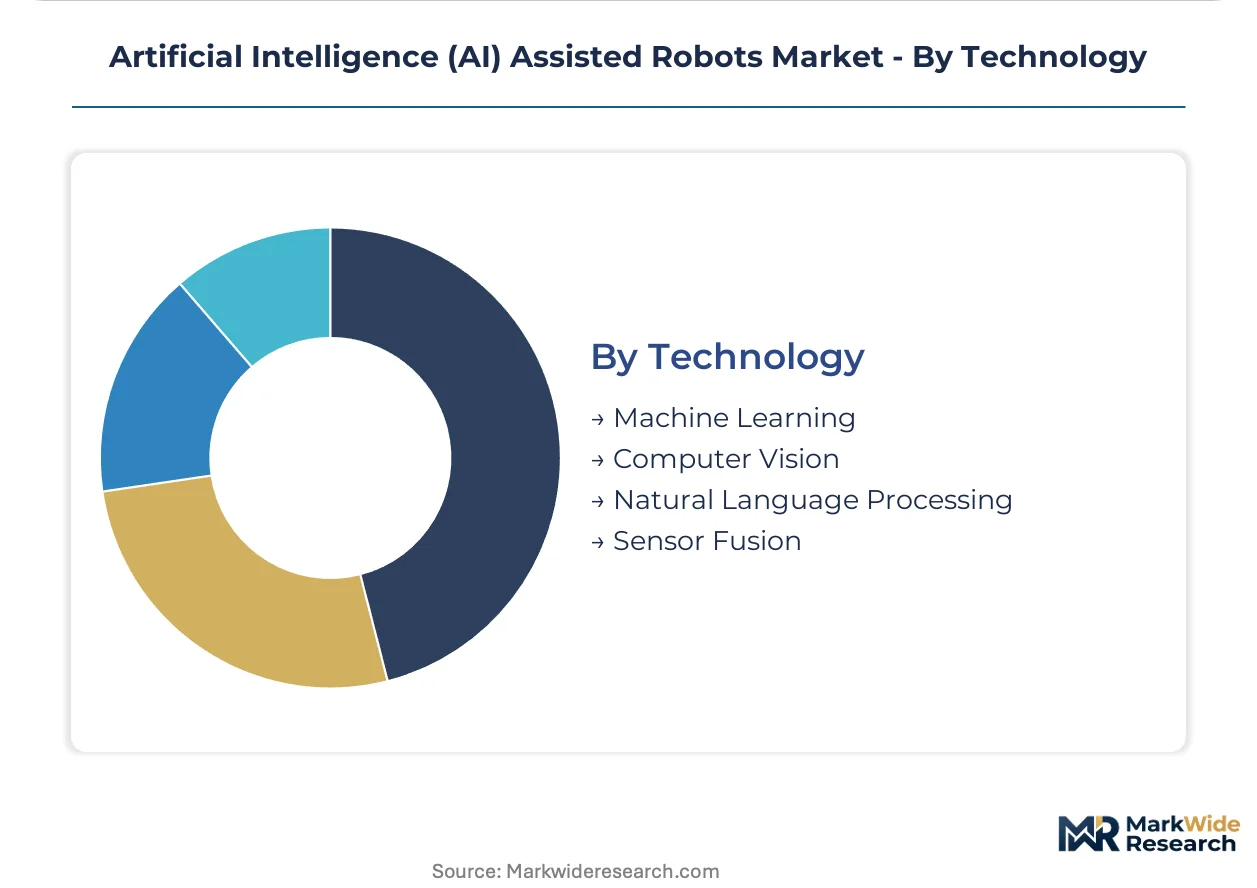
Computer Vision absorbs the steepest R&D allocation. Machine Learning is expanding most quickly through operational data network effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese manufacturing corridors where precision engineering requirements sustain premium procurement, while cost-sensitive electronics assembly in Taiwan and South Korea compresses margins through direct vendor negotiation.
United States
FDA 510(k) pathways for surgical robots and IRA clean energy manufacturing credits drive dual demand streams. The Nevada and Texas battery gigafactory clusters absorb vision-guided defect detection systems at conveyor speeds exceeding human capacity. Automotive OEMs in Detroit and Silicon Valley specify integrated controller-software stacks that reduce interoperability engineering burden.
Germany
EU AI Act risk-tiered conformity assessments and MDR device classification shape procurement priorities for Mittelstand manufacturers. Bavarian automotive suppliers in Stuttgart specify sub-millimeter repeatability systems for battery module assembly where cycle time consistency gates line economics. Baden-Württemberg precision engineering firms front-load clinical validation for surgical robot platforms.
Japan
PMDA regulatory streamlining and METI procurement incentives target aging demographic care automation. Nagoya and Osaka electronics plants deploy ISO/TS 15066-certified collaborative robots for precision component handling where retooling frequency favors reprogrammable platforms. Toyota City corridor tier-1 suppliers consolidate vendor relationships around complete perception-to-actuation solutions.
South Korea
MFDS medical device approval pathways and semiconductor packaging expansion drive specialized demand. Direct vendor-to-factory relationships bypass traditional integrator markups in Busan-Ulsan semiconductor facilities. Seoul Capital Area battery manufacturers specify GPU-accelerated edge inference for adaptive grinding operations.
China
NMPA medical device classifications and MIIT smart manufacturing directives structure domestic procurement. Yangtze River Delta electronics assemblers integrate transformer-based visual perception for zero-shot object recognition that collapses new product introduction engineering from weeks to hours. Pearl River Delta automotive plants absorb collaborative robot deployments for fenceless human-robot workflows.
Artificial Intelligence (AI) Assisted Robots Market Vendor Landscape
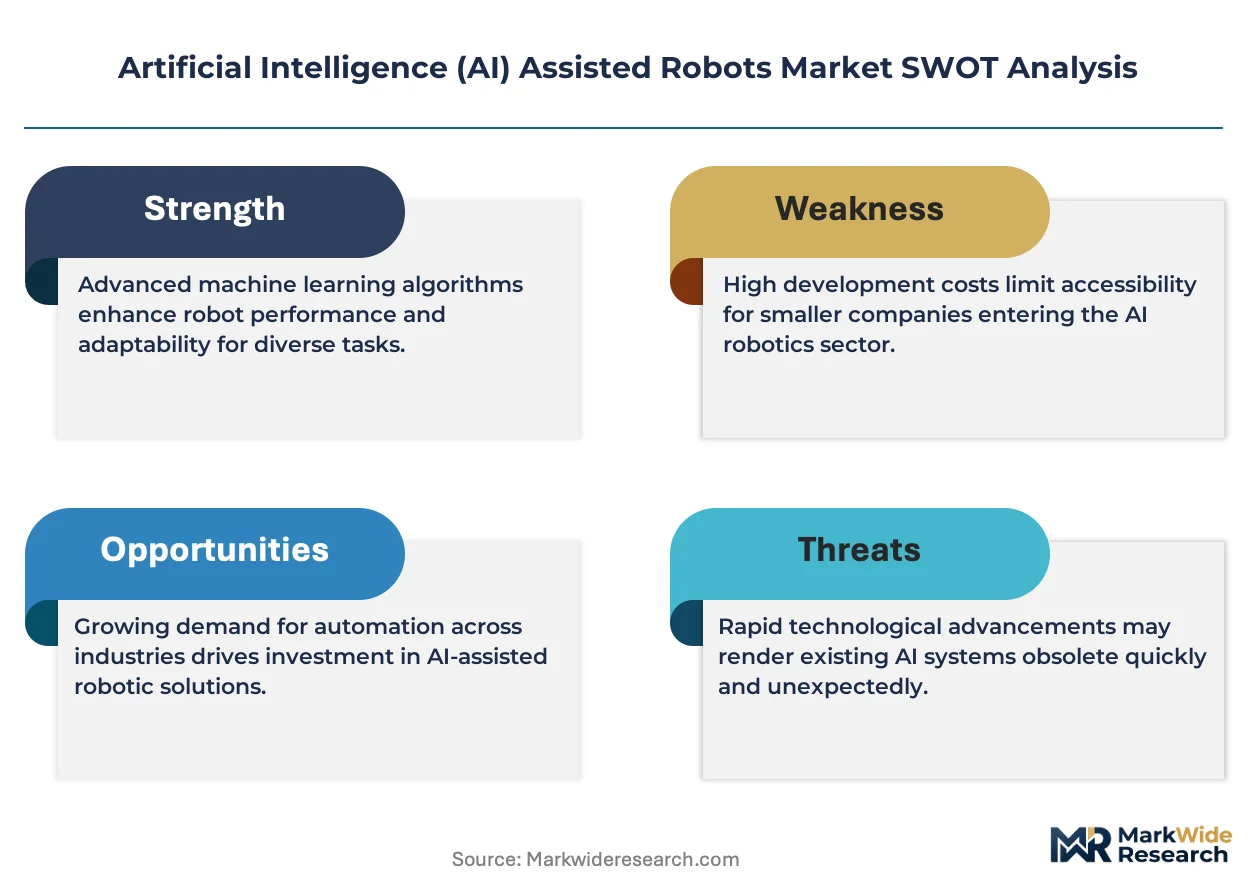
GPU-accelerated compute specialists and integrated controller-software providers split the market along hardware-software coupling fault lines. Structure concentrates around platform vendors with certified regulatory compliance and component suppliers with silicon supply advantages. Two archetypes dominate: edge inference hardware vendors anchoring perception stacks, and industrial automation incumbents tightening hardware-software integration. Competitive moves center on direct-to-factory channel expansion and modular compliance engineering for multi-jurisdictional certification parallelism.
Within the edge inference tier, NVIDIA Corporation exemplifies GPU-accelerated platform dominance, while ABB and FANUC Corporation occupy positions as integrated controller-software providers with manufacturing scale advantages. NVIDIA represents the silicon-specialist archetype where compute hardware procurement priorities reshape vendor selection. ABB anchors the European industrial automation position through hardware-software stack integration. FANUC Corporation sits within the Japanese manufacturing-scale tier competing on unit economics for high-volume industrial deployments.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| ABB |
| Intel Corporation |
| Boston Dynamics |
| Hanson Robotics |
| FANUC Corporation |
| KUKA AG |
| Yaskawa Electric Corporation |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
The Yokohama-Long Beach maritime corridor's container rate volatility feeds directly into landed cost spreads for GPU-accelerated perception hardware, compressing margins for systems integrators while amplifying price differentiation between certified and uncertified robot platforms across German and Japanese automotive plants.
Pricing Analysis
The customization-premium spread between configured-to-order surgical robots and standard collaborative arm units runs three to five multiples, with FDA Class II certification tier and ISO/TS 15066 safety grade as the primary price differentiation drivers. Project-based pricing with embedded software licensing dominates medical deployments, while per-unit transactional models prevail in high-volume automotive pick-and-place applications. Pricing pressure stems from direct-to-factory procurement bypassing traditional integrator markups, with South Korean semiconductor packaging facilities exhibiting the highest buyer price sensitivity and German Mittelstand manufacturers the lowest.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from NVIDIA and Intel have become critical liquidity tools for downstream robot OEMs managing GPU silicon procurement cycles. Component concentration rests on Taiwan for advanced perception chip foundry services, South Korea for memory modules, and Japan for precision servo motors and harmonic drives. Raw material dependencies include rare earth magnets for motor assemblies, high-purity silicon for compute substrates, and specialized aluminum alloys for lightweight arm structures. Single-source vulnerability around NVIDIA's CUDA ecosystem constitutes the dominant supply chain risk. Distribution runs through direct vendor-to-factory contracts in electronics and automotive corridors, displacing traditional systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as transformer-based visual perception collapses new product introduction engineering from weeks to hours, accelerating penetration beyond structured automation into unstructured bin picking and surgical guidance applications.
For Market Incumbents: Build regulatory certification moats by front-loading FDA 510(k) and EU MDR conformity investments ahead of AI Act risk-tiered enforcement timelines. Consolidate channel control through direct-to-factory technical sales teams that displace systems integrators in German automotive corridors. Deepen backward integration into edge inference silicon supply through strategic foundry partnerships, countering GPU supply concentration risk from NVIDIA's dominance. For New Entrants and Emerging Players: Mid-market collaborative robot deployments in Japanese electronics plants represent the most penetrable entry point, where retooling frequency favors reprogrammable platforms and ISO/TS 15066 certification gaps persist among incumbent portfolios. Taiwanese semiconductor packaging facilities offer secondary white-space through direct procurement relationships that bypass established integrator networks. A software-first go-to-market angle emphasizing zero-shot object recognition capabilities reduces deployment engineering barriers against hardware-centric incumbents. For Investors and Strategic Acquirers: Computer vision software specialists with transformer-based architectures and established regulatory affairs functions present the most compelling acquisition target archetype for platform consolidation plays. Long-term viability hinges on differentiation in sub-millisecond latency perception stacks rather than mechanical arm commoditization. Watch for inflection signals in PMDA regulatory streamlining pace and METI procurement incentive disbursement rates as leading indicators of Japanese healthcare automation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Pre-Certification | Front-loaded third-party assessment investments compress time-to-market for high-risk collaborative robot deployments in German healthcare settings. |
| Direct-to-Factory Channel Expansion | Bypassing systems integrators in South Korean semiconductor packaging facilities captures margin compression from procurement disintermediation. |
| Transformer-Based Vision Stack Development | Zero-shot object recognition capabilities collapse new product introduction engineering from weeks to hours for automotive battery manufacturers. |
| GPU Supply Diversification Partnership | Strategic foundry relationships with Intel and emerging silicon vendors reduce single-source dependency risk from NVIDIA's CUDA ecosystem dominance. |
| PMDA Regulatory Affairs Function Buildout | Dedicated clinical validation teams parallel engineering operations to exploit METI procurement incentives targeting Japan's aging demographic care automation. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with robotics R&D directors, automotive plant engineers, hospital purchasing committee members, biomedical equipment specialists, and semiconductor facility automation managers. Secondary validation drew from FDA 510(k) filings, PMDA medical device registration databases, EU MDR conformity assessment records, and hyperscaler GPU capex disclosures. Bottom-up unit shipment estimates across robot type and application segments were triangulated against top-down market value reconstructions derived from OEM revenue disclosures and foundry production allocations.
Calibration against historical penetration curves in comparable automation technologies anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include robot type, application environment, end-user industry, and technology architecture, with additional granularity on regulatory risk tier and compute hardware procurement priority. CAGRs were derived from slope-consistent growth trajectory fitting rather than endpoint anchoring. Industry-specific forecast inputs incorporated GPU supply elasticity parameters and multi-jurisdictional certification parallelism timelines.
Stress conditions across GPU supply disruption severity, EU AI Act enforcement acceleration, and PMDA regulatory streamlining pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding transformer-based perception adoption curves and direct-to-factory channel migration rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Brain Computer Interface Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
AI Recruitment Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Security Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence Based Personalization Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
Smart Virtual Personal Assistants Market
Artificial Intelligence (AI)
AI in Medical Writing Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
No-Code AI Platform Market
Artificial Intelligence (AI)
North America Conversational AI Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market