
 South Africa Data Center Cooling Market | 2026-2036
South Africa Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Data Center Cooling Market Insights
Market Dynamics
Project finance and green bond structures is rewriting competitive access in South Africa data center cooling, allowing infrastructure funds and real estate trusts to enter without heavy balance sheets. Schneider Electric leverages its integrated power and cooling portfolio to anchor large colocation builds in Johannesburg. Vertiv Group Corp. competes through service density and local technical support networks. STULZ GmbH specializes in precision air conditioning systems that dominate enterprise and banking installations.
Technology and Segment Structure
Data center cooling encompasses the engineered systems that remove waste heat from server environments, typically operating across supply air temperatures of 18°C to 27°C per ASHRAE guidelines, with liquid cooling emerging for high-density GPU clusters exceeding 30 kW per rack. Air cooling still occupies the majority of installed base across South Africa's legacy facilities, though liquid cooling is displacing legacy architectures in hyperscale and AI training deployments. Colocation and hyperscale deployment models concentrate capital expenditure and vendor selection power among fewer buyers, compressing procurement cycles.
Regulatory Environment and Outlook
NERSA enforces grid reliability and power quality standards that directly shape backup cooling and thermal storage requirements, while South African building codes and municipal bylaws in Johannesburg, Cape Town, and Tshwane govern water usage for evaporative systems. ISO 50001 energy management certification and local green building council ratings increasingly filter vendor shortlists for enterprise and public sector tenders. Stakeholders must monitor how pending carbon disclosure mandates and renewable energy procurement rules reshape total cost of ownership calculations for cooling infrastructure.
Market Dynamics
Hyperscale cloud expansion in Johannesburg and Cape Town is compressing procurement cycles and forcing cooling vendors to bundle thermal management with power infrastructure under single-contract structures.
Growth Catalysts
- NERSA Reliability Mandates:South Africa's energy regulator enforces power quality standards that compel data center operators to upgrade cooling efficiency and install thermal storage systems.
- GPU Cluster Density:AI training deployments exceeding 30 kW per rack are pulling liquid cooling architectures into hyperscale facilities faster than legacy air systems can adapt.
- Gauteng Province Concentration:Hyperscale facility clustering in Johannesburg creates localized demand spikes that justify dedicated cooling infrastructure investments.
Market Restraints
- Grid Instability Premium:Eskom's load-shedding regime forces operators to oversize backup cooling capacity, inflating capital intensity by 25-40% versus stable-grid comparators.
- Import Equipment Dependency:Precision cooling hardware concentrates manufacturing in Germany and the United States, exposing buyers to currency volatility and extended lead times.
- Water Scarcity Constraints:Municipal bylaws in Cape Town and Tshwane restrict evaporative cooling water draw, limiting deployment of adiabatic systems in drought-prone zones.
Strategic Opportunities
- Western Cape Expansion:Cape Town's submarine cable landing points and cooler ambient temperatures position the region for low-PUE hyperscale development underserved by current cooling supply.
- Green Bond Finance:Project finance structures certified under Climate Bonds Initiative standards unlock institutional capital for cooling retrofits without operator balance-sheet strain.
- Immersion Cooling Convergence:Dielectric fluid systems paired with waste heat recovery are opening district heating revenue streams for colocation operators in dense urban zones.
Industry Challenges
- Thermal Engineer Scarcity:South Africa produces fewer than 50 specialized data center HVAC engineers annually, constraining deployment velocity for complex liquid cooling integrations.
- ISO 50001 Certification Burden:Enterprise and public sector tenders increasingly require energy management certification that smaller cooling contractors cannot obtain within 18-month procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Data Center Cooling Market |
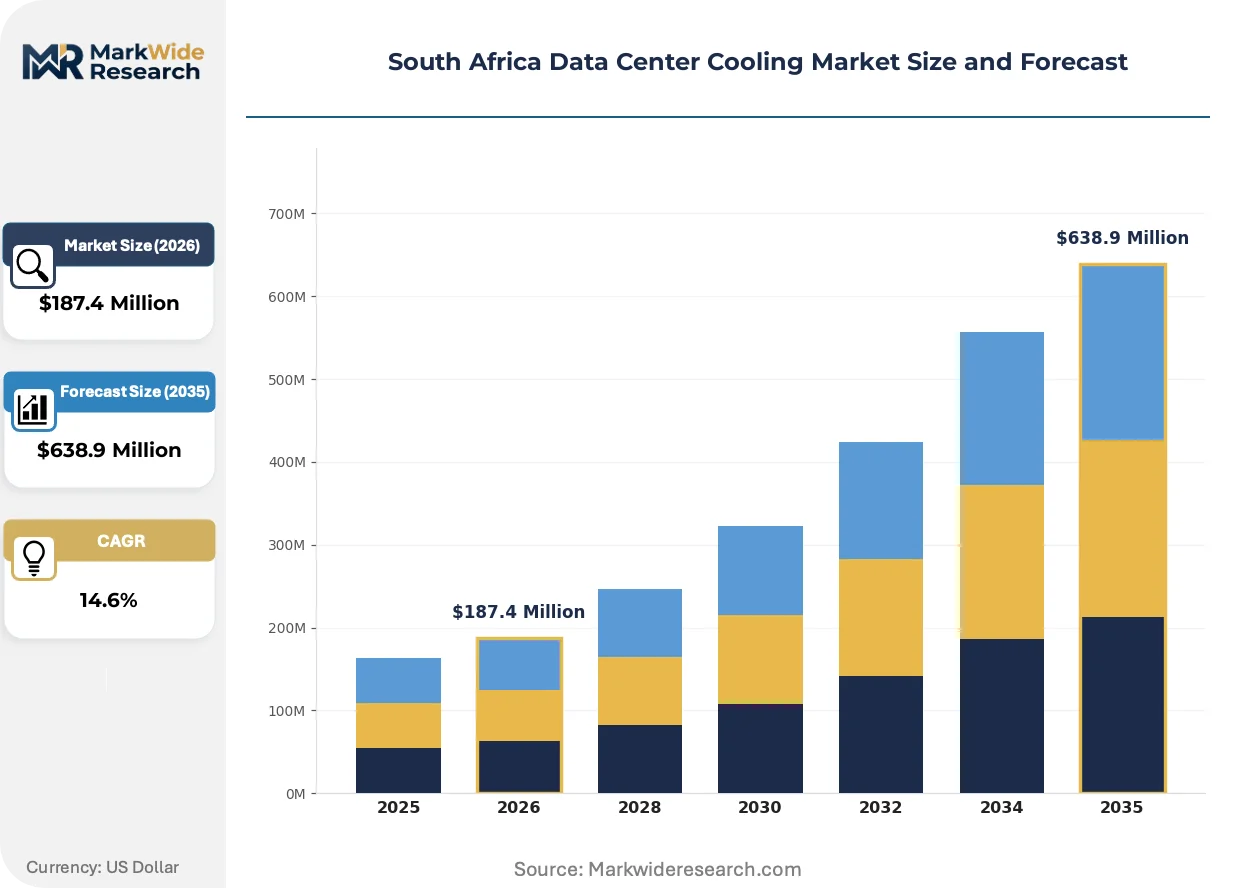
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Technology: Air Cooling, Liquid Cooling, Refrigerant-Based Cooling, Evaporative Cooling End User: Telecommunication, Banking, IT Services, Cloud Providers Capacity: Up to 500 kW, 500 kW to 1 MW, 1 MW to 5 MW, Above 5 MW Deployment Model: On-Premises, Colocation, Edge, Hyperscale |
| Companies Covered | Schneider Electric, Vertiv Group Corp., STULZ GmbH, Rittal GmbH & Co. KG, Johnson Controls International plc, Emerson Electric, Mitsubishi Electric Corporation, Teraco Data Environments, Digital Realty, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Data Center Cooling Market Trends and Innovations
Liquid and air cooling architectures are converging in South African facilities as operators seek thermal flexibility without full infrastructure replacement.
Direct-to-chip liquid cooling is hybridizing with perimeter air handlers in Johannesburg hyperscale builds. Cloud operators deploying NVIDIA H100 clusters are adopting this dual-mode approach to manage 40-50 kW rack densities while retaining legacy air backup. The architecture is compressing vendor selection timelines by allowing phased capital deployment rather than wholesale system replacement.
NERSA's pending carbon disclosure rules for large power consumers will force cooling load transparency in facility reporting. Operators exceeding 1 MW connected load must document thermal energy consumption and backup diesel generator runtime. Enterprise colocation customers are already filtering vendor shortlists for ISO 14001 environmental management certification to preempt compliance exposure.
Buying committees at South African banks and telecom operators are unbundling cooling service contracts from hardware procurement. Facilities managers now contract thermal performance outcomes separately from equipment capex, shifting vendor risk onto uptime guarantees and energy efficiency warranties. This pattern concentrates most visibly in Gauteng's financial services sector where procurement teams have adopted European-style performance contracting templates.
South Africa Data Center Cooling Market Segmentation
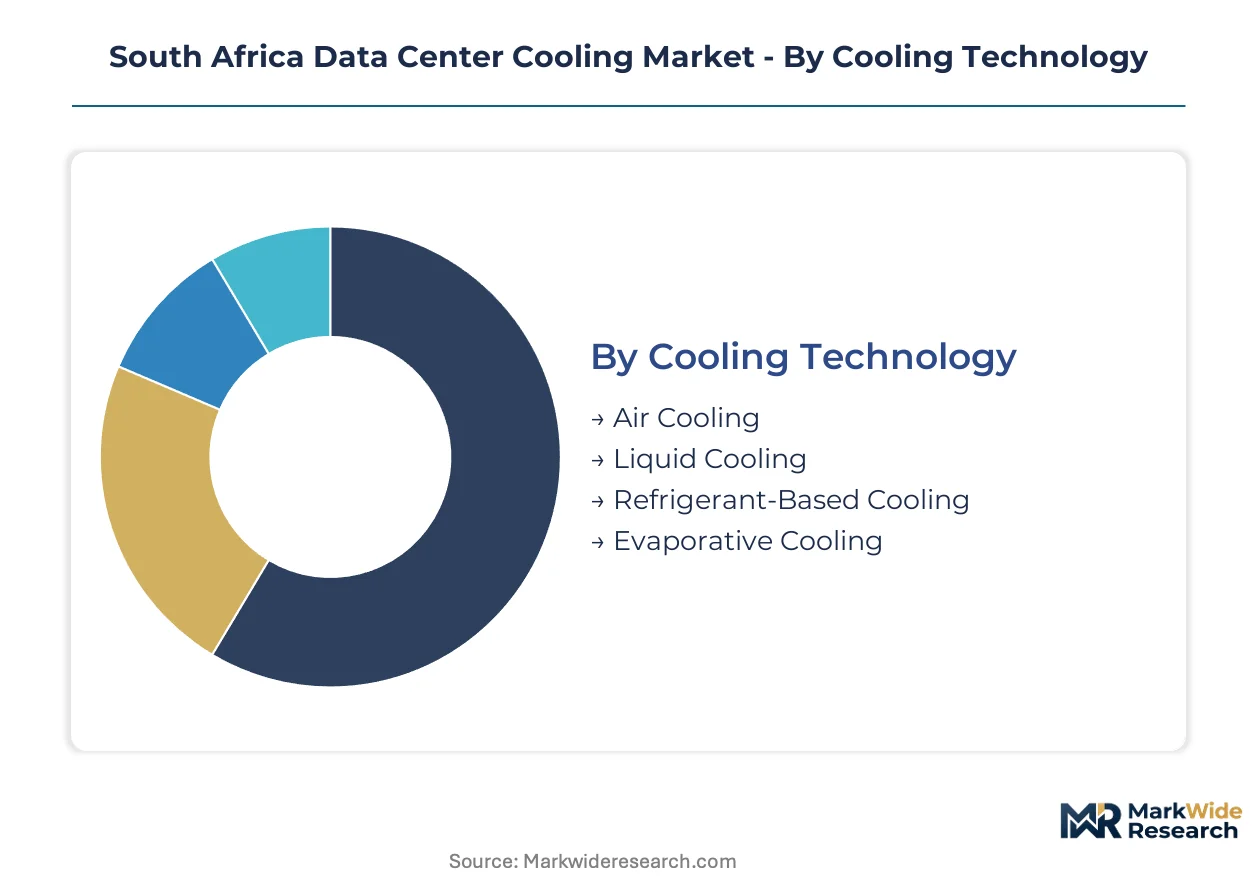
Cooling technology selection in South Africa's data center market hinges on NERSA power reliability mandates, ambient temperature profiles across provinces, and rack density requirements from AI training clusters. Segmentation reveals how procurement power concentrates among hyperscale cloud operators while legacy enterprise facilities lag in thermal infrastructure refresh cycles.
Cooling Technology:
Cost tier differentiation separates established mechanical systems from emerging liquid architectures that command premium capex for density tolerance.
- Air Cooling:Perimeter air handlers and raised-floor distribution dominate legacy facilities across Gauteng's banking and telecom installations. Johannesburg's enterprise data centers retain this architecture for densities below 15 kW per rack where NERSA-mandated efficiency upgrades still permit air-side economizer operation.
- Liquid Cooling:Direct-to-chip and immersion systems address GPU clusters exceeding 30 kW per rack in hyperscale Cape Town and Johannesburg builds. Cloud providers deploying NVIDIA H100 infrastructure specify liquid loops to compress PUE below 1.15 while NERSA carbon disclosure rules force thermal load transparency.
- Refrigerant-Based Cooling:Precision air conditioning units with DX coils serve mid-tier colocation facilities requiring tight humidity control.
- Evaporative Cooling:Adiabatic systems face municipal water restrictions in drought-prone Cape Town and Tshwane despite favorable ambient conditions in Western Cape.
Air cooling commands the established base. The steepest expansion runs through liquid cooling.
End User:
Application type determines procurement sophistication, with financial services demanding ISO 50001-certified thermal performance and cloud operators prioritizing density scalability.
- Telecommunication:Vodacom and MTN operate distributed facilities requiring redundant cooling across provincial edge nodes where grid instability forces 25-40% backup capacity oversizing.
- Banking:FirstRand, Standard Bank, and Absa specify precision cooling with thermal storage integration to satisfy Basel operational risk frameworks and NERSA power quality standards.
- IT Services:Systems integrators and managed service providers favor modular cooling architectures that scale with contract renewals.
- Cloud Providers:Amazon Web Services, Microsoft Azure, and Google Cloud compress procurement cycles through bundled power-cooling contracts in Johannesburg and Cape Town hyperscale campuses.
Banking retains the deepest installed base. Cloud providers are climbing the fastest.
Capacity:
Volume thresholds align with facility lifecycle stage, from enterprise server rooms through dedicated hyperscale buildings.
- Up to 500 kW:Enterprise server rooms and branch data closets in South Africa's banking and retail sectors deploy split-system precision cooling with limited redundancy.
- 500 kW to 1 MW:Mid-market colocation facilities in Durban and Port Elizabeth concentrate procurement among local mechanical contractors.
- 1 MW to 5 MW:Regional cloud availability zones and financial services primary sites specify redundant chiller plants with N+1 configuration.
- Above 5 MW:Hyperscale campuses in Johannesburg's Waterfall City and Cape Town's Atlantic Seaboard justify dedicated cooling infrastructure with district heat recovery potential.
Sub-megawatt facilities command the established base. The steepest expansion runs through above-5 MW hyperscale builds.
Deployment Model:
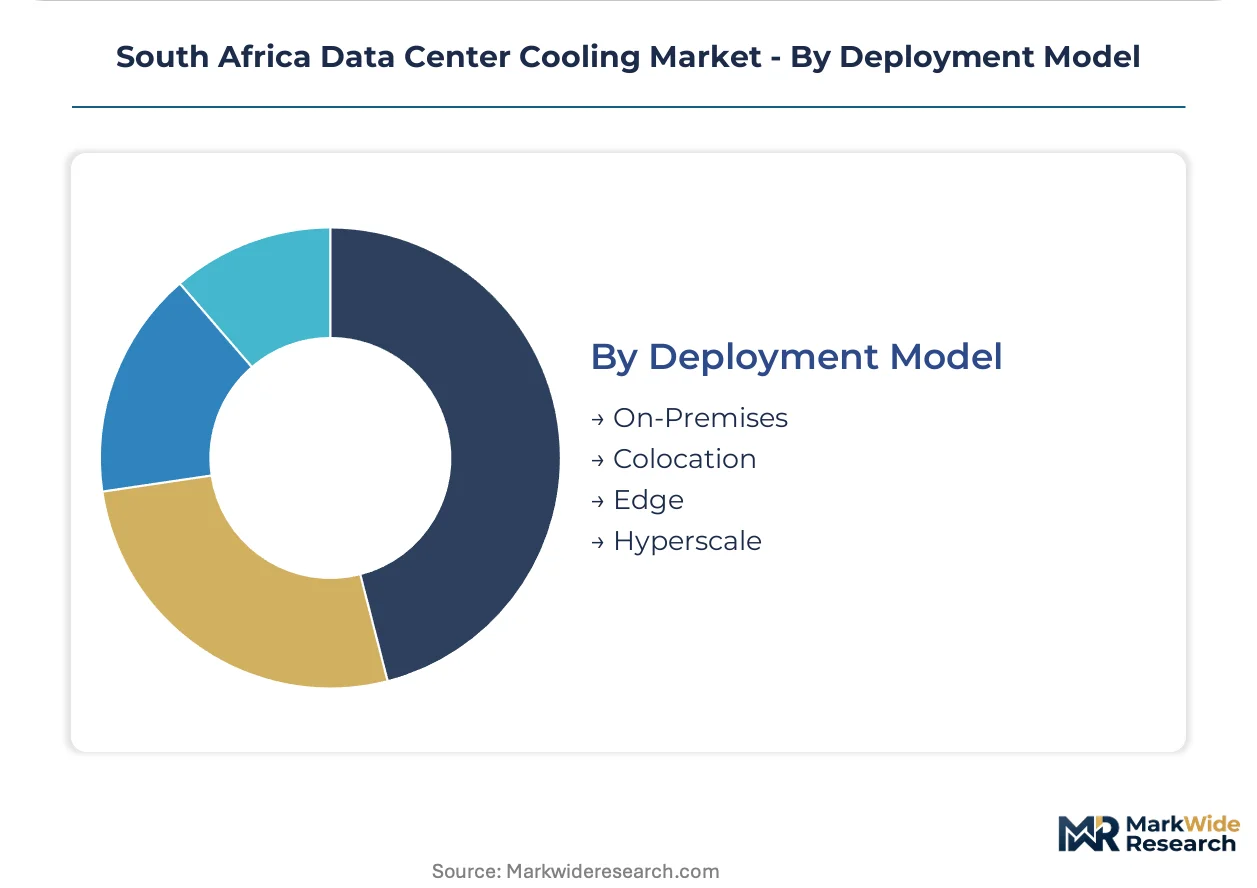
Customer type determines capital structure, risk allocation, and vendor relationship intensity across the thermal infrastructure lifecycle.
- On-Premises:Enterprise-owned facilities in South Africa's mining and manufacturing sectors retain legacy air-cooled architectures with limited refresh budgets.
- Colocation:Teraco, Africa Data Centres, and Vantage Data Centers bundle thermal performance guarantees into power purchase agreements, shifting operational risk from tenants.
- Edge:Distributed compute nodes for autonomous vehicles and industrial IoT specify ruggedized cooling systems for uncontrolled environments in Mpumalanga and Northern Cape.
- Hyperscale:Cloud operators deploy liquid cooling with waste heat recovery in dense urban zones where municipal district heating infrastructure exists.
On-premises retains the deepest installed base. Hyperscale is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NERSA's power reliability mandates and municipal water restrictions are redrawing data center cooling deployment patterns across South Africa's provinces. Cloud operators prioritize locations with grid stability and favorable ambient temperatures.
Gauteng Province
Johannesburg's hyperscale clustering concentrates cooling demand in Waterfall City and Midrand corridors. NERSA enforces strict power quality standards that compel thermal storage integration. Banking and telecom facilities dominate the installed base, with FirstRand and Standard Bank driving precision cooling specifications.
Western Cape
Cape Town's submarine cable landing points attract cloud expansion despite municipal water bylaws restricting evaporative systems. Cooler ambient temperatures enable low-PUE air-side economizer operation. The Atlantic Seaboard corridor is emerging as a hyperscale target zone underserved by current cooling infrastructure.
KwaZulu-Natal
Durban's port infrastructure positions the province for import-dependent equipment distribution. Mid-market colocation facilities concentrate procurement among local mechanical contractors. Humid subtropical climate limits free cooling hours, favoring refrigerant-based precision systems.
Eastern Cape
Port Elizabeth's industrial base supports manufacturing and logistics data center demand. Grid instability forces 25-40% backup cooling oversizing per Eskom's load-shedding regime. Provincial government tenders increasingly filter for ISO 50001-certified thermal performance.
Free State
Bloemfontein's central location appeals to edge computing nodes serving agricultural and mining IoT applications. Lower land costs attract distributed facility planning. Limited municipal water infrastructure constrains adiabatic cooling deployment in this drought-prone zone.
South Africa Data Center Cooling Market Competitive Landscape
Channel-controlling players compete with product-specialist players across South Africa's data center cooling market. Integrated power-cooling portfolios anchor large colocation builds, while precision air conditioning specialists dominate enterprise banking installations. Two strategic archetypes define competitive positioning: full-stack infrastructure vendors bundling thermal and electrical systems, and component specialists leveraging local technical density. M&A activity concentrates on acquiring regional service networks, while green bond finance structures enable new entrants without heavy balance sheets.
Within the integrated infrastructure tier, Schneider Electric and Vertiv Group Corp. exemplify channel-controlling strategies through bundled procurement contracts. STULZ GmbH represents the precision-specialist archetype, occupying a position in enterprise and financial services segments where tight humidity control commands premium positioning. These three anchors illustrate how vendor selection power concentrates among hyperscale cloud operators while legacy facilities lag in refresh cycles.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv Group Corp. |
| STULZ GmbH |
| Rittal GmbH & Co. KG |
| Johnson Controls International plc |
| Emerson Electric |
| Mitsubishi Electric Corporation |
| Teraco Data Environments |
| Digital Realty |
| Others |
Pricing and Supply Chain Analysis
German and US precision cooling equipment manufacturing concentrates upstream capability, anchoring margin capture in compressor assemblies and control systems while South African operators absorb currency volatility and extended procurement cycles.
Pricing Analysis
Certification level creates the primary spread across South Africa's data center cooling market. ISO 50001 energy management certification commands premium positioning in enterprise and public sector tenders, while uncertified mechanical contractors compete on price in sub-megawatt colocation builds. Cost compression in air-cooled legacy systems is intensifying because hyperscale operators are bundling thermal and power infrastructure under single-contract structures. Banking and financial services facilities show least price sensitivity due to Basel operational risk frameworks mandating thermal storage integration.
Supply Chain Analysis
Precision cooling hardware feeds from manufacturing clusters in Germany, the United States, and China. Compressor assemblies, refrigerant charge systems, and building management controllers draw from these upstream nodes. Single-source vulnerability concentrates in specialized HVAC engineering talent, with South Africa producing fewer than 50 qualified data center thermal engineers annually. Distribution runs through Teraco, Africa Data Centres, and Vantage Data Centers, which bundle thermal performance guarantees into power purchase agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's data center cooling market sits in early-cycle expansion as NERSA reliability mandates and GPU cluster density above 30 kW per rack force infrastructure replacement across legacy facilities.
For Market Incumbents: Insulate service revenue streams by deepening technical support density in Gauteng's hyperscale corridors. Schneider Electric and Vertiv Group Corp. should anchor bundled power-cooling contracts before green bond finance structures enable institutional capital entry. Local certification investment in ISO 14001 environmental management preempts NERSA's pending carbon disclosure rules. For New Entrants and Emerging Players: Cape Town's Atlantic Seaboard corridor represents the most penetrable entry point, underserved by current cooling supply despite submarine cable landing points and favorable ambient temperatures. Mid-market colocation facilities in Durban and Port Elizabeth offer secondary white-space where local mechanical contractors dominate procurement. A performance-contracting go-to-market angle mirrors European templates already adopted by Gauteng financial services procurement teams. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across above-5 MW hyperscale builds as liquid cooling with waste heat recovery becomes standard. Regional service networks with NERSA-compliant thermal storage integration capability represent the priority acquisition archetype. The signal to watch is green bond issuance volume certified under Climate Bonds Initiative standards, which unlocks institutional capital without operator balance-sheet strain.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Storage Integration | NERSA power quality standards in Johannesburg force backup cooling capacity upgrades across banking facilities. |
| Liquid Cooling Deployment | Direct-to-chip systems address NVIDIA H100 clusters exceeding 40 kW per rack in Cape Town hyperscale builds. |
| Green Bond Finance Structuring | Climate Bonds Initiative certification unlocks institutional capital for cooling retrofits without operator balance-sheet strain. |
| Performance Contracting Adoption | European-style thermal outcome contracts shift vendor risk onto uptime guarantees in Gauteng financial services procurement. |
| Waste Heat Recovery Installation | Dielectric fluid systems open district heating revenue streams for colocation operators in dense urban zones. |
Research Methodology
Operator-level perspectives from data center facility managers, thermal engineering consultants, NERSA regulatory officers, colocation procurement leads, and hyperscale cloud infrastructure planners anchored the qualitative base. Primary interview findings triangulated against Eskom grid reliability disclosures, municipal water restriction bylaws in Cape Town and Tshwane, hyperscaler capex announcements, and ISO certification registry data. Bottom-up equipment shipment analysis and top-down facility construction tracking converged on segment-level estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity bands reflecting grid stability assumptions and GPU cluster density adoption curves. Segmentation dimensions modeled include cooling technology type, end-user vertical, capacity tier, and deployment model. CAGRs derived from equipment replacement cycles tied to NERSA mandate compliance deadlines and AI training infrastructure rollout schedules.
Macroeconomic conditions sit as an overlay; deviation in rand-dollar exchange rates, Eskom load-shedding severity, or global semiconductor equipment lead times would shift the trajectory. Cross-checking against hyperscaler announced facility openings and green bond issuance pipelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
Sweden Data Center Cooling Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
China Data Center Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
Austria Data Center Cooling Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
Europe Data Center Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
Middle East District Cooling Market