
 US Transcription Market | 2026-2036
US Transcription Market Size, Share, and Industry Trends Forecast 2026-2036
US Transcription Market Intelligence
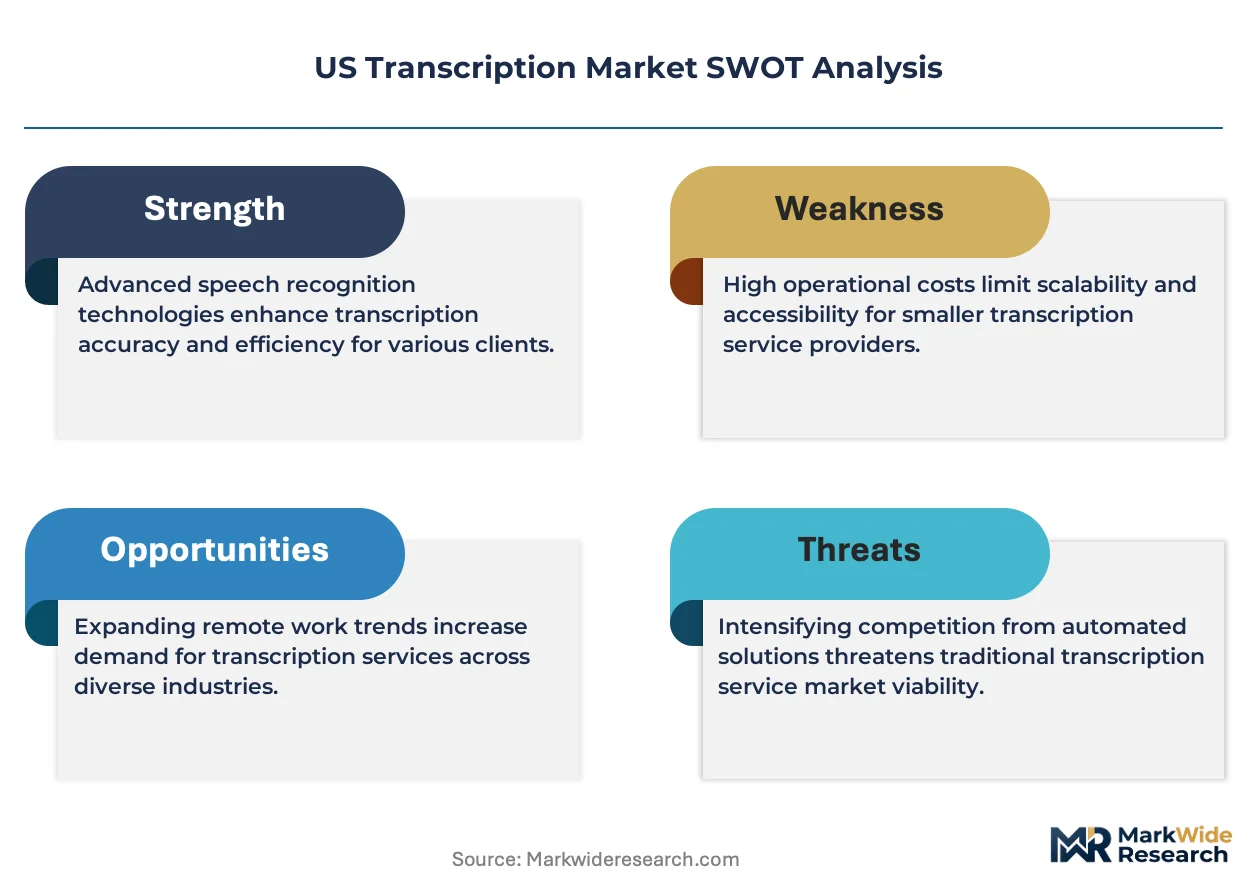
Subscription-based software-defined transcription layers is rebalancing how vendors monetize audio-to-text workflows. Verbit leverages proprietary adaptive speech recognition to sustain technology leadership in enterprise verticals. Rev anchors its position through crowdsourced human-in-the-loop quality control, while TranscribeMe specializes in medical-grade documentation for HIPAA-regulated health systems.
US transcription converts spoken audio into structured text through automated speech recognition engines, human stenography, or hybrid AI-assisted workflows, with output accuracy thresholds typically exceeding 99% for medical and legal applications. Medical transcription commands the largest service-type segment due to chronic documentation burdens in electronic health record systems. AI-based solutions represent the fastest-expanding technology category as natural language processing models reduce per-minute processing costs. Cloud-based delivery modes now dominate enterprise procurement, displacing legacy on-premise installations.
FDA documentation requirements for clinical trial transcripts and HIPAA privacy rules enforced by the Office for Civil Rights shape product standards and liability frameworks across healthcare transcription vendors. State-level medical board regulations in California, Texas, and New York impose additional certification requirements on clinical documentation providers. Stakeholders must monitor evolving FTC guidance on AI-generated transcript accuracy claims and state attorney general enforcement patterns affecting automated speech-to-text liability.
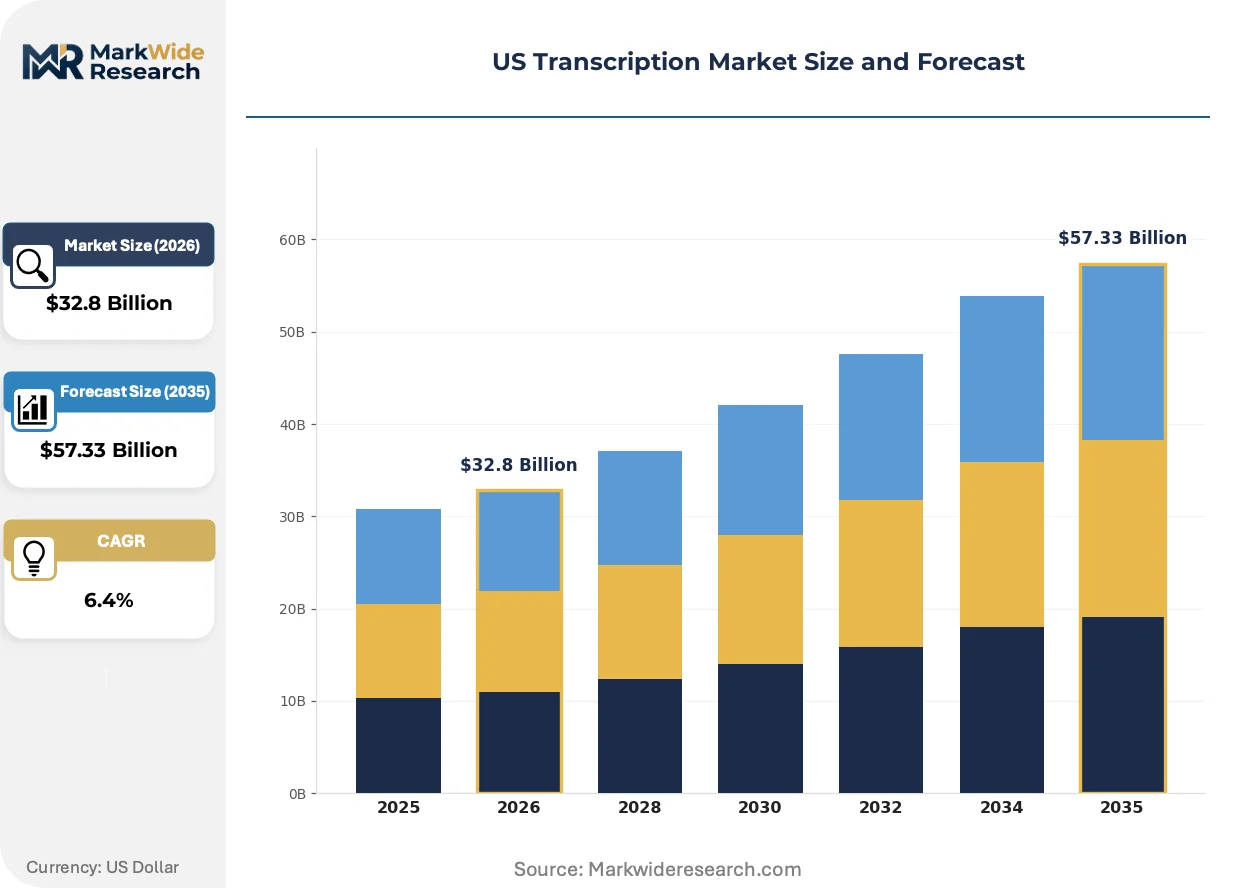
Market Dynamics
AI speech recognition engines are compressing transcription economics while HIPAA enforcement tightens liability frameworks for clinical documentation vendors across California, Texas, and New York health systems.
Growth Catalysts
- HIPAA Privacy Rule Enforcement:The Office for Civil Rights mandates auditable transcript security protocols, compelling health systems to upgrade from legacy dictation workflows to encrypted cloud-based documentation platforms.
- Electronic Health Record Burdens:Clinician documentation time constraints in ambulatory and acute care settings drive procurement of automated speech-to-text tools integrated with Epic and Cerner systems.
- Natural Language Processing Advances:Transformer-based models reduce medical terminology error rates below human baseline, accelerating enterprise adoption of AI-first transcription stacks.
Market Restraints
- Compute Cost Volatility:GPU cluster pricing for real-time inference creates margin pressure on vendors operating cloud-native transcription services at enterprise scale.
- Specialized Labor Concentration:Certified medical transcriptionists cluster in Florida and Arizona retirement corridors, creating geographic supply bottlenecks during demand spikes.
- Regulatory Fragmentation:California medical board certification requirements diverge from Texas and New York standards, forcing multi-state vendors to maintain parallel compliance architectures.
Strategic Opportunities
- Rural Health Clinic Penetration:Federally qualified health centers in Mississippi and Alabama remain underpenetrated by automated transcription, presenting first-mover expansion potential.
- Behavioral Health Documentation:Psychiatric and substance abuse treatment facilities generate rising transcription volumes as parity laws expand reimbursement for mental health services.
- FTC AI Accuracy Guidance:Emerging federal standards on algorithmic performance claims create compliance moats for vendors with validated accuracy benchmarking.
Industry Challenges
- Clinical NLP Specialist Scarcity:Vendors compete for machine learning engineers with biomedical informatics training, compressing development timelines for domain-specific models.
- EHR Integration Complexity:Health system IT departments demand HL7 FHIR-compliant APIs, requiring substantial engineering investment for transcription platform interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Transcription Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Medical Transcription, Legal Transcription, Business Transcription, Academic Transcription Technology: Speech Recognition, Manual Transcription, AI-Based Solutions, Cloud-Based Solutions End User: Healthcare Providers, Law Firms, Corporations, Educational Institutions Delivery Mode: Online, Offline, On-Demand, Real-Time |
| Companies Covered | Verbit, LexTranscribe, Rev, Mediscribes, Integreon, GoTranscript, HappyScribe, Oris Technologies, TranscribeMe, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Transcription Market Strategic Shifts & Innovations
Adaptive speech recognition architectures are redefining performance benchmarks while regulatory scrutiny intensifies around algorithmic accountability in clinical settings.
Transformer-based medical speech models is absorbing transcription workloads previously reserved for human specialists. Large health systems in California deploy these engines for emergency department documentation. The technology is absorbing routine discharge summary generation, compressing per-case labor costs and reallocating clinical staff to complex cases requiring interpretive judgment.
FDA documentation requirements for clinical trial transcripts now mandate timestamped chain-of-custody records for regulatory submissions. Pharmaceutical sponsors must demonstrate transcript integrity from audio capture through archival storage. Oncology and rare disease trial sponsors face the steepest compliance burden, driving investment in audit-ready transcription infrastructure.
Subscription pricing for transcription APIs now dominates enterprise procurement, displacing per-minute transactional models. Health system purchasing departments negotiate annual contracts with usage tiers and accuracy guarantees. This shift is most visible in Texas and New York integrated delivery networks consolidating vendor relationships under master service agreements.
US Transcription Market Segmentation
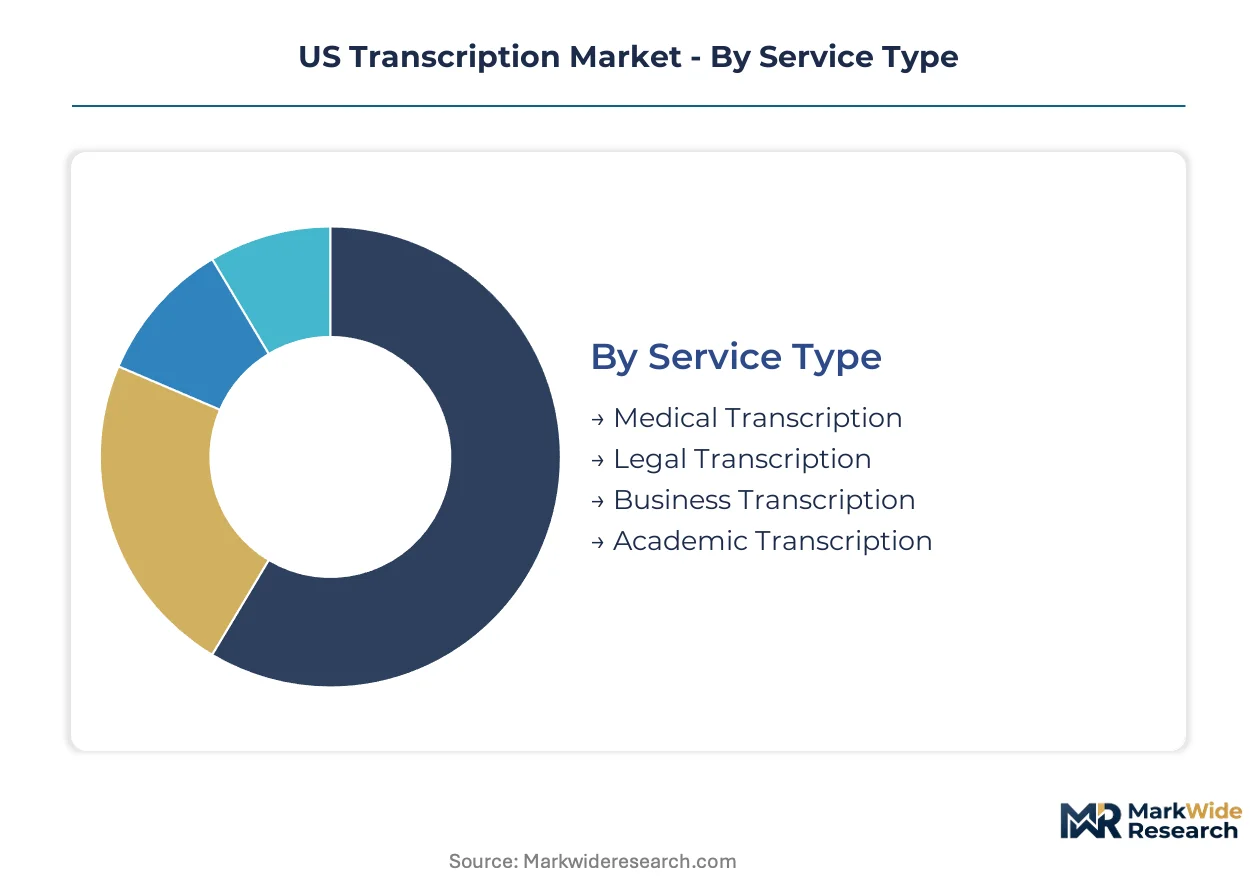
Segmentation reveals how capital intensity, regulatory exposure, and technology maturity fragment procurement patterns across US transcription buyers. Health systems in California and Texas drive divergent technology choices based on HIPAA enforcement stringency and EHR integration budgets.
Service Type:
Medical transcription demands the heaviest upfront investment in HIPAA-compliant infrastructure and certified workforce pipelines, while legal transcription requires specialized stenography certification networks.
- Medical Transcription:Converts physician dictation into structured EHR documentation with ICD-10 coding integration. Epic and Cerner deployments in California and Texas health systems absorb the largest contract volumes as clinician documentation burdens intensify under value-based reimbursement.
- Legal Transcription:Produces verbatim court records and deposition transcripts with certified notarization chains. Manhattan and Chicago litigation boutiques sustain premium pricing for rush turnaround on complex commercial disputes.
- Business Transcription:Supports earnings calls, board meetings, and regulatory filings with standardized formatting.
- Academic Transcription:Delivers lecture capture and research interview documentation for university disability services and qualitative research teams.
Most installed capacity flows through medical transcription. Expansion is steepest in legal transcription as litigation finance growth drives deposition volume.
Technology:
Cloud deployment models concentrate capital expenditure in GPU clusters and API infrastructure, while manual transcription shifts cost structure toward labor certification and quality assurance layers.
- AI-Based Solutions:Deploy transformer architectures for medical terminology recognition with sub-5% word error rates. Health systems in New York and Texas pilot these engines for emergency department documentation, reallocating human editors to complex cases.
- Cloud-Based Solutions:Deliver API-accessible transcription with elastic scaling and subscription metering. Enterprise procurement in California favors these platforms for HL7 FHIR integration with existing Cerner installations.
- Speech Recognition:Legacy engine technology with narrower domain adaptation than modern neural approaches.
- Manual Transcription:Human stenography and transcriptionist workflows for certification-required legal and medical documentation.
Cloud-based solutions carry the dominant installed base. AI-based solutions are climbing the fastest as NLP model accuracy crosses clinical usability thresholds.
End User:
Healthcare providers impose the steepest compliance architecture requirements, while law firms prioritize turnaround speed and chain-of-custody documentation.
- Healthcare Providers:Hospitals and health systems requiring HIPAA audit trails and EHR integration. California integrated delivery networks and Texas rural health clinics represent contrasting procurement maturity levels.
- Law Firms:Litigation practices and corporate legal departments demanding certified transcripts with timestamped integrity for appellate records.
- Corporations:Fortune 500 compliance and investor relations teams for earnings call documentation.
- Educational Institutions:University accessibility offices and research departments for lecture capture and qualitative data processing.
Healthcare providers absorb the majority of installed transcription capacity. Law firms show the steepest expansion trajectory as litigation volume climbs and court reporter shortages intensify.
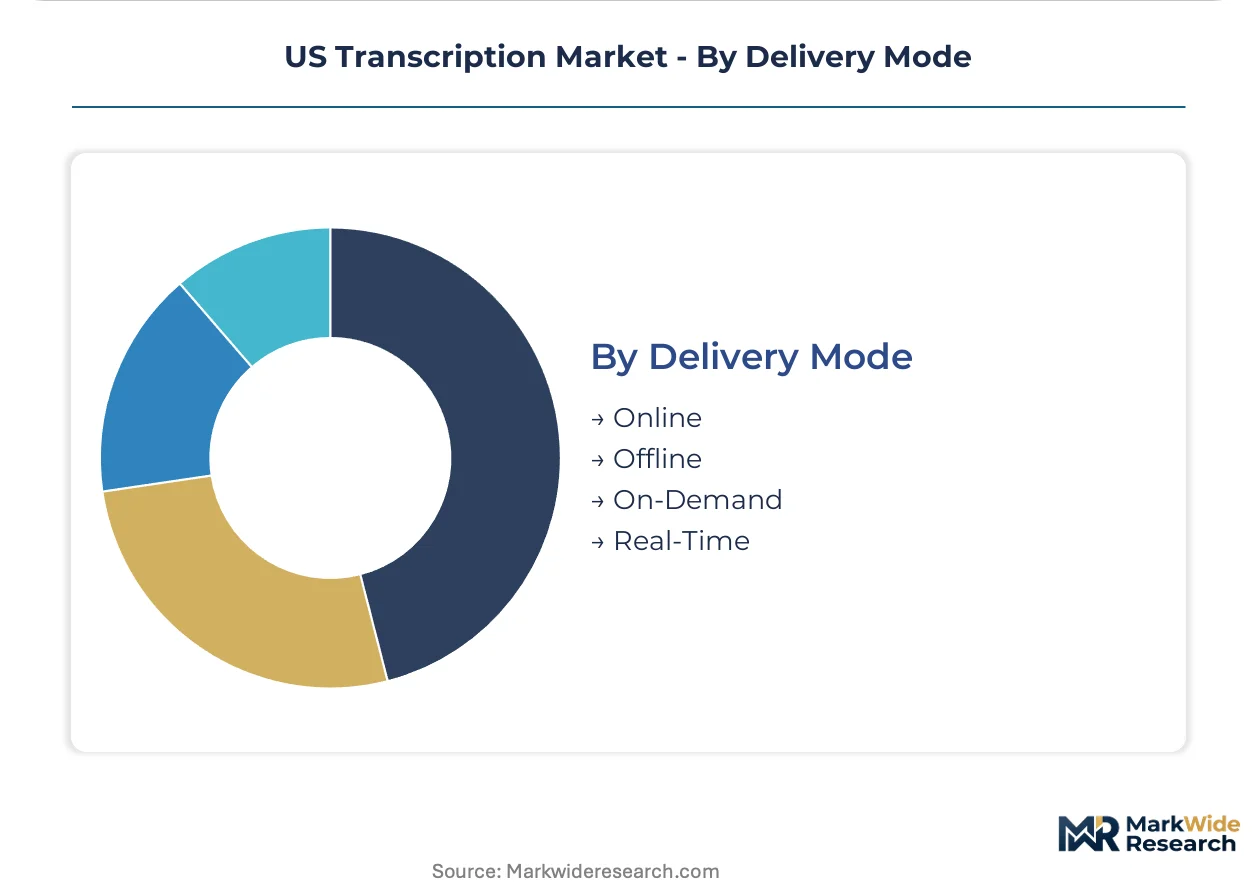
Delivery Mode:
Real-time infrastructure demands continuous GPU availability and low-latency edge deployment, while on-demand models optimize for batch processing economics.
- Real-Time:Live transcription for court proceedings, broadcast captioning, and telemedicine encounters with sub-second latency requirements. California court systems and Texas health systems pilot these deployments for accessibility compliance.
- On-Demand:API-triggered transcription with variable turnaround commitments from minutes to hours. Dominates enterprise SaaS procurement with usage-based pricing tiers.
- Online:Browser-based upload and retrieval workflows for ad-hoc transcription needs.
- Offline:Batch processing of archived audio with extended turnaround windows and reduced per-minute pricing.
On-demand delivery carries the largest installed base. Real-time deployment is gaining share fastest as telemedicine and remote court proceedings normalize post-pandemic workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany extracts higher transcription value per healthcare encounter than Brazil, where manual documentation still dominates public hospital workflows. Canada and the United Kingdom occupy intermediate positions, with cloud adoption accelerating faster than continental Europe but slower than North American leaders.
United States
California health systems and Texas rural clinics drive divergent procurement patterns for HIPAA-compliant documentation platforms. The Office for Civil Rights enforces audit-ready security protocols that compel encrypted cloud migrations. Epic and Cerner deployments in the San Francisco Bay Area and Houston medical centers absorb the largest enterprise contract volumes.
Germany
Hospital digitization mandates under the Hospital Future Act accelerate speech-to-text procurement for electronic patient records. The Federal Office for Information Security certifies health data processing systems, creating compliance barriers for non-EU vendors. Berlin and Munich hospital networks pilot transformer-based medical documentation engines for emergency department workflows.
United Kingdom
NHS trusts in England deploy automated transcription to reduce clinician administrative burdens under workforce recovery plans. The National Data Guardian issues guidance on voice data processing that shapes vendor security architectures. London teaching hospitals and Manchester integrated care systems lead procurement of AI-assisted documentation tools.
Canada
Provincial health authorities in Ontario and British Columbia expand transcription procurement to address specialist documentation backlogs. Health Canada oversees medical device software classifications that affect speech recognition platform approvals. Toronto and Vancouver health networks consolidate vendor relationships under multi-year enterprise agreements with accuracy guarantees.
Brazil
Public hospital digitization programs in São Paulo and Minas Gerais create demand for Portuguese-language medical transcription infrastructure. The National Health Surveillance Agency regulates software as medical devices, slowing foreign platform entry. Private hospital chains in Rio de Janeiro adopt hybrid human-AI workflows faster than public institutions.
US Transcription Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with technology-integrated platforms capturing health system contracts while crowdsourced human networks dominate legal and media verticals. The vendor landscape organizes into three tiers: adaptive AI engine developers, human-in-the-loop quality networks, and vertical-specific compliance specialists. Consolidation pressure intensifies as health systems demand unified platforms spanning real-time and batch documentation. M&A activity concentrates on NLP capability acquisition and geographic expansion into underpenetrated state markets.
Within the adaptive AI tier, Verbit and Oris Technologies exemplify proprietary engine development strategies, while TranscribeMe occupies a position as a HIPAA-specialized compliance anchor for regulated health documentation. Rev sits within the crowdsourced quality tier, representing human-in-the-loop architectures that sustain premium positioning in legal and entertainment segments where certification chains matter.
| Leading Market Players |
|---|
| Verbit |
| LexTranscribe |
| Rev |
| Mediscribes |
| Integreon |
| GoTranscript |
| HappyScribe |
| Oris Technologies |
| TranscribeMe |
| Others |
Cost & Logistics Intelligence
Transformer-based speech recognition deployment is compressing per-minute processing costs while concentrating GPU cluster procurement among hyperscale cloud providers in Virginia and Oregon. This technology shift simultaneously erodes legacy per-transaction pricing power and rewards vendors with captive infrastructure or long-term compute reservations.
Pricing Analysis
Capacity additions in cloud GPU regions are reshaping price floors for real-time transcription APIs. Subscription-based SaaS tiers now dominate enterprise procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by accuracy guarantees and HIPAA certification depth. Pricing pressure stems from open-source speech model commoditization in the standard tier. Federally qualified health centers in Mississippi and Alabama exhibit highest price sensitivity; Manhattan litigation boutiques show least.
Supply Chain Analysis
Single-source vulnerability sits with NVIDIA GPU supply for training and inference clusters. Hardware concentration centers on Taiwan semiconductor fabrication, South Korea memory production, and US-based cloud data center operations. Raw material dependencies include advanced silicon wafers, high-bandwidth memory modules, and specialized cooling systems. Tariff exposure on Chinese-manufactured server components presents structural risk. Distribution runs through direct API provisioning and health system IT vendor consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US transcription rests on AI-driven labor substitution in medical documentation and premium-tier pricing for FDA-validated clinical trial transcript chains.
For Market Incumbents: Hedge against open-source model commoditization by securing exclusive EHR integration partnerships with Epic and Cerner deployments in California and Texas. Invest in HIPAA certification depth as a compliance moat against cloud-native entrants lacking audit-ready infrastructure. Vertical integration into specialized medical NLP talent pools in Boston and San Francisco protects development velocity. For New Entrants and Emerging Players: Behavioral health documentation workflows present a technology-first wedge for psychiatric and substance abuse facilities underserved by legacy vendors. Target Mississippi and Alabama rural health clinics with lightweight, browser-based transcription tools requiring minimal IT integration. Pursue direct sales to federally qualified health centers bypassing consolidated GPO contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among HIPAA-specialized compliance platforms with validated FDA documentation chains. Long-term viability favors vendors with durable EHR integration moats and recurring revenue concentration above transactional per-minute models. Watch FTC AI accuracy guidance enforcement patterns as inflection indicator for competitive differentiation sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic and Cerner API certification locks in multi-year health system contracts with switching costs. |
| Acquisition of Specialist Firm | Clinical NLP talent absorption accelerates domain-specific model development timelines. |
| Geographic Expansion | Mississippi and Alabama rural clinic penetration captures underpenetrated Medicare reimbursement flows. |
| Strategic Partnership | FDA-validated transcript chains for oncology trials command premium pricing from pharmaceutical sponsors. |
| Product Launch | Real-time telemedicine transcription tools address accessibility compliance in California court systems. |
Research Approach
Bottom-up health system procurement modeling reconciled against top-down cloud transcription API deployment tracking forms the analytical core. Primary interviews with hospital CIOs, health system purchasing committee members, clinical documentation directors, and medical transcription vendor executives combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital GPO contract disclosures, and hyperscaler capex reports. Triangulation across stakeholder inputs and regulatory filings ensures segment-level accuracy.
Historical trendline analysis of transcription volume growth across medical, legal, and business verticals informs projection parameters. Segmentation dimensions modeled include service type, technology deployment mode, end-user industry, and state-level regulatory cluster. CAGRs derive from fitted growth curves adjusted for HIPAA enforcement intensity and EHR adoption saturation. NLP model accuracy improvement trajectories and GPU cost decline curves serve as industry-specific forecast inputs across the projection horizon.
The model holds under stable HIPAA enforcement and continued cloud migration; deviation in FTC AI accuracy mandate timing or GPU supply disruption would shift trajectory bounds. Forecasts reflect documented assumptions on health system IT budget allocation and clinical documentation burden growth. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
Price Optimization and Management Software Market
Digital Solutions
IT Service Management Market
Digital Solutions
Asia Pacific B2C Legal Services Market
Digital Solutions
Labor Management System in Retail Market
Digital Solutions
Digital Shelf Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Beacons Management Software Market
Digital Solutions
Legal Transcription Market
Digital Solutions
Global Data Catalog Market
Digital Solutions
Global Surface Computing Market
Digital Solutions
Global Enterprise Mobility Management (EMM) Market
Digital Solutions
Global Freelance Platforms Market
Digital Solutions
Data Labeling Solution and Services Market
Digital Solutions
Image Recognition in Retail Market