
 Global AI Based Surgical Robots Market | 2026-2036
Global AI Based Surgical Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global AI Based Surgical Robots Market Intelligence
The shift towards leasing and as-a-service models for high-cost capital equipment is reshaping competitive positioning for new entrants. Intuitive Surgical leverages its extensive installed base and long-term service contracts to maintain market leadership. Medtronic competes by integrating its robotic systems with a broad portfolio of surgical instruments and implants. Stryker Corporation differentiates through its focus on specialized orthopedic and spine robotic-assisted procedures.
AI-based surgical robots integrate advanced algorithms with mechanical arms to assist surgeons during operations. These platforms use computer vision and machine learning to analyze patient data, enhancing procedural accuracy to the sub-millimeter level. Hospitals remain the primary end-user segment, driven by the need to improve surgical outcomes and reduce recovery times. Orthopedic surgery represents a fast-growing procedure type, where AI aids in complex joint replacement operations.
Regulatory pathways from bodies like the U.S. Food and Drug Administration (FDA) and China's National Medical Products Administration (NMPA) govern market access. In Europe, CE marking under the Medical Device Regulation (MDR) imposes strict clinical evidence and post-market surveillance requirements. Vendor success depends on navigating these complex regional approval processes while demonstrating clear clinical and economic value to healthcare providers.
Market Dynamics
The central tension shaping the market is the high capital cost of AI-enabled surgical systems clashing with hospital budget constraints. This dynamic is accelerating the adoption of leasing and as-a-service business models, altering the competitive landscape for all vendors.
Growth Catalysts
- Enhanced Precision:AI-driven computer vision and machine learning algorithms provide sub-millimeter accuracy, a critical factor driving adoption in complex procedures like orthopedic joint replacements.
- Hospital Investment:Demand from hospitals in the United States, focused on improving surgical outcomes and shortening patient recovery times, remains a primary market accelerant.
- Regulatory Pathways:Clearer, albeit stringent, regulatory frameworks from bodies like the U.S. FDA and China's NMPA provide a structured path for new device approvals.
Market Restraints
- High Capital Outlay:The substantial upfront investment required for robotic surgical systems remains a significant barrier for smaller hospitals and healthcare facilities with limited budgets.
- Regulatory Scrutiny:The European Union's Medical Device Regulation (MDR) imposes strict clinical evidence and post-market surveillance requirements, lengthening approval timelines and increasing costs.
- System Interoperability:Integrating new robotic platforms with diverse legacy hospital information systems and existing surgical workflows presents a major technical and operational hurdle.
Strategic Opportunities
- Ambulatory Surgery Centers:Expansion into the growing segment of ambulatory surgery centers offers a new customer base for smaller, more specialized, and lower-cost robotic systems.
- Procedural Autonomy:Developing AI for semi-autonomous or fully autonomous execution of specific surgical sub-tasks, such as suturing, represents a significant area for value creation.
- Data Monetization:Aggregating and anonymizing surgical data from a large installed base can create new revenue streams through analytics services for training, research, and device improvement.
Industry Challenges
- Surgical Skill Gaps:A persistent shortage of surgeons and clinical staff proficient in operating and maintaining advanced AI-based robotic systems constrains wider system utilization.
- Data Security and Privacy:Ensuring the security of sensitive patient data used by AI algorithms and complying with regulations like HIPAA and GDPR is a critical operational challenge.
- Lack of Standardization:The absence of standardized training curricula and performance metrics across competing robotic platforms complicates credentialing and comparative effectiveness research.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AI Based Surgical Robots Market |
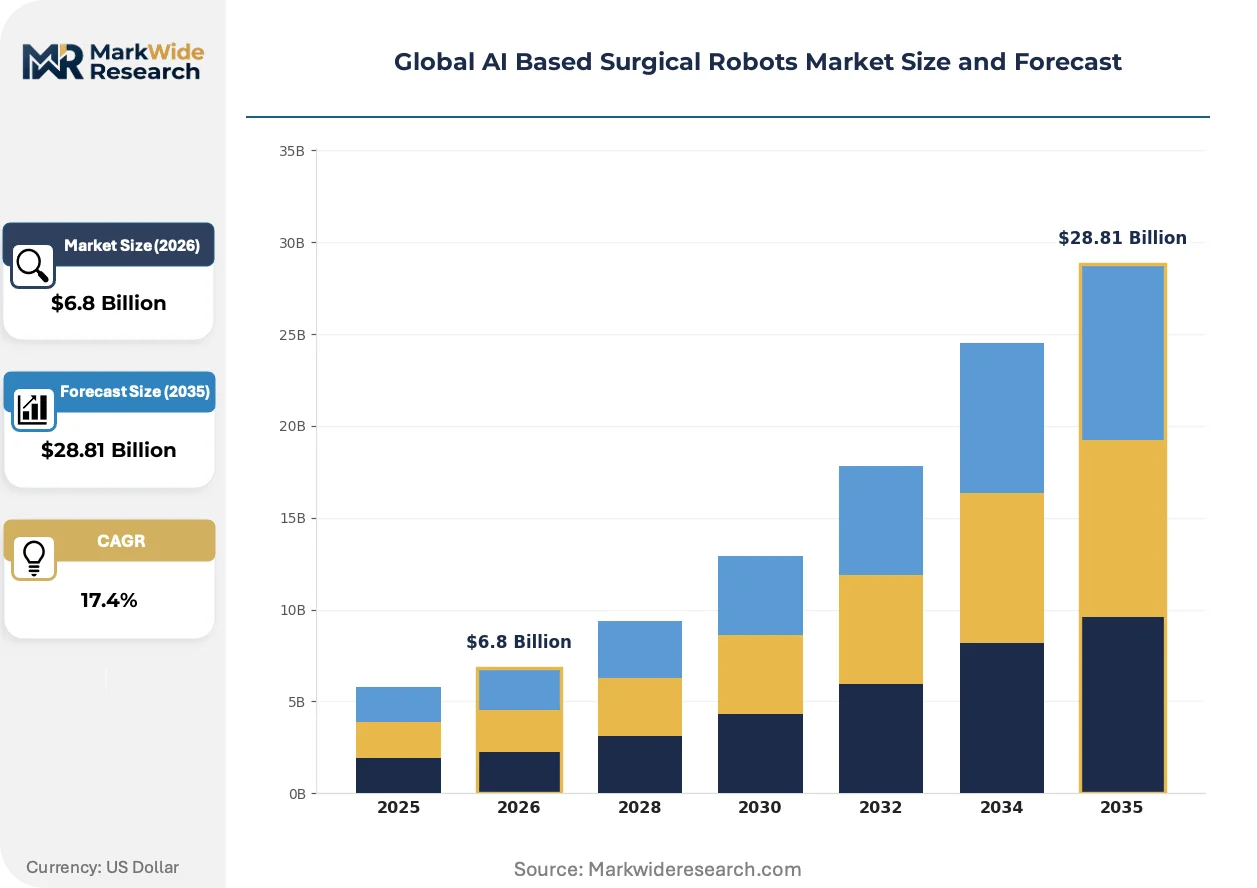
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arm, Surgical Console, Vision System, Software End User: Hospitals, Ambulatory Surgery Centers, Clinics, Research Institutions Procedure Type: Orthopedic Surgery, Cardiothoracic Surgery, Urological Surgery, Neurosurgery Technology: Machine Learning, Computer Vision, Haptics, Automation |
| Companies Covered | Intuitive Surgical, Medtronic, Stryker Corporation, Johnson & Johnson, CMR Surgical, Accuray Incorporated, Zimmer Biomet, Smith and Nephew, Asensus Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AI Based Surgical Robots Market Strategic Shifts & Innovations
The evolution from robotic assistance to AI-driven surgical intelligence is the market's defining theme. This transition is not just technological; it is fundamentally altering business models and the regulatory environment for medical device manufacturers worldwide.
Real-time data fusion technology combines pre-operative MRI or CT scans with live intra-operative sensor data to create a dynamic, 4D patient anatomy model. Hospitals specializing in neurosurgery and complex spinal procedures are rapidly adopting these platforms to enhance surgical navigation. This advanced capability is collapsing the gap between static pre-surgical plans and the dynamic reality of the operating room.
In Europe, the EU AI Act classifies high-risk applications, including medical devices, under a stringent regulatory tier. This forces manufacturers to provide extensive documentation on algorithm training data, risk management, and human oversight mechanisms. Consequently, vendors targeting the European market are re-architecting their software to prioritize transparency and explainability to meet CE marking requirements under the new framework.
A notable shift in hospital procurement behavior involves moving from large capital expenditures to flexible, usage-based contracts for surgical robots. This "robot-as-a-service" model replaces a multi-million dollar upfront cost with predictable, recurring operational expenses tied to procedure volume. The model is gaining significant traction in large U.S. hospital networks seeking to standardize technology across their facilities while preserving capital.
Global AI Based Surgical Robots Market Segmentation
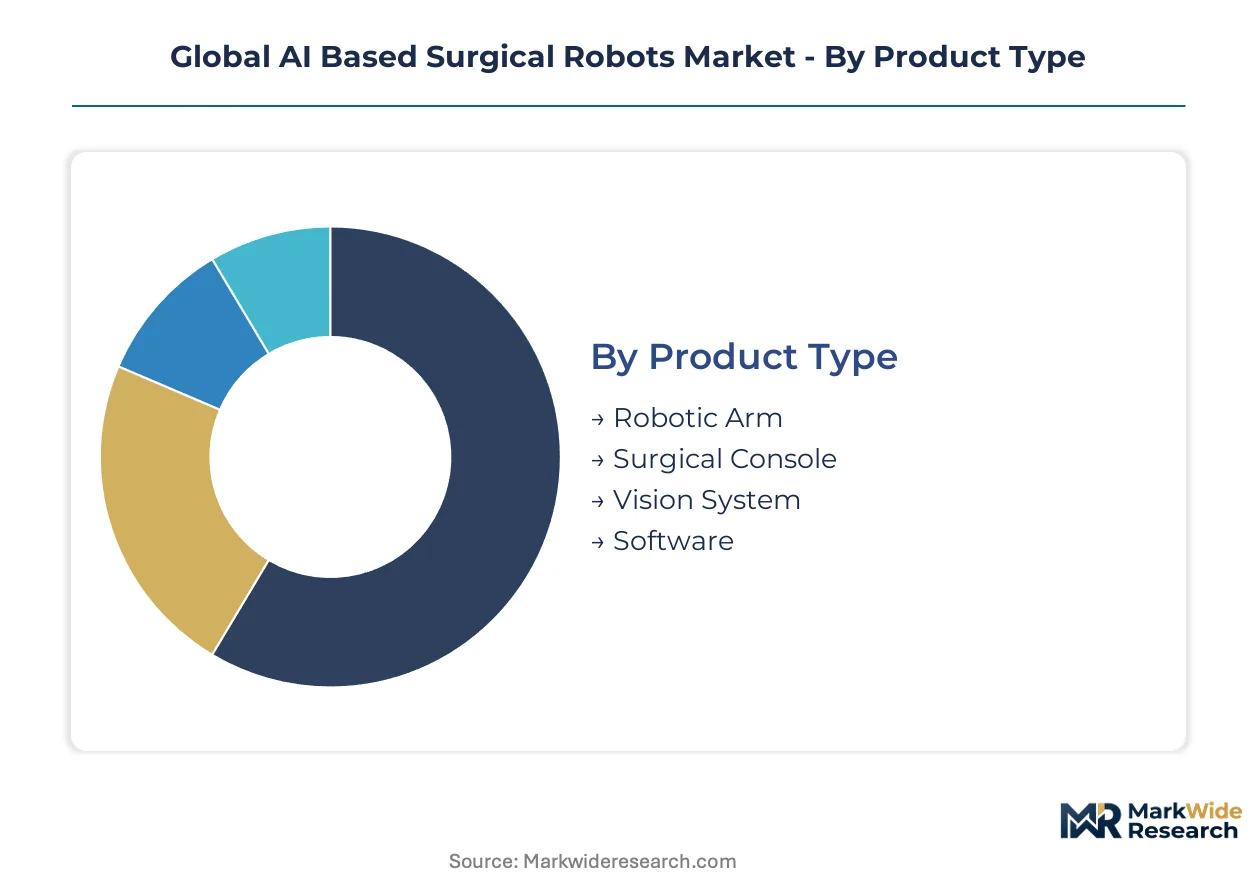
The global AI based surgical robots market is intricately segmented across various dimensions, reflecting the diverse applications and technological advancements shaping this critical healthcare sector. Understanding these segments provides a granular view of demand drivers, technological adoption patterns, and the evolving competitive landscape for robotic surgical systems.
Product Type:
The product type dimension categorizes the physical and software components that constitute AI-enabled surgical robotic platforms.
- Robotic Arm:These mechanical manipulators execute surgical tasks with high precision, guided by AI algorithms and surgeon input. Demand for robotic arms is concentrating in orthopedic surgery, where their sub-millimeter accuracy significantly improves joint replacement outcomes.
- Surgical Console:This interface provides the surgeon with real-time visual feedback and controls to operate the robotic arm and instruments. Hospitals prioritize consoles offering intuitive controls and immersive 3D visualization for enhanced procedural efficiency.
- Vision System:Comprising high-definition cameras and imaging processors, vision systems provide magnified, real-time views of the surgical field. Integration with AI-driven computer vision enhances tissue recognition and anatomical mapping.
- Software:This segment includes AI algorithms for image analysis, machine learning for procedural guidance, and operating system software that orchestrates robotic functions. The United States leads in investment in advanced surgical software, driven by the need for enhanced procedural autonomy.
Robotic Arm holds installed capacity. Software is rotating up the share rankings.
End User:
The customer type for AI based surgical robots varies by facility size, patient volume, and specialization, influencing procurement strategies.
- Hospitals:These large medical institutions represent the primary end-user segment, acquiring AI surgical robots to improve patient outcomes, reduce recovery times, and enhance their surgical capabilities. United States hospital networks are standardizing technology across their facilities, driving demand.
- Ambulatory Surgery Centers:Specialized outpatient facilities are increasingly adopting smaller, more focused robotic systems for less complex procedures. This segment is expanding most quickly due to cost-efficiency and patient convenience.
- Clinics:Smaller specialized clinics may invest in AI-assisted tools for specific diagnostic or minor interventional procedures. These facilities often seek compact, user-friendly robotic solutions.
- Research Institutions:Academic and private research centers utilize AI surgical robots for developing new surgical techniques, training future surgeons, and validating advanced algorithms. Research institutions drive innovation in semi-autonomous surgical tasks.
Hospitals command the largest volume. Ambulatory Surgery Centers are gaining share fastest.
Procedure Type:
The application of AI surgical robots spans diverse surgical specialties, each presenting unique precision requirements and clinical benefits.
- Orthopedic Surgery:This segment involves joint replacements, spinal procedures, and trauma surgery, where AI robots provide unparalleled precision for bone cutting and implant placement. Demand is robust in regions with aging populations seeking improved mobility.
- Cardiothoracic Surgery:AI-assisted robots aid in minimally invasive heart and lung procedures, enabling surgeons to perform delicate maneuvers in confined spaces. These platforms reduce invasiveness and patient recovery periods.
- Urological Surgery:Robotic systems are routinely used for prostatectomies, nephrectomies, and bladder surgeries, offering enhanced dexterity and visualization. The precision of these systems minimizes complications in sensitive anatomical areas.
- Neurosurgery:AI robots assist in complex brain and spinal cord operations, utilizing advanced imaging and navigation to target lesions with sub-millimeter accuracy. This application requires the highest level of robotic precision.
Orthopedic Surgery currently accounts for the largest share. Neurosurgery shows a steep expansion trajectory.
Technology:
The functional capability of AI surgical robots is defined by the underlying artificial intelligence and sensing technologies integrated into the platforms.
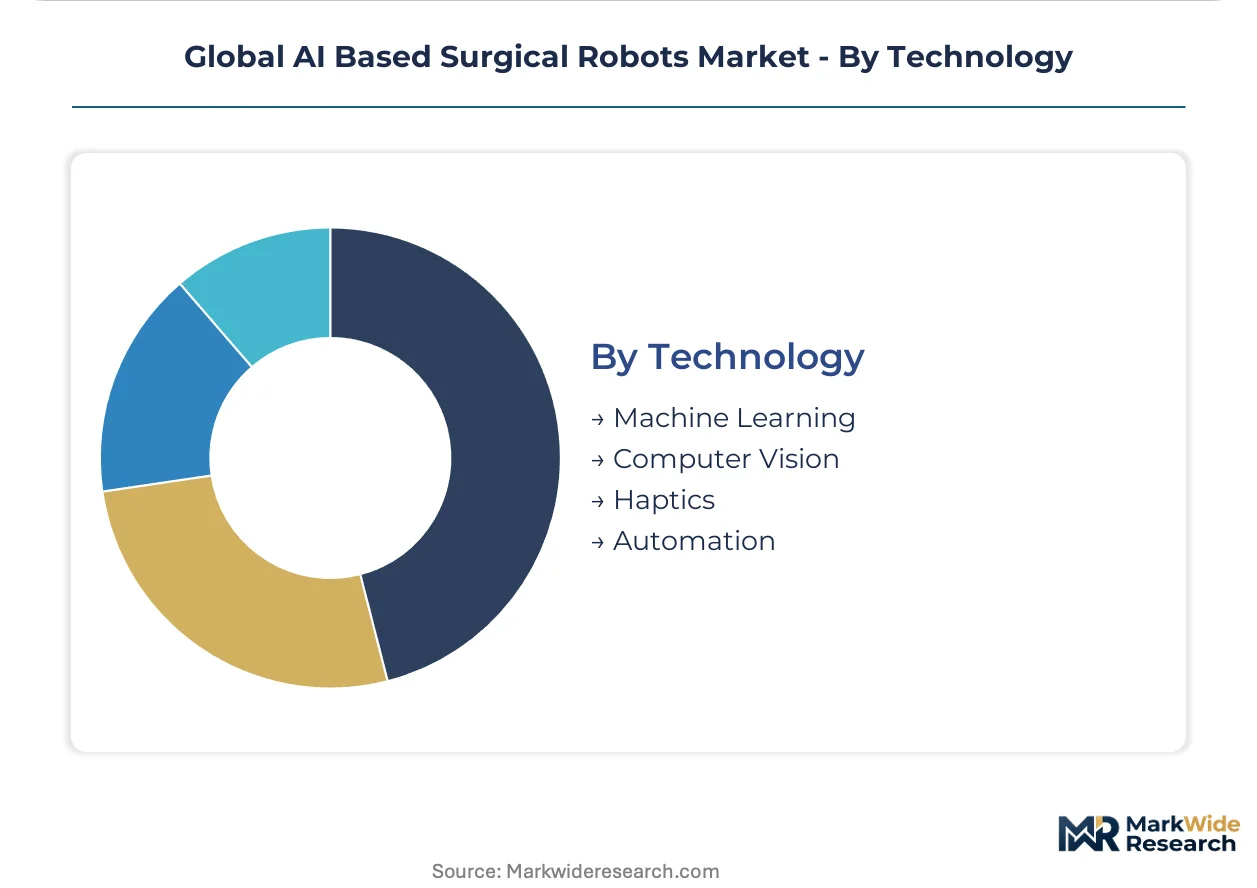
- Machine Learning:Algorithms analyze vast datasets of surgical procedures and patient outcomes to provide predictive insights and optimize robotic movements. Machine learning models enhance real-time decision support during operations.
- Computer Vision:This technology enables robots to interpret visual data from cameras, recognize anatomical structures, and track surgical instruments. Computer vision is critical for dynamic 4D patient anatomy models.
- Haptics:Haptic feedback systems provide surgeons with a sense of touch and force, allowing them to feel tissue resistance and pressure during robotic manipulation. This technology enhances surgeon control and safety.
- Automation:This refers to the robot's ability to perform specific surgical sub-tasks autonomously or semi-autonomously, under surgeon supervision. Automation reduces surgeon fatigue and standardizes repetitive actions.
Machine Learning holds significant developmental investment. Computer Vision is experiencing rapid implementation across new platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government initiatives promoting healthcare technology adoption are accelerating the global AI based surgical robots market. These policies often include funding for advanced medical equipment and streamlined regulatory pathways. Such incentives significantly reduce financial barriers for hospitals and healthcare providers.
United States
Demand from hospitals in the United States drives significant investment in advanced surgical technologies for improved patient outcomes. The U.S. Food and Drug Administration (FDA) provides structured regulatory pathways for new medical device approvals. Major innovation hubs like Boston and Silicon Valley foster intense development in medical AI and robotics.
Germany
Germany's market for AI based surgical robots sees strong demand for precision in orthopedic surgery, driven by an aging population. The European Union's Medical Device Regulation (MDR) imposes strict CE marking requirements for market entry. Cities such as Munich and Heidelberg are key centers for research and development in medical robotics.
China
Chinese hospital investment in advanced surgical technologies focuses on improving healthcare infrastructure and local innovation. The National Medical Products Administration (NMPA) governs market access and product registration within the country. Shanghai and Beijing actively cultivate AI and robotics research clusters, supporting domestic manufacturers.
Japan
Japanese demand for minimally invasive procedures and advanced medical technologies is high, influenced by its aging demographic. The Ministry of Health, Labour and Welfare (MHLW) oversees medical device approvals and safety standards. Tokyo's medical technology parks are prominent centers for robotic surgery development and commercialization.
India
Indian demand for accessible advanced healthcare is rising, supported by government initiatives for medical device manufacturing. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices and clinical trials. Bengaluru and Hyderabad are emerging as significant hubs for medical AI startups and robotic technology integration.
Global AI Based Surgical Robots Market Key Industry Players
Channel-controlling players compete with product-specialist players across the AI based surgical robots market. The market exhibits a tiered structure, with established medical device conglomerates alongside focused robotics innovators. Large incumbent firms leverage their extensive installed bases and broad surgical instrument portfolios to maintain market share and expand their influence. Strategic partnerships, technology licensing, and targeted portfolio diversification are common competitive moves to expand procedural capabilities and reach new end-user segments effectively.
Within the integrated solutions archetype, Intuitive Surgical, a U.S.-based corporation, leverages its extensive installed base and long-term service contracts to maintain market leadership. Medtronic, another prominent U.S.-based medical technology company, occupies a position through its broad portfolio of surgical instruments and implants, integrating robotic systems into a wider offering. Stryker Corporation, also a U.S.-headquartered entity, exemplifies specialization, focusing on specialized orthopedic and spine robotic-assisted procedures, thereby differentiating its market approach.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson |
| CMR Surgical |
| Accuray Incorporated |
| Zimmer Biomet |
| Smith and Nephew |
| Asensus Surgical |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes, vital for delivering advanced microprocessors and precision components, directly influence the cost structure of AI-based surgical robots, affecting both manufacturing concentration and the ultimate price differentiation for end-users.
Pricing Analysis
Certification level (FDA/CE-grade) creates the primary spread in AI surgical robot pricing. The dominant pricing structure is shifting towards usage-based contracts and "robot-as-a-service" models, replacing large capital expenditures. Price differentiation stems from advanced software features, after-sales service, and specialized training packages. Pricing pressure intensifies for smaller hospitals and ambulatory surgery centers due to budget constraints. Large hospital networks, focused on standardizing technology, exhibit less price sensitivity for comprehensive solutions.
Supply Chain Analysis
Single-source vulnerability for specialized AI chips and high-precision mechanical parts dominates the supply chain risk for AI surgical robots. Manufacturing concentrates heavily in the United States for final assembly and software integration, drawing critical microprocessors from Taiwan and advanced optical sensors from Germany. Raw material dependencies include specialized alloys for robotic arms and high-performance computing components. Distribution runs through direct sales teams and specialized service networks, ensuring installation, training, and ongoing technical support for hospital systems globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI based surgical robots market represents a defensive-moat story, primarily due to significant regulatory entrenchment and high switching costs for healthcare providers.
For Market Incumbents: Pre-empt competitive threats from AI-native startups by accelerating internal R&D in semi-autonomous surgical capabilities. Expand installed base through flexible leasing and as-a-service models to counter hospital budget constraints. Invest in certification processes for new AI algorithms under stringent frameworks like the EU AI Act. Deepen long-term service contracts to reinforce customer loyalty against emerging lower-cost alternatives.
For New Entrants and Emerging Players: Underpenetration in ambulatory surgery centers (ASCs) offers a significant white-space opportunity for specialized, lower-cost robotic systems. Target specific procedural niches like ophthalmology or ENT with compact, user-friendly platforms. A compelling go-to-market angle involves offering "robot-as-a-service" contracts tailored for outpatient facilities. Focus on developing AI software solutions that can integrate with existing hardware infrastructure, reducing capital outlay for new customers.
For Investors and Strategic Acquirers: AI software developers specializing in surgical intelligence and precision component manufacturers represent attractive acquisition targets. The market exhibits strong long-term growth potential over the next decade, driven by aging populations and demand for minimally invasive procedures. A signal to watch is the increasing adoption rate of semi-autonomous surgical sub-tasks within established hospital networks. Prioritize firms with robust intellectual property portfolios and clear regulatory pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Usage-Based Contract Offerings | Addresses hospital budget constraints and accelerates technology adoption across diverse healthcare settings. |
| Invest in AI Software Development | Enhances procedural autonomy and improves data analytics for surgical outcomes and training. |
| Target Ambulatory Surgery Centers | Unlocks a growing customer base for specialized, cost-effective robotic surgical systems. |
| Strengthen Regulatory Affairs Capabilities | Ensures efficient market access and compliance with evolving medical device regulations globally. |
| Form Strategic Hospital System Partnerships | Facilitates technology standardization and broadens market penetration within major healthcare networks. |
Research Approach
A standing panel of hospital procurement managers, orthopedic surgeons, biomedical engineers, and regulatory affairs specialists provided ongoing calibration for this market analysis. Primary interviews were conducted with these industry stakeholders, validated against extensive secondary research. Secondary sources included FDA device approvals, NMPA product registrations, EU MDR guidance documents, and medical journal databases. This approach enabled robust bottom-up and top-down triangulation of market data.
Scenario-bracketing informed the analytical framework used to project market volume and value across the projection horizon. Segmentation dimensions modeled included product type, end-user, procedure type, technology, and regional regulatory cluster. Compound annual growth rates were derived from historical trends, expert consensus, and projected healthcare expenditure growth. Surgical procedure volumes and advancements in AI algorithm capabilities served as key industry-specific forecast inputs.
Practitioners should monitor unforeseen regulatory changes and rapid technological obsolescence for early signals that could impact market dynamics. Forecasts reflect assumptions documented within the analytical framework. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Industrial Robotics Market
Robotics and Automation
Food Robotics Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
Microsurgery Robot Market
Robotics and Automation
Intelligent Parcel Delivery Lockers Market
Robotics and Automation
APAC Service Robots Market
Robotics and Automation
Wearable Robots and Exoskeletons Market
Robotics and Automation
Vision Guided Robotics Market
Robotics and Automation
Global Construction Robot Market
Robotics and Automation
Palletizing Robots Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
Robotics End of Arm Tooling Market
Robotics and Automation
Assistive Robotics Market