
 US Anhydrous Hydrogen Fluoride Market | 2026-2036
US Anhydrous Hydrogen Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
US Anhydrous Hydrogen Fluoride Market Intelligence
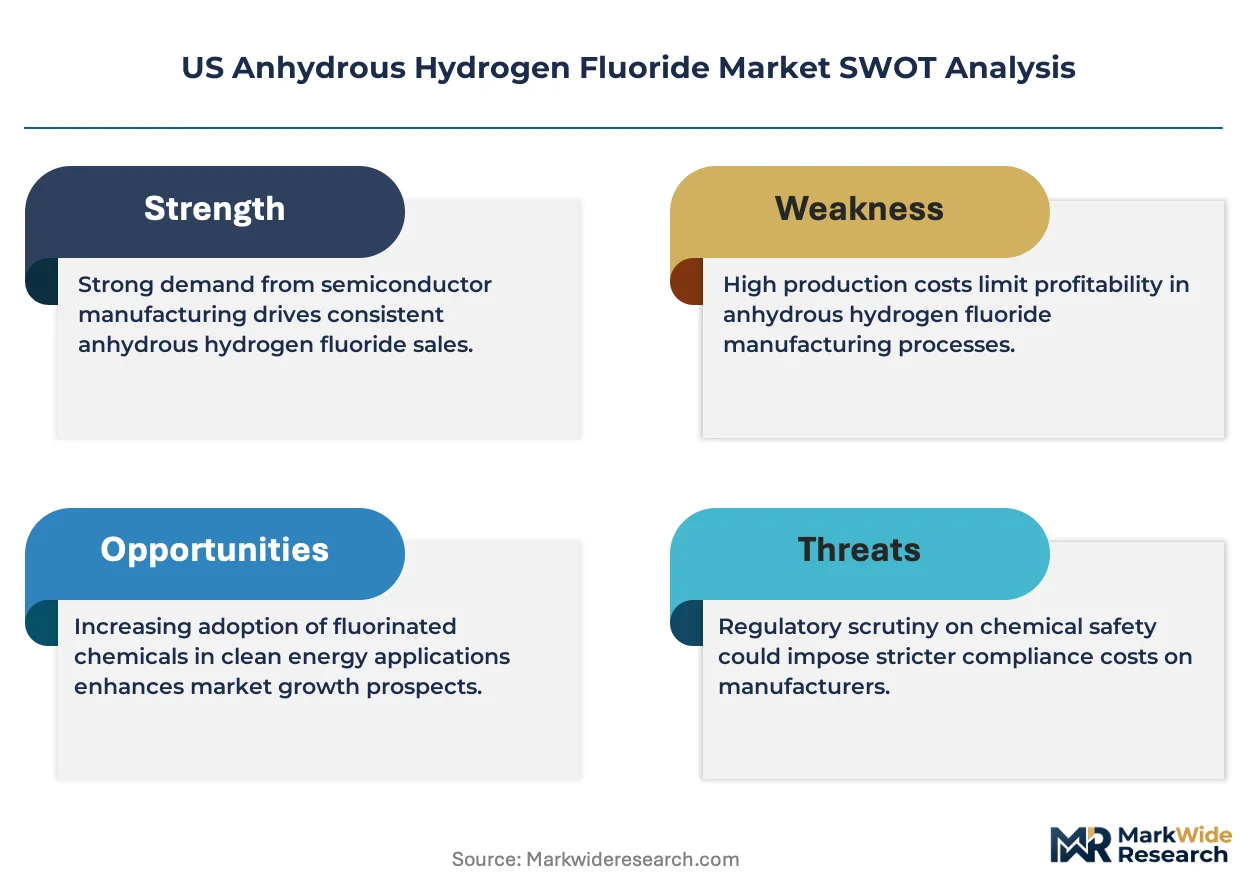
Electronic-grade specification tiers is rotating toward the center of value creation in the US Anhydrous Hydrogen Fluoride Market. Honeywell International Inc. leverages captive fluorspar sourcing and integrated refining to command premium positioning. Solvay anchors Gulf Coast supply chains with dedicated pipeline networks serving petrochemical corridors. Arkema specializes in high-purity grades for semiconductor etching applications, differentiating through contamination thresholds below ten parts per billion.
Anhydrous hydrogen fluoride is a colorless, corrosive liquid or gas with the chemical formula HF, produced through the reaction of fluorspar with sulfuric acid; it serves as the foundational feedstock for fluorocarbons, fluoropolymers, and uranium enrichment. Electronic-grade material commands the highest purity thresholds and tightest supply allocations, while industrial-grade volumes dominate tonnage flows into petrochemical and metal processing channels. Semiconductor companies represent the fastest-expanding end-user category, though chemical manufacturers still absorb the largest absolute volume. Direct sales channels control the majority of electronic-grade transactions, with distributors handling fragmented industrial-grade accounts across smaller metal processors.
EPA oversight of fluorinated greenhouse gas emissions intersects with OSHA workplace exposure limits to elevate capital costs for new production capacity. The Chemours Company and Linde plc navigate this framework through emissions capture investments and process intensification technologies. Stakeholders must monitor how state-level permitting timelines in Texas and Arizona affect project economics for planned capacity additions.
Market Dynamics
EPA fluorinated greenhouse gas regulations are compressing production economics while semiconductor-grade demand concentrates in Texas and Arizona fabrication corridors. Suppliers face simultaneous pressure to decarbonize operations and expand electronic-grade capacity.
Growth Catalysts
- CHIPS Act incentives:Federal subsidies for domestic semiconductor manufacturing are accelerating cleanroom construction in Arizona and Texas, pulling electronic-grade anhydrous hydrogen fluoride into long-term supply agreements.
- Advanced node etching:Sub-3 nanometer chip architectures require contamination thresholds below ten parts per billion, locking in premium-grade material specifications for etching and cleaning processes.
- Gulf Coast infrastructure:Established pipeline networks and integrated fluorspar-to-acid complexes in Louisiana and Texas reduce logistics costs for industrial-grade volumes serving petrochemical corridors.
Market Restraints
- Fluorspar import dependence:Domestic acid-grade fluorspar mining remains minimal, forcing reliance on Mexican and South African ore shipments subject to freight volatility and geopolitical friction.
- EPA F-Gas compliance costs:Mandatory emissions capture systems and monitoring infrastructure add capital intensity to brownfield expansions, stretching project timelines in permitting-heavy jurisdictions.
- Alternative fluorine sources:Fluorosilicic acid recovery from phosphate fertilizer operations offers partial substitution for industrial applications, capping pricing power in commodity-grade segments.
Strategic Opportunities
- Idaho-Montana fluorspar belt:Revitalized domestic mining projects could reduce import exposure and anchor captive supply for integrated producers willing to absorb exploration risk.
- Battery electrolyte fluorides:Lithium hexafluorophosphate and lithium bis(fluorosulfonyl)imide production for electric vehicle batteries represents an emerging demand vertical with distinct purity requirements.
- Carbon border adjustments:Proposed EU CBAM mechanisms on fluorinated chemical imports create competitive advantage for US producers with verified low-emission production pathways.
Industry Challenges
- Specialized corrosion engineering:Monel and Hastelloy infrastructure maintenance requires scarce metallurgical expertise, constraining workforce scalability for plant expansions.
- Electronic-grade certification timelines:Semiconductor customer qualification protocols extend eighteen to thirty-six months, delaying revenue recognition from new capacity investments.
- Legacy equipment retrofit complexity:Converting industrial-grade lines to electronic-grade specifications demands full process isolation and analytical instrumentation upgrades that disrupt ongoing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Anhydrous Hydrogen Fluoride Market |
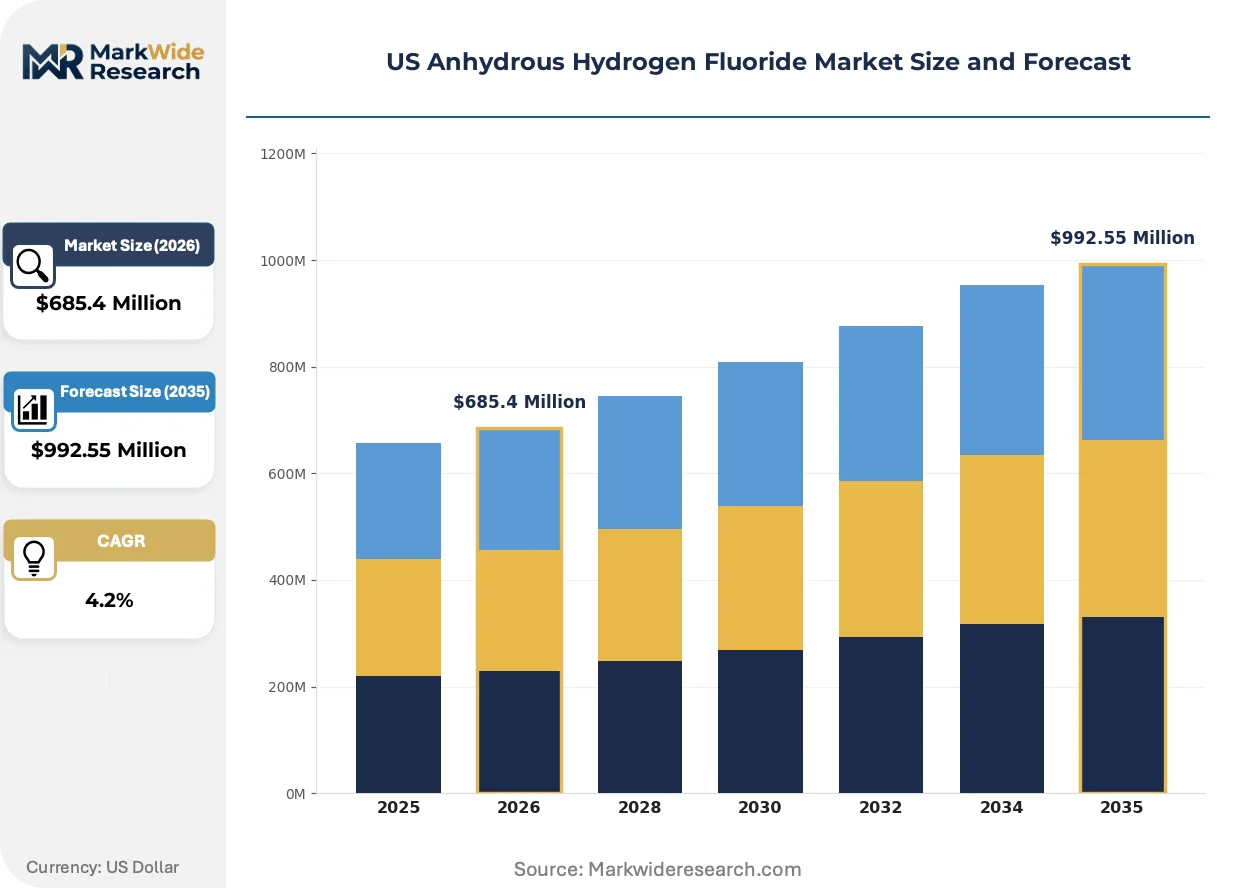
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Grade, Industrial Grade, Reagent Grade, Pharmaceutical Grade Application: Petrochemicals, Electronics, Metal Processing, Pharmaceuticals End User: Chemical Manufacturers, Semiconductor Companies, Oil Refineries, Healthcare Providers Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Honeywell International Inc., Solvay, Linde plc, Arkema, LANXESS, The Chemours Company, Daikin Industries, Ltd., Stella Chemifa Corporation, Navin Fluorine International Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Anhydrous Hydrogen Fluoride Market Strategic Shifts & Innovations
Process intensification and contamination control technologies are bifurcating competitive positioning between commodity suppliers and precision-grade specialists. The market is separating into distinct capability tiers.
Membrane-based HF purification is displacing traditional distillation sequences in electronic-grade production. Semiconductor fabs in Arizona and Texas are demanding sub-ppb specifications that legacy column operations cannot reliably achieve. This technology compression is forcing industrial-grade producers to accept permanent exclusion from premium segments or undertake complete process rebuilds.
EPA enforcement of the American Innovation and Manufacturing Act is tightening hydrofluorocarbon phase-down schedules. Chemical manufacturers must reconfigure feedstock sourcing and byproduct handling to avoid penalties. Texas Gulf Coast operations face the most acute compliance pressure due to concentrated HFC-23 byproduct generation from fluorocarbon synthesis.
Direct pipeline supply contracts are replacing tanker-truck spot purchases among large semiconductor fabs. Arizona fabrication clusters are negotiating fifteen-year take-or-pay agreements with dedicated purity guarantees. This channel consolidation squeezes distributor margins and locks in volume allocations before competing capacity comes online.
US Anhydrous Hydrogen Fluoride Market Segmentation
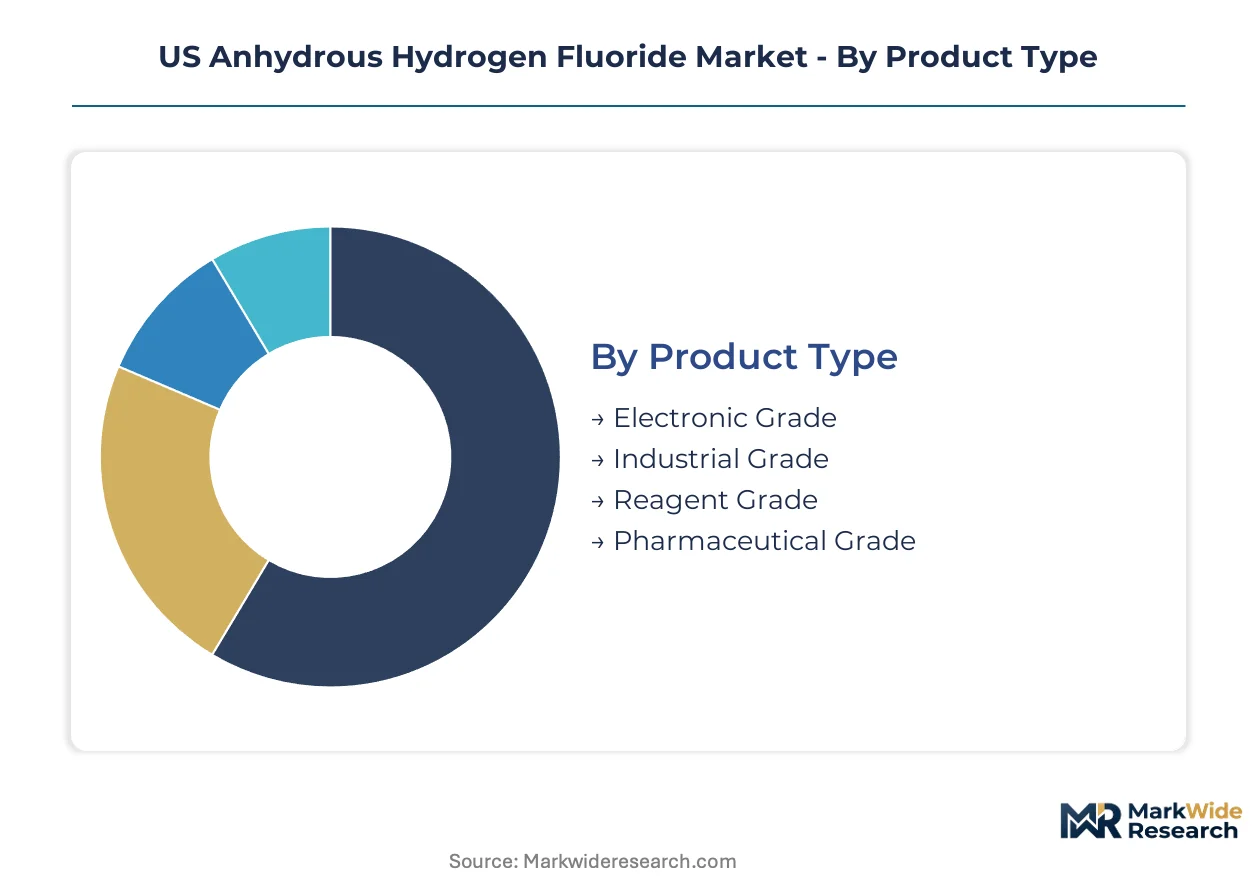
Grade purity tiers and channel configurations determine margin capture in the US anhydrous hydrogen fluoride market. Semiconductor qualification protocols and EPA compliance costs fragment competitive positioning across product categories.
Product Type:
Margin pools concentrate in contamination-controlled specifications where qualification barriers protect pricing power.
- Electronic Grade:Specifications demand contamination thresholds below ten parts per billion for sub-3 nanometer chip etching. Arizona and Texas fabrication clusters are locking in fifteen-year take-or-pay agreements with dedicated purity guarantees. This segment commands the steepest expansion trajectory as CHIPS Act subsidies accelerate cleanroom construction.
- Industrial Grade:Standard purity material serves fluorocarbon feedstock and metal pickling operations across Gulf Coast petrochemical corridors. Louisiana and Texas pipeline networks reduce logistics costs for high-volume tonnage flows. Pricing pressure from fluorosilicic acid substitutes caps margin expansion in commodity applications.
- Reagent Grade:Laboratory and analytical applications require consistent purity for standardized testing protocols.
- Pharmaceutical Grade:cGMP-compliant production for fluorinated active pharmaceutical ingredient synthesis faces stringent FDA validation requirements.
Industrial Grade holds installed capacity. Electronic Grade is rotating up the share rankings.
Application:
Volume concentration tracks Gulf Coast chemical infrastructure density and Southwest semiconductor cluster expansion.
- Electronics:Wafer etching and chamber cleaning processes at Arizona and Texas fabs consume ultra-high-purity material with sub-ppb metal ion specifications. Advanced node migration below 3 nanometers is tightening contamination thresholds faster than legacy purification methods can achieve.
- Petrochemicals:Fluorocarbon and fluoropolymer synthesis absorbs the largest absolute tonnage through Louisiana-Texas integrated production complexes. EPA F-Gas regulations are forcing emissions capture retrofits that elevate capital intensity for brownfield expansions.
- Metal Processing:Stainless steel pickling and aluminum brightening operations in Ohio and Pennsylvania industrial corridors drive steady industrial-grade demand.
- Pharmaceuticals:Fluorinated drug intermediate production requires validated supply chains with batch-level documentation for FDA submission packages.
Petrochemicals anchors volume throughput. Electronics is gaining share fastest.
End User:
Procurement sophistication separates long-term contract negotiators from spot market purchasers.
- Semiconductor Companies:Arizona and Texas fabrication facilities are consolidating supply through direct pipeline connections with fifteen-year take-or-pay structures. Qualification protocols extending eighteen to thirty-six months delay supplier switching and protect incumbent margins.
- Chemical Manufacturers:Fluorocarbon and fluoropolymer producers along the Gulf Coast represent the largest absolute volume consumption through integrated fluorspar-to-acid complexes. EPA hydrofluorocarbon phase-down schedules are forcing feedstock reconfiguration for HFC-23 byproduct management.
- Oil Refineries:Alkylation catalyst regeneration and acid recycling operations in Texas and California require corrosion-resistant logistics infrastructure.
- Healthcare Providers:Pharmaceutical manufacturing and research institutions demand cGMP-compliant supply with full chain-of-custody documentation.
Chemical Manufacturers maintains capacity dominance. Semiconductor Companies is climbing the fastest.
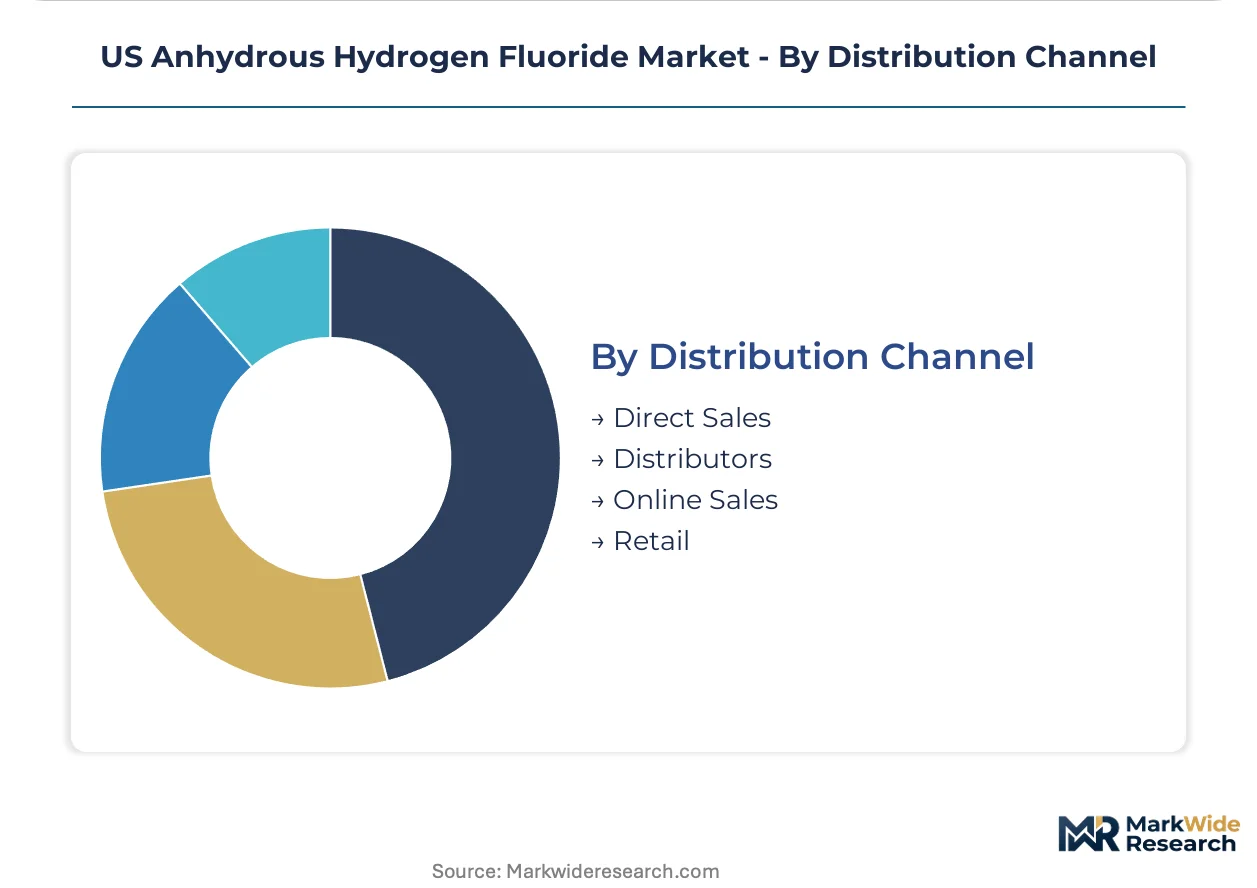
Distribution Channel:
Channel selection correlates with purity tier and customer scale, fragmenting margin capture between integrated suppliers and intermediaries.
- Direct Sales:Pipeline-connected supply dominates electronic-grade transactions for Arizona and Texas semiconductor fabs with dedicated purity guarantees and real-time contamination monitoring. This channel captures premium pricing through long-term contractual structures.
- Distributors:Fragmented industrial-grade accounts across smaller metal processors and regional chemical blenders rely on tanker-truck logistics with spot pricing exposure. Margin compression intensifies as direct pipeline contracts consolidate large-volume purchasers.
- Online Sales:Reagent-grade and small-package laboratory supply serves research institutions with standardized catalog offerings.
- Retail:Limited to specialty hardware and limited-quantity consumer applications with minimal market presence.
Direct Sales controls premium tier allocations. Distributors is defending position in fragmented industrial accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US anhydrous hydrogen fluoride market operates as a net importer of acid-grade fluorspar ore while maintaining substantial domestic refining capacity concentrated along Gulf Coast chemical corridors. Export volumes of electronic-grade material remain limited as domestic semiconductor fabs absorb premium-tier production.
Texas
Texas hosts the nation's densest concentration of petrochemical HF consumption through integrated fluorspar-to-acid complexes serving fluorocarbon synthesis. EPA enforcement of F-Gas regulations targets Houston-area facilities for HFC-23 byproduct capture retrofits. The Austin-San Antonio corridor anchors emerging semiconductor-grade demand from Samsung and Texas Instruments fabrication expansions.
Arizona
Arizona's Phoenix-Tucson semiconductor cluster drives the fastest-growing electronic-grade consumption as TSMC and Intel construct advanced-node fabs. CHIPS Act subsidies accelerate cleanroom construction timelines, pulling long-term supply agreements from regional distributors. The state lacks indigenous fluorspar deposits, forcing complete dependence on rail-shipped ore from Mexico and Gulf Coast ports.
Louisiana
Louisiana's Mississippi River chemical corridor processes industrial-grade volumes into fluoropolymer feedstocks for Gulf Coast export markets. OSHA workplace exposure enforcement elevates capital costs for brownfield expansions at aging St. James Parish facilities. Baton Rouge-area producers navigate simultaneous pressure from EPA emissions mandates and hurricane-season logistics disruptions.
California
California's semiconductor fabs in Silicon Valley and San Diego consume electronic-grade material despite lacking proximate production infrastructure. CARB regulations on fluorinated greenhouse gases exceed federal EPA stringency, complicating supply chain compliance for imported material. The state's environmental permitting timelines stretch capacity addition projects beyond typical Gulf Coast schedules.
Idaho-Montana Border
The Idaho-Montana fluorspar belt hosts revitalized mining exploration targeting reduced import dependence for integrated producers. BLM permitting processes govern access to historic deposits near Bannock Creek and Warm Springs. Successful development would anchor captive supply for producers willing to absorb five-to-seven-year exploration-to-production timelines.
US Anhydrous Hydrogen Fluoride Market Key Industry Players
Listed leaders compete with private specialists across integrated supply chain control, with public chemical conglomerates commanding Gulf Coast infrastructure while private refiners capture niche electronic-grade allocations. The market structures into three tiers: multinational diversified chemicals with captive fluorspar sourcing, regional pipeline-integrated refiners serving petrochemical corridors, and high-purity specialists qualifying for semiconductor supply chains. Dominant competitive moves include backward integration into fluorspar mining concessions and fifteen-year take-or-pay contracting with Arizona-Texas fabrication clusters.
Within the multinational diversified tier, Honeywell International Inc. and Solvay exemplify Gulf Coast infrastructure dominance through integrated refining complexes. Arkema occupies a position among high-purity specialists targeting sub-ppb contamination thresholds for advanced node etching. These three anchors demonstrate how electronic-grade qualification barriers protect incumbent margins against commodity-grade competitors.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Solvay |
| Linde plc |
| Arkema |
| LANXESS |
| The Chemours Company |
| Daikin Industries, Ltd. |
| Stella Chemifa Corporation |
| Navin Fluorine International Limited |
| Others |
Cost & Logistics Intelligence
Fluorosilicic acid recovery from phosphate fertilizer operations is displacing commodity-grade anhydrous hydrogen fluoride in metal pickling applications, simultaneously shifting supply geography toward Florida and North Carolina phosphate corridors while compressing pricing power in industrial-grade tiers. This substitution dynamic concentrates margin capture in electronic-grade specifications where contamination thresholds below ten parts per billion create insurmountable qualification barriers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with fifteen-year take-or-pay agreements dominating electronic-grade transactions. Price differentiation rests on certification level—semiconductor qualification protocols versus standard industrial specifications—and volume scale, with pipeline-connected fabs securing dedicated allocations. Cost compression in industrial-grade segments is intensifying because fluorosilicic acid substitutes cap pricing power, while spot market purchasers at smaller metal processors exhibit the highest price sensitivity.
Supply Chain Analysis
Strategic stockpile preferences dominate fluorspar sourcing as integrated producers maintain six-to-nine-month ore inventories to buffer Mexican and South African supply volatility. Geographic supply concentrates in Mexico, South Africa, and China for acid-grade fluorspar, while domestic refining clusters in Louisiana and Texas process material into electronic and industrial grades. Raw material dependencies include sulfuric acid, fluorspar ore, and corrosion-resistant alloys for Monel and Hastelloy infrastructure. Single-source vulnerability runs through the Veracruz-to-Texas rail corridor. Distribution runs through pipeline networks for large semiconductor fabs and tanker-truck logistics for fragmented industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US anhydrous hydrogen fluoride market operates as a defensive-moat story where eighteen-to-thirty-six-month semiconductor qualification protocols create switching costs that protect incumbent margins against commodity-grade competitors.
For Market Incumbents: Compound qualification barriers by accelerating backward integration into Idaho-Montana fluorspar concessions before exploration timelines compress. Lock in fifteen-year take-or-pay pipeline contracts with Arizona-Texas fabrication clusters to preempt competing capacity. Electronic-grade certification timelines serve as the primary moat against industrial-grade producers attempting tier migration.
For New Entrants and Emerging Players: Semiconductor aftermarket services represent a service-layer gap where incumbents under-serve regional fabs with real-time contamination monitoring and rapid-response logistics. Target battery electrolyte fluoride production for electric vehicle applications, where distinct purity requirements and less entrenched qualification protocols offer faster revenue recognition. Partner with Idaho-Montana mining developers to secure captive fluorspar supply without competing directly for semiconductor-grade certifications.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private high-purity refiners holding active semiconductor qualifications but lacking Gulf Coast infrastructure scale. Five-to-ten-year viability hinges on CHIPS Act subsidy durability and advanced node migration below three nanometers. Monitor EPA F-Gas enforcement intensity as the inflection indicator—accelerated hydrofluorocarbon phase-down schedules would force feedstock reconfiguration that favors integrated producers with emissions capture investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Mining | Idaho-Montana belt development reduces Mexican ore dependence for integrated producers. |
| Long-term Supply Agreement | Fifteen-year take-or-pay contracts with TSMC and Intel fabs lock volume allocations. |
| Capacity Expansion | Electronic-grade line additions in Texas serve Austin-San Antonio semiconductor corridor. |
| Green Manufacturing Transition | Emissions capture retrofits satisfy EPA F-Gas mandates for HFC-23 byproduct management. |
| Joint Venture | Pipeline network partnerships between Louisiana refiners and Arizona distributors reduce logistics costs. |
Research Approach
Desk research of SEC 10-K filings, customs and trade data from the US Census Bureau, and American Chemistry Council industry reports preceded structured interviews with plant managers at Gulf Coast refining complexes, procurement leads at semiconductor fabrication facilities, distribution channel partners, and technical R&D directors specializing in contamination control. Primary fieldwork combined with secondary validation enabled bottom-up volume triangulation against top-down macroeconomic indicators.
Variance decomposition across grade tier, end-use industry, and regional production hub shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectories weighted by capacity utilization assumptions. Forecast inputs incorporated CHIPS Act subsidy disbursement timelines and EPA F-Gas enforcement intensity scenarios without year-specific calibration.
Underlying assumptions cover sustained semiconductor capital expenditure, stable fluorspar ore freight rates, and consistent EPA regulatory stringency, with deviation risk concentrated in Mexican rail corridor disruptions and alternative fluorine source substitution rates. Revision becomes warranted when battery electrolyte fluoride demand crosses thresholds that materially redirect electronic-grade capacity allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Global Industrial Separators Market
Industrial Chemicals
Mass Finishing Consumables Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
Hazardous Chemicals Packaging Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Global Acid Proof Lining Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
2-Ethylhexanol (2-EH) Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
Propylene Oxide Market