
 Propylene Oxide Market | 2026-2036
Propylene Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Propylene Oxide Market Analysis
ISO 14001 environmental management certification is redrawing supplier eligibility for automotive and construction sector contracts. Dow Inc. leverages its integrated propylene-to-oxide chain across the US Gulf Coast to sustain feedstock cost advantages. LyondellBasell anchors European supply through its Rotterdam facility while competing on hydrogen peroxide technology scale. BASF SE differentiates via specialty polyether polyols for high-performance insulation applications.
Propylene oxide is a highly reactive cyclic ether with a three-membered epoxide ring, produced primarily through chlorohydrin or hydrogen peroxide oxidation routes, serving as the essential building block for polyether polyols and propylene glycol manufacturing. Polyether polyols command the dominant product position due to their irreplaceable role in polyurethane foam systems across furniture and automotive seating. The hydrogen peroxide technology segment is gaining fastest adoption as producers phase out chlorine-intensive processes under tightening effluent standards. End-use demand concentrates in construction insulation and automotive lightweighting, where thermal performance specifications continue to tighten.
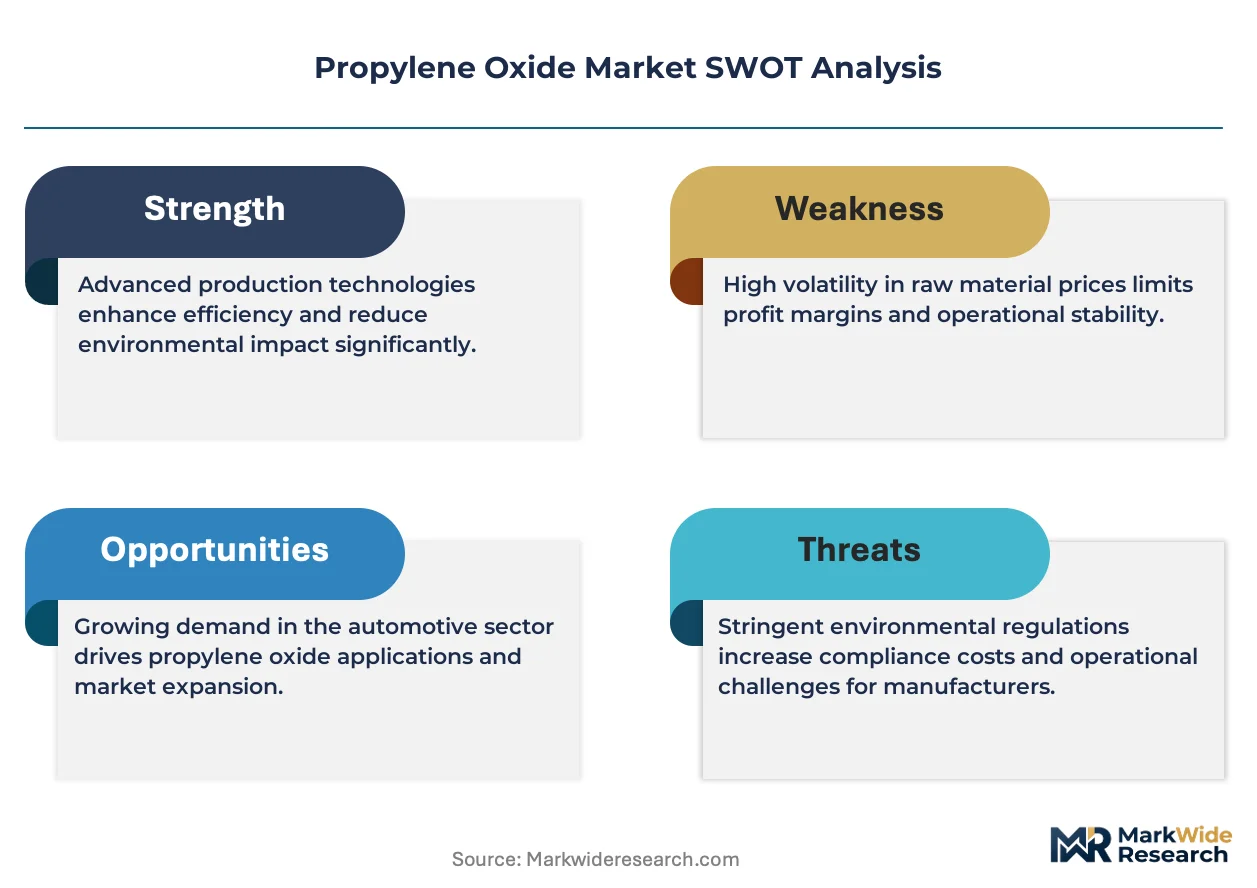
EPA effluent guidelines in the US, REACH chemical registration in Europe, and China's MEE emission standards collectively constrain chlorohydrin process expansion while accelerating capital flows toward peroxide-based alternatives. The EU F-Gas Regulation indirectly amplifies propylene oxide demand by restricting hydrofluorocarbon blowing agents, pushing insulation formulators toward water-blown polyurethane systems. Stakeholders must monitor technology licensing costs and regional carbon border adjustments to determine optimal capacity placement and process investment sequencing.
Market Dynamics
Process technology substitution is the dominant structural force reshaping propylene oxide manufacturing, as hydrogen peroxide oxidation routes displace chlorohydrin methods under tightening effluent standards across major production basins.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on hydrofluorocarbon blowing agents in insulation are redirecting formulators toward water-blown polyurethane systems, amplifying polyether polyol consumption.
- Automotive lightweighting specifications:Thermal performance mandates for electric vehicle battery enclosures are accelerating high-performance foam adoption in Germany, China, and the United States.
- China MEE emission standards:Tighter wastewater discharge limits are forcing capacity rationalization at older chlorohydrin facilities, tightening supply and supporting price formation for compliant producers.
Market Restraints
- Propylene feedstock volatility:Naphtha-to-olefin spreads and refinery operating rates transmit directly into oxide production economics, compressing margin visibility for non-integrated operators.
- Technology licensing concentration:Proprietary hydrogen peroxide process rights remain concentrated among a handful of technology licensors, constraining entry for independent producers.
- Chlorohydrin asset stranding:REACH compliance timelines and EPA effluent guidelines are accelerating depreciation of legacy European and North American chlorohydrin capacity.
Strategic Opportunities
- India construction insulation penetration:Building energy code enforcement is widening addressable demand for rigid polyurethane foam in commercial and residential envelopes.
- Specialty polyether polyols:High-functionality grades for automotive seating and medical devices command price premiums and resist commoditization pressures.
- Integrated propylene-to-oxide complexes:Captive feedstock supply and co-product optimization are reshaping competitive economics for greenfield investments.
Industry Challenges
- Process engineering talent scarcity:Epoxidation chemistry expertise and hydrogen peroxide handling certification requirements are narrowing the qualified operator pool.
- ISO 14001 audit timelines:Environmental management certification cycles are extending supplier qualification periods for automotive and construction sector contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propylene Oxide Market |
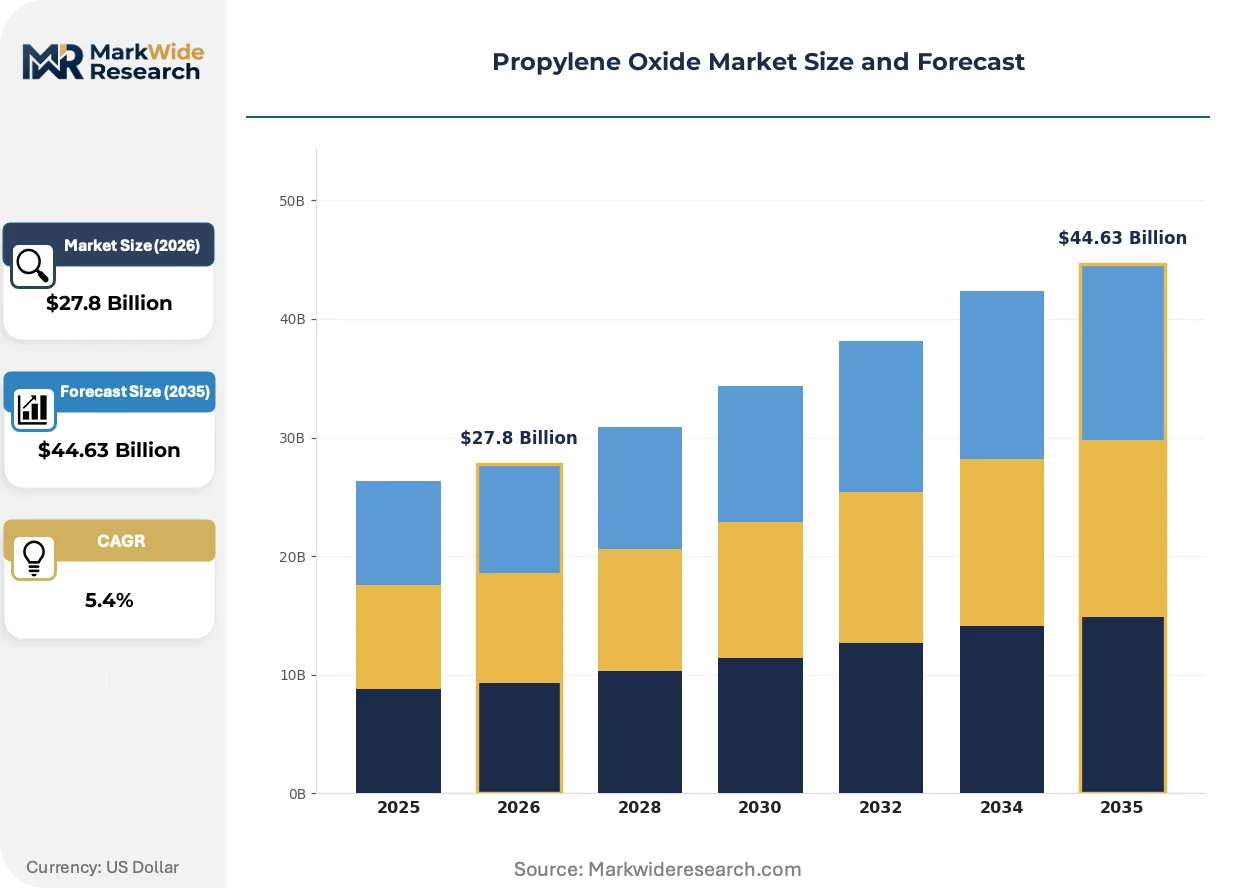
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $44.63 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyether Polyols, Propylene Glycol, Surfactants, Solvents End Use Industry: Automotive, Construction, Furniture, Electronics Technology: Hydrogen Peroxide, Chlorohydrin Process, Non-Catalytic, Catalytic Application: Adhesives, Insulation, Coatings, Cleaners |
| Companies Covered | Dow Inc., LyondellBasell Industries Holdings B.V., BASF SE, Shell PLC, INEOS Oxide, Huntsman Corporation, SABIC, Sumitomo Chemical Co., Ltd., Indorama Ventures Public Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propylene Oxide Market Emerging Trajectories
Technology licensing patterns and regulatory chemistry restrictions are fragmenting process economics and reshaping where new capacity can be placed profitably.
Electrochemical epoxidation pathways are fragmenting the technology landscape for propylene oxide production. Early-stage developers are piloting membrane-based systems that eliminate chlorine entirely from the reaction scheme. Automotive seating suppliers and insulation formulators are monitoring these trials for potential supply chain diversification. The technology is fragmenting capital allocation decisions as investors weigh unproven electrochemical yields against mature peroxide economics.
REACH chemical registration requirements are tightening substance data obligations for chlorohydrin-based propylene oxide sold into European polyurethane value chains. ECHA dossier updates are demanding expanded toxicological endpoints and exposure scenario documentation. Formulators serving construction and automotive OEMs are accelerating supplier audits to verify compliance documentation, compressing qualification timelines for non-European producers.
Specification-driven procurement is consolidating buying power among large polyurethane system houses and tier-one automotive suppliers. Long-term offtake agreements with minimum volume commitments are displacing spot market purchases for standard-grade polyether polyols. This concentration is most visible in Germany and the United States, where integrated chemical majors are securing captive outlets for captive oxide production.
Propylene Oxide Market Segmentation
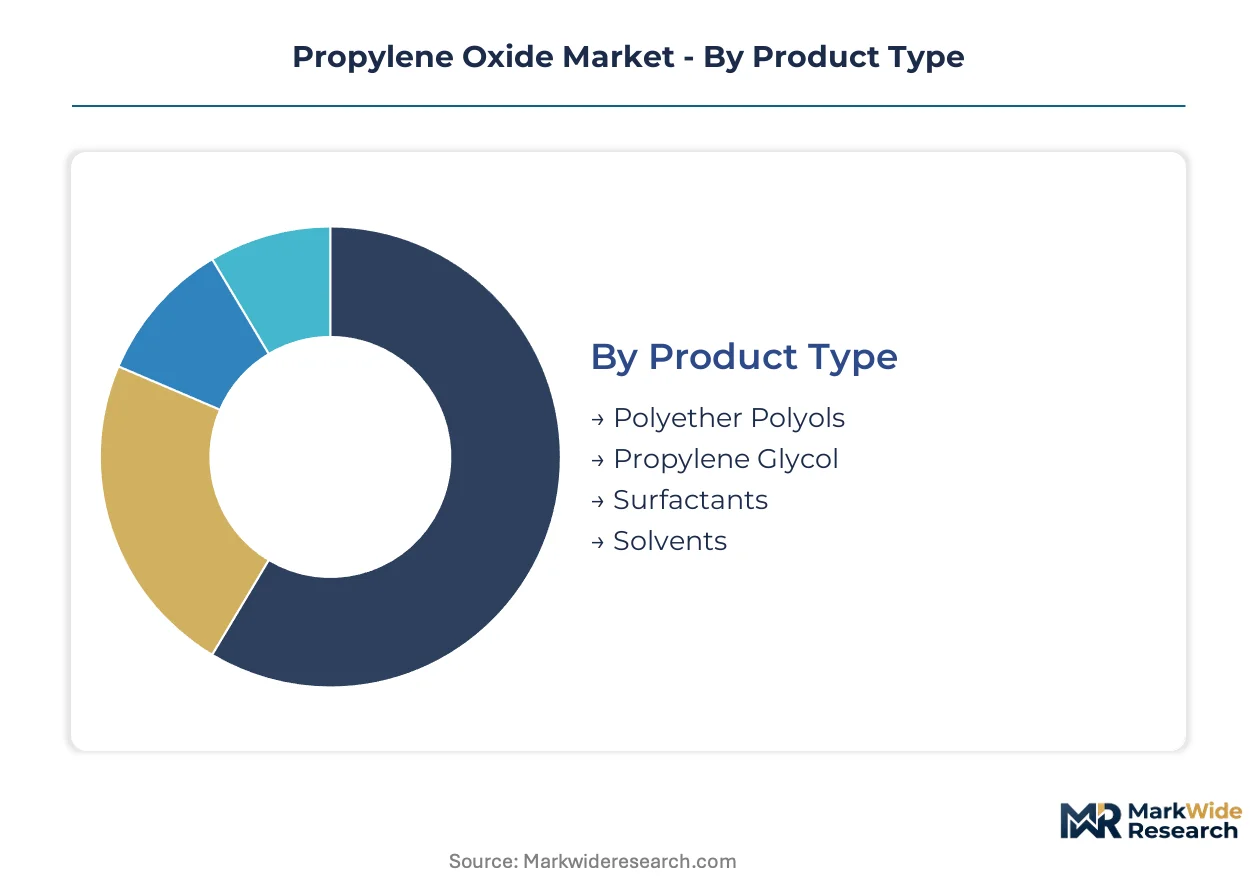
Segmentation reveals where substitution pressures and regulatory chemistry restrictions are fragmenting profit pools across propylene oxide value chains. Understanding these divisions helps stakeholders align capacity investments with the most defensible demand corridors.
Product Type:
Polyether polyols face the strongest substitution threat from bio-based polyols in automotive seating, while propylene glycol confronts glycerin-derived alternatives in de-icing and unsaturated polyester resins.
- Polyether Polyols:These long-chain polymers with terminal hydroxyl groups constitute the primary outlet for propylene oxide consumption. Furniture manufacturers in China and Germany absorb the largest volumes as water-blown polyurethane rigid foam displaces hydrofluorocarbon systems under EU F-Gas Regulation constraints.
- Propylene Glycol:A hygroscopic liquid serving pharmaceutical, food-grade, and industrial solvent applications. US FDA and EMA pharmacopeia standards bifurcate the market into high-purity and technical grades, with pharmaceutical specifications commanding substantial price premiums.
- Surfactants:Propylene oxide-derived non-ionic surfactants find use in industrial cleaning and personal care formulations.
- Solvents:Dipropylene glycol and tripropylene glycol ethers serve coating and ink applications with moderate growth trajectories.
Polyether polyols anchors the volume base while propylene glycol gains share at the steepest rate.
End Use Industry:
Cost tier differentiation separates specification-driven automotive contracts from price-sensitive construction procurement, with furniture occupying an intermediate position on performance requirements.
- Automotive:Electric vehicle battery enclosure thermal management specifications are accelerating high-performance foam adoption. OEMs in Germany, China, and the United States enforce ISO 14001 environmental management certification as a supplier gatekeeping mechanism.
- Construction:Rigid polyurethane insulation panels for commercial and residential building envelopes represent the dominant application. India's BIS energy code enforcement is widening addressable demand as states tighten compliance monitoring.
- Furniture:Flexible polyurethane foam for mattresses and upholstered seating consumes standard-grade polyether polyols in high volumes.
- Electronics:Encapsulation compounds and thermal interface materials utilize specialty-grade propylene oxide derivatives.
Construction absorbs the largest absolute volumes while automotive commands the highest price realization per kilogram.
Technology:
Application suitability divides the landscape between legacy chlorine chemistry and emerging peroxide routes, with catalytic variants gaining traction in greenfield planning.
- Hydrogen Peroxide:The oxidation route eliminates chlorine from the reaction scheme entirely, producing only water as co-product. China MEE emission standards and EPA effluent guidelines are accelerating capital migration toward this technology as chlorohydrin permits become harder to secure.
- Chlorohydrin Process:The traditional route employing chlorine and lime generates substantial calcium chloride waste streams. REACH registration requirements and ECHA dossier updates are tightening substance data obligations for European sales, compressing margins at legacy assets.
- Non-Catalytic:Direct oxidation approaches without heterogeneous catalysts occupy niche positions in pilot installations.
- Catalytic:Silver and gold-based epoxidation catalysts are under active development for potential yield improvements.
Hydrogen peroxide technology anchors the investment pipeline while catalytic approaches represent the most speculative R&D allocation.
Application:
Customer type fragmentation separates formulation specialists from direct OEM supply, with insulation system houses consolidating procurement power through long-term offtake agreements.
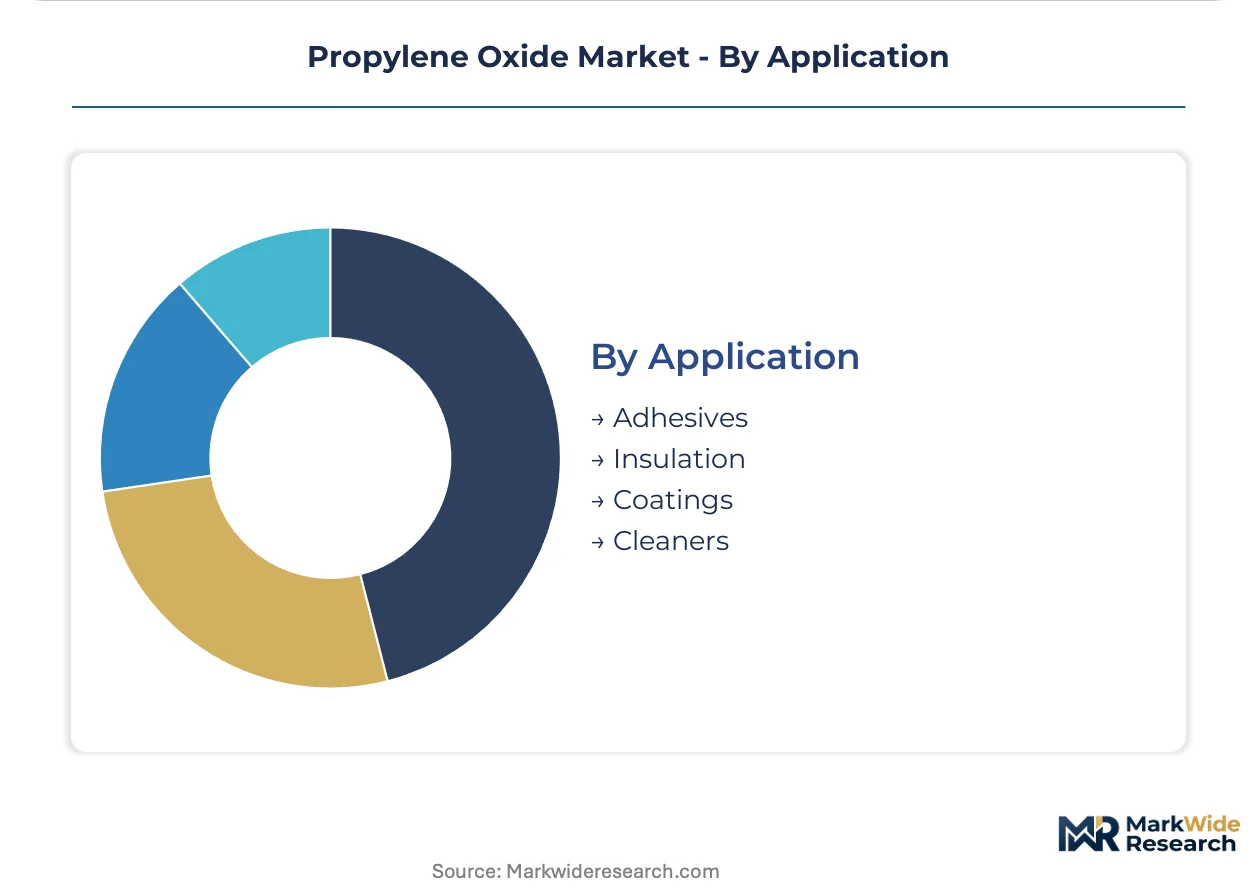
- Insulation:Rigid polyurethane foam for wall, roof, and refrigeration applications commands the largest propylene oxide consumption. EU F-Gas Regulation restrictions on hydrofluorocarbon blowing agents are redirecting formulators toward water-blown systems, amplifying polyether polyol demand.
- Adhesives:Reactive hot-melt and two-component polyurethane adhesives serve automotive assembly and construction bonding applications. Formulators prioritize low-monomer polyols to meet workplace exposure limits enforced by OSHA and European occupational health directives.
- Coatings:Polyurethane paint and varnish systems utilize propylene glycol ethers as coalescing agents and flow modifiers.
- Cleaners:Industrial degreasing and electronic cleaning formulations employ surfactant derivatives.
Insulation commands the dominant volume position while adhesives expand most quickly on automotive lightweighting specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive seating suppliers and insulation formulators concentrate procurement power across three distinct buyer archetypes: integrated chemical majors, independent polyurethane system houses, and specification-driven OEMs. This concentration pattern varies sharply by geography, with Germany and China hosting the most demanding certification requirements while India presents volume-scale opportunities.
China
Electric vehicle battery enclosure manufacturing and rigid foam insulation for commercial construction absorb the largest propylene oxide volumes. MEE emission standards are forcing chlorohydrin facility closures in Shandong and Jiangsu provinces. The Yangtze River Delta chemical cluster around Shanghai and Ningbo anchors hydrogen peroxide technology investments from state-backed enterprises.
Germany
Automotive lightweighting specifications for EV thermal management and high-performance building insulation drive premium-grade polyether polyol consumption. EU F-Gas Regulation enforcement through ECHA restricts hydrofluorocarbon blowing agents, redirecting formulators toward water-blown systems. The North Rhine-Westphalia chemical corridor around Leverkusen and Ludwigshafen concentrates BASF SE and Covestro production assets.
United States
Furniture manufacturing in the Southeast and automotive seating in the Midwest sustain flexible foam demand at scale. EPA effluent guidelines are accelerating chlorohydrin asset retirement along the Gulf Coast. Dow Inc. leverages its integrated propylene-to-oxide chain across Texas and Louisiana to maintain feedstock cost positions.
India
Commercial building envelope insulation and residential mattress manufacturing are widening addressable demand as BIS energy code enforcement tightens across Maharashtra and Gujarat. State-level compliance monitoring is accelerating rigid polyurethane panel adoption. The Gujarat chemical belt near Vadodara and Dahej is absorbing new hydrogen peroxide-based capacity additions.
Saudi Arabia
Construction insulation for megaproject developments and downstream petrochemical integration are driving propylene oxide consumption growth. SABIC's existing infrastructure anchors regional supply positioning. The Eastern Province industrial zone around Jubail is consolidating feedstock-advantaged production for export-oriented polyether polyol manufacturing.
Propylene Oxide Market Vendor Landscape
Player mix skews toward integrated petrochemical conglomerates with captive propylene supply and technology licensors controlling hydrogen peroxide process rights. Three structural tiers have crystallized: Gulf Coast and Middle Eastern producers with feedstock integration, European majors competing on specialty polyol differentiation, and Asian state-backed entities scaling peroxide-based capacity. Competitive moves center on technology licensing negotiations and long-term offtake agreements with automotive OEMs.
Within the integrated major tier, Dow Inc., LyondellBasell Industries Holdings B.V., and BASF SE exemplify divergent geographic and technological positioning. Dow anchors North American supply through Gulf Coast integration. LyondellBasell represents European hydrogen peroxide technology scale. BASF SE occupies the specialty polyether polyol differentiation vector. Shell PLC and INEOS Oxide sit within the European chlorohydrin transition segment. Huntsman Corporation, SABIC, Sumitomo Chemical Co., Ltd., and Indorama Ventures Public Company Limited populate the Asia-Pacific and Middle Eastern capacity expansion wave.
| Leading Market Players |
|---|
| Dow Inc. |
| LyondellBasell Industries Holdings B.V. |
| BASF SE |
| Shell PLC |
| INEOS Oxide |
| Huntsman Corporation |
| SABIC |
| Sumitomo Chemical Co., Ltd. |
| Indorama Ventures Public Company Limited |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at integrated propylene-to-oxide complexes on the US Gulf Coast establishes price floors that non-integrated operators cannot match, concentrating supply-side power among backward-integrated majors while compressing margin visibility for merchant producers dependent on spot propylene purchases.
Pricing Analysis
Cost-plus contracts with propylene indexation dominate long-term offtake agreements between integrated producers and polyurethane system houses. Price differentiation separates ISO 14001-certified supply for automotive OEMs from technical-grade material serving construction insulation. Pricing pressure stems from chlorohydrin asset rationalization in Europe and North America as REACH compliance costs accumulate. Construction insulation buyers exhibit highest price sensitivity, while automotive seating suppliers prioritize specification compliance over unit economics.
Supply Chain Analysis
China, the United States, and Germany anchor global propylene oxide production capacity, with the Yangtze River Delta and Gulf Coast chemical clusters feeding downstream polyether polyol manufacturing. Feedstock supply draws from refinery propylene streams, hydrogen peroxide merchant supply, and lime sourcing for residual chlorohydrin operations. Single-source vulnerability concentrates in hydrogen peroxide technology licensing, where proprietary process rights restrict capacity expansion. Distribution runs through integrated chemical majors' captive polyol production, long-term contracts with system houses, and spot sales to independent formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment protects incumbent positions: REACH registration requirements and ISO 14001 certification timelines create switching costs that lock in qualified suppliers and deter rapid supplier substitution.
For Market Incumbents: Secure long-term hydrogen peroxide technology licensing agreements before proprietary rights further concentrate among remaining licensors. Deepen backward integration into propylene supply through pipeline connectivity to regional crackers, defending margin position against feedstock volatility. Accelerate specialty polyether polyol R&D to escape commoditization in standard-grade construction insulation. For New Entrants and Emerging Players: ISO 14001 fast-track certification programs offer entry pathways into automotive supply chains where incumbent qualification backlogs extend procurement timelines. Target India's commercial building insulation segment where BIS energy code enforcement outpaces domestic capacity expansion. Pursue joint venture structures with state-backed entities in Gujarat to access feedstock-advantaged production economics. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hydrogen peroxide-based assets with remaining chlorohydrin transition runway over greenfield electrochemical bets. Acquisition targets should demonstrate captive propylene supply or secured long-term offtake with tier-one automotive suppliers. The signal to watch is MEE enforcement intensity in Shandong and Jiangsu provinces, which determines Chinese supply rationalization velocity and regional price formation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Gulf Coast crackers and Middle Eastern PDH units anchor cost-competitive oxide production. |
| Hydrogen Peroxide Technology Licensing | Proprietary process rights from LyondellBasell and Sumitomo constrain capacity expansion timing. |
| ISO 14001 Certification Investment | Automotive OEM supplier audits in Germany and the United States gate contract eligibility. |
| Specialty Polyether Polyol R&D | High-functionality grades for EV battery enclosures command price premiums over construction grades. |
| Long-term Supply Agreement Structuring | Minimum volume commitments with polyurethane system houses displace spot market exposure. |
Methodological Framework
A standing panel of plant operations directors, procurement leads at automotive seating suppliers, polyurethane system house technical directors, and hydrogen peroxide technology licensors provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA effluent guideline dockets, ECHA REACH registration databases, China MEE emission standard filings, and SEC 10-K disclosures from integrated chemical majors. Bottom-up capacity and demand modeling triangulated against top-down trade flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry concentration, technology route, and regional production hub clustering. CAGRs were derived from demand elasticity analysis against construction activity indices, automotive production forecasts, and insulation code adoption curves. Industry-specific inputs incorporated EU F-Gas Regulation phase-out timelines and MEE wastewater discharge limit enforcement patterns.
Underlying assumptions cover propylene feedstock cost trajectories, technology licensing availability, and regulatory compliance timeline adherence, with deviation risk concentrated in electrochemical epoxidation yield breakthroughs and carbon border adjustment implementation scope. Recalibration cycles align with material shifts in REACH dossier update schedules, MEE inspection intensity reporting, and F-Gas Regulation review proceedings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Sulfur Recovery Technology Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market
Industrial Chemicals
Cooling Tower Chemicals Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
Dynamite Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Flame-Retardant Phosphate Esters for EV E-Drivetrains Market
Industrial Chemicals
Hydrofluoric Acid (HF) for Semiconductor Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Global Battery Grade Lithium Hydroxide Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Global Plating on Plastics Market