
 Global Chemical Mechanical Planarization Market | 2026-2036
Global Chemical Mechanical Planarization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemical Mechanical Planarization Market Intelligence
The European Union's REACH regulation on chemical substances is hardening the cost-of-entry for new slurry formulations. This framework demands extensive testing and registration, favoring established suppliers with deep regulatory expertise. Applied Materials Inc. leverages its scale in integrated process toolsets, offering comprehensive solutions to chipmakers. Meanwhile, DuPont de Nemours Inc. specializes in advanced pad materials and slurry chemistries, driving performance at leading-edge nodes.
Chemical Mechanical Planarization is a surface finishing process that uses a combination of chemical slurry and mechanical polishing to achieve nanometer-scale planarity on semiconductor wafers. This precise flattening is critical for enabling the multi-layer interconnects in advanced integrated circuits. Consumables like slurry and pads constitute the largest product segments, with formulations tailored for specific materials such as copper or tungsten. Semiconductor fabrication is the primary application, driving volume, while use in MEMS production presents distinct technical requirements.
The market operates within a complex regulatory environment defined by quality standards like ISO 9001 and environmental rules. The US EPA governs the disposal of chemical waste from CMP processes, while China's GB standards dictate chemical safety and handling protocols. These regulations directly influence consumable formulation and operational costs for end users. The critical decision for fabricators involves balancing the performance gains from advanced consumables against their cost and environmental footprint.
Market Dynamics
The geographic concentration of semiconductor fabrication, driven by national industrial policies like the US CHIPS Act, is the central force shaping the Chemical Mechanical Planarization market. This funnels demand for consumables into a few key manufacturing hubs.
Growth Catalysts
- Advanced Device Architectures:The transition to complex 3D structures like FinFET and 3D NAND in logic and memory devices requires a greater number of precise planarization steps per wafer, directly increasing consumable consumption.
- Government Incentives:National initiatives, including the US CHIPS Act and the European Chips Act, are stimulating unprecedented investment in new foundry construction, creating a structural uplift in demand for CMP equipment and materials.
- AI Hardware Proliferation:The expansion of data centers and edge devices for artificial intelligence workloads necessitates the production of more powerful processors and accelerators, which rely on leading-edge CMP processes for their fabrication.
Market Restraints
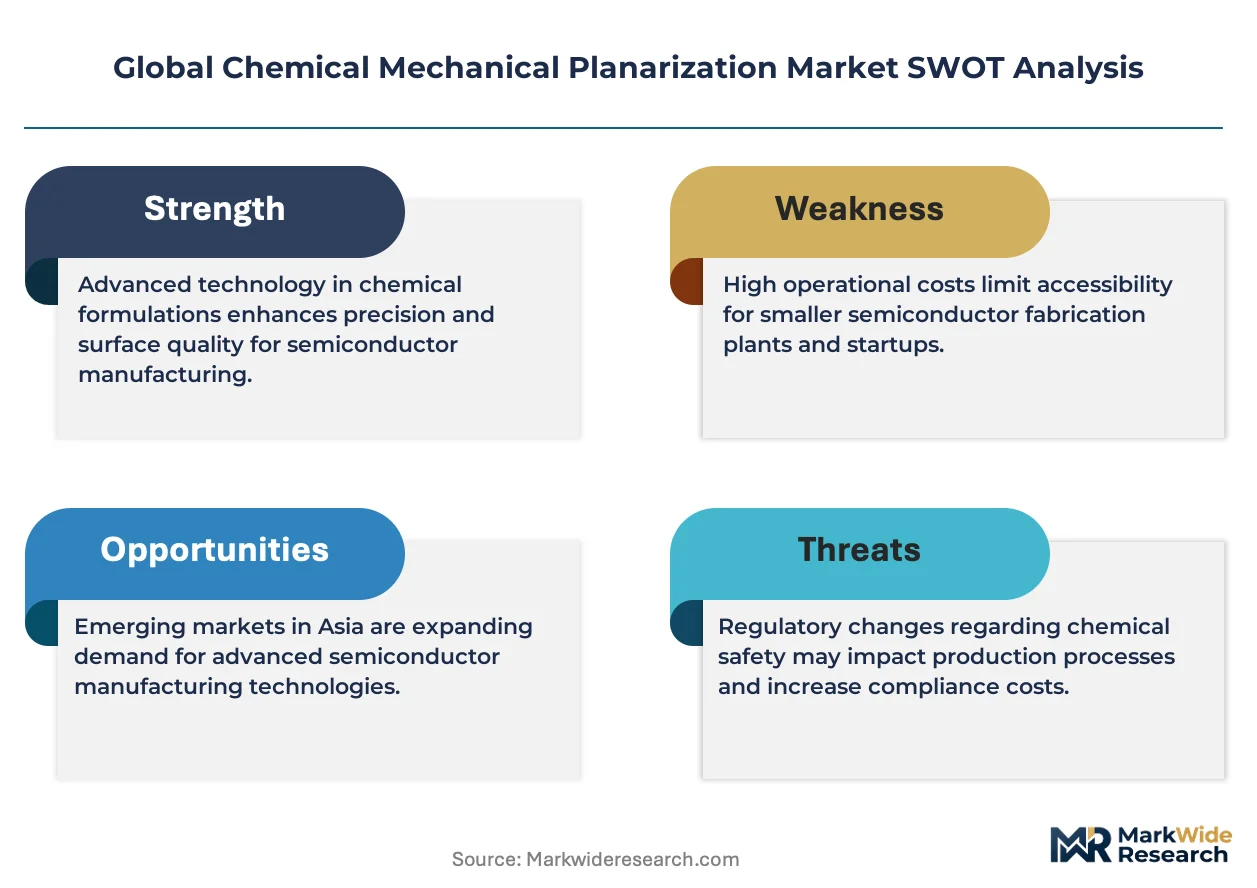
- Regulatory Hurdles:The European Union's REACH framework imposes significant testing and registration costs for new chemical slurry formulations, creating high barriers to entry and slowing innovation for suppliers not equipped for the compliance burden.
- Input Cost Volatility:The market is sensitive to price fluctuations of high-purity raw materials, such as cerium oxide and colloidal silica, whose supply chains are highly concentrated and subject to geopolitical risk.
- Defectivity Challenges:At advanced process nodes below 5nm, preventing nanometer-scale scratches, dishing, and contamination during the CMP process becomes exceptionally difficult, acting as a technical barrier to achieving high-yield manufacturing.
Strategic Opportunities
- New Material Planarization:Developing specialized slurry and pad combinations for emerging compound semiconductor materials, such as Gallium Nitride (GaN) and Silicon Carbide (SiC), opens new revenue streams in the power electronics and radio-frequency device sectors.
- Sustainable Consumables:Formulation of "green" slurries with reduced environmental impact and development of recyclable polishing pads address tightening EPA regulations and meet the corporate sustainability goals of major chipmakers.
- Emerging Fab Ecosystems:Supplying consumables to nascent semiconductor manufacturing initiatives in geographies like India, supported by its Production Linked Incentive (PLI) scheme, represents a long-term growth frontier beyond established hubs.
Industry Challenges
- Supply Chain Vulnerability:High concentration in the sourcing of critical raw materials for slurries and pads creates significant operational risk, exposing consumable manufacturers to potential disruptions from geopolitical tensions or logistical failures.
- Intellectual Property Complexity:Slurry formulations are valuable trade secrets, leading to a landscape where intense IP protection strategies can stifle collaborative development and create litigation risks for new market entrants.
- Specialized Talent Scarcity:A shortage of process engineers and materials scientists with deep expertise in CMP chemistry and physics presents a major operational challenge for foundries and suppliers, particularly in newly established manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemical Mechanical Planarization Market |
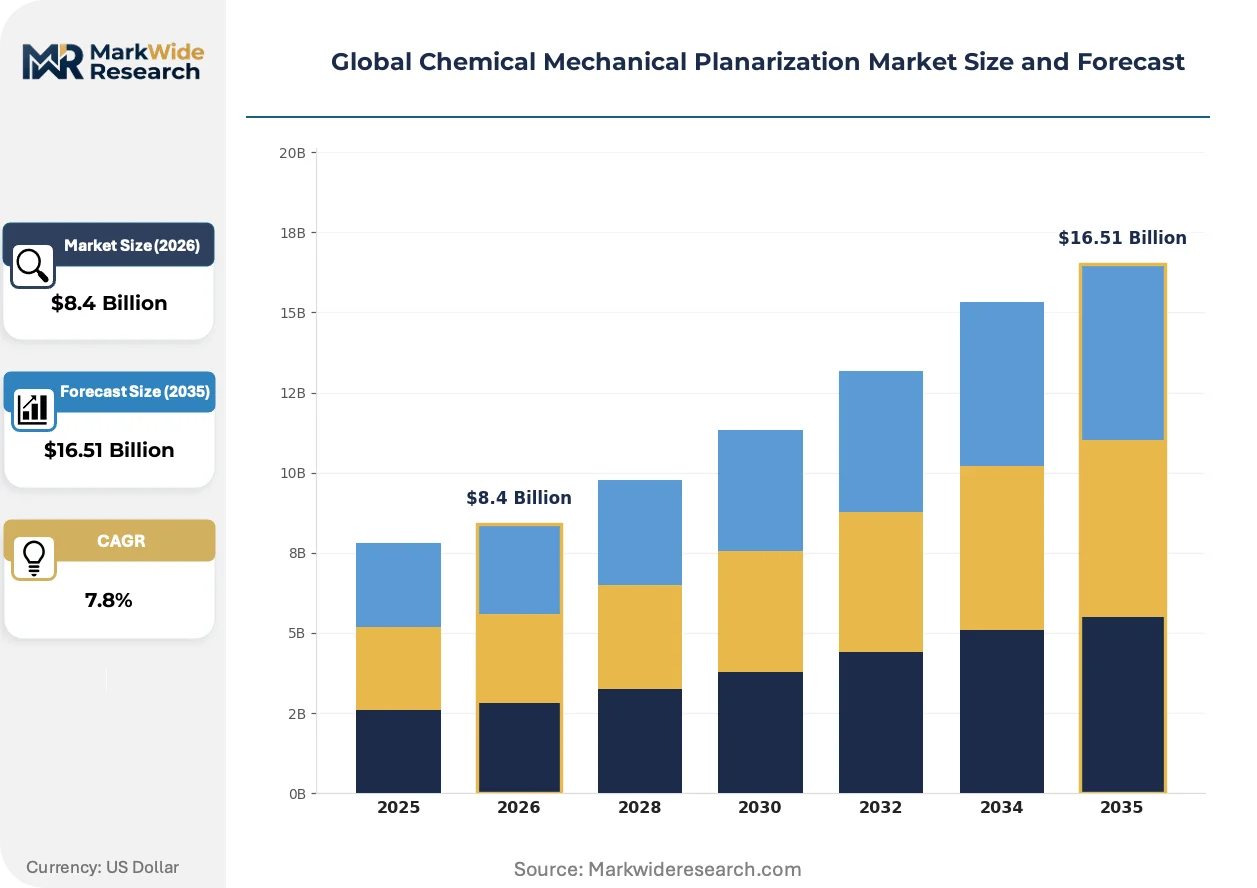
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slurry, Pads, Polishing Equipment, Conditioning Disks, Pad Cleaning Systems Application: Semiconductor Fabrication, Data Storage Devices, LED Manufacturing, MEMS Production, Optical Components Technology: Fixed Abrasive, Slurry-Based, Electrochemical, Ultraprecision Polishing, Hybrid Systems End User: Chipmakers, Data Storage Manufacturers, Display Producers, Precision Equipment Fabricators, Research Institutions |
| Companies Covered | Applied Materials Inc., DuPont de Nemours Inc., Cabot Microelectronics, Ebara Corporation, Entegris Inc., Fujimi Incorporated, Lapmaster Wolters GmbH, Hitachi High-Technologies Corporation, Lam Research Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemical Mechanical Planarization Market Strategic Shifts & Innovations
Innovation in the CMP market is driven by the dual needs of atomic-scale surface control and the accommodation of an increasingly diverse materials palette in semiconductor manufacturing. This forces a tighter integration of chemistry, mechanics, and process control.
Selective slurries provide the ability to remove one material at a much higher rate than another, a critical function for complex, multi-layered device topographies. Leading-edge semiconductor fabricators are widely adopting these formulations for sub-7nm logic and advanced memory production. This advanced chemical selectivity is converging with in-situ metrology, where real-time process monitoring enables dynamic adjustments to polishing parameters to maximize wafer yield.
China's national GB standards governing chemical safety, handling, and labeling are becoming increasingly rigorous. This directly impacts all slurry and pad suppliers operating in the country, mandating localized compliance testing and more extensive documentation for market access. Consequently, consumable vendors targeting China's domestic foundry expansion are embedding GB standard compliance into their core formulation and supply chain strategies.
A preference is emerging among top-tier chipmakers to procure CMP tools, consumables, and process support as a single, pre-qualified integrated solution from one vendor. This model displaces the traditional practice of buying equipment and consumables from separate suppliers and performing lengthy in-house qualification. The trend is most prominent in the United States and Taiwan, where new fabs prioritize accelerated production ramps and guaranteed process window stability.
Global Chemical Mechanical Planarization Market Segmentation
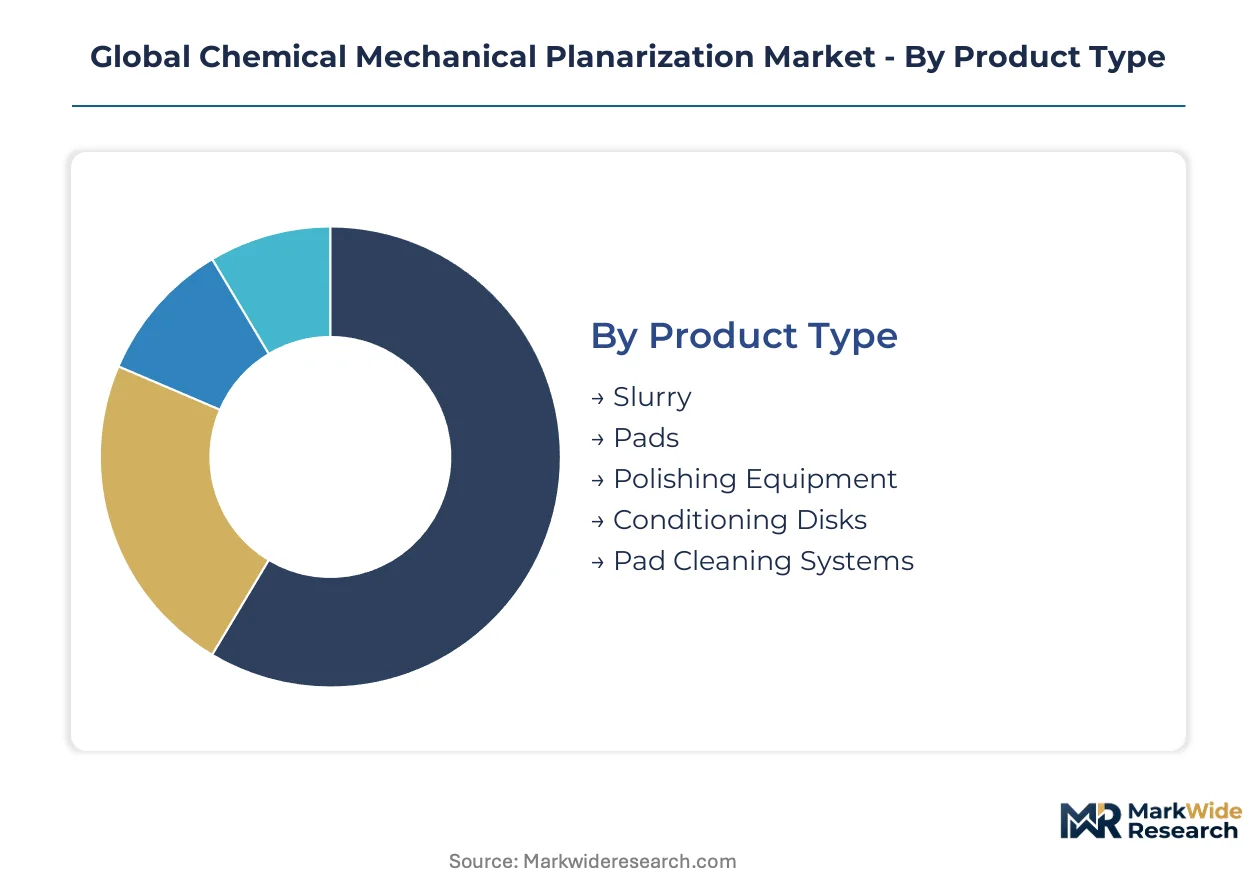
The Chemical Mechanical Planarization market's segmentation provides a structured view of its diverse components, applications, and technological approaches. Understanding these distinct segments is crucial for identifying areas of concentrated demand and emerging growth opportunities within semiconductor manufacturing.
Product Type:
The product segmentation reflects the varying degrees of integration and consumable nature within the overall planarization process, from chemical compounds to mechanical systems.
- Slurry:This critical chemical component, often tailored for specific materials like copper or tungsten, drives nanometer-scale planarity in advanced logic and memory devices. Demand for advanced slurry formulations concentrates in major semiconductor manufacturing hubs such as Taiwan and the United States due to leading-edge foundry expansion.
- Pads:These mechanical polishing interfaces, typically made from polyurethane or composite materials, are essential for uniform material removal and surface quality. Chipmakers in South Korea prioritize advanced pad materials for defectivity control at sub-5nm nodes, impacting yield.
- Polishing Equipment:Automated systems provide precise control over polishing parameters, crucial for high-volume and high-precision semiconductor fabrication.
- Conditioning Disks:These devices maintain the abrasive surface of polishing pads, ensuring consistent performance and extending pad life in critical processes.
- Pad Cleaning Systems:These systems remove slurry residue and debris from pads, preventing contamination and ensuring optimal polishing efficiency for subsequent wafers.
Volume placements concentrate in Slurry; the faster expansion belongs to Pads.
Application:
Application segmentation highlights the diverse industries relying on nanometer-scale surface finishing, each with distinct process requirements and material considerations.
- Semiconductor Fabrication:This primary application demands ultra-precise planarization for creating multi-layer interconnects in advanced logic and memory devices. Government incentives, including the US CHIPS Act, are driving significant demand for CMP consumables and equipment in this sector.
- MEMS Production:This segment requires specialized CMP processes for micron-scale structures and delicate materials used in sensors and actuators. Technical requirements for MEMS differ significantly from high-volume wafer production in terms of material selectivity.
- Data Storage Devices:CMP is utilized for achieving smooth, flat surfaces on magnetic media and read/write heads, essential for enhancing data density.
- LED Manufacturing:Planarization techniques are employed for substrate preparation, improving light extraction efficiency and overall device performance in optoelectronics.
- Optical Components:This area benefits from CMP to create ultra-smooth surfaces on lenses and mirrors, critical for high-performance imaging and laser systems.
The dominant end-use remains Semiconductor Fabrication, while MEMS Production presents specialized growth.
Technology:
The technology segmentation delineates various approaches to material removal, from purely mechanical to advanced chemical-mechanical synergies, responding to evolving material challenges.
- Slurry-Based:This predominant method combines chemical etching with mechanical abrasion via an abrasive fluid, achieving high material removal rates and superior surface quality. This technology is widely adopted for sub-7nm logic and advanced memory production across global foundries.
- Hybrid Systems:These systems integrate multiple polishing mechanisms, such as electrochemical and mechanical, to optimize material removal and surface finish for complex device architectures. Hybrid systems address new material planarization challenges in power electronics and advanced packaging.
- Fixed Abrasive:This technique utilizes abrasives embedded directly into the polishing pad, offering consistent removal rates and often reducing slurry consumption.
- Electrochemical:This method employs an electrochemical reaction to selectively remove material, frequently used for specific metal layers in semiconductor manufacturing.
- Ultraprecision Polishing:This advanced technique achieves atomic-scale surface flatness, critical for demanding applications like advanced optical components and next-generation lithography masks.
Traditional Slurry-Based methods command the largest share, but Hybrid Systems are gaining traction for next-generation processes.
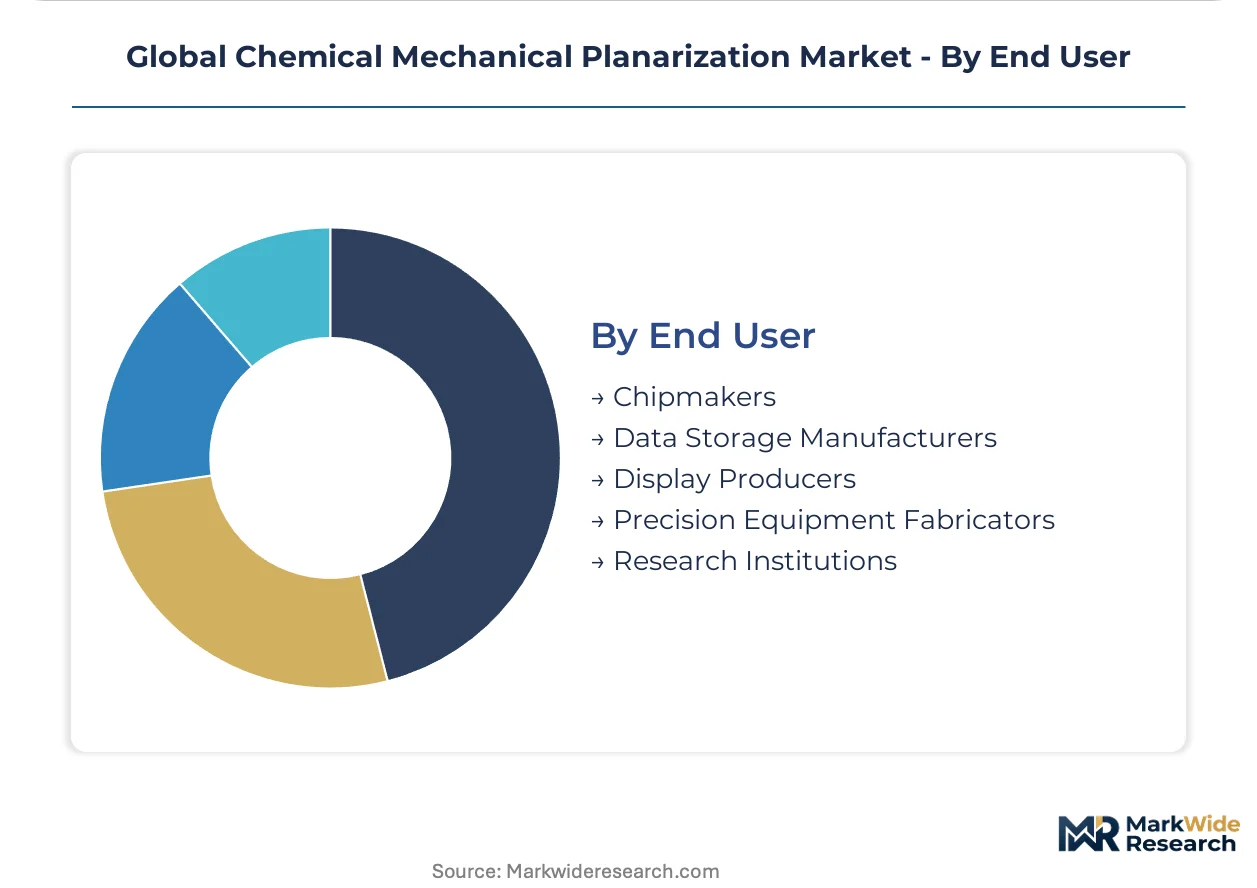
End User:
End-user segmentation differentiates the market based on the operational scale and specific requirements of various manufacturing and development entities, influencing product and service demand.
- Chipmakers:This segment represents the largest end-user group, comprising integrated device manufacturers and foundries that require vast quantities of CMP consumables for high-volume wafer processing. These entities prioritize integrated solutions and process stability for high-yield manufacturing in the United States and Taiwan.
- Research Institutions:These organizations engage in fundamental material science studies and process development for future semiconductor technologies, requiring specialized CMP tools and experimental slurries. Research institutions often contribute to the development of new material planarization techniques.
- Data Storage Manufacturers:These companies utilize CMP for producing smooth platter surfaces and read/write heads, essential for high-density data recording.
- Display Producers:This segment employs planarization for achieving uniform surfaces on glass substrates used in flat-panel displays, directly impacting visual quality.
- Precision Equipment Fabricators:These fabricators apply CMP for finishing critical components in high-accuracy machinery, ensuring tight tolerances and optimal performance.
Chipmakers drive the bulk of commercial demand, while Research Institutions influence future technological directions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US CHIPS Act and similar national initiatives are driving significant investment into new foundry construction, concentrating Chemical Mechanical Planarization (CMP) market demand. This strategic focus funnels consumables into key manufacturing hubs, influencing regional consumption patterns for advanced slurries and pads. These policies aim to secure domestic semiconductor supply chains and accelerate technological advancement.
United States
Demand for advanced logic and memory devices, coupled with the proliferation of AI hardware, drives significant CMP consumable consumption in the United States. The US CHIPS Act provides substantial incentives for domestic semiconductor manufacturing, stimulating new fab construction. Major semiconductor clusters in Arizona and New York are expanding, creating robust demand for high-precision planarization materials.
Taiwan
Taiwan's leading-edge foundry expansion, particularly for sub-7nm logic and advanced memory production, creates sustained demand for specialized CMP slurries and pads. Government support for the semiconductor industry helps maintain its global leadership in chip fabrication. The Hsinchu Science Park remains a critical hub, continuously pushing the boundaries of CMP process requirements.
South Korea
South Korean chipmakers prioritize advanced pad materials for defectivity control at sub-5nm nodes, directly impacting wafer yield in high-volume manufacturing. National semiconductor strategies support the development of next-generation memory and logic devices. Major fabrication facilities in Gyeonggi Province require continuous innovation in CMP consumables to meet stringent quality standards.
India
India's nascent semiconductor manufacturing initiatives represent a long-term growth frontier for CMP consumables, driven by the country's ambitious digital transformation goals. The Production Linked Incentive (PLI) scheme offers financial support to attract semiconductor and display manufacturing. Emerging industrial zones, such as those in Gujarat, are poised to become new centers for chip production and associated material demand.
Germany
Germany's high-precision semiconductor fabrication and advanced manufacturing sectors contribute to a steady demand for CMP equipment and materials. The European Chips Act aims to strengthen the region's semiconductor ecosystem, including new fab investments. The Silicon Saxony cluster in Dresden continues to be a focal point for advanced chip production and related process development.
Global Chemical Mechanical Planarization Market Key Industry Players
United States producers anchor one tier, offering integrated process toolsets and comprehensive solutions to chipmakers. European and Asian specialists hold another tier, providing advanced materials and specialized consumables. The market structure exhibits a tiered consolidation, with a few large players dominating the integrated solutions segment and numerous specialized firms competing in niche material markets. Strategic partnerships between equipment manufacturers and consumable suppliers, along with portfolio diversification into new material planarization, represent dominant competitive moves.
Specialists in advanced materials and chemistries include DuPont de Nemours Inc., known for its advanced pad materials and slurry chemistries. Applied Materials Inc. represents the integrated process toolset providers, offering comprehensive solutions to chipmakers. Cabot Microelectronics occupies a position as a key supplier of critical chemical mechanical planarization slurries, essential for various semiconductor manufacturing steps. These companies anchor different segments of the market, addressing diverse customer needs from integrated process support to specialized material performance.
| Leading Market Players |
|---|
| Applied Materials Inc. |
| DuPont de Nemours Inc. |
| Cabot Microelectronics |
| Ebara Corporation |
| Entegris Inc. |
| Fujimi Incorporated |
| Lapmaster Wolters GmbH |
| Hitachi High-Technologies Corporation |
| Lam Research Corporation |
| Others |
Cost & Logistics Intelligence
Cerium oxide commodity price fluctuations cascade directly through the Chemical Mechanical Planarization market, influencing slurry and pad pricing tiers for global chipmakers. This volatility impacts consumable manufacturers' cost structures and strategic sourcing decisions.
Pricing Analysis
Short lead-time delivery commands premium pricing for specialized CMP consumables, while spot inventory often receives discounts. The dominant pricing model involves contract-based long-term offtake agreements with major chipmakers. Price differentiation stems from quality grade, particularly for sub-5nm node performance, and comprehensive after-sales service bundles. Pricing softness emerges from chipmakers' continuous drive for cost efficiency in high-volume fabrication, impacting high-volume foundries more than less price-sensitive research institutions.
Supply Chain Analysis
Reverse logistics for used CMP pads and spent slurries are gaining importance, driven by environmental regulations and sustainability goals. The supply of critical raw materials, such as cerium oxide and colloidal silica, centers on China and other specialized producers. This creates single-source vulnerability and geopolitical risk for consumable manufacturers. Distribution runs through direct sales channels to major chipmakers and specialized regional distributors, particularly in Taiwan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Chemical Mechanical Planarization market is witnessing a vertical integration race, as players seek greater control over critical raw material supply chains or integrated process toolsets. This strategy aims to secure competitive advantage and operational resilience.
For Market Incumbents:Deploy integrated process toolsets to maintain market share against specialized material suppliers. Incumbents like Applied Materials Inc. should invest heavily in R&D for "green" slurries and advanced pad materials to meet tightening EPA regulations. This proactive approach mitigates threats from new material planarization challenges and regulatory hurdles like REACH. Consolidate market presence through strategic partnerships with emerging fab ecosystems.
For New Entrants and Emerging Players:Capture market share by specializing in new material planarization for compound semiconductors like Gallium Nitride and Silicon Carbide. New entrants should target India's nascent semiconductor manufacturing initiatives, leveraging its Production Linked Incentive scheme. Penetrate the MEMS production segment by offering highly specialized slurry and pad combinations. Rapid compliance with China's GB standards provides a distinct go-to-market advantage in that growing region.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers seeking specialized material science firms with strong intellectual property in selective slurries. This market offers long-term viability, driven by advanced device architectures and the proliferation of AI hardware. Acquisition targets should possess deep regulatory expertise for frameworks like REACH. Practitioners should monitor increased M&A activity in sustainable consumable development for early signals of market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | This move ensures a stable supply of high-purity raw materials for growing global demand. |
| Green Manufacturing Transition | This initiative addresses tightening environmental regulations and chipmakers' sustainability mandates. |
| Strategic Partnership | This forms integrated solutions, accelerating process qualification for major foundries. |
| Portfolio Diversification | This opens new revenue streams in emerging compound semiconductor markets. |
| IP Acquisition | This secures proprietary formulations for selective slurries and advanced pad chemistries. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, providing a robust foundational dataset. Primary research involved in-depth interviews with process engineers, R&D directors, and procurement leads at leading foundries and material suppliers. This approach combined bottom-up market sizing with top-down validation against industry reports and academic journals.
Regional manufacturing hubs, product types, and key application segments were modeled at a granular level across the analysis window. This analytical framework derived compound annual growth rates from historical trends and projected technological advancements. Forecast inputs included global wafer start projections and new fab construction timelines, particularly those driven by national incentives.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical tensions affecting raw material supply and rapid shifts in semiconductor process nodes. Practitioners should monitor major government policy announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
HFO (Hydrofluoro-Olefin) Refrigerants Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Pressure Filter Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Oilfield Scale Inhibitors Market
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Vacuum Degreasers Market
Industrial Chemicals
Silicates Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
Lime Market