
 Sodium Ascorbyl Phosphate (SAP) Market | 2026-2036
Sodium Ascorbyl Phosphate (SAP) Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Ascorbyl Phosphate (SAP) Market Analytics
Asset-light contract manufacturing partnerships are reshaping competitive entry in the Sodium Ascorbyl Phosphate (SAP) market, allowing smaller cosmetic ingredient suppliers to compete without captive fermentation or phosphorylation capacity. BASF SE leverages its integrated vitamin chemistry platform to sustain cost advantages across phosphorylated ascorbate derivatives. Evonik Industries AG anchors its position through specialty surfactant and active ingredient expertise that extends into stabilized vitamin C delivery systems. Nikko Chemicals specializes in Asian cosmetic raw material distribution, occupying a critical channel position between Chinese manufacturers and Japanese formulators.
Sodium Ascorbyl Phosphate is a phosphorylated ester of L-ascorbic acid, typically supplied as a white crystalline powder with enhanced aqueous stability and reduced oxidative degradation compared to native vitamin C, functioning primarily as an antioxidant active in topical and nutraceutical applications. The powder product type dominates current manufacturing volumes due to superior shelf stability and ease of formulation integration, though serum applications are generating faster value growth as premium skin care brands prioritize bioavailable vitamin C delivery. Skin care application leads absolute demand, while pharmaceutical formulations represent a concentrated margin pool where CDSCO and FDA compliance requirements limit supplier qualification.
REACH registration requirements in Europe and CDSCO cosmetic ingredient guidelines in India are tightening purity and impurity profiling standards, directly shaping which suppliers qualify for pharmaceutical-grade and dermal-grade procurement lists. FDA oversight of cosmetic active ingredients under the Modernization of Cosmetics Regulation Act is elevating documentation burdens for U.S.-market access. Stakeholders must monitor regulatory divergence between major cosmetic markets to determine whether centralized multi-jurisdiction manufacturing or region-specific compliance investments offer lower total cost of qualification.
Market Dynamics
Phosphorylation process optimization and REACH-driven purity escalation are compressing margins for non-integrated SAP suppliers while rewarding asset-light contract manufacturers with qualified CDSCO and FDA documentation capabilities.
Growth Catalysts
- CDSCO cosmetic ingredient guidelines:India's tightening dermal-grade standards are filtering out unqualified suppliers and concentrating procurement among documented manufacturers with validated impurity profiling.
- Serum formulation demand:Premium skin care brands in China and Japan are prioritizing bioavailable vitamin C delivery systems, accelerating value migration from powder to liquid dosage forms.
- Fermentation capacity expansion:Domestic Chinese pharmaceutical producers are scaling L-ascorbic acid precursor output, reducing import dependency for phosphorylation feedstock.
Market Restraints
- L-ascorbic acid price volatility:Corn-derived sorbitol feedstock costs fluctuate with agricultural commodity cycles, transmitting margin pressure downstream to phosphorylation specialists.
- Phosphorylation reactor concentration:Contract manufacturing capacity clusters in Jiangsu and Zhejiang provinces, creating geographic supply risk from localized environmental enforcement actions.
- Native vitamin C substitution:Ethyl ascorbic acid and magnesium ascorbyl phosphate compete in cost-sensitive cosmetic formulations, limiting SAP pricing power in economy-tier segments.
Strategic Opportunities
- Indian pharmaceutical-grade qualification:CDSCO's expanding dermal-active registry offers first-mover advantage for suppliers investing in localized stability testing and documentation.
- Encapsulation technology convergence:Liposomal delivery systems combined with SAP are opening nutraceutical applications beyond topical cosmetics, targeting oral antioxidant positioning.
- Direct-to-formulator digital channels:Specialty chemical platforms are disintermediating traditional Asian raw material distributors, enabling smaller European suppliers to access Chinese cosmetic labs.
Industry Challenges
- Phosphorylation chemist scarcity:Specialized expertise in selective esterification under controlled pH conditions remains concentrated among aging technical workforces in Germany and Japan.
- Multi-jurisdiction dossier compilation:Simultaneous REACH, FDA, and CDSCO qualification demands redundant stability studies, stretching documentation timelines for mid-cap suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Ascorbyl Phosphate (SAP) Market |
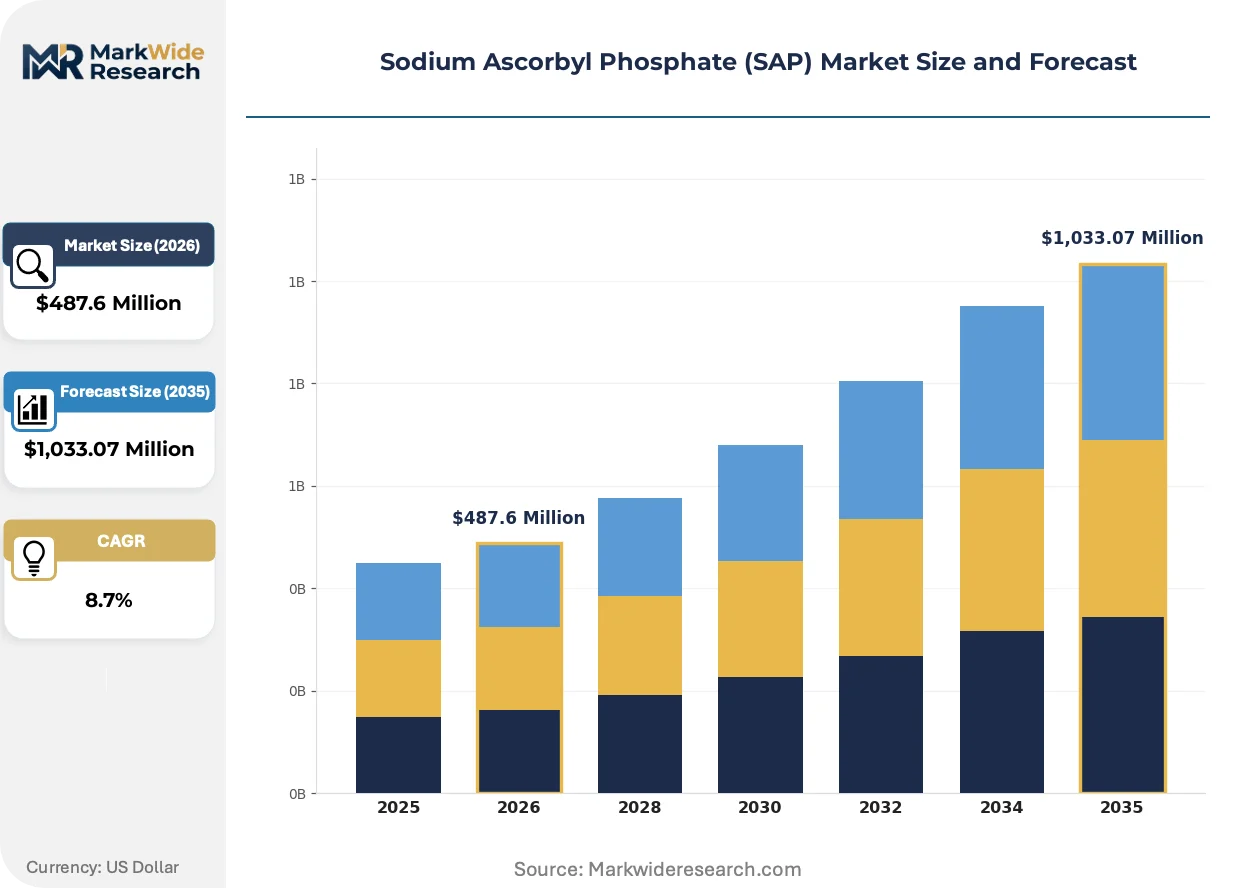
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Serum, Cream End User: Cosmetic Manufacturers, Pharmaceutical Companies, Research Institutions, Consumer Goods Application: Skin Care, Hair Care, Nutritional Supplements, Pharmaceutical Formulations Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | BASF SE, Evonik Industries AG, Merck KGaA, Hawkins, Inc., Haihang Industry, Nikko Chemicals, Universal Preserve-A-Chem, Shandong Xinhua Pharmaceutical Co., Ltd., Zhejiang Tianxin Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Ascorbyl Phosphate (SAP) Market Evolving Landscape
Stabilization chemistry and regulatory documentation automation are redefining competitive advantage, separating suppliers with integrated quality systems from commodity phosphorylation operators.
Continuous-flow phosphorylation reactors are replacing batch esterification in advanced manufacturing facilities, enabling real-time pH control and reduced oxidative degradation during sodium salt formation. European and Japanese cosmetic ingredient suppliers are adopting this capital-intensive technology to secure pharmaceutical-grade qualification. Native L-ascorbic acid powder for direct topical use is rendering obsolete in premium serum applications where aqueous stability and formulation compatibility determine procurement decisions.
REACH registration requirements for phosphorylated ascorbate derivatives are tightening impurity profiling standards beyond cosmetic-grade thresholds toward pharmaceutical specifications. ECHA's evolving guidance on esterified vitamin C substances is forcing reformulation of existing safety data sheets and exposure assessments. German and French cosmetic manufacturers are responding by consolidating supplier lists to pre-qualified vendors with complete dossier packages, excluding newer market entrants.
Chinese cosmetic formulators are compressing supplier qualification cycles from 18-month documentation reviews to 6-month pilot-scale validation programs. Direct technical collaboration between phosphorylation specialists and brand R&D labs is displacing traditional distributor-mediated procurement in Shanghai and Guangzhou clusters. This pattern is most visible among domestic skin care brands targeting Tmall premium positioning, where formulation speed-to-market outweighs historical supplier relationships.
Sodium Ascorbyl Phosphate (SAP) Market Segmentation
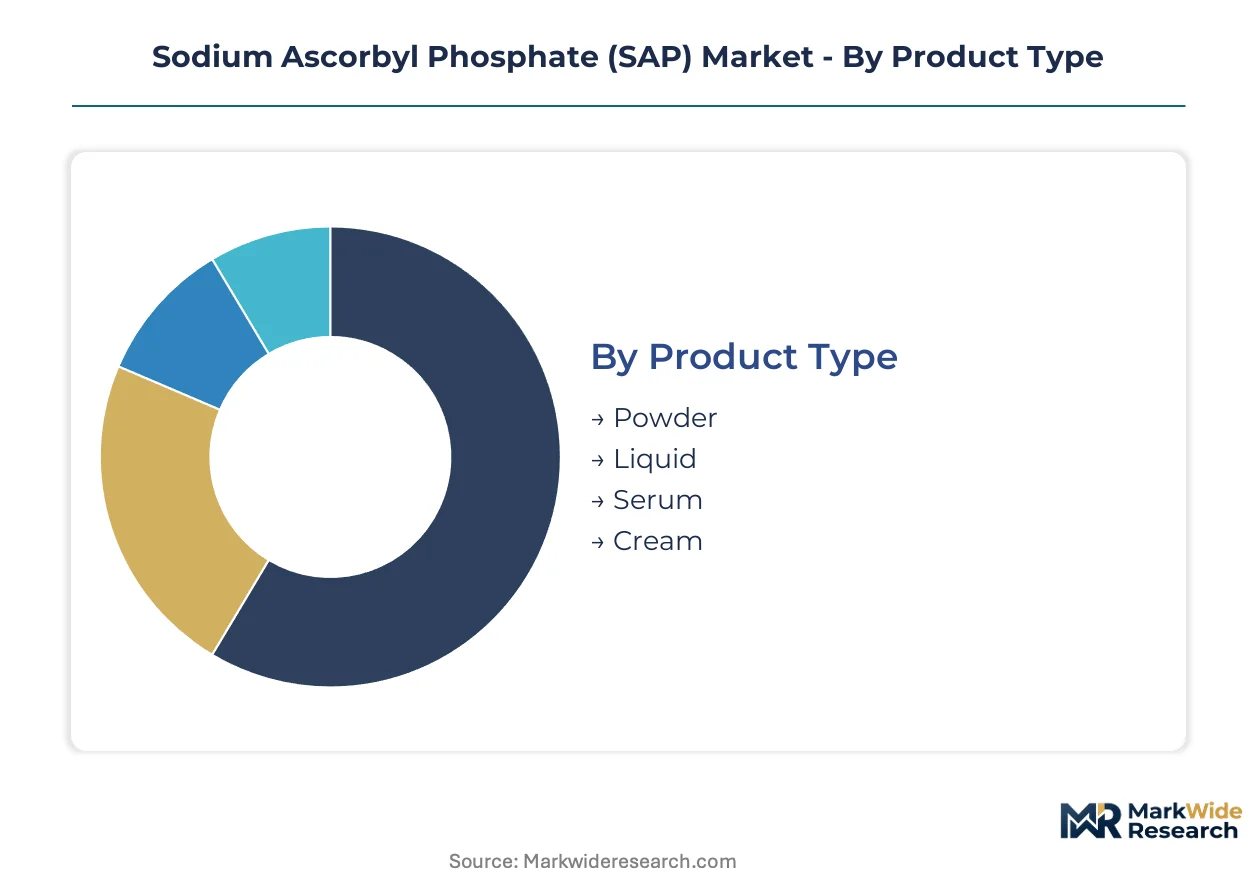
Segmentation in the Sodium Ascorbyl Phosphate market reveals distinct technical and commercial requirements across product formats and end-use verticals. Each segment demands specialized stability profiles, documentation standards, and supply chain configurations that shape supplier qualification and procurement patterns.
Product Type:
After-sales service intensity varies sharply across product formats, with liquid and serum forms requiring formulation technical support that powder suppliers rarely provide.
- Powder:Crystalline sodium ascorbyl phosphate with superior shelf stability and standardized assay specifications dominates bulk procurement from Chinese and Indian cosmetic manufacturers. Jiangsu-based phosphorylation facilities supply multi-ton quantities to formulators seeking cost-efficient antioxidant integration without aqueous degradation risks.
- Liquid:Pre-solubilized SAP concentrates reduce manufacturing complexity for mid-tier cosmetic labs lacking controlled pH environments. Demand concentrates in European contract manufacturers seeking REACH-compliant, ready-to-dilute inputs that bypass in-house phosphorylation investment.
- Serum:High-potency delivery systems command premium positioning in Japanese and South Korean skin care markets. These formulations require stabilized pH buffering and compatibility testing with common cosmetic actives.
- Cream:Emulsion-compatible SAP variants with lipophilic coating address occlusion stability challenges in leave-on topical products. Formulators in Brazilian and Mexican markets favor this format for regional humidity conditions.
By volume, Powder leads. By growth pace, Serum is ahead.
End User:
Cost tier differentiation separates qualified pharmaceutical-grade suppliers from commodity cosmetic-grade providers, with documentation burden as the primary sorting mechanism.
- Cosmetic Manufacturers:Skin care formulators in Shanghai, Tokyo, and Seoul drive specification innovation, demanding batch-to-batch color consistency and heavy metal testing below 10 ppm thresholds. CDSCO-registered Indian suppliers are gaining share in this segment through accelerated qualification timelines.
- Pharmaceutical Companies:Dermal-active and nutraceutical applications require FDA or EMA drug master file submissions, limiting viable suppliers to integrated vitamin chemistry platforms with validated impurity profiling. German and Swiss manufacturers anchor this concentrated margin pool.
- Research Institutions:Academic and clinical trial sponsors procure small-batch, high-purity reference materials for stability studies and comparative efficacy research. Custom synthesis capabilities differentiate suppliers serving this fragmented demand.
- Consumer Goods:Mass-market personal care brands prioritize cost optimization over performance differentiation, sourcing through Asian trading houses with limited technical service attachment.
Cosmetic Manufacturers absorb the largest absolute volumes. Pharmaceutical Companies generate the steepest margin expansion trajectory.
Application:
Volume concentration in skin care creates supply chain scale economies that hair care and pharmaceutical applications leverage for secondary sourcing.
- Skin Care:Facial serums, moisturizers, and sun care formulations constitute the dominant consumption channel, with Chinese domestic brands on Tmall and Douyin driving rapid formulation cycles. Phosphorylated ascorbate stability in aqueous bases determines procurement decisions.
- Hair Care:Scalp treatments and conditioning products incorporate SAP for oxidative stress protection in follicular applications. Japanese and South Korean hair science specialists specify lower molecular weight derivatives for cuticle penetration.
- Nutritional Supplements:Oral antioxidant positioning in encapsulated formats opens adjacent demand beyond topical cosmetics. Liposomal delivery convergence with SAP is expanding this application fastest.
- Pharmaceutical Formulations:Wound healing and photodamage repair indications require sterile-grade SAP with endotoxin testing, restricting supply to cGMP-certified fermentation and phosphorylation facilities.
Skin Care commands volume leadership. Nutritional Supplements are climbing the fastest.
Distribution Channel:
Customer type stratification separates technical buyers seeking direct manufacturer relationships from price-sensitive purchasers defaulting to intermediated channels.
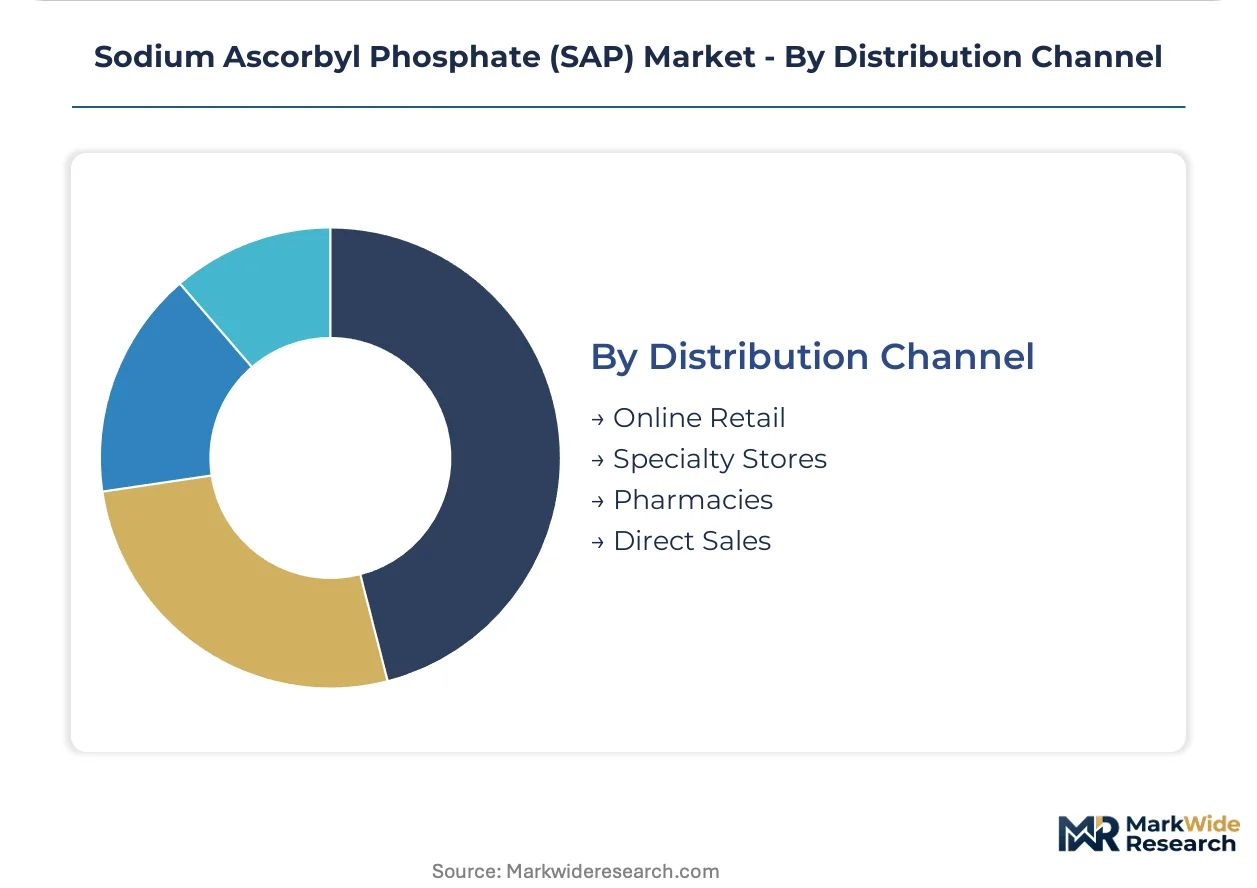
- Online Retail:Specialty chemical platforms and B2B marketplaces are disintermediating traditional Asian raw material distributors, enabling European mid-cap suppliers to access Chinese cosmetic R&D labs without local presence investment.
- Specialty Stores:Regional cosmetic ingredient distributors in Mumbai, Bangkok, and Jakarta maintain inventory positions for just-in-time delivery to formulators with limited storage capacity.
- Pharmacies:Compounding and small-batch pharmaceutical procurement flows through licensed distributors with cold chain capabilities for temperature-sensitive liquid concentrates.
- Direct Sales:Integrated manufacturers with captive fermentation capacity, including select Chinese pharmaceutical groups, bypass channel intermediaries for large-account relationships.
Online Retail is expanding most quickly. Specialty Stores retain the largest transaction volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented phosphorylation capacity in China and Germany supplies formulators across cosmetic and pharmaceutical tiers, while import-dependent markets in India and Brazil concentrate procurement among documented suppliers with multi-jurisdiction dossiers. Trade flows reflect regulatory qualification asymmetries rather than pure cost arbitrage.
China
Jiangsu and Zhejiang provinces host concentrated contract manufacturing clusters serving domestic cosmetic brands on Tmall and Douyin. NMPA cosmetic ingredient registration requirements are tightening stability documentation for imported SAP. Shanghai-based formulators are compressing supplier qualification cycles to six months through direct technical collaboration with phosphorylation specialists.
Germany
Integrated vitamin chemistry platforms anchor pharmaceutical-grade supply to EMA-registered drug master file holders. REACH registration requirements for phosphorylated ascorbate derivatives are elevating impurity profiling standards beyond cosmetic thresholds. Bavarian and North Rhine-Westphalian chemical parks concentrate fermentation and esterification capacity under unified environmental permits.
India
CDSCO cosmetic ingredient guidelines are filtering procurement toward documented manufacturers with validated heavy metal testing below 10 ppm. Maharashtra and Gujarat-based formulators source through Mumbai distributors for just-in-time delivery. Domestic pharmaceutical producers are scaling L-ascorbic acid precursor output to reduce phosphorylation feedstock import dependency.
United States
FDA oversight under the Modernization of Cosmetics Regulation Act is elevating documentation burdens for active ingredient market access. New Jersey and California cosmetic labs prioritize suppliers with complete REACH dossier packages to streamline dual-qualification. Direct-to-formulator digital channels are disintermediating traditional Asian raw material distributors.
Japan
PMDA cosmetic standards and METI chemical management frameworks shape premium skin care formulation requirements. Tokyo and Osaka-based brands specify serum-grade SAP with batch-to-batch color consistency for high-potency delivery systems. Nikko Chemicals occupies critical channel positioning between Chinese manufacturers and domestic formulators.
Sodium Ascorbyl Phosphate (SAP) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with phosphorylation and fermentation assets. The supplier base stratifies between integrated vitamin chemistry platforms with captive precursor supply and asset-light contract manufacturers with qualified documentation capabilities. Three archetypes dominate: German-Swiss pharmaceutical-grade integrators, Chinese fermentation-backed phosphorylation operators, and Japanese-Korean cosmetic raw material distributors. Competitive moves center on CDSCO and FDA qualification investments and continuous-flow reactor adoption for pharmaceutical-grade purity.
Among integrated chemistry platforms, BASF SE and Evonik Industries AG exemplify the pharmaceutical-grade tier with REACH-registered dossier capabilities. Nikko Chemicals occupies the distribution-specialist archetype, bridging Chinese manufacturing scale and Japanese formulation precision. Shandong Xinhua Pharmaceutical Co., Ltd. and Zhejiang Tianxin Pharmaceutical Co., Ltd. represent Chinese fermentation-backed phosphorylation capacity serving both domestic cosmetic brands and export markets.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Merck KGaA |
| Hawkins, Inc. |
| Haihang Industry |
| Nikko Chemicals |
| Universal Preserve-A-Chem |
| Shandong Xinhua Pharmaceutical Co., Ltd. |
| Zhejiang Tianxin Pharmaceutical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Jiangsu and Zhejiang fermentation clusters in China anchor upstream phosphorylation capacity, concentrating margin capture among integrated operators with captive L-ascorbic acid supply while forcing non-integrated contract manufacturers toward documentation-based differentiation.
Pricing Analysis
Cosmetic formulators anchor a three-tier pricing structure across pharmaceutical-grade, dermal-grade, and cosmetic-grade certification levels. Price differentiation hinges on REACH dossier completeness and CDSCO registration status alongside batch-to-batch color consistency guarantees. Cost compression in economy-tier powder supply is intensifying because ethyl ascorbic acid and magnesium ascorbyl phosphate substitution limits SAP pricing power. Mass-market personal care brands exhibit highest price sensitivity; pharmaceutical companies with sterile-grade requirements show lowest.
Supply Chain Analysis
Corn-derived sorbitol feedstock draws from agricultural commodity markets in the United States, Brazil, and China, transmitting price volatility downstream to phosphorylation specialists. Raw material dependencies center on L-ascorbic acid precursor, phosphorylation reagents, and pH stabilization chemistries. Single-source vulnerability concentrates in Jiangsu and Zhejiang reactor clusters exposed to localized environmental enforcement. Distribution runs through specialty chemical platforms disintermediating traditional Asian raw material distributors for direct manufacturer access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics around regulatory documentation interoperability is reshaping competitive advantage, as REACH-registered dossiers become transferable credentials across FDA and CDSCO qualification pathways.
For Market Incumbents: Harden CDSCO and FDA dossier defenses through continuous-flow reactor investments that secure pharmaceutical-grade purity thresholds. Consolidate supplier qualification relationships with Shanghai and Guangzhou formulators before digital channel disintermediation accelerates. Capacity expansion in Bavarian chemical parks reinforces EMA-registered drug master file positions against Chinese fermentation-backed challengers.
For New Entrants and Emerging Players: Build out asset-light contract manufacturing partnerships with validated impurity profiling capabilities to bypass captive fermentation capital requirements. Indian pharmaceutical-grade qualification offers the most penetrable white-space given CDSCO's expanding dermal-active registry and compressed six-month validation cycles. Direct-to-formulator digital channels enable European mid-cap suppliers to access Chinese cosmetic R&D labs without local presence investment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous-flow phosphorylation reactor installations as pharmaceutical-grade qualification demands replace batch esterification assets. Long-term viability favors integrated vitamin chemistry platforms with backward control over fermentation feedstock and multi-jurisdiction dossier capabilities. Monitor liposomal delivery system convergence with SAP as the inflection signal for nutraceutical application expansion beyond topical cosmetics.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Reactor Adoption | Real-time pH control enables pharmaceutical-grade qualification for EMA-registered suppliers. |
| CDSCO Registration Investment | Accelerated six-month validation timelines capture Indian dermal-grade procurement concentration. |
| Backward Integration into Fermentation | Captive L-ascorbic acid supply insulates margin pools from sorbitol commodity volatility. |
| Direct-to-Formulator Digital Channels | Specialty chemical platforms disintermediate Nikko Chemicals-style distributor intermediaries. |
| Liposomal Delivery Convergence | Encapsulation technology opens oral antioxidant positioning beyond topical skin care applications. |
Research Methodology
Desk research of customs trade data, ECHA REACH registration databases, and CDSCO cosmetic ingredient filings preceded structured interviews with phosphorylation plant managers, cosmetic formulator R&D directors, and specialty chemical distribution channel partners. Primary fieldwork with Jiangsu-based contract manufacturers and Mumbai raw material distributors combined with secondary validation from SEC 10-K filings of integrated vitamin chemistry platforms. Bottom-up volume triangulation across powder, liquid, and serum product formats reconciled against top-down market sizing.
Assumptions held regulatory divergence patterns and corn-sorbitol price correlation coefficients fixed across the projection horizon while varying CDSCO enforcement intensity and serum formulation adoption curves. Segmentation dimensions modeled include product type, end-user certification tier, application stability requirements, and regional production hub concentration. CAGRs derived from logistic diffusion curves fitted to serum-grade SAP penetration patterns in Japanese and South Korean premium skin care markets, with cross-checking against pharmaceutical-grade capacity expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed pharmaceutical groups or accelerated FDA enforcement under MoCRA would shift outcomes beyond modeled ranges. Cross-checking against EMA drug master file submission rates and NMPA cosmetic ingredient registration volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Aerosol Cans Market
Specialty Chemicals
North America Perms and Relaxants Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Lanolin Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
4-ADPA Market
Specialty Chemicals
Middle East and Africa Amino Acids Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
Organo-Modified Bentonite Market
Specialty Chemicals
Gallic Acid Market
Specialty Chemicals
Global Aerosol Market
Specialty Chemicals
Global Chemical Vapor Deposition (CVD) Market
Specialty Chemicals
Caryophyllene Market
Specialty Chemicals
Glutathione Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market