
 Stainless Steel Foil Market | 2026-2036
Stainless Steel Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Foil Market Analytics
Electronics OEMs are unwinding legacy procurement from general-purpose distributors toward mill-direct relationships. NIPPON STEEL CORPORATION leverages captive cold-rolling capacity to serve Asian semiconductor fabricators. Outokumpu anchors European supply through integrated ferrochrome operations in Finland. ArcelorMittal competes on scale, shipping precision slit coils from Belgian mills to automotive Tier-1 stampers.
Stainless steel foil denotes cold-rolled austenitic or ferritic sheet below 0.2 mm thickness, typically supplied in 300-series or 400-series grades with controlled surface finish per ASTM A240 or EN 10088. Manufacturers produce it via tandem rolling with intermediate annealing to achieve tight gauge tolerances for heat dissipation, corrosion barriers, and electromagnetic shielding. Thin-gauge rolls command premium positioning in semiconductor and aerospace channels where thickness uniformity directly determines yield. Heat shield applications across the thickness taxonomy show fastest volume expansion as EV thermal management architectures multiply. Custom sizes capture disproportionate margin pools due to setup complexity and die inventory requirements that deter commodity competitors.
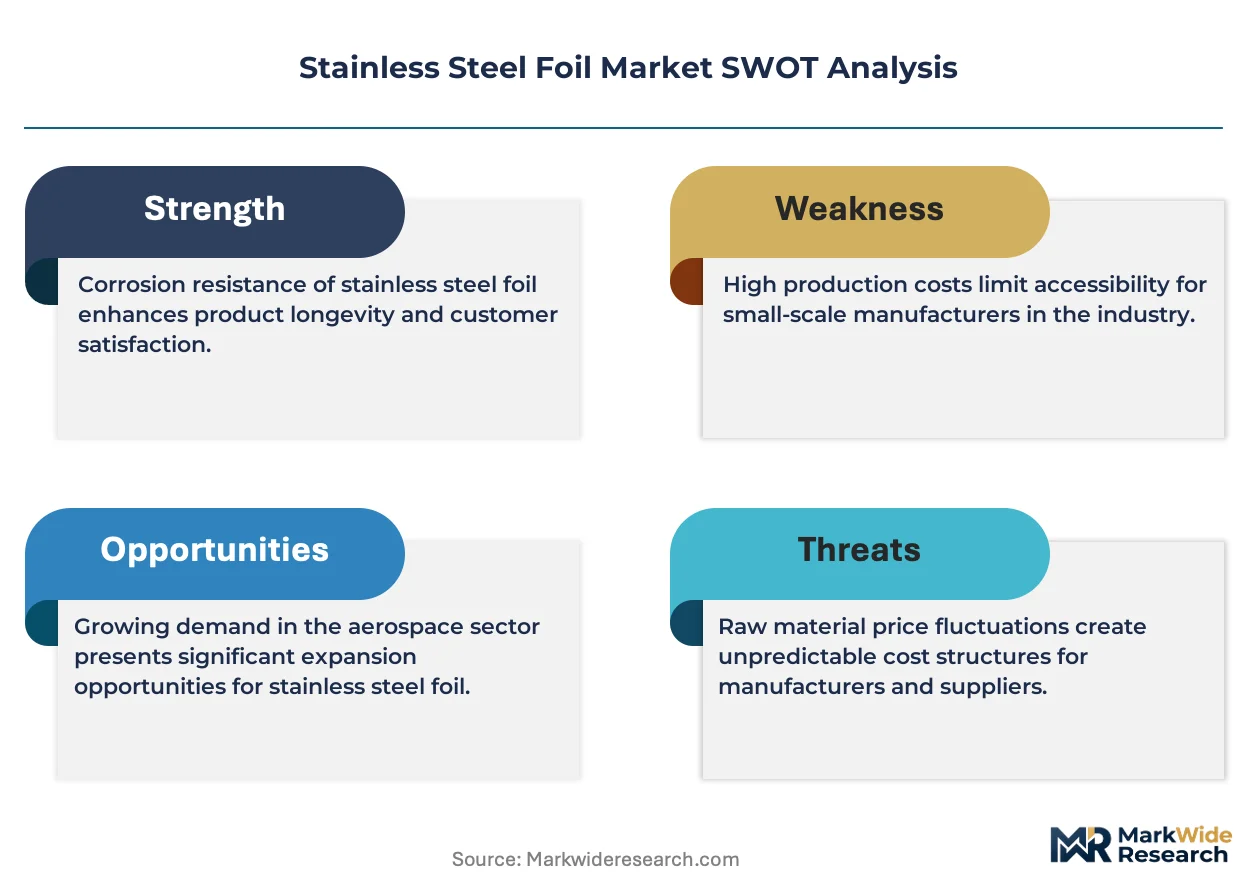
FDA, EPA, and REACH frameworks govern surface chemistry, hexavalent chromium limits, and end-of-life recyclability across major demand nodes. The EU F-Gas Regulation and evolving MEE standards in China further constrain process chemistries in cold-rolling and passivation lines. Stakeholders must monitor alloy surcharge volatility and dual-certification burdens as regional decarbonization timelines diverge.
Market Dynamics
Electronics OEMs are dismantling legacy distributor relationships and contracting directly with cold-rolling mills to secure gauge-controlled foil for semiconductor substrates and EV thermal management systems.
Growth Catalysts
- EV Thermal Architecture Expansion:Battery pack manufacturers are specifying 0.05-0.10 mm austenitic foil for cell-to-cell heat spreaders as thermal runaway protection mandates tighten across automotive safety frameworks.
- REACH Material Purity Mandates:ECHA enforcement of hexavalent chromium limits in surface passivation is filtering out commodity suppliers and consolidating volume among integrated producers with captive finishing lines.
- Flexible Circuit Substrate Demand:Smartphone and wearable manufacturers are qualifying ultra-thin 300-series foil for roll-to-roll etching processes in high-density interconnect boards.
Market Restraints
- Ferrochrome Price Volatility:Nickel and chromium alloy surcharges swing quarterly, compressing margin predictability for toll processors without captive mining or long-term offtake agreements.
- Finnish-German Supply Concentration:European ferrochrome and cold-rolling capacity clusters in the Baltic rim, exposing buyers to single-point disruption risks from energy cost spikes or logistics bottlenecks.
- Polymer Composite Substitution:Graphene-enhanced thermal interface materials and ceramic-coated aluminum are capturing share in cost-sensitive heat shield applications below 150°C operating thresholds.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme subsidies for semiconductor packaging and mobile phone assembly are creating first-mover advantages for foil suppliers establishing slitting and warehousing operations near Chennai and Noida.
- Hydrogen Electrolyzer Bipolar Plates:Proton exchange membrane stack manufacturers are prototyping 0.1 mm 316L foil as corrosion-resistant current collectors in next-generation green hydrogen production systems.
- Dual-Carbon Alignment in China:MEE carbon intensity benchmarks for cold-rolling operations are advantaging electric-arc furnace producers with renewable power purchase agreements over blast-furnace competitors.
Industry Challenges
- Precision Gauge Metrology Talent:Cold-rolling mills face acute shortages of technicians trained in eddy-current thickness profiling and surface roughness interferometry for sub-0.05 mm specifications.
- Dual-Certification Burden:Suppliers serving both EU and US channels must maintain parallel ASTM A240 and EN 10088 test protocols, extending qualification timelines and audit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Foil Market |
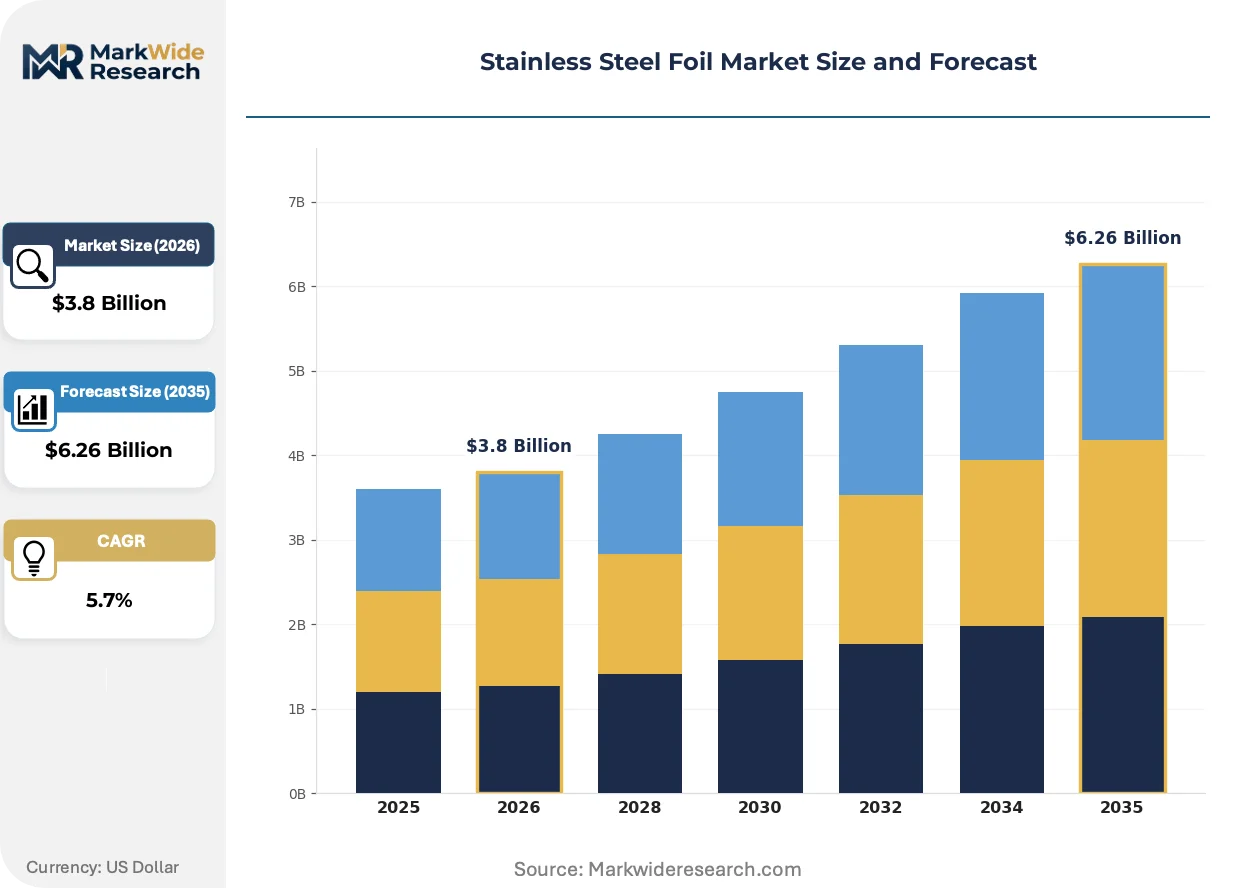
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rolls, Sheets, Strips, Custom Sizes End User: Aerospace, Electronics, Food Packaging, Medical Devices Application: Heat Shields, Insulation, Surface Protection, Decorative Components Thickness: Thin, Medium, Heavy, Extra Heavy |
| Companies Covered | Tata Steel, Ulbrich Stainless Steels and Special Metals Inc., ArcelorMittal, JFE Steel, KOBE STEEL, LTD., NIPPON STEEL CORPORATION, Acerinox, Wieland Rolled Products NA, Outokumpu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Foil Market Evolving Landscape
Active developments across metallurgy, surface engineering, and procurement architecture are compressing product lifecycles and redrawing competitive boundaries in precision foil supply.
Atomic-layer deposition (ALD) of ceramic barrier coatings onto stainless substrates is decomposing the traditional trade-off between corrosion resistance and electrical conductivity. Aerospace heat exchanger manufacturers are piloting ALD-alumina-coated 321 foil for turbine applications where chromium depletion cannot be tolerated. This deposition approach is decomposing incumbent passivation chemistries by eliminating hexavalent chromium entirely from the finishing sequence.
EU F-Gas Regulation phase-down schedules are forcing cold-rolling mills to retrofit annealing furnaces with hydrogen-based atmosphere systems or electric radiant heating. Finnish integrated producers have committed to hydrogen-fired continuous annealing lines by 2027 to maintain CE-marked access. Automotive stampers in Germany are now requiring supplier declarations of F-Gas-free processing for heat shield components bound for export markets.
Direct mill contracting is displacing tiered distributor networks as semiconductor fabricators consolidate vendor bases and demand lot-level traceability. Outokumpu and Nippon Steel have established dedicated technical service teams for wafer-processing equipment OEMs, bypassing regional steel service centers entirely. This channel compression is most visible in Taiwan and South Korea, where foundry capital expenditure cycles concentrate purchasing power among three dominant buyers.
Stainless Steel Foil Market Segmentation
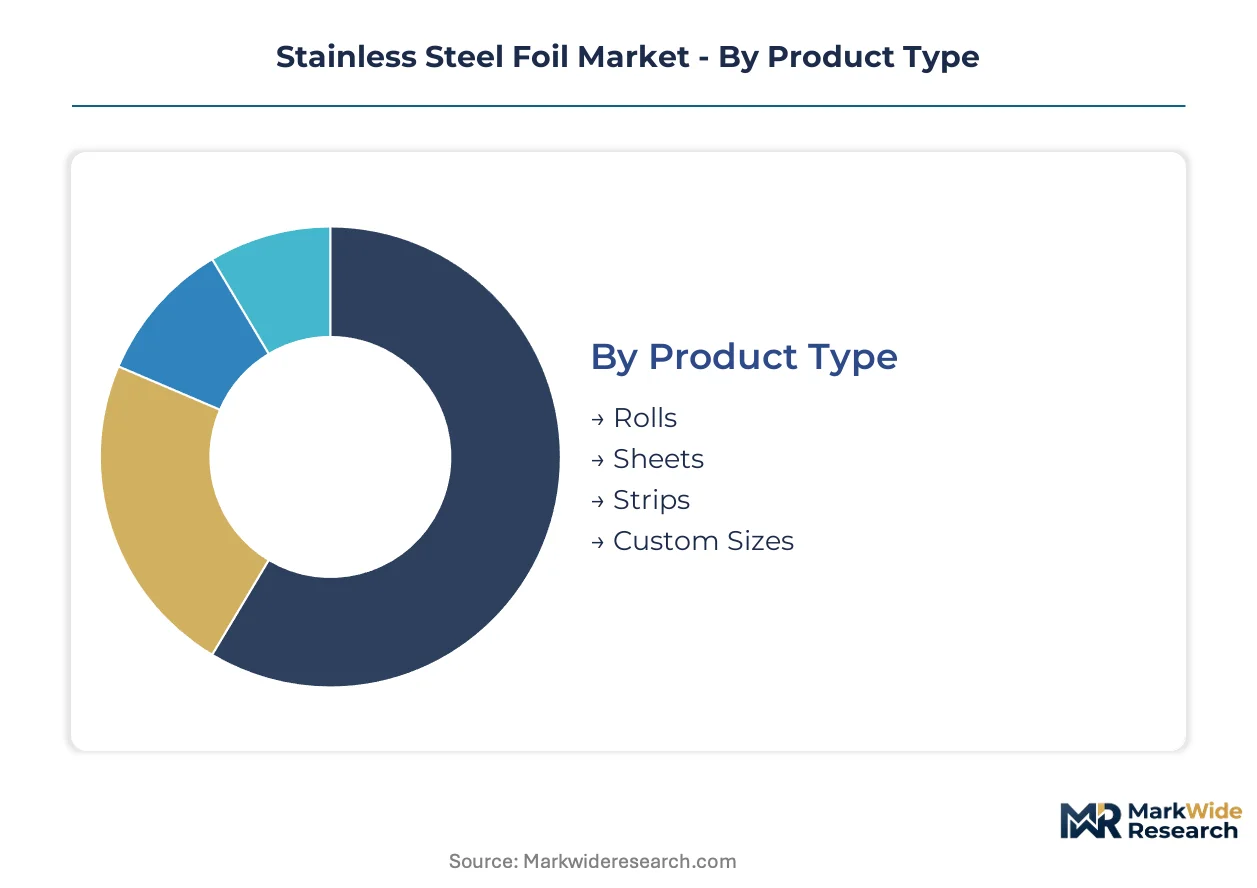
Segmentation in stainless steel foil reveals how channel architecture shapes margin capture. Precision requirements in semiconductor and aerospace verticals fragment supply chains by specification tier rather than geography alone.
Product Type:
Channel economics diverge sharply between commodity formats and engineered configurations, with distributor networks handling standard rolls while mill-direct relationships dominate custom specifications.
- Rolls:Continuous coiled supply in widths from 300mm to 1250mm serves high-volume stamping operations. Electronics contract manufacturers in Taiwan and South Korea consume precision-slit rolls for flexible circuit lamination, with lot-level traceability requirements now standard for semiconductor fabricator qualification.
- Custom Sizes:Die-cut blanks and precision-slit narrow coils command premium positioning due to setup complexity and dedicated tooling inventory. Automotive Tier-1 thermal management suppliers in Germany specify custom widths for cell-to-cell heat spreaders, locking in multi-year offtake agreements to amortize die costs.
- Sheets:Flat-cut panels serve job-shop metal fabricators with lower volume requirements and broader tolerance bands.
- Strips:Narrow-width coils target continuous processing lines in food packaging and medical device manufacturing.
Rolls dominate installed base. Custom sizes are where expansion concentrates.
End User:
Customer sophistication tiers separate specification-driven buyers from price-sensitive procurement, with certification burdens creating moats around medical and aerospace segments.
- Electronics:Smartphone, wearable, and semiconductor equipment OEMs drive demand for ultra-thin 300-series foil with surface roughness below 0.2 micrometers Ra. Roll-to-roll etching processes for high-density interconnect boards require gauge uniformity within ±2% across coil lengths, with Taiwan-based foundries consolidating vendor bases to three approved mills.
- Aerospace:Turbine heat exchanger and airframe manufacturers specify 321 and 347 grades for chromium depletion resistance at elevated temperatures. ALD ceramic barrier coatings are displacing traditional passivation for critical applications where hexavalent chromium elimination is mandatory.
- Food Packaging:Converters specify 304 and 316L for corrosion resistance in acidic food contact, with FDA compliance driving surface chemistry documentation.
- Medical Devices:Implantable and surgical instrument manufacturers require dual-certified material per ASTM F899 and ISO 5832, with electropolished finishes commanding substantial premiums.
Electronics commands volume leadership. Aerospace offers the steepest expansion trajectory.
Application:
Functional performance requirements stratify procurement by thermal, mechanical, and aesthetic demands, with heat management applications commanding the most stringent specifications.
- Heat Shields:Battery pack manufacturers specify 0.05-0.10 mm austenitic foil for cell-to-cell thermal runaway protection as UN ECE R100 and GB/T standards tighten. EV platform architectures are multiplying heat shield count per vehicle, with German automotive OEMs requiring F-Gas-free processing declarations.
- Insulation:Cryogenic and high-temperature barrier applications in chemical processing and LNG infrastructure favor stabilized grades with controlled thermal expansion.
- Surface Protection:Temporary and permanent corrosion barriers in industrial equipment and consumer appliances utilize lower-cost 400-series ferritic grades.
- Decorative Components:Appliance and architectural applications prioritize surface finish consistency over mechanical properties, with BA and 2B finishes standard.
Surface protection anchors volume. Heat shields are climbing the fastest.
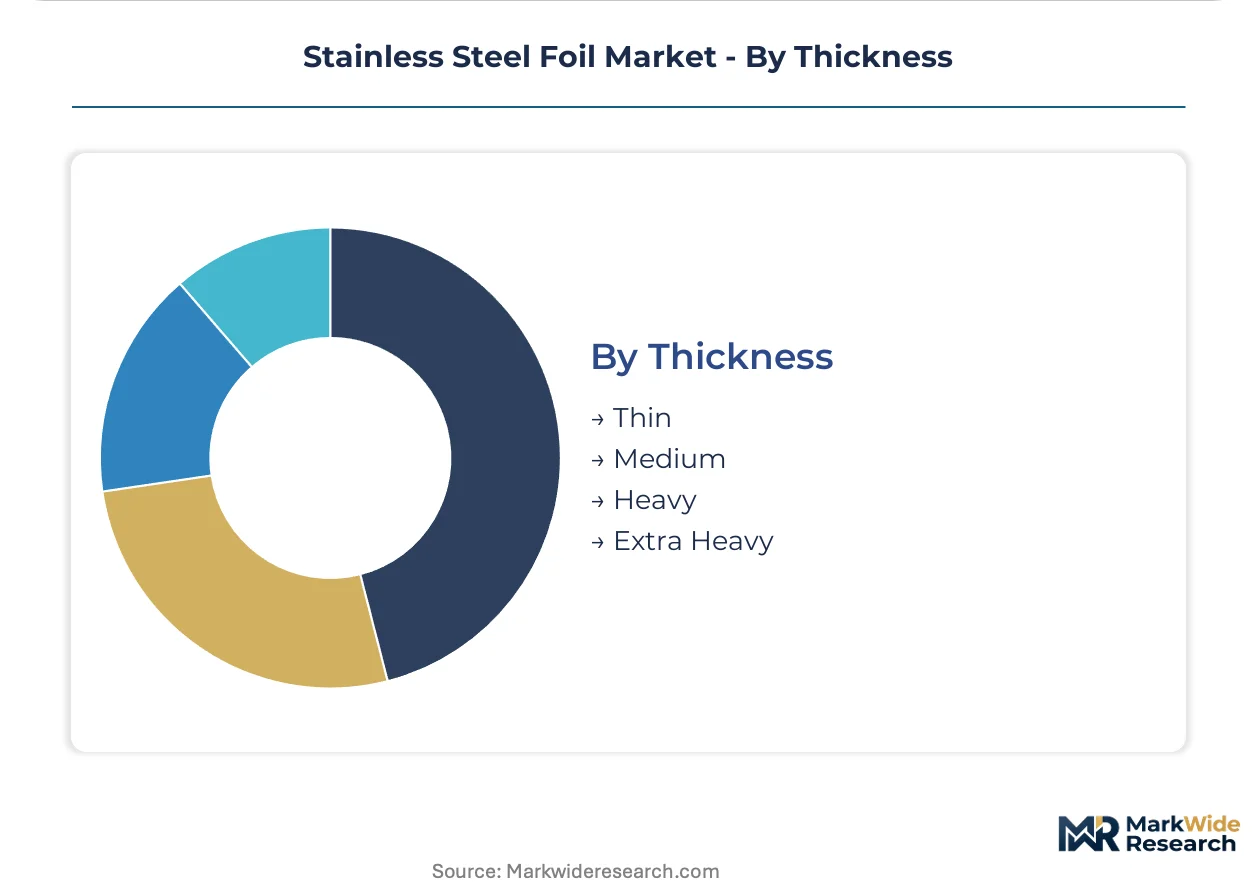
Thickness:
Gauge capability separates integrated producers with tandem cold-rolling lines from toll processors, with sub-0.05 mm specifications requiring specialized metrology and annealing control.
- Thin:Below 0.05 mm gauges serve semiconductor substrate and precision electromagnetic shielding applications. Finnish integrated producers with hydrogen-fired annealing lines have secured qualification for the most demanding wafer-processing equipment OEMs.
- Medium:0.05-0.20 mm range captures the majority of automotive thermal management and electronics flex circuit demand.
- Heavy:0.20-0.50 mm gauges target structural applications and industrial heat exchangers with less stringent flatness requirements.
- Extra Heavy:Above 0.50 mm transitions toward precision strip and light-gauge sheet applications, with distinct competitive dynamics.
Medium thickness holds installed base dominance. Thin gauges are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hamburg-Rotterdam rail corridor underwrites Northern Europe's ferrochrome and cold-rolling logistics, while the Yangtze River Delta's port cluster handles Asia's precision foil exports. These infrastructure assets anchor regional supply security for semiconductor and automotive thermal management buyers.
China
EV battery manufacturers in Ningbo and Shenzhen specify 0.05-0.10 mm austenitic foil for cell-to-cell heat spreaders as GB/T standards tighten. MEE carbon intensity benchmarks for cold-rolling operations advantage electric-arc furnace producers with renewable power purchase agreements over blast-furnace competitors. The Yangtze River Delta cluster around Shanghai concentrates slitting and warehousing capacity for electronics contract manufacturers.
Germany
Automotive Tier-1 stampers in Bavaria and Baden-Württemberg consume precision-slit coils for thermal runaway protection systems as UN ECE R100 mandates expand. The EU F-Gas Regulation forces cold-rolling mills to retrofit annealing furnaces with hydrogen-based atmosphere systems by 2027. The Ruhr industrial corridor anchors European ferrochrome processing through integrated operations with captive finishing lines.
United States
Semiconductor equipment OEMs in Oregon and Arizona qualify ultra-thin 300-series foil for wafer-processing chambers. FDA surface chemistry documentation requirements govern medical device applications, while EPA hexavalent chromium limits constrain passivation chemistries. The Pacific Northwest cluster near Portland houses precision gauge metrology facilities serving foundry capital expenditure cycles.
Japan
Flexible circuit substrate manufacturers in Osaka and Nagoya drive demand for roll-to-roll etching processes in high-density interconnect boards. METI industrial standards enforce thickness uniformity specifications within ±2% across coil lengths. The Kansai region's steel service centers maintain dedicated technical service teams for smartphone and wearable OEMs.
South Korea
Foundry operators in Gyeonggi Province consolidate vendor bases to three approved mills for lot-level traceability requirements. MFDS medical device regulations parallel FDA frameworks for implantable applications. The Seoul Capital Area concentrates electronics manufacturing subsidies that attract foil suppliers establishing regional slitting operations.
Stainless Steel Foil Market Competitive Landscape
Listed leaders compete with private specialists across gauge capability and certification breadth, creating a tiered structure where integrated producers with captive cold-rolling capacity command premium positioning. The vendor base separates into three strategic archetypes: Asian mill-direct suppliers with semiconductor channel access, European integrated producers with ferrochrome mining integration, and North American toll processors serving medical and aerospace certification tiers. Dominant competitive moves include hydrogen-fired annealing line investments for F-Gas compliance and dedicated technical service team deployments for foundry qualification programs.
Among integrated Asian producers, NIPPON STEEL CORPORATION and JFE Steel exemplify the mill-direct archetype serving semiconductor fabricators, while Outokumpu anchors the European tier with Finnish ferrochrome integration. These three occupy positions where captive upstream control and precision finishing capability converge.
| Leading Market Players |
|---|
| Tata Steel |
| Ulbrich Stainless Steels and Special Metals Inc. |
| ArcelorMittal |
| JFE Steel |
| KOBE STEEL, LTD. |
| NIPPON STEEL CORPORATION |
| Acerinox |
| Wieland Rolled Products NA |
| Outokumpu |
| Others |
Value Network & Pricing Analysis
Captive cold-rolling capacity at Finnish and Japanese integrated mills creates scale economies that compress unit costs below toll-processing competitors, concentrating supply-side pricing power among producers with in-house ferrochrome and hydrogen-fired annealing lines. This scale concentration elevates price floors for sub-0.05 mm precision gauges where metrology talent scarcity limits new entrant participation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment. Premium tiers capture semiconductor fabricators requiring ASTM A240 and EN 10088 dual certification with lot-level traceability, while economy tiers serve industrial surface protection with broader tolerance bands. Cost compression in the standard tier intensifies as polymer composite substitutes capture heat shield applications below 150°C. Automotive Tier-1 stampers exhibit lowest price sensitivity due to thermal runaway liability exposure, whereas food packaging converters prioritize unit economics over performance specifications.
Supply Chain Analysis
Strategic stockpiling of ferrochrome and nickel alloy surcharges dominates inventory strategy among European automotive stampers facing quarterly price volatility, while East Asian electronics contract manufacturers maintain just-in-time coil deliveries to minimize working capital. Supply concentrates in Finland, Germany, and China, drawing from chromium ore dependencies anchored in South African and Kazakh mining operations. Single-point vulnerability persists at the Hamburg-Rotterdam rail corridor where energy cost spikes disrupt Baltic rim ferrochrome logistics. Distribution runs through mill-direct technical service teams for semiconductor channels, with regional steel service centers handling commodity rolls.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stainless steel foil demand traces foundry capital expenditure cycles and EV platform rollout schedules, positioning the market for cyclical recovery as battery thermal management architectures multiply heat shield count per vehicle.
For Market Incumbents: Fortify qualification moats by accelerating hydrogen-fired annealing line deployments ahead of EU F-Gas Regulation deadlines, locking in CE-marked access for German automotive stampers. Deepen backward integration into captive ferrochrome processing to insulate margin structures from alloy surcharge volatility that compresses toll processors.
For New Entrants and Emerging Players: Technical service gaps in precision gauge metrology training present white-space openings for regional slitting and warehousing operations near Chennai and Noida, where PLI scheme subsidies concentrate electronics manufacturing. Target India's semiconductor packaging segment with dedicated qualification support teams, bypassing incumbent distributor networks through direct mill relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated producers with ALD ceramic coating capabilities and renewable-powered electric-arc furnace operations. Long-term viability hinges on dual-carbon alignment in China and F-Gas compliance in Europe, with acquisition screens prioritizing mills with hydrogen annealing commitments and foundry technical service infrastructure. Watch hydrogen electrolyzer bipolar plate prototyping as an inflection signal for 316L foil demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Fired Annealing Line Deployment | Secures CE-marked access under EU F-Gas Regulation phase-down schedules for German automotive channels. |
| Backward Integration into Ferrochrome Processing | Insulates margin structures from quarterly nickel and chromium alloy surcharge volatility. |
| Regional Slitting Operation Establishment | Captures PLI scheme subsidies in India's Chennai-Noida electronics manufacturing corridor. |
| ALD Ceramic Coating Capability Investment | Eliminates hexavalent chromium from finishing sequences for aerospace heat exchanger qualification. |
| Dual-Certification Quality System Implementation | Accelerates semiconductor fabricator approval timelines across ASTM A240 and EN 10088 protocols. |
Research Methodology
Initial hypotheses were tested against primary input from cold-rolling mill operations directors, semiconductor equipment OEM procurement leads, automotive Tier-1 thermal management engineers, and ferrochrome trading specialists, then refined against secondary validation from SEC steel producer filings, EU ECHA regulatory databases, Chinese MEE carbon intensity disclosures, and Japanese METI industrial standards. Bottom-up coil shipment data triangulated against top-down EV battery pack and flexible circuit substrate demand models.
Variance-decomposition across product type, end-user vertical, application function, and thickness gauge shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume build-ups incorporating alloy surcharge assumptions, foundry capex cycle phasing, and thermal runaway regulatory adoption curves. Forecast inputs included hydrogen electrolyzer bipolar plate prototyping timelines and F-Gas Regulation compliance retrofit schedules.
Forecasts assume regulatory continuity in EU REACH enforcement, Chinese MEE carbon benchmarks, and US EPA hexavalent chromium limits; material policy shifts would require re-modeling. Revision becomes warranted when ferrochrome price volatility exceeds historical bands or when polymer composite thermal interface materials capture share above 150°C operating thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Metal Finishing Market
Metals
Magnesium Metal Market
Metals
Global Duplex Stainless Steel Market
Metals
North America Metal Casting Market
Metals
Ruthenium Market
Metals
Japan Aluminium Powder Market
Metals
Steel Sheet for Home Appliances Market
Metals
High Purity Tungsten Market
Metals
Steel Salvage Drums Market
Metals
Europe Metal Service Centers Market
Metals
South America Metal Finishing Market
Metals
Rolled Steel Motor Market
Metals
Cobalt Market
Metals
Asia-Pacific Metal Finishing Market
Metals
Battery Metals Market
Metals
Aluminum Flat Products Market