
 Fluorocarbon Gases Market | 2026-2036
Fluorocarbon Gases Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorocarbon Gases Market Foresight
China is reconfiguring regional supply dynamics through capacity additions in fluorochemical manufacturing clusters. The Chemours Company leverages its vertical integration across fluoroproducts to sustain cost advantages in refrigerant and specialty gas production. Daikin Industries anchors its position through captive supply chains and proprietary fluoropolymer chemistry for HVAC applications. Solvay S.A. differentiates via high-purity fluorocarbon grades targeting semiconductor and pharmaceutical end users.
Fluorocarbon gases comprise carbon-fluorine bonded compounds including hydrofluorocarbons (HFCs), perfluorocarbons (PFCs), and hydrofluoroolefins (HFOs), characterized by thermal stability, chemical inertness, and tunable vapor pressure profiles that enable precise temperature control and plasma etching applications. These properties make them indispensable in refrigeration cycles, electronics fabrication, and fire suppression systems where non-flammability and dielectric performance are critical. Refrigerants command the largest product category by volume, though HFO-based formulations are capturing margin pools as regulatory phase-downs constrain legacy HFC production. Electronics Manufacturing represents the fastest-growing application segment, driven by wafer etching and chamber cleaning demand from semiconductor fabs scaling advanced node production.
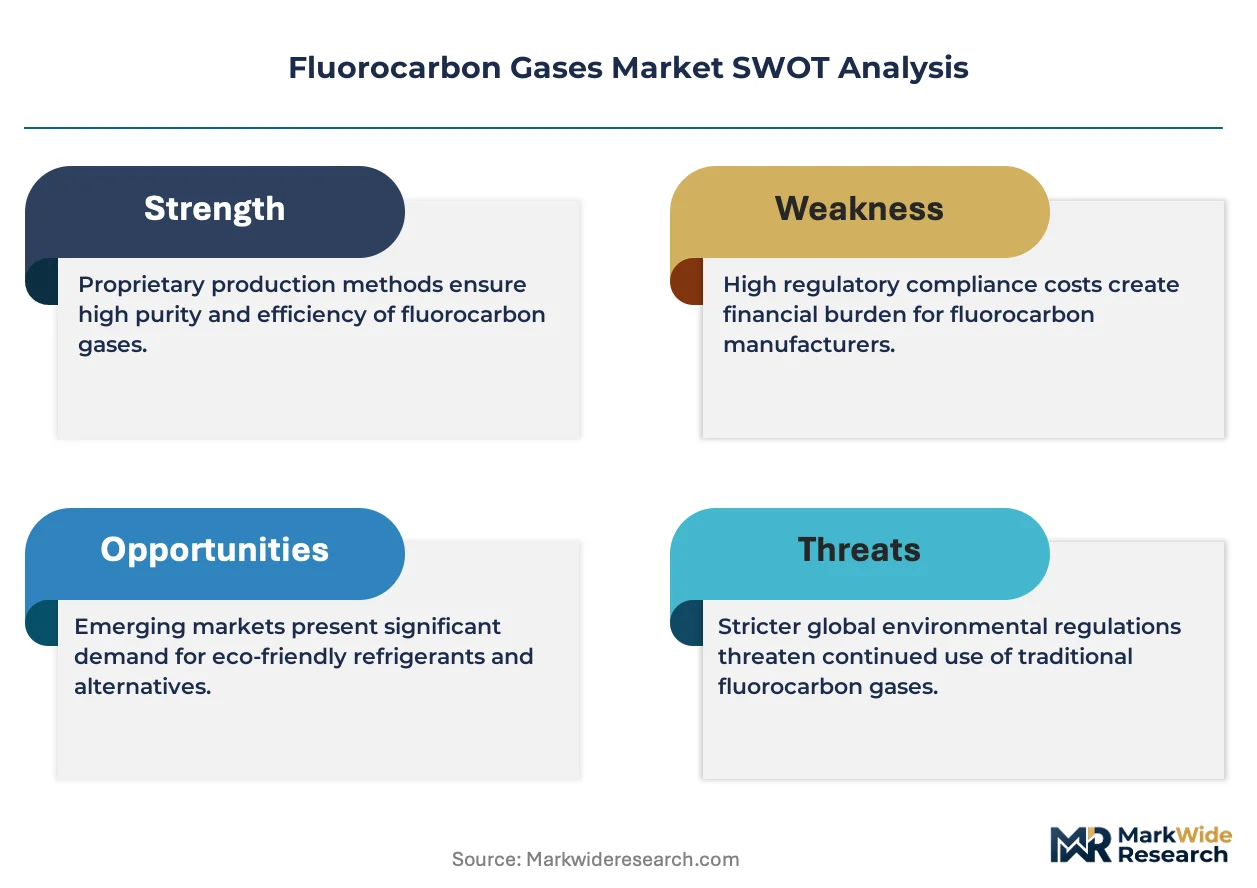
The EPA Significant New Alternatives Policy (SNAP) program and the Kigali Amendment framework constrain high-GWP fluorocarbon production, redirecting investment toward next-generation formulations with reduced atmospheric warming potential. ECHA REACH registration requirements and the EU F-Gas Regulation impose progressively tighter quotas on HFC imports, compelling reformulation across European HVAC and industrial refrigeration supply chains. Stakeholders must monitor regulatory thresholds for GWP limits in major demand centers while positioning manufacturing assets to serve the transition toward low-GWP fluorocarbon alternatives.
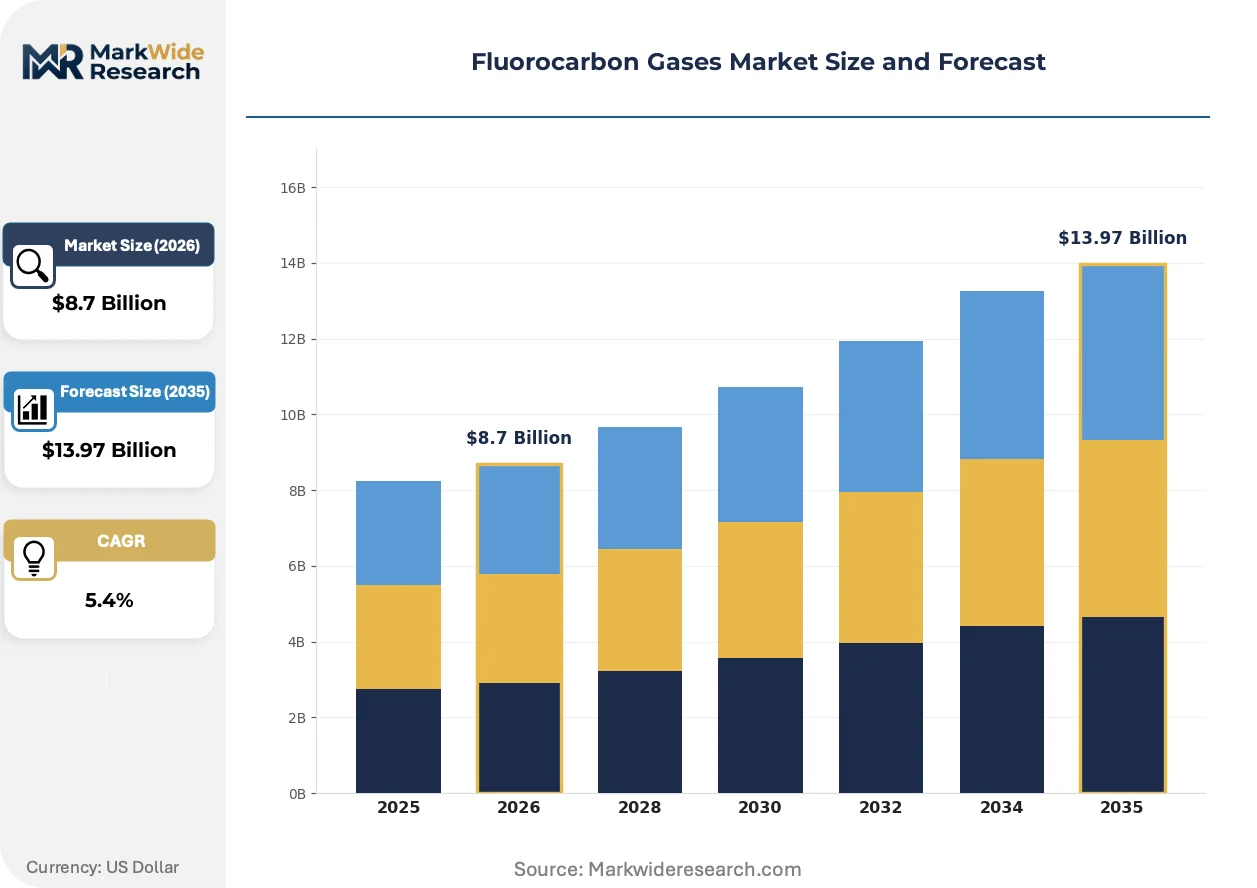
Market Dynamics
The Kigali Amendment's phase-down schedules are compressing manufacturing economics for high-GWP fluorocarbons while simultaneously unlocking premium pricing pools for next-generation formulations. This regulatory architecture now governs capacity investment decisions across major production clusters.
Growth Catalysts
- Semiconductor Etching Demand:Advanced node fabrication below 7nm requires fluorocarbon-based plasma chemistries for atomic-precision etching. Wafer fabs in Taiwan and South Korea are expanding chamber cleaning protocols.
- EU F-Gas Regulation:The quota system constrains legacy HFC supply, forcing HVAC OEMs to reformulate around HFO blends with substantially lower atmospheric warming potential.
- China's Electronics Manufacturing:Domestic semiconductor self-sufficiency targets are driving captive fluorocarbon consumption for wafer processing and equipment maintenance.
Market Restraints
- Fluorspar Supply Concentration:Acid-grade fluorspar mining concentrates in Mongolia and Mexico, exposing fluorochemical producers to concentrate price volatility and export licensing disruptions.
- High Capex for HFO Conversion:Retrofitting refrigerant plants to manufacture hydrofluoroolefins requires specialized catalyst systems and explosion-rated process equipment.
- Technical Performance Gaps:Low-GWP alternatives exhibit inferior thermodynamic efficiency in high-ambient-temperature climates, limiting adoption in Middle Eastern and Indian commercial refrigeration.
Strategic Opportunities
- Indian Cold Chain Expansion:Post-harvest food loss reduction mandates under India's National Cold Chain Grid are driving fluorocarbon demand for transport refrigeration units and controlled-atmosphere storage.
- Medical Aerosol Propellants:HFO-1234ze and HFO-1336mzz are displacing HFC-134a in metered-dose inhalers as pharmaceutical formulators address EMA sustainability disclosure requirements.
- Fire Suppression Convergence:Data center operators are integrating fluoroketone clean agents with AI-driven thermal monitoring systems for localized fire suppression without equipment damage.
Industry Challenges
- Fluorochemical Process Engineering Talent:Specialized expertise in anhydrous HF handling and fluorination reactor design remains concentrated at a handful of academic and industrial training centers.
- REACH Registration Timelines:ECHA's data requirements for novel HFO substances extend commercialization cycles by 18-24 months, compressing effective patent life.
- Legacy Equipment Compatibility:Existing refrigeration infrastructure using mineral oil lubricants requires complete system replacement to accommodate polar HFO refrigerant chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorocarbon Gases Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerants, Propellants, Solvents, Fire Suppressants, Dielectric Fluids Application: Air Conditioning, Fire Protection, Electronics Manufacturing, Pharmaceutical Processing, Metal Production End User Industry: HVAC Manufacturers, Electronics Producers, Chemical Plants, Pharmaceutical Firms, Metal Fabricators Distribution Channel: Direct Sales, Distributors, OEM Suppliers, Online Procurement, Industrial Wholesalers |
| Companies Covered | The Chemours Company, Daikin Industries, Ltd., 3M Company, Solvay S.A., Honeywell International Inc., Arkema S.A., Dongyue Group, AGC Inc., Gujarat Fluorochemicals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorocarbon Gases Market Shifts & Advancements
Formulation chemistry is pivoting toward molecular architectures that balance regulatory compliance with thermodynamic performance. Three distinct vectors are reshaping competitive positioning across the value chain.
Hydrofluoroolefin refrigerant technology is migrating from high-GWP hydrofluorocarbon formulations in commercial HVAC and automotive air conditioning systems. European and Japanese OEMs are accelerating HFO-1234yf adoption for passenger vehicle platforms ahead of 2027 GWP thresholds. The transition is compressing margins for legacy HFC producers while rewarding early movers with proprietary HFO catalyst patents.
The EPA SNAP program continues to delist high-GWP blowing agents and refrigerants for specific end-uses, most recently targeting supermarket refrigeration and foams. This regulatory pressure is forcing appliance manufacturers to redesign compressor architectures around A2L-classified mildly flammable alternatives. North American HVAC contractors are responding by upskilling technician certification for flammable refrigerant handling.
Semiconductor fabs are consolidating fluorocarbon procurement through long-term supply agreements rather than spot market purchases. Equipment utilization metrics now drive volume commitments with penalty clauses for off-spec material. This behavioral shift is most pronounced in Taiwan and South Korea, where foundry consolidation has concentrated buyer power among three dominant wafer manufacturers.
Fluorocarbon Gases Market Segmentation
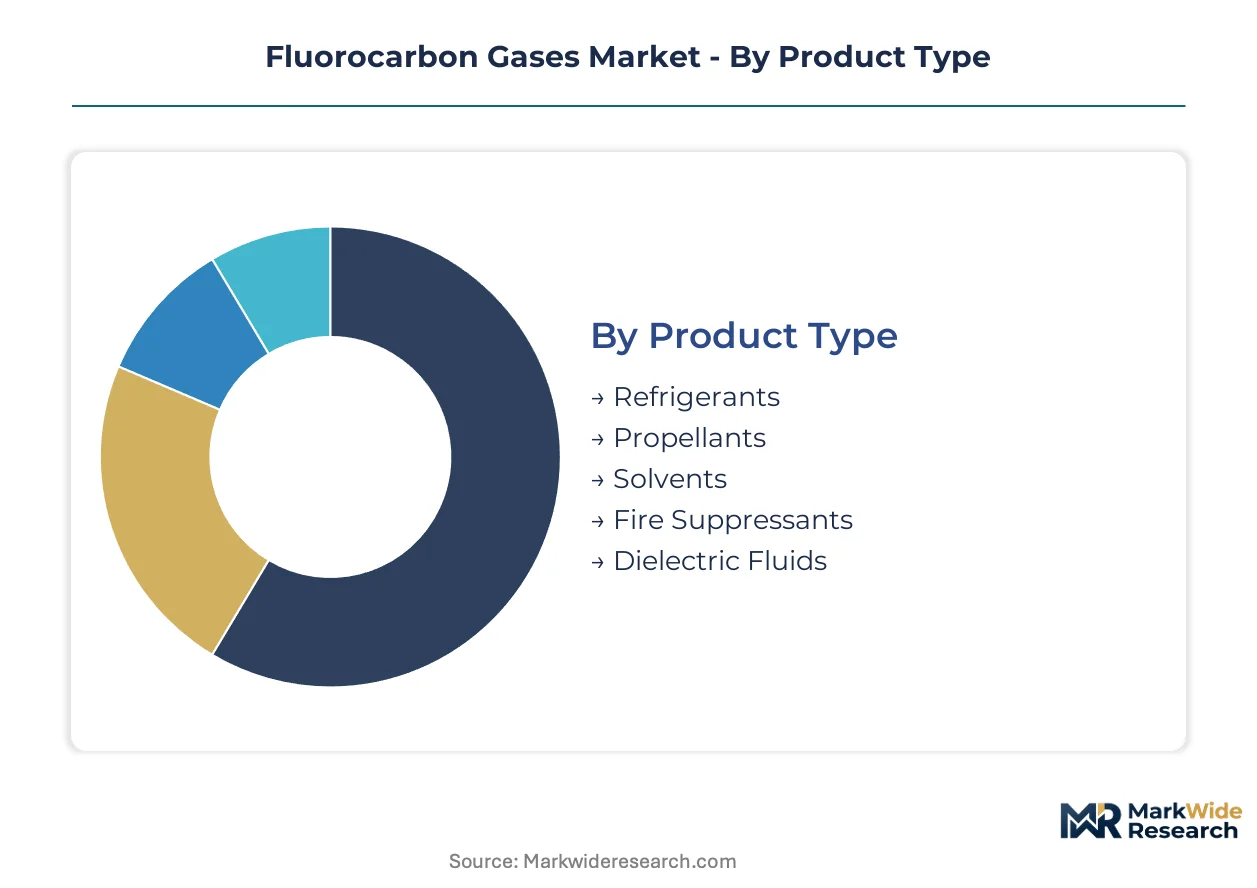
Fluorocarbon gas procurement patterns diverge sharply across product chemistries and end-use specifications. Segmentation reveals how regulatory pressure and application performance requirements partition demand into distinct commercial channels with specialized supply relationships.
Product Type:
Mature refrigerant formulations coexist with emerging low-GWP alternatives across this category, creating tiered technology adoption curves.
- Refrigerants:Hydrofluorocarbon and hydrofluoroolefin blends dominate tonnage, with HFO-1234yf and HFO-1234ze capturing premium positioning in automotive and commercial HVAC systems under EPA SNAP and EU F-Gas constraints. European OEMs and Japanese manufacturers are accelerating reformulation timelines ahead of regulatory deadlines.
- Propellants:Metered-dose inhaler applications drive pharmaceutical-grade specifications, where HFO-1234ze displaces legacy HFC-134a to meet EMA sustainability disclosure requirements. Medical device manufacturers in Germany and Switzerland are consolidating supplier qualifications around single-source HFO feedstock agreements.
- Solvents:Precision cleaning applications in semiconductor wafer processing utilize perfluorocarbon carriers with ultra-low particulate specifications.
- Fire Suppressants:Fluoroketone clean agents command data center protection contracts requiring zero equipment residue post-discharge.
- Dielectric Fluids:High-voltage transformer and switchgear applications exploit electrical insulation properties with thermal management performance.
Refrigerants retain volume leadership; propellants hold the steepest expansion curve.
Application:
Cost tier differentiation separates commodity-scale cooling from precision-process applications with stringent purity requirements.
- Air Conditioning:Residential and commercial HVAC systems consume bulk refrigerant volumes, with installation base retrofits and new equipment sales driving divergent formulation requirements. Indian and Southeast Asian construction booms are expanding addressable equipment stock.
- Electronics Manufacturing:Plasma etching and chamber cleaning in semiconductor fabs demand fluorocarbon process gases with sub-ppb metallic impurity limits. Taiwan and South Korean foundries are locking in multi-year supply agreements with penalty clauses for specification deviations.
- Fire Protection:Total flooding systems for critical infrastructure deploy fluorinated clean agents with rapid suppression kinetics.
- Pharmaceutical Processing:Cryogenic applications and reaction media utilize inert fluorocarbon carriers with validated batch consistency.
- Metal Production:Magnesium foundry protection and primary aluminum smelting employ sulfur hexafluoride alternatives with reduced atmospheric persistence.
Air Conditioning commands installed base scale; Electronics Manufacturing gains share fastest through process intensity.
End User Industry:
Customer type fragmentation creates divergent procurement behaviors between specification-driven manufacturers and price-sensitive commodity buyers.
- HVAC Manufacturers:Original equipment producers in China and Mexico are vertically integrating refrigerant blending operations to secure quota-constrained HFC access and proprietary HFO formulations. Daikin and Chemours have established captive supply arrangements with major OEMs.
- Electronics Producers:Semiconductor device manufacturers impose statistical process control requirements on fluorocarbon gas deliveries, with Taiwan Semiconductor Manufacturing and Samsung Foundry driving qualification protocols.
- Chemical Plants:Fluoropolymer and agrochemical synthesis operations consume feedstock-scale fluorocarbon intermediates.
- Pharmaceutical Firms:Inhaler and sterile packaging applications require GMP-validated supply chains with documented batch genealogy.
- Metal Fabricators:Non-ferrous casting and welding shield gas applications prioritize thermal stability and oxidation resistance.
HVAC Manufacturers anchor procurement volume; Electronics Producers exhibit the most aggressive supplier consolidation behavior.
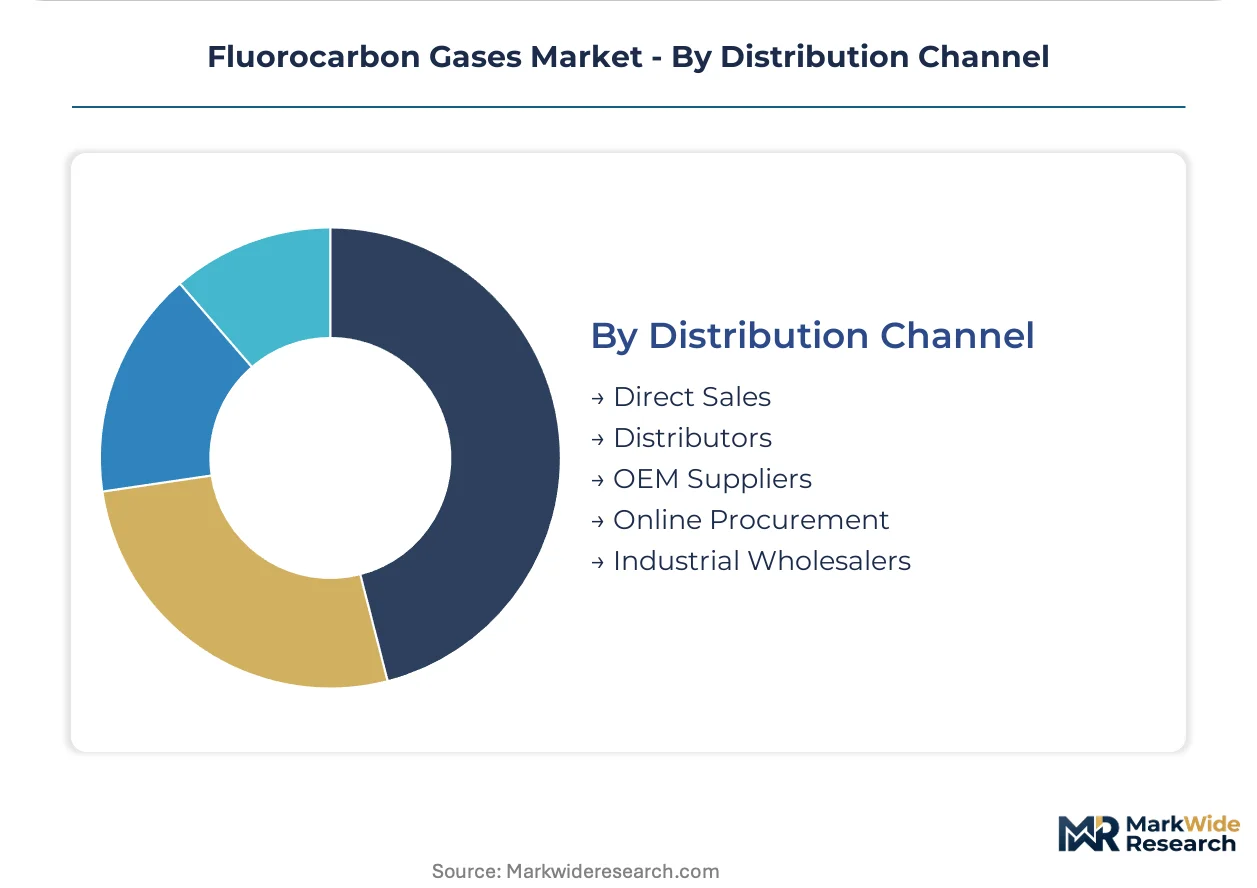
Distribution Channel:
Supply concentration patterns favor direct relationships for high-volume accounts while fragmented technical service needs sustain intermediary layers.
- Direct Sales:Tier-one refrigerant consumers and semiconductor fabs negotiate frame contracts with indexed pricing and dedicated logistics assets. Chemours and Solvay operate direct sales organizations for accounts exceeding contractual volume thresholds.
- Distributors:Regional refrigerant packagers and specialty gas blenders provide technical support and inventory pooling for mid-scale industrial accounts.
- OEM Suppliers:Captive supply arrangements integrate fluorocarbon delivery into equipment purchase agreements with lifecycle service bundling.
- Online Procurement:Standardized refrigerant cylinders and disposable containers migrate to digital platforms for transactional spot purchases.
- Industrial Wholesalers:Broad-line MRO distributors serve maintenance refrigerant needs with limited technical specification requirements.
Direct Sales captures value concentration; OEM Suppliers are climbing fastest through equipment-integrated contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acid-grade fluorspar mining concentrates in Mongolia and Mexico, creating feedstock dependencies that ripple through downstream fluorochemical production. Major manufacturing clusters have formed around captive HF supply and integrated refrigerant blending operations. Regulatory phase-down schedules in major demand centers are redirecting investment flows toward low-GWP formulation capacity.
China
Domestic semiconductor self-sufficiency targets under MIIT guidance are driving captive fluorocarbon consumption for wafer etching and chamber cleaning. The country's dual carbon goals constrain high-GWP HFC expansion while channeling investment into HFO manufacturing. Manufacturing clusters in Zhejiang and Shandong provinces host integrated fluorochemical complexes serving electronics and HVAC export markets.
United States
EPA SNAP program delistings are accelerating HFO-1234yf adoption in automotive air conditioning ahead of 2027 GWP thresholds. The IRA's clean manufacturing provisions indirectly support low-GWP refrigerant conversion through industrial decarbonization incentives. Gulf Coast petrochemical corridors maintain fluorocarbon blending capacity serving North American HVAC and electronics OEMs.
Germany
EU F-Gas Regulation quotas are compressing legacy HFC supply and forcing HVAC OEMs to reformulate around HFO blends. ECHA REACH registration timelines extend commercialization cycles for novel fluorocarbon substances. Industrial concentrations in North Rhine-Westphalia and Bavaria anchor refrigerant formulation and specialty gas purification for pharmaceutical and semiconductor end users.
Japan
METI energy efficiency standards and fluorocarbon emission reduction targets are driving HFO adoption in commercial refrigeration and residential heat pumps. Proprietary fluoropolymer chemistry from domestic producers supports captive HVAC supply chains. Manufacturing clusters in Osaka and Nagoya prefectures concentrate precision fluorocarbon gas production for semiconductor equipment maintenance.
South Korea
Samsung Foundry and SK Hynix are locking in multi-year fluorocarbon supply agreements with penalty clauses for metallic impurity deviations. MFDS pharmaceutical regulations are accelerating HFO-1234ze adoption in metered-dose inhaler formulations. The Gyeonggi-do semiconductor belt represents concentrated demand for sub-ppb purity fluorocarbon process gases in advanced node fabrication.
Fluorocarbon Gases Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and intermediate production. The vendor base organizes around three strategic archetypes: diversified chemical conglomerates with captive fluorspar access, specialized fluorochemical producers with proprietary catalyst technology, and regional refrigerant blenders serving installation and maintenance channels. Consolidation pressures favor backward integration into acid-grade fluorspar and anhydrous HF production. Technology licensing agreements and long-term offtake contracts represent dominant competitive moves for securing formulation IP and quota-constrained HFC access.
Within the diversified chemical conglomerate tier, The Chemours Company and Daikin Industries occupy positions reflecting vertical integration across fluoroproducts. Solvay S.A. exemplifies the specialty-grade vector targeting semiconductor and pharmaceutical purity requirements. Among Asia-Pacific-based producers, Dongyue Group and Gujarat Fluorochemicals Limited represent regional scale players with proximity to electronics manufacturing demand centers. Honeywell International Inc. and Arkema S.A. sit within the technology-licensing archetype, leveraging proprietary HFO catalyst patents to capture premium positioning in regulatory-driven transitions.
| Leading Market Players |
|---|
| The Chemours Company |
| Daikin Industries, Ltd. |
| 3M Company |
| Solvay S.A. |
| Honeywell International Inc. |
| Arkema S.A. |
| Dongyue Group |
| AGC Inc. |
| Gujarat Fluorochemicals Limited |
| Others |
Supply & Pricing Matrix
Single-source fluorspar dependency in Mongolia and Mexico determines both the premium spread for high-purity fluorocarbon grades and the geographic clustering of downstream blending operations. Buyers face asymmetric leverage where concentrate export licensing disruptions cascade immediately into refrigerant contract renegotiations and semiconductor fab supply security premiums.
Pricing Analysis
The Kigali Amendment dictates the pricing tier structure across fluorocarbon formulations, compressing margins on legacy HFC production while unlocking substantial premiums for HFO-1234yf and HFO-1234ze alternatives. Three-tier pricing structure across pharmaceutical-grade, semiconductor-grade, and industrial-grade specifications separates Chemours and Solvay's high-purity offerings from regional blenders serving maintenance channels. Cost compression in commodity refrigerant tiers is intensifying because China's domestic HFO capacity additions are eroding import dependency. HVAC OEMs in India and Southeast Asia exhibit the sharpest price sensitivity, while Taiwan and South Korean semiconductor fabs prioritize specification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for fluorochemical producers serving dual-market OEMs. Acid-grade fluorspar concentrates in Mongolia and Mexico, with anhydrous HF production clustering in Zhejiang, Shandong, and Gulf Coast petrochemical corridors. The supply chain draws from captive mining operations, specialized fluorination reactor assets, and batch-distillation purification stages. Single-source vulnerability in Mongolian concentrate exports threatens feedstock security for European and North American refrigerant blenders. Distribution runs through direct frame contracts for tier-one semiconductor and HVAC accounts, with regional packagers serving fragmented maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorocarbon procurement is consolidating around platform-economics logic where long-term supply agreements function as interoperability standards binding equipment OEMs to qualified chemical suppliers. Semiconductor fabs in Taiwan and South Korea are mandating penalty-clause contracts that embed fluorocarbon specifications directly into wafer processing equipment maintenance protocols.
For Market Incumbents: Harden backward integration into acid-grade fluorspar mining concessions in Mongolia and Mexico to secure feedstock autonomy against export licensing volatility. Expand HFO manufacturing capacity in Zhejiang and Shandong provinces to capture quota-constrained HFC substitution demand from domestic HVAC OEMs. Chemours and Daikin must defend their catalyst patent positions through aggressive licensing enforcement as Chinese producers scale proprietary fluorination technology. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian cold chain infrastructure where post-harvest loss reduction mandates are driving transport refrigeration unit demand without established supplier relationships. Target pharmaceutical-grade HFO-1234ze propellant qualifications for European metered-dose inhaler manufacturers facing EMA sustainability disclosure deadlines. A technical service bundling approach—combining refrigerant supply with technician certification and equipment retrofit consulting—penetrates mid-scale industrial accounts underserved by direct sales organizations. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors specialty-grade producers with validated semiconductor supply relationships over commodity refrigerant blenders facing margin compression. Long-term viability hinges on positioning for HFO formulation IP rather than legacy HFC quota trading. Acquisition targets should exhibit captive fluorspar access or proprietary fluoropolymer chemistry. The signal to watch is EPA SNAP delisting acceleration for additional HFC end-uses, which would compress the effective window for stranded asset risk in high-GWP production capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Mining | Mongolian and Mexican concentrate concessions secure feedstock autonomy against export licensing disruptions. |
| HFO Manufacturing Scale-Up | Proprietary catalyst capacity in Zhejiang captures premium positioning under Kigali Amendment phase-down schedules. |
| Long-term Supply Agreement with Semiconductor Fabs | Penalty-clause contracts with TSMC and Samsung Foundry lock in sub-ppb purity qualification requirements. |
| Pharmaceutical-Grade Propellant Certification | EMA-validated HFO-1234ze supply chains capture inhaler reformulation mandates ahead of sustainability disclosures. |
| Technician Certification Program Expansion | A2L refrigerant handling credentials enable North American HVAC contractor channel control for mildly flammable alternatives. |
Research Methodology
Initial hypotheses were tested against primary input from fluorochemical plant managers, semiconductor fab procurement directors, HVAC OEM supply chain leads, and specialty gas distribution channel partners and refined through secondary validation against customs trade data, SEC 10-K filings, EPA SNAP regulatory dockets, and ECHA REACH registration databases. Bottom-up capacity and demand modeling was cross-checked against top-down macroeconomic drivers to ensure convergence across estimation approaches.
Demand-supply balance dynamics across the projection horizon were modeled through segmented analysis of refrigerant grade tiers, end-use industry concentrations, regional production hub configurations, and purity specification requirements. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for regulatory phase-down schedules and technology substitution elasticities. Semiconductor wafer etching intensity metrics and HVAC equipment stock replacement cycles served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in construction activity indices, electronics capital expenditure cycles, or fluorspar concentrate pricing volatility would shift the trajectory of refrigerant and specialty gas demand forecasts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Helium Gas Market
Industrial Gases
High Purity Methane Gas Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Global Industrial Gas Market
Industrial Gases
Neon Gas for Laser Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Syngas Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Industrial Gas Regulator Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
Global Rare Gases Market
Industrial Gases
US Industrial Gas Regulator Market