
 Global Low GWP Refrigerants Market | 2026-2036
Global Low GWP Refrigerants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low GWP Refrigerants Market Foresight
The capital-intensity divergence between integrated fluorochemical producers and specialty gas distributors is redrawing competitive boundaries in low GWP refrigerant supply. Honeywell International Inc. leverages its integrated fluorine chemistry platform to sustain captive production of HFO-1234yf precursors. The Chemours Company anchors its position through controlled access to Opteon production assets in Texas and Louisiana. Daikin Industries Ltd. differentiates via in-house compressor-refrigerant system optimization at its Osaka technology center.
Low GWP refrigerants encompass synthetic hydrofluoroolefins, naturally occurring hydrocarbons such as propane and isobutane, and inorganic compounds including ammonia and carbon dioxide, all formulated to deliver thermodynamic performance with global warming potential ratings substantially below legacy hydrofluorocarbon alternatives. Hydrofluoroolefins currently command the largest value share among product types due to their drop-in compatibility with existing vapor compression infrastructure, while natural refrigerants represent the fastest-expanding category as ammonia and CO2 systems penetrate industrial chilling applications. Among end users, cold storage facilities and food processing units concentrate demand for ultra-low temperature cascade systems using CO2 and ammonia blends.
The EU F-Gas Regulation and REACH framework mandate phasedown schedules that directly constrain high-GWP refrigerant supply, while the US EPA SNAP program governs acceptable alternatives under the Clean Air Act. Japan's METI enforces GWP thresholds through revised Fluorocarbon Emissions Control Law compliance requirements. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate formulation registration timelines and equipment certification obligations.
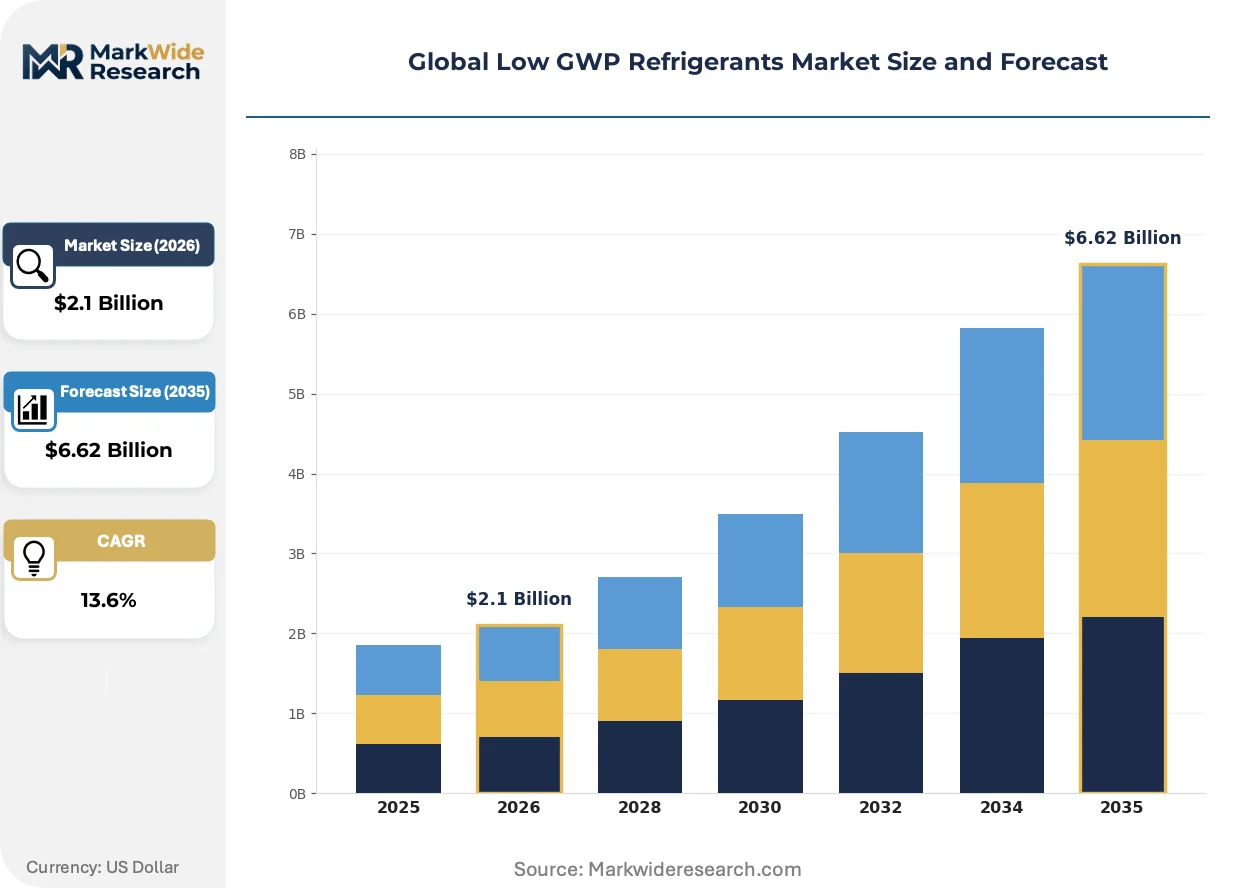
Market Dynamics
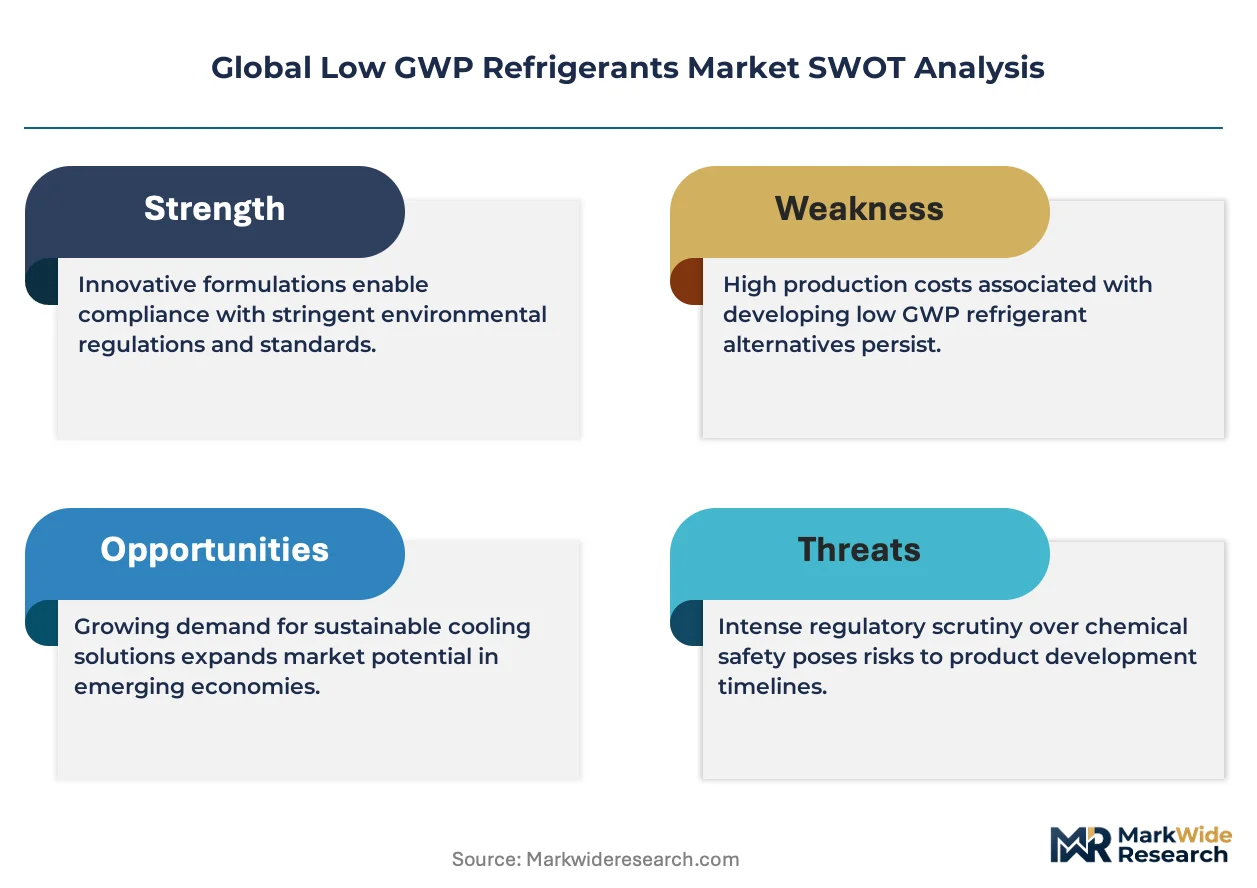
Regulatory phase-down mandates across multiple jurisdictions are forcing simultaneous reformulation of installed equipment bases and manufacturing supply chains, compressing transition timelines for refrigerant producers and equipment OEMs alike.
Growth Catalysts
- EU F-Gas Regulation:Binding GWP reduction quotas for hydrofluorocarbon imports are accelerating retrofit cycles in commercial refrigeration across Germany, France, and Italy.
- Cold chain infrastructure:Expansion of frozen food logistics networks in the United States and Japan is pulling demand for ultra-low temperature CO2 cascade systems.
- HFO-1234yf:Automotive air-conditioning systems in passenger vehicle manufacturing are standardizing on this hydrofluoroolefin for original equipment and service fill.
Market Restraints
- Fluorinated feedstock concentration:Chinese production of chlorodifluoromethane and tetrafluoroethylene precursors creates supply vulnerability for Western HFO manufacturers.
- Equipment incompatibility:Natural refrigerant systems using ammonia require stainless steel piping and specialized compressor oils that retrofit markets cannot economically absorb.
- REACH registration timelines:European Chemicals Agency data requirements for novel HFO blends extend commercialization windows by 18-24 months versus legacy products.
Strategic Opportunities
- India cold storage buildout:National Cold Chain Mission subsidies for warehouse construction are opening demand for ammonia-CO2 hybrid systems in agricultural processing zones.
- Heat pump deployment:Residential heating electrification in Nordic countries is creating cross-seasonal demand for low-GWP working fluids in reversible vapor compression units.
- Refrigerant reclaim infrastructure:Mandatory recovery and purification mandates under Japan's Fluorocarbon Emissions Control Law are enabling service-based revenue models for certified reclaim operators.
Industry Challenges
- Flammability certification protocols:ASHRAE and ISO safety standards for A2L mildly flammable HFOs require specialized technician training that contractor networks lack.
- Legacy system stranded asset risk:R-404A and R-410A equipment with 15-20 year residual life cannot economically accommodate refrigerant phase-down schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low GWP Refrigerants Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.62 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrofluoroolefins, Natural Refrigerants, Hydrocarbons, Inorganic Compounds Technology: Absorption Cooling, Vapor Compression, Magnetic Refrigeration, Thermoelectric Cooling Application: Commercial Cooling, Domestic Refrigeration, Industrial Chilling, Transportation Cooling End User: Cold Storage Facilities, Food Processing Units, Chemical Plants, Pharmaceutical Manufacturing |
| Companies Covered | Honeywell International Inc., The Chemours Company, Daikin Industries Ltd., Arkema S.A., Linde plc, Orbia, Sinochem Holdings, A-Gas, Air Liquide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low GWP Refrigerants Market Shifts & Advancements
Formulation science and equipment engineering are converging to solve thermodynamic performance gaps that previously limited low-GWP alternatives to niche applications.
Hydrofluoroolefin-based blends with GWP values under 150 are fragmenting the commercial refrigeration retrofit market. Supermarket operators in California and New York are deploying these formulations in existing direct-expansion cases without compressor replacement. This drop-in compatibility is fragmenting demand between full system replacement and refrigerant-only conversion strategies.
Japan's METI has tightened enforcement thresholds under the revised Fluorocarbon Emissions Control Law. Leak detection and repair intervals now mandate quarterly inspection for systems above 300 kg charge. Commercial facility managers are responding by consolidating distributed refrigeration into centralized ammonia-CO2 cascade plants with lower total refrigerant inventory.
Buyer consolidation among multinational food retailers is compressing supplier qualification timelines. Procurement teams at Tesco, Carrefour, and Ahold Delhaize are unbundling refrigerant supply from equipment maintenance contracts, forcing chemical suppliers to certify directly against retailer sustainability scorecards rather than through OEM intermediaries.
Global Low GWP Refrigerants Market Segmentation
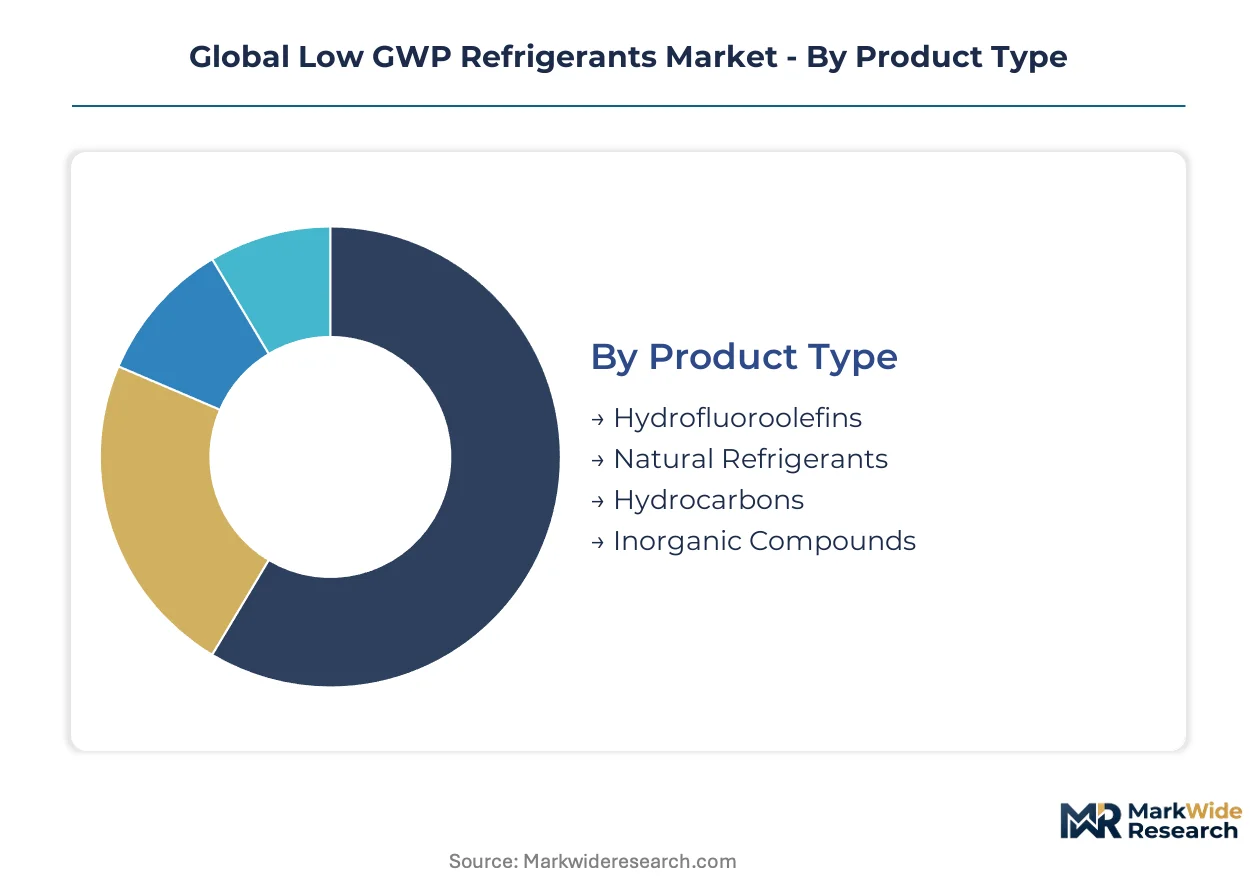
Segmentation in low GWP refrigerants reveals divergent supply chain configurations across product chemistries and cooling technologies. Equipment OEMs and chemical suppliers calibrate portfolio investments differently depending on whether segments serve retrofit markets or new installation demand.
Product Type:
Hydrofluoroolefins dominate export-led supply chains anchored in integrated fluorochemical production, while natural refrigerants and hydrocarbons cluster around regional biomass and petrochemical feedstock availability.
- Hydrofluoroolefins:Synthetic unsaturated fluorocarbon compounds engineered for drop-in compatibility with existing vapor compression hardware. Demand concentrates in automotive air-conditioning manufacturing across the United States and Japan, where HFO-1234yf has displaced legacy R-134a under EPA SNAP and METI enforcement timelines.
- Natural Refrigerants:Naturally occurring substances including ammonia and carbon dioxide with negligible direct global warming potential. Cold storage construction in Germany and France is pulling industrial-scale CO2 cascade systems as the EU F-Gas Regulation tightens import quotas on fluorinated alternatives.
- Hydrocarbons:Propane and isobutane formulations derived from petroleum refining byproduct streams. Domestic appliance manufacturing in Turkey and Thailand specifies these for household refrigerator production serving Middle Eastern and Southeast Asian markets.
- Inorganic Compounds:Ammonia and water-based absorption systems deployed where waste heat recovery is technically feasible. Chemical process industries in the Netherlands and Belgium integrate these into combined heat and power configurations.
Hydrofluoroolefins hold the largest share; momentum sits with natural refrigerants.
Technology:
Technology segments split between mature vapor compression dominating volume and emerging alternatives capturing niche premium applications.
- Vapor Compression:The dominant thermodynamic cycle using mechanical work to transfer heat between refrigerant phase changes. Commercial retrofit activity in California supermarkets and New York retail chains specifies low-GWP HFO blends for existing direct-expansion infrastructure.
- Absorption Cooling:Heat-activated refrigeration using lithium bromide or ammonia-water working fluid pairs. Industrial facilities in Saudi Arabia and the UAE deploy these where waste heat from power generation or petrochemical processing is available.
- Magnetic Refrigeration:Solid-state cooling exploiting magnetocaloric effects in gadolinium-based alloys. Research installations at Osaka University and Cambridge University test scalability for medical cold chain applications.
- Thermoelectric Cooling:Peltier-effect heat pumping using semiconductor junctions for precise temperature control. Semiconductor fabrication cleanrooms in South Korea and Taiwan specify these for localized thermal management.
Vapor compression commands installed base dominance; magnetic refrigeration is climbing the fastest despite early-stage commercialization.
Application:
Application segments track divergent regulatory pressure timelines and equipment replacement cycles across cooling end-uses.
- Commercial Cooling:Supermarket refrigeration, convenience store cases, and food service equipment. Tesco and Carrefour procurement teams in the United Kingdom and France now unbundle refrigerant supply from maintenance contracts, forcing direct chemical supplier certification.
- Industrial Chilling:Process cooling for manufacturing, cold storage warehouses, and distribution centers. India's National Cold Chain Mission subsidies are accelerating ammonia-CO2 hybrid system deployment in agricultural processing zones around Mumbai and Delhi.
- Domestic Refrigeration:Household refrigerators and freezers. Turkish manufacturers export hydrocarbon-charged units throughout the Middle East and North Africa.
- Transportation Cooling:Refrigerated trucks, shipping containers, and rail cars. Japanese logistics operators consolidate distributed systems into centralized plants to comply with METI quarterly leak inspection mandates.
Commercial cooling holds the largest share; industrial chilling is gaining share fastest on cold chain infrastructure buildout.
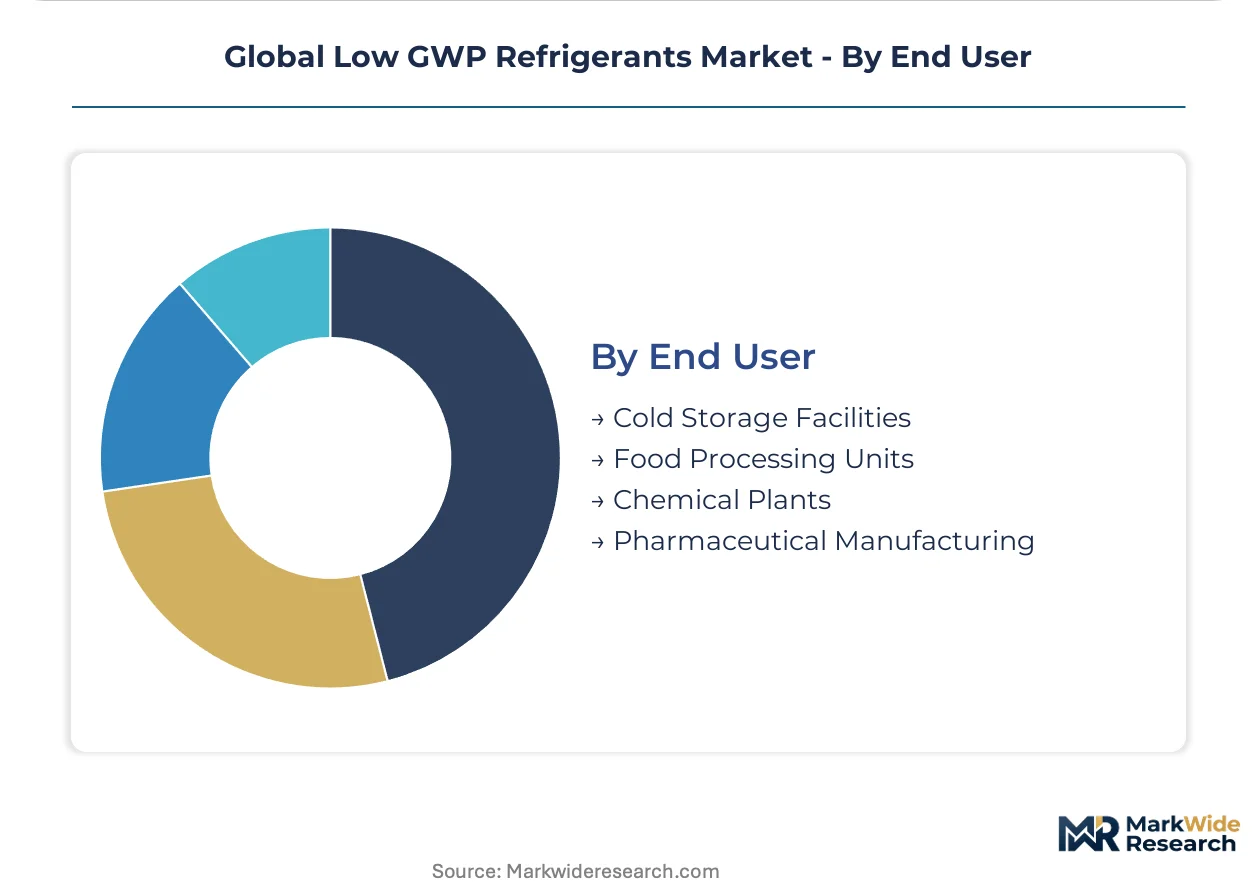
End User:
End user concentration varies by temperature requirement and regulatory scrutiny intensity.
- Cold Storage Facilities:Frozen and chilled warehousing for food and pharmaceutical distribution. Operators in Germany and the Netherlands are consolidating distributed systems into centralized ammonia-CO2 cascade plants to reduce total refrigerant inventory under ECHA reporting requirements.
- Food Processing Units:Slaughterhouses, dairies, and prepared food manufacturing. Facilities in Japan face METI-mandated quarterly leak detection intervals for systems above 300 kg charge, accelerating equipment replacement decisions.
- Chemical Plants:Process cooling for petrochemical and specialty chemical production. Sites on the US Gulf Coast balance HFO adoption against chlorodifluoromethane precursor supply vulnerabilities from Chinese production.
- Pharmaceutical Manufacturing:Temperature-controlled production and storage for vaccines and biologics. Cold chain integrity requirements in this segment command premium pricing for ultra-low temperature systems.
Cold storage facilities hold the largest share; food processing units show steepest expansion trajectory on regulatory compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France absorb price premiums for regulatory compliance, while operators in India and Thailand select refrigerants primarily on upfront capital cost. Japan sits between these poles, trading off efficiency gains against total lifecycle investment. This elasticity gradient shapes supplier pricing power and product mix across markets.
United States
California's supermarket retrofit mandates and New York's building decarbonization targets pull HFO-1234yf and R-454B formulations into commercial cooling. EPA SNAP program approvals govern acceptable alternatives under Clean Air Act authority. Cold storage construction in the Central Valley and dairy processing clusters around Wisconsin accelerate ammonia-CO2 hybrid deployment.
Germany
Cold chain operators face binding GWP reduction quotas under EU F-Gas Regulation import limits. ECHA registration requirements extend commercialization timelines for novel HFO blends by 18-24 months versus legacy products. Industrial refrigeration in the Ruhr region and Lower Saxony food processing zones consolidate distributed systems into centralized cascade plants.
Japan
Automotive OEMs standardize HFO-1234yf for passenger vehicle air-conditioning under METI enforcement timelines. Revised Fluorocarbon Emissions Control Law mandates quarterly leak inspection for systems above 300 kg charge. Logistics operators in the Kanto region consolidate distributed refrigeration into centralized plants to reduce compliance burden.
India
National Cold Chain Mission subsidies for warehouse construction open demand for ammonia-CO2 hybrid systems in agricultural processing. Bureau of Indian Standards certification requirements govern refrigerant purity and equipment safety specifications. Cold storage buildout concentrates around Mumbai, Delhi, and Bangalore distribution corridors.
France
Supermarket procurement teams at Carrefour unbundle refrigerant supply from maintenance contracts, forcing direct chemical supplier certification. EU F-Gas Regulation phasedown schedules constrain R-404A and R-410A availability for existing equipment. Frozen food logistics networks in the Île-de-France and Lyon regions specify ultra-low temperature CO2 systems.
Global Low GWP Refrigerants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated fluorochemical producers commanding formulation science and regional gas distributors controlling last-mile service revenue. The market structures around three tiers: multinational chemical conglomerates with captive precursor supply, mid-scale refrigerant blenders serving retrofit demand, and specialty gas distributors with reclaim infrastructure. Dominant competitive moves include backward integration into chlorodifluoromethane feedstocks and geographic expansion through distributor acquisitions.
Within the integrated chemical tier, Honeywell International Inc. and The Chemours Company occupy positions anchored by fluorine chemistry platforms and controlled production asset access. Daikin Industries Ltd. exemplifies the equipment-chemical convergence archetype through in-house compressor-refrigerant system optimization. These three represent distinct strategic postures: captive precursor supply, controlled asset access, and vertical system integration.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| The Chemours Company |
| Daikin Industries Ltd. |
| Arkema S.A. |
| Linde plc |
| Orbia |
| Sinochem Holdings |
| A-Gas |
| Air Liquide |
| Others |
Supply & Pricing Matrix
HFO-1234yf displacing legacy R-134a in automotive air-conditioning simultaneously shifts production geography toward integrated fluorochemical complexes in the United States and Japan while compressing margin structures for blenders lacking captive precursor supply. This substitution dynamic redistributes pricing power upstream to chlorodifluoromethane and tetrafluoroethylene producers, forcing downstream refrigerant distributors to compete on reclaim infrastructure rather than formulation premiums.
Pricing Analysis
Reclaim service contracts and extended purity warranties drive lifetime value for commercial cooling operators facing EU F-Gas Regulation phasedown timelines. Three-tier pricing structure across premium certified-reclaim, standard virgin-blend, and economy spot-purchase tiers separates buyers by compliance urgency and inventory scale. Cost compression in the standard tier intensifies because Chinese precursor exports create feedstock price volatility. Cold storage facility operators in Germany and France show least price sensitivity due to binding GWP quotas, while Indian warehouse developers under National Cold Chain Mission subsidies prioritize upfront capital minimization.
Supply Chain Analysis
Strategic stockpiling of HFO precursors dominates inventory strategy among Western integrated producers confronting Chinese chlorodifluoromethane supply vulnerability. Manufacturing concentration centers on the United States, Japan, and China, with formulation blending distributed to regional gas distributors in Germany, France, and India. Tetrafluoroethylene, chlorodifluoromethane, and hydrofluoric acid constitute critical input dependencies. Single-source vulnerability from Chinese precursor production creates structural risk for European and North American HFO manufacturers. Distribution runs through specialty gas distributors with cylinder-fleet infrastructure and certified reclaim capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EU F-Gas Regulation phasedown schedules and EPA SNAP approval timelines create switching costs that protect incumbent positions against commodity substitution.
For Market Incumbents: Secure backward integration into chlorodifluoromethane feedstocks or long-term offtake agreements with Chinese precursor suppliers to defend against supply disruption. Expand reclaim infrastructure in Germany and Japan where mandatory recovery laws concentrate service revenue. Capacity addition in Texas and Louisiana production corridors reinforces asset control against emerging blenders. For New Entrants and Emerging Players: Differentiate on ammonia-CO2 hybrid system integration for India's National Cold Chain Mission agricultural zones, where technical service capabilities matter more than formulation patents. Target cold storage construction around Mumbai and Delhi as the most penetrable geography given subsidy-driven demand acceleration. Pursue direct certification against Tesco and Carrefour sustainability scorecards as the primary go-to-market angle, bypassing OEM intermediaries. For Investors and Strategic Acquirers: The market sits at a regulatory-enforcement acceleration phase that favors integrated chemical conglomerates with captive fluorine chemistry platforms over standalone blenders. Long-term viability across the analysis window rests on REACH registration completion and EPA SNAP approval portfolios. Acquisition target archetype: regional gas distributors with certified reclaim infrastructure in Japan or Germany. The signal to watch is METI enforcement tightening or ECHA registration timeline extensions that strand novel HFO commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Honeywell's captive HFO-1234yf precursor production insulates margin structures from Chinese feedstock volatility. |
| Reclaim Infrastructure Expansion | Japan's Fluorocarbon Emissions Control Law mandates enable service-based revenue models for certified operators. |
| Direct Retailer Certification | Carrefour and Tesco unbundling refrigerant supply from maintenance contracts forces chemical suppliers to certify independently. |
| Ammonia-CO2 Hybrid System Deployment | India's National Cold Chain Mission subsidies accelerate agricultural zone adoption around Mumbai and Delhi corridors. |
| REACH Registration Investment | ECHA data requirements for novel HFO blends extend commercialization windows by 18-24 months versus legacy products. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with refrigerant procurement managers at cold storage operators, automotive OEM platform engineers, and specialty gas distribution executives; and secondary validation through EPA SNAP approval databases, ECHA REACH registration filings, EU F-Gas Regulation quota tracking, and customs trade data on fluorochemical precursors. Bottom-up volume estimates from equipment installation rates and refrigerant charge sizes triangulated against top-down chemical producer capacity disclosures.
Across the projection horizon, the analytical framework modeled demand by product chemistry, cooling technology, application segment, and end-user regulatory exposure. CAGRs derived from equipment replacement cycle analysis, phasedown schedule enforcement trajectories, and cold chain infrastructure investment flows. Industry-specific forecast inputs included METI leak inspection interval changes and National Cold Chain Mission subsidy disbursement patterns.
Forecasts assume regulatory continuity in EU F-Gas Regulation phasedown schedules, EPA SNAP approval timelines, and Japan's Fluorocarbon Emissions Control Law enforcement; material policy shifts would require re-modeling. Revision becomes warranted when Chinese precursor export restrictions or REACH registration timeline accelerations cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Multi Component Injection Moulding Technology Market
Industrial Chemicals
Global Isocyanate Market
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
Bleaching Clay Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
Profenofos Market
Industrial Chemicals
Global Itaconic Acid Market