
 Food Grade Sodium Hypochlorite Market | 2026-2036
Food Grade Sodium Hypochlorite Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Sodium Hypochlorite Market Foresight
Beverage manufacturing is restructuring demand patterns across the Food Grade Sodium Hypochlorite Market as carbonated soft drink and bottled water producers expand sanitization protocols. Solvay Chemicals leverages its European chlor-alkali network to sustain supply continuity for continental bottlers. Olin Corporation anchors North American production through integrated bleach manufacturing on the US Gulf Coast. Westlake Chemical Corporation competes via scale advantages in bulk sodium hypochlorite distribution.
Food grade sodium hypochlorite is an aqueous chlorine solution typically containing 5-6% available chlorine, manufactured through electrolysis of sodium chloride and purified to meet food contact safety thresholds for direct and indirect food surface applications. Liquid formulations dominate volume throughput due to ease of dosing in automated CIP systems, while tablet and granule formats capture premium margins in remote or small-scale processing settings where storage stability matters. Surface sanitization applications lead absolute consumption, though water treatment for process and rinse water shows the fastest structural expansion as beverage plants tighten microbial specifications.
The EPA regulates residual chlorine limits under the Safe Drinking Water Act and Food Contact Substance Notification requirements, while the FDA enforces Current Good Manufacturing Practice standards for sanitizing compounds in food facilities. BIS certification in India and EFSA guidance on chlorine-based disinfectants in Europe further fragment compliance obligations across supply chains. Stakeholders must monitor evolving maximum residue limits and alternative sanitizer substitution pressures as clean-label preferences permeate food retail channels.
Market Dynamics
Beverage manufacturers are tightening microbial specifications for process water, forcing sodium hypochlorite suppliers to certify against evolving EPA Food Contact Substance Notification thresholds while managing chlorine purity at lower residual limits.
Growth Catalysts
- Bottled Water Expansion:Premium hydration brands in the United States are retrofitting lines with automated CIP systems that demand consistent 5-6% available chlorine dosing, locking in volume contracts with certified suppliers.
- FDA cGMP Enforcement:Enhanced Current Good Manufacturing Practice audits for sanitizing compounds are disqualifying non-food-grade bleach sources, consolidating procurement toward registered manufacturers.
- Electrolysis Technology:On-site sodium hypochlorite generation systems are penetrating mid-scale dairy processors, reducing transportation costs and stabilizing supply security for perishable operations.
Market Restraints
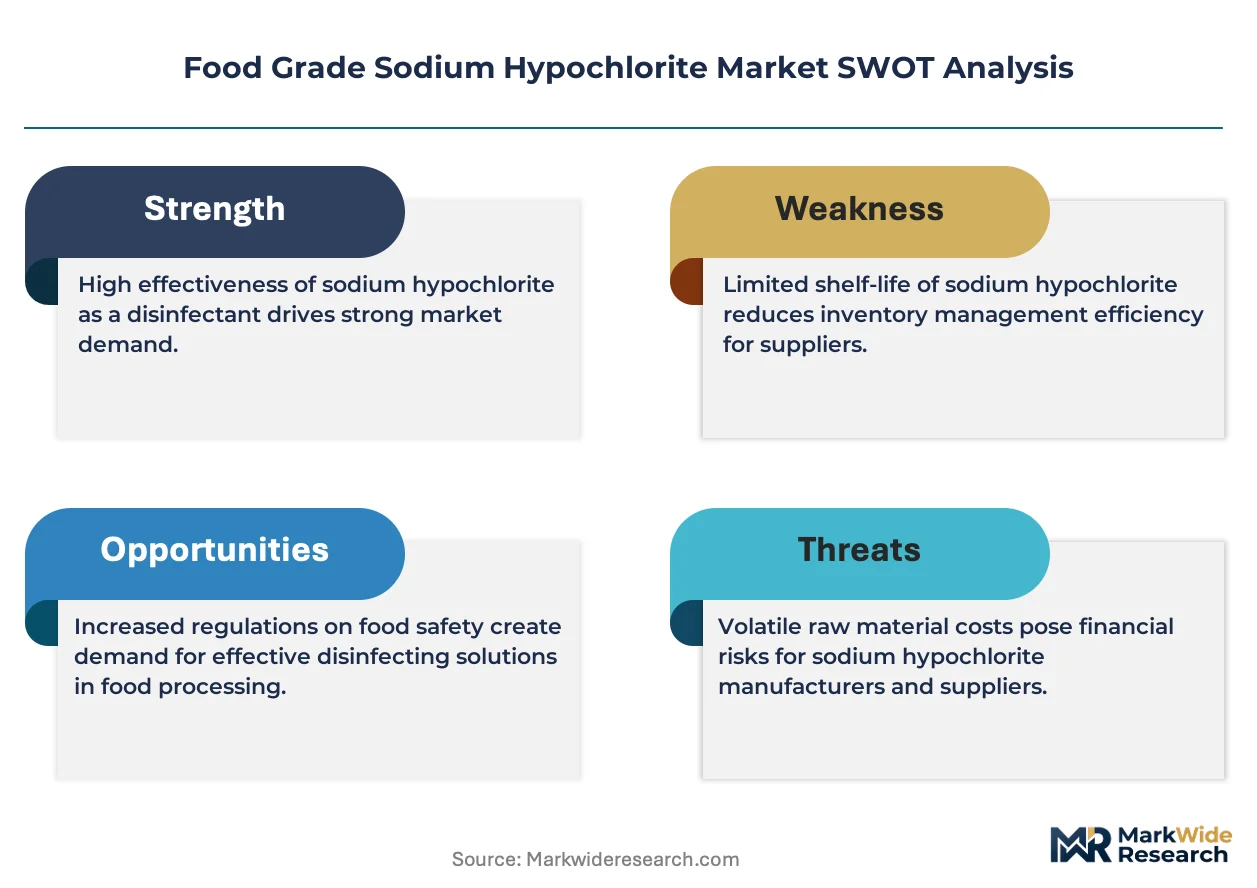
- Caustic Soda Volatility:Chlor-alkali feedstock price swings compress margin predictability for bleach manufacturers, particularly those without backward integration into salt-to-chlorine production.
- Gulf Coast Concentration:Bulk liquid sodium hypochlorite production clusters along hurricane-exposed Texas and Louisiana corridors, exposing national supply chains to weather-related disruption risk.
- Peracetic Acid Substitution:Meat and poultry processors are trialing alternative sanitizers with shorter contact times and no chlorine residual, threatening share in surface sanitization applications.
Strategic Opportunities
- India FSSAI Alignment:Food Safety and Standards Authority of India regulations are converging with Codex standards, opening import pathways for EPA-registered suppliers into underserved subcontinental beverage bottling.
- Tablet Format Premiumization:Remote protein processing facilities in Australia's interior are adopting stabilized hypochlorite granules where liquid logistics fail, capturing 40-60% price premiums over bulk bleach.
- EU Green Deal Chemistry:EFSA guidance on sustainable disinfectant sourcing is creating preference windows for electrolytically produced hypochlorite with verified carbon footprints versus legacy chlor-alkali imports.
Industry Challenges
- Analytical Chemist Shortage:Food-grade certification requires residual chlorine testing at parts-per-billion precision, yet qualified laboratory personnel are scarce in secondary dairy processing counties.
- Legacy Dosing System Retrofit:Automated CIP integration demands stainless-compatible pumps and corrosion-resistant sensors, forcing capital outlays that strain mid-tier meat plant budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Sodium Hypochlorite Market |
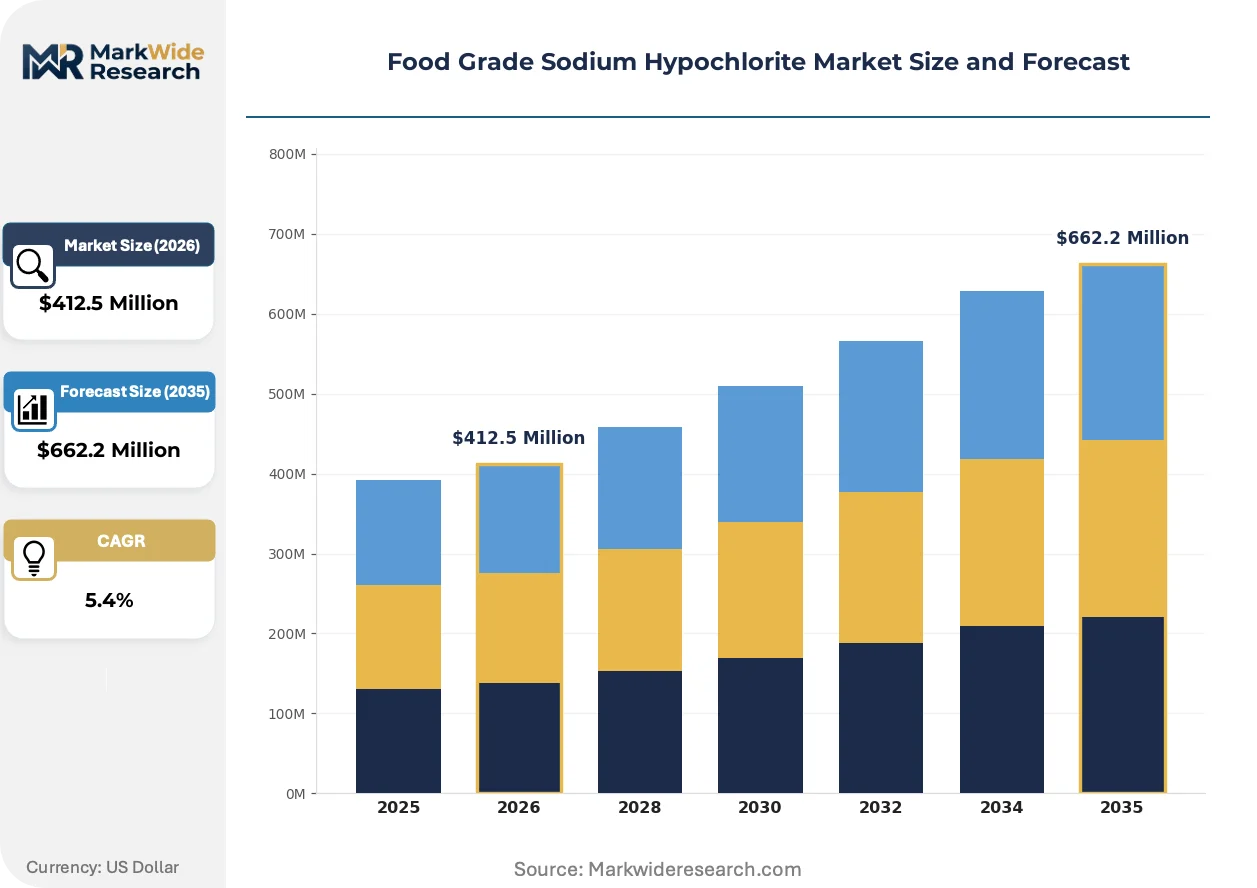
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Tablets, Granules Application: Surface Sanitization, Water Treatment, Food Processing Equipment, Packaging Disinfection End User: Food Processing Units, Beverage Manufacturers, Dairy Plants, Meat Processing Facilities Packaging Type: Drums, Bottles, Jerry Cans, Bulk Containers |
| Companies Covered | AGC Group, Solvay Chemicals, BASF SE, Olin Corporation, AkzoNobel, Arkema, OxyChem, Westlake Chemical Corporation, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Sodium Hypochlorite Market Shifts & Advancements
Electrochemical generation methods and real-time residual monitoring are compressing the gap between production and point-of-use, while regulatory data requirements are forcing documentation investments that favor integrated suppliers over merchant traders.
Membrane cell electrolysis is rewriting chlorine purity standards by eliminating mercury and diaphragm process contaminants, enabling sub-10 ppb heavy metal specifications that satisfy organic beverage brand requirements. Premium kombucha and cold-pressed juice bottlers in California and New York are specifying membrane-grade hypochlorite for bottle rinsing, pressuring commodity suppliers to upgrade chlor-alkali assets or exit food-grade segments entirely.
EPA's enhanced Food Contact Substance Notification review timelines are extending market entry lead times for new sodium hypochlorite sources, compressing competitive pressure on existing registrants. The agency's 2024 guidance on cumulative dietary chlorine exposure is forcing beverage manufacturers to document rinse-water residuals across multiple sanitizing steps, accelerating demand for automated dosing controls with data logging capabilities.
Consolidated procurement through national beverage co-manufacturers is displacing regional chemical distributor relationships, as contract packagers centralize sanitizer sourcing to satisfy retailer audit requirements. Large soft drink bottlers in the southeastern United States are mandating supplier ISO 22000 certification and quarterly third-party purity testing, excluding smaller bleach merchants from approved vendor lists and concentrating volume with integrated chlor-alkali producers.
Food Grade Sodium Hypochlorite Market Segmentation
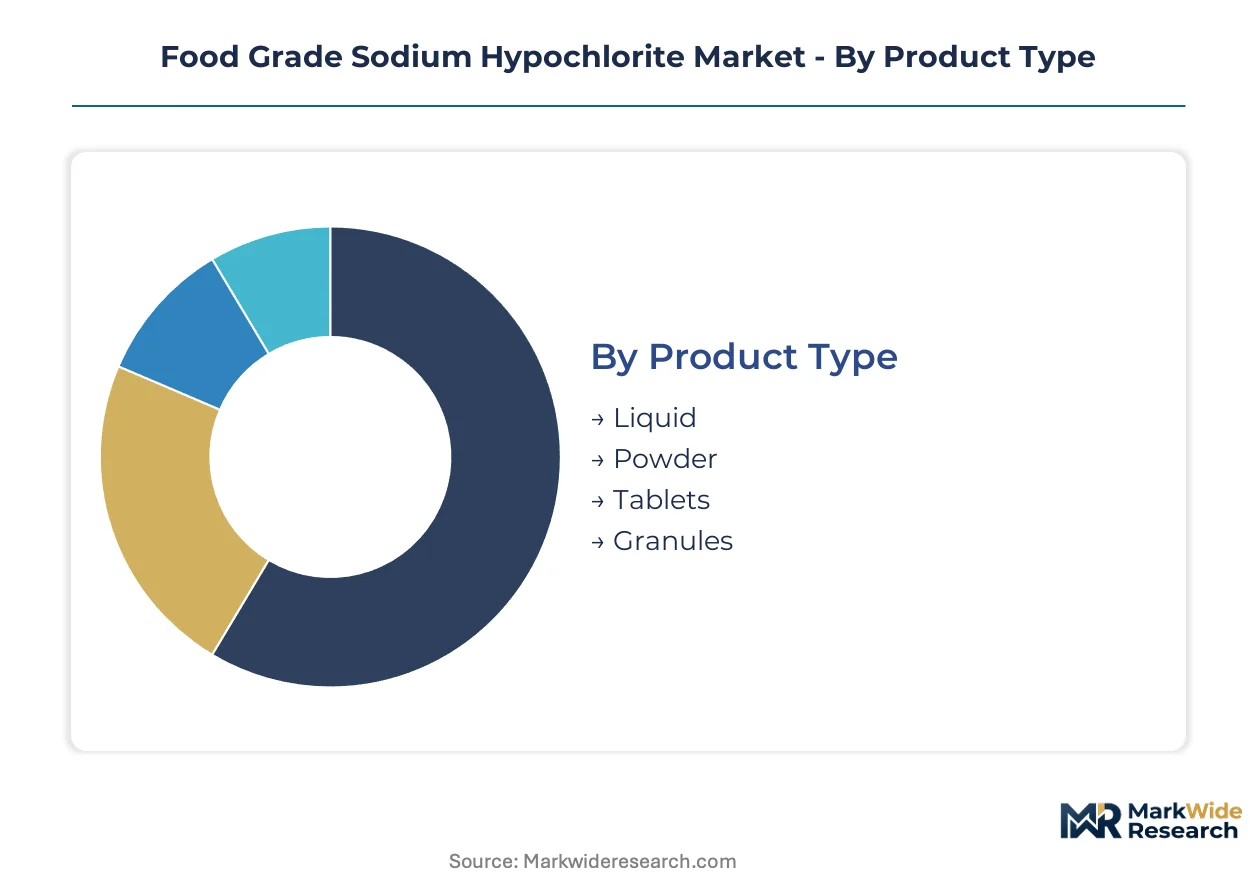
Food grade sodium hypochlorite procurement splits sharply between high-volume liquid contracts for automated CIP systems and premium-priced solid formats serving remote processing sites. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume throughput dominates.
Product Type:
Liquid formulations command absolute volume throughput while solid formats extract price premiums from logistics-constrained buyers.
- Liquid:Aqueous solutions containing 5-6% available chlorine dominate beverage bottling and dairy CIP systems for precise automated dosing. United States carbonated soft drink producers lock in multi-year supply agreements with Gulf Coast manufacturers to secure batch consistency.
- Tablets:Stabilized compressed formulations serve Australian interior protein processors where bulk liquid transport fails, capturing substantial markups over equivalent chlorine content. Outback beef facilities specify tablet formats to eliminate spillage risk during remote site delivery.
- Powder:Dehydrated hypochlorite salts target small-scale food processors in India's tier-2 cities requiring extended shelf stability without refrigeration infrastructure.
- Granules:Free-flowing crystalline products penetrate Southeast Asian seafood drying operations where controlled dissolution rates improve worker safety during manual mixing.
Today's leader: Liquid. Tomorrow's challenger: Tablets.
Application:
Surface contact applications anchor current consumption while process water treatment climbs fastest on tightening microbial specifications.
- Surface Sanitization:Direct food-contact and non-contact surface disinfection absorbs the majority of chlorine volume across meat, dairy, and produce handling facilities. FDA cGMP enforcement is disqualifying non-food-grade bleach sources, consolidating procurement toward registered suppliers.
- Water Treatment:Process and rinse water disinfection shows steepest expansion trajectory as EPA Food Contact Substance Notification thresholds tighten residual chlorine limits. Premium kombucha bottlers in California now specify sub-10 ppb heavy metal specifications for bottle rinsing applications.
- Food Processing Equipment:CIP system integration demands stainless-compatible dosing pumps and corrosion-resistant sensors, forcing capital outlays that strain mid-tier plant budgets.
- Packaging Disinfection:Bottle and container sterilization protocols in bottled water manufacturing require documented rinse-water residuals across multiple sanitizing steps.
Surface Sanitization holds installed base dominance. Water Treatment gains share fastest on regulatory tightening.
End User:
Beverage sector procurement is restructuring supply relationships through consolidated national co-manufacturer contracts.
- Beverage Manufacturers:Carbonated soft drink and bottled water producers drive format standardization through automated CIP retrofits, mandating ISO 22000 certification from suppliers. Southeastern United States bottlers now require quarterly third-party purity testing.
- Meat Processing Facilities:Beef and poultry plants trial peracetic acid alternatives with shorter contact times, threatening chlorine share in surface applications despite established cost advantages.
- Dairy Plants:Fluid milk and cheese processors adopt on-site electrolytic generation systems to reduce transportation costs and stabilize supply security for perishable operations.
- Food Processing Units:General ingredient handling and prepared food facilities balance cost pressures against retailer audit requirements for documented sanitizer sourcing.
Beverage Manufacturers dictate contract terms today. Dairy Plants reshape supply architecture tomorrow through captive production.
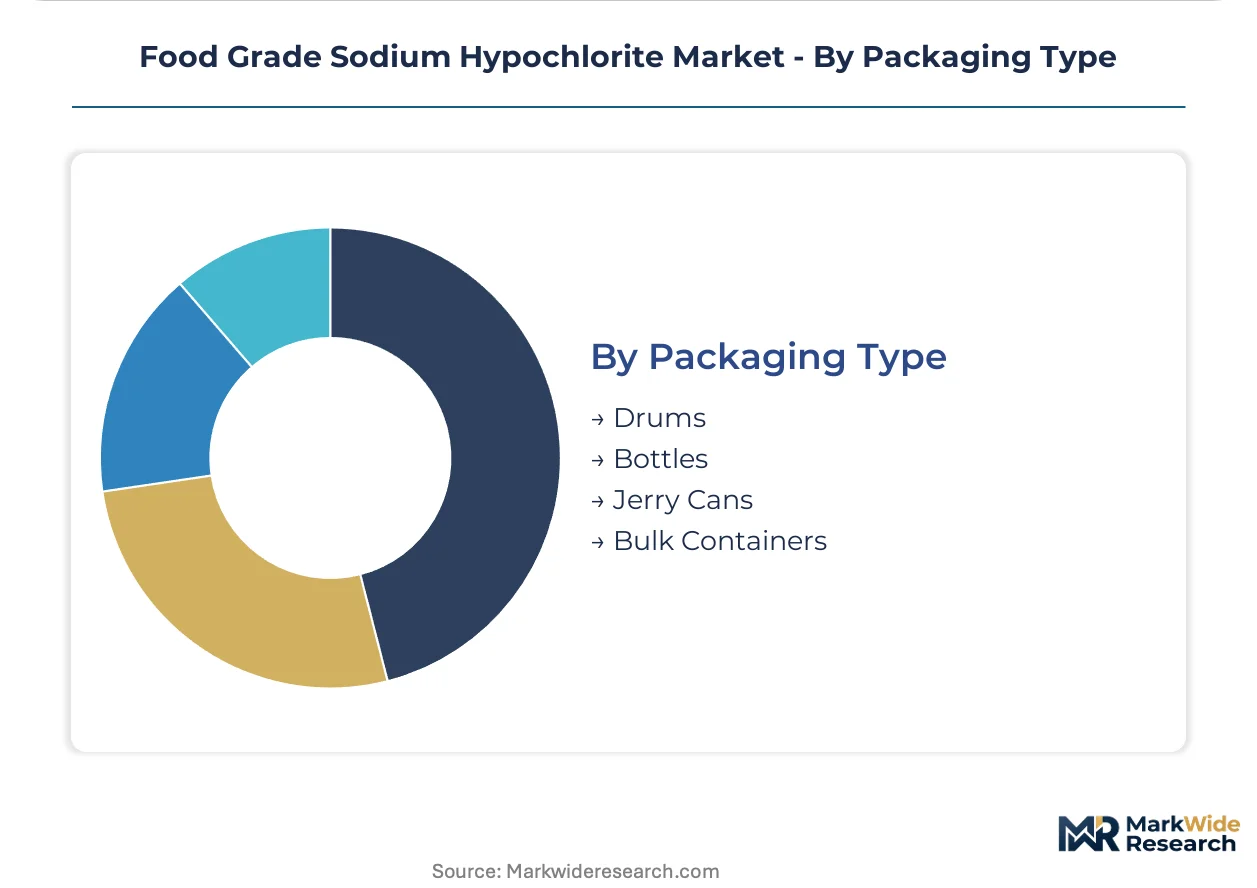
Packaging Type:
Container economics split between bulk logistics efficiency and small-lot flexibility for distributed processing networks.
- Bulk Containers:Tanker and intermediate bulk container deliveries minimize per-unit chlorine cost for high-throughput beverage bottlers with dedicated storage infrastructure.
- Drums:Standard 55-gallon steel and polyethylene drums serve mid-scale meat processors requiring weekly replenishment without capital investment in bulk tanks.
- Jerry Cans:5-20 liter portable containers penetrate India's subcontinental beverage bottling expansion where FSSAI regulatory alignment opens import pathways for EPA-registered suppliers.
- Bottles:Retail-scale packaging targets artisanal food producers and institutional kitchen operators with infrequent sanitization needs.
Bulk Containers define cost leadership. Jerry Cans unlock geographic expansion into compliance-evolving markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers migrate toward jurisdictions with streamlined food-contact substance approvals and lower compliance friction. Cost-of-compliance gaps between EPA-registered US suppliers and emerging-market producers are narrowing as Codex-aligned standards propagate.
United States
Beverage bottlers in the Southeast are mandating ISO 22000 certification and quarterly third-party purity testing from sodium hypochlorite suppliers. The EPA's Food Contact Substance Notification program enforces residual chlorine documentation across multiple sanitizing steps. Gulf Coast chlor-alkali corridors in Texas and Louisiana concentrate bulk liquid production, though hurricane exposure elevates supply security premiums.
Germany
EFSA guidance on sustainable disinfectant sourcing is creating preference windows for electrolytically produced hypochlorite with verified carbon footprints. The EU Green Deal Chemistry initiative pressures legacy chlor-alkali imports. Industrial clusters along the Rhine corridor are retrofitting CIP systems to accommodate membrane-grade chlorine specifications demanded by organic beverage brands.
India
FSSAI regulations are converging with Codex standards, opening import pathways for EPA-registered suppliers into underserved subcontinental beverage bottling. BIS certification requirements fragment compliance obligations for domestic manufacturers. Maharashtra and Gujarat dairy processors are adopting on-site electrolytic generation systems to reduce transportation costs in perishable operations.
China
Dual carbon goals are accelerating membrane cell electrolysis upgrades that eliminate mercury process contaminants. SAMR enforcement of GB standards for food-contact chemicals is tightening residual heavy metal specifications. Yangtze River Delta beverage manufacturers are specifying sub-10 ppb heavy metal limits for bottle rinsing applications, pressuring commodity suppliers to upgrade assets.
Australia
Remote protein processing facilities in the interior are adopting stabilized hypochlorite tablets where bulk liquid logistics fail, capturing substantial price premiums. TGA alignment with Codex disinfectant standards is simplifying import pathways for certified suppliers. Outback beef facilities specify solid formats to eliminate spillage risk during remote site delivery.
Food Grade Sodium Hypochlorite Market Competitive Landscape
Backward integration into salt-to-chlorine production dominates the current landscape as bleach manufacturers seek margin predictability against caustic soda volatility. The vendor base stratifies between integrated chlor-alkali majors with captive supply security and merchant traders dependent on spot feedstock markets. Three archetypes define competitive positioning: Gulf Coast-anchored volume producers, European sustainability-certified specialists, and Asia-Pacific cost-optimized exporters. Capacity expansion and portfolio diversification toward on-site generation systems represent the dominant competitive vectors.
Among integrated chemical majors, Solvay Chemicals exemplifies the European sustainability-certified archetype through its chlor-alkali network positioning, while Olin Corporation anchors North American production scale through integrated bleach manufacturing. Westlake Chemical Corporation occupies the bulk distribution tier, competing via logistics reach into automated CIP-dependent beverage bottling corridors. These three entities represent distinct strategic postures without implying specific market share claims or operational details beyond their evident geographic and structural positioning.
| Leading Market Players |
|---|
| AGC Group |
| Solvay Chemicals |
| BASF SE |
| Olin Corporation |
| AkzoNobel |
| Arkema |
| OxyChem |
| Westlake Chemical Corporation |
| Lonza Group |
| Others |
Supply & Pricing Matrix
EU Green Deal Chemistry mandates gate both qualified supply and premium-tier pricing access, as EFSA guidance on sustainable disinfectant sourcing restricts market entry to electrolytically produced hypochlorite with verified carbon footprints while commanding substantial markups over legacy chlor-alkali imports.
Pricing Analysis
Distributor margins compress as national beverage co-manufacturers consolidate procurement through direct contracts with integrated chlor-alkali producers. Three-tier pricing structure across membrane-grade premium, standard food-grade, and economy industrial bleach separates organic beverage certifiers from conventional dairy processors from non-food merchant traders. Cost compression in standard tiers intensifies because caustic soda feedstock volatility squeezes non-integrated manufacturers. Mid-tier meat processors exhibit highest price sensitivity due to capital constraints on CIP retrofit investments, while premium kombucha bottlers show lowest sensitivity when specifying sub-10 ppb heavy metal specifications.
Supply Chain Analysis
Regional distribution centers along the US Gulf Coast anchor hub-and-spoke patterns radiating into southeastern beverage bottling corridors, though hurricane exposure elevates supply security premiums. Production concentrates in the United States, Germany, and China as membrane cell electrolysis upgrades eliminate mercury process contaminants. Feedstock flows draw from salt deposits, chlorine gas production, and caustic soda integration. Single-source vulnerability runs through Texas and Louisiana chlor-alkali corridors where weather-related disruptions cascade nationwide. Distribution runs through bulk tanker deliveries to high-throughput bottlers, drum shipments to mid-scale processors, and jerry can channels into India's regulatory-evolving markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EPA-registered US suppliers capture premium pricing in India's FSSAI-converging import pathways against domestic BIS certification fragmentation that elevates compliance costs for local manufacturers.
For Market Incumbents: Lock in multi-year volume contracts with automated CIP-dependent beverage bottlers before on-site electrolytic generation penetrates mid-scale dairy operations. Backward integration into salt-to-chlorine production insulates margin predictability against caustic soda volatility. Fortify Gulf Coast production redundancy against hurricane exposure through distributed storage assets. Invest in membrane cell electrolysis upgrades to satisfy organic brand sub-10 ppb heavy metal specifications and disqualify commodity competitors from premium tiers. For New Entrants and Emerging Players: Enter via India's underserved subcontinental beverage bottling expansion where FSSAI regulatory alignment with Codex standards opens import pathways for EPA-registered suppliers. Target remote protein processing facilities in Australia's interior with stabilized hypochlorite tablets where bulk liquid logistics fail and capture 40-60% price premiums. Pursue EU Green Deal Chemistry certification to access EFSA preference windows for verified low-carbon electrolytic production. Lead with ISO 22000 certification and quarterly third-party purity testing to satisfy retailer audit requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional bleach distributors with established FDA-registered supplier relationships because national beverage co-manufacturer consolidation is displacing fragmented distributor networks and concentrating volume with integrated producers. Platform aggregation of mid-scale distributors with captive storage infrastructure and certified supplier access offers defensive cash flow streams. Monitor EPA Food Contact Substance Notification review timeline extensions as inflection indicator for competitive pressure on existing registrants and barrier elevation for new market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Electrolysis Upgrade | Eliminates mercury contaminants to satisfy organic beverage brand sub-10 ppb heavy metal specifications. |
| On-Site Generation System Deployment | Reduces transportation costs and stabilizes supply security for perishable dairy operations. |
| ISO 22000 Certification Investment | Unlocks approved vendor status with large southeastern US soft drink bottlers mandating quarterly purity testing. |
| Backward Integration into Chlor-Alkali | Insulates margin predictability against caustic soda feedstock price volatility through captive salt-to-chlorine production. |
| Tablet Format Manufacturing Capacity | Captures premium pricing from remote Australian protein processors where bulk liquid transport fails. |
Research Methodology
Direct dialogue with chlor-alkali plant managers, beverage procurement leads, dairy technical directors, and chemical distribution channel partners grounded qualitative findings, validated against customs and trade data, SEC filings from integrated chemical majors, EPA Food Contact Substance Notification records, and EFSA disinfectant guidance documents. Bottom-up volume modeling across product type, application, and end-user segments was triangulated with top-down market sizing from production capacity disclosures and regional consumption patterns.
Bottom-up demand estimation aggregated individual end-user consumption profiles across beverage bottling, meat processing, dairy operations, and food processing units, while top-down validation calibrated against chlor-alkali production data and bleach manufacturing capacity. Segmentation dimensions spanned liquid/tablet/powder/granule formats, surface sanitization versus water treatment versus equipment CIP versus packaging disinfection applications, and beverage manufacturer versus meat processor versus dairy plant versus general food processing end users. CAGRs were derived from regression analysis of historical volume trends against regulatory enforcement intensity and capital expenditure cycles in automated CIP system adoption.
Inputs from EPA registration databases, EFSA guidance publications, and FSSAI regulatory filings were available through the study window; gaps in real-time chlor-alkali feedstock pricing transparency and proprietary contract terms between national beverage co-manufacturers and integrated suppliers introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding regulatory timeline adherence, electrolytic generation technology penetration rates, and peracetic acid substitution velocity in meat and poultry applications. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
North America Quicklime Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
Quenching Fluids and Salts Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Swimming Pool Salt Chlorinator Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
Soil Treatment Chemicals Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Profenofos Market
Industrial Chemicals
Hydrogen Silicone Fluid Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Non-Corrosive Fluxes Market