
 Global Refrigerants Market | 2026-2036
Global Refrigerants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Refrigerants Market Foresight
Specialized fluorochemical engineering talent is collapsing across Western Europe and North America, tightening the labor pipeline for next-generation refrigerant development. Honeywell International Inc. leverages its integrated R&D infrastructure to sustain patent-protected hydrofluoroolefin production at scale. The Chemours Company anchors its competitive position through backward integration into fluorinated feedstock chemistry. Dongyue Group Ltd. dominates fluoropolymer and refrigerant precursor manufacturing from its Shandong production base.
Refrigerants are thermodynamic working fluids characterized by specific boiling points, critical temperatures, and global warming potential ratings that enable efficient heat absorption and rejection in closed-cycle systems. These compounds function through phase-change mechanisms, transitioning between liquid and vapor states at controlled pressures to transfer thermal energy in cooling equipment. Natural refrigerants, including ammonia and carbon dioxide variants, are gaining share as hydrofluorocarbon alternatives face regulatory phase-down schedules. Hydrofluoroolefin formulations within the hydrofluorocarbon category command premium positioning due to their reduced environmental impact and compatibility with existing system architectures. Air conditioning applications sustain the largest volume consumption, though cold storage warehouses represent the fastest-growing end user segment as food supply chain infrastructure expands.
The US Environmental Protection Agency enforces phasedown mandates under the American Innovation and Manufacturing Act, restricting high-global-warming-potential refrigerant production and import volumes. The European Union F-Gas Regulation imposes quota allocations and product bans that reshape formulation strategies for equipment manufacturers serving EU member states. India's Central Pollution Control Board implements refrigerant handling certifications that govern technician qualifications and recovery protocols. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with divergent compliance timelines and avoid stranded inventory positions.
Market Dynamics
The Kigali Amendment's hydrofluorocarbon phase-down mandates are compressing formulation timelines while forcing equipment manufacturers to redesign system architectures around lower-global-warming-potential alternatives.
Growth Catalysts
- Cold Chain Infrastructure Expansion:India's food processing modernization and pharmaceutical logistics networks are accelerating refrigerant consumption for warehouse climate control systems.
- F-Gas Regulation Quotas:The European Union's phased allocation system is compelling equipment OEMs to qualify hydrofluoroolefin blends ahead of mandated hydrofluorocarbon volume restrictions.
- Natural Refrigerant Retrofits:Ammonia and carbon dioxide systems are penetrating industrial freezing applications as facilities seek exemption from synthetic refrigerant compliance burdens.
Market Restraints
- Fluorinated Feedstock Concentration:China's dominance in fluorspar mining and hydrogen fluoride processing creates supply vulnerability for Western hydrofluoroolefin producers.
- Retrofit Cost Barriers:Existing commercial refrigeration infrastructure requires complete compressor and expansion valve replacement to accommodate next-generation refrigerant chemistries.
- Technical Property Trade-offs:Low-global-warming-potential hydrofluoroolefins exhibit reduced volumetric cooling capacity versus legacy hydrofluorocarbon formulations, demanding larger system footprints.
Strategic Opportunities
- Mobile Air Conditioning Convergence:Electric vehicle thermal management systems are creating incremental refrigerant demand as battery cooling loops integrate with cabin climate control.
- Heat Pump Deployment Acceleration:Germany's building sector decarbonization incentives are expanding reversible-cycle refrigerant volumes for residential heating substitution.
- Refrigerant Recovery Infrastructure:India's Central Pollution Control Board certification mandates are opening service-contract opportunities for cylinder reclamation and purification equipment providers.
Industry Challenges
- Fluorochemical Engineering Scarcity:Western Europe and North America face collapsing pipelines of specialized talent capable of synthesizing next-generation refrigerant molecules at commercial scale.
- Cross-Jurisdictional Compliance Fragmentation:Divergent phase-down schedules between the US EPA's American Innovation and Manufacturing Act and EU F-Gas Regulation create stranded inventory risks for multinational formulation portfolios.
- System Compatibility Certification:Equipment manufacturers must validate seal materials, lubricant miscibility, and pressure rating adequacy across proliferating refrigerant blend variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Refrigerants Market |
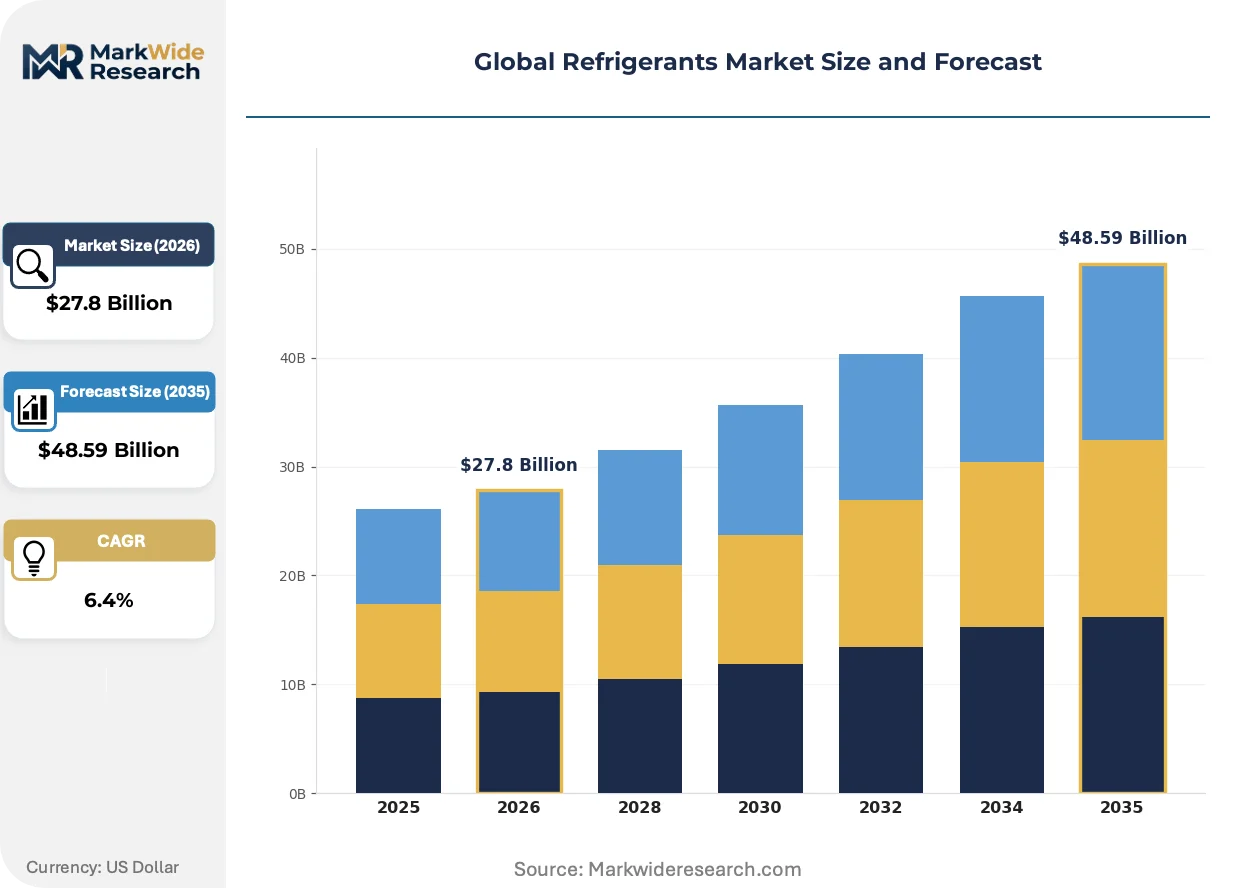
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $48.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrofluorocarbons, Chlorofluorocarbons, Hydrochlorofluorocarbons, Natural Refrigerants, Hydrocarbon Refrigerants, Inorganic Refrigerants Application: Air Conditioning, Heat Pumps, Refrigeration Systems, Cryogenics, Automotive Cooling Systems, Industrial Process Cooling End User: Commercial Facilities, Residential Buildings, Food Processing Units, Chemical Plants, Cold Storage Warehouses, Marine Vessels Distribution Channel: Direct Sales, Wholesale Suppliers, Distributors, Online Marketplaces, Retail Outlets, Specialized Dealers |
| Companies Covered | Honeywell International Inc., The Chemours Company, Daikin Industries Ltd., Arkema Group, Linde Plc, Air Liquide SA, Dongyue Group Ltd., AGC Inc., A-Gas International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Refrigerants Market Shifts & Advancements
Formulation chemistry is pivoting toward hydrofluoroolefin architectures as thermodynamic performance and environmental compliance converge in equipment design specifications. Three developments are compressing competitive timelines.
Hydrofluoroolefin-1234yf is supplanting hydrofluorocarbon-134a in mobile air conditioning systems as automakers redesign thermal loops for compliance with EPA vehicle emission standards. Passenger car OEMs in Germany, Japan, and the United States have completed platform transitions, while commercial vehicle segments accelerate qualification programs. This substitution is compressing demand for legacy hydrofluorocarbon production capacity and redirecting capital toward hydrofluoroolefin polymerization assets.
The European Union F-Gas Regulation's quota allocation mechanism is forcing refrigerant blenders to register hydrofluorocarbon consumption volumes against declining annual baselines. Equipment manufacturers serving EU member states now pre-qualify hydrofluoroolefin alternatives two product generations ahead of mandatory phase-down deadlines. Commercial refrigeration OEMs are most exposed, with supermarket display case and cold storage warehouse segments accelerating system redesign cycles.
Food retailers are consolidating refrigerant procurement through national service contracts that bundle cylinder supply, leak detection, and recovery reclamation into unified agreements. Independent contractors and regional distributors are losing share to integrated facility management providers with certified technician networks and centralized refrigerant tracking systems. This concentration is most visible in the United Kingdom and France, where supermarket chains face intensified scrutiny from environmental regulators on leakage rate disclosures.
Global Refrigerants Market Segmentation
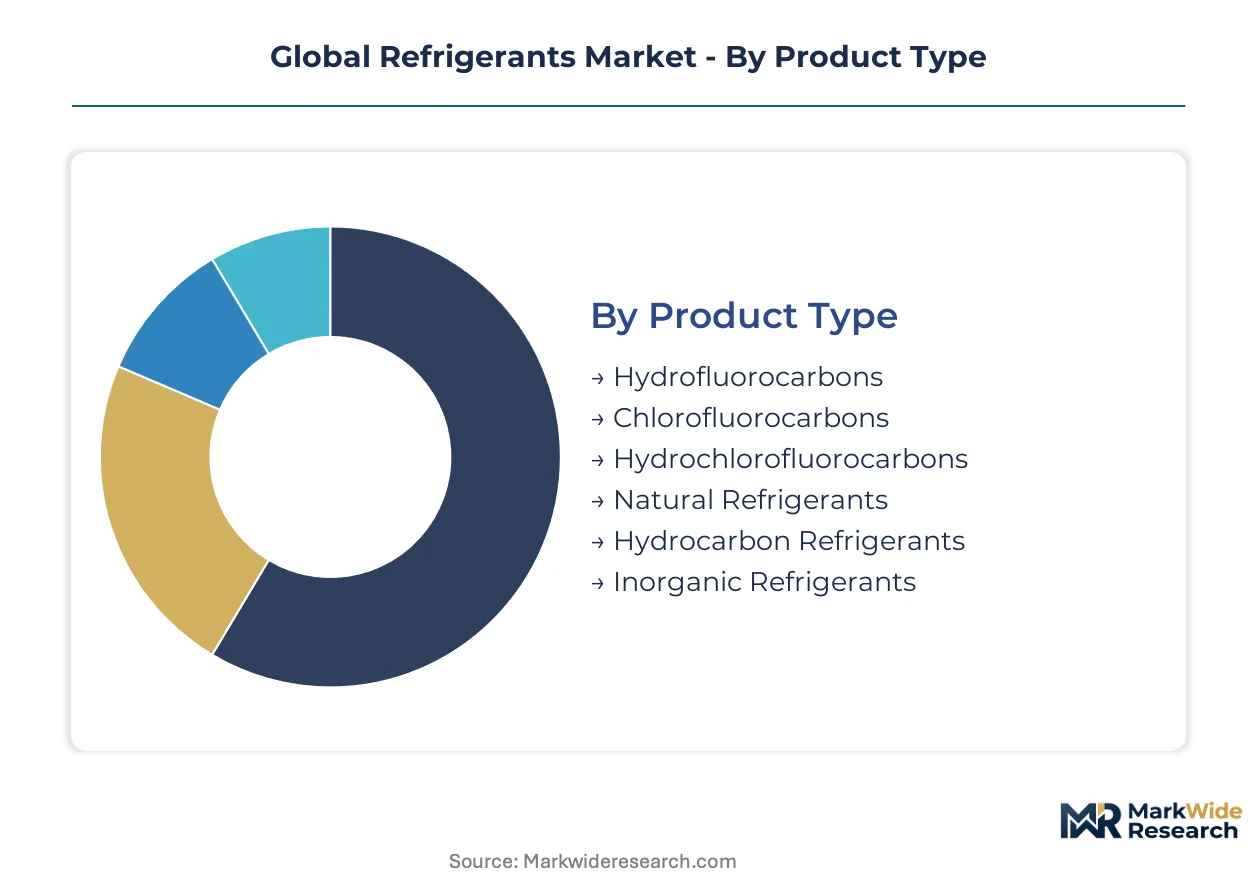
Refrigerant segmentation reveals how regulatory phase-downs and thermal performance requirements split demand across incompatible chemistries. Substitution pressures vary dramatically by product category, with some segments facing imminent obsolescence while others capture displaced volume.
Product Type:
Hydrofluorocarbons face the most severe substitution threat as Kigali Amendment schedules force formulation switches, while natural refrigerants gain protected status through regulatory exemptions.
- Hydrofluorocarbons:Synthetic fluorinated compounds dominate installed base volumes across commercial air conditioning and industrial cooling. EPA phasedown mandates under the American Innovation and Manufacturing Act are compressing production quotas and redirecting capital toward hydrofluoroolefin alternatives.
- Natural Refrigerants:Ammonia and carbon dioxide formulations bypass synthetic refrigerant compliance burdens through environmental exemptions. Cold storage warehouses in Germany and industrial freezing facilities in India are retrofitting systems to qualify for simplified regulatory treatment.
- Chlorofluorocarbons:Ozone-depleting substances now restricted to legacy equipment maintenance and reclaimed cylinder supply.
- Hydrochlorofluorocarbons:Transitional chemistry facing complete phase-out under Montreal Protocol schedules.
- Hydrocarbon Refrigerants:Propane and isobutane blends penetrating domestic refrigeration with flammability-rated system architectures.
- Inorganic Refrigerants:Water and air cycles limited to specialized industrial heat rejection applications.
Hydrofluorocarbons anchor the volume base while natural refrigerants gain share at the steepest rate.
Application:
Cost tier stratification separates premium-specification mobile systems from commoditized stationary cooling, with thermal management complexity driving formulation selection.
- Air Conditioning:Largest consumption segment spanning residential split systems and commercial chillers. India's building stock expansion and Middle Eastern urban cooling requirements sustain cylinder demand despite efficiency regulations tightening refrigerant charge limits.
- Automotive Cooling Systems:Passenger vehicle thermal loops integrate battery cooling with cabin climate control in electric vehicle platforms. German and Japanese OEMs have completed hydrofluoroolefin-1234yf transitions, while commercial vehicle segments accelerate qualification timelines.
- Heat Pumps:Reversible-cycle systems expanding across German residential heating substitution programs.
- Refrigeration Systems:Supermarket display cases and commercial cold rooms facing accelerated redesign cycles under EU F-Gas quota pressure.
- Cryogenics:Ultra-low temperature medical and scientific applications requiring specialized blend formulations.
- Industrial Process Cooling:Chemical manufacturing and petrochemical refining with customized refrigerant specifications.
Air conditioning sustains the largest revenue pool while automotive cooling systems expand most quickly through electrification-driven thermal management integration.
End User:
Customer type concentration clusters around facility scale and regulatory exposure, with food chain infrastructure commanding specialized service relationships.
- Cold Storage Warehouses:Fastest-expanding end user segment driven by India's food processing modernization and pharmaceutical logistics networks. Central Pollution Control Board certification mandates are consolidating procurement through integrated facility management providers with certified technician networks.
- Commercial Facilities:Office buildings, retail spaces, and hospitality properties with standardized maintenance contracts and leak detection requirements. United Kingdom and French supermarket chains face intensified regulatory scrutiny on leakage rate disclosures.
- Food Processing Units:Slaughterhouses, dairies, and prepared food manufacturing with continuous cooling demands.
- Residential Buildings:Distributed split-system installations with price-sensitive replacement cycles.
- Chemical Plants:Process cooling with corrosion-resistant and high-temperature formulation requirements.
- Marine Vessels:Container ship reefer units and offshore platform climate control with salt-environment compatibility constraints.
Commercial facilities anchor the volume base while cold storage warehouses gain share at the steepest rate.
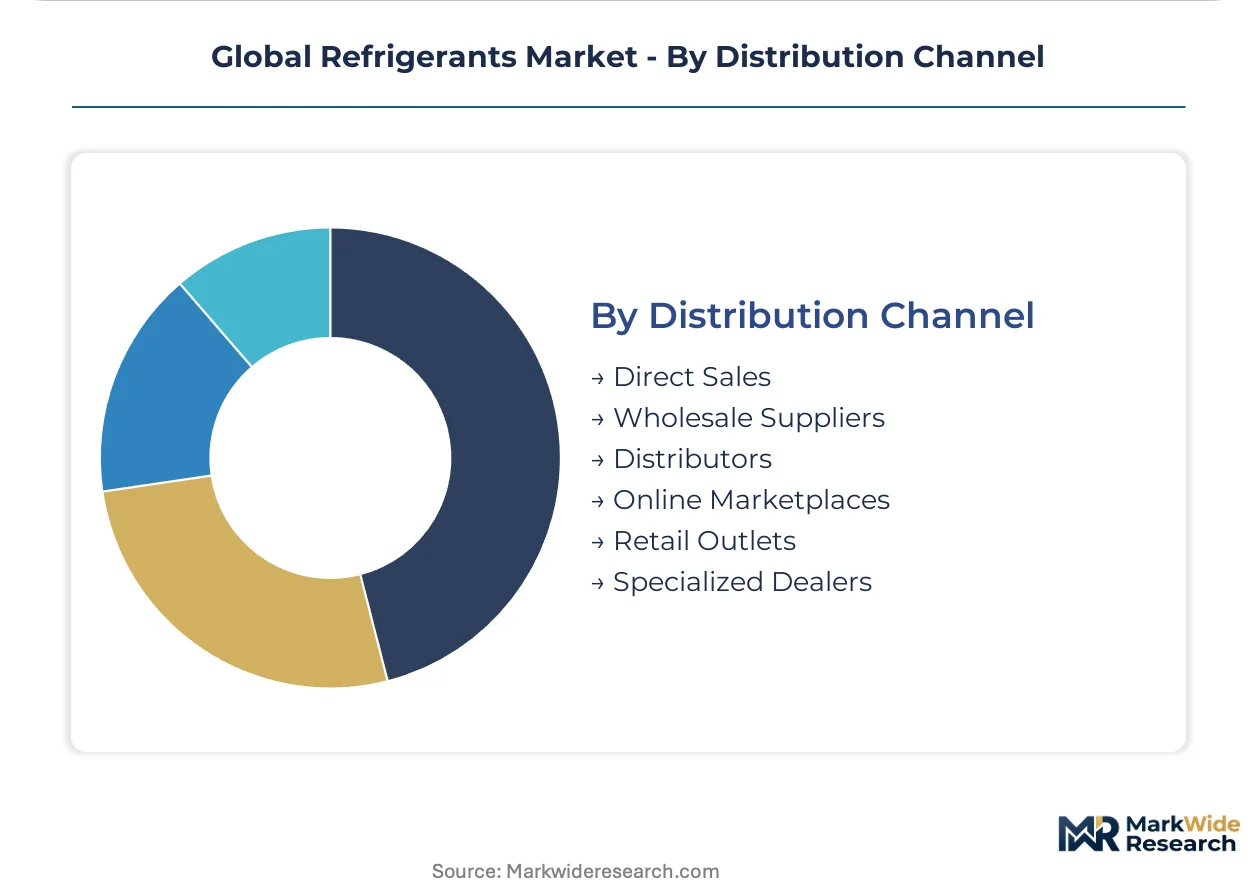
Distribution Channel:
Supply chain configuration stratifies by customer technical sophistication, with certified handling requirements filtering access to qualified intermediaries.
- Distributors:Regional networks with cylinder tracking systems and recovery equipment dominate commercial and industrial procurement. India's Central Pollution Control Board certification requirements are excluding independent contractors without reclamation capabilities.
- Direct Sales:Large-volume contracts from multinational formulators to equipment OEMs and national retail chains. Food retailers in the United Kingdom and France are consolidating procurement through unified service agreements bundling supply, leak detection, and recovery reclamation.
- Wholesale Suppliers:Volume aggregation for contractor networks and regional service providers.
- Specialized Dealers:Technical specification support for complex industrial applications.
- Online Marketplaces:Limited penetration due to hazardous material shipping restrictions and cylinder certification requirements.
- Retail Outlets:Consumer-accessible small-charge products for domestic appliance servicing.
Distributors anchor the volume base while direct sales gains share at the steepest rate through national contract consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Central Pollution Control Board anchors the dominant geography through mandatory technician certification and refrigerant recovery protocols that reshape procurement patterns across South Asia.
United States
Electric vehicle thermal management integration accelerates hydrofluoroolefin-1234yf adoption across Detroit and California automotive clusters. The EPA enforces phasedown mandates under the American Innovation and Manufacturing Act, restricting high-global-warming-potential production volumes. Houston's petrochemical corridor hosts fluorinated feedstock processing facilities supplying Gulf Coast refrigerant blenders.
Germany
Residential heat pump deployment expands reversible-cycle refrigerant demand for building sector decarbonization. The EU F-Gas Regulation imposes quota allocations compelling equipment OEMs to qualify hydrofluoroolefin blends ahead of volume restrictions. The Ruhr industrial region concentrates supermarket display case manufacturers accelerating system redesign cycles.
China
Shandong Province's fluoropolymer and refrigerant precursor manufacturing base dominates global fluorspar-to-hydrofluoroolefin supply chains. The Ministry of Ecology and Environment implements dual carbon goals pressuring domestic formulators toward lower-emission chemistries. Zhejiang's chemical processing clusters expand hydrofluorocarbon alternative production capacity for export markets.
India
Food chain modernization and pharmaceutical logistics networks accelerate cold storage warehouse refrigerant consumption across Maharashtra and Gujarat. Central Pollution Control Board certification mandates consolidate procurement through integrated facility management providers with certified technician networks. Telangana's Hyderabad pharma corridor drives specialized climate control system installations.
Japan
Automotive OEMs in Nagoya and Tokyo complete hydrofluoroolefin platform transitions for passenger vehicle thermal loops. METI oversees industrial energy efficiency standards influencing commercial refrigeration system specifications. Osaka's HVAC equipment manufacturers pre-qualify next-generation refrigerant blends for Southeast Asian export markets.
Global Refrigerants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the refrigerants sector. The market structure consolidates around integrated chemical conglomerates with captive fluorinated feedstock supply and specialized formulators with regional distribution networks. Three archetypes dominate: multinational diversified chemical groups with patent-protected hydrofluoroolefin platforms, Asia-Pacific commodity producers leveraging scale economics in precursor manufacturing, and regional reclamation service providers with certified recovery infrastructure. Competitive dynamics center on backward integration into fluorspar mining and hydrogen fluoride processing, alongside strategic partnerships with equipment OEMs for refrigerant blend pre-qualification.
Among integrated chemical conglomerates, Honeywell International Inc., The Chemours Company, and Dongyue Group Ltd. occupy positions representing distinct geographic and structural approaches. Honeywell exemplifies the patent-anchored technology archetype through its integrated R&D infrastructure. The Chemours Company represents backward integration into fluorinated feedstock chemistry. Dongyue Group anchors the Asia-Pacific scale-production archetype from its Shandong manufacturing base. These three entities collectively illustrate how competitive positioning fragments across technology control, supply chain depth, and regional market access rather than consolidating around uniform capabilities.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| The Chemours Company |
| Daikin Industries Ltd. |
| Arkema Group |
| Linde Plc |
| Air Liquide SA |
| Dongyue Group Ltd. |
| AGC Inc. |
| A-Gas International Ltd. |
| Others |
Supply & Pricing Matrix
Hydrofluoroolefin feedstock substitution for legacy hydrofluorocarbon precursors simultaneously redraws procurement geography toward Shandong Province and compresses margin structures for Western blenders facing fluorspar cost pass-throughs. This input transition rewards integrated producers with captive hydrogen fluoride capacity while exposing non-integrated formulators to volatile spot-market pricing for fluorinated intermediates.
Pricing Analysis
Geographic price spreads between Chinese-origin hydrofluoroolefin precursors and finished European formulations exceed transport-cost differentials alone. The dominant structure runs through contract-based long-term offtake agreements with volume-scale and certification-grade drivers separating premium EPA-registered blends from commodity-tier alternatives. Cost compression in mid-tier hydrofluorocarbon alternatives intensifies as Indian cold storage procurement consolidates through national service contracts. Cold storage warehouse operators exhibit highest price sensitivity due to thin refrigeration-as-a-service margins, while German automotive OEMs prioritize thermal performance over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites fluoropolymer feedstock flows from Shandong to Southeast Asian blending facilities. Supply concentrates in China, Germany, and the United States, with raw material dependencies spanning fluorspar mining, hydrogen fluoride processing, and hydrofluoroolefin polymerization catalysts. Single-source vulnerability in Chinese fluorspar concentrate exposes Western producers to export license volatility. Distribution runs through certified cylinder networks with Central Pollution Control Board handling requirements filtering access to qualified intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against natural refrigerant encroachment as ammonia and carbon dioxide systems capture regulatory-exempt share in industrial freezing. Incumbents must navigate this displacement threat while securing feedstock positions.
For Market Incumbents: Consolidate backward integration into hydrogen fluoride processing to offset Chinese fluorspar pricing power. Lock long-term offtake agreements with Shandong precursor producers before capacity allocation tightens. Prioritize EPA and EU F-Gas Regulation certification maintenance as compliance timelines compress formulation windows.
For New Entrants and Emerging Players: Central Pollution Control Board technician certification fast-tracks service-contract entry into India's cold storage warehouse segment. Target Maharashtra and Gujarat pharmaceutical logistics corridors where integrated facility management procurement is consolidating. Lead with reclamation equipment bundling to differentiate from established cylinder suppliers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional reclamation service providers lacking hydrofluoroolefin blend capabilities. Five-to-ten year viability hinges on feedstock integration depth rather than distribution reach alone. Watch German heat pump deployment rates as inflection indicator for reversible-cycle refrigerant demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Processing | Captive hydrogen fluoride supply insulates margins from Chinese export volatility. |
| Long-term Supply Agreement with Automotive OEMs | Hydrofluoroolefin-1234yf platform commitments lock volume through electrification transition. |
| Refrigerant Recovery Infrastructure Buildout | Central Pollution Control Board certification creates service-contract moats in India. |
| Joint Venture for Natural Refrigerant Systems | Ammonia and carbon dioxide expertise hedges against synthetic refrigerant phase-down acceleration. |
| Geographic Expansion into German Heat Pump Distribution | Building sector decarbonization incentives expand reversible-cycle refrigerant addressable market. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with refrigerant formulator R&D directors, equipment OEM procurement leads, and certified technician network operators; and secondary validation through customs trade data, EPA phasedown quota filings, and EU F-Gas Regulation registry disclosures. Bottom-up triangulation against top-down sectoral spending estimates anchored volume and value outputs.
Across the analysis window, the forecasting framework modeled demand by refrigerant chemistry tier, application thermal complexity, end-user facility scale, and regional regulatory cluster. CAGRs derived from segment-level build-ups incorporating equipment replacement cycles, phase-down compliance deadlines, and cold chain infrastructure investment flows. Hydrofluoroolefin adoption curves and natural refrigerant retrofit penetration served as primary demand swing variables.
Decision-makers should treat outputs as directional under sustained Kigali Amendment implementation and stable fluorspar trade flows; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EU F-Gas Regulation quota mechanics and Indian certification enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Mining Chemicals Market
Industrial Chemicals
Global Plating on Plastics Market
Industrial Chemicals
Global Ethiprole Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Alkyl Acrylate Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Inorganic Coagulants Market
Industrial Chemicals
Toluene Diisocyanates (TDI) Market