
 Metal Treatment Chemical Market | 2026-2036
Metal Treatment Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Treatment Chemical Market Analysis
Aerospace-grade surface preparation specifications is bifurcating the competitive landscape into qualified suppliers and commodity players. BASF leverages its captive phosphate chemistry portfolio to anchor European OEM supply chains. Henkel AG & Co. KGaA sustains dual qualification across Boeing and Airbus approved-product lists. Nihon Parkerizing dominates Japan's automotive pretreatment segment through integrated process licensing.
Metal treatment chemicals comprise formulated solutions that modify substrate surfaces through cleaning, conversion coating, or corrosion inhibition, typically operating at controlled pH ranges between 2.0 and 12.5 depending on process function. These formulations serve primarily to enhance coating adhesion, extend component lifecycles, and enable subsequent manufacturing steps in precision metalworking. Corrosion inhibitors command the largest revenue pool within product type segmentation due to recurring application cycles in marine and infrastructure end uses. Liquid formulations lead form-based demand because of dosing precision in continuous process lines, though powder concentrates are gaining traction in cost-sensitive metal fabrication shops seeking freight efficiency. Aerospace application requirements drive the highest specification premiums, while automotive manufacturing generates the greatest absolute volume throughput across global supply chains.
REACH restrictions on hexavalent chromium compounds and EPA effluent guidelines for metal finishing operations are reshaping formulation portfolios toward trivalent and non-chrome alternatives. ECHA substance authorization processes and OSHA permissible exposure limits for nickel and cobalt salts add compliance layers that favor suppliers with in-house toxicology and regulatory affairs capabilities. Stakeholders must monitor evolving substance restriction timelines and pre-qualify alternative chemistries before existing formulations face sunset dates.
Market Dynamics
REACH authorization timelines for hexavalent chromium compounds are forcing automotive and aerospace pretreatment suppliers to reformulate entire product portfolios before sunset dates, compressing R&D cycles and reallocating capital toward trivalent and non-chrome chemistry platforms.
Growth Catalysts
- Phosphate-free pretreatment mandates:Germany's KBA and Japan's METI are accelerating OEM line conversions to zirconium-based thin-film technologies, creating specification pull across Tier-1 supplier networks.
- Marine corrosion protection cycles:Shipyards in South Korea and China's Yangtze River corridor are extending dry-docking maintenance frequencies, driving recurring inhibitor demand for hull and tank coating systems.
- Aerospace surface preparation standards:Boeing and Airbus approved-product list qualifications are concentrating procurement toward dual-qualified chemical suppliers with Nadcap accreditation.
Market Restraints
- Raw material concentration:Fluorozirconate and fluorotitanate precursor supply concentrates among Chinese specialty fluoride producers, exposing formulators to export license volatility.
- Effluent compliance costs:EPA metal finishing effluent guidelines and local wastewater discharge permits in the US are raising operating expenditure for captive surface treatment operations.
- Performance gap in high-salt environments:Trivalent chromium alternatives still exhibit adhesion failure rates above hexavalent baselines in ASTM B117 salt spray testing above 2,000 hours.
Strategic Opportunities
- Indian automotive component clusters:Tamil Nadu and Gujarat precision metalworking corridors are tightening surface finishing specifications without established local formulation capacity, creating import substitution windows.
- EU Green Deal chemistry incentives:CSRD-aligned sustainability reporting is rewarding suppliers with verified lifecycle assessments and bio-based corrosion inhibitor platforms.
- Powder concentrate distribution:Freight-cost-sensitive metal fabrication shops in Brazil and Mexico are shifting from liquid bulk to powder dosing systems with on-site reconstitution.
Industry Challenges
- Formulation toxicology expertise scarcity:ECHA substance authorization processes require dedicated regulatory affairs capabilities that mid-size suppliers struggle to staff.
- Dual qualification timeline compression:Boeing and Airbus concurrent approval cycles demand 18-24 month validation programs that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Treatment Chemical Market |
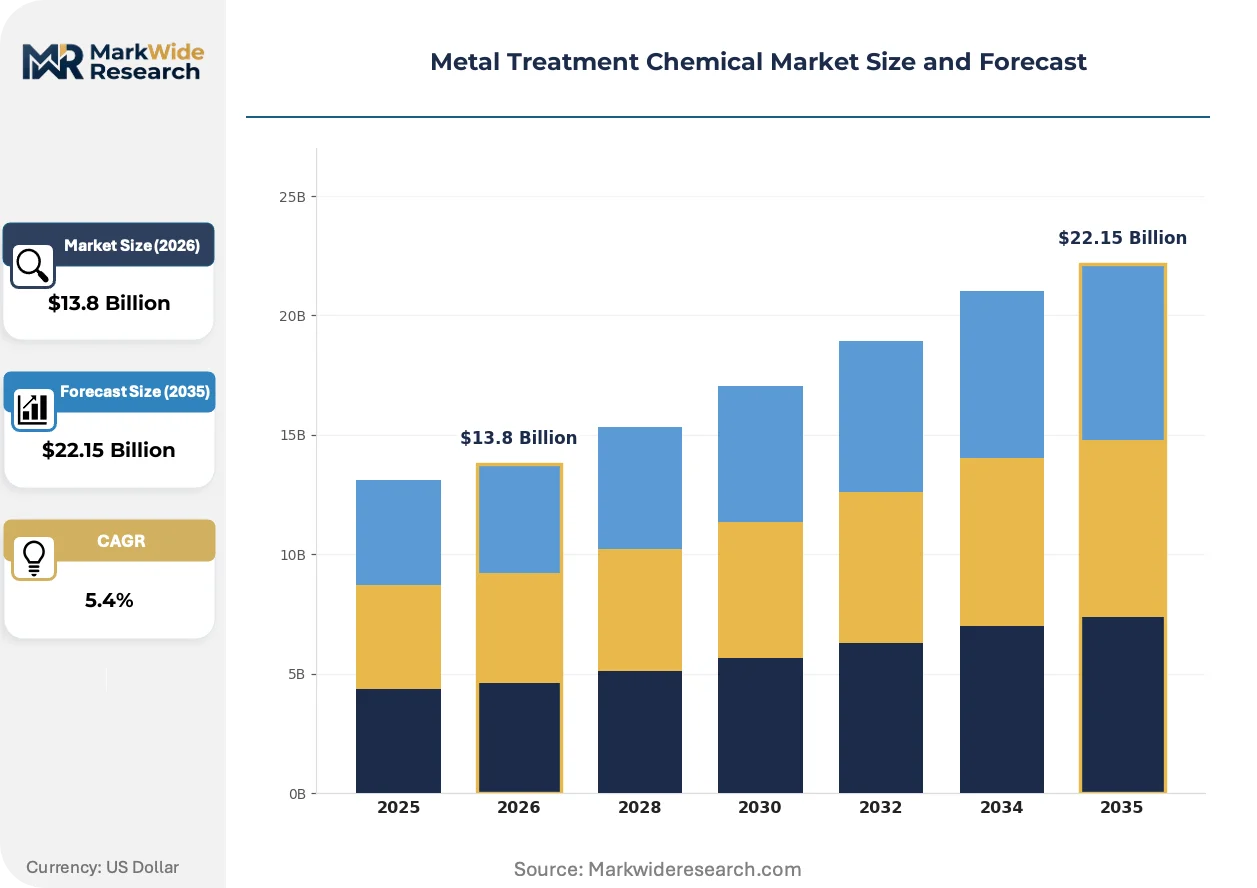
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
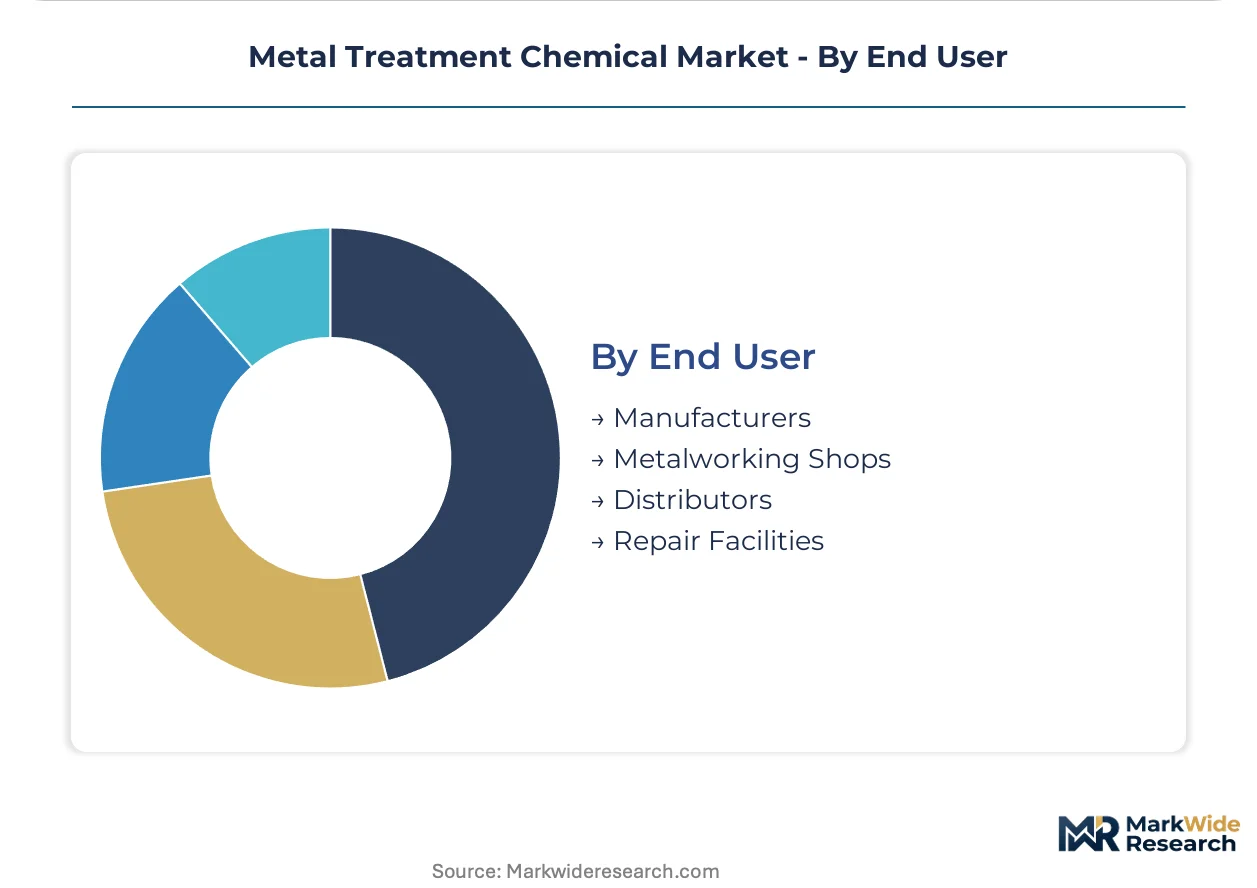
| Segmentation | Product Type: Alkaline Cleaners, Acidic Cleaners, Corrosion Inhibitors, Rust Preventatives Application: Aerospace, Automotive Manufacturing, Metal Fabrication, Marine Form: Liquid, Powder, Concentrate, Emulsion End User: Manufacturers, Metalworking Shops, Distributors, Repair Facilities |
| Companies Covered | BASF, Henkel AG & Co. KGaA, Chemetall GmbH, PPG Industries, Nippon Paint Holdings, Nihon Parkerizing, Dow, Element Solutions Inc, MKS Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Treatment Chemical Market Emerging Trajectories
Zirconium-based thin-film conversion coatings are displacing traditional iron and zinc phosphates across automotive pretreatment lines, enabled by tighter pH control systems and real-time bath monitoring. This chemistry shift is rewriting supplier qualification criteria and equipment interoperability standards.
Silane-based hybrid sol-gel pretreatments are decomposing the barrier between cleaning and conversion coating process steps. Automotive OEMs in Germany and Japan are adopting these at pilot scale for aluminum-intensive vehicle architectures. The technology is decomposing capital expenditure structures by eliminating separate degreasing and phosphating tanks, compressing line footprints by 30-40 percent in greenfield installations.
REACH sunset date acceleration for chromium trioxide and chromic acid is forcing aerospace approved-product list revisions. MRO providers and OEM finishing operations are pre-qualifying trivalent and cerium-based alternatives ahead of 2024-2027 authorization expiries. European surface treatment houses bear the highest compliance burden, with ECHA downstream user obligations extending to coating applicators and maintenance facilities.
Specification-driven procurement consolidation is concentrating chemical supply contracts among suppliers with multi-site technical service capabilities. Tier-1 automotive metal stampers in the US Midwest and Mexico are unbundling chemical supply from process equipment, favoring standalone formulation vendors over integrated equipment-chemistry packages. This pattern is most pronounced in high-volume press shops serving Detroit-based OEMs, where chemical cost-per-vehicle transparency has become a negotiation priority.
Metal Treatment Chemical Market Segmentation
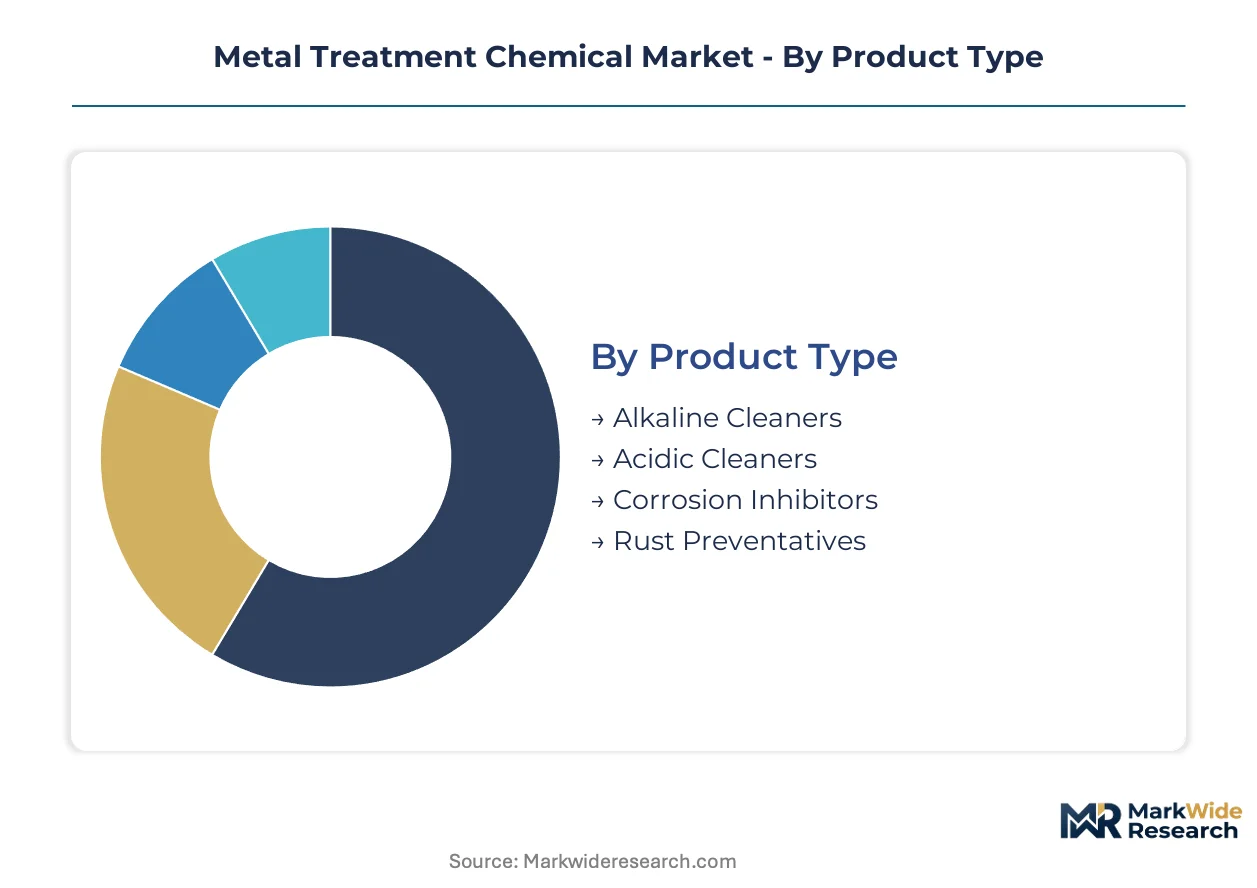
Metal treatment chemical procurement follows specification tiers that separate aerospace-qualified formulations from commodity-grade alternatives. End-users select product categories based on coating adhesion requirements, environmental compliance burdens, and process line automation levels.
Product Type:
REACH authorization timelines for hexavalent chromium compounds force suppliers to maintain parallel formulation portfolios across regulatory jurisdictions.
- Corrosion Inhibitors:These formulations create passive surface layers through chromate, phosphate, or organic inhibitor chemistries. Marine infrastructure operators in South Korea and China's Yangtze River corridor drive recurring demand for hull and tank protection systems with extended dry-docking cycles.
- Rust Preventatives:Oil-based and solvent-deposited films provide temporary protection during inter-process storage and shipment. Automotive OEMs in Germany specify thin-film alternatives that eliminate downstream cleaning steps prior to assembly coating.
- Alkaline Cleaners:Caustic and silicated formulations remove drawing compounds and stamping lubricants from ferrous substrates.
- Acidic Cleaners:Mineral acid and organic acid blends descale and pickle hot-rolled steel prior to conversion coating.
Corrosion inhibitors handle the majority of throughput; rust preventatives are the fastest mover on share as phosphate-free pretreatment lines multiply.
Application:
Specification premiums vary by a factor of three between aerospace surface preparation and general metal fabrication.
- Aerospace:Boeing and Airbus approved-product list qualifications mandate Nadcap-accredited chemical suppliers with 18-24 month validation cycles. Trivalent chromium and cerium-based alternatives are pre-qualifying ahead of ECHA sunset dates for hexavalent compounds.
- Automotive Manufacturing:Pretreatment lines in Germany and Japan are converting to zirconium-based thin-film technologies under KBA and METI mandates. Silane-based hybrid sol-gel systems are compressing line footprints by eliminating separate degreasing and phosphating tanks.
- Marine:Shipyards extend coating maintenance frequencies, driving demand for high-performance inhibitor systems in ballast tanks and cargo holds.
- Metal Fabrication:Job shops prioritize cost-per-part over specification premiums, favoring powder concentrates for freight efficiency.
Automotive manufacturing generates the greatest absolute volume; aerospace commands the steepest specification premiums and supplier concentration.
Form:
Liquid formulations dominate continuous process lines where precise dosing control reduces chemistry waste and rework rates.
- Liquid:Pump-and-meter delivery systems enable real-time bath monitoring and automatic replenishment in high-volume automotive pretreatment operations. Dosing precision justifies higher freight costs against powder alternatives.
- Powder:Freight-cost-sensitive metal fabrication shops in Brazil and Mexico are shifting from liquid bulk to on-site reconstitution systems. Concentrate ratios of 10:1 to 20:1 reduce transportation expenditure and storage footprint.
- Concentrate:Semi-bulk containers serve mid-volume operations with intermittent production schedules.
- Emulsion:Water-extendable systems bridge solvent performance with aqueous discharge compliance.
Liquid holds the dominant share in value terms; powder is expanding most quickly in cost-sensitive regional markets.
End User:
Procurement unbundling is separating chemical supply from process equipment in Tier-1 automotive networks.
- Manufacturers:OEM captive surface treatment operations specify dual-qualified suppliers with multi-site technical service capabilities. Chemical cost-per-vehicle transparency has become a negotiation priority for Detroit-based procurement teams.
- Metalworking Shops:Independent stampers and precision machinists in Tamil Nadu and Gujarat corridors are tightening surface finishing specifications without established local formulation capacity.
- Distributors:Regional chemical distributors consolidate small-lot demand from fragmented fabrication customers.
- Repair Facilities:MRO providers pre-qualify trivalent alternatives ahead of aerospace approved-product list revisions.
Manufacturers absorb the largest chemical volume; metalworking shops are gaining share fastest as precision component clusters formalize surface specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in formulated metal treatment chemicals tilt toward net imports in precision manufacturing economies while fluorozirconate precursor supply concentrates among Chinese specialty fluoride producers. Germany and Japan maintain formulation surpluses in automotive pretreatment. The United States runs deficits in aerospace-qualified conversion coatings.
Germany
KBA mandates are accelerating phosphate-free pretreatment line conversions across Volkswagen and BMW supplier networks. REACH authorization timelines for hexavalent chromium compounds compress R&D cycles toward trivalent alternatives. Bavarian automotive clusters around Munich and Ingolstadt are deploying zirconium-based thin-film technologies at scale.
China
Yangtze River corridor shipyards are extending dry-docking maintenance frequencies, driving recurring inhibitor demand for hull protection systems. MEE effluent guidelines are tightening wastewater discharge parameters for metal finishing operations. Shanghai and Jiangsu precision metalworking zones are importing higher-specification conversion coating formulations.
United States
EPA metal finishing effluent guidelines are raising operating expenditure for captive surface treatment operations in Detroit-based automotive networks. OSHA permissible exposure limits for nickel and cobalt salts add compliance layers to aerospace finishing houses. Midwest Tier-1 stampers are unbundling chemical supply from process equipment packages.
Japan
METI environmental standards are pushing automotive OEMs toward zirconium-based thin-film pretreatment chemistries. JIS certification requirements maintain qualification barriers for imported formulations. Nagoya and Toyota City automotive corridors are converting iron phosphate lines under domestic regulatory pressure.
India
Tamil Nadu and Gujarat precision metalworking clusters are tightening surface finishing specifications without established local formulation capacity. BIS standards for automotive coatings are formalizing pretreatment requirements for export component suppliers. Chennai and Ahmedabad automotive component hubs are creating import substitution windows for qualified chemical vendors.
Metal Treatment Chemical Market Vendor Landscape
Listed leaders compete with private specialists across qualification-intensive aerospace and automotive pretreatment segments. The vendor base concentrates around dual-qualified suppliers with Nadcap accreditation and multi-site technical service capabilities. Three archetypes dominate: integrated chemical conglomerates with captive phosphate portfolios, standalone surface treatment specialists with equipment-chemistry bundles, and regional formulators serving cost-sensitive fabrication shops. Competitive moves center on pre-qualification of trivalent chromium alternatives ahead of ECHA sunset dates and geographic expansion into Indian automotive component clusters lacking local formulation capacity.
Within the integrated chemical tier, BASF and Dow occupy positions anchored by captive raw material access and broad formulation portfolios. Henkel AG & Co. KGaA exemplifies the standalone specialist archetype with dual Boeing and Airbus qualification status. Nihon Parkerizing represents the regional dominance model through integrated process licensing in Japan's automotive pretreatment segment.
| Leading Market Players |
|---|
| BASF |
| Henkel AG & Co. KGaA |
| Chemetall GmbH |
| PPG Industries |
| Nippon Paint Holdings |
| Nihon Parkerizing |
| Dow |
| Element Solutions Inc |
| MKS Instruments |
| Others |
Supply Flow & Price Mechanics
REACH authorization timelines for hexavalent chromium compounds gate both supplier qualification and price differentiation simultaneously, concentrating procurement power among dual-qualified vendors with ECHA toxicology capabilities while compressing margins for commodity formulators lacking regulatory bandwidth.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation stems from Nadcap certification grade and volume scale, with aerospace-qualified formulations commanding multiples over general fabrication grades. Cost compression in the standard tier is intensifying because Tier-1 automotive stampers are unbundling chemical supply from equipment packages. Metal fabrication shops in Brazil and Mexico exhibit the highest price sensitivity, while Boeing and Airbus dual-qualified suppliers face the least.
Supply Chain Analysis
Inventory cycles for fluorozirconate precursors stretch 8-12 weeks, exposing formulators to Chinese export license volatility. Supply concentrates among Chinese specialty fluoride producers for fluorozirconate and fluorotitanate inputs, with German and Japanese formulation houses drawing from these precursors. Single-source vulnerability in precursor supply creates systemic risk for trivalent conversion coating production. Distribution runs through regional chemical distributors consolidating fragmented fabrication demand alongside direct OEM supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates sticky supplier relationships; ECHA substance authorization processes embed switching costs that protect qualified incumbents from price-based displacement.
For Market Incumbents: Consolidate technical service capabilities across multi-site automotive networks before specification unbundling accelerates. Backward integration into fluorozirconate precursor supply reduces exposure to Chinese export volatility. Invest in silane-based hybrid sol-gel R&D to capture phosphate-free line conversion demand from Germany's KBA-mandated OEMs.
For New Entrants and Emerging Players: Anchor in Tamil Nadu and Gujarat precision metalworking clusters where BIS standards are tightening without established local formulation capacity. Target powder concentrate distribution to freight-cost-sensitive metal fabrication shops in Brazil and Mexico. Lead with on-site reconstitution systems and technical training partnerships to bypass entrenched liquid-formulation incumbents.
For Investors and Strategic Acquirers: REACH sunset date acceleration for chromium trioxide reshapes the acquisition landscape toward trivalent-qualified specialists with pre-validated aerospace product lists. Five-to-ten year viability favors suppliers with captive regulatory affairs capabilities and multi-site technical service footprints. Monitor Boeing and Airbus approved-product list revision timing as the critical inflection signal for portfolio revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive fluorozirconate production insulates formulators from Chinese export license volatility. |
| Nadcap Accreditation Investment | Dual aerospace qualification concentrates procurement toward validated chemical suppliers. |
| Phosphate-Free Formulation R&D | Zirconium-based thin-film platforms capture KBA and METI-mandated OEM line conversions. |
| Indian Market Technical Service Expansion | Multi-site service capabilities secure specification pull from Tamil Nadu and Gujarat clusters. |
| Powder Concentrate Distribution Buildout | Freight-efficient dosing systems penetrate cost-sensitive Brazilian and Mexican fabrication shops. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with chemical plant managers, automotive procurement leads at Tier-1 stampers, distribution channel partners, and technical R&D directors; and secondary validation through customs/trade data, Cefic sector reports, SEC 10-K filings, and ECHA substance authorization databases. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, form, and end-user segments.
Across the projection horizon, the analytical framework modeled grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived from segment-level demand elasticity analysis and input cost trajectory assumptions. Forecast inputs incorporated REACH authorization timeline acceleration, phosphate-free pretreatment line conversion rates, and aerospace approved-product list revision cycles.
Material uncertainties — regulatory sunset date delays, precursor supply disruptions, and alternative chemistry performance gaps — sit outside the modeled envelope. Forecasts reflect documented assumptions about substitution timelines and specification adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Lime Market
Industrial Chemicals
Cooling Tower Chemicals Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Dynamite Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
North America Quicklime Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Explosion Venting Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
Global Desalting and Buffer Exchange Market