
 Asia Neopentyl Glycol (NPG) Market | 2026-2036
Asia Neopentyl Glycol (NPG) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Neopentyl Glycol (NPG) Market Outlook
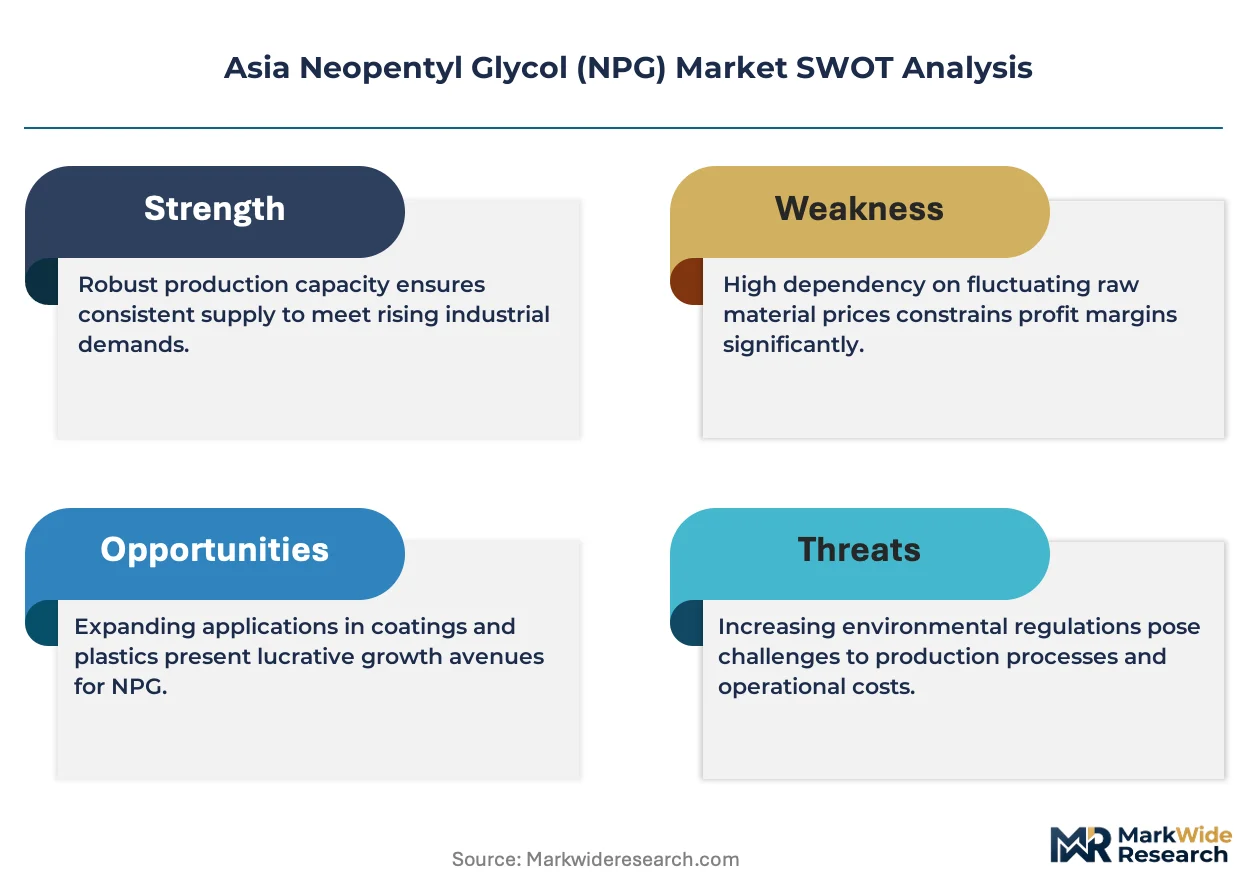
Buyer concentration among Asia's top powder coating formulators is hardening as regional procurement shifts toward long-term supply contracts with integrated resin producers. BASF SE leverages its Ludwigshafen-derived process technology to sustain premium-grade NPG output across Asian distribution hubs. Mitsubishi Gas Chemical Company anchors supply security for Japanese automotive coating tiers through captive hydrogenation capacity at its Niigata complex. Wanhua Chemical Group dominates domestic Chinese volumes by controlling upstream isobutyraldehyde supply at its Yantai operations.
Neopentyl glycol is a dihydric alcohol with the molecular formula C5H12O2, manufactured industrially through aldol condensation of isobutyraldehyde followed by hydrogenation, yielding a white crystalline solid with a melting point near 127 degrees Celsius and exceptional hydrolytic stability. Its primary commercial purpose centers on synthesizing saturated polyester resins for powder coatings and unsaturated polyester resins for gel coats, where the gem-dimethyl structure imparts superior weathering resistance and thermal stability compared to conventional glycols. The resin product type occupies the dominant margin pool given its irreplaceable role in automotive and architectural powder coatings, while the solvent form segment leads volume growth as Asian manufacturers shift toward waterborne delivery systems to meet tightening volatile organic compound limits. End use industry dynamics favor coatings over adhesives and plastics, since construction and automotive OEM specifications increasingly mandate NPG-based polyester backbone chemistries for exterior durability certification.
China's MEE enforces national volatile organic compound emission standards that directly constrain solvent-based coating production and redirect formulation investment toward NPG-compatible powder and waterborne systems. Japan's METI chemical management framework and South Korea's MFDS industrial chemical notification requirements create layered compliance barriers for imported NPG and derivative resin formulations. India's BIS quality certification mandates for construction-grade coatings are extending upstream to raw material purity specifications, affecting import sourcing patterns across the subcontinent. Stakeholders must monitor divergence between China's GB standards and emerging ASEAN harmonization proposals, as regulatory fragmentation threatens to segment supply chain configurations and testing cost structures across the region.
Market Dynamics
China's dual carbon goals are compressing formulation timelines across Asia's coating sector, forcing polyester resin producers to accelerate NPG-compatible waterborne and powder system development.
Growth Catalysts
- MEE volatile organic compound standards:China's emission limits are phasing out solvent-based coating production lines and redirecting capital toward NPG-based powder formulations.
- Automotive exterior durability specifications:Japanese and South Korean OEM certification requirements now mandate saturated polyester backbone chemistries for weathering resistance.
- Jiangsu-Zhejiang resin cluster expansion:Integrated polyester production hubs in eastern China are absorbing rising NPG volumes through captive hydrogenation and aldol condensation capacity.
Market Restraints
- Isobutyraldehyde supply concentration:Upstream feedstock control by integrated Chinese petrochemical complexes creates pricing leverage over non-captive NPG producers.
- Cross-border chemical notification friction:South Korea's MFDS industrial chemical requirements and Japan's METI frameworks impose layered compliance costs on imported NPG shipments.
- Alternative glycol substitution in cost-sensitive segments:Trimethylolpropane and hexanediol compete for lower-specification coating applications where weathering performance is secondary.
Strategic Opportunities
- India BIS quality certification extension:Upstream raw material purity mandates for construction-grade coatings are opening specification-driven sourcing windows for high-grade NPG.
- ASEAN harmonization divergence:Regulatory fragmentation between China's GB standards and emerging Southeast Asian proposals creates first-mover advantages for dual-certified suppliers.
- Waterborne delivery system convergence:The intersection of high-solid formulations and powder coating technologies is expanding addressable market scope beyond traditional solvent replacement.
Industry Challenges
- Hydrogenation catalyst expertise scarcity:Specialized process engineering talent for aldol-to-NPG conversion is concentrated among legacy Japanese and German technology licensors.
- Dual certification timeline compression:Simultaneous compliance with China's GB standards and Japan's JIS specifications extends product qualification cycles for cross-border suppliers.
- Legacy solvent-based coating asset stranding:Southeast Asian formulators face write-down pressure on conventional production equipment amid accelerated environmental standard adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Neopentyl Glycol (NPG) Market |
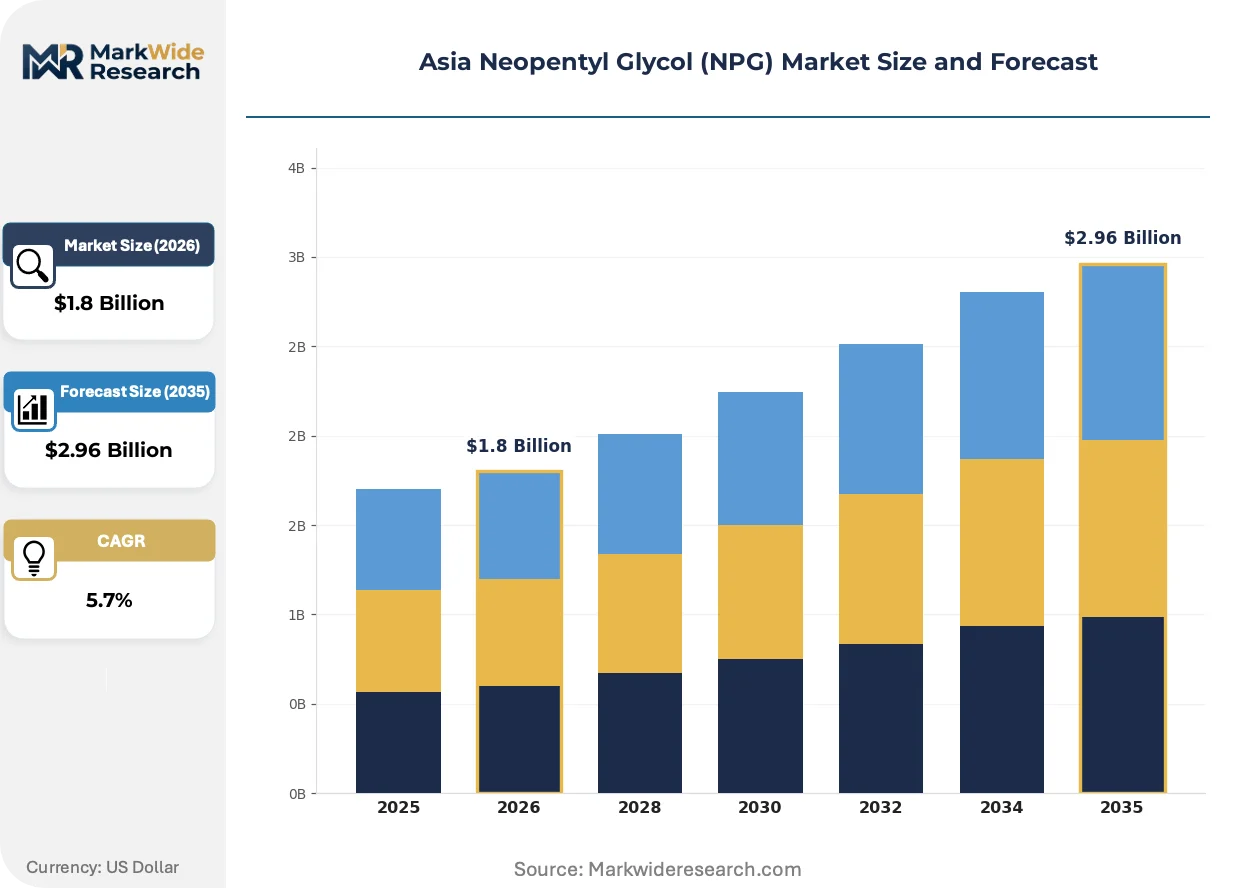
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Intermediate, Resin, Plasticizer End Use Industry: Coatings, Adhesives, Plastics, Construction Sales Channel: Direct Sales, Distributors, Online Retail, Export Form: Liquid, Solid, Powder, Emulsion |
| Companies Covered | LG Chem, Eastman Chemical Company, BASF SE, Shandong Dongchen Ind. Group Corp., OXEA GmbH, Mitsubishi Gas Chemical Company, Zhejiang NHU Co., Ltd., Wanhua Chemical Group, Perstorp Holding AB, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Neopentyl Glycol (NPG) Market Strategic Shifts
Formulation chemistry advances and regulatory stringency are converging to elevate NPG from commodity glycol to specification-critical resin backbone material across Asia's industrial coating sector.
Continuous hydrogenation process intensification is unifying aldol condensation and catalytic reduction stages into single-reactor configurations. Japanese engineering contractors are deploying these systems at Niigata and Yokkaichi complexes to compress energy intensity and yield higher-purity crystalline output. The technology is unifying premium-grade and standard-grade production lines, collapsing historical quality-tier segmentation.
China's MEE national volatile organic compound emission standards are tightening enforcement scope from facility-level to product-level compliance. Coating manufacturers in Shandong and Guangdong provinces are retrofitting production lines ahead of 2025 inspection cycles. Powder coating formulators are responding by locking multi-year NPG supply contracts with integrated resin producers.
Specification-driven procurement is consolidating buyer power among Asia's top ten powder coating formulators. Long-term offtake agreements with hydrogenation-integrated suppliers are displacing spot-market purchasing in automotive and architectural segments. Japanese automotive coating tiers exhibit the most pronounced contract concentration, with tier-one suppliers demanding certified chain-of-custody documentation.
Asia Neopentyl Glycol (NPG) Market Segmentation
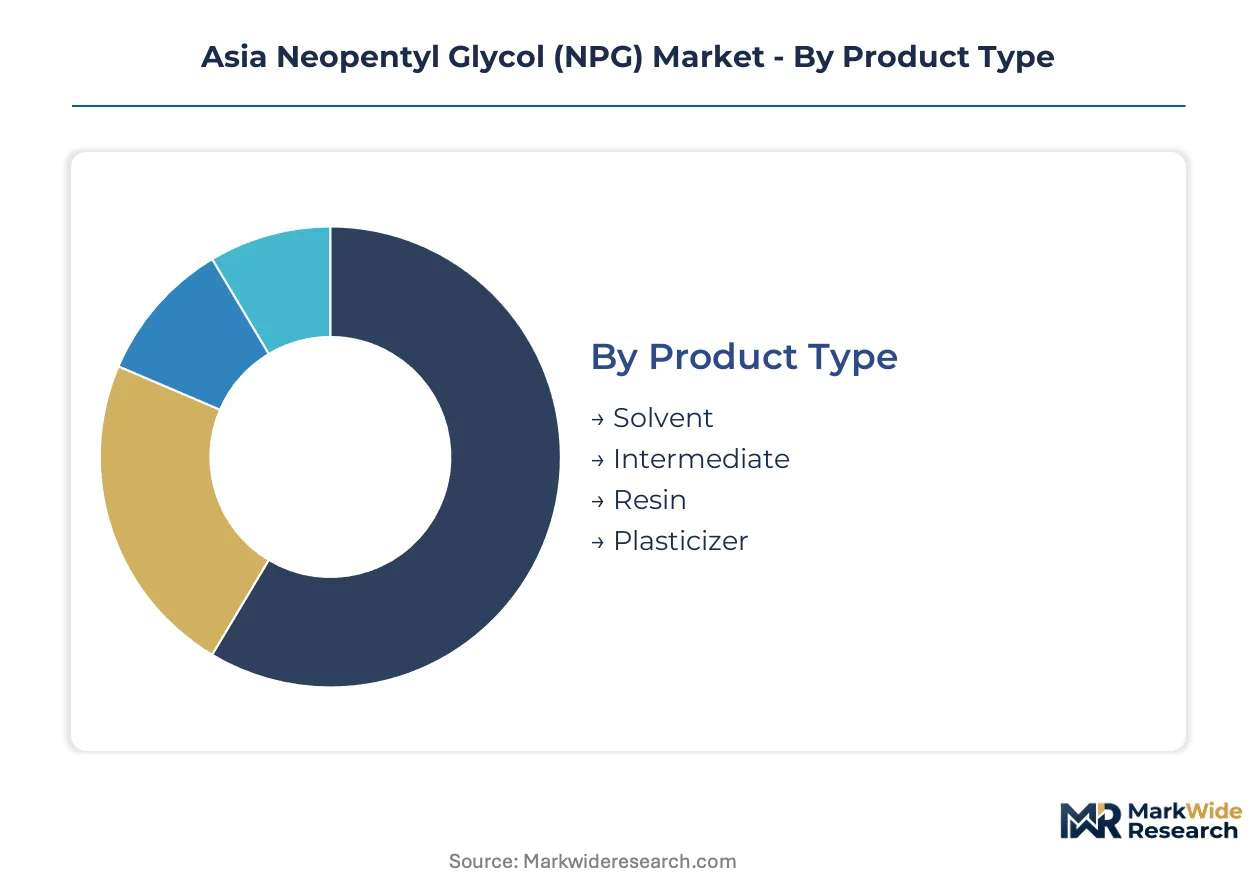
Segmentation in Asia's NPG market reflects divergent certification burdens across product grades and end-use applications. Powder coating formulators in Japan and automotive tiers in South Korea impose distinct purity specifications that reshape procurement patterns across each segment category.
Product Type:
Resin-grade NPG demands Japan's JIS K 6751 certification and China's GB/T 23957 compliance for automotive coating applications, while solvent and intermediate grades navigate lighter notification requirements under South Korea's MFDS framework.
- Resin:Saturated polyester backbone material with gem-dimethyl structure delivering hydrolytic stability above 127 degrees Celsius melting point. Demand concentrates in Jiangsu-Zhejiang clusters where integrated hydrogenation capacity supplies powder coating formulators facing MEE volatile organic compound enforcement.
- Solvent:Waterborne delivery system component with high-solid formulation compatibility displacing conventional glycol ethers. Japanese architectural coating manufacturers in Osaka and Nagoya prefectures are absorbing volumes as METI chemical safety frameworks tighten solvent substitution timelines.
- Intermediate:Aldol condensation precursor for specialty ester synthesis with moderate purity requirements.
- Plasticizer:Niche PVC compatibility agent with limited penetration in Asian polymer compounding.
Resin sits at the top of the volume ranking, with Solvent climbing the fastest.
End Use Industry:
Cost tier differentiation separates specification-critical coating applications from commodity-grade construction uses, with automotive exterior durability mandates commanding premium pricing over general industrial maintenance coatings.
- Coatings:Powder and waterborne system backbone chemistry where Japanese OEM certification requires certified chain-of-custody documentation. Jiangsu province polyester resin clusters consume captive NPG volumes through integrated aldol-hydrogenation configurations.
- Construction:India's BIS IS 5410 quality certification for architectural-grade coatings extends upstream to raw material purity specifications, redirecting import sourcing toward high-crystallinity grades.
- Adhesives:Saturated polyester hot-melt formulations with moderate weathering requirements.
- Plastics:Limited unsaturated polyester gel coat penetration in Asian fiberglass reinforced plastic molding.
Coatings maintains the dominant revenue position, though Construction is expanding most quickly under India's certification extension.
Sales Channel:
Supply concentration among integrated resin producers favors direct procurement relationships, while distributor networks retain relevance for smaller formulators lacking volume scale for captive hydrogenation economics.
- Direct Sales:Long-term offtake agreements between hydrogenation-integrated suppliers and top-ten powder coating formulators. Japanese automotive coating tiers demand certified documentation locking multi-year supply security.
- Distributors:Regional chemical distribution networks serving mid-tier construction coating manufacturers in India's western and southern states.
- Export:Cross-border shipment channels navigating South Korea's MFDS industrial chemical notification and Japan's METI layered compliance barriers.
- Online Retail:Limited laboratory-grade and small-batch specialty solvent transactions.
Direct Sales commands the largest transaction value, with Export channels gaining share fastest under ASEAN regulatory divergence.
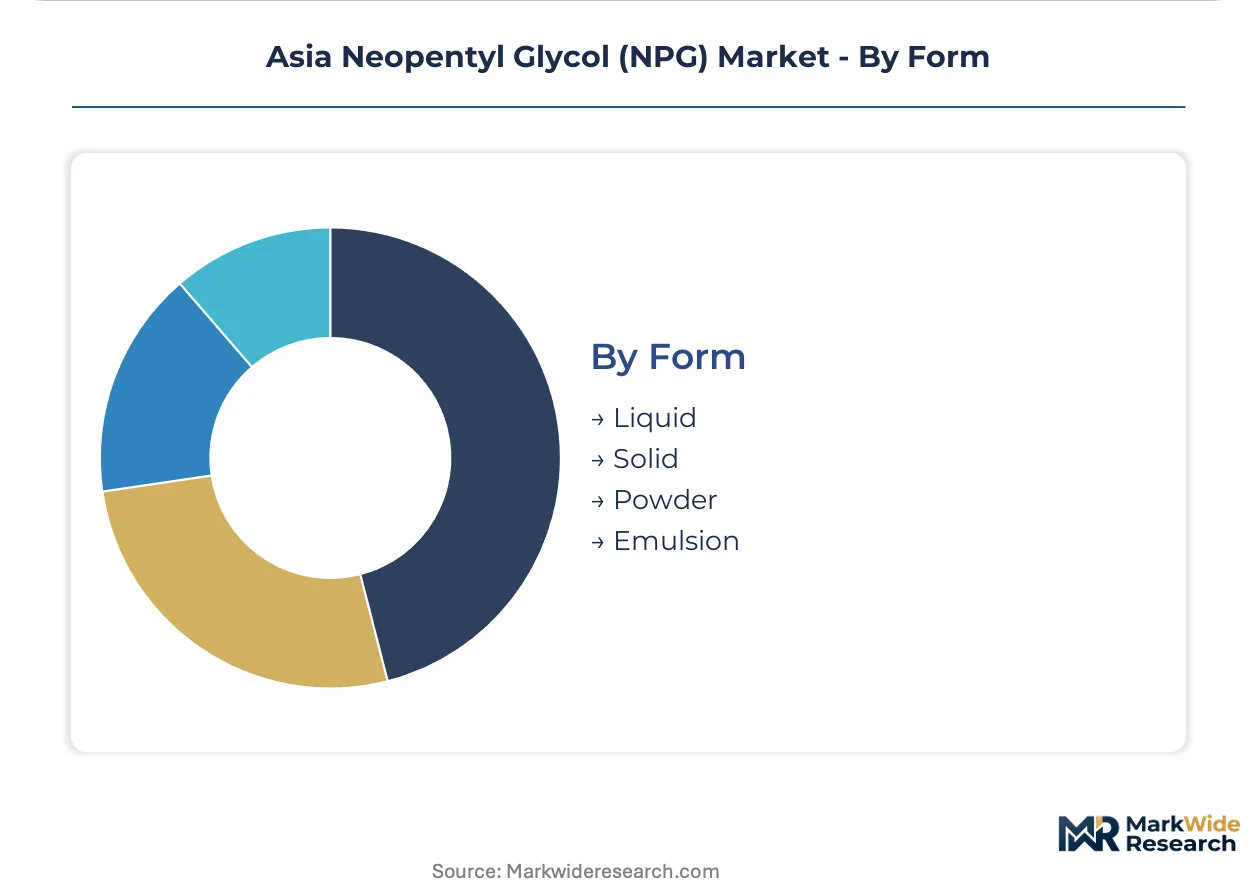
Form:
Maturity gradients separate established solid crystalline handling infrastructure from emerging emulsion delivery systems requiring modified storage and transport protocols across Asian distribution networks.
- Solid:White crystalline material with established bulk handling systems across eastern Chinese polyester resin clusters. Continuous hydrogenation process intensification at Japanese Niigata and Yokkaichi complexes yields higher-purity crystalline output collapsing historical quality-tier segmentation.
- Liquid:Molten or solvent-diluted configurations for waterborne formulation compatibility. Shandong and Guangdong province coating manufacturers are retrofitting production lines to accommodate liquid NPG handling ahead of MEE inspection cycles.
- Powder:Micronized solid form for specialized dispersion requirements.
- Emulsion:Water-based delivery system emerging for high-solid coating formulations.
Solid remains the dominant form by tonnage, with Liquid showing the steepest expansion trajectory under waterborne system convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NPG consumption dwarfs Japan's by an order of magnitude, yet Japanese specifications command premium positioning across automotive coating tiers. India's certification-driven import redirection and South Korea's notification barriers add complexity to regional supply configurations.
China
Jiangsu and Zhejiang province polyester resin clusters absorb the majority of regional NPG volumes through integrated aldol-hydrogenation configurations. MEE national volatile organic compound emission standards are phasing out solvent-based coating production lines ahead of 2025 inspection cycles. Wanhua Chemical Group's Yantai operations control upstream isobutyraldehyde supply, creating captive economics that dominate domestic pricing.
Japan
METI chemical management frameworks impose layered compliance barriers on imported NPG and derivative resin formulations. Automotive exterior durability specifications now mandate saturated polyester backbone chemistries certified to JIS K 6751 standards. Mitsubishi Gas Chemical Company anchors supply security through captive hydrogenation capacity at its Niigata complex, serving tier-one coating suppliers.
South Korea
MFDS industrial chemical notification requirements create friction for cross-border NPG shipments from Chinese integrated producers. Automotive OEM certification requirements mirror Japanese weathering resistance standards, driving specification-grade procurement. Busan-Ulsan petrochemical corridors host downstream polyester resin formulators locked into multi-year supply contracts.
India
BIS quality certification mandates for construction-grade coatings are extending upstream to raw material purity specifications under IS 5410 frameworks. Western and southern state coating manufacturers rely on regional distributor networks lacking volume scale for direct procurement. Maharashtra and Gujarat industrial corridors show fastest absorption of high-crystallinity import grades.
Thailand
Emerging ASEAN harmonization proposals diverge from China's GB standards, threatening to segment supply chain configurations across Southeast Asian markets. Bangkok-centered construction coating formulators face asset stranding pressure on legacy solvent-based equipment. Eastern seaboard industrial zones attract speculative NPG storage capacity ahead of anticipated regulatory convergence.
Asia Neopentyl Glycol (NPG) Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Asia's NPG supply base, creating a tiered structure where captive feedstock control separates price-setters from price-takers. German and Japanese technology licensors concentrate specialized hydrogenation catalyst expertise, while Chinese state-affiliated petrochemical groups leverage backward integration into isobutyraldehyde. Strategic moves center on long-term offtake contracting and dual-certification capacity expansion to capture cross-border automotive coating demand.
Among diversified chemical conglomerates, BASF SE and LG Chem exemplify multinational positioning across premium-grade resin specifications and waterborne formulation compatibility. Mitsubishi Gas Chemical Company occupies a specialized tier serving Japanese automotive coating tiers through certified chain-of-custody documentation. Wanhua Chemical Group anchors the Chinese domestic vector with upstream control over isobutyraldehyde supply at its Yantai operations.
| Leading Market Players |
|---|
| LG Chem |
| Eastman Chemical Company |
| BASF SE |
| Shandong Dongchen Ind. Group Corp. |
| OXEA GmbH |
| Mitsubishi Gas Chemical Company |
| Zhejiang NHU Co., Ltd. |
| Wanhua Chemical Group |
| Perstorp Holding AB |
| Others |
Value Chain & Pricing Dynamics
Continuous hydrogenation process intensification at Japanese Niigata and Yokkaichi facilities collapses historical quality-tier segmentation while simultaneously compressing production economics and concentrating premium-grade supply among technology-licensed operators. This unified reactor configuration eliminates separate aldol condensation and catalytic reduction stages, reshaping cost structures for resin-grade output and reinforcing pricing leverage for integrated producers with captive hydrogenation expertise.
Pricing Analysis
Capacity additions in eastern China are reshaping price floors for standard-grade NPG as Jiangsu-Zhejiang polyester resin clusters absorb captive volumes through integrated aldol-hydrogenation configurations. Three-tier pricing structure across premium, standard, and economy levels separates JIS K 6751-certified automotive grades from construction-grade and intermediate specifications. Price differentiation hinges on certification tier and volume scale, with Japanese automotive coating tiers exhibiting lowest price sensitivity due to mandated chain-of-custody documentation. Cost compression in standard grades is intensifying because Wanhua Chemical Group's upstream isobutyraldehyde control at Yantai operations feeds aggressive domestic pricing.
Supply Chain Analysis
Direct-to-coating-manufacturer channels handle automotive tier demand through multi-year offtake agreements with certified documentation requirements. Supply concentrates in China, Japan, and South Korea, with Chinese integrated petrochemical complexes dominating volume and Japanese operators controlling premium-grade certification. Raw material dependencies center on isobutyraldehyde feedstock, specialized hydrogenation catalysts, and formaldehyde co-reactants. Single-source vulnerability runs through concentrated catalyst expertise among legacy German and Japanese technology licensors. Distribution runs through direct procurement relationships for top-ten powder coating formulators, with regional distributors serving mid-tier Indian construction coating manufacturers lacking volume scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia's NPG market functions as a stable compounder anchored by irreplaceable resin backbone specifications in automotive and architectural powder coatings. Regulatory enforcement of volatile organic compound limits across China's MEE framework and Japan's METI chemical management systems sustains formulation transition demand.
For Market Incumbents: Cement supply security through captive hydrogenation capacity expansion in eastern Chinese clusters and dual-certification investment covering both China's GB standards and Japan's JIS K 6751 specifications. Isobutyraldehyde supply concentration among Chinese state-affiliated petrochemical groups threatens margin compression for non-captive producers, making upstream control or long-term feedstock contracting essential defensive levers.
For New Entrants and Emerging Players: Continuous hydrogenation process licensing from Japanese engineering contractors offers technology-first wedge positioning against legacy batch producers. India's western and southern state construction coating markets present the most penetrable geography, with BIS IS 5410 quality certification extension redirecting import sourcing toward specification-grade suppliers lacking established distributor relationships.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale hydrogenation-integrated specialists because regulatory fragmentation between China's GB standards and emerging ASEAN harmonization proposals extends product qualification cycles that favor incumbent certification holders. Acquisition targets should display dual-certified capacity serving cross-border automotive coating demand. Watch MEE enforcement scope expansion from facility-level to product-level compliance as the inflection signal accelerating contract concentration among top-ten powder coating formulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isobutyraldehyde | Wanhua Chemical Group's Yantai operations demonstrate pricing leverage through upstream feedstock control. |
| Dual-Certification Capacity Expansion | Simultaneous GB and JIS K 6751 compliance captures cross-border automotive coating procurement. |
| Long-term Supply Agreement | Japanese tier-one coating suppliers demand multi-year offtake contracts with certified chain-of-custody documentation. |
| Continuous Hydrogenation Technology Licensing | Niigata and Yokkaichi process intensification collapses quality-tier segmentation and compresses energy intensity. |
| Green Manufacturing Transition | Waterborne delivery system convergence expands addressable market scope beyond traditional solvent replacement. |
Study Parameters
Multiple input streams — plant manager interviews at hydrogenation facilities, procurement lead discussions at downstream coating OEMs, and technical R&D director consultations — were reconciled against customs trade data, ACC regional reports, and SEC 10-K chemical segment disclosures. Bottom-up volume estimates from individual production facility capacities were triangulated against top-down consumption projections derived from polyester resin output statistics across Jiangsu-Zhejiang clusters.
Historical capacity utilization patterns were cross-referenced against expert panel assessments of MEE enforcement timelines and automotive OEM specification adoption curves. Segmentation dimensions modeled include grade tier (resin, solvent, intermediate), end-use industry (coatings, construction, adhesives), packaging format (solid crystalline, liquid, emulsion), and regional production hub concentration. CAGRs were derived through regression analysis of historical price-volume relationships adjusted for regulatory phase-in schedules.
The model holds under steady MEE enforcement progression and stable isobutyraldehyde feedstock availability; deviation in catalyst supply disruptions or ASEAN regulatory harmonization acceleration would shift trajectory assumptions. Forecasts reflect documented base conditions without contingency weighting. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Chemical Reactors Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Hydrofluoric Acid (HF) for Semiconductor Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
Global Electronic Grade Sulfuric Acid Market
Industrial Chemicals
Enzymatic Acrylamide-Reduction Systems Market
Industrial Chemicals
Vacuum Degreasers Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
Technical Enzymes Market