
 Anhydrous Hydrogen Fluoride Market | 2026-2036
Anhydrous Hydrogen Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Anhydrous Hydrogen Fluoride Market Intelligence
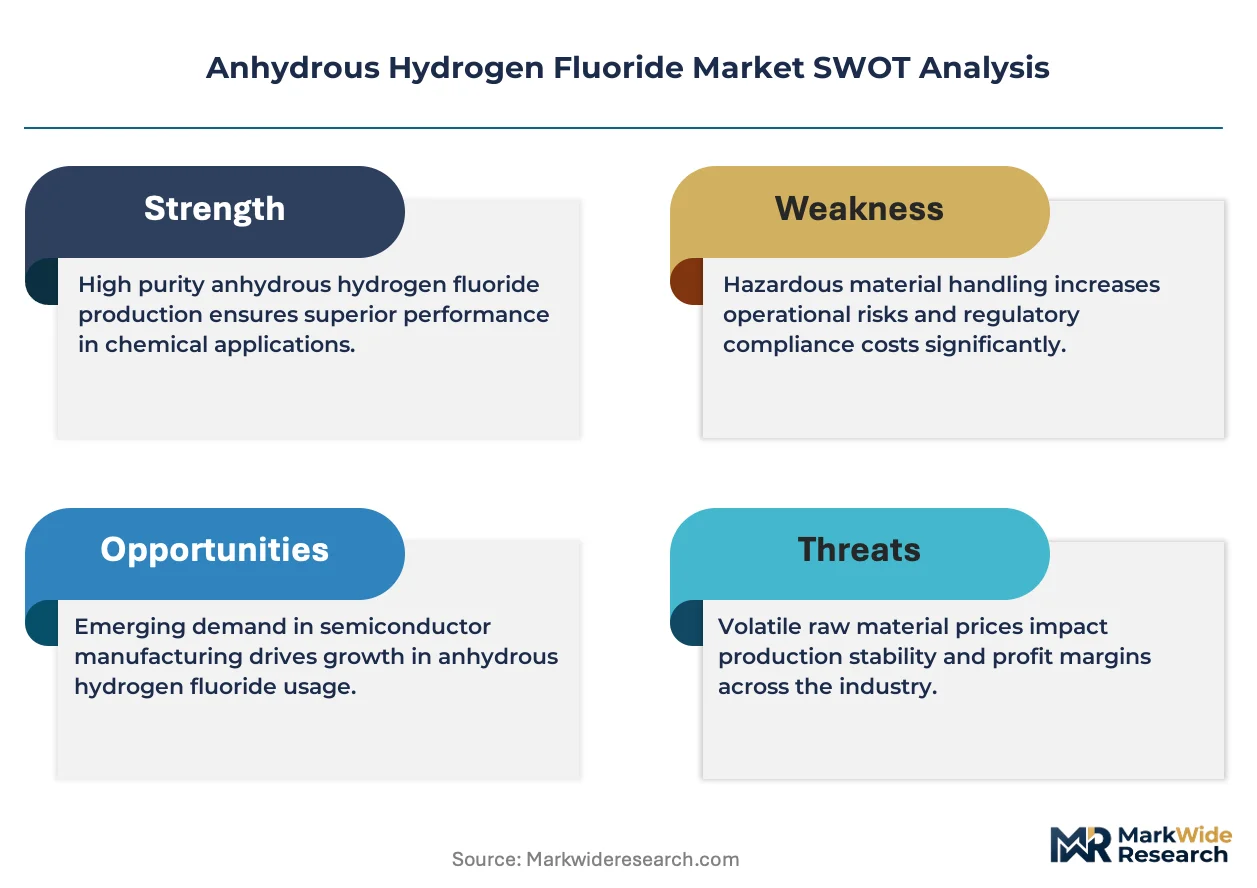
Aftermarket fluorochemical recycling and acid regeneration services is rewriting margin distribution across the value chain. Linde plc leverages its industrial gas infrastructure to control bulk distribution networks in North America. Honeywell International Inc. anchors its position through captive supply arrangements with downstream refrigerant producers. Navin Fluorine International Limited specializes in high-purity grades for Indian semiconductor foundries.
Anhydrous hydrogen fluoride is a colorless, corrosive liquid or gas with the chemical formula HF, typically containing less than 1% water content and manufactured through the reaction of fluorspar with sulfuric acid followed by purification; it serves as the foundational feedstock for fluorine-containing chemicals across industrial and electronic applications. Electronics grade material commands premium positioning due to sub-ppb purity requirements in semiconductor etching processes, while industrial grade sustains volume leadership through fluorochemical manufacturing and metal processing demand. Membrane separation technology is displacing conventional distillation in new capacity additions, particularly for specialty grade production where energy efficiency determines project economics.
EPA regulations under the Clean Air Act and OSHA permissible exposure limits shape facility siting and worker safety investments across US production sites. REACH registration requirements and the EU F-Gas Regulation restrict certain fluorinated gas applications while tightening supply chain traceability obligations for European market participants. China's MEE enforces emissions intensity benchmarks that filter marginal producers from the country's expanding fluorochemical base. Stakeholders must weigh capital allocation between purification technology upgrades and geographic diversification of supply origins.
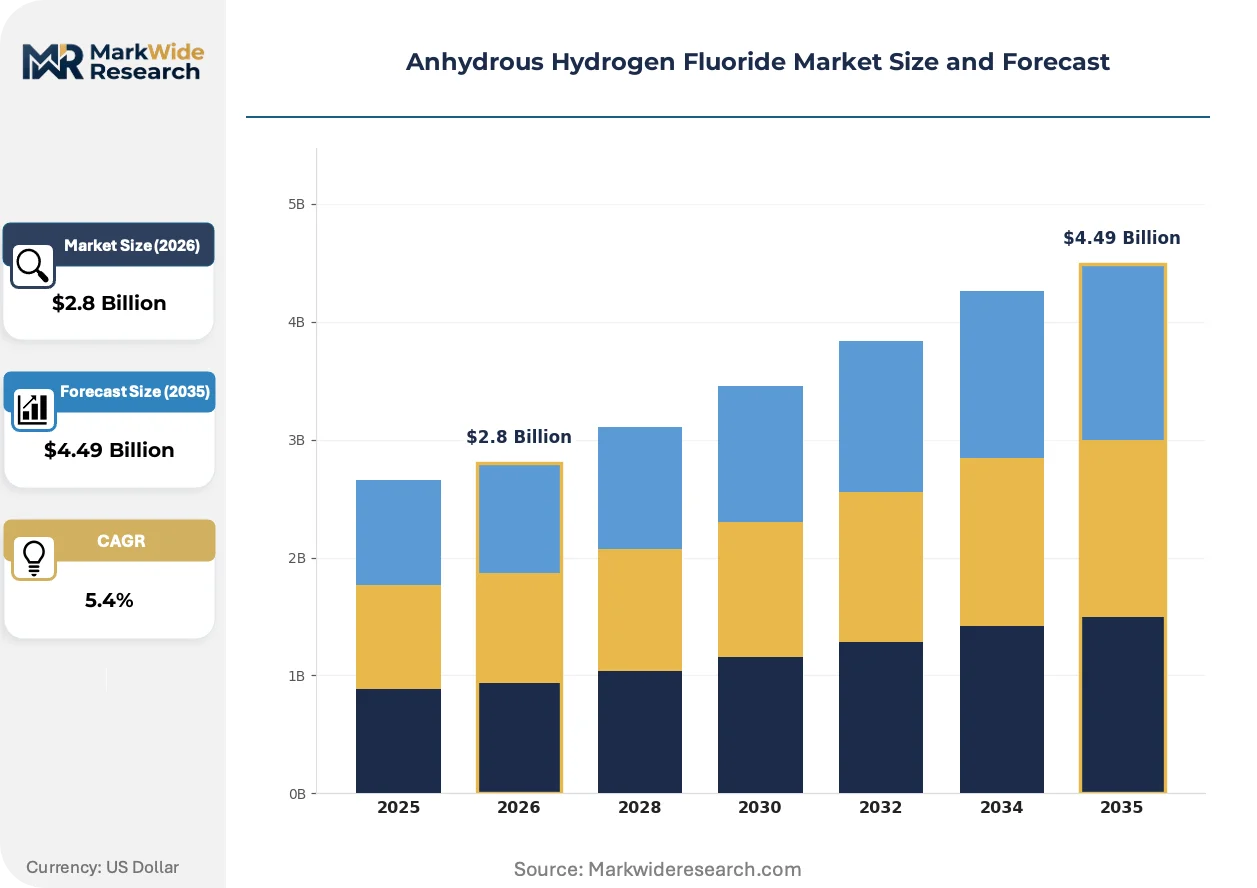
Market Dynamics
Membrane separation technology is migrating from pilot installations to commercial-scale deployment, compressing energy intensity benchmarks for electronics-grade production and forcing capital reallocation across incumbent purification asset bases.
Growth Catalysts
- Semiconductor foundry expansion:Sub-ppb purity requirements for advanced node etching processes are pulling specialty-grade volumes through dedicated supply contracts with captive fluorochemical producers.
- China's dual carbon goals:MEE emissions intensity benchmarks are filtering marginal acid-grade producers from the country's expanding fluorochemical base, consolidating output among integrated operators with membrane purification capabilities.
- Fluorspar-to-acid vertical integration:Captive mining and acid regeneration investments in East China's Zhejiang and Jiangsu clusters are securing feedstock cost positions for downstream refrigerant and pharmaceutical intermediate manufacturing.
Market Restraints
- Fluorspar supply concentration:Over sixty percent of acid-grade fluorspar originates from Chinese and Mexican mining operations, exposing processors to export quota volatility and freight cost spikes.
- EU F-Gas Regulation phase-down:Refrigerant demand destruction in European HVAC applications is compressing industrial-grade HF offtake volumes and forcing capacity idling at non-diversified producers.
- Caustic etching substitution:TMAH-based wet etching chemistries are displacing buffered oxide etch formulations in select MEMS fabrication steps, constraining electronics-grade growth in niche device categories.
Strategic Opportunities
- Indian semiconductor manufacturing:PLI scheme incentives for domestic foundry construction are creating import-substitution demand for electronics-grade material that local purification capacity cannot yet satisfy.
- Aftermarket acid regeneration:Spent fluoride stream recovery services are opening recurring revenue pools adjacent to commodity acid sales, with margin structures insulated from spot pricing volatility.
- Green hydrogen fluoride pathways:Fluorosilicic acid recovery from phosphate fertilizer waste streams offers an alternative feedstock route that bypasses fluorspar mining entirely for select industrial applications.
Industry Challenges
- High-purity certification timelines:Semiconductor customer qualification cycles for new electronics-grade suppliers extend eighteen to thirty-six months, locking out capital before revenue recognition.
- Corrosion-resistant alloy procurement:Monel and Hastelloy fabrication lead times for reactor vessels and distillation columns have stretched to fourteen months, delaying greenfield project commissioning.
- Fluorine chemist talent scarcity:Experienced process safety engineers with HF handling credentials command premium compensation in tight labor markets, inflating operating cost structures for regional producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anhydrous Hydrogen Fluoride Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics Grade, Industrial Grade, Reagent Grade, Specialty Grade Technology: Distillation, Absorption, Membrane Separation, Cryogenic Process Application: Fluorochemical Manufacturing, Metal Processing, Petrochemical Processing, Catalyst Production, Refrigerant Production End User: Chemical Manufacturers, Semiconductor Foundries, Metal Fabricators, Refining Companies, Refrigeration Firms |
| Companies Covered | Linde plc, Navin Fluorine International Limited, Honeywell International Inc., Foosung Co. Ltd., Fubao Group, Solvay, LANXESS, Orbia Fluor & Energy Materials, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anhydrous Hydrogen Fluoride Market Strategic Shifts & Innovations
Purification technology roadmaps and regulatory chemistry restrictions are converging to reshape competitive positioning across grade tiers, with energy efficiency and traceability emerging as the dual axes of differentiation.
Membrane separation systems are migrating from conventional distillation trains in new capacity additions, particularly for electronics-grade production where energy consumption determines project economics. Semiconductor foundries in Taiwan and South Korea are specifying membrane-purified material in procurement contracts, compressing the addressable market for legacy distillation-based suppliers unable to retrofit existing assets.
REACH registration requirements and the EU F-Gas Regulation are tightening supply chain traceability obligations for European market participants while restricting certain fluorinated gas applications. Industrial-grade producers serving refrigerant manufacturers face volume headwinds as hydrofluorocarbon phase-down schedules accelerate, forcing portfolio pivots toward pharmaceutical and agrochemical intermediate applications.
Long-term offtake agreements with fixed purity escalators are displacing spot market transactions for electronics-grade material. Semiconductor foundries in East Asia are consolidating procurement through integrated chemical suppliers with captive acid regeneration capabilities, compressing trading margins for merchant market participants and favoring backward-integrated producers with dedicated logistics infrastructure.
Anhydrous Hydrogen Fluoride Market Segmentation
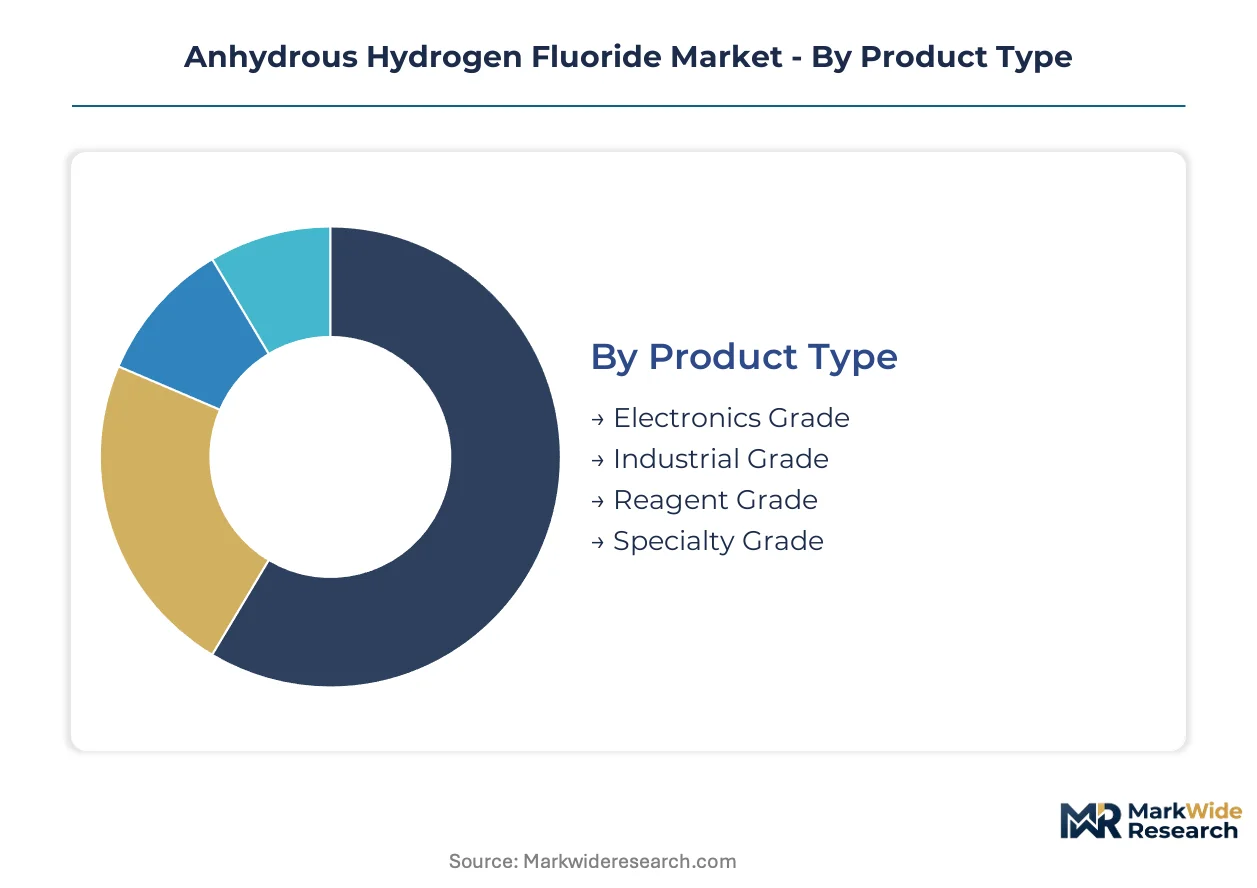
Grade purity thresholds and purification technology choices determine margin capture across the anhydrous hydrogen fluoride value chain. Semiconductor qualification requirements and refrigerant phase-down schedules are rebalancing segment weights faster than historical replacement cycles.
Product Type:
Purity specifications stratify the market into four tiers, with sub-ppb contamination limits separating premium electronics material from commodity industrial grades.
- Electronics Grade:Sub-ppb metallic impurity specifications enable advanced node semiconductor etching processes. Taiwan and South Korea foundries are consolidating procurement through membrane-purified supply contracts with fixed purity escalators.
- Industrial Grade:Standard purity material sustains volume leadership through fluorochemical manufacturing and metal processing applications. China's Zhejiang and Jiangsu fluorochemical clusters absorb the majority of industrial-grade offtake for downstream refrigerant and pharmaceutical intermediate production.
- Reagent Grade:Laboratory and analytical applications require consistent lot-to-lot purity certification. Academic and institutional procurement runs through specialized chemical distributors with cold-chain logistics capabilities.
- Specialty Grade:Custom-formulated material serves pharmaceutical fluorination and agrochemical intermediate synthesis. Indian contract manufacturers are expanding offtake for active pharmaceutical ingredient production.
Industrial Grade holds installed capacity. Electronics Grade is rotating up the share rankings.
Technology:
Energy intensity benchmarks and capital recovery timelines differentiate purification approaches, with membrane systems gaining traction in new capacity additions.
- Membrane Separation:Polymeric and ceramic membrane systems reduce energy consumption by displacing thermal distillation in electronics-grade production. South Korean semiconductor foundries are specifying membrane-purified material in procurement contracts, compressing demand for legacy distillation-based supply.
- Distillation:Conventional multi-stage distillation trains dominate existing installed capacity, particularly for industrial-grade material where energy costs represent a smaller share of total production economics. Retrofit decisions hinge on electricity pricing and carbon intensity regulations.
- Absorption:Liquid absorption processes recover hydrogen fluoride from vent streams and acid regeneration operations. Aftermarket service providers are building captive absorption capacity to capture recurring revenue from spent fluoride stream recovery.
- Cryogenic Process:Low-temperature separation enables ultra-high purity production for specialty semiconductor applications. Limited commercial deployment reflects capital intensity and narrow addressable demand.
Distillation dominates legacy assets. Membrane Separation is climbing the fastest on new project pipelines.
Application:
Downstream demand fragmentation across fluorochemical synthesis, materials processing, and energy applications creates divergent growth trajectories.
- Fluorochemical Manufacturing:Feedstock demand for refrigerants, fluoropolymers, and pharmaceutical intermediates represents the largest volume sink. China's dual carbon goals and MEE emissions intensity benchmarks are filtering marginal acid-grade producers, consolidating output among integrated operators.
- Refrigerant Production:Hydrofluorocarbon manufacturing consumes industrial-grade material in alkylation and fluorination reactions. EU F-Gas Regulation phase-down schedules are compressing European demand, forcing capacity pivots toward pharmaceutical and agrochemical applications.
- Metal Processing:Stainless steel pickling and aluminum fluoride production absorb steady industrial-grade volumes. Automotive lightweighting trends in Germany and Japan are sustaining aluminum smelter demand for fluoride feedstock.
- Petrochemical Processing:Alkylation catalyst regeneration and refinery fluoride applications require consistent acid quality. US Gulf Coast refining complexes represent concentrated demand nodes with dedicated logistics infrastructure.
- Catalyst Production:Fluorinated catalyst precursors for petrochemical and specialty chemical synthesis demand controlled impurity profiles. Custom synthesis houses in Switzerland and Japan specialize in small-batch catalyst-grade material.
Fluorochemical Manufacturing holds installed capacity. Refrigerant Production is rotating up the share rankings as pharmaceutical intermediate demand accelerates.
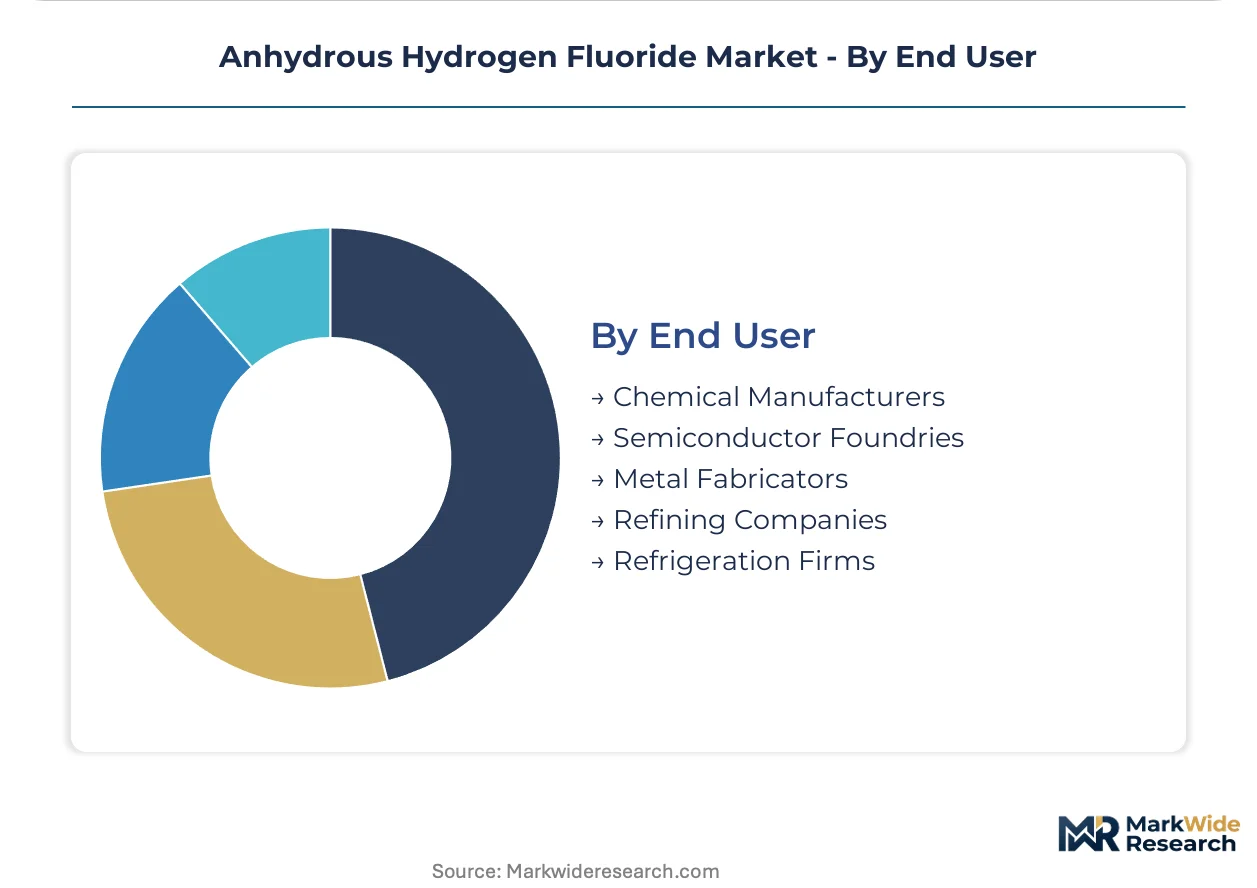
End User:
Customer scale and integration depth determine procurement modality, with captive supply arrangements displacing spot market transactions.
- Semiconductor Foundries:Advanced node etching operations require qualified electronics-grade supply with eighteen-to-thirty-six-month certification timelines. Taiwan and South Korea foundries are consolidating procurement through integrated chemical suppliers with dedicated acid regeneration capabilities.
- Chemical Manufacturers:Integrated fluorochemical producers with captive mining and acid regeneration assets control cost positions across refrigerant and pharmaceutical intermediate value chains. East China's Zhejiang and Jiangsu clusters concentrate backward-integrated chemical manufacturing capacity.
- Refrigeration Firms:Hydrofluorocarbon and emerging hydrofluoroolefin producers face volume headwinds from EU F-Gas Regulation restrictions, forcing portfolio diversification into pharmaceutical and agrochemical feedstock applications.
- Metal Fabricators:Stainless steel processors and aluminum smelters consume industrial-grade material in surface treatment and electrolyte applications. German automotive supplier networks sustain European metal processing demand.
- Refining Companies:Petrochemical alkylation operations require consistent acid quality for catalyst regeneration. US Gulf Coast and Middle Eastern refining hubs represent concentrated demand with long-term offtake contracting preferences.
Chemical Manufacturers hold installed capacity. Semiconductor Foundries is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: East Asian semiconductor foundries pull electronics-grade volumes through membrane-purified supply contracts, while Chinese industrial clusters absorb industrial-grade material for downstream fluorochemical synthesis. European refrigerant demand faces structural compression under F-Gas Regulation phase-down schedules.
China
East China's Zhejiang and Jiangsu provinces concentrate fluorochemical manufacturing capacity serving refrigerant and pharmaceutical intermediate demand. The Ministry of Ecology and Environment enforces emissions intensity benchmarks that filter marginal acid-grade producers from the expanding base. Captive mining and acid regeneration investments in these clusters secure feedstock cost positions for integrated operators.
United States
Gulf Coast petrochemical complexes represent concentrated demand nodes for alkylation catalyst regeneration and refinery fluoride applications. EPA regulations under the Clean Air Act and OSHA permissible exposure limits shape facility siting and worker safety investments across production sites. Linde plc leverages industrial gas infrastructure to control bulk distribution networks serving downstream chemical manufacturers.
South Korea
Semiconductor foundries in Seoul Capital Area and Busan-Ulsan specify membrane-purified electronics-grade material in procurement contracts with fixed purity escalators. The country's national industrial regulator maintains strict contamination thresholds for advanced node etching processes. Domestic purification capacity expansion lags behind foundry construction timelines, sustaining import dependence.
Germany
Automotive lightweighting trends sustain aluminum smelter demand for fluoride feedstock in North Rhine-Westphalia and Bavaria. The EU F-Gas Regulation restricts hydrofluorocarbon applications while tightening supply chain traceability obligations for market participants. German chemical manufacturers face volume headwinds from refrigerant phase-down schedules, forcing portfolio pivots toward pharmaceutical intermediate applications.
Japan
Custom synthesis houses in Kanto and Kansai regions specialize in small-batch catalyst-grade material for petrochemical and specialty chemical applications. METI oversees industrial chemical safety standards governing HF handling and transportation infrastructure. Domestic producers maintain qualification relationships with semiconductor foundries through eighteen-to-thirty-six-month certification cycles.
Anhydrous Hydrogen Fluoride Market Key Industry Players
Capability concentration sits with membrane purification specialists; scale advantage sits with integrated industrial gas and chemical conglomerates. The market structures around three tiers: backward-integrated miners with captive acid regeneration, industrial gas distributors controlling logistics infrastructure, and high-purity specialists serving semiconductor qualification requirements. Dominant competitive moves include captive supply arrangements with downstream refrigerant producers and aftermarket acid regeneration service expansion.
Among diversified industrial gas and chemical conglomerates, Linde plc, Honeywell International Inc., and Solvay occupy positions spanning bulk distribution networks and specialty grade production. Within the high-purity specialist tier, Navin Fluorine International Limited exemplifies regional purification capability serving Indian semiconductor foundry demand. Foosung Co. Ltd. represents Korean industrial chemical manufacturing with electronics-grade positioning. These named entities anchor archetype differentiation rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Linde plc |
| Navin Fluorine International Limited |
| Honeywell International Inc. |
| Foosung Co. Ltd. |
| Fubao Group |
| Solvay |
| LANXESS |
| Orbia Fluor & Energy Materials |
| Arkema |
| Others |
Cost & Logistics Intelligence
East China's Zhejiang and Jiangsu fluorochemical clusters concentrate membrane-purification capacity for electronics-grade material, translating feedstock cost advantages into pricing power over merchant market participants. Captive acid regeneration investments in these provinces compress delivered costs for integrated operators while exposing non-integrated buyers to spot market volatility.
Pricing Analysis
Long-term offtake agreements with fixed purity escalators dominate electronics-grade procurement, displacing spot transactions as semiconductor foundries consolidate supplier relationships. Price differentiation hinges on certification grade and volume scale, with sub-ppb qualified material commanding substantial premiums over industrial-grade alternatives. Cost compression in industrial-grade tiers intensifies as China's MEE emissions benchmarks filter marginal producers. Merchant buyers in refrigerant manufacturing exhibit highest price sensitivity due to demand destruction from EU F-Gas Regulation phase-down schedules.
Supply Chain Analysis
Extended payment terms from integrated chemical manufacturers in China and South Korea are squeezing working capital for regional distributors serving smaller downstream accounts. Raw material flows draw from acid-grade fluorspar mining in China and Mexico, with sulfuric acid and energy inputs anchoring variable cost structures. Single-source vulnerability concentrates in Chinese fluorspar export quotas, exposing processors to supply interruption risk. Distribution runs through industrial gas infrastructure controlled by bulk handlers with dedicated cold-chain logistics for high-purity material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among semiconductor foundries consolidating procurement through integrated chemical suppliers, fragmenting negotiating leverage for smaller refrigerant manufacturers and metal processors.
For Market Incumbents: Pre-empt membrane purification technology adoption by retrofitting distillation assets or acquiring regional specialists with qualified semiconductor supply relationships. Captive fluorspar mining investments in East China secure feedstock positions against export quota volatility. Defensive consolidation through acid regeneration service expansion captures recurring revenue pools insulated from spot pricing pressure. For New Entrants and Emerging Players: Indian semiconductor manufacturing clusters present underpenetrated demand for electronics-grade material that domestic purification capacity cannot yet satisfy. Specialty pharmaceutical fluorination applications in contract manufacturing offer white-space entry with lower certification barriers than semiconductor qualification. Go-to-market execution should anchor on qualification partnerships with established distributors holding existing foundry relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane purification specialists with semiconductor-qualified capacity over legacy distillation operators facing retrofit capital demands. Long-term viability across the analysis window rests on backward integration into fluorspar resources or forward integration into acid regeneration services. Monitor MEE enforcement intensity in China as the signal for supply-side consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Purification Capacity Expansion | Reduces energy intensity for electronics-grade production serving Taiwan and South Korea foundries. |
| Backward Integration into Fluorspar Mining | Secures feedstock cost positions against Chinese export quota volatility and freight spikes. |
| Acid Regeneration Service Buildout | Captures recurring revenue from spent fluoride recovery adjacent to commodity acid sales. |
| Long-term Supply Agreement with Foundries | Locks in offtake volumes with fixed purity escalators, compressing spot market exposure. |
| Joint Venture in Indian Semiconductor Corridor | Positions for PLI scheme-driven demand with local purification and logistics infrastructure. |
Research Approach
A standing panel of fluorochemical plant managers, semiconductor procurement leads, acid regeneration service operators, and logistics specialists provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC filings from listed chemical conglomerates, MEE emissions disclosure databases, and EU F-Gas Regulation compliance registries. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across grade tiers and regional production hubs.
Scenario-bracketing anchored the analytical framework, with high and low cases reflecting divergent MEE enforcement intensity and semiconductor capital expenditure trajectories across the projection horizon. Segmentation dimensions modeled include grade purity tier, purification technology type, end-use application, and regional manufacturing cluster. CAGRs derived from fitted growth curves incorporating fluorspar cost trajectories, membrane technology diffusion rates, and regulatory phase-down schedules for fluorinated gases.
Practitioners should monitor Chinese fluorspar export policy shifts, EU F-Gas Regulation amendment timelines, and semiconductor node transition announcements for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Calcium Hydride Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Myclobutanil Market
Chemicals
Monoisopropanolamine (MIPA) Market
Chemicals
Aluminium Chloride Market
Chemicals
Fluorochemicals Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Guaiazulene Market
Chemicals
Iscotrizinol Market
Chemicals
Global Inorganic Fluorides Market
Chemicals
Mercuric Chloride Market
Chemicals
Benzhydrol Market
Chemicals
North America Oxo-Alcohol Market
Chemicals
India Anhydrous Hydrogen Fluoride Market
Chemicals
Fluoroantimonic Acid Market
Chemicals
Guaiacol Market