
 Fluoropolymer Masterbatch Market | 2026-2036
Fluoropolymer Masterbatch Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoropolymer Masterbatch Market Analysis
High-performance polymer compounding is rewriting material specifications across critical infrastructure applications. RTP Company leverages its multi-site manufacturing footprint to sustain consistent supply to medical device OEMs. Clariant differentiates through color-critical formulations that anchor its position in aerospace-certified masterbatch supply. Ampacet Corporation competes on scale in fluoropolymer concentrates for wire and cable sheathing.
Fluoropolymer masterbatch denotes a concentrated dispersion of PTFE, FEP, PFA, or PVDF resin combined with pigments, fillers, and processing aids, typically manufactured via twin-screw extrusion to achieve uniform filler distribution at loadings of 15-40% active content. Its primary purpose is to impart chemical resistance, low friction coefficients, and thermal stability to commodity polymers without requiring full fluoropolymer substitution. PTFE-based masterbatches command the largest volume share due to their established use in automotive fuel system components, while PVDF grades represent the fastest-expanding category driven by lithium-ion battery binder applications. Granule form dominates commercial supply chains because of superior feeding consistency in injection molding, though powder variants occupy niche positions in compression molding of semiconductor-grade components.
EPA chemical safety evaluations under TSCA and REACH substance restrictions administered by ECHA are elevating purity requirements for perfluorinated additives, directly influencing reformulation investments by compounders. FDA biocompatibility standards for healthcare masterbatches and ISO 10993 testing protocols further segment market access between medical-grade and industrial-grade suppliers. Stakeholders must monitor regulatory pre-announcements on per- and polyfluoroalkyl substance restrictions to time capacity decisions and alternative chemistry investments.
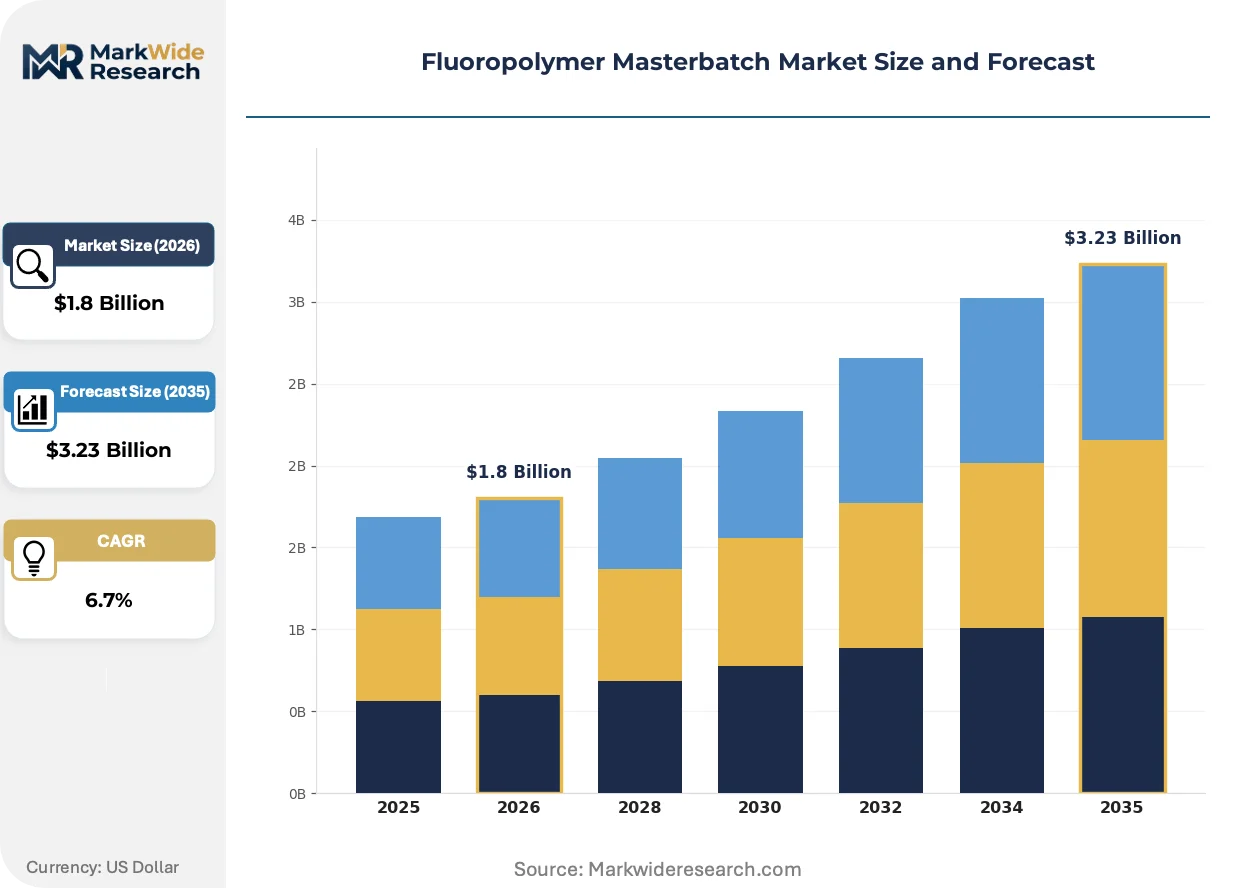
Market Dynamics
REACH substance restrictions and EPA chemical safety evaluations under TSCA are forcing compounders to accelerate reformulation cycles, compressing product development timelines from 18 months to under 12 months for wire and cable insulation grades.
Growth Catalysts
- Electric vehicle battery binders:PVDF masterbatch demand from lithium-ion cell manufacturers is scaling in parallel with gigafactory construction across China and Germany.
- REACH compliance mandates:ECHA restrictions on perfluorinated additives are accelerating replacement chemistry investments by European automotive fuel system suppliers.
- Medical device biocompatibility:ISO 10993 testing protocols are expanding addressable market for PTFE-based masterbatches in implantable component manufacturing.
Market Restraints
- Fluoropolymer resin concentration:PTFE and PVDF feedstock supply concentrates among three multinational chemical producers, creating input cost volatility.
- Substitution threat:High-performance polyimide and PEEK compounds are capturing share in semiconductor-grade compression molding applications.
- Technical limitation:Masterbatch loadings above 40% active content suffer from filler agglomeration, capping performance enhancement in extreme chemical environments.
Strategic Opportunities
- Underpenetrated aerospace coatings:India and Brazil represent white space for color-critical fluoropolymer formulations in commercial aircraft interior components.
- Regulatory tailwind:EU F-Gas Regulation phase-down is creating demand for low-GWP fluoropolymer alternatives in HVAC membrane applications.
- Technology convergence:Twin-screw extrusion paired with real-time rheology monitoring is enabling custom masterbatch development for medical device OEMs.
Industry Challenges
- Compounding expertise scarcity:Qualified process engineers capable of uniform filler distribution at 15-40% loadings are concentrated among a handful of specialized compounders.
- Certification timeline compression:FDA biocompatibility clearance cycles for healthcare masterbatches now exceed 14 months, delaying commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoropolymer Masterbatch Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, PFA, PVDF End Use Industry: Automotive, Electronics, Healthcare, Aerospace Form: Granules, Powders, Sheets, Films Color: Natural, Black, White, Custom |
| Companies Covered | RTP Company, Avi Additives Pvt. Ltd., Ampacet Corporation, Clariant, Cabot Corporation, Avient Corporation, Everflon, Sarvan Carbochem LLP, Americhem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoropolymer Masterbatch Market Emerging Trajectories
Digital formulation platforms and predictive rheology modeling are compressing development cycles for custom fluoropolymer concentrates. These tools enable compounders to simulate filler dispersion patterns before physical production.
Real-time spectroscopic monitoring during twin-screw extrusion is virtualizing quality assurance protocols. Medical device OEMs in Switzerland and Massachusetts are adopting this technology to eliminate batch-to-batch variation. The shift is compressing qualification timelines for implantable-grade PTFE masterbatches from six months to under eight weeks.
ECHA's expanding REACH authorization list for perfluorinated substances is elevating purity documentation requirements. Compounders must now submit full substance identity portfolios for masterbatch additives above 0.1% concentration. Wire and cable sheathing suppliers serving European infrastructure projects are absorbing the compliance cost through dedicated regulatory affairs teams.
Specification-driven procurement is consolidating buyer power among tier-one automotive and medical OEMs. These customers now mandate locked formulations with multi-year supply guarantees, displacing spot-market purchasing. The pattern is most pronounced in Germany and Japan, where fuel system and battery manufacturers are integrating masterbatch suppliers into early-stage vehicle platform development.
Fluoropolymer Masterbatch Market Segmentation
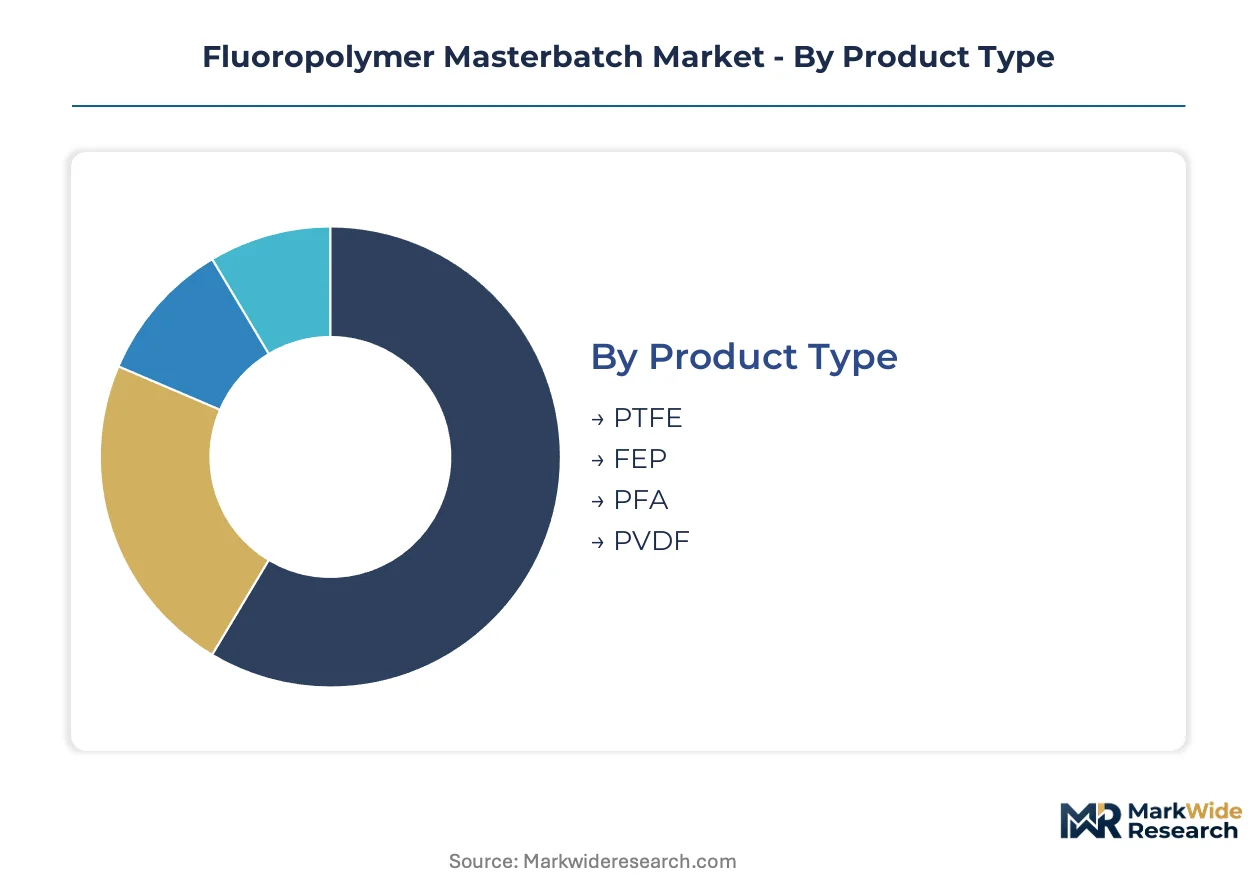
Fluoropolymer masterbatch segmentation reveals how resin chemistry, physical form, and end-use certification requirements fragment supply chains. Each dimension creates distinct technical barriers and pricing tiers that compounders must navigate.
Product Type:
Resin chemistry determines thermal ceiling, chemical resistance, and processing window—directly mapping to application value and formulation complexity.
- PTFE:Polytetrafluoroethylene masterbatches deliver the lowest coefficient of friction among commercial fluoropolymers and withstand continuous service temperatures to 260°C. Automotive fuel system manufacturers in Germany and Japan specify PTFE concentrates for fuel line coatings where permeation resistance is non-negotiable.
- PVDF:Polyvinylidene fluoride grades exhibit exceptional electrochemical stability and adhesion to metal substrates, properties that lithium-ion battery cell producers in China require for electrode binder formulations. Gigafactory construction across Jiangsu and Sichuan provinces is absorbing capacity expansions from domestic compounders.
- FEP:Fluorinated ethylene propylene offers melt-processability PTFE lacks, enabling thinner-wall extrusions for wire insulation.
- PFA:Perfluoroalkoxy resins bridge the performance gap between PTFE and FEP for semiconductor-grade tubing applications.
PTFE holds installed capacity. PVDF is rotating up the share rankings.
End Use Industry:
Application verticals impose divergent certification regimes that stratify suppliers into medical-grade, automotive-grade, and industrial-grade tiers.
- Automotive:Fuel system components, wire harness sheathing, and under-hood gaskets demand masterbatches meeting OEM material specifications plus EPA evaporative emission standards. Tier-one suppliers in Stuttgart and Detroit now require locked formulations with 7-year supply guarantees.
- Electronics:Wire and cable insulation for data centers and EV charging infrastructure drives volume, with compounders in South Korea specializing in low-smoke halogen-free FEP grades for 5G base station cabling.
- Healthcare:ISO 10993 biocompatibility testing and FDA master file submissions create 14-month qualification timelines that filter out general industrial compounders.
- Aerospace:Color-critical interior components require batch-to-batch color consistency within Delta E 1.0, a specification only a handful of European compounders currently meet.
Automotive commands volume concentration. Healthcare is climbing the fastest on margin contribution.
Form:
Physical presentation dictates feeding behavior in downstream processing equipment and determines which compounders can serve which molding technologies.
- Granules:Pelletized masterbatches feed consistently through gravimetric dosing systems in high-speed injection molding lines, explaining their dominance in automotive and electronics supply chains. Twin-screw extrusion with underwater pelletizing yields spherical granules with low fines content preferred by Japanese automotive OEMs.
- Powders:Fine-ground PTFE and PVDF powders disperse more uniformly in compression molding of semiconductor wafer carriers, though dust handling requirements limit supplier participation.
- Sheets:Pre-consolidated masterbatch sheets suit lamination processes for chemical-resistant tank linings.
- Films:Cast film formats enable direct incorporation into multilayer barrier packaging for pharmaceutical blister packs.
Granules hold installed capacity. Powders are rotating up the share rankings.
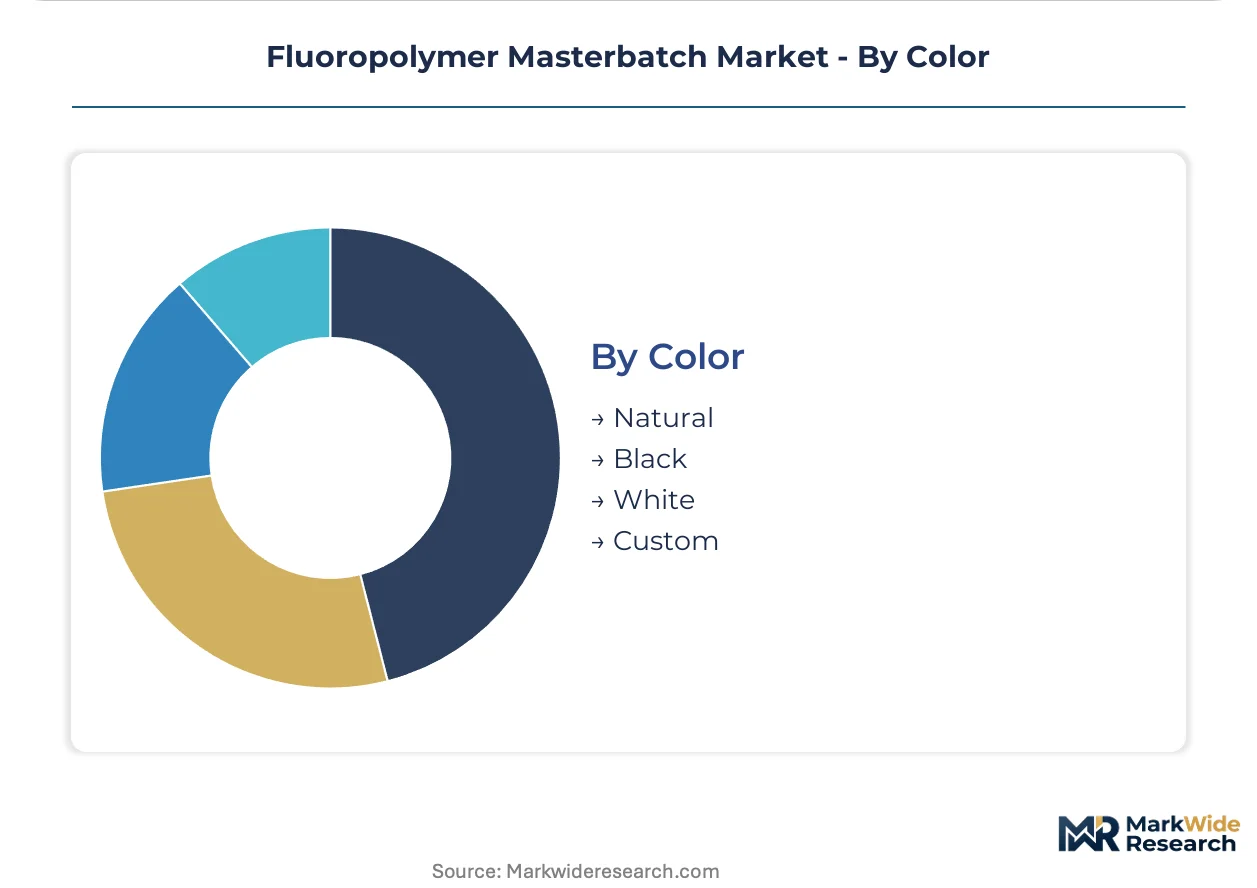
Color:
Pigmentation level determines regulatory burden and technical complexity, with custom color matching requiring spectrophotometric verification and lot-to-lot traceability.
- Natural:Unpigmented masterbatches avoid colorant-related regulatory scrutiny and serve applications where the base resin's inherent ivory or translucent appearance is acceptable, including many semiconductor and chemical processing components.
- Black:Carbon black pigmentation dominates wire and cable insulation for UV resistance and identification coding, with compounders in the US Gulf Coast specializing in conductive grades for antistatic applications.
- White:Titanium dioxide loadings for medical device housings and food-contact applications must meet FDA 21 CFR 178.3297 specifications for pigment purity.
- Custom:Color-matched formulations for aerospace interiors and branded automotive components require spectrophotometric batch release and retained sample archives for regulatory audit trails.
Natural holds installed capacity. Custom is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders export fluoropolymer masterbatches to automotive OEMs in Stuttgart and Wolfsburg, while Chinese domestic production scales to serve lithium-ion battery gigafactories in Jiangsu and Sichuan provinces.
United States
Wire and cable insulation for data centers and EV charging infrastructure drives masterbatch consumption along the Gulf Coast. EPA chemical safety evaluations under TSCA are elevating purity documentation requirements for perfluorinated additives. Houston-based compounders specialize in conductive carbon black grades for antistatic applications.
Germany
Automotive fuel system components and under-hood gaskets absorb PTFE masterbatch volumes from Stuttgart suppliers. ECHA REACH substance restrictions on perfluorinated additives are compressing reformulation cycles to under 12 months. Bavarian compounders anchor aerospace-certified color-critical formulations for commercial aircraft interiors.
China
PVDF masterbatch demand from lithium-ion cell manufacturers is scaling with gigafactory construction across Jiangsu and Sichuan provinces. MIIT industrial standards and dual carbon goals are tightening material specifications for domestic EV supply chains. Yangtze River Delta compounders are expanding capacity in parallel with battery production scaling.
Japan
Automotive OEMs in Nagoya and Tokyo specify locked formulations with 7-year supply guarantees for fuel line coatings. METI energy policy and JIS standards govern masterbatch specifications for wire harness sheathing. Kansai-based compounders deliver spherical granules with low fines content preferred by tier-one suppliers.
Switzerland
Medical device OEMs in Basel and Zurich are adopting real-time spectroscopic monitoring to eliminate batch-to-batch variation. Swissmedic biocompatibility requirements and ISO 10993 testing protocols filter out general industrial compounders. Swiss specialists compress qualification timelines for implantable-grade PTFE masterbatches from six months to under eight weeks.
Fluoropolymer Masterbatch Market Vendor Landscape
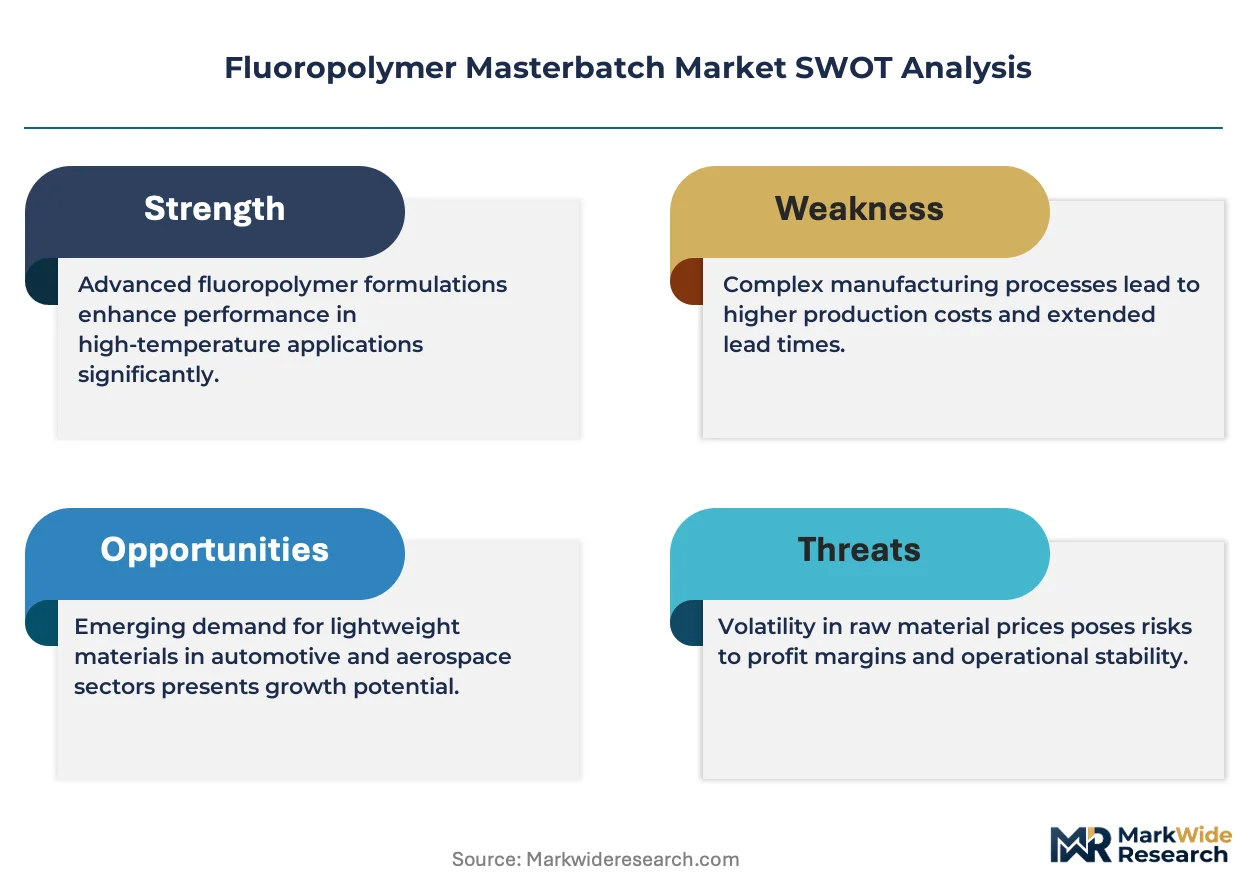
On the supply side, the industry is tiered between multinational chemical producers controlling fluoropolymer resin feedstock and specialized compounders managing formulation expertise. Concentration concentrates upstream among three resin suppliers, while downstream compounding fragments across regional specialists and application-focused formulators. Strategic archetypes include medical-grade biocompatibility specialists, automotive-scale volume suppliers, and color-critical aerospace formulators. Dominant competitive moves encompass backward integration into captive resin supply and technology licensing partnerships for twin-screw extrusion with real-time rheology monitoring.
Among US-based compounders, RTP Company and Ampacet Corporation exemplify scale-driven supply to automotive and wire and cable end-uses. RTP Company anchors the medical device OEM supply tier through multi-site manufacturing footprints, while Ampacet Corporation occupies a position in fluoropolymer concentrates for infrastructure sheathing applications. European specialists Clariant and Avient Corporation represent the color-critical and formulation-differentiated archetype, with Clariant sitting within aerospace-certified masterbatch supply and Avient exemplifying portfolio breadth across resin chemistries.
| Leading Market Players |
|---|
| RTP Company |
| Avi Additives Pvt. Ltd. |
| Ampacet Corporation |
| Clariant |
| Cabot Corporation |
| Avient Corporation |
| Everflon |
| Sarvan Carbochem LLP |
| Americhem |
| Others |
Supply Flow & Price Mechanics
Underutilized compounding capacity in the Yangtze River Delta is compressing spot pricing for PVDF masterbatches while locking in long-term contract premiums for automotive-grade PTFE formulations. This utilization asymmetry between battery binder and fuel system supply tiers is reshaping supplier investment priorities across Chinese and German production clusters.
Pricing Analysis
Next-generation real-time rheology monitoring systems command 15-25% premiums over conventional twin-screw extrusion equipment, while legacy granule formulations face margin erosion from commoditized supply. Three-tier pricing structure across medical-grade biocompatibility, automotive-scale volume, and industrial-standard tiers anchors the market, with ISO 10993 certification and FDA master file status driving the widest spreads. Cost compression in wire and cable insulation grades is intensifying because REACH compliance documentation requirements are absorbing compounder overhead. Tier-one automotive OEMs in Stuttgart and Detroit exhibit the lowest price sensitivity due to locked formulation mandates, while spot-market buyers in Southeast Asian electronics supply chains negotiate aggressively on volume.
Supply Chain Analysis
Specialized fluoropolymer compounders in Germany, China, and Japan hold concentrated capacity for medical-grade and aerospace-certified formulations, while general industrial blending is fragmenting across regional specialists. Feedstock supply draws from PTFE and PVDF resin producers concentrated among three multinational chemical suppliers, creating input cost volatility that propagates through quarterly contract renegotiations. Single-source vulnerability in semiconductor-grade PFA resin supply poses structural risk to implantable device manufacturers in Switzerland and Massachusetts. Distribution runs through direct OEM supply agreements for automotive and medical tiers, with spot-market distributors serving wire and cable and general industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-performance polyimide and PEEK compounds are capturing functional share in semiconductor-grade compression molding, forcing fluoropolymer masterbatch incumbents to defend application-specific value propositions through certification depth and formulation lock-in.
For Market Incumbents: Pre-empt substitution threats by deepening captive resin supply relationships and accelerating FDA biocompatibility clearance investments for implantable-grade PTFE lines. Lock automotive OEMs into 7-year formulation guarantees with dedicated regulatory affairs support to displace spot-market competitors. Prioritize real-time spectroscopic monitoring adoption to compress medical device qualification timelines from fourteen months to under eight weeks.
For New Entrants and Emerging Players: Underpenetrated aerospace interior components in India and Brazil represent the most penetrable entry point for color-critical formulation specialists lacking legacy automotive certification burden. Target lithium-ion battery binder applications in emerging European gigafactory locations where incumbent compounders lack established supply relationships. Lead with custom color matching and spectrophotometric batch release capabilities to differentiate from volume-commoditized suppliers.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap compounders with locked automotive formulations and nascent medical-grade certification pipelines, where technology licensing partnerships for twin-screw extrusion with rheology monitoring can accelerate value capture. Long-term viability hinges on regulatory pre-positioning ahead of ECHA REACH authorization expansions for perfluorinated substances. Watch for inflection in EPA TSCA chemical safety evaluation announcements that would trigger accelerated reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Supply | Secures PTFE and PVDF feedstock access against three-supplier concentration risk. |
| Technology Licensing for Real-Time Rheology Monitoring | Enables Swiss and Massachusetts medical device OEMs to eliminate batch-to-batch variation. |
| Long-Term Supply Agreement with Automotive OEMs | Locks 7-year formulation guarantees with Stuttgart and Detroit tier-one suppliers. |
| Joint Venture for European Gigafactory Proximity | Positions PVDF masterbatch capacity adjacent to German lithium-ion cell manufacturing. |
| Green Manufacturing Transition for Low-GWP Alternatives | Aligns fluoropolymer formulations with EU F-Gas Regulation phase-down requirements. |
Methodological Framework
The analysis maps PTFE, PVDF, FEP, and PFA resin chemistry tiers alongside granule, powder, sheet, and film physical forms, each validated through plant managers at compounders, procurement leads at automotive and battery OEMs, distribution channel partners, and technical R&D directors. Primary interviews with these stakeholders combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA REACH substance restriction announcements. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Assumptions held fixed include ECHA REACH authorization list expansion trajectories, EPA TSCA evaluation timelines, and MIIT industrial standard enforcement intensity across the analysis window, while electric vehicle production scaling and gigafactory construction pacing were varied across scenarios. Segmentation dimensions modeled encompass resin chemistry grade, end-use industry certification tier, physical form factor, and regional production hub concentration. CAGRs were derived from regression analysis of historical capacity utilization against downstream demand indicators, incorporating fluoropolymer resin price volatility and reformulation cycle compression effects.
Stress conditions across REACH substance restriction severity, PVDF feedstock supply disruption, and polyimide substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that regulatory acceleration or battery chemistry shifts toward silicon anodes could materially revise trajectory. Quarterly review of ECHA pre-announcements, EPA chemical safety evaluation schedules, and OEM platform development timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Global Stable Isotope Labeled Compounds Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
China Collagen Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Resin Capsule Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
GCC Hydroxypropyl Methylcellulose Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
High Performance Foam Market
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Global Engineering Plastic Compounds Market