
 Global Industrial Separators Market | 2026-2036
Global Industrial Separators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Separators Market Outlook
Advanced polymer composites are replacing stainless steel in separator housings, rebalancing unit economics toward lighter, corrosion-resistant designs. Alfa Laval leverages its Nordic manufacturing base to sustain leadership in marine and offshore separation systems. GEA Group anchors its position through captive supply of precision-engineered bowl assemblies. Andritz AG competes aggressively in the pulp and paper recovery segment with specialized decanter technology.
Industrial separators are mechanical or physicochemical devices engineered to isolate immiscible phases, suspended solids, or dissolved components from process streams, typically operating at pressures from vacuum to 150 bar and temperatures spanning -40°C to 400°C depending on application severity. Their primary purpose centers on product purification, resource recovery, and effluent compliance across continuous and batch manufacturing operations. Centrifuges command the largest installed base owing to decades of proven reliability in oil recovery and mineral processing, while membrane technology represents the fastest-expanding margin pool as pharmaceutical and biotechnology end users demand selective molecular separation without thermal degradation. Magnetic separators occupy a mature, stable niche in bulk solids handling where ferrous contamination control drives replacement cycles rather than capacity expansion.
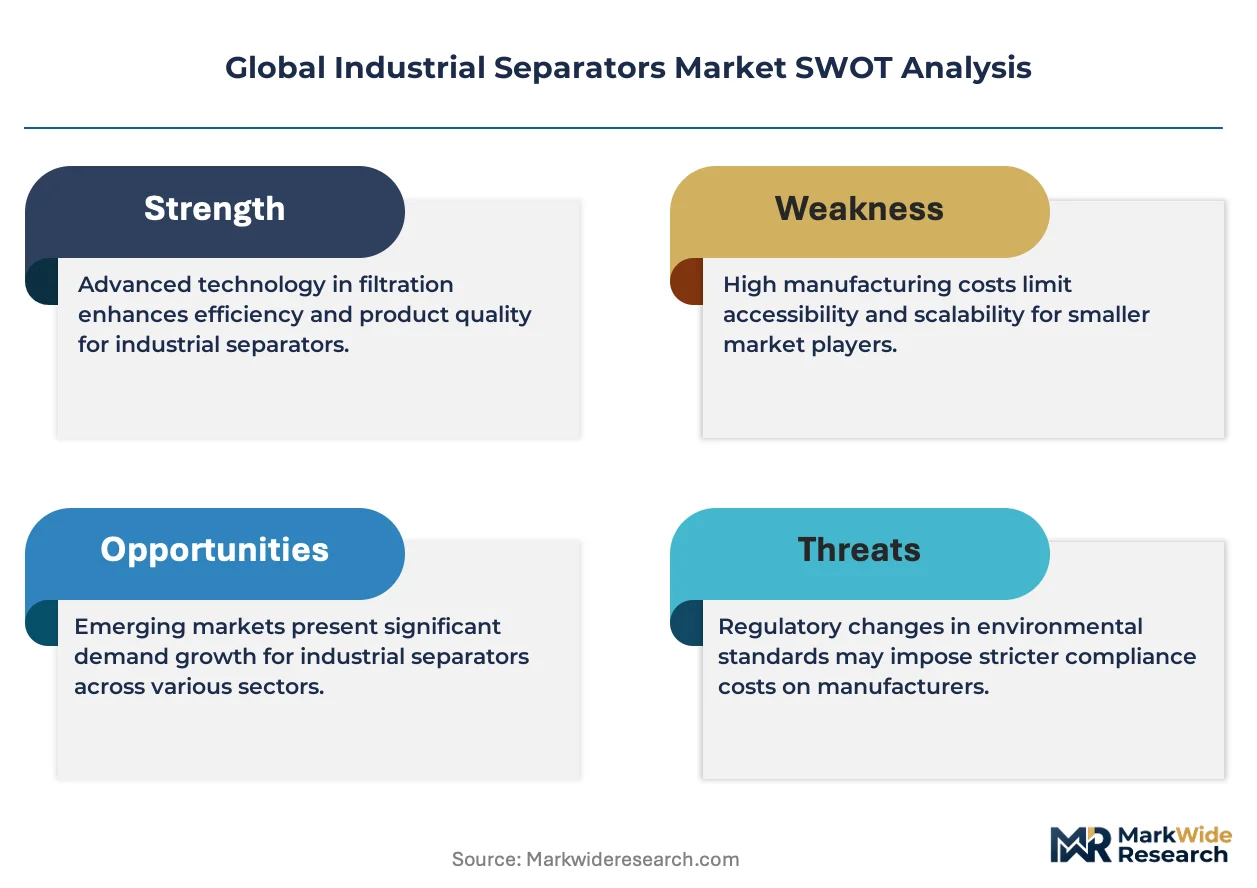
The US EPA enforces effluent limitation guidelines that compel wastewater treatment facilities to upgrade separation performance, while REACH in Europe restricts hazardous substances in separator coatings and elastomers, reshaping material specifications for equipment sold into EU member states. China’s MEE implements increasingly stringent discharge standards for chemical manufacturing zones, forcing domestic and foreign suppliers to certify equipment against GB standards for oil content and suspended solids removal. Stakeholders must monitor how divergent regional compliance timelines affect capital deployment priorities and aftermarket service attach rates.
Market Dynamics
Membrane technology is compressing replacement cycles across pharmaceutical and biotechnology process lines, forcing incumbent centrifuge suppliers to defend installed base through service contract restructuring and performance guarantees.
Growth Catalysts
- EU Green Deal discharge mandates:Wastewater treatment operators in Germany are accelerating membrane-based separator procurement ahead of tightening effluent standards.
- China's dual carbon goals:Energy-efficiency requirements are driving centrifuge system upgrades in chemical manufacturing clusters.
- Advanced polymer composites:Lighter, corrosion-resistant housing materials are expanding addressable applications in offshore and marine environments.
Market Restraints
- Specialized alloy input volatility:Precision-engineered bowl assemblies depend on nickel and titanium supply concentration from limited smelter networks.
- REACH substance restrictions:Hazardous substance limitations on coatings and elastomers force material reformulation and requalification timelines.
- Membrane fouling limitations:Biological process streams degrade polymeric membrane performance, constraining uptime in continuous fermentation operations.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO compliance requirements for sterile processing create demand for validated separation skids.
- Carbon capture integration:Amine solvent recovery applications are converging with membrane and centrifuge technologies in power generation retrofits.
- Outcome-based service models:Chemical manufacturers are unbundling equipment ownership from performance guarantees, creating recurring revenue pools.
Industry Challenges
- Multiphysics simulation expertise gap:Computational fluid dynamics competency for high-G separation modeling concentrates in limited engineering pools.
- GB standard certification timelines:Foreign suppliers face extended validation periods for oil content and suspended solids removal equipment in China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Separators Market |
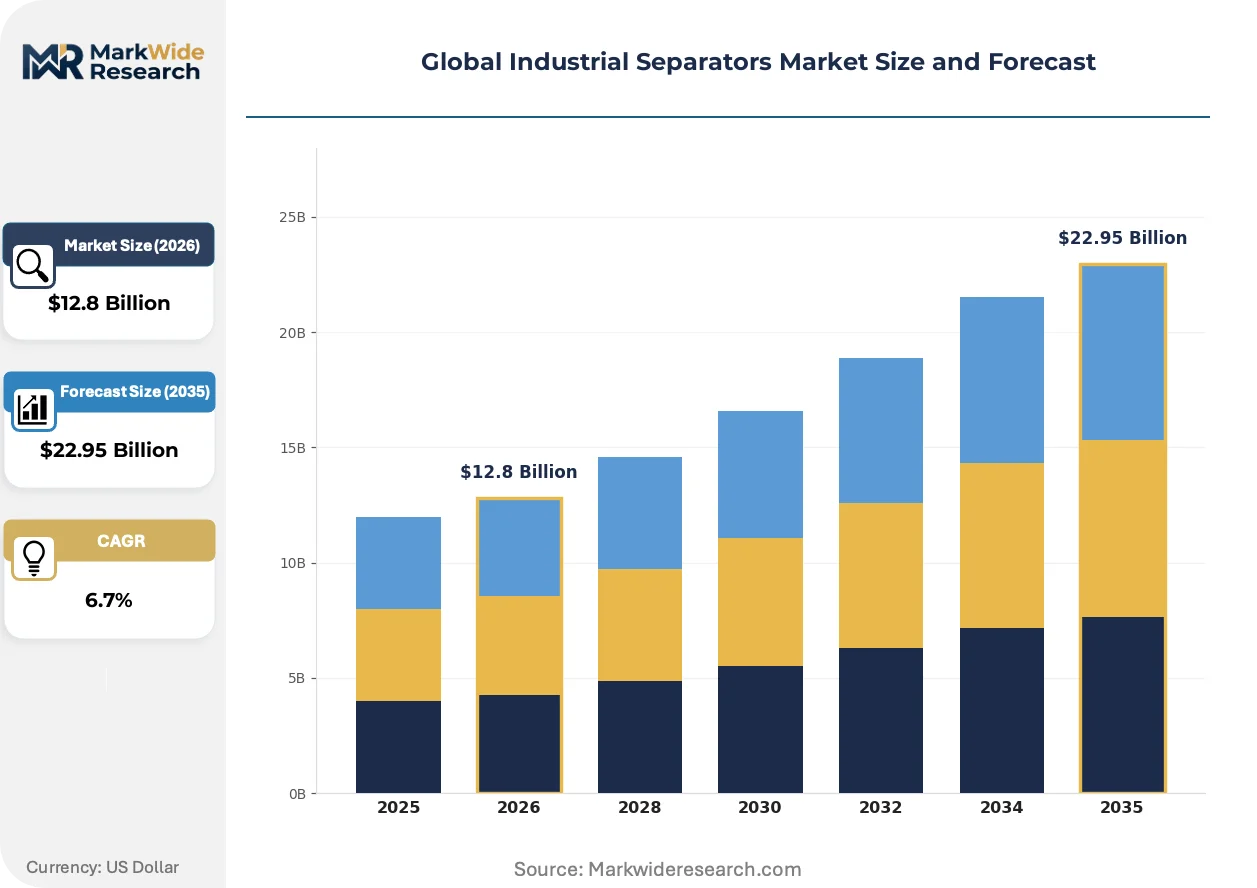
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifuges, Separating Funnels, Magnetic Separators, Filter Presses Technology: Gravity Separation, Distillation, Membrane Technology, Flotation End User: Food Processing, Chemical Manufacturing, Oil & Gas, Pharmaceuticals Application: Wastewater Treatment, Oil Recovery, Mineral Processing, Biotechnology |
| Companies Covered | Alfa Laval, GEA Group, Schlumberger, Andritz AG, Flottweg SE, Eaton Corporation, Parker Hannifin, Eriez Manufacturing, GIAMAG Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Separators Market Strategic Shifts
Digitalization of separation performance monitoring is compressing maintenance intervals and enabling predictive intervention models across process industries.
Machine learning algorithms applied to vibration and torque signatures are automating bowl imbalance detection in decanter centrifuges. Oil recovery operators in the North Sea are deploying these systems at scale. The technology is automating shift from scheduled to condition-based maintenance, reducing unplanned downtime.
EPA effluent limitation guidelines are forcing wastewater treatment facilities to upgrade separation performance through membrane bioreactor retrofits. Municipal operators face capital constraints that favor modular, containerized systems over greenfield construction. Pharmaceutical discharge compliance is driving adoption of dissolved air flotation as pre-treatment.
Consolidated buying by integrated chemical multinationals is compressing vendor negotiation cycles and demanding lifecycle cost guarantees. Engineering-procurement-construction firms are capturing separator specification authority from end-user process engineers. This concentration is most visible in US Gulf Coast petrochemical expansions.
Global Industrial Separators Market Segmentation
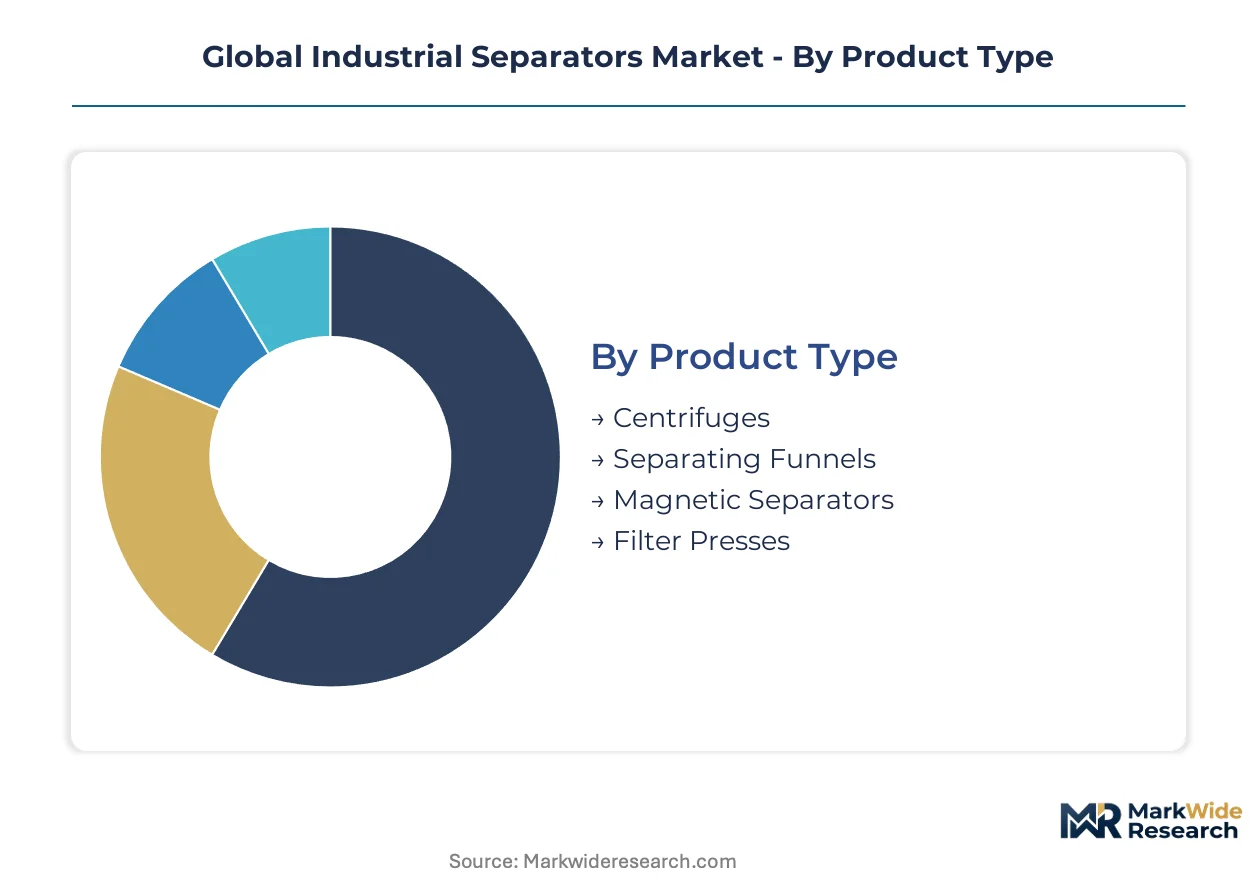
Industrial separator procurement diverges sharply across process intensity, regulatory exposure, and fluid characteristics. Technology selection hinges on phase immiscibility, particle size distribution, and thermal sensitivity of target fractions.
Product Type:
Mechanical separation principles determine capital intensity, energy consumption, and maintenance cadence across installed equipment bases.
- Centrifuges:High-G rotational systems exploit density differentials to accelerate phase separation in continuous-flow operations. Oil recovery operators in the North Sea and mineral processing facilities in Western Australia favor decanter configurations for their tolerance of high solids loading and abrasive slurries.
- Magnetic Separators:Permanent magnet or electromagnet assemblies extract ferrous contamination from dry bulk solids streams. Food processing facilities in Germany deploy these systems upstream of milling operations to protect downstream equipment and comply with EU food safety standards.
- Separating Funnels:Batch-scale liquid-liquid extraction devices serve laboratory and pilot-plant validation workflows. Pharmaceutical R&D centers in Switzerland utilize these for solvent recovery during active pharmaceutical ingredient synthesis.
- Filter Presses:Mechanical dewatering equipment compresses slurry between recessed plates to extract filtrate. Municipal wastewater treatment plants in India favor these for biosolids management given their low operational complexity and minimal power requirements.
Centrifuges lead on scale; membrane-integrated filtration systems lead on momentum in pharmaceutical and biotechnology deployment.
Technology:
Physical separation mechanisms span passive gravitational settling to active molecular sieving, each imposing distinct energy and precision trade-offs.
- Membrane Technology:Polymeric or ceramic barriers execute selective permeation based on molecular weight cutoff or charge exclusion. Biopharmaceutical manufacturers in Massachusetts deploy tangential flow filtration for protein concentration and diafiltration without thermal denaturation.
- Gravity Separation:Density-driven settling in clarifiers or thickeners requires no external energy input beyond feed pumping. Oil sands extraction facilities in Alberta rely on primary gravity separation before downstream centrifugation to reduce energy intensity of bitumen recovery.
- Distillation:Thermal phase separation exploits volatility differentials for solvent purification and azeotrope breaking. Specialty chemical producers in Belgium deploy wiped-film evaporators for heat-sensitive compounds under vacuum conditions.
- Flotation:Bubble attachment and surface chemistry enable selective recovery of hydrophobic particles from aqueous suspensions. Mining operations in Chile apply froth flotation for copper sulfide concentration ahead of smelting.
Gravity separation dominates installed capacity; membrane technology climbs the fastest in high-value pharmaceutical and biotechnology process lines.
End User:
Process maturity, regulatory stringency, and margin structure shape equipment specification authority across vertical markets.
- Oil & Gas:Upstream production, midstream transport, and downstream refining each demand specialized separation for crude dehydration, gas processing, and catalyst recovery. Offshore platforms in the Norwegian Continental Shelf specify compact, explosion-proof centrifuge skids to minimize footprint and satisfy NORSOK safety standards.
- Pharmaceuticals:Sterile processing and validation documentation requirements elevate equipment qualification burdens. Fill-finish facilities in Ireland procure membrane filtration trains with full extractables and leachables testing to satisfy EMA marketing authorization requirements.
- Chemical Manufacturing:Commodity and specialty chemical producers balance throughput maximization against solvent recovery economics. Chlor-alkali plants in Louisiana deploy mercury-free membrane cell technology to comply with EPA mercury emission regulations.
- Food Processing:Hygienic design standards and allergen control protocols constrain equipment selection. Dairy cooperatives in New Zealand install self-cleaning disc stack centrifuges for cream separation and bacteria removal in milk standardization.
Oil and gas commands the largest equipment installed base; pharmaceuticals generates the steepest expansion trajectory through bioprocessing capacity additions.
Application:
Fluid composition, contaminant loading, and product value recovery potential dictate technology matching and system sizing.
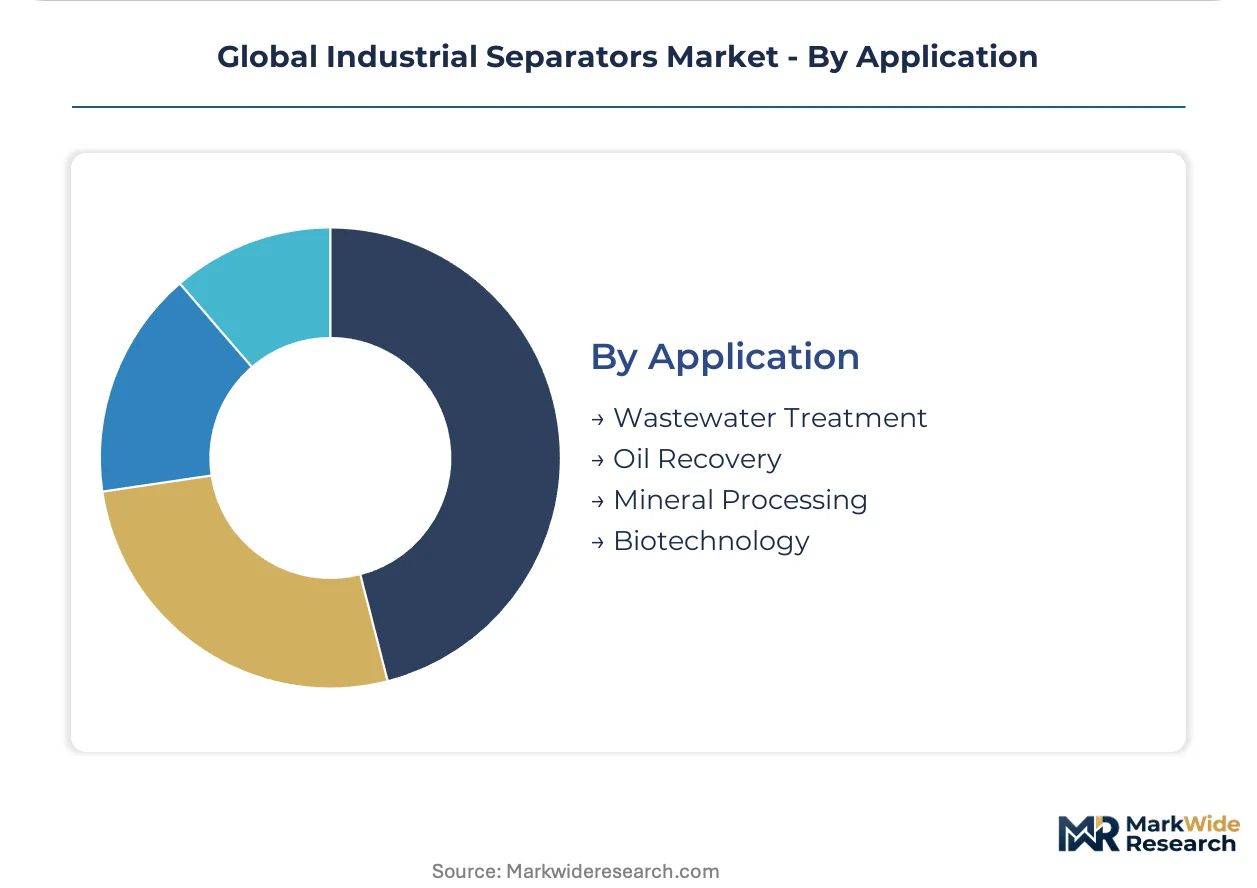
- Wastewater Treatment:Municipal and industrial effluent polishing demands suspended solids removal, nutrient recovery, and pathogen reduction. Advanced membrane bioreactor installations in Singapore achieve water reuse quality for semiconductor fabrication feedstock.
- Oil Recovery:Produced water treatment and crude dehydration determine operational uptime and environmental compliance. Steam-assisted gravity drainage operations in Canada deploy induced gas flotation followed by walnut shell filtration for oil-in-water reduction.
- Mineral Processing:Solid-liquid separation efficiency governs water recycling rates and tailings management costs. Iron ore concentrators in Brazil utilize high-capacity thickeners and filter presses to maximize water recovery in water-scarce regions.
- Biotechnology:Cell harvest, lysate clarification, and product purification require gentle handling of shear-sensitive biological materials. Contract manufacturing organizations in South Korea deploy continuous centrifugation and depth filtration trains for monoclonal antibody production.
Wastewater treatment leads on addressable unit volume; biotechnology leads on value per installed liter of separation capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical manufacturing clusters in North Rhine-Westphalia and Bavaria are driving membrane separator procurement ahead of EU discharge mandates. The report identifies five national markets anchoring equipment demand through 2035.
United States
Gulf Coast petrochemical expansions in Texas and Louisiana are accelerating centrifuge system deployments for catalyst recovery and solvent purification. EPA effluent limitation guidelines compel wastewater treatment facilities across the Ohio River Valley to upgrade membrane bioreactor capacity. Engineering-procurement-construction firms in Houston are consolidating separator specification authority from end-user process engineers.
Germany
Rhine-Ruhr industrial corridor operators are expanding membrane-based procurement ahead of EU Green Deal discharge mandates tightening in 2027. REACH substance restrictions on coatings and elastomers force material reformulation for equipment sold into EU member states. Alfa Laval leverages its Nordic manufacturing proximity to sustain marine and offshore separation system leadership from Hamburg port facilities.
China
Yangtze River Delta chemical manufacturing clusters are upgrading centrifuge systems to meet dual carbon energy-efficiency targets. MEE implements increasingly stringent discharge standards for manufacturing zones in Jiangsu and Zhejiang provinces. Domestic and foreign suppliers face extended GB standard certification timelines for oil content removal equipment in Shanghai pilot free trade zones.
India
Hyderabad and Bangalore pharmaceutical manufacturing corridors are expanding validated separation skid capacity for CDSCO sterile processing compliance. Maharashtra chemical zones deploy gravity thickeners and filter presses for water-scarce region tailings management. Contract manufacturing organizations in Ahmedabad are importing membrane filtration trains with full extractables testing documentation.
Brazil
Minas Gerais iron ore concentrators utilize high-capacity thickeners to maximize water recovery in drought-affected mining regions. ANVISA pharmaceutical regulations drive adoption of dissolved air flotation pre-treatment systems in São Paulo state biotechnology corridors. Offshore platforms in the Campos Basin specify compact centrifuge skids to minimize footprint and satisfy local content requirements.
Global Industrial Separators Market Competitive Environment
Service contract restructuring dominates the current landscape as incumbent centrifuge suppliers defend installed base against membrane technology displacement. The vendor base concentrates around three tiers: diversified engineering conglomerates with captive precision component supply, specialized separation technology houses with deep application expertise, and regional fabricators serving cost-sensitive bulk solids markets. Strategic archetypes include Nordic maritime system specialists, German precision-engineering anchors, and North American integrated flow control conglomerates. Competitive moves center on outcome-based performance guarantees and backward integration into precision bowl assembly manufacturing.
Among diversified engineering groups, Alfa Laval AB and GEA Group AG exemplify the precision-component tier through their respective Nordic and German manufacturing footprints. Andritz AG occupies a position within the specialized technology tier, anchoring pulp and paper recovery applications. These three represent distinct competitive vectors: maritime proximity, captive supply chain control, and vertical application depth.
| Leading Market Players |
|---|
| Alfa Laval |
| GEA Group |
| Schlumberger |
| Andritz AG |
| Flottweg SE |
| Eaton Corporation |
| Parker Hannifin |
| Eriez Manufacturing |
| GIAMAG Technologies |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between marine-class separators and standard industrial units manifests in pricing spreads exceeding raw material cost differentials, while REACH-compliant coating reformulation forces dual sourcing strategies across EU and non-EU supply nodes. Procurement managers in German chemical clusters now specify GB-standard pre-certified skids for Chinese expansion, compressing vendor negotiation leverage through bundled compliance documentation.
Pricing Analysis
Input-cost pass-through from nickel and titanium alloy volatility concentrates in precision-engineered bowl assemblies, where captive foundry capacity insulates Nordic suppliers from spot market swings. Three-tier pricing structure across marine-certified, process-industry standard, and economy-grade bulk solids equipment reflects divergent qualification burdens and aftermarket service bundling. Pricing pressure stems from membrane technology displacement in pharmaceutical applications, forcing centrifuge incumbents to absorb retrofit costs through extended performance guarantees. Municipal wastewater operators exhibit highest price sensitivity due to capital constraint structures, while offshore oil recovery contractors prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Local-content requirements in Brazil's ANVISA pharmaceutical corridors and China's Shanghai pilot free trade zones are reshaping sourcing patterns toward certified domestic fabrication partnerships. Precision bowl assembly manufacturing concentrates in Germany, Sweden, and Japan, drawing from nickel smelter networks in Russia and Canada. Supply chain risk centers on single-source dependency for explosion-proof motor assemblies serving North Sea platforms. Distribution runs through engineering-procurement-construction firms capturing specification authority in US Gulf Coast petrochemical expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Germany's REACH-driven coating reformulation costs and India's CDSCO compliance documentation fees creates margin expansion opportunities for dual-certified suppliers. Divergent regulatory timelines across EU Green Deal mandates and China's dual carbon enforcement windows reward flexible manufacturing footprints.
For Market Incumbents: Extend service contract restructuring into outcome-based performance guarantees defending centrifuge installed base against membrane displacement in biotechnology process lines. Captive supply of precision-engineered bowl assemblies anchors margin control when alloy input volatility concentrates in limited smelter networks. Backward integration into polymer composite housing production captures lightweighting demand from offshore platform specifications. For New Entrants and Emerging Players: Capture modular containerized membrane bioreactor demand from municipal wastewater operators facing capital constraints in US Ohio River Valley EPA compliance upgrades. CDSCO sterile processing validation in Hyderabad and Bangalore pharmaceutical corridors represents the most penetrable white-space target. Partner with established extractables and leachables testing laboratories to accelerate documentation timelines for membrane filtration train procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where multiphysics simulation expertise for high-G separation modeling concentrates in limited engineering pools across Nordic and German precision-engineering clusters. Long-term viability favors specialized separation technology houses with vertical application depth over diversified conglomerates exposed to commodity cyclicality. Watch GB standard certification timeline compression in China as inflection signal for foreign supplier market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Bowl Manufacturing | Captive foundry capacity insulates margins from nickel alloy spot volatility concentrated in Russian and Canadian smelter networks. |
| Outcome-Based Service Contract Restructuring | Performance guarantees defend centrifuge installed base against membrane technology displacement in Massachusetts biopharmaceutical manufacturing. |
| Polymer Composite Housing Platform Expansion | Lightweight corrosion-resistant designs address NORSOK safety standards for compact offshore platform installations. |
| GB Standard Pre-Certification Investment | Accelerated validation timelines unlock procurement pipelines in Shanghai pilot free trade zone chemical manufacturing clusters. |
| Extractables and Leachables Testing Partnership | Documentation bundling satisfies EMA marketing authorization requirements for Irish fill-finish membrane filtration train procurement. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and EPC specification leads with secondary validation from customs trade data, SEC 10-K filings, and ACC industry reports. This study triangulates volume estimates across centrifuge, membrane, and magnetic separator technology classes against capacity announcements from precision component suppliers.
Input-output matrices map equipment deployment to process intensity, regulatory exposure, and fluid characteristics across the projection horizon. Segmentation dimensions include product type, technology mechanism, end-user vertical, and application severity, with CAGRs derived from regression analysis against energy-efficiency mandate enforcement timelines and pharmaceutical capacity expansion announcements. Forecast inputs incorporate EPA effluent limitation guideline implementation schedules and EU Green Deal discharge mandate compliance windows.
Alloy input cost volatility, membrane fouling rate variability in biological process streams, and divergent regional certification timeline compression are the dominant revision risks warranting ongoing watch. A small set of named triggers—including MEE discharge standard enforcement intensity in Jiangsu province and CDSCO sterile processing validation backlog clearance—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Mining Chemicals Market
Industrial Chemicals
Inorganic Coagulants Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Explosion Venting Market
Industrial Chemicals
Detergent Making Machinery Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Bleaching Clay Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Tall Oil Fatty Acid Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Global Battery Grade Lithium Hydroxide Market