
 Mass Finishing Consumables Market | 2026-2036
Mass Finishing Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Mass Finishing Consumables Market Outlook
ISO 14001 environmental management certification is unwinding competitive barriers as smaller compound suppliers face compliance costs that larger rivals absorb more easily. Rösler Group leverages captive ceramic media production across German and Chinese facilities to control input costs. Washington Mills Ceramics anchors North American supply through fused mineral manufacturing in Niagara Falls, New York. Walther Trowal competes on system-media bundling that locks in recurring consumable purchases.
Mass finishing consumables encompass abrasive media, chemical compounds, and polishing agents engineered to specific hardness, density, and particle-size distributions for controlled material removal in vibratory or centrifugal finishing equipment. Ceramic and plastic-bonded abrasives typically range from 1 to 50 mm in nominal diameter, with Mohs hardness selections matched to substrate properties for deburring, radiusing, and surface refinement of machined metal components. Abrasives and compounds capture the majority of value given their recurring replacement cycle, while polishing media commands premium positioning in medical and aerospace end uses where Ra surface roughness below 0.2 micrometers is mandatory. Tumbling media growth outpaces other product categories as automated continuous-flow systems displace batch operations in high-volume automotive and electronics manufacturing.
EPA effluent guidelines in the United States restrict heavy-metal content in spent finishing slurries, pushing compound reformulation toward boron-free and phosphorus-reduced chemistries. ECHA REACH Annex XVII substance restrictions in Europe mandate substitution of crystalline silica in ceramic media, elevating R&D costs for media manufacturers serving EU customers. OSHA permissible exposure limits for metalworking fluids further tighten workplace handling protocols for liquid compounds. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments made for one market may not transfer cleanly to another, fragmenting product portfolios and complicating scale economics.
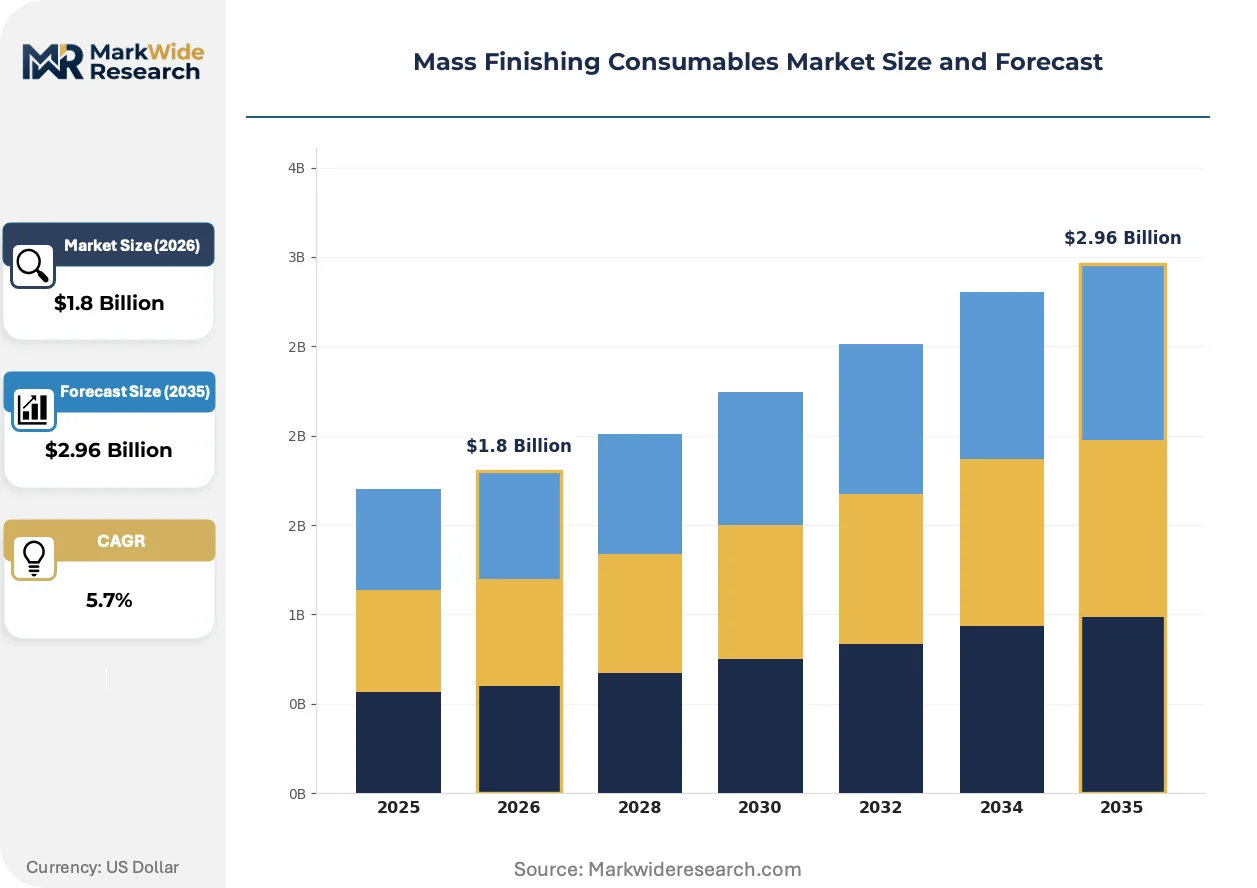
Market Dynamics
REACH chemical restrictions in Europe are forcing compound reformulation across the supply base, while precision finishing requirements from electric drivetrain manufacturing in Germany and Japan pull technical specifications upward simultaneously.
Growth Catalysts
- Electric drivetrain finishing:Automotive OEMs in Germany and Japan demand tighter surface tolerances for motor housings and battery trays, expanding specification ranges for ceramic and plastic-bonded abrasives.
- Biodegradable compound mandates:ECHA REACH Annex XVII substance restrictions accelerate R&D investment in boron-free and phosphorus-reduced chemistries, creating first-mover advantages for compliant suppliers.
- Yangtze River Delta machining clusters:Export-oriented contract manufacturers in China's Jiangsu and Zhejiang provinces concentrate demand for automated continuous-flow finishing systems.
Market Restraints
- Fused mineral input volatility:Washington Mills Ceramics and other North American suppliers face energy cost swings affecting fused aluminum oxide production economics.
- Crystalline silica substitution costs:ECHA REACH mandates eliminate traditional ceramic media formulations, elevating R&D burdens that smaller compound suppliers cannot absorb.
- Heavy-metal effluent compliance:EPA guidelines in the United States restrict spent slurry disposal, forcing capital expenditure on wastewater treatment for job shops.
Strategic Opportunities
- Medical device surface refinement:Aerospace and medical end uses requiring Ra below 0.2 micrometers command premium positioning for polishing media with limited qualified supply.
- System-media bundling models:Equipment manufacturers lock in recurring consumable purchases through integrated service contracts, displacing spot procurement.
- ISO 14001 certification arbitrage:Environmental management compliance creates tiered supplier access, with certified vendors qualifying for automotive OEM direct contracts.
Industry Challenges
- Metalworking fluid exposure protocols:OSHA permissible exposure limits tighten workplace handling requirements for liquid compounds, demanding facility upgrades and training investment.
- Regulatory portfolio fragmentation:Compliance investments for EPA effluent rules do not transfer to ECHA REACH requirements, forcing parallel product development tracks.
- Automated system integration:Batch-to-continuous-flow equipment transitions require process engineering expertise scarce among traditional job shop operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mass Finishing Consumables Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Abrasives, Compounds, Polishing Media, Tumbling Media Application: Deburring, Cleaning, Surface Preparation, Polishing End User: Automotive, Aerospace, Electronics, Medical Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Rösler Group, Washington Mills Ceramics, Walther Trowal, Norican Group, Sinto Group, OTEC Precision Finish, SPALECK GmbH, Kramer Industries, Mass Finishing Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mass Finishing Consumables Market Strategic Shifts
Compound chemistry and media manufacturing are diverging across regulatory jurisdictions, with formulation strategies hardening around geography-specific compliance rather than universal product platforms.
Ceramic media formulations is bifurcating between REACH-compliant silica-free compositions for European markets and legacy formulations serving regions without equivalent restrictions. German automotive suppliers and Japanese precision component manufacturers drive adoption of engineered density gradients for controlled material removal. This technical split is compressing scale economics for multinational media producers forced to maintain parallel production lines.
ECHA REACH Annex XVII crystalline silica restrictions are eliminating traditional ceramic bonding agents from EU-bound product portfolios. Media manufacturers serving European customers absorb elevated R&D costs for alternative mineral binders while managing inventory segmentation. Medical device and aerospace finishing applications in Switzerland and Germany face the tightest substitution timelines given their surface roughness specifications.
Buyer concentration among automated system operators is consolidating consumable procurement through multi-year framework agreements. Tier-one automotive suppliers in Stuttgart and Toyota City bypass distributors for direct compound supply contracts. China's Yangtze River Delta contract manufacturers lag this transition, maintaining spot purchasing through regional trading companies.
Mass Finishing Consumables Market Segmentation
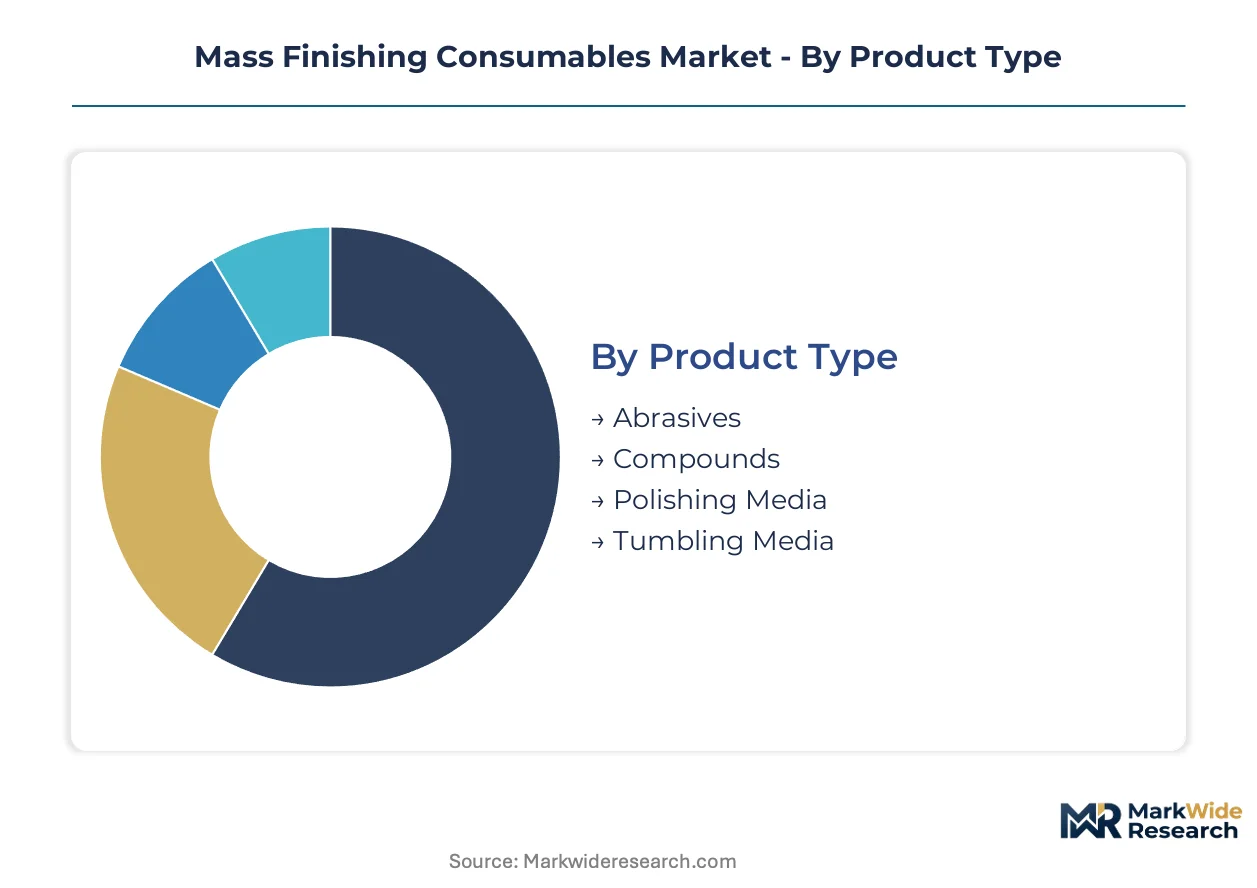
Mass finishing consumables serve heterogeneous technical requirements across precision manufacturing verticals. Segmentation reveals how formulation chemistry, application intensity, and procurement channel structure fragment addressable demand into distinct commercial battlegrounds.
Product Type:
Abrasives concentrate in export-oriented automotive supply chains serving Germany and Japan, while polishing media serves domestic medical device clusters in Switzerland and the United States.
- Abrasives:Ceramic and plastic-bonded abrasives span 1-50 mm nominal diameters with Mohs hardness matched to substrate properties. Demand clusters in Germany's Stuttgart automotive corridor and Japan's Toyota City precision component manufacturers for electric drivetrain finishing. REACH Annex XVII crystalline silica restrictions force parallel formulation tracks for EU-bound versus legacy market supply.
- Compounds:Liquid chemical formulations engineered for specific pH, viscosity, and cutting action in vibratory or centrifugal equipment. Yangtze River Delta contract manufacturers in Jiangsu and Zhejiang provinces absorb volume for export electronics housings, though spot purchasing through regional trading companies persists.
- Polishing Media:Premium-positioned consumables for Ra surface roughness below 0.2 micrometers in medical and aerospace end uses.
- Tumbling Media:Automated continuous-flow system consumables displacing batch operations in high-volume automotive and electronics manufacturing.
Abrasives command the established base. The steepest expansion runs through tumbling media.
Application:
Cost tier stratification separates capital-intensive surface preparation from premium polishing workflows in medical device manufacturing.
- Deburring:Controlled material removal from machined edges using aggressive ceramic media. German automotive OEMs specify tighter tolerances for motor housings and battery trays, expanding ceramic and plastic-bonded abrasive ranges.
- Surface Preparation:Intermediate finishing for coating adhesion or subsequent processing steps. China's Yangtze River Delta machining clusters concentrate demand for automated continuous-flow systems serving export contract manufacturers.
- Cleaning:Compound-driven removal of machining oils, oxides, and particulate contamination from metal substrates.
- Polishing:Final-stage surface refinement to sub-micrometer roughness specifications. Swiss and German medical device manufacturers face the tightest substitution timelines for REACH-compliant silica-free formulations.
Deburring absorbs the volume base. Polishing claims the margin expansion trajectory.
End User:
Customer type fragmentation separates tier-one automotive direct procurement from distributor-mediated job shop supply.
- Automotive:Precision finishing for electric drivetrain components including motor housings, battery trays, and inverter enclosures. German and Japanese OEMs pull technical specifications upward through direct compound supply contracts bypassing distributors.
- Aerospace:Surface refinement to Ra below 0.2 micrometers for turbine blades, structural fasteners, and landing gear components. Limited qualified supply creates premium positioning for compliant polishing media manufacturers.
- Electronics:High-volume finishing of aluminum and magnesium housings for smartphones, laptops, and consumer devices.
- Medical:Implant-grade surface preparation for orthopedic and cardiovascular devices requiring biocompatibility certification.
Automotive anchors volume demand. Medical commands the premium tier expansion.
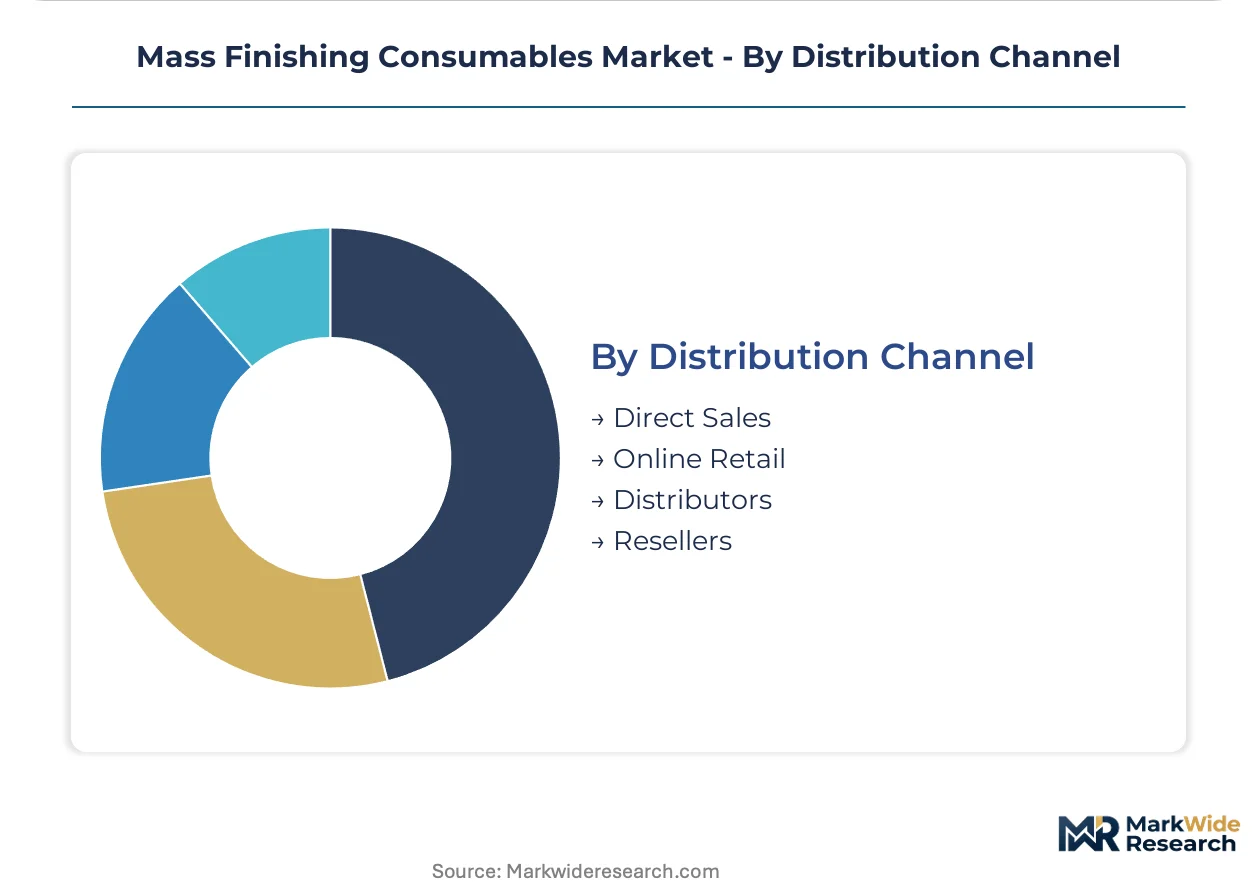
Distribution Channel:
Supply concentration in automated system bundling displaces traditional spot procurement for high-volume end users.
- Direct Sales:Multi-year framework agreements between consumable manufacturers and tier-one automotive suppliers. Stuttgart and Toyota City operations consolidate procurement through integrated service contracts locking in recurring purchases.
- Distributors:Regional inventory holding for job shops and mid-volume manufacturers requiring technical support and mixed-product availability.
- Online Retail:Spot purchasing for standard abrasive grades and commodity compounds by small-scale operators.
- Resellers:Trading company intermediation in China's Yangtze River Delta maintaining spot purchasing patterns among export-oriented contract manufacturers.
Direct sales capture the structural shift. Resellers retain residual fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH Annex XVII crystalline silica restrictions are reshaping formulation strategies across European supply chains, while EPA effluent guidelines in the United States and Japan's precision manufacturing standards pull technical specifications in divergent directions.
United States
EPA effluent guidelines restrict heavy-metal content in spent finishing slurries, forcing compound reformulation toward boron-free chemistries. OSHA permissible exposure limits for metalworking fluids tighten workplace handling protocols nationwide. Washington Mills Ceramics anchors North American fused mineral supply through manufacturing operations in Niagara Falls, New York.
Germany
Automotive OEMs in Stuttgart demand tighter surface tolerances for electric drivetrain motor housings and battery trays. ECHA REACH mandates eliminate traditional ceramic bonding agents from EU-bound product portfolios. Rösler Group leverages captive ceramic media production across German facilities to control input costs for precision component manufacturers.
Japan
Precision component manufacturers in Toyota City specify engineered density gradients for controlled material removal in electric drivetrain finishing. METI industrial standards govern surface roughness specifications for automotive and aerospace applications. Japanese automotive OEMs pull technical specifications upward through direct compound supply contracts that bypass traditional distribution channels.
China
Export-oriented contract manufacturers in Jiangsu and Zhejiang provinces concentrate demand for automated continuous-flow finishing systems. MEE environmental regulations tighten wastewater discharge standards for machining clusters. Yangtze River Delta machining clusters absorb volume for electronics housings serving international consumer device brands.
Switzerland
Swissmedic certification requirements impose strict substitution timelines for REACH-compliant silica-free formulations in medical device finishing. Medical device manufacturers face mandatory Ra surface roughness below 0.2 micrometers for implant-grade orthopedic and cardiovascular components. Swiss precision finishing operations command premium positioning for polishing media with limited qualified supply.
Mass Finishing Consumables Market Competitive Environment
Player mix skews toward integrated equipment-consumable bundlers and specialized media compounders. The market structures around three tiers: multinational system manufacturers with captive consumable supply, regional media specialists with formulation expertise, and commodity distributors serving fragmented job shop demand. Two strategic archetypes dominate competitive positioning: integrated bundlers capturing recurring revenue through service contracts, and formulation specialists defending margin through regulatory compliance capabilities. Capacity expansion in REACH-compliant ceramic media and backward integration into fused mineral production represent the dominant competitive moves.
Among German-integrated bundlers, Rösler Group and Walther Trowal exemplify the system-media bundling archetype that locks in recurring consumable purchases. Washington Mills Ceramics occupies a position among North American mineral processors with upstream control over fused aluminum oxide production. These three companies represent the geographic and structural diversity of competitive positioning: European bundlers, American mineral processors, and Japanese precision specialists each anchor distinct value chain segments.
| Leading Market Players |
|---|
| Rösler Group |
| Washington Mills Ceramics |
| Walther Trowal |
| Norican Group |
| Sinto Group |
| OTEC Precision Finish |
| SPALECK GmbH |
| Kramer Industries |
| Mass Finishing Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term framework agreements between consumable manufacturers and tier-one automotive suppliers lock in both supply access and price visibility across multi-year horizons, insulating compound producers from spot volatility while exposing them to volume-commitment penalties if ECHA REACH reformulation timelines slip.
Pricing Analysis
Cost-plus contracts with fused aluminum oxide indexation anchor North American ceramic media pricing, while three-tier pricing structure across premium, standard, and economy levels segments buyers by ISO 14001 certification status and volume scale. Pricing pressure stems from crystalline silica substitution R&D costs that smaller compound suppliers cannot absorb, compressing margins in the standard tier. Job shops and mid-volume manufacturers show highest price sensitivity, whereas medical device finishers accept premium positioning for REACH-compliant silica-free formulations.
Supply Chain Analysis
Fused mineral processing capacity in Niagara Falls, New York anchors North American ceramic media supply, drawing from bauxite and alumina feedstocks subject to energy cost volatility. Single-source vulnerability concentrates in German captive ceramic production serving Stuttgart automotive corridors, while tariff exposure looms over Yangtze River Delta trading company intermediation. Distribution runs through integrated equipment-consumable bundlers for high-volume automotive, with regional distributors holding inventory for fragmented job shop demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between EPA effluent guidelines and ECHA REACH Annex XVII crystalline silica restrictions fragments product portfolios, creating niche formulation opportunities for compliant specialists.
For Market Incumbents: Fortify backward integration into fused mineral production to control input cost volatility threatening Washington Mills Ceramics and similar processors. Expand REACH-compliant ceramic media capacity in German facilities before Swissmedic certification deadlines tighten, locking in automotive OEM direct contracts that bypass distributor margin capture. For New Entrants and Emerging Players: Differentiate on biodegradable compound chemistry for European medical device finishers facing mandatory substitution timelines. Target China's Yangtze River Delta contract manufacturers with spot-compatible compound formulations, leveraging trading company relationships while tier-one automotive suppliers consolidate procurement through system bundlers. For Investors and Strategic Acquirers: Regional media specialists with captive REACH-compliant formulation expertise present acquisition targets with defensive moats against regulatory fragmentation. Watch for inflection when ECHA expands Annex XVII substance restrictions beyond crystalline silica, forcing parallel R&D investment that consolidates supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fused Mineral Production | Washington Mills Ceramics anchors North American supply through Niagara Falls manufacturing, controlling aluminum oxide input costs. |
| REACH-Compliant Ceramic Media Capacity Expansion | Rösler Group's German facilities capture automotive OEM contracts requiring silica-free formulations for ECHA compliance. |
| System-Media Bundling Service Contracts | Walther Trowal locks in recurring consumable purchases through integrated equipment-consumable agreements with tier-one suppliers. |
| Biodegradable Compound R&D Investment | First-mover advantages accrue to suppliers with boron-free and phosphorus-reduced chemistries ahead of ECHA mandates. |
| ISO 14001 Certification Arbitrage | Environmental management compliance creates tiered supplier access qualifying vendors for direct automotive OEM procurement. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with consumable procurement managers at tier-one automotive suppliers, plant engineers at Yangtze River Delta contract manufacturers, technical R&D directors at compound formulators, and aftermarket service heads at equipment bundlers. Secondary validation drew from EPA effluent guideline filings, ECHA REACH Annex XVII substance restriction databases, SEC 10-K disclosures from fused mineral processors, and customs trade data for ceramic media imports. Bottom-up volume modeling triangulated against top-down market sizing across product type, application intensity, and end-user procurement channel segmentation.
Across the analysis window, the analytical framework modeled consumable demand by product chemistry tier, end-use vertical precision requirements, equipment automation level, and regional regulatory cluster. CAGRs were derived from segment-level volume trajectories weighted by pricing stratification across premium REACH-compliant, standard legacy-formulation, and economy spot-procurement tiers. Forecast inputs included electric drivetrain penetration rates in German and Japanese automotive, and automated continuous-flow system displacement of batch operations in high-volume electronics manufacturing.
Forecasts assume regulatory continuity in EPA effluent guidelines and ECHA REACH Annex XVII enforcement; material policy shifts would require re-modeling compound chemistry substitution timelines and ceramic media formulation segmentation. Practitioners should keep alternative scenarios live as crystalline silica restriction expansion and biodegradable compound mandate acceleration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Industrial Closures Market
Industrial Chemicals
Asia-Pacific Bio Transformer Oil Market
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Chemical Process Mixers Market
Industrial Chemicals
Industrial Phosphate Market
Industrial Chemicals
Cryogenic Column Market
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
2-Ethylhexanol (2-EH) Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Decahydronaphthalene (Decalin) Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Global Isocyanate Market