
 1-Octanol Market | 2026-2036
1-Octanol Market Size, Share, and Industry Trends Forecast 2026-2036
1-Octanol Market Analysis
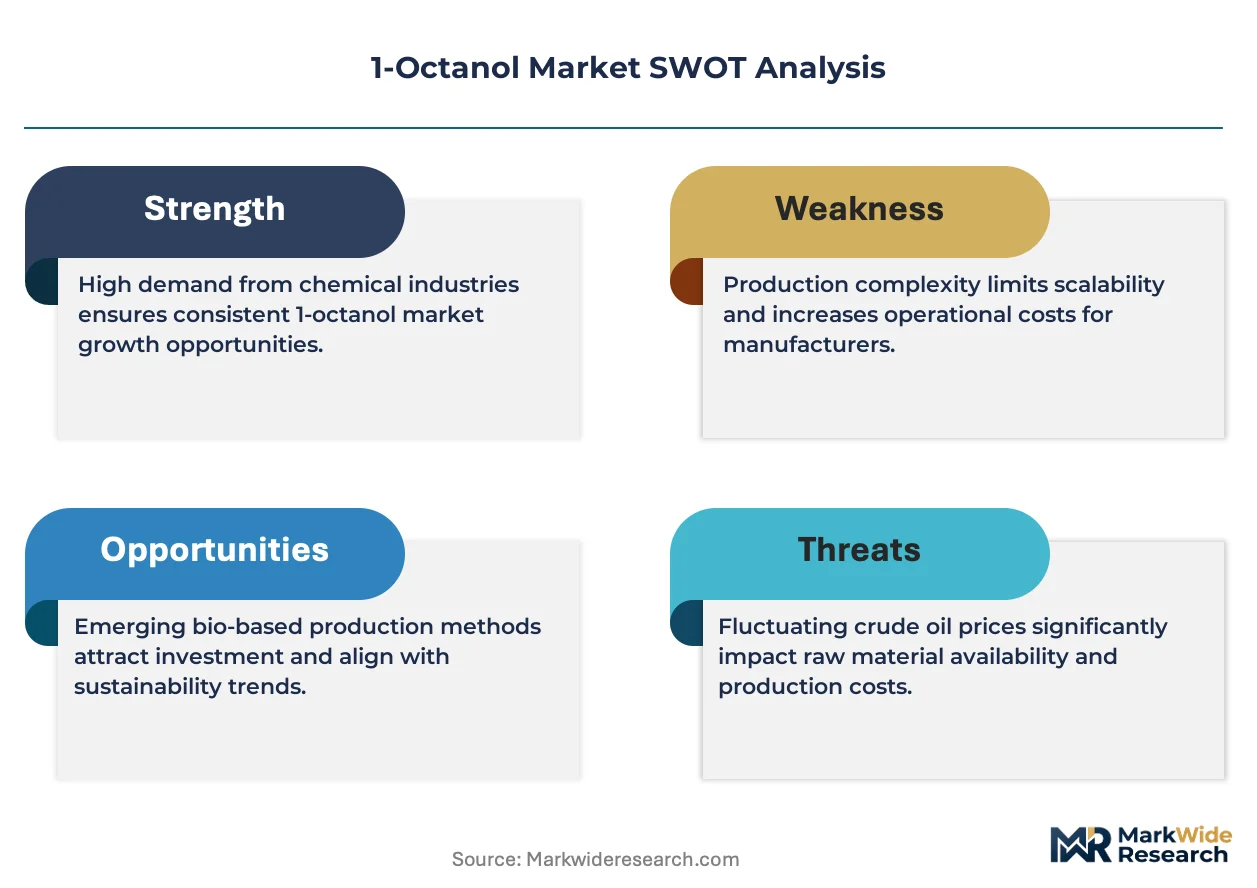
Personal care and fragrance formulation is consolidating as the dominant demand channel for high-purity 1-octanol, displacing slower-growing industrial solvent offtake. Sasol Limited leverages its Fischer-Tropsch feedstock integration to sustain cost leadership in purified grades across European markets. Kao Corporation anchors its position through captive surfactant demand in Japan and Southeast Asia. Emery Oleochemicals specializes in oleochemical-derived 1-octanol, competing on renewable carbon content credentials against petrochemical rivals.
1-Octanol is a saturated fatty alcohol with an eight-carbon straight-chain structure, typically produced via hydroformylation of heptene or hydrogenation of caprylic acid, exhibiting a boiling point of 195°C and limited water solubility at 0.5 g/L. Its primary industrial purpose centers on serving as a chemical intermediate for ester-based plasticizers, fragrance compounds, and ethoxylated surfactants. Purified 1-octanol commands premium positioning in fragrance and personal care applications where odor specifications are stringent, while technical grade material occupies volume-driven solvent and additive markets with thinner margin pools. Surfactant applications represent the fastest-expanding segment as formulators seek biodegradable alternatives to petrochemical-derived emulsifiers.
REACH registration requirements in Europe, FDA oversight of food-contact and cosmetic applications in the United States, and China's GB standards for chemical purity collectively shape product specifications and market access conditions for 1-octanol suppliers. ECHA's evolving restrictions on hazardous substance classifications are pushing producers to document supply chain transparency and impurity profiles more rigorously. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
Personal care formulators are consolidating specifications around high-purity 1-octanol grades, tightening impurity tolerances for odor-critical fragrance applications while displacing technical-grade solvent offtake. REACH registration deadlines are compressing qualification timelines for new suppliers entering European cosmetic markets.
Growth Catalysts
- Biodegradable surfactant mandates:Formulators in Germany and France are substituting petrochemical emulsifiers with ethoxylated 1-octanol derivatives to meet EU Green Deal targets for aquatic toxicity reduction.
- Fischer-Tropsch integration:Synthetic fuel producers are repurposing C8 alcohol streams from gas-to-liquid plants into cosmetic-grade material, expanding purified supply without dedicated oleochemical investment.
- REACH compliance premiums:ECHA's updated impurity disclosure requirements are rewarding registered suppliers with documented supply chain transparency, creating preference windows against unregistered imports.
Market Restraints
- Palm kernel oil volatility:Oleochemical-derived 1-octanol faces margin compression when Malaysian feedstock prices spike, exposing natural alcohol producers to agricultural commodity cycles.
- Rhine corridor concentration:Specialty purification capacity clusters around Ludwigshafen and Leverkusen, creating geographic single-point vulnerability for European cosmetic-grade supply.
- Linear alcohol substitution:C10-C12 mid-cut alcohols from ethylene oligomerization are capturing share in industrial solvent applications where odor specifications are less stringent.
Strategic Opportunities
- India personal care expansion:BIS certification pathways for imported cosmetic-grade material remain underpenetrated, offering first-mover advantage to REACH-registered European suppliers.
- Renewable carbon labeling:Mass-balance certification under ISCC PLUS is enabling premium positioning for bio-attributed 1-octanol in prestige fragrance formulations.
- Direct-to-compounder distribution:Bypassing traditional distributor networks allows producers to capture formulation technical service revenue and secure multi-year offtake commitments.
Industry Challenges
- Gas chromatography expertise scarcity:Analytical chemists capable of validating sub-ppm odor-active impurity profiles are concentrated among legacy fragrance houses, constraining independent producer qualification speed.
- Multipurpose reactor retrofit costs:Converting existing hydrogenation assets to cosmetic-grade 1-octanol service requires stainless steel upgrades and dedicated cleaning protocols that strain mid-cap capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1-Octanol Market |
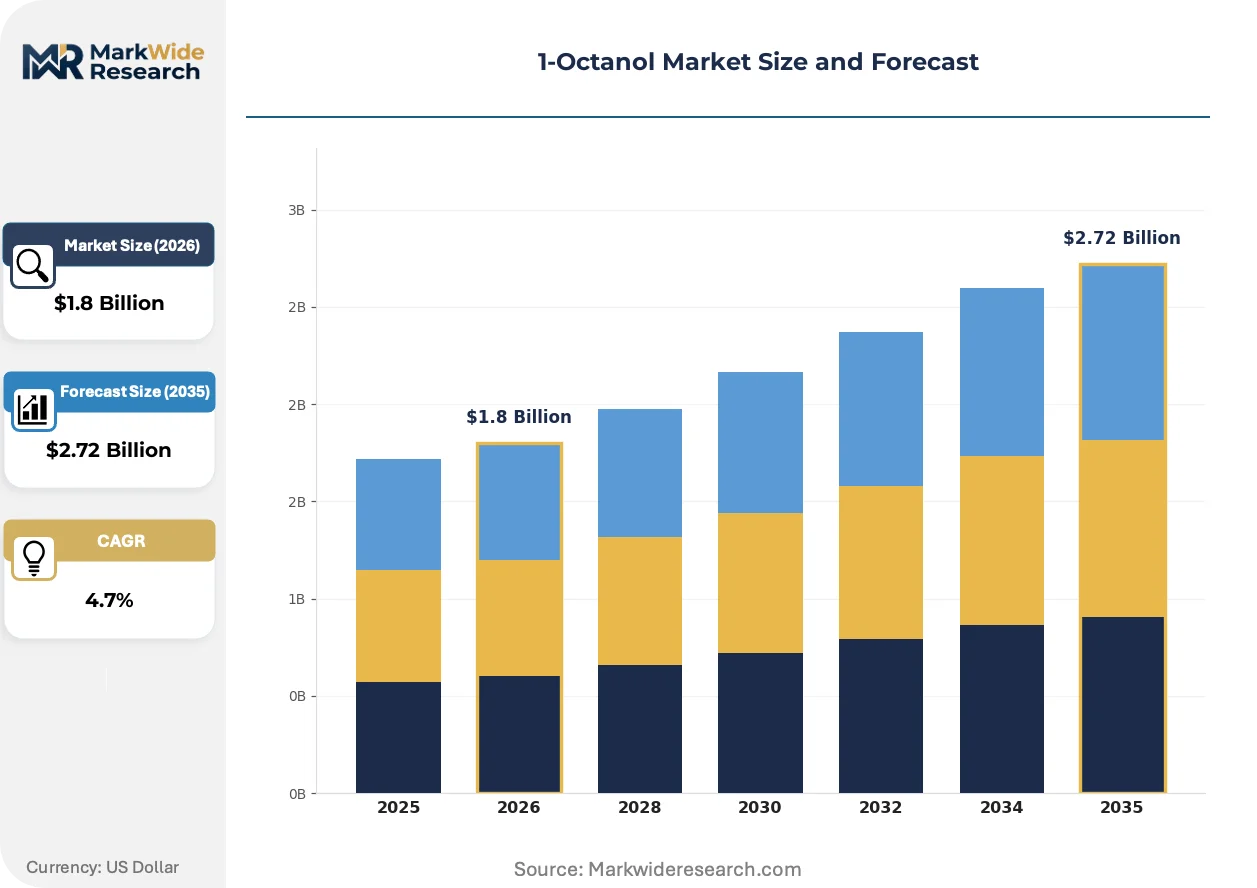
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purified 1-Octanol, Technical Grade, Mixed Isomers, Octyl Alcohol Application: Fragrance, Solvents, Surfactants, Additives End User: Personal Care, Industrial, Chemical, Food Additives Packaging Type: Drums, Bulk, Bottles, Tanker Trucks |
| Companies Covered | Sasol Limited, BASF SE, Kao Corporation, Ecogreen Oleo, PTT Global Chemical, Musim Mas, KLK Oleo, Emery Oleochemicals, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1-Octanol Market Emerging Trajectories
Process intensification and regulatory disclosure automation are compressing development cycles for 1-octanol derivatives. Formulators now demand real-time carbon footprint data alongside traditional certificates of analysis.
Membrane pervaporation for water removal from crude alcohol streams is absorbing capital investment from thermal distillation retrofits. Japanese surfactant producers are piloting these units to reduce energy intensity in C8 alcohol finishing. The technology is absorbing margin pressure from natural gas price volatility by cutting steam demand per ton of purified output.
REACH's SCIP database requirements for articles containing substances of very high concern are forcing downstream documentation of 1-octanol-derived plasticizers in polymer applications. Suppliers must now provide granular composition data to compounders. Fragrance houses with established regulatory affairs infrastructure are capturing preferential supply terms from producers seeking compliant distribution channels.
Fragrance compounders are consolidating supplier panels around vertically integrated alcohol producers capable of delivering lot-specific sensory profiles. Smaller regional distributors are losing shelf space to direct relationships with purification specialists. This consolidation is most visible in Germany, where four major fragrance houses now account for the majority of high-purity 1-octanol procurement volume.
1-Octanol Market Segmentation
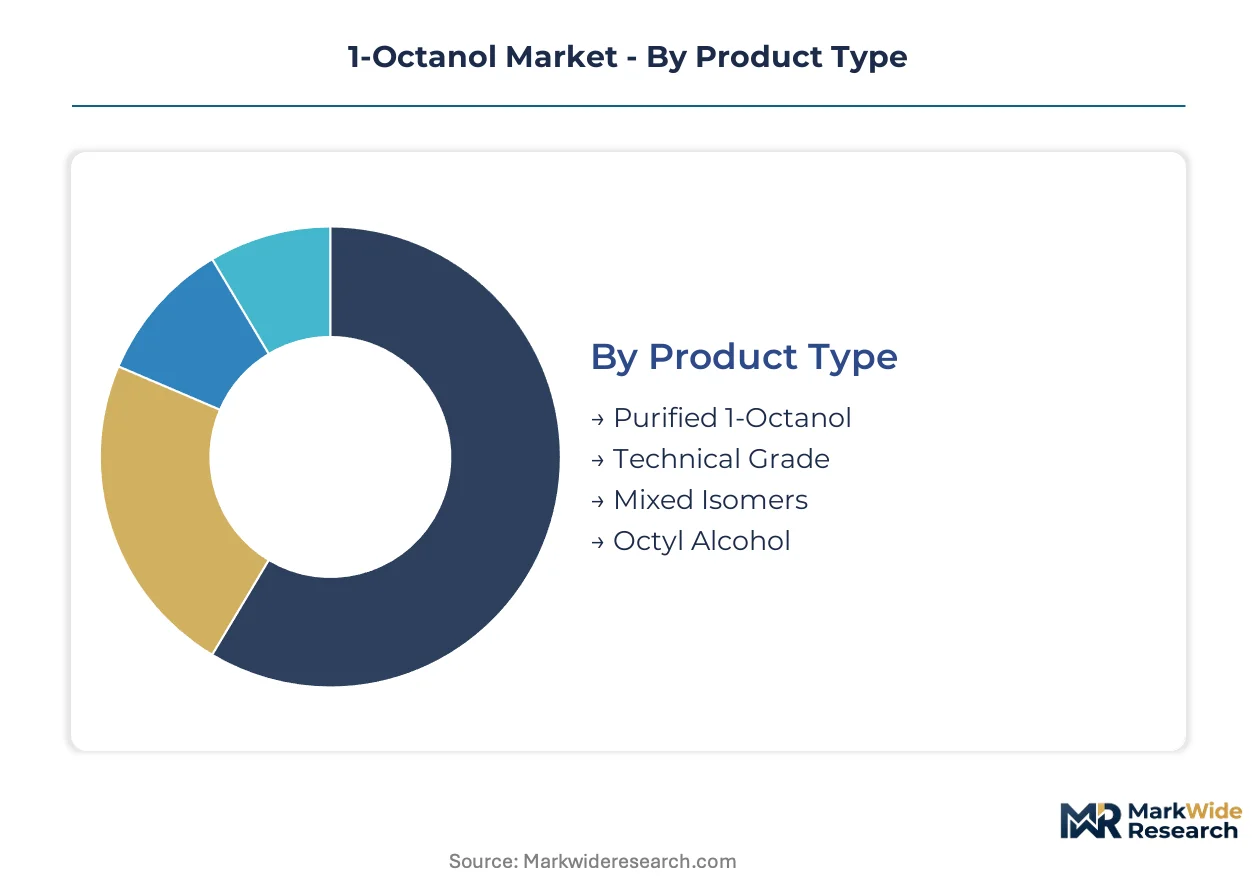
Segmentation in the 1-Octanol market separates certification-heavy cosmetic grades from commodity solvent material. Each tier commands distinct margin pools and faces divergent regulatory scrutiny from ECHA, FDA, and BIS.
Product Type:
Purified grades require REACH registration and FDA cosmetic ingredient listing; technical grades face lighter documentation burdens.
- Purified 1-Octanol:Sub-ppm odor-active impurity specifications validated through gas chromatography. Fragrance houses in Germany and France consolidate procurement around REACH-registered suppliers with documented supply chain transparency. ECHA's updated disclosure requirements compress qualification timelines for unregistered imports.
- Technical Grade:Broader impurity tolerances acceptable for industrial solvent applications. Demand concentrates in German chemical manufacturing clusters along the Rhine corridor where odor specifications are less stringent. C10-C12 mid-cut alcohols from ethylene oligomerization capture share in these volume-driven markets.
- Mixed Isomers:Branched-chain C8 alcohol blends serving cost-sensitive surfactant feedstock markets.
- Octyl Alcohol:Generic designation covering both synthetic and natural-origin C8 alcohols in trade documentation.
Leading the category by volume: Technical Grade. Growing fastest: Purified 1-Octanol.
Application:
Margin structures diverge sharply between premium fragrance formulation and commodity solvent offtake.
- Fragrance:Stringent odor specifications demand lot-specific sensory profiles. Four major fragrance houses in Germany now account for the majority of high-purity procurement volume, consolidating supplier panels around vertically integrated alcohol producers.
- Solvents:Volume-driven applications in coatings and cleaning formulations where price sensitivity dominates supplier selection.
- Surfactants:Ethoxylated 1-octanol derivatives displace petrochemical emulsifiers under EU Green Deal aquatic toxicity mandates. Formulators in Germany and France lead substitution efforts.
- Additives:Plasticizer and processing aid applications requiring REACH SCIP database documentation for downstream polymer compounders.
Surfactants climb the fastest as biodegradable mandates tighten; fragrance holds the premium margin tier.
End User:
Customer sophistication determines specification stringency and contract structure complexity.
- Personal Care:BIS certification pathways for imported cosmetic-grade material remain underpenetrated in India, offering first-mover advantage to REACH-registered European suppliers.
- Industrial:Technical-grade offtake from coatings, adhesives, and metalworking fluid compounders with thinner margin pools.
- Chemical:Intermediate demand for ester-based plasticizers and specialty derivatives serving polymer and agrochemical synthesis.
- Food Additives:FDA food-contact oversight restricts supplier qualification to documented GRAS status holders.
Personal care commands the steepest premium; industrial absorbs the highest shipment volumes.
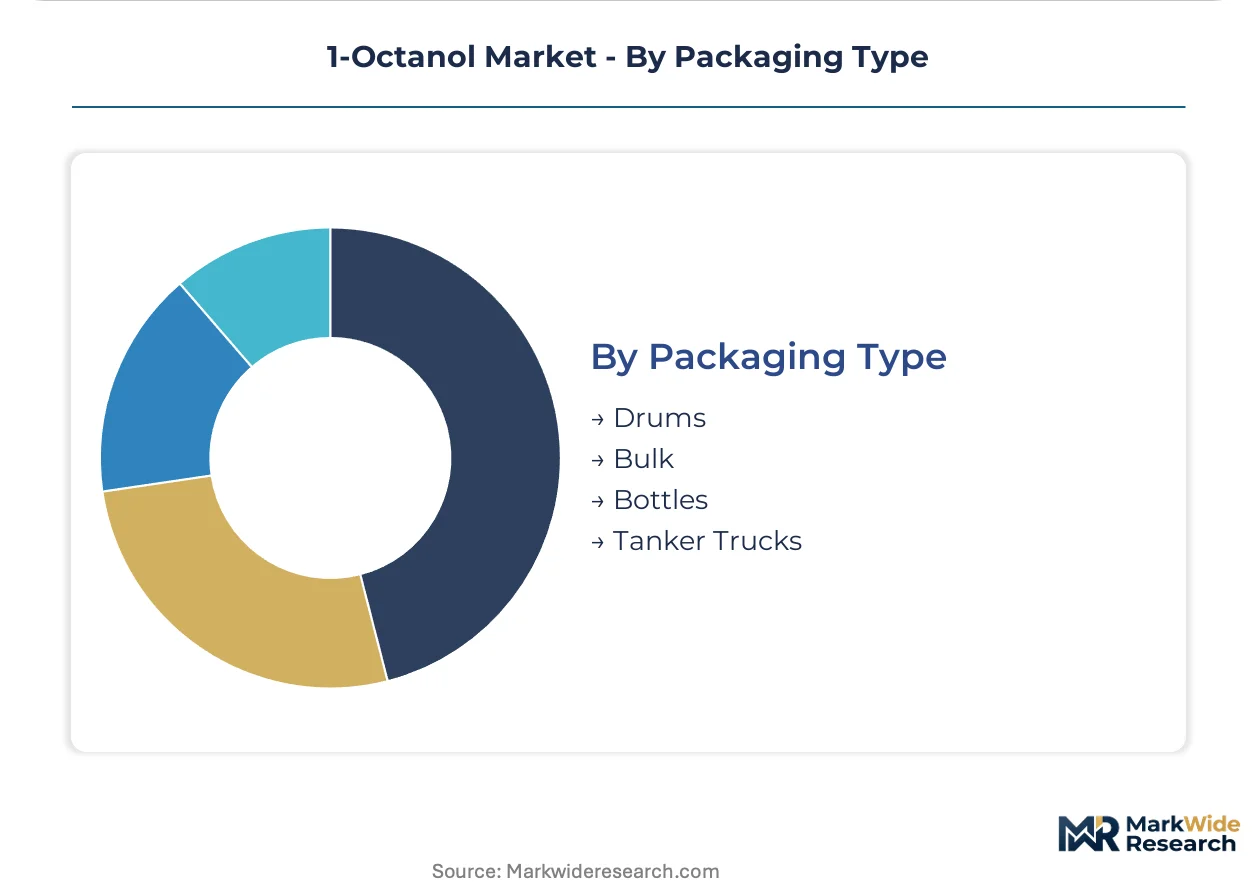
Packaging Type:
Logistics configuration tracks customer scale and handling infrastructure sophistication.
- Drums:Standard 200-liter steel containers serving mid-scale compounders without bulk unloading capability.
- Bulk:ISO tank and flexitank deliveries to fragrance houses and surfactant producers with dedicated storage.
- Bottles:Laboratory and pilot-scale quantities for formulation development and quality validation.
- Tanker Trucks:Direct-to-plant deliveries for high-volume industrial solvent consumers with on-site tank farms.
Bulk shipments dominate purified grade movements; drums retain industrial solvent share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhine industrial corridor tax incentives and special economic zone status in Germany concentrate European purification capacity for cosmetic-grade material.
Germany
Specialty chemical producers cluster around Ludwigshafen and Leverkusen to serve fragrance houses consolidating supplier panels. REACH registration deadlines compress qualification timelines for cosmetic-grade imports. ECHA's updated impurity disclosure requirements reward registered suppliers with documented supply chain transparency.
France
Formulators in the Paris region and Lyon chemical basin substitute petrochemical emulsifiers with ethoxylated 1-octanol derivatives under EU Green Deal mandates. ANSM oversight of cosmetic ingredient safety tightens documentation burdens for imported material. The Normandy petrochemical corridor repurposes existing hydrogenation assets for purified alcohol finishing.
United States
FDA cosmetic ingredient listing requirements restrict supplier qualification to documented GRAS status holders serving personal care compounders in New Jersey and California. EPA oversight of industrial solvent applications maintains lighter documentation burdens for technical-grade offtake. Gulf Coast Fischer-Tropsch producers expand purified supply without dedicated oleochemical investment.
Japan
METI's biodegradable surfactant guidelines accelerate ethoxylated 1-octanol adoption among Kansai-region formulators. PMDA oversight of cosmetic applications maintains stringent purity specifications. Osaka-based surfactant producers pilot membrane pervaporation units to reduce energy intensity in C8 alcohol finishing.
India
BIS certification pathways for imported cosmetic-grade material remain underpenetrated, offering first-mover advantage to REACH-registered European suppliers. Maharashtra and Gujarat chemical corridors absorb technical-grade solvent offtake from coatings and adhesives compounders. CDSCO's evolving cosmetic regulations anticipate alignment with EU purity standards.
1-Octanol Market Vendor Landscape
Top-tier vendors anchor the purified-grade segment, while mid-cap specialists occupy technical-grade and regional distribution tiers. The vendor base stratifies across Fischer-Tropsch-integrated synthetics, oleochemical-derived naturals, and captive surfactant consumers. Three archetypes dominate: backward-integrated petrochemical majors, palm oil-linked oleochemical processors, and fragrance-house captives. Capacity expansion and direct-to-compounder distribution represent the two dominant competitive moves reshaping channel economics.
Within the Fischer-Tropsch integration tier, Sasol Limited and SABIC exemplify synthetic production archetypes leveraging gas-to-liquid feedstock streams. Among oleochemical specialists, Emery Oleochemicals and KLK Oleo occupy positions competing on renewable carbon content credentials. Kao Corporation anchors the captive-demand archetype through in-house surfactant consumption in Japan and Southeast Asia.
| Leading Market Players |
|---|
| Sasol Limited |
| BASF SE |
| Kao Corporation |
| Ecogreen Oleo |
| PTT Global Chemical |
| Musim Mas |
| KLK Oleo |
| Emery Oleochemicals |
| SABIC |
| Others |
Supply Flow & Price Mechanics
Malaysian palm kernel oil futures cascade through oleochemical 1-octanol cost structures, compressing margins for natural alcohol producers when feedstock spikes while Fischer-Tropsch synthetics maintain pricing stability through gas-to-liquid feedstock integration. REACH registration premiums and FDA cosmetic-grade certifications stratify pricing tiers, with documented supply chain transparency commanding measurable premiums over unregistered imports.
Pricing Analysis
Short lead-time premiums of 15-20% apply to cosmetic-grade 1-octanol for fragrance houses facing compressed qualification timelines under ECHA deadlines. Three-tier pricing structure separates REACH-registered purified grades from technical solvent material and mixed-isomer feedstocks, with certification level and volume scale as primary differentiation drivers. Cost compression in technical-grade solvent markets intensifies because C10-C12 mid-cut alcohols from ethylene oligomerization capture industrial share. Industrial solvent buyers exhibit highest price sensitivity; fragrance compounders absorbing premium grades demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates in India's BIS certification pathways reshape sourcing patterns, rewarding REACH-registered European suppliers with first-mover positioning against unregistered imports. Purified-grade production concentrates in Germany, South Africa, and Japan, drawing from Fischer-Tropsch syngas, palm kernel oil, and petroleum-derived heptene feedstocks respectively. Single-source vulnerability concentrates around the Rhine corridor purification cluster serving German fragrance houses. Distribution runs through direct-to-compounder relationships for premium grades and traditional chemical distributor networks for technical solvent volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into Fischer-Tropsch syngas or captive palm oil processing defines competitive positioning, as feedstock control separates margin leaders from price-takers exposed to agricultural commodity cycles.
For Market Incumbents: Cement qualification speed advantages by embedding gas chromatography expertise directly within production facilities, reducing dependency on legacy fragrance house analytical services. Expand membrane pervaporation finishing capacity to cut energy intensity and defend margin position against natural gas price volatility. Prioritize ISCC PLUS mass-balance certification to capture renewable carbon premiums in prestige fragrance formulations.
For New Entrants and Emerging Players: Membrane pervaporation technology-first wedge opens technical service revenue streams through direct-to-compounder distribution models bypassing traditional chemical distributors. Target India's underpenetrated BIS certification pathway for imported cosmetic-grade material, where REACH-registered European suppliers currently hold limited presence. Lead with formulation technical service capabilities to secure multi-year offtake commitments from personal care compounders.
For Investors and Strategic Acquirers: The window for entry favors Fischer-Tropsch-integrated synthetics and oleochemical processors with documented supply chain transparency infrastructure. Long-term viability hinges on regulatory compliance capabilities spanning REACH, FDA, and emerging GB standards alignment. Watch ECHA's evolving SCIP database requirements as the inflection indicator for downstream documentation burdens reshaping supplier preference.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fischer-Tropsch Syngas | Sasol and SABIC anchor cost leadership through gas-to-liquid feedstock control. |
| Membrane Pervaporation Capacity Addition | Japanese surfactant producers cut steam demand per ton of purified C8 alcohol output. |
| ISCC PLUS Mass-Balance Certification | Emery Oleochemicals and KLK Oleo compete on renewable carbon credentials. |
| Direct-to-Compounder Distribution Bypass | Fragrance houses in Germany consolidate supplier panels around purification specialists. |
| REACH-Registered Supply Chain Transparency | ECHA's updated disclosure requirements reward documented impurity profiles. |
Methodological Framework
Independent corroboration across fragrance house procurement directors, surfactant producer technical R&D leads, oleochemical plant managers, and Fischer-Tropsch operations specialists underwrites the qualitative findings in this study. Secondary validation draws from ECHA registration databases, FDA cosmetic ingredient listings, customs and trade flow data, and SEC filings from publicly traded chemical producers. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down capacity assessments from major production facilities.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects, with segmentation modeling spanning grade tier, application, end-use industry, and regional production hub. CAGRs derive from curve-fitting approaches applied to historical consumption data and forward-looking capacity expansion announcements. Forecast inputs incorporate REACH registration timelines, EU Green Deal biodegradable surfactant mandates, and palm kernel oil price volatility assumptions.
Several conditions sit outside the modeled scope, including unforeseen regulatory divergence between ECHA and FDA cosmetic ingredient standards, abrupt feedstock price shocks from Malaysian palm oil supply disruptions, and technological substitution by C10-C12 mid-cut alcohols in industrial applications. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Vacuum Degreasers Market
Industrial Chemicals
Tallow Fatty Acid Market
Industrial Chemicals
Global Neopentyl Glycol Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Multi Component Injection Moulding Technology Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Defatting Systems Market
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Trimethylolpropane (TMP) Market