
 Hazardous Chemicals Packaging Market | 2026-2036
Hazardous Chemicals Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Hazardous Chemicals Packaging Market Foresight
Capital-intensity divergence between integrated drum recyclers and regional blow-molders is rotating procurement leverage toward asset-heavy suppliers. Greif, Inc. leverages its closed-loop reconditioning network across North America to lock in multi-year supply contracts with agrochemical formulators. Mauser Packaging Solutions anchors European demand through captive steel drum production and captive IBC refurbishment facilities. Schutz GmbH & Co. KGaA dominates intermediate bulk container engineering with proprietary composite layering technology that exceeds UN performance tests.
Hazardous chemicals packaging encompasses engineered containment systems designed to prevent leakage, corrosion, and reaction during transport and storage of toxic, flammable, or reactive substances, typically constructed with multi-layer polymer barriers, epoxy-coated steel, or borosilicate glass rated for specific UN packing group classifications. These systems serve the primary purpose of ensuring occupational safety, environmental protection, and regulatory compliance across supply chains handling regulated substances. Drums retain the largest volume share in base chemical logistics, though IBCs are capturing share in pharmaceutical intermediate distribution where cube efficiency reduces freight cost per liter. Composite materials are expanding fastest in corrosive chemical applications where polyethylene-steel hybrid construction outperforms monolithic alternatives in drop and stack testing, while glass bottling remains concentrated in analytical reagent and laboratory end users where inertness and visibility are non-negotiable.
EPA hazardous waste manifest requirements and DOT 49 CFR hazardous materials regulations govern container construction, testing, and marking in the United States, forcing manufacturers to maintain certified quality management systems as a condition of market access. REACH compliance and the EU Packaging and Packaging Waste Directive impose substance restrictions and extended producer responsibility obligations on suppliers serving European chemical manufacturers. Forward-looking stakeholders must monitor the trajectory of UN Model Regulation revisions and their adoption timelines across national dangerous goods codes to anticipate redesign cycles and testing investments.
Market Dynamics
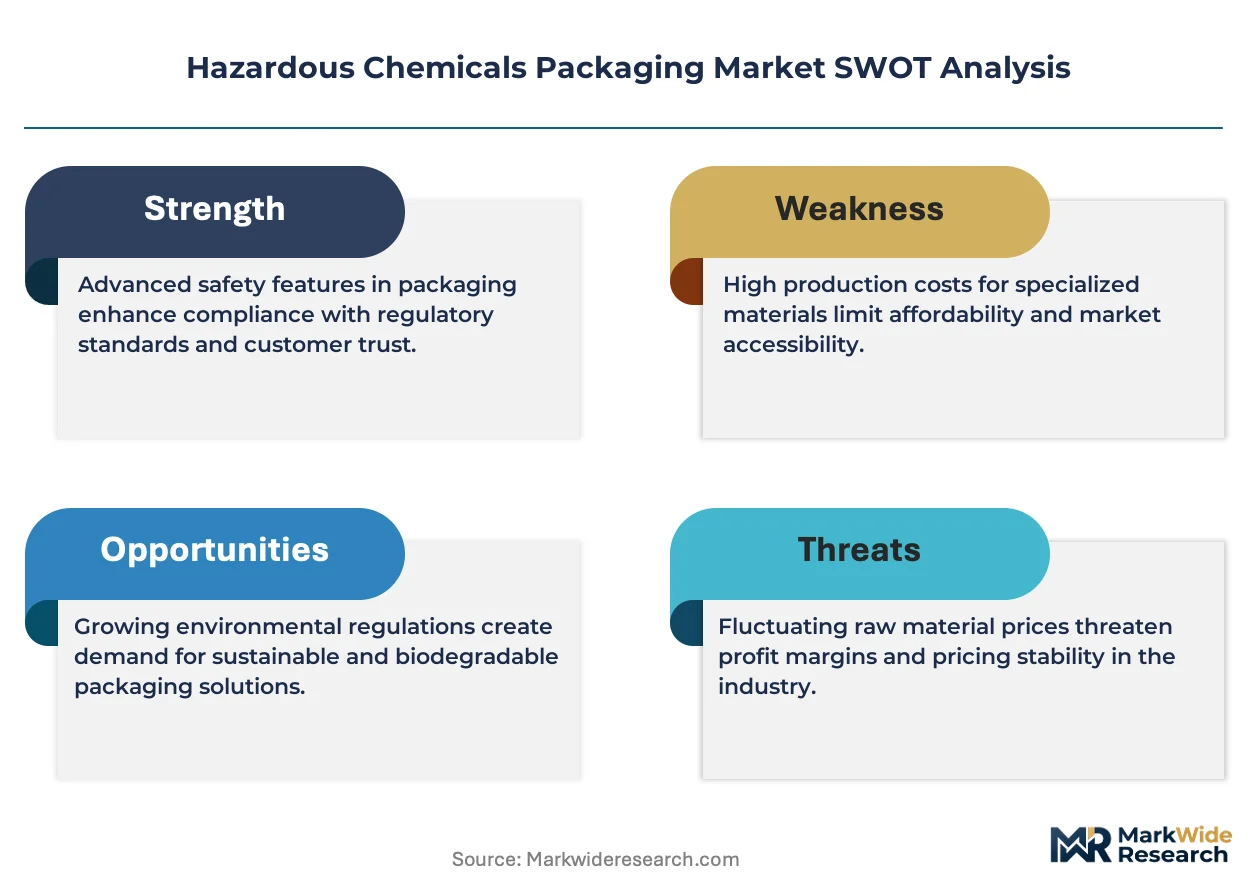
UN Model Regulation harmonization cycles are compressing redesign timelines for hazardous chemicals packaging manufacturers, forcing simultaneous compliance investments across multiple national dangerous goods codes.
Growth Catalysts
- Agrochemical Export Expansion:Brazilian formulators require ANVISA-certified composite IBCs for cross-border pesticide shipments, pulling demand for UN-certified multi-trip containers.
- REACH Substance Restrictions:ECHA's tightening limits on heavy metals in packaging coatings accelerate replacement cycles for legacy steel drums across EU chemical corridors.
- Polymer-Steel Hybrid Engineering:Advanced co-extrusion bonding techniques enable thinner-walled composite drums that pass drop tests at reduced tare weight, cutting freight costs per unit.
Market Restraints
- Steel Price Volatility:Hot-rolled coil fluctuations in Germany's Rhine-Ruhr corridor compress drum fabricator margins during contract renegotiations with KBA-regulated logistics providers.
- Recertification Bottlenecks:UN performance testing queue times at notified bodies extend 14-18 weeks, freezing new product launches for corrosive chemical applications.
- Flexible Intermediate Bulk Container Substitution:FIBC liner systems with barrier films capture low-risk chemical powder volumes previously locked into rigid IBC formats.
Strategic Opportunities
- India Agrochemical Formalization:CDSCO-aligned state licensing boards mandate UN-certified packaging for registered pesticide manufacturers, opening demand in Gujarat and Maharashtra chemical clusters.
- Digital Twin Integration:IoT-enabled drum tracking converges with blockchain manifest systems to create auditable custody chains for EPA hazardous waste generators.
- Refurbishment Network Gaps:Underdeveloped reconditioning infrastructure in Southeast Asian port zones creates first-mover advantage for closed-loop service models.
Industry Challenges
- Multi-Jurisdiction Testing Overlap:DOT 49 CFR, ADR, and IMDG certification requirements for identical drum specifications triple qualification costs without harmonized mutual recognition.
- Specialized Welder Scarcity:Epoxy-lined steel drum production requires certified corrosion-resistant welding technicians, a skill pool concentrated in legacy industrial regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazardous Chemicals Packaging Market |
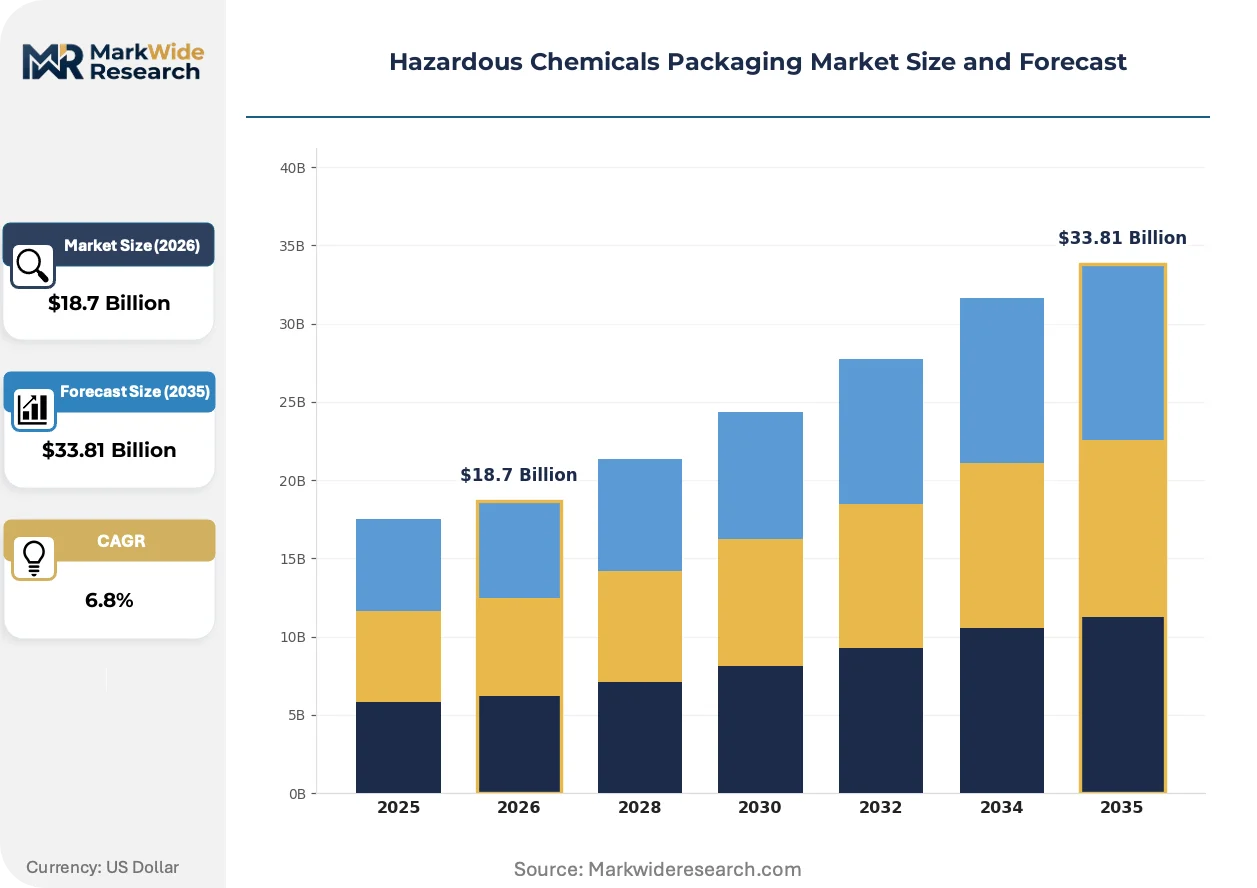
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drums, Bottles, Pails, IBCs Material: Polyethylene, Steel, Glass, Composite End User: Chemical Manufacturers, Pharmaceutical Companies, Oil & Gas, Laboratories Package Design: Single-Use, Reusable, Stackable, Modular |
| Companies Covered | Greif, Inc., Mauser Packaging Solutions, Schutz GmbH & Co. KGaA, THIELMANN US LLC, Berlin Packaging, Sonoco Products Company, Amcor plc, Precision IBC, Inc., Time Technoplast Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazardous Chemicals Packaging Market Shifts & Advancements
Material science advances and regulatory digitization are restructuring competitive advantage around testing velocity and circular service capabilities rather than pure manufacturing scale.
Multi-layer fluoropolymer barrier films are displacing monolithic high-density polyethylene in corrosive acid packaging. Specialty chemical distributors in Germany's KBA-regulated transport corridors adopt these laminates at accelerated rates. The technology is displacing conventional drum specifications in sulfuric and hydrochloric acid logistics where permeation resistance determines compliance.
EU Packaging and Packaging Waste Directive extended producer responsibility obligations now mandate financing mechanisms for container collection and recycling. Chemical manufacturers face pass-through cost structures for drum recovery services. REACH-registered substance volumes above 1,000 tonnes annually trigger the strictest packaging traceability requirements, compressing supplier qualification windows.
Leasing-based drum management contracts replace outright purchase for agrochemical formulators seeking working capital efficiency. Third-party pooling operators assume cleaning, testing, and redeployment burdens previously handled in-house. This model concentrates fastest in Brazil's ANVISA-regulated pesticide sector where seasonal demand spikes strain owned-fleet utilization.
Hazardous Chemicals Packaging Market Segmentation
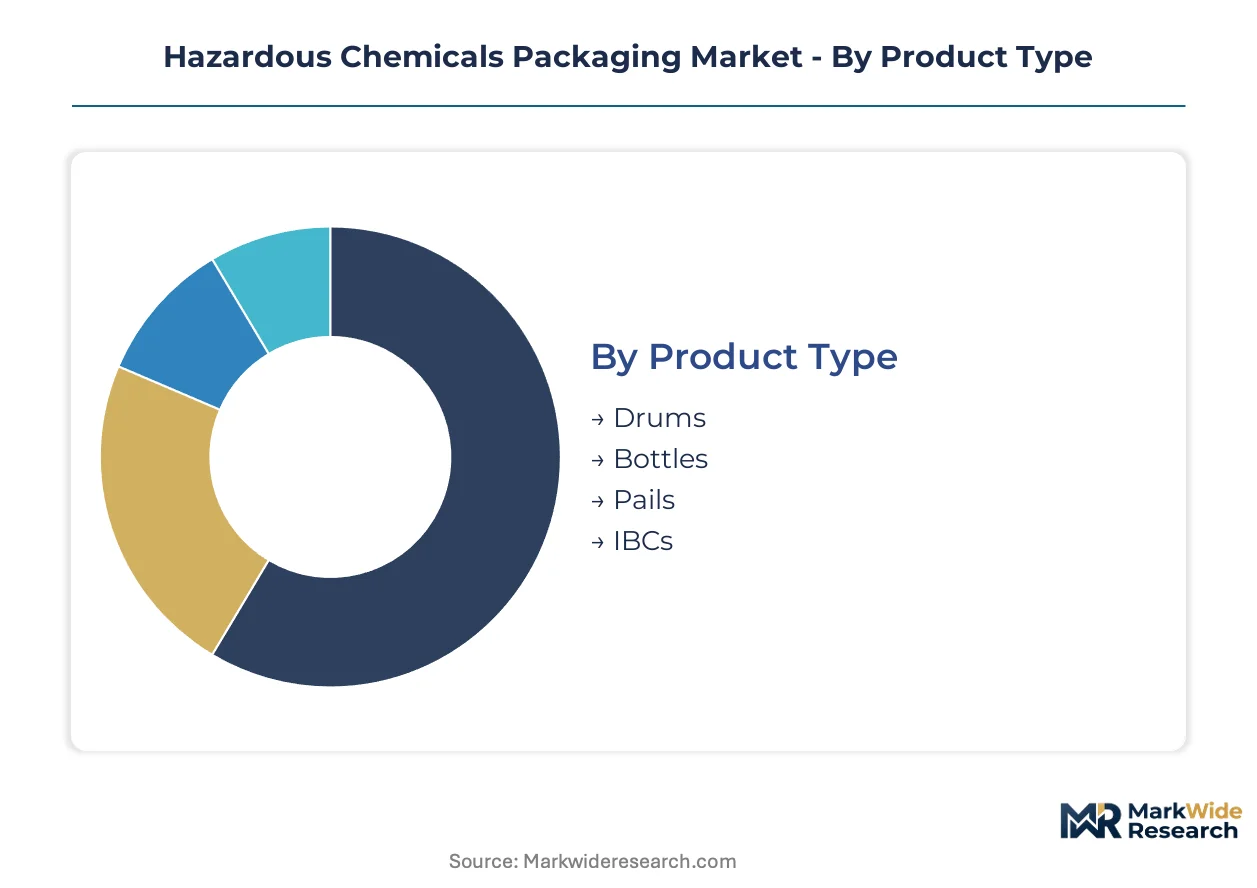
Segmentation in hazardous chemicals packaging reveals how regulatory pressure and logistics economics split demand across container formats. Channel strategies differ sharply between bulk chemical distributors and specialty reagent suppliers.
Product Type:
Channel-mix patterns show drums and IBCs flowing through industrial chemical distributors, while bottles and pails serve laboratory and maintenance-repair-operational channels.
- Drums:Cylindrical steel or polyethylene containers rated for 200-220 liters dominate base chemical logistics. Rhine-Ruhr corridor fabricators supply KBA-regulated transport fleets with epoxy-lined variants for corrosive cargoes.
- IBCs:Intermediate bulk containers with composite steel-polyethylene construction capture pharmaceutical intermediate distribution where cube efficiency reduces freight cost per liter. ANVISA-certified units pull demand from Brazilian agrochemical exporters.
- Bottles:Borosilicate glass and fluoropolymer-barrier designs serve analytical reagent channels where inertness and visibility are non-negotiable.
- Pails:Open-head and tight-head configurations handle smaller-volume chemical and coating applications through industrial supply distributors.
Drums dominate installed base. IBCs are where expansion concentrates.
Material:
Cost-tier stratification separates commodity polymer volumes from premium composite and glass specifications serving regulated applications.
- Polyethylene:High-density and fluoropolymer-barrier grades handle corrosive acid logistics where permeation resistance determines EPA hazardous waste manifest compliance.
- Steel:Epoxy-coated and stainless variants anchor UN-certified drum production for flammable and toxic substances under DOT 49 CFR construction standards.
- Glass:Borosilicate and soda-lime formulations retain laboratory end users requiring chemical inertness and visual inspection capability.
- Composite:Polyethylene-steel hybrid construction with proprietary co-extrusion bonding outperforms monolithic alternatives in drop and stack testing for corrosive chemical applications.
Steel commands premium pricing in flammable goods channels. Composite materials are climbing the fastest on corrosive chemical substitution.
End User:
Application-specific requirements drive specification divergence between bulk commodity handlers and precision-dependent sectors.
- Chemical Manufacturers:Base chemical producers and specialty formulators purchase drums and IBCs through long-term supply contracts with integrated packaging service providers.
- Pharmaceutical Companies:GMP-compliant container systems with batch traceability and cleaning validation documentation serve active pharmaceutical ingredient logistics.
- Oil & Gas:Exploration and production chemicals require steel drum specifications rated for offshore IMDG transport and extended weathering exposure.
- Laboratories:Research and quality control facilities source smaller-format glass and fluoropolymer containers through scientific supply distributors.
Chemical manufacturers represent the largest volume channel. Pharmaceutical companies drive the steepest specification escalation.
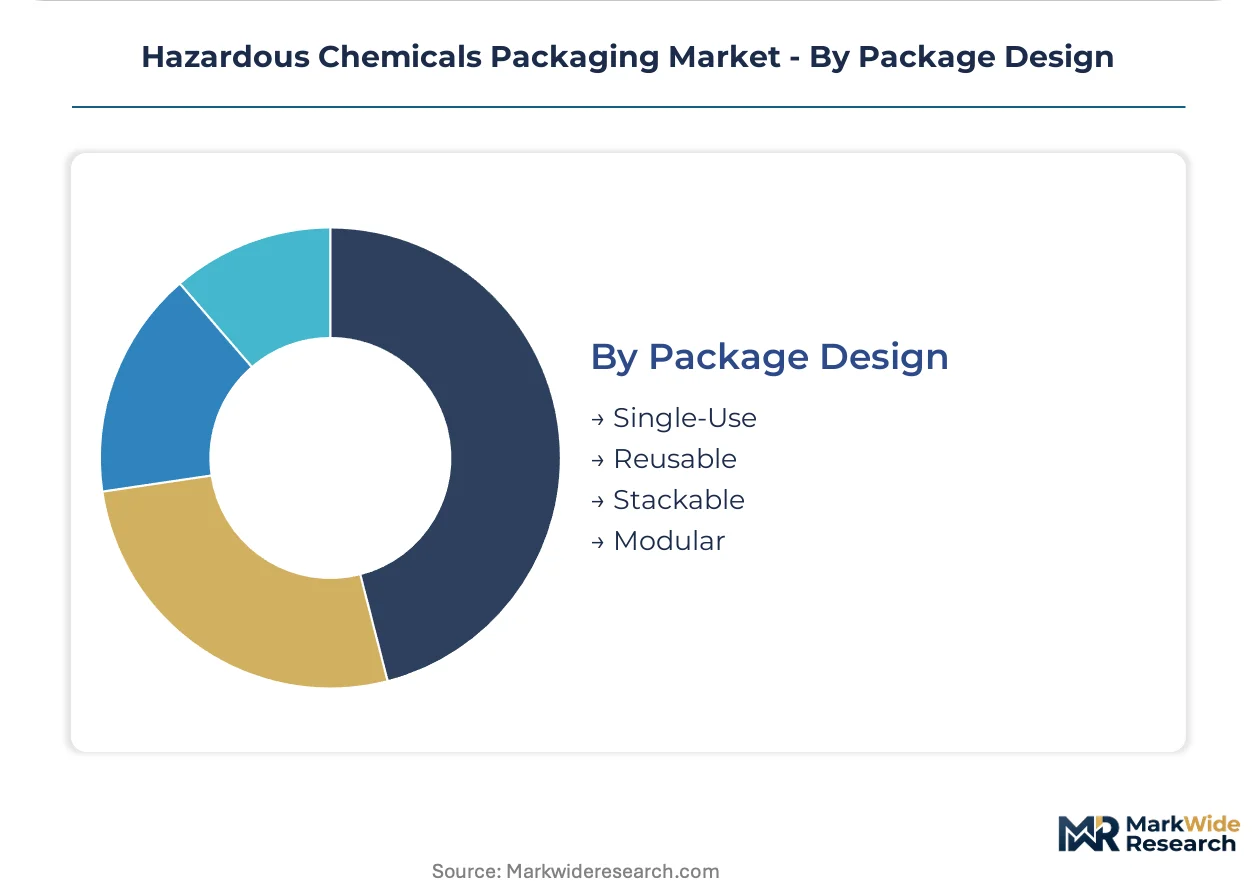
Package Design:
Customer-type preferences split between capital-constrained operators seeking working capital efficiency and asset-heavy users prioritizing operational control.
- Single-Use:One-way containers eliminate return logistics for remote construction sites and export shipments where reconditioning infrastructure is absent.
- Reusable:Leasing-based drum management contracts with third-party pooling operators concentrate in Brazil's ANVISA-regulated pesticide sector where seasonal demand spikes strain owned-fleet utilization.
- Stackable:Cube-optimized IBC and drum geometries maximize warehouse density for chemical distributors in Germany's KBA-regulated logistics corridors.
- Modular:Component-based systems with interchangeable liners and outer shells reduce inventory SKUs for multi-product chemical formulators.
Reusable designs dominate total cost-of-ownership calculations. Single-use formats gain share in infrastructure-constrained geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container-format preferences diverge sharply by geography. German chemical corridors favor reusable steel drum systems under strict transport regulations, while Brazilian agrochemical exporters prioritize composite IBCs for ANVISA-certified cross-border pesticide shipments. Indian state licensing boards are now mandating UN-certified packaging for registered pesticide manufacturers.
United States
EPA hazardous waste manifest requirements and DOT 49 CFR regulations govern drum construction, testing, and marking standards. Gulf Coast petrochemical clusters drive demand for offshore-rated steel specifications serving IMDG transport to Latin American markets. Houston-area fabricators supply corrosion-resistant epoxy-lined variants for acid logistics.
Germany
KBA enforces strict hazardous goods vehicle standards across the Rhine-Ruhr chemical corridor. REACH substance restrictions on heavy metals in packaging coatings accelerate replacement cycles for legacy drum specifications. Cologne-Düsseldorf industrial zones concentrate steel drum demand among base chemical distributors.
Brazil
ANVISA transport requirements pull procurement toward UN-certified composite IBCs for cross-border pesticide shipments. Agrochemical formulators in São Paulo state expand multi-trip container fleets to manage seasonal demand spikes. Port zones around Santos face underdeveloped reconditioning infrastructure.
India
CDSCO-aligned state licensing boards mandate UN-certified packaging for registered pesticide manufacturers in Gujarat and Maharashtra chemical clusters. Domestic drum fabricators face recertification bottlenecks with 14-18 week UN performance testing queues. Mumbai-Pune industrial corridor drives pharmaceutical intermediate IBC demand.
China
NMPA and GB standards govern container specifications for hazardous chemical logistics. Yangtze River Delta chemical producers source composite drums with fluoropolymer barrier films for corrosive acid applications. Shanghai port zones concentrate export-facing packaging demand for specialty chemical distributors.
Hazardous Chemicals Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in hazardous chemicals packaging. Tier-one players operate closed-loop reconditioning networks and captive refurbishment facilities that lock in multi-year supply contracts. Mid-scale fabricators compete on regional proximity and testing velocity rather than asset breadth. Dominant competitive moves include geographic expansion into underdeveloped refurbishment zones and technology licensing for composite layering processes.
Within the integrated service tier, Greif, Inc. and Mauser Packaging Solutions exemplify asset-heavy models with North American and European reconditioning footprints. Schutz GmbH & Co. KGaA occupies a specialist position in intermediate bulk container engineering. These three entities represent contrasting archetypes: the closed-loop network operator, the captive production-refurbishment integrator, and the proprietary technology licensor.
| Leading Market Players |
|---|
| Greif, Inc. |
| Mauser Packaging Solutions |
| Schutz GmbH & Co. KGaA |
| THIELMANN US LLC |
| Berlin Packaging |
| Sonoco Products Company |
| Amcor plc |
| Precision IBC, Inc. |
| Time Technoplast Ltd. |
| Others |
Supply & Pricing Matrix
Composite IBC substitution for conventional steel drums in Brazil's ANVISA-regulated agrochemical corridors is redrawing procurement geography while compressing unit economics through lighter tare weights and reduced freight intensity. This material pivot simultaneously fragments supplier power across polymer-steel hybrid fabricators and erodes legacy drum premiums in corrosive chemical applications.
Pricing Analysis
Reconditioning service contracts and third-party pooling agreements now generate lifetime value multiples exceeding initial container sales for integrated packaging operators. Three-tier pricing structure across premium UN-certified, standard industrial-grade, and economy single-use tiers separates agrochemical formulators with seasonal demand spikes from pharmaceutical companies requiring GMP-validated batch traceability. Pricing pressure stems from hot-rolled coil volatility in Germany's Rhine-Ruhr corridor compressing steel drum fabricator margins. Small-volume laboratory end users exhibit highest price sensitivity, while oil and gas offshore operators absorb premium specifications without volume negotiation.
Supply Chain Analysis
Port congestion around Santos and Mumbai-Pune logistics corridors elevates inbound container costs for epoxy-coated steel coil and fluoropolymer barrier film imports. Supply concentrates in Germany, China, and the United States for steel drum fabrication, composite IBC engineering, and fluoropolymer film extrusion respectively. Raw material dependencies center on hot-rolled steel coil, high-density polyethylene resin, and specialized corrosion-resistant welding consumables. Single-source vulnerability runs through certified welder pools concentrated in legacy industrial regions. Distribution runs through integrated reconditioning networks and industrial chemical distributors with captive fleet operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refurbishment and reconditioning services are expanding faster than virgin container production, transforming capital expenditure models into recurring revenue relationships. This service-attach dynamic favors operators with closed-loop infrastructure over pure manufacturing scale.
For Market Incumbents: Secure multi-year pooling contracts with Brazilian agrochemical formulators before ANVISA certification requirements harden supplier qualification windows. Deepen backward integration into fluoropolymer barrier film production to offset polymer price volatility and capture margin from composite IBC specification escalation. For New Entrants and Emerging Players: UN performance testing fast-tracks at notified bodies with sub-10-week queue times offer entry wedges into India's CDSCO-mandated pesticide packaging formalization. Target Gujarat and Maharashtra chemical clusters where domestic fabricators face recertification bottlenecks. Lead with digital twin-enabled tracking systems that converge with EPA hazardous waste manifest requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed reconditioning network operators lacking composite IBC engineering capabilities. Five-to-ten-year viability hinges on regulatory harmonization velocity rather than manufacturing scale. Watch UN Model Regulation revision adoption timelines across national dangerous goods codes as the primary inflection signal for redesign cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Film Production | Captures margin from composite IBC specification escalation in corrosive acid logistics. |
| Reconditioning Network Expansion | Locks in multi-year supply contracts with agrochemical formulators seeking working capital efficiency. |
| Digital Twin Integration | Creates auditable custody chains converging with EPA hazardous waste manifest requirements. |
| UN Certification Fast-Track Investment | Accelerates product launches where recertification bottlenecks freeze competitor timelines. |
| Geographic Expansion into Southeast Asian Port Zones | Captures first-mover advantage in underdeveloped refurbishment infrastructure markets. |
Research Methodology
Cross-validation between primary interviews with drum reconditioning operators, agrochemical procurement leads, and UN performance testing laboratory directors and secondary validation through customs trade data, ACC industry reports, and SEC filings anchors the qualitative findings. Bottom-up triangulation across plant-level capacity assessments and top-down demand modeling from chemical production volumes ensures segmentation integrity.
Sensitivity analysis across steel price volatility scenarios, UN certification queue time variations, and polymer-steel substitution rates informs the analytical framework. Segmentation dimensions modeled include packaging format, material grade tier, end-use industry, and regional regulatory cluster. CAGRs derive from volume-weighted average growth across these segments. Forecast inputs incorporate REACH substance restriction timelines and ANVISA adoption velocity.
The analysis sits within stated boundaries; outcomes outside sustained regulatory harmonization progress and stable polymer-steel cost differentials would require recalibration. Forecasts reflect documented assumptions regarding certification queue normalization and composite material performance validation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Foam Market
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
Global Aerosol Propellant Market
Industrial Chemicals
Global Industrial Separators Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Hydrogen Silicone Fluid Market
Industrial Chemicals
2,3-Butanediol Market
Industrial Chemicals
Global CMP Slurry Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
Toluene Diisocyanates (TDI) Market
Industrial Chemicals
Explosion Venting Market