
 US and Canada Tonic Water Market | 2026-2036
US and Canada Tonic Water Market Size, Share, and Industry Trends Forecast 2026-2036
US and Canada Tonic Water Market Intelligence
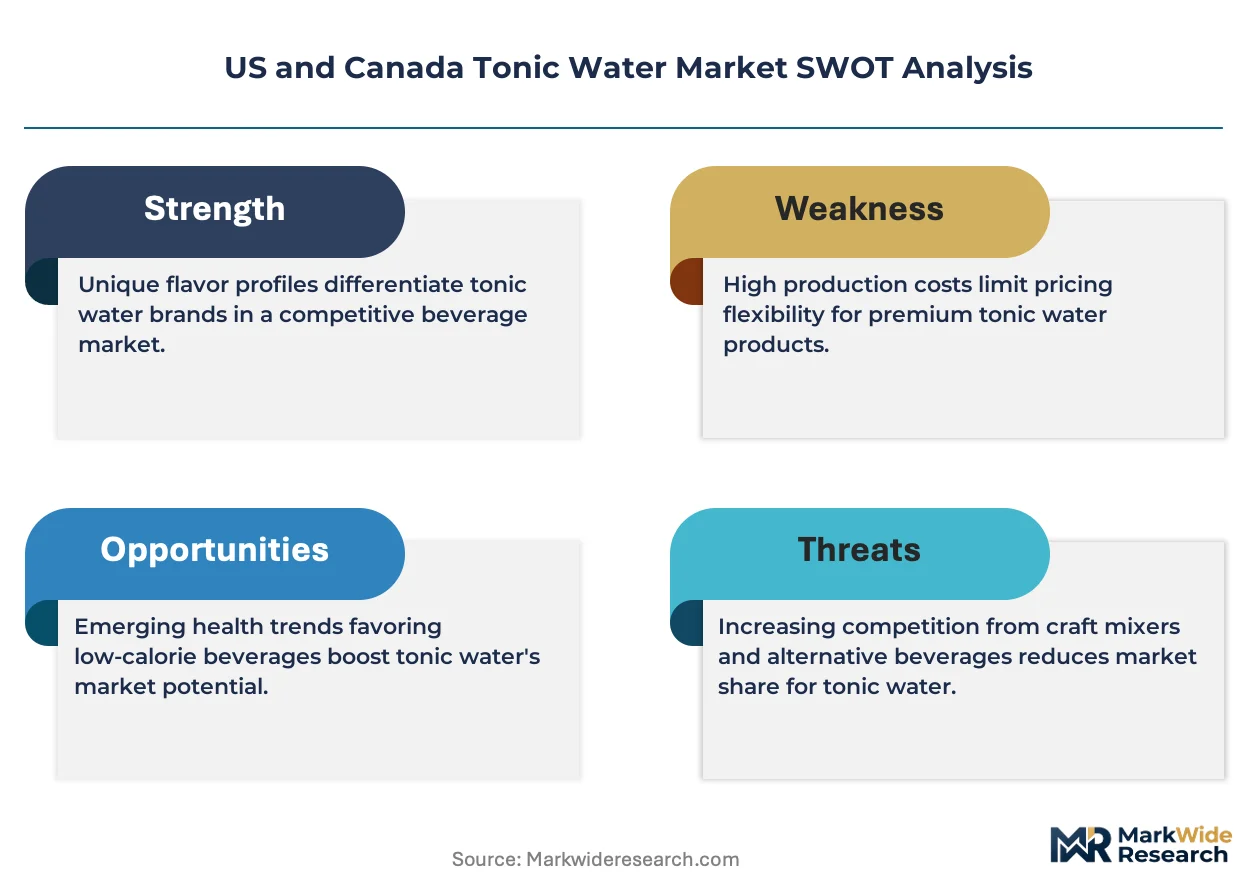
Expanded craft production in Quebec and the Pacific Northwest is narrowing the gap between premium and mass-market offerings. Fever-Tree leverages its premium brand positioning and strong relationships with high-end bars. In contrast, Schweppes, a key brand for Keurig Dr Pepper Inc., sustains its market share through extensive retail distribution channels. Fentimans specializes in botanically brewed mixers, effectively appealing to a dedicated niche consumer base.
Tonic water is a carbonated soft drink distinguished by the inclusion of quinine, which imparts its signature bitter flavor profile. Its primary commercial purpose is as a mixer in alcoholic and non-alcoholic cocktails, most notably the gin and tonic. While the classic product type remains a volume staple, flavored variants incorporating citrus and herbal notes represent the fastest-growing segment. The HoReCa customer type and distribution via specialty stores are critical for margin growth in the premium category.
Product formulation and labeling are strictly governed by the US Food and Drug Administration (FDA) and Health Canada. These regulatory bodies set maximum permissible levels for quinine and enforce transparent nutritional information on packaging. Adherence to these specific standards is a prerequisite for market access across both nations. The key strategic decision for producers involves balancing rising consumer demand for all-natural ingredients with managing input cost volatility.
Market Dynamics
The primary force shaping the US and Canada tonic water market is the bifurcation of demand. A sophisticated cocktail culture in metropolitan centers pulls the market toward premium, craft formulations, while mass-market channels require volume and price competitiveness.
Growth Catalysts
- Elevated Cocktail Culture:A sophisticated consumer base in cities like New York and Toronto demands premium tonic waters, viewing them as essential, non-negotiable components for high-end cocktails.
- Flavored Variant Expansion:Consumer interest in novel taste profiles propels the fastest-growing segment of flavored tonics, which incorporate natural citrus and herbal notes to broaden category appeal.
- HoReCa Sector Influence:The hotel, restaurant, and catering channel acts as a critical launchpad for premium brands, building consumer awareness and supporting higher margin structures.
Market Restraints
- Input Cost Volatility:Fluctuation in the price and availability of raw materials, especially quinine from cinchona bark and other botanicals, creates significant pressure on producer cost structures.
- Regulatory Quinine Limits:Strict maximum quinine levels mandated by the FDA and Health Canada constrain product formulation, capping the signature bitterness that defines traditional tonic water.
- Threat of Substitution:The market faces competition from other carbonated mixers like seltzers and club soda, which consumers can easily substitute in mixed drinks, particularly in non-gin cocktails.
Strategic Opportunities
- Non-Alcoholic Cocktails:The growing demand for sophisticated adult non-alcoholic beverages creates an opportunity for tonic water as a premium standalone drink or a base for complex mocktails.
- Mid-Market Geographic Growth:Producers can target expansion in mid-sized US and Canadian cities where craft beverage trends are emerging but premium mixer options remain limited.
- Direct-to-Consumer Sales:E-commerce platforms offer a channel for niche brands to build a national footprint in the US and Canada, bypassing crowded retail shelves and engaging consumers directly.
Industry Challenges
- Botanical Supply Chain Management:Securing a consistent and high-quality supply of specialized botanicals from diverse global regions presents a significant logistical hurdle for manufacturers.
- "Natural" Labeling Compliance:Adhering to FDA and Health Canada regulations for "natural" claims requires rigorous formulation and documentation, adding complexity and cost to product development.
- Crowded Market Messaging:Communicating a distinct brand identity is increasingly difficult as the aesthetic and ingredient gap between premium and mass-market tonic waters narrows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Canada Tonic Water Market |
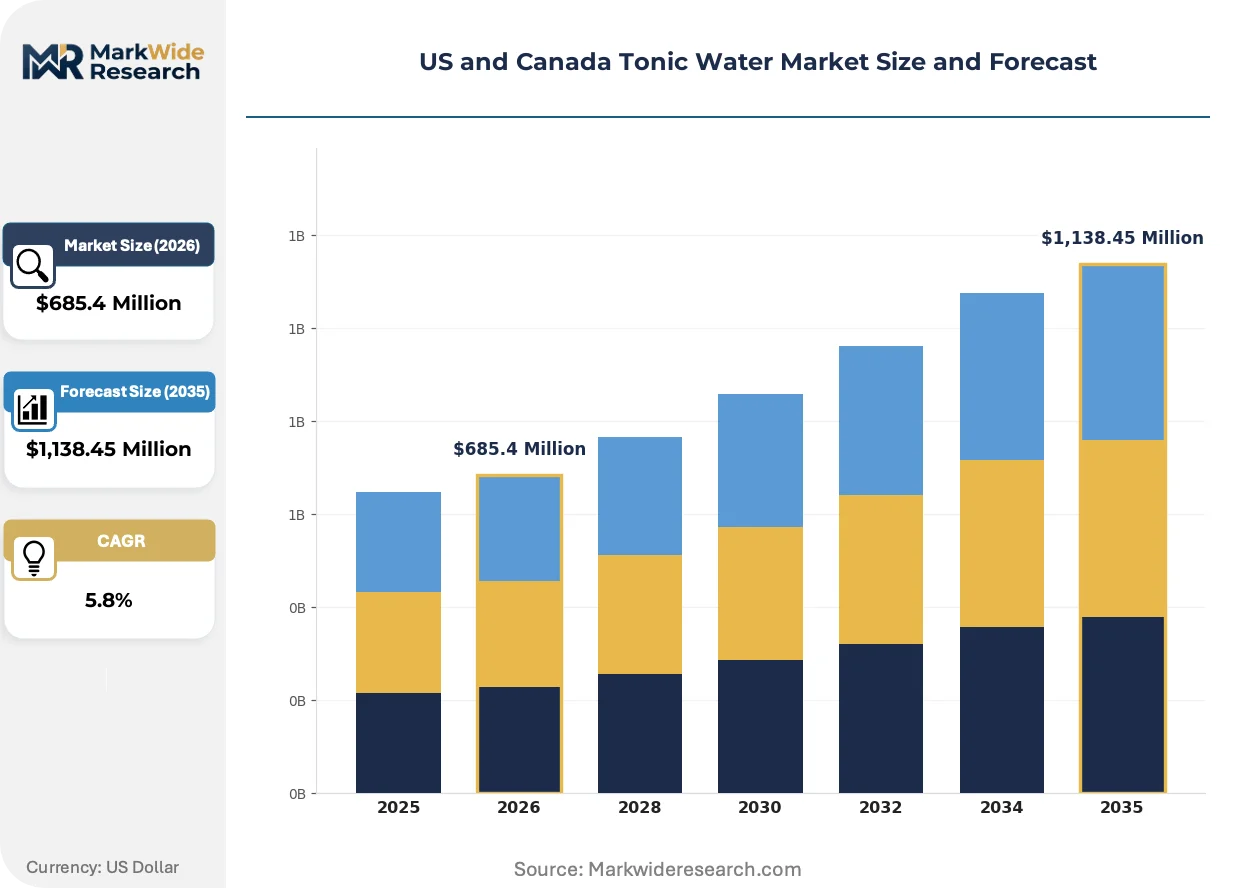
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Diet, Flavored, Organic Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Bars Customer Type: Retail Consumers, HoReCa, Event Planners, Mixologists Packaging Type: Bottles, Cans, Bulk, Single-Serve |
| Companies Covered | Canada Dry, Fentimans, Keurig Dr Pepper Inc., Boylan Bottling Company, Polar Beverages, Fever-Tree, Q Tonic, LLC, White Rock Beverages, Schweppes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Canada Tonic Water Market Strategic Shifts & Innovations
The evolution of consumer taste toward more complex and less artificial flavor profiles is the central theme. This shift compels producers to rethink ingredient sourcing, formulation, and how they communicate product attributes beyond simple bitterness.
Botanical brewing and cold-extraction methods capture delicate flavor compounds from ingredients beyond just quinine. Premium and craft producers are rapidly adopting these techniques to create signature flavor profiles. The market's core identity is migrating from a singular focus on quinine bitterness to a broader spectrum of complex, layered botanical infusions similar to herbal sodas.
Increased focus from the FDA and Health Canada on front-of-pack nutritional labeling is impacting product design. This pressure forces brands to reformulate products to lower sugar, often replacing high-fructose corn syrup with cane sugar or stevia. Flavored tonic varieties are most affected, needing to balance taste with appealing nutritional panels.
A significant behavioral shift sees consumers purchasing premium tonic water for sophisticated at-home cocktail creation. This disrupts the model where premium brands were discovered primarily through the HoReCa channel, now sharing that role with specialty retail and e-commerce. This at-home premiumization is most visible in major US and Canadian metropolitan markets.
US and Canada Tonic Water Market Segmentation
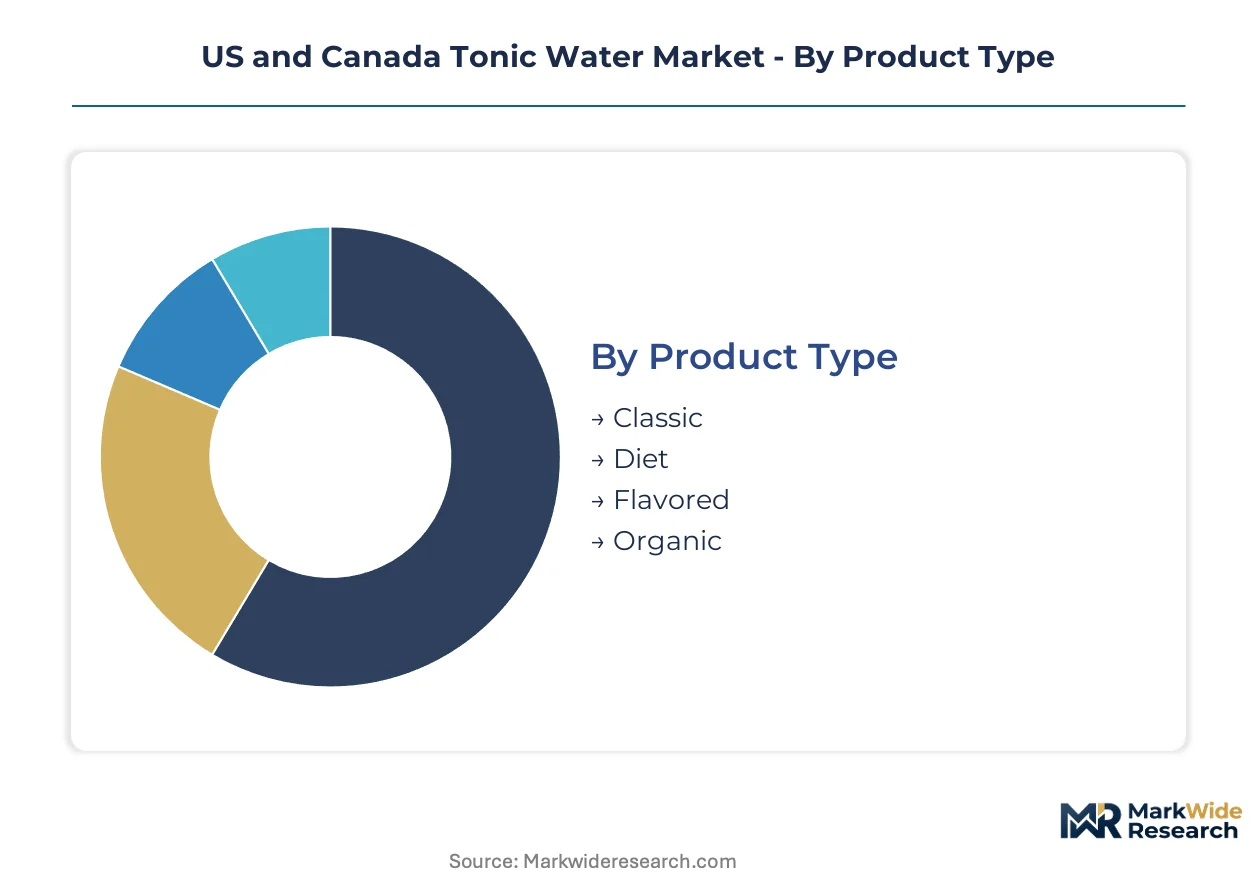
The US and Canada tonic water market is meticulously segmented to understand varied consumer preferences and distribution dynamics. This segmentation provides a granular view of product evolution, channel efficacy, and customer engagement, which is critical for strategic planning.
Product Type:
The use-case spectrum for tonic water spans traditional cocktail mixing to health-conscious beverage choices, influencing product type development.
- Classic:This product contains quinine and sugar, offering the traditional bitter profile essential for standard mixed drinks. High volume demand concentrates in bars across New York and Toronto for authentic gin and tonics.
- Flavored:These variants are infused with natural citrus or herbal extracts, diversifying the taste profile beyond traditional bitterness. Strong consumer interest in US metropolitan areas drives demand for novel at-home cocktail creations.
- Diet:Formulated with artificial sweeteners or sugar alternatives, this type reduces calorie content without compromising the bitter essence. It appeals to health-conscious consumers in urban centers.
- Organic:Produced using organically sourced quinine and other natural ingredients, this segment caters to consumers seeking clean-label beverages.
Established volume favors Classic tonic; emerging adoption favors Flavored variants.
Distribution Channel:
Distribution channels are structured to reach diverse customer types, from individual consumers to large hospitality venues.
- Supermarkets:These broad retail outlets offer wide accessibility and competitive pricing for mass-market tonic water brands. This channel dominates sales for everyday household consumption across the US and Canada.
- Specialty Stores:These curated retail environments focus on premium and craft beverage selections, often providing unique product discovery. They are critical for margin growth and brand discovery in major US and Canadian cities.
- Online Retail:E-commerce platforms facilitate direct-to-consumer sales, enabling niche brands to reach a national footprint. This channel supports national footprint expansion for smaller, premium producers.
- Bars:As on-premise consumption venues, bars are crucial for brand visibility and shaping cocktail culture trends. They are essential for premium brand positioning and consumer trial in urban hubs.
Volume is concentrated in Supermarkets, while Online Retail offers growth opportunities.
Customer Type:
Customer types exhibit varied purchasing behaviors and margin expectations, influencing product and service offerings.
- HoReCa:This segment includes Hotels, Restaurants, and Catering services, purchasing tonic water for on-premise consumption. It acts as a critical launchpad for premium brands, particularly in high-end establishments across North America.
- Retail Consumers:These are individual consumers purchasing tonic water for at-home consumption through various retail channels. This segment drives the mass-market and at-home premiumization trends in US and Canadian metros.
- Mixologists:Professional bartenders seek unique and high-quality mixers for craft cocktails, influencing product development and ingredient sourcing. This segment influences trends and premium product adoption within the beverage industry.
- Event Planners:These organizers source beverages for corporate events, weddings, and private parties, often requiring bulk or single-serve formats. This segment requires bulk and single-serve options for large-scale service.
Profitability is maximized through HoReCa, while Retail Consumers drive broad market penetration.
Packaging Type:
Packaging types are designed to accommodate varying consumption volumes and distribution requirements across the market.
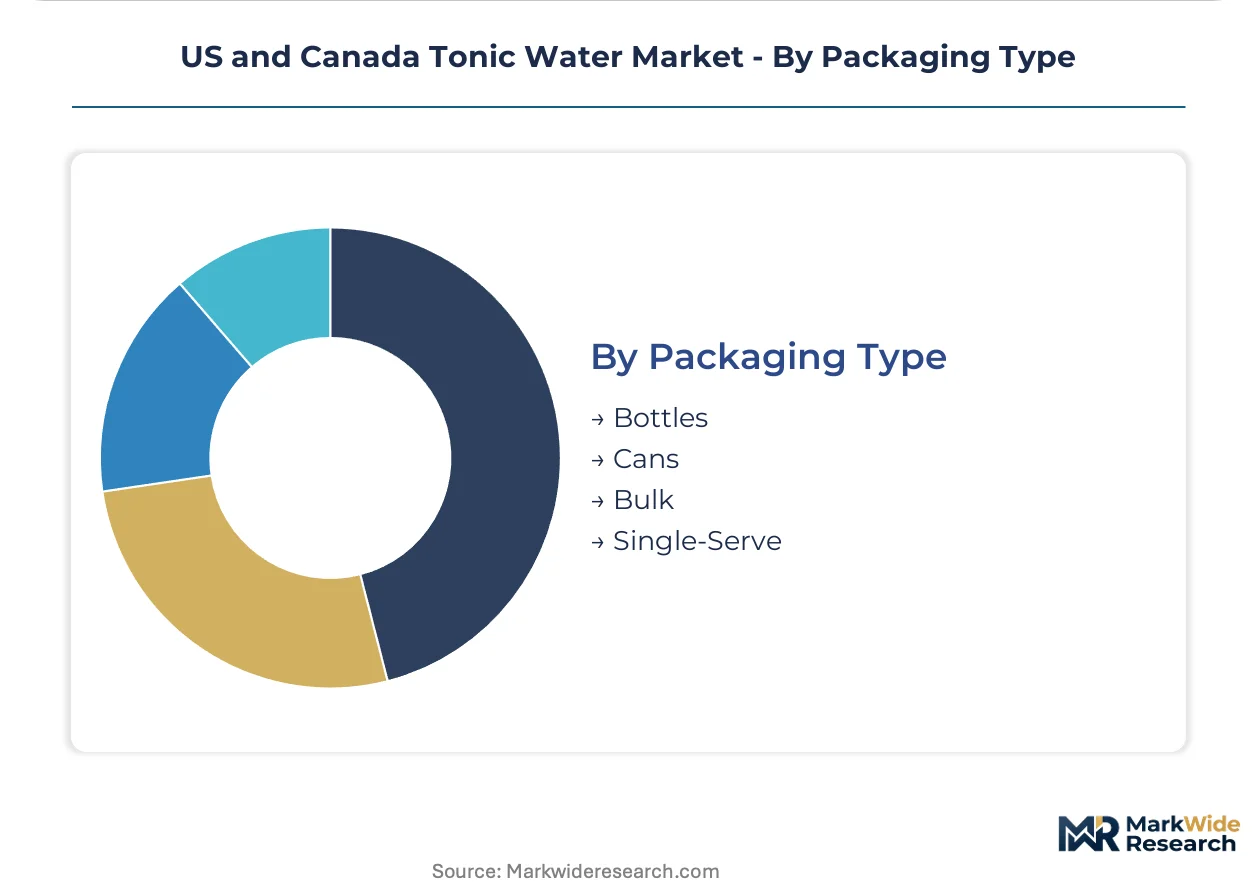
- Bottles:Glass or plastic containers are often associated with premium brands and traditional presentation, maintaining product integrity. This type is preferred by retail consumers and high-end HoReCa establishments in the US and Canada.
- Cans:Aluminum containers offer portability, durability, and a modern aesthetic, appealing to convenience-oriented consumers. This type appeals to younger consumers and is gaining traction for convenience in both US and Canadian markets.
- Bulk:Large format containers are typically used for commercial purposes in bars, restaurants, and catering operations. This type is essential for high-volume HoReCa operations and cost-efficiency.
- Single-Serve:Small, individual portions are designed for immediate consumption or travel convenience. This type caters to convenience-oriented consumers and on-the-go scenarios.
Traditional preference leans towards Bottles, but Cans are seeing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive retail distribution networks underpin the US and Canada tonic water market. These channels facilitate broad product availability, from mass-market offerings to premium craft formulations. E-commerce platforms further expand reach, enabling niche brands to connect directly with consumers across both nations.
New York Metropolitan Area
Sophisticated cocktail culture drives demand for premium tonic waters in New York. FDA regulations concerning quinine content influence product formulation for brands sold here. High-end bars in Manhattan consistently drive premium brand visibility and consumer trial for new mixer options.
Toronto Metropolitan Area
Elevated cocktail culture and a strong HoReCa sector influence tonic water consumption in Toronto. Health Canada regulations for nutritional labeling impact how brands communicate product attributes. Upscale restaurants in downtown Toronto foster demand for unique mixer options and premium brand positioning.
Quebec
Expanded craft production and a focus on local ingredient sourcing characterize the Quebec market. Health Canada's "natural" labeling compliance guides product development for regional brands. Craft beverage producers in Montreal and surrounding regions narrow the gap between premium and mass-market offerings.
Pacific Northwest
Emerging craft beverage trends and a consumer focus on all-natural ingredients define the Pacific Northwest. FDA standards for product formulation ensure adherence to safety and quality guidelines. Portland and Seattle's vibrant culinary scenes support growth in flavored and organic tonic water variants.
US and Canada Tonic Water Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the US and Canada tonic water market. This market exhibits a tiered structure, with a clear distinction between volume-driven mass-market brands and quality-focused premium producers. Strategic archetypes include global beverage conglomerates, craft mixer specialists, and regional bottlers. Dominant competitive moves involve portfolio diversification into flavored variants and expanding distribution channels.
Among established market players, Fever-Tree exemplifies premium brand positioning through strong relationships with high-end bars. Schweppes, a key brand for Keurig Dr Pepper Inc., represents mass-market dominance via extensive retail distribution channels. Fentimans occupies a niche specialist position, appealing to consumers seeking botanically brewed mixers.
| Leading Market Players |
|---|
| Canada Dry |
| Fentimans |
| Keurig Dr Pepper Inc. |
| Boylan Bottling Company |
| Polar Beverages |
| Fever-Tree |
| Q Tonic, LLC |
| White Rock Beverages |
| Schweppes |
| Others |
Cost & Logistics Intelligence
Quinine supply from cinchona bark, primarily sourced from specific global regions, directly influences margin pools for premium tonic water brands. Input cost volatility creates significant pressure on producers.
Pricing Analysis
FDA and Health Canada regulations dictate the pricing tier structure for tonic water, particularly concerning quinine content. Pricing stratifies across premium, standard, and economy tiers. Brand premium and natural ingredient sourcing drive differentiation in the high-end segment. Pricing softness for mass-market offerings stems from intense supermarket competition and input cost volatility. Retail consumers purchasing mass-market products exhibit the highest price sensitivity.
Supply Chain Analysis
Regional bottlers and craft production facilities in Quebec and the Pacific Northwest hold significant manufacturing capacity for tonic water. The supply chain draws heavily from global regions for cinchona bark and diverse botanicals. Commodity price volatility for quinine and other natural ingredients presents a structural risk. Distribution runs through a fragmented network of supermarkets, specialty stores, online platforms, and on-premise bars.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US and Canada tonic water market presents a significant fragmentation opportunity driven by an elevated cocktail culture. Consumer demand for sophisticated non-alcoholic beverages creates numerous niche segments.
For Market Incumbents: Entrench existing HoReCa relationships by offering exclusive product lines and mixologist training programs. Diversify product portfolios with novel flavored variants to counter the threat of substitution from other carbonated mixers. Invest in backward integration for key botanical sourcing to mitigate input cost volatility. Leverage established retail distribution networks to maintain mass-market share against emerging craft brands.
For New Entrants and Emerging Players: Pursue mid-market geographic growth in emerging craft beverage hubs across the US and Canada where premium mixer options are limited. Target the non-alcoholic cocktail segment with unique botanically brewed formulations. Leverage direct-to-consumer e-commerce platforms to build a national footprint for niche, premium offerings. Emphasize transparent "natural" labeling compliance as a core brand differentiator.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional bottlers and craft mixer specialists seeking broader distribution or deeper market penetration. The long-term viability of the tonic water market rests on sustained consumer demand for sophisticated, complex beverage experiences. Target acquisition profiles include brands with strong "natural" ingredient positioning or advanced botanical brewing techniques. Watch the HoReCa sector's expansion beyond tier-one cities as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Flavored Variants | Broadens consumer appeal beyond classic gin and tonics, capturing novel taste preferences. |
| Direct-to-Consumer E-commerce Expansion | Enables niche brands to bypass traditional retail and engage directly with a national consumer base. |
| Strategic Sourcing for Botanicals | Mitigates input cost volatility and ensures consistent quality for premium product formulations. |
| HoReCa Channel Partnership Deepening | Reinforces premium brand positioning and drives consumer trial in high-visibility urban establishments. |
| Lower Sugar Formulation Development | Addresses evolving consumer health preferences and complies with nutritional labeling requirements. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to inform this analysis. Primary interviews with mixologists, HoReCa purchasers, brand managers, and botanical suppliers provided qualitative insights. Secondary validation drew from FDA filings, Health Canada guidelines, and relevant trade association reports. This approach ensured a robust bottom-up and top-down triangulation of market dynamics.
Quantitative models were calibrated using a multi-factor approach across the analysis window. Segmentation dimensions included product type, distribution channel, customer type, packaging type, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical performance, projected consumer shifts, and competitive landscape assessments. Key forecast inputs included quinine price trends and the adoption rate of lower-sugar formulations.
Macroeconomic conditions sit as an overlay; deviation in global commodity prices or consumer discretionary spending would shift the trajectory. Forecasts reflect assumptions documented at the time of publication. Regulatory changes from FDA or Health Canada also represent critical risk factors for product formulation. Quarterly review of botanical supply and consumer taste profiles is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Europe Coconut Water Market
Beverages
Europe Animal-Based Food and Beverage Market
Beverages
Water Flavor Market
Beverages
Juice Concentrates Market
Beverages
Orange Juice Market
Beverages
Direct Piping Water Dispenser Market
Beverages
Kvass Market
Beverages
Europe Sugar Free Energy Drinks Market
Beverages
Smoothies Market
Beverages
Bottled Deep Ocean Water Market
Beverages
Sparkling Juice Drinks Market
Beverages
Morocco Bottled Water Market
Beverages
Collagen-Infused Water Market
Beverages
Crystal Boba Market
Beverages
Yerba Mate Market
Beverages
Citrus Water Market