
 Flavored Powder Drinks Market | 2026-2036
Flavored Powder Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Flavored Powder Drinks Market Intelligence
FSSC 22000 certification for food safety is collapsing the distinction between premium and mass-market suppliers, forcing all manufacturers to adhere to stringent production standards. Nestlé S.A. leverages its global manufacturing footprint to meet these standards at scale across diverse product lines. In contrast, The Kraft Heinz Company differentiates through established brand loyalty and extensive control over distribution channels in key markets like the United States and Canada.
Flavored powder drinks are dehydrated formulations designed for reconstitution with liquids like water or milk. These products are engineered for specific solubility rates and particle sizes to ensure a consistent consumer experience and shelf stability. While beverage mixes for general consumption hold the largest volume share, the nutritional supplements segment shows the highest growth potential. Distribution is increasingly shifting towards online retail, which offers wider product selection and direct-to-consumer access for specialized brands.
The U.S. FDA's regulations on nutrient content claims and the European EFSA's scrutiny of health claims directly govern product formulation and marketing language. In parallel, standards from India's FSSAI on approved additives and labeling create distinct regional compliance requirements for market entry. Future market leadership will be determined by the ability to balance innovative, functional formulations with adherence to a complex and diverging set of international food safety laws.
Market Dynamics
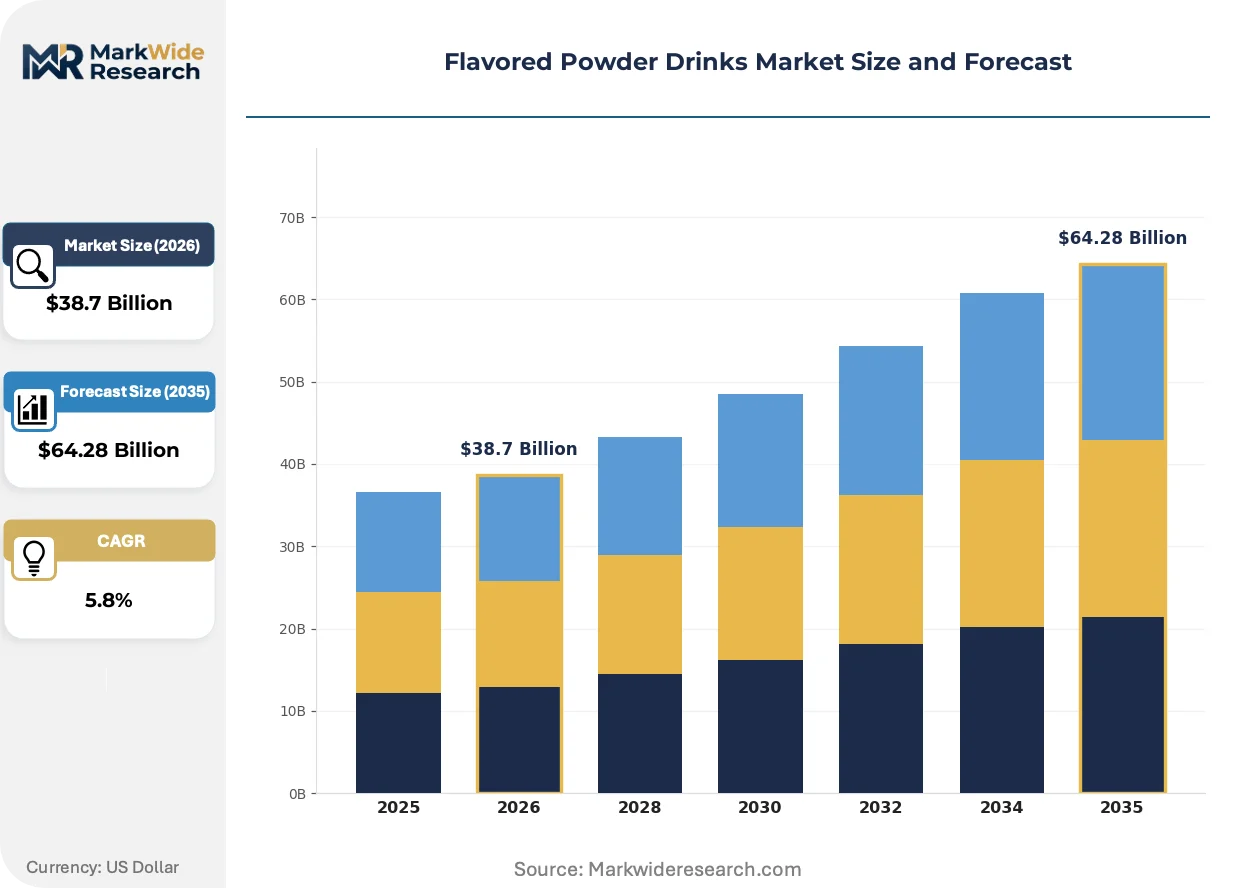
The convergence of stringent food safety certifications like FSSC 22000 with rising consumer demand for functional, clean-label ingredients is the central force shaping the market. This dynamic creates a competitive field where both scale and formulation expertise are critical for success.
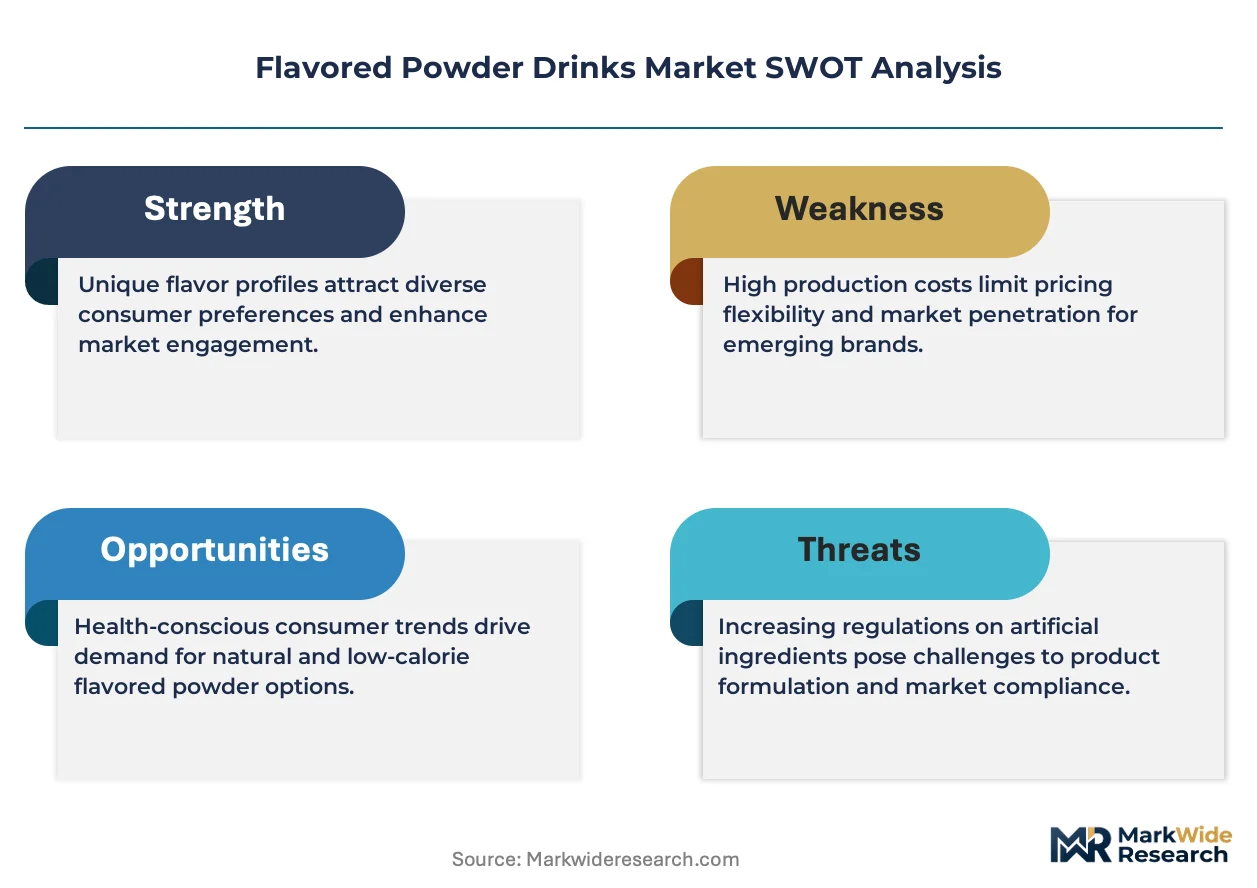
Growth Catalysts
- Clean-Label Demand:The consumer shift towards transparent sourcing and recognizable ingredients, particularly in the United States, favors products free from artificial additives.
- E-commerce Expansion:Online retail and direct-to-consumer platforms provide specialized brands with broader market access, bypassing traditional shelf-space competition.
- Nutrient Claim Frameworks:U.S. FDA regulations, while strict, provide a clear pathway for marketing products with scientifically validated functional benefits.
Market Restraints
- Input Cost Volatility:Prices for functional ingredients like whey protein isolate and vitamins are subject to fluctuation, impacting manufacturer margins.
- Regulatory Divergence:Conflicting requirements from the European EFSA and India's FSSAI on additives and health claims create complex compliance challenges for global brands.
- Substitution from RTD:The convenience of ready-to-drink functional beverages presents a direct substitution threat for on-the-go consumption occasions.
Strategic Opportunities
- Geographic Expansion:Southeast Asian markets, with a growing middle class and wellness consciousness, represent a significant growth area for market entry.
- Personalized Nutrition:The convergence of at-home diagnostics and custom blending enables highly individualized powder formulations tailored to consumer needs.
- Subscription Models:Direct-to-consumer brands build recurring revenue and customer loyalty through subscription services for nutritional supplements.
Industry Challenges
- Compliance Management:Adhering to a complex web of international food safety standards like FSSC 22000 is a constant operational burden.
- Supply Chain Verification:Substantiating clean-label claims requires extensive and costly verification processes for every raw material.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavored Powder Drinks Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports Drinks, Nutritional Supplements, Beverage Mixes, Instant Drinks Form: Granular, Sachets, Tablets, Liquid Concentrates Target Audience: Health Enthusiasts, Athletes, Busy Professionals, Children Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Convenience Stores |
| Companies Covered | The Kraft Heinz Company, Unilever PLC, Nestlé S.A., Cargill, Incorporated, Conagra Brands, Inc., The Coca-Cola Company, Mondelēz International, Inc., Keurig Dr Pepper Inc., PepsiCo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavored Powder Drinks Market Strategic Shifts & Innovations
Market evolution is defined by the intersection of advanced food science and digital retail. This fusion enables new product categories and alters how consumers discover and integrate these beverages into their daily routines.
Micro-encapsulation technology protects sensitive ingredients like probiotics and vitamins from degradation. Functional food brands targeting health-conscious consumers are rapidly adopting this process. The technology is miniaturizing the delivery mechanism for complex nutrients, enabling more potent and stable formulations within a single powder serving.
The European Food Safety Authority (EFSA) maintains a stringent approval process for health claims on food products. This regulation forces manufacturers to provide extensive scientific evidence for any claimed benefit, such as improved athletic performance. The nutritional supplements segment is most affected, leading companies to invest in clinical trials or pivot to general wellness marketing in the EU.
A key behavioral shift involves consumers moving from single retail purchases to recurring subscription models from direct-to-consumer brands. This model disrupts traditional supermarket channels by creating a direct feedback loop and predictable revenue for specialized companies. The trend is most visible in the United States within niche segments like ketogenic or vegan powder mixes.
Flavored Powder Drinks Market Segmentation
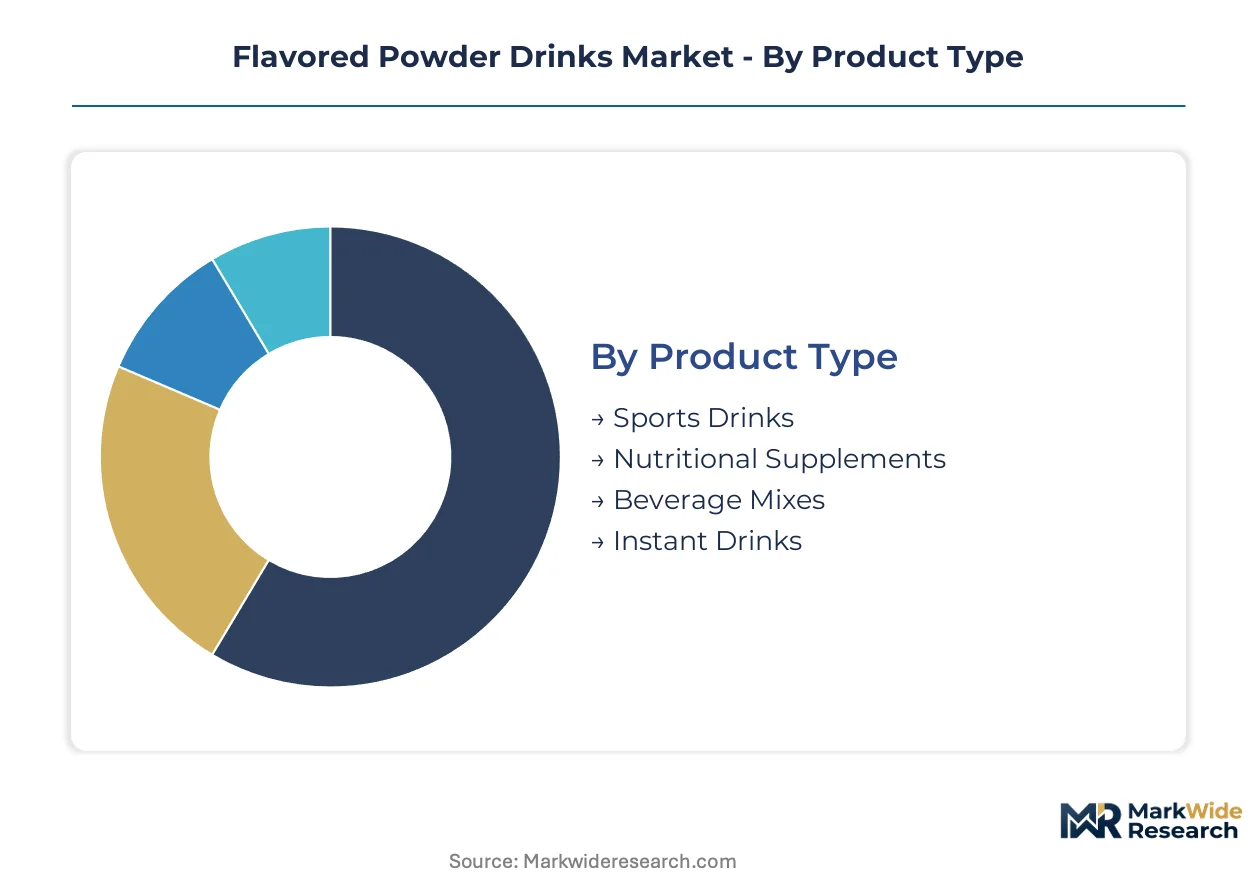
Segmentation provides a granular view of the Flavored Powder Drinks Market, revealing distinct consumer preferences and operational dynamics. Analyzing these segments helps manufacturers tailor product development and market entry strategies. This detailed breakdown highlights key areas of growth and competitive intensity.
Product Type:
The distribution channels for flavored powder drinks vary significantly by product type, influencing both consumer access and market penetration across the United States and Canada.
- Nutritional Supplements:These formulations deliver targeted health benefits, often containing proteins, vitamins, or specific botanicals. Demand concentrates in the United States, driven by a strong wellness and fitness culture and direct-to-consumer online sales.
- Beverage Mixes:Designed for general consumption, these products offer a convenient and cost-effective way to prepare flavored drinks. They hold significant volume share in traditional retail channels, particularly in supermarkets across diverse markets.
- Sports Drinks:These powders focus on hydration and electrolyte replenishment for active individuals.
- Instant Drinks:This segment includes coffee, tea, and other quick-preparation beverages.
Beverage Mixes dominate the installed base for flavored powder drinks. Nutritional Supplements are where expansion concentrates.
Form:
Different forms of flavored powder drinks cater to distinct application scenarios, from on-the-go consumption to bulk preparation for household use.
- Granular:This common form allows for flexible dosing and easy mixing in various liquids. It is prevalent in bulk consumer products and industrial applications, offering cost efficiency in packaging and transport.
- Sachets:Single-serving sachets provide convenience and precise portion control, reducing waste. Demand is strong among busy professionals in urban centers, valuing portability and ease of use.
- Tablets:These effervescent or dissolvable forms offer a compact and mess-free option for quick preparation.
- Liquid Concentrates:While less common, these provide a highly soluble and potent option for flavor delivery.
Convenience and precise dosing are driving innovation within the form factor segment.
Target Audience:
The diverse needs of various target audiences dictate specific product formulations and marketing strategies for flavored powder drinks across different age groups.
- Health Enthusiasts:This group prioritizes products with functional benefits, clean-label ingredients, and specific dietary alignments. Demand from this segment is a significant tailwind in the United States, driving innovation in ingredient sourcing.
- Athletes:Focused on performance, recovery, and muscle support, athletes seek products with high protein content and specific amino acids. This audience frequently purchases through specialized online retail platforms.
- Busy Professionals:This segment values convenience, quick preparation, and functional benefits like energy or focus.
- Children:Products for children often focus on appealing flavors, added vitamins, and reduced sugar content.
Premiumization and specialized needs drive product development within the health-conscious and athletic consumer groups.
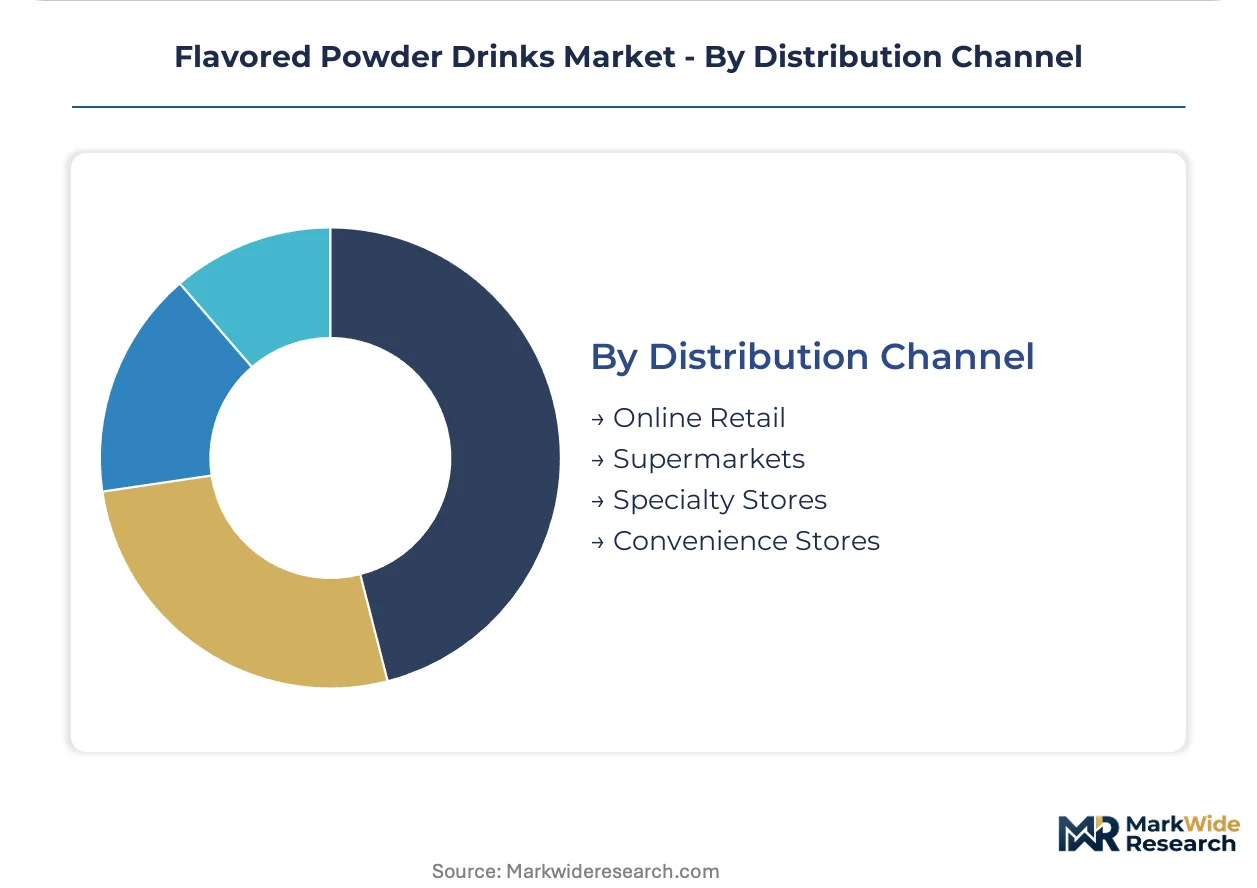
Distribution Channel:
The reach and volume potential of each distribution channel significantly influence market presence for flavored powder drinks, shaping consumer access and brand visibility.
- Online Retail:This channel offers extensive product selection and direct-to-consumer access for specialized brands, bypassing traditional shelf-space competition. Its expansion is a key growth catalyst across North America and Europe.
- Supermarkets:These large-format stores provide broad consumer access and high volume sales for established brands. They remain a primary channel for general beverage mixes and value-oriented products.
- Specialty Stores:These outlets cater to niche markets, offering curated selections of health-focused or gourmet powder drinks.
- Convenience Stores:This channel offers immediate consumption options, focusing on single-serve and impulse purchases.
Digital transformation and evolving consumer preferences are reshaping the landscape for product accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks, such as the U.S. FDA's nutrient content claims, significantly influence product development and marketing in the flavored powder drinks market. These guidelines establish clear pathways for functional beverage innovation, fostering consumer trust and shaping market strategies. International compliance standards further define regional market dynamics.
United States
Demand for functional flavored powder drinks in the United States is driven by a strong wellness and fitness culture, alongside convenient consumption patterns. The U.S. FDA's regulations on nutrient content claims provide a clear framework for marketing these products effectively. California's health and wellness industry clusters around Los Angeles and San Francisco, fostering specialized product innovation and ingredient sourcing.
Germany
German consumers prioritize clean-label ingredients and scientifically backed functional benefits in their powdered beverages, reflecting a discerning market. The European EFSA maintains stringent approval processes for health claims, directly impacting product formulation across the entire EU. Munich's advanced food science research institutions actively collaborate with manufacturers, developing cutting-edge nutrient delivery systems.
India
India's growing middle class and increasing health consciousness drive demand for convenient, functional flavored powder drinks across urban centers. The FSSAI's regulations on approved additives and labeling create distinct regional compliance requirements for market entry and product differentiation. Bengaluru's vibrant startup ecosystem fosters new brands focusing on traditional Indian ingredients and holistic wellness solutions.
Brazil
Brazilian consumers show strong demand for sports nutrition and functional beverages supporting active lifestyles, often preferring innovative tropical flavors. ANVISA's comprehensive food and beverage regulations govern product safety and labeling for all powdered drink formulations sold domestically. São Paulo's extensive food processing sector serves as a vital hub for both domestic production and efficient distribution across the broader Latin American market.
Flavored Powder Drinks Market Key Industry Players
Player mix skews toward large, diversified food and beverage conglomerates, alongside a growing number of specialized functional ingredient providers. The market structure is tiered, with established brands dominating traditional retail and agile direct-to-consumer specialists gaining traction online. Three strategic archetypes emerge: global consumer goods giants, niche health and wellness innovators, and ingredient suppliers with proprietary technologies. Dominant competitive moves include strategic partnerships for distribution and continuous portfolio diversification into functional categories.
Among the global consumer goods giants, Nestlé S.A., The Kraft Heinz Company, and PepsiCo, Inc. represent significant market presence through their extensive brand portfolios and distribution networks. Nestlé S.A. exemplifies a strategy leveraging global manufacturing footprints to meet stringent production standards across diverse product lines. The Kraft Heinz Company occupies a position anchored by established brand loyalty and extensive control over distribution channels in key North American markets. PepsiCo, Inc. further contributes to this landscape with its broad beverage offerings, adapting formulations to health and wellness trends. These entities collectively shape market dynamics through their scale and ability to adapt to evolving consumer preferences for convenience and functionality.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Unilever PLC |
| Nestlé S.A. |
| Cargill, Incorporated |
| Conagra Brands, Inc. |
| The Coca-Cola Company |
| Mondelēz International, Inc. |
| Keurig Dr Pepper Inc. |
| PepsiCo, Inc. |
| Others |
Cost & Logistics Intelligence
FSSC 22000 certification gates both supply qualification and price differentiation, driving manufacturers to invest in compliant production to access premium market segments. This dynamic integrates stringent food safety standards directly into the cost structure, influencing product positioning from raw material sourcing to final consumer pricing.
Pricing Analysis
Certification level (FSSC 22000, organic) creates the primary spread in the flavored powder drinks market. Pricing operates on a hybrid model, combining per-unit transactional sales with recurring subscription services for specialized brands. Brand loyalty and clean-label ingredient verification are significant price differentiation drivers. Pricing pressure stems from input cost volatility for functional ingredients like whey protein isolate. Health enthusiasts and athletes exhibit lower price sensitivity for performance-oriented formulations, while general beverage mix consumers are highly price-sensitive.
Supply Chain Analysis
Concentrated processing capacity for specialized functional ingredients, particularly whey protein in the United States and advanced vitamins in Europe, represents a critical chokepoint. The supply chain draws from diverse global sources for flavorings and sweeteners, with significant volumes originating from China and India. Input cost volatility for key raw materials like protein and botanical extracts poses a structural risk. Distribution runs through a dual model, leveraging traditional supermarkets for volume and online retail for specialized, direct-to-consumer access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a buyer-power-shift story, driven by the fragmentation of traditional retail channels and the rise of direct-to-consumer platforms that empower specialized brands.
For Market Incumbents: Fortify existing distribution networks by integrating digital sales capabilities and optimizing last-mile delivery for online orders. Diversify product portfolios into high-growth functional categories, leveraging established brand trust to counter emerging D2C threats. Invest in micro-encapsulation technology to protect sensitive ingredients, enhancing product stability and efficacy. Secure long-term supply agreements for key functional ingredients to mitigate input cost volatility.
For New Entrants and Emerging Players: Differentiate on formulation expertise and niche targeting, focusing on underserved dietary preferences like ketogenic or vegan powder mixes. Target Southeast Asian markets with tailored product offerings, capitalizing on a growing middle class and wellness consciousness. Leverage online retail and subscription models for direct customer engagement, bypassing traditional shelf-space competition. Emphasize transparent sourcing and clean-label claims to build consumer trust quickly.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across functional ingredient sourcing and micro-encapsulation technologies, signaling a need for strategic investments. The long-term viability favors entities capable of navigating complex international regulatory landscapes and verifying clean-label claims. Target niche health and wellness innovators with proprietary formulations or strong direct-to-consumer platforms. The signal to watch is the adoption rate of personalized nutrition solutions, indicating future market direction.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Expands market reach into high-growth functional beverage segments, attracting health-conscious consumers. |
| Direct-to-Consumer Expansion | Builds recurring revenue streams and fosters direct customer relationships for specialized brands. |
| Clean-Label Certification | Enhances consumer trust and product premiumization by verifying ingredient transparency and quality. |
| Micro-encapsulation Investment | Protects sensitive functional ingredients, improving product stability and efficacy for consumers. |
| Geographic Market Entry | Captures new demand in emerging markets like Southeast Asia, leveraging growing wellness trends. |
Research Approach
Operator-level perspectives from food scientists, product development managers, supply chain leads, and marketing executives anchored the qualitative base of this analysis. Primary interviews were triangulated with extensive secondary validation from regulatory filings by the U.S. FDA, European EFSA, and India's FSSAI, alongside industry association reports and public company financial statements. This approach ensured a robust bottom-up and top-down understanding of market dynamics.
Sensitivity analysis framed the quantitative modeling, assessing market behavior under various economic and regulatory conditions over the projection horizon. Segmentation dimensions modeled included product type (nutritional supplements, beverage mixes), form (granular, sachets), target audience (health enthusiasts, athletes), distribution channel (online retail, supermarkets), and regional regulatory frameworks. Compound annual growth rates were derived from a comprehensive evaluation of market drivers, restraints, and strategic opportunities, using consumer health consciousness indices and ingredient price forecasts as key inputs.
Material uncertainties — geopolitical events, rapid shifts in consumer health trends, and unforeseen regulatory changes — sit outside the modeled envelope, influencing future market trajectories. Forecasts reflect assumptions regarding current market structures and technological advancements. Practitioners should keep alternative scenarios live as ingredient supply chains and consumer preferences evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Rose Floral Water Market
Beverages
South America Mate Market
Beverages
Yerba Mate Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Soy Drinks Market
Beverages
Reconstituted Juice Market
Beverages
Blenders Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Victorian Jars Market
Beverages
South America Ready to Drink Beverages Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market
Beverages
Apple Cider Vinegar Market
Beverages
Nitro-Infused Cola Market