
 Orange Juice Market | 2026-2036
Orange Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Orange Juice Market Outlook
The gap between premium not-from-concentrate and commodity from-concentrate orange juice is expanding as consumers trade up for perceived freshness and lower processing intensity. Citrosuco leverages backward integration into Brazilian citrus groves to secure raw material cost stability across harvest cycles. Coca-Cola Company anchors its Minute Maid portfolio in retail shelf-space dominance through long-standing supermarket partnerships. PepsiCo differentiates Tropicana via cold-chain logistics investments that preserve flavor profiles in premium refrigerated segments.
Orange juice is the extracted liquid obtained from Citrus sinensis fruit, typically standardized to 11.8 degrees Brix soluble solids and pasteurized at 90–95 degrees Celsius to inactivate pectinesterase and ensure shelf stability; it serves primarily as a retail beverage and foodservice ingredient delivering vitamin C fortification. Not-from-concentrate commands the dominant value share as consumers pay premiums for minimal processing narratives, while organic certification captures the fastest volume growth trajectory driven by pesticide-residue concerns in conventional citrus agriculture. Bulk packaging for beverage manufacturers represents the most mature margin pool, with processors converting excess supply into concentrate for industrial formulation.
The FDA governs orange juice identity standards under 21 CFR 146.135–146.140, mandating minimum Brix levels and permissible additive disclosures that shape product formulation across domestic supply chains. USDA organic certification and EPA pesticide tolerance limits further constrain agricultural practices, elevating compliance costs for growers transitioning to certified organic groves. Stakeholders must monitor citrus greening disease spread and corresponding regulatory responses affecting grove replanting subsidies and import phytosanitary barriers.
Market Dynamics
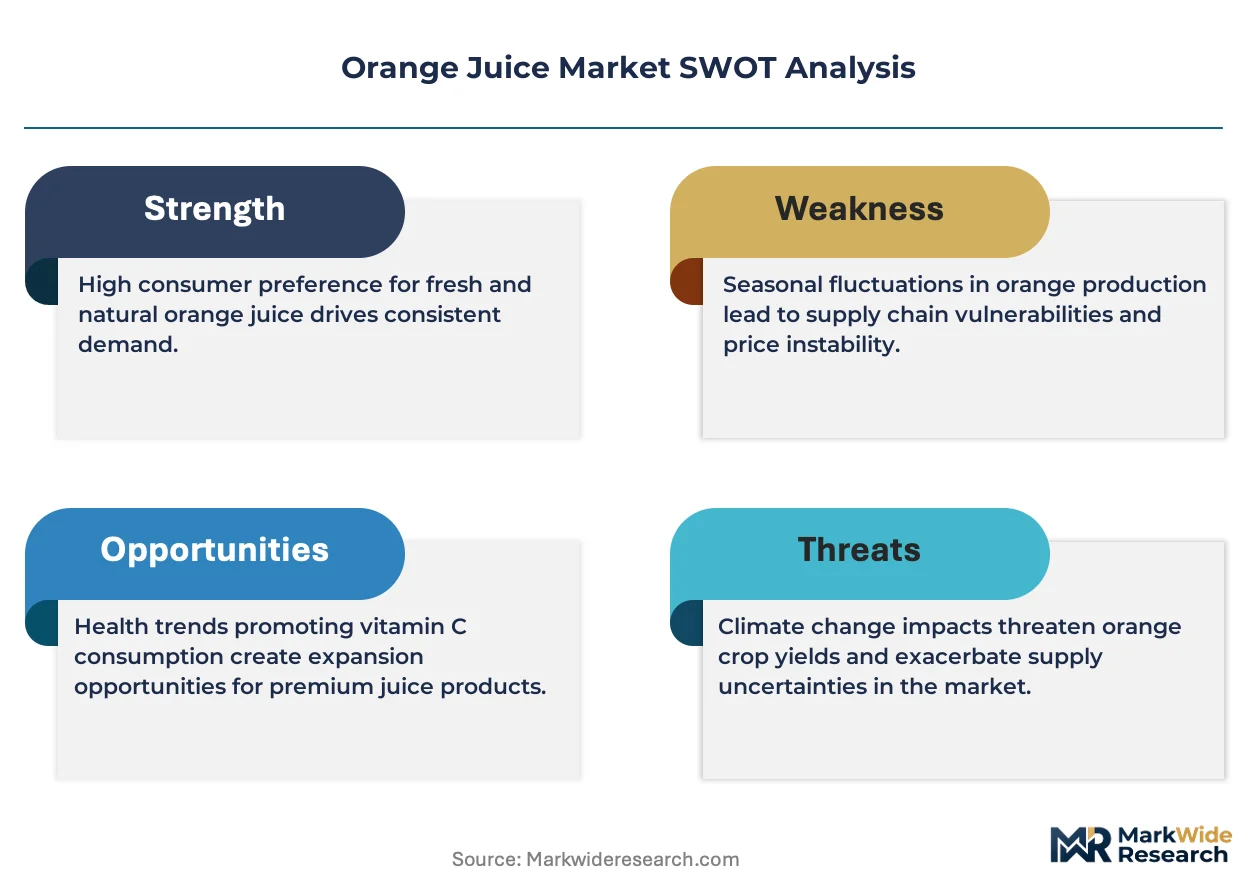
The FDA's updated Nutrition Facts labeling requirements for added sugars are forcing processors to reformulate products and reposition portfolios around clean-label positioning, while citrus greening disease pressures Brazilian and Floridian supply bases simultaneously.
Growth Catalysts
- Not-from-concentrate preference:North American retail beverage buyers in supermarkets are expanding purchases of NFC formats, trading up for perceived freshness and minimal processing narratives.
- 21 CFR 146.135–146.140 compliance:FDA identity standards mandate minimum Brix levels and additive disclosures that reinforce quality differentiation among compliant domestic processors.
- Cold-chain infrastructure:Refrigerated logistics investments preserve flavor profiles in premium segments, enabling extended distribution reach for temperature-sensitive NFC products.
Market Restraints
- Citrus greening disease:Huanglongbing pathogen devastates groves in São Paulo and Florida, compressing raw material availability and elevating replanting costs for growers.
- Input cost volatility:Fertilizer and fuel price swings in Brazilian real terms destabilize processor margins across harvest cycles.
- Substitution threat:Plant-based alternatives and functional waters capture health-conscious consumers seeking lower-sugar hydration options.
Strategic Opportunities
- Organic certification tailwind:USDA organic standards and EPA pesticide tolerance limits create premium positioning for growers transitioning certified groves, capturing fastest volume growth trajectory.
- Direct-to-foodservice channels:Bulk packaging for beverage manufacturers and institutional kitchens bypasses retail slotting fee structures, accessing mature margin pools.
- Phytosanitary barrier alignment:Export-oriented processors in Brazil's São Paulo citrus belt leverage growing phytosanitary compliance to capture expanding Asian import volumes.
Industry Challenges
- Grove replanting capex intensity:Citrus greening remediation requires multi-year capital deployment for resistant rootstock transitions and irrigation system upgrades.
- Certification timeline compression:USDA organic certification demands three-year transition periods with elevated compliance costs, delaying revenue recognition for transitioning growers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orange Juice Market |
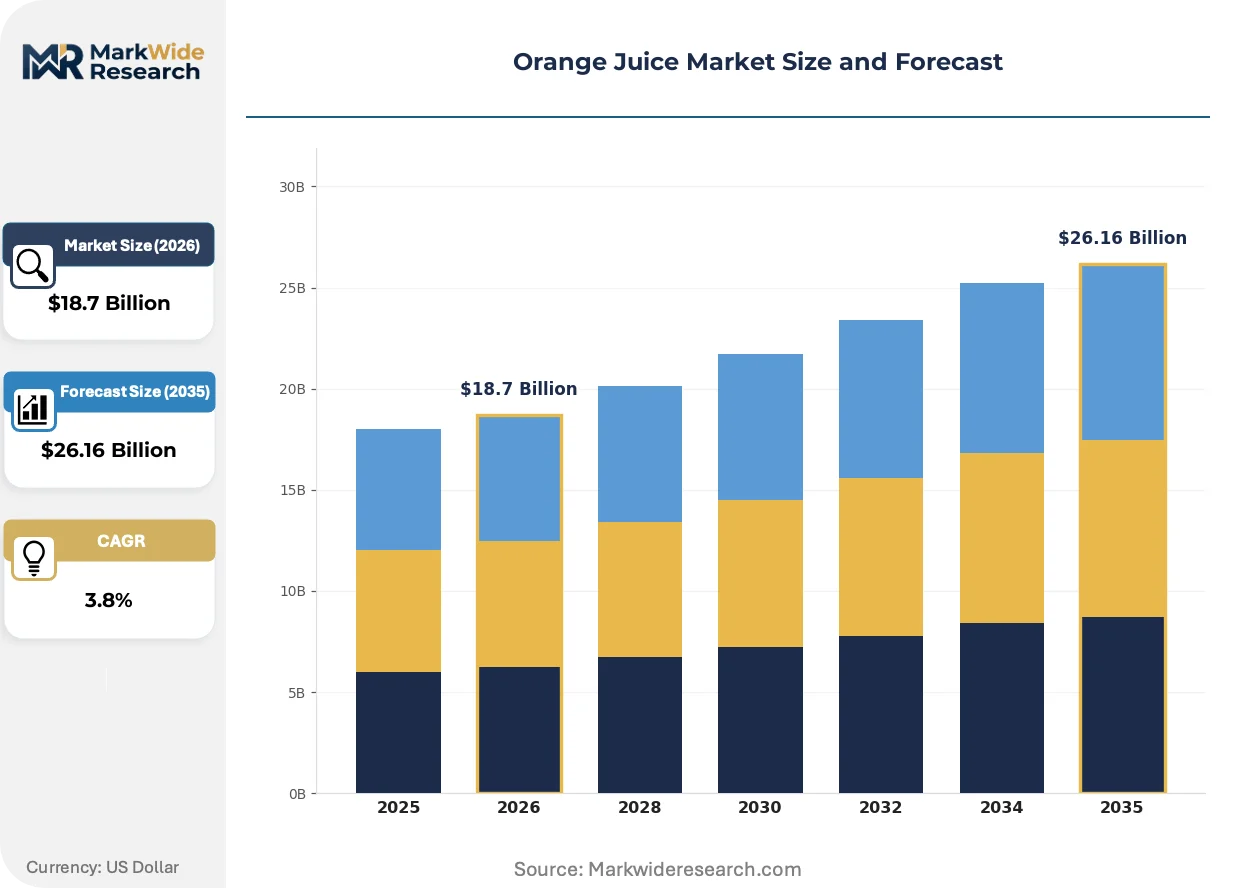
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Not From Concentrate, From Concentrate, Organic, Freshly Squeezed Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale End User: Households, Foodservice, Beverage Manufacturers, Exporters Packaging Type: Bottles, Cartons, Tetra Packs, Bulk |
| Companies Covered | Citrosuco, Dole Food Company, Inc., Coca-Cola Company (Minute Maid), Sunkist Growers, Inc., Florida's Natural Growers, PepsiCo, Inc. (Tropicana), Cutrale, Dr Pepper Snapple Group, Inc., Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orange Juice Market Strategic Shifts
Processing technology and regulatory disclosure requirements are reshaping competitive positioning across the orange juice value chain, compressing traditional concentrate economics while elevating premium cold-chain segments.
High-pressure processing technology is consolidating pasteurization alternatives across premium NFC lines. Retail chains with dedicated refrigerated sets are adopting HPP at accelerating rates. This non-thermal approach is consolidating shelf-life extension capabilities without the flavor degradation associated with 90–95 degree Celsius heat treatment, compressing the quality gap between industrial and artisanal production.
REACH chemical registration requirements in Europe are tightening additive disclosure standards for imported juice concentrates. Industrial buyers reformulating for EU compliance face elevated documentation burdens. Beverage manufacturers serving continental European markets are responding by sourcing from Brazilian processors with pre-certified supply chain traceability systems.
Buyer procurement patterns are rotating toward specification-grade contracts with embedded quality auditing clauses. Foodservice operators and co-manufacturers are displacing spot-market purchasing with multi-year agreements tied to Brix standardization and pesticide residue testing protocols. This contractual evolution is most visible in North American institutional channels where volume buyers demand 11.8 degrees Brix consistency with full agricultural input documentation.
Orange Juice Market Segmentation
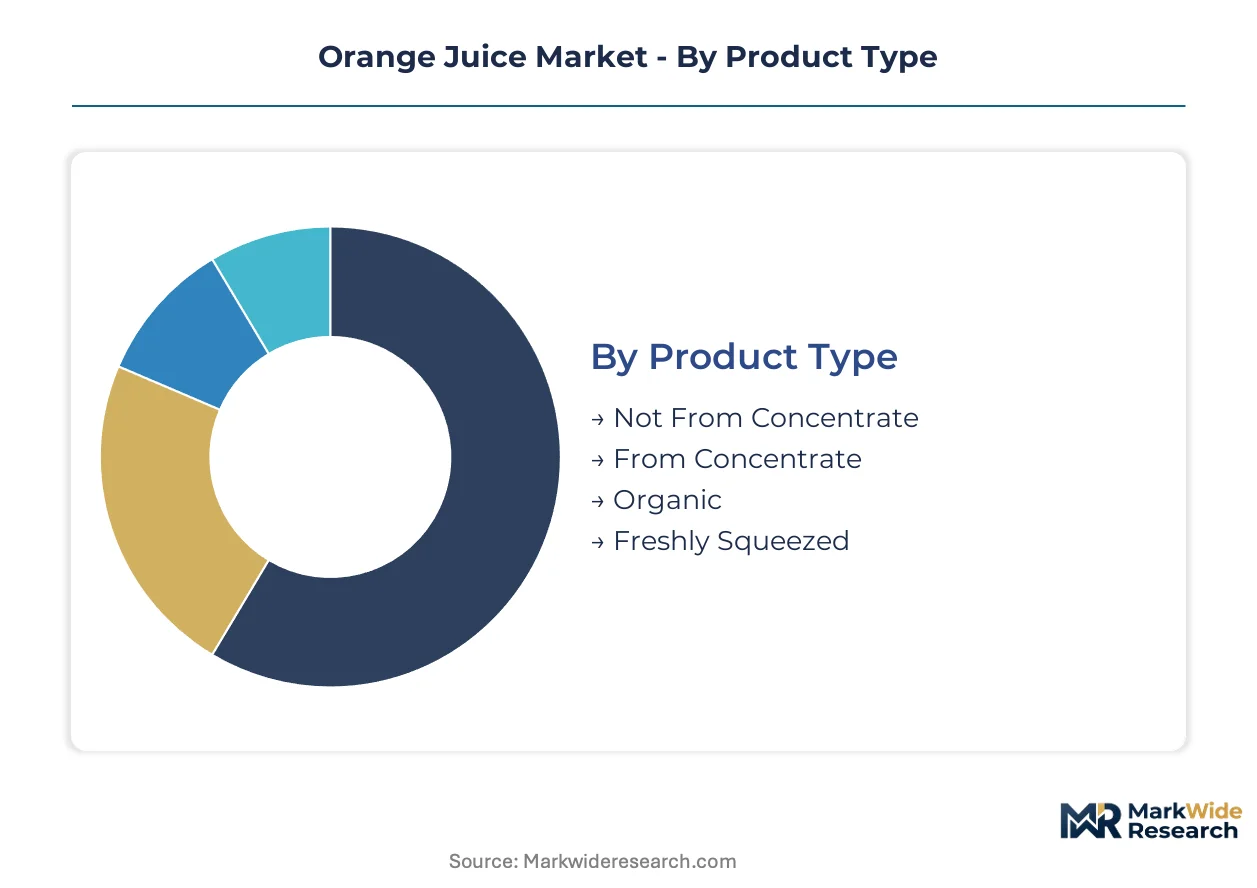
Orange juice processors segment portfolios across processing intensity, distribution reach, and customer specifications to capture divergent margin pools. Each segmentation dimension carries distinct capital requirements and regulatory exposure that shape competitive positioning across harvest cycles.
Product Type:
Consumer upgrade cycles from commodity concentrate to premium minimally-processed formats are compressing traditional economics while elevating cold-chain infrastructure requirements.
- Not From Concentrate:Single-strength juice pasteurized at lower thermal loads retains volatile flavor compounds and cloud stability. North American supermarket refrigerated sets anchor demand for NFC's perceived freshness narrative, with retailers allocating expanded shelf space to chilled premium placements.
- From Concentrate:Evaporated and reconstituted product standardized to 11.8 degrees Brix offers supply flexibility and ambient distribution economics. Bulk institutional procurement and private-label retail programs concentrate volume in this segment despite narrowing household penetration.
- Organic:USDA-certified groves meeting EPA pesticide tolerance limits command three-year transition timelines and elevated agricultural input costs. Health-conscious households seeking residue-free alternatives drive the steepest expansion trajectory in premium retail channels.
- Freshly Squeezed:Unpasteurized juice with minimal shelf life serves immediate-consumption occasions in foodservice and specialty retail. Brazilian São Paulo processors and Florida grove operators supply this perishable segment through expedited logistics networks.
Volume placements concentrate in From Concentrate; the faster expansion belongs to Organic.
Distribution Channel:
Channel economics vary sharply across customer acquisition costs, temperature control requirements, and slotting fee structures that determine net processor margins.
- Supermarkets:Brick-and-mortar retail with dedicated refrigerated sets and ambient juice aisles captures the dominant value share through high-frequency household shopping trips. Long-standing supplier relationships and category captain arrangements entrench incumbent processors.
- Online Retail:Direct-to-consumer and third-party marketplace fulfillment demands specialized cold-chain last-mile capabilities. Subscription models for premium NFC and organic formats are expanding most quickly in urban markets with dense delivery networks.
- Convenience Stores:Ambient shelf-stable concentrates and single-serve chilled bottles serve immediate consumption and travel occasions. Limited refrigeration capacity constrains premium SKU penetration.
- Wholesale:Foodservice distributors and institutional procurement channels bypass retail markups through specification-grade bulk contracts. Brix standardization and full agricultural documentation requirements characterize this mature margin pool.
Supermarkets dominate absolute volume; online retail channels are climbing the fastest.
End User:
Customer specifications diverge across consumption occasion, quality auditing requirements, and contract structures that shape processor salesforce deployment.
- Households:Individual and family consumption drives retail pack sizes from single-serve to multi-liter containers. Breakfast occasion anchoring and vitamin C fortification messaging sustain repeat purchase behavior.
- Foodservice:Restaurants, hotels, and institutional kitchens demand consistent Brix profiles and food safety documentation. Multi-year supply agreements with embedded quality auditing clauses are displacing spot-market purchasing.
- Beverage Manufacturers:Industrial buyers formulate orange juice into blends, smoothies, and functional beverages requiring concentrate or NFC inputs. REACH compliance and additive disclosure standards tighten sourcing requirements for EU-bound products.
- Exporters:Brazilian processors in São Paulo's citrus belt capture Asian import volumes through phytosanitary certification alignment. Containerized bulk shipments and aseptic packaging extend shelf life for ocean freight transit.
Households anchor volume consumption; exporters are gaining share fastest on Asian demand.
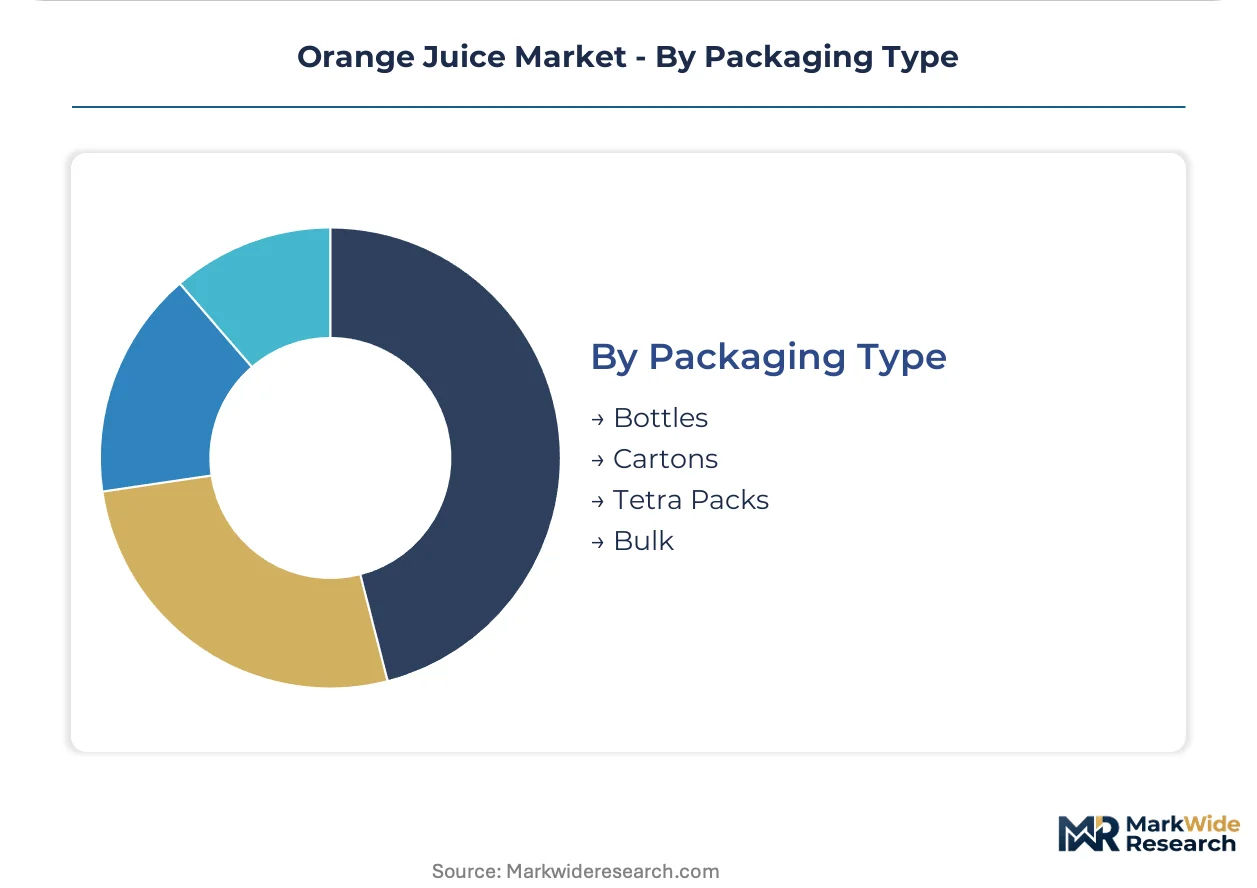
Packaging Type:
Material selection trades off shelf-life extension, temperature sensitivity, sustainability positioning, and unit economics across distribution distances.
- Bottles:PET and glass containers dominate refrigerated NFC retail, with clarity enabling visual quality signaling. Rigid packaging supports premium price positioning but elevates logistics cube and weight costs.
- Cartons:Gable-top paperboard with polyethylene barriers serves chilled retail and institutional channels. Renewable material content supports sustainability claims for environmentally-positioned brands.
- Tetra Packs:Aseptic brick carton technology enables ambient distribution of NFC and reconstituted products without refrigeration. Extended shelf life opens geographic expansion for processors lacking cold-chain infrastructure.
- Bulk:Stainless steel tanks, bag-in-box, and drum formats supply foodservice and industrial formulation. Lowest per-unit packaging cost supports mature margin pools in ingredient channels.
Cartons dominate household volume placements; Tetra Packs show the fastest expansion on ambient distribution advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's citrus belt anchors global orange juice processing capacity, with Brazilian processors capturing expanding export volumes through phytosanitary compliance alignment. Demand concentrates across four distinct national markets where regulatory frameworks and consumption patterns diverge sharply.
United States
Retail beverage buyers in North American supermarkets are expanding purchases of not-from-concentrate formats, trading up for perceived freshness. The FDA governs orange juice identity standards under 21 CFR 146.135–146.140, mandating minimum Brix levels and additive disclosures. Florida's grove operators supply the freshly squeezed segment through expedited logistics networks serving immediate-consumption occasions.
Brazil
Export-oriented processors capture growing Asian import volumes through containerized bulk shipments and aseptic packaging. ANVISA phytosanitary certification requirements shape export documentation burdens for São Paulo-based processors. The São Paulo citrus belt concentrates raw material availability despite citrus greening disease pressures elevating replanting costs for growers.
China
Urban households drive demand for premium NFC and organic formats through subscription models in dense delivery networks. SAMR food safety standards and GB labeling requirements constrain imported concentrate sourcing for beverage manufacturers. Yangtze River Delta retail chains allocate expanded shelf space to chilled premium placements.
Germany
Industrial buyers reformulating for EU compliance face elevated documentation burdens under REACH chemical registration requirements. EFSA additive disclosure standards tighten sourcing requirements for imported juice concentrates. Beverage manufacturers serving continental European markets source from Brazilian processors with pre-certified supply chain traceability systems.
Orange Juice Market Competitive Environment
Capital-heavy producers with captive citrus groves compete with asset-light brand marketers who outsource processing to third-party facilities. The market structure consolidates around three tiers: integrated Brazilian processors controlling upstream supply, multinational beverage conglomerates dominating retail shelf space, and regional cooperatives serving foodservice channels. Strategic moves concentrate on backward integration into Brazilian citrus groves and cold-chain logistics investments preserving flavor profiles in premium refrigerated segments.
Among Brazil-based integrated processors, Citrosuco and Cutrale exemplify the upstream-control archetype through grove ownership securing raw material cost stability. Coca-Cola Company and PepsiCo occupy positions as multinational brand architects leveraging long-standing supermarket partnerships and refrigerated distribution infrastructure. Florida's Natural Growers represents the cooperative model serving retail private-label and institutional procurement channels with specification-grade bulk contracts.
| Leading Market Players |
|---|
| Citrosuco |
| Dole Food Company, Inc. |
| Coca-Cola Company (Minute Maid) |
| Sunkist Growers, Inc. |
| Florida's Natural Growers |
| PepsiCo, Inc. (Tropicana) |
| Cutrale |
| Dr Pepper Snapple Group, Inc. |
| Nestlé S.A. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into Brazilian citrus groves anchors both supply security and pricing power for processors commanding premium not-from-concentrate tiers. Captive grove ownership insulates Citrosuco and Cutrale from raw material cost volatility while enabling margin capture across the value chain.
Pricing Analysis
Yield-per-hectare outcomes tether price premiums to grove productivity and disease resistance metrics. Three-tier pricing structure across premium not-from-concentrate, standard from-concentrate, and economy private-label levels segments buyers by quality tolerance and occasion. Cost compression in commodity concentrate tiers is intensifying because Brazilian real depreciation elevates export competitiveness. Foodservice procurement teams demonstrate highest price sensitivity; organic-certified retail households exhibit lowest elasticity.
Supply Chain Analysis
USDA organic certification and EPA pesticide tolerance limits gate supplier eligibility for premium channel access. Raw material availability concentrates in Brazil, the United States, and Mexico, with São Paulo's citrus belt feeding global export volumes. Processor operations hinge on fertilizer inputs, fuel for harvesting logistics, and aseptic packaging materials. Single-source vulnerability runs through Brazilian grove concentration exposed to citrus greening pathogen spread. Distribution runs through refrigerated cold-chain networks for premium tiers and ambient containerized bulk for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grove replanting cycles and resistant rootstock development timelines constrain supply expansion, propping pricing for processors with secured raw material positions.
For Market Incumbents: Acquire certified organic grove capacity to capture fastest-expanding premium segment demand. Defensive consolidation should prioritize cold-chain logistics assets preserving flavor profiles in not-from-concentrate distribution. Citrosuco's backward integration model demonstrates how upstream control counters substitution threats from plant-based alternatives.
For New Entrants and Emerging Players: Capture direct-to-foodservice white space bypassing retail slotting fee structures. Online retail subscription models for organic formats in dense urban delivery networks offer the most penetrable entry vector. Private-label manufacturing for supermarket chains provides volume scale without brand marketing overhead.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated Brazilian processors with phytosanitary-certified export infrastructure. Long-term viability across the analysis window favors upstream assets with multi-year grove supply contracts. Monitor citrus greening disease spread rates in São Paulo as the critical inflection signal for raw material cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Groves | Captive supply secures USDA organic positioning against EPA tolerance compliance costs. |
| Cold-Chain Infrastructure Expansion | Refrigerated distribution preserves NFC flavor profiles for premium supermarket placement. |
| Direct-to-Foodservice Channel Development | Bulk specification contracts bypass retail markups accessing mature institutional margin pools. |
| Phytosanitary Certification Alignment | ANVISA compliance enables Brazilian processors to capture expanding Asian import volumes. |
| High-Pressure Processing Technology Deployment | Non-thermal pasteurization extends shelf life without FDA-mandated heat treatment flavor degradation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with citrus grove operators, processor procurement directors, supermarket category buyers, foodservice distribution managers, and cold-chain logistics providers validated demand patterns. FDA 21 CFR identity standards documentation, USDA organic certification databases, Brazilian ANVISA export records, and EU REACH chemical registration filings supplied regulatory constraint parameters. Bottom-up volume modeling triangulated against top-down value reconstructions.
Segment-level granularity modeled processing intensity tiers, distribution channel economics, and end-user specification requirements across the projection horizon. Product type segmentation captured not-from-concentrate, from-concentrate, organic, and freshly squeezed format dynamics. CAGRs derived from harvest cycle volume projections, export flow trajectories, and per-capita consumption elasticity estimates. Citrus greening disease spread assumptions and resistant rootstock adoption curves shaped supply-side constraints.
The model holds under stable phytosanitary regulatory frameworks; deviation in FDA additive disclosure mandates or EU REACH enforcement intensity would shift processor compliance cost structures. Forecasts embed assumptions regarding Brazilian real exchange rate stability and fertilizer input cost trajectories. A model refresh is warranted upon material change in citrus greening remediation subsidy programs or Asian import tariff schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
South East Asia Bottled Water Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
North America Yerba Mate Market
Beverages
Soy Drinks Market
Beverages
Hydration Infusers Market
Beverages
Germany Probiotic Drinks Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
India Bottled Water Market
Beverages
India Cafes & Bars Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Birch Water Market
Beverages
India Soy Beverages Market
Beverages
Vegetable Juice Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Apple Cider Vinegar Market