
 Global Nutating Mixers Market | 2026-2036
Global Nutating Mixers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nutating Mixers Market Foresight
The capital-intensity divergence between precision-engineering specialists and volume-oriented assemblers is bifurcating competitive dynamics in nutating mixer supply. Thermo Fisher Scientific leverages captive manufacturing of brushless drive systems to sustain premium positioning in pharmaceutical-grade equipment. IKA Works GmbH anchors its European franchise through specialized multi-stage configurations for high-viscosity chemical processing. Benchmark Scientific competes on modular platform architectures that reduce field service costs for mid-scale laboratories.
Nutating mixers employ a three-dimensional orbital motion where the mixing vessel tilts and rotates simultaneously, typically operating at speeds between 20 and 100 rpm with tilt angles of 20 to 35 degrees to achieve homogeneous blending without shear damage to sensitive formulations. The primary industrial purpose centers on gentle mixing of cell cultures, pharmaceutical suspensions, and cosmetic emulsions where conventional agitation would compromise product integrity. Variable-speed electric units command the widest application footprint across pharmaceutical end users, while magnetic drive technology is gaining fastest in aseptic processing environments where seal contamination risks must be eliminated. Fixed-speed pneumatic models retain durable positions in hazardous chemical processing settings where electrical spark hazards are restricted.
FDA cGMP guidelines and EMA Annex 1 sterile manufacturing requirements shape material selection, surface finish standards, and validation documentation burdens for equipment suppliers seeking pharmaceutical market access. ISO 9001 quality management and IEC 61010 electrical safety certifications operate as baseline market-entry requirements across all major jurisdictions, with regional additions such as CE marking under the EU Machinery Directive. Stakeholders must monitor evolving clean-in-place validation protocols and energy efficiency regulations as procurement criteria tighten in regulated processing industries.
Market Dynamics
Pharmaceutical manufacturers in Germany, the United States, and South Korea are consolidating procurement around FDA-validated variable-speed electric units, compressing supplier margins for non-validated equipment and concentrating demand among precision-engineering specialists with captive brushless drive capabilities.
Growth Catalysts
- EMA Annex 1 sterile manufacturing mandates:European biologics producers must replace legacy agitation equipment with seal-free magnetic drive nutating mixers, creating replacement demand across GMP-certified facilities.
- Cell therapy manufacturing expansion:Commercial-scale allogeneic cell production requires gentle three-dimensional orbital motion to preserve cell viability, driving specification of tilt-angle-optimized units in cleanroom environments.
- South Korean pharmaceutical cluster consolidation:MFDS-registered CDMOs in Songdo and Osong are standardizing on variable-speed electric platforms for multi-product bioreactor feeding operations.
Market Restraints
- Brushless motor supply concentration:Precision-matched drive systems for pharmaceutical-grade tilt control depend on Japanese and German motor specialists, exposing assemblers to 16-24 week lead times.
- Stainless steel 316L price volatility:Vessel fabrication costs fluctuate with nickel alloy markets, compressing margins for volume-oriented suppliers without long-term material hedging.
- Magnetic drive torque limitations:Current seal-free technologies cannot reliably transmit sufficient rotational force above 80 rpm in high-viscosity chemical suspensions, restricting application scope.
Strategic Opportunities
- India biologics manufacturing buildout:CDSCO's accelerated approval pathways for biosimilars are attracting greenfield investments in Hyderabad and Bengaluru, creating first-mover positioning for validated equipment suppliers.
- Single-use vessel integration:Convergence of disposable polymer technologies with precision tilt mechanisms enables campaign-based manufacturing without CIP validation burdens.
- EU Green Deal energy efficiency incentives:Brushless DC drive retrofits qualify for national industrial decarbonization grants in Germany and the Netherlands, subsidizing upgrade cycles.
Industry Challenges
- Clean-in-place validation documentation:FDA 483 observations for inadequate surface finish verification are extending commissioning timelines by 4-8 months for new installations.
- Multi-axis motion control integration:Legacy distributed control systems in chemical processing plants require costly PLC upgrades to interface with modern variable-frequency drive protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nutating Mixers Market |
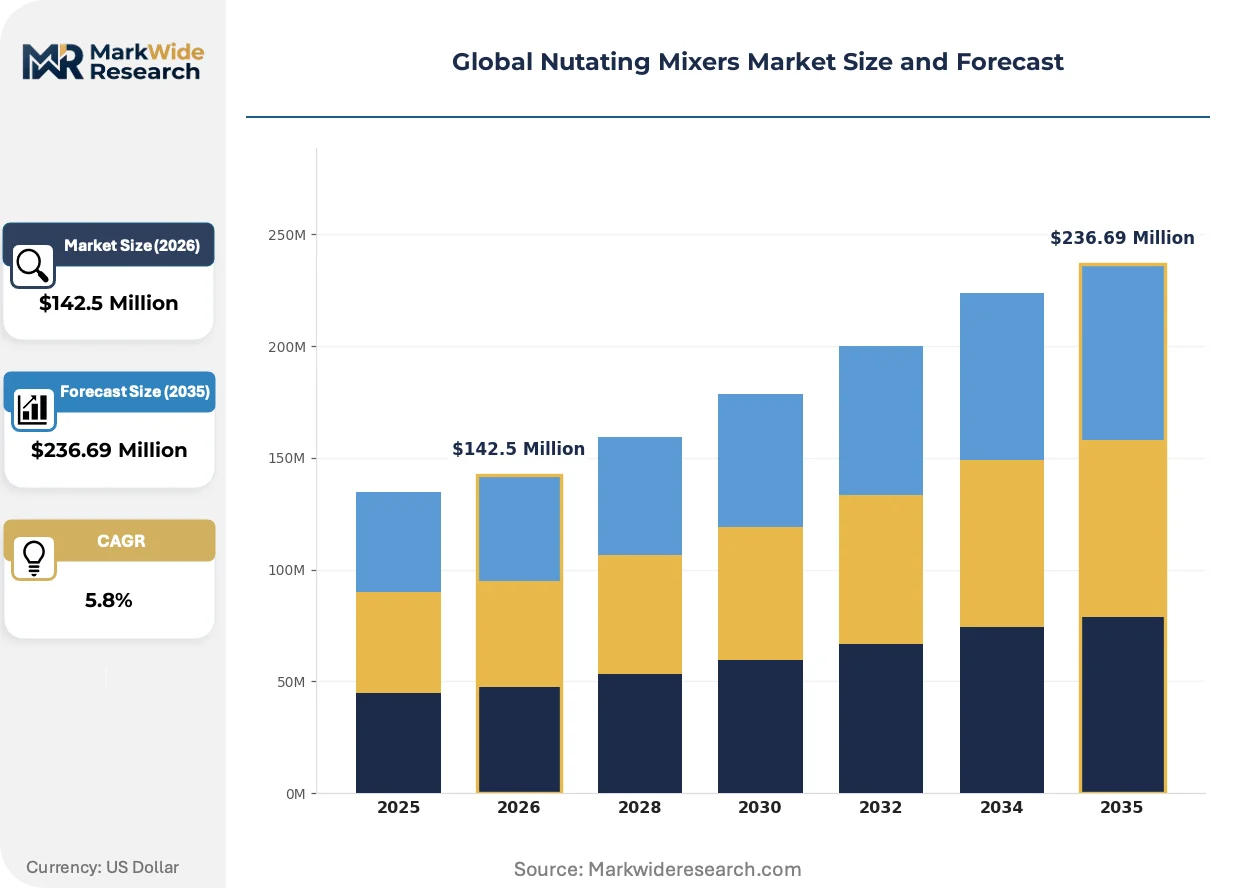
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-stage, Multi-stage, Variable-speed, Fixed-speed, Magnetic drive Technology: Hydraulic, Pneumatic, Electric, Manual, Gear-driven Application: Chemical Processing, Food & Beverage, Pharmaceuticals, Water Treatment, Cosmetic Manufacturing End User: Chemical Plants, Food Processors, Drug Manufacturers, Wastewater Facilities, Personal Care Producers |
| Companies Covered | Thermo Fisher Scientific, Cole-Parmer, Benchmark Scientific, Heidolph Instruments, IKA Works GmbH, Silverson Machines, Admix Inc., Eppendorf AG, Labnet International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nutating Mixers Market Shifts & Advancements
Equipment architecture is separating into two distinct performance tiers as end-users sharpen specifications around aseptic validation, energy efficiency, and digital integration capabilities.
Brushless DC drive technology with integrated variable-frequency control is bifurcating the installed base. Pharmaceutical manufacturers with FDA submission requirements specify closed-loop speed regulation below 0.5% variance for cell culture applications. Chemical processors without sterile constraints continue sourcing conventional AC induction motors, widening the performance gap between validated and industrial-grade procurement categories.
REACH restrictions on perfluorinated compounds are forcing seal material transitions in European pharmaceutical equipment. Suppliers must validate alternative elastomer compounds for magnetic drive isolation barriers under ECHA scrutiny. German and Swiss equipment manufacturers are accelerating fluoropolymer-free seal development to maintain CE marking compliance for 2025 implementation deadlines.
Service contract unbundling is disrupting traditional capital-equipment sales models. Mid-scale biotechnology laboratories in the United States now lease tilt-mechanism platforms with per-batch usage fees rather than purchasing outright. Thermo Fisher and IKA Works are piloting subscription-based maintenance and calibration programs in Boston and San Diego clusters to capture recurring revenue from capital-constrained emerging biotechs.
Global Nutating Mixers Market Segmentation
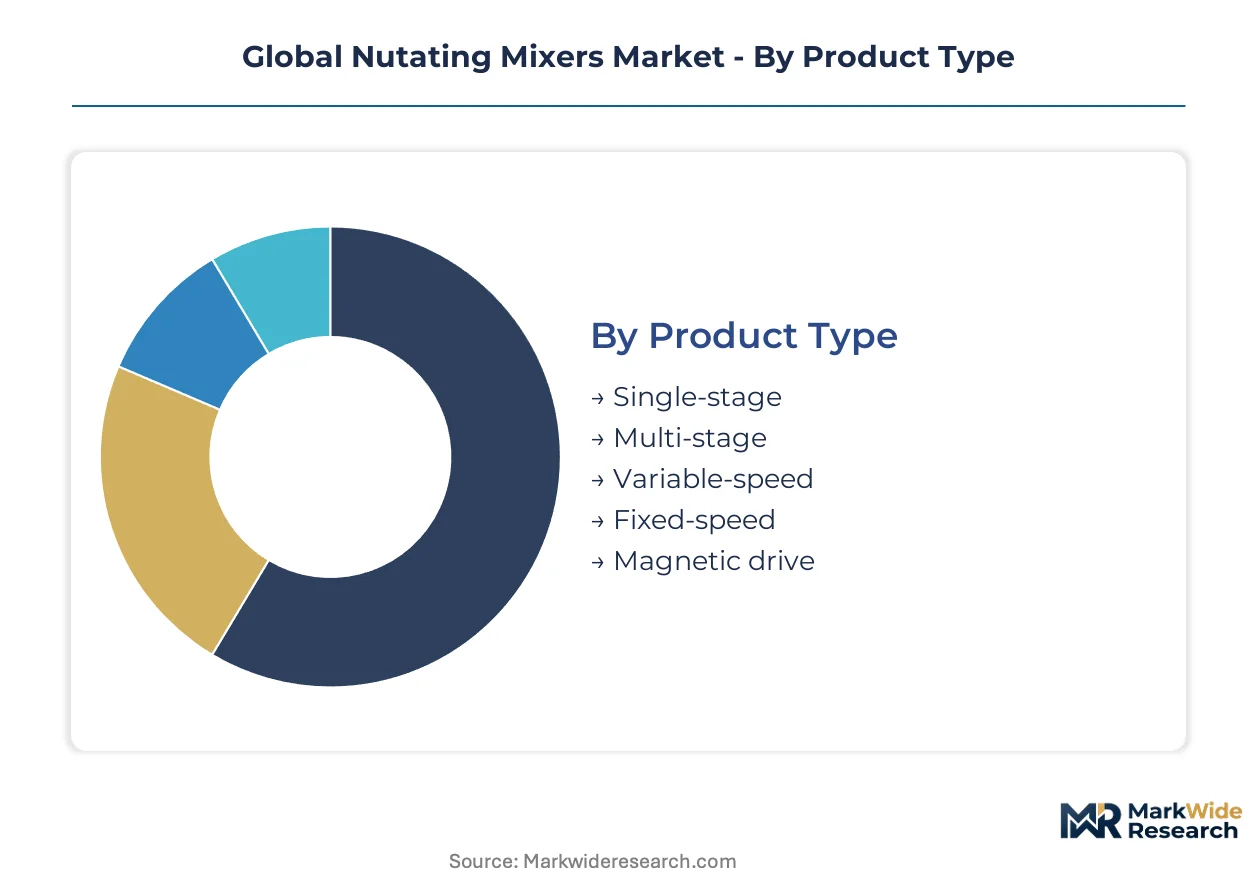
Segmentation in nutating mixers reveals how technical specifications diverge across regulatory environments and viscosity demands. Procurement patterns split sharply between validated pharmaceutical platforms and industrial chemical workhorses. Understanding these fault lines exposes where substitution pressure from orbital shakers, magnetic stirrers, and peristaltic pumps threatens incumbent technologies.
Product Type:
Substitution pressure from magnetic stirrers and orbital shakers concentrates most intensely on fixed-speed pneumatic units, while variable-speed electric platforms defend position through closed-loop precision that alternative technologies cannot replicate.
- Variable-speed:Brushless DC drives with closed-loop frequency control maintain speed variance below 0.5% for cell culture applications. Drug manufacturers in Germany and the United States specify these units for bioreactor feeding operations where shear sensitivity demands precise tilt-angle modulation.
- Magnetic drive:Seal-free torque transmission eliminates contamination risks in aseptic processing. EMA Annex 1 sterile manufacturing mandates are accelerating replacement of conventional shaft-sealed units in European GMP-certified facilities, though torque limitations above 80 rpm restrict high-viscosity chemical applications.
- Single-stage:Basic tilt-rotation mechanisms serve standard laboratory blending with minimal moving parts.
- Multi-stage:Cascaded orbital motion profiles handle progressive viscosity changes in polymer synthesis.
- Fixed-speed:Pneumatic actuation persists in hazardous chemical environments where electrical spark risks trigger ATEX restrictions.
Variable-speed electric units anchor the volume base while magnetic drive configurations gain share at the steepest rate.
Technology:
Cost tier stratification separates premium closed-loop electric systems from maintenance-intensive pneumatic infrastructure, with hydraulic and manual technologies occupying shrinking niche positions.
- Electric:Variable-frequency drives with brushless motors dominate pharmaceutical procurement through energy efficiency and digital integration capabilities. EU Green Deal industrial decarbonization grants in Germany and the Netherlands subsidize retrofit cycles, accelerating displacement of legacy AC induction systems.
- Pneumatic:Compressed-air actuation retains durable positions in explosive atmosphere classifications where IECEx compliance mandates non-electrical power transmission. Chemical processors in South Korea's Yeosu industrial cluster specify these units for solvent-based suspension handling.
- Hydraulic:High-torque fluid power systems persist in heavy-viscosity chemical processing despite maintenance burdens.
- Manual:Hand-cranked mechanisms survive in field-deployable or backup power scenarios with minimal specification requirements.
- Gear-driven:Mechanical ratio systems occupy cost-sensitive industrial applications where speed precision is secondary to capital expenditure constraints.
Electric platforms command the premium tier while pneumatic systems defend installed base through hazardous location certification.
Application:
Application segmentation tracks how viscosity ranges and regulatory stringency reshape competitive dynamics across processing industries.
- Pharmaceuticals:Aseptic cell culture, vaccine suspension, and biologic formulation work demand FDA-validated surface finishes and clean-in-place protocols. CDSCO's accelerated biosimilar approval pathways in India are attracting greenfield investments in Hyderabad and Bengaluru, expanding addressable demand for validated equipment.
- Chemical Processing:High-viscosity polymer and suspension handling prioritizes torque transmission over sterile containment. REACH restrictions on perfluorinated compounds are forcing seal material transitions in European equipment, compressing margins for suppliers without fluoropolymer-free alternatives.
- Food & Beverage:Hygienic design requirements under FDA Food Safety Modernization Act and EU hygiene package directives govern material selection.
- Cosmetic Manufacturing:Emulsion stability testing and batch consistency protocols drive specification in personal care clusters.
- Water Treatment:Coagulant dispersion and sludge conditioning applications emphasize corrosion resistance over precision control.
Pharmaceutical applications concentrate the highest margins while chemical processing provides the broadest volume foundation.
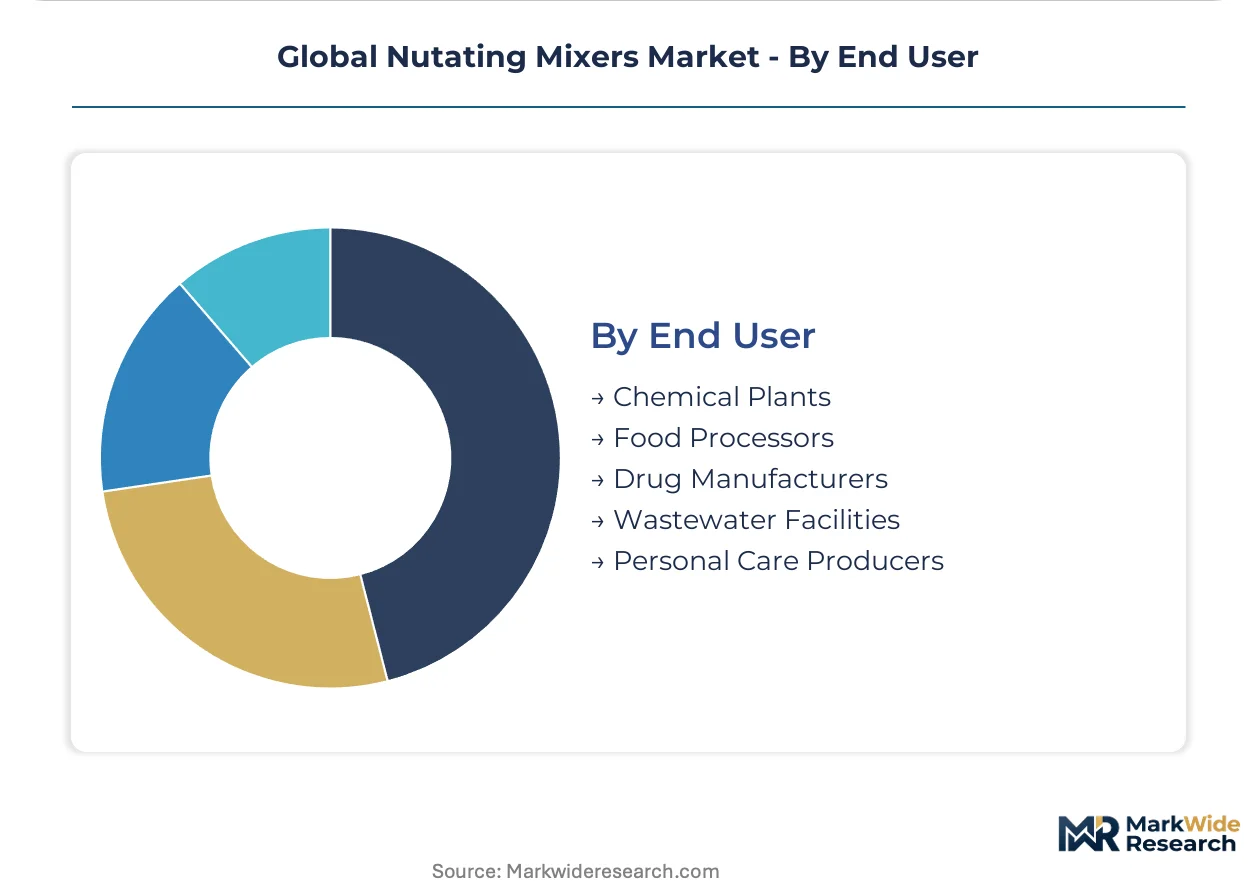
End User:
Customer type segmentation exposes divergent procurement authority structures between centralized pharmaceutical engineering teams and distributed chemical plant maintenance organizations.
- Drug Manufacturers:Corporate engineering standards at firms like Thermo Fisher's bioproduction customers mandate platform standardization across multi-site networks. Service contract unbundling is disrupting capital sales models, with Boston and San Diego biotechnology clusters piloting subscription-based maintenance programs.
- Chemical Plants:Distributed maintenance budgets and legacy distributed control systems create upgrade friction. Multi-axis motion control integration demands costly PLC modifications to interface with modern variable-frequency drive protocols, extending replacement cycles.
- Food Processors:USDA and FDA food safety compliance drives hygienic design specifications with cleanability documentation requirements.
- Personal Care Producers:Campaign-based manufacturing patterns favor modular platforms with rapid changeover capabilities.
- Wastewater Facilities:Municipal procurement cycles and total cost of ownership calculations prioritize equipment longevity over technical sophistication.
Drug manufacturers set the specification frontier while chemical plants provide the recurring replacement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision-engineering clusters while volume procurement gravitates toward South Korean pharmaceutical manufacturing hubs, creating a structural asymmetry in regional profitability.
United States
FDA cGMP validation requirements and cell therapy manufacturing expansion drive specification of brushless drive systems. The FDA's tightened sterile processing guidelines under 21 CFR Part 211 accelerate replacement cycles in legacy facilities. Boston and San Diego biotechnology clusters standardize on variable-speed electric platforms for multi-product bioreactor feeding operations.
Germany
EMA Annex 1 sterile manufacturing mandates and EU Green Deal industrial decarbonization grants reshape procurement toward magnetic drive and energy-efficient configurations. ECHA scrutiny of perfluorinated compounds forces seal material transitions before 2025 deadlines. Stuttgart and Karlsruhe precision-engineering clusters deepen captive manufacturing of brushless drive systems for pharmaceutical-grade tilt control.
South Korea
MFDS-registered CDMO consolidation and hazardous chemical processing demand bifurcate the installed base between validated electric units and ATEX-compliant pneumatic systems. The Yeosu industrial cluster specifies compressed-air actuation for solvent-based suspension handling, while Songdo and Osong pharmaceutical hubs standardize on variable-speed platforms.
India
CDSCO accelerated biosimilar approval pathways attract greenfield biologics investments in Hyderabad and Bengaluru. National pharmaceutical regulator mandates for aseptic processing equipment create first-mover positioning opportunities for validated suppliers. Domestic stainless steel 316L fabrication capabilities expand vessel production for mid-scale laboratory segments.
Switzerland
Swissmedic certification requirements and REACH compliance deadlines concentrate demand for fluoropolymer-free seal development among precision-equipment manufacturers. Basel pharmaceutical manufacturing clusters specify closed-loop speed regulation below 0.5% variance for cell culture applications. German-speaking equipment specialists leverage cross-border supply relationships with Baden-Württemberg component fabricators.
Global Nutating Mixers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision-engineering specialists commanding premium positioning through captive drive system manufacturing while volume-oriented assemblers compete on modular platform architectures. The vendor base separates into three strategic tiers: integrated multinationals with pharmaceutical validation capabilities, regional specialists in high-viscosity chemical processing, and modular platform providers targeting mid-scale laboratories. Dominant competitive moves include backward integration into brushless motor supply chains and geographic expansion into India's emerging biologics manufacturing corridors.
Among integrated laboratory equipment multinationals, Thermo Fisher Scientific and Eppendorf AG exemplify the validation-centric archetype, while IKA Works GmbH represents German precision-engineering specialization in multi-stage chemical processing configurations. Benchmark Scientific occupies a position within the modular platform tier, targeting capital-constrained emerging biotechnology operations with service-contract unbundling models.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Cole-Parmer |
| Benchmark Scientific |
| Heidolph Instruments |
| IKA Works GmbH |
| Silverson Machines |
| Admix Inc. |
| Eppendorf AG |
| Labnet International |
| Others |
Supply & Pricing Matrix
FDA cGMP validation requirements and EMA Annex 1 sterile manufacturing mandates simultaneously gate supplier qualification and create three-tier price stratification across pharmaceutical-grade, industrial-grade, and non-validated equipment tiers. This dual-gating mechanism concentrates pricing power among precision-engineering specialists with captive brushless drive manufacturing while compressing margins for volume-oriented assemblers dependent on external motor sourcing.
Pricing Analysis
The customization-premium spread between configured-to-order FDA-validated units and standard catalog equipment spans roughly 40-60 percent in effective pricing, with brushless DC drive integration and surface finish documentation driving the wedge. Price differentiation rests on certification grade (FDA/EMA tier vs. industrial grade) and after-sales service bundling, with subscription-based maintenance models gaining traction in Boston and San Diego biotechnology clusters. Cost compression in the non-validated tier is intensifying because South Korean and Indian domestic fabricators are expanding stainless steel vessel production. Mid-scale contract development and manufacturing organizations exhibit highest price sensitivity, while multi-site pharmaceutical engineering teams at top-tier drug manufacturers prioritize specification compliance over unit economics.
Supply Chain Analysis
Strategic stockpiling of Japanese and German precision-matched brushless motors has become standard practice among pharmaceutical-grade equipment manufacturers facing 16-24 week lead time exposures. Geographic supply concentration centers on Germany, Japan, and South Korea for motion control systems, with domestic stainless steel 316L fabrication expanding in India and China for vessel production. Raw material dependencies include nickel alloy pricing volatility, rare-earth magnet availability, and specialized elastomer compounds for seal-free magnetic drive barriers. Single-source vulnerability in precision motor supply creates structural risk for assemblers without backward integration into drive system manufacturing. Distribution runs through direct OEM channels for validated pharmaceutical equipment and regional distributor networks for industrial chemical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where FDA and EMA validation documentation creates switching costs that lock pharmaceutical manufacturers into established supplier relationships. The defensive moat deepens as clean-in-place protocol verification extends commissioning timelines and raises barriers for unvalidated competitors.
For Market Incumbents: Compound defensive positioning through backward integration into brushless motor supply chains and expansion of captive manufacturing in Stuttgart and Karlsruhe precision-engineering clusters. Magnetic drive torque limitations above 80 rpm present vulnerability to orbital shaker substitution in high-viscosity chemical processing; preemptive R&D investment in enhanced torque transmission architectures protects installed base. Capacity addition in Hyderabad and Bengaluru CDSCO-registered corridors captures India biologics manufacturing buildout before validation documentation requirements fully crystallize.
For New Entrants and Emerging Players: CDSCO accelerated approval pathways for biosimilars offer the most penetrable entry vector, with greenfield investments in Hyderabad and Bengaluru creating first-mover positioning before FDA-validated incumbents establish local service infrastructure. Single-use vessel integration with precision tilt mechanisms represents underserved white space in campaign-based manufacturing segments. Go-to-market execution should emphasize modular platform architectures with rapid field service deployment to differentiate from entrenched precision-engineering specialists.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across magnetic drive and brushless DC configurations as REACH-compliant seal development and fluoropolymer-free material validation escalate fixed R&D burdens. Long-term viability across the five-to-ten year window favors precision-engineering specialists with captive drive manufacturing over volume-oriented assemblers exposed to motor supply concentration. Acquisition target archetype: mid-scale German or Swiss equipment manufacturers with EMA validation credentials and underutilized brushless motor fabrication capacity. Signal to watch: MFDS-registered CDMO procurement standardization in Songdo and Osong as indicator of Asia-Pacific specification migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brushless Drive Manufacturing | Captive motor production insulates Thermo Fisher and IKA Works from Japanese supply concentration. |
| Fluoropolymer-Free Seal Development | REACH compliance deadlines force ECHA-validated material transitions before 2025 implementation. |
| Subscription-Based Maintenance Programs | Per-batch usage fees capture recurring revenue from capital-constrained Boston biotechnology clusters. |
| Single-Use Vessel Integration | Disposable polymer convergence eliminates CIP validation burdens for campaign-based manufacturing. |
| Geographic Expansion into India Biologics Corridors | CDSCO accelerated pathways attract greenfield Hyderabad and Bengaluru investments for first-mover positioning. |
Research Methodology
A spread of perspectives from pharmaceutical engineering directors, CDMO procurement leads, chemical plant maintenance managers, and precision-equipment manufacturing executives converged on the working assumptions. Primary interviews with regulatory affairs specialists at FDA-validated facilities and aftermarket service heads at German and Swiss equipment manufacturers combined with secondary validation from EMA submission databases, FDA 483 observation records, and SEC filings of listed laboratory equipment multinationals. Bottom-up unit demand modeling and top-down industry revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled include product type (variable-speed electric, magnetic drive, fixed-speed pneumatic), technology tier (brushless DC, conventional AC, compressed-air actuation), application vertical (pharmaceutical, chemical processing, food and beverage), and end-user category (drug manufacturers, chemical plants, contract research organizations) across the projection horizon. CAGRs were derived from regression analysis against biologics manufacturing capacity expansion, sterile processing regulatory enforcement intensity, and industrial decarbonization subsidy uptake. Industry-specific forecast inputs incorporated MFDS-registered CDMO procurement patterns and EU Green Deal energy efficiency retrofit cycles.
Decision-makers should treat outputs as directional under base assumptions of sustained EMA Annex 1 enforcement and continued nickel alloy price volatility; material deviation would warrant model refresh. Forecasts reflect documented assumptions regarding brushless motor supply lead times and REACH seal material transition timelines. Revision becomes warranted when magnetic drive torque performance crosses thresholds enabling high-viscosity chemical substitution or when CDSCO validation requirements diverge from FDA cGMP equivalence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Wine Bottling Machine Market
Food Processing Equipment
Batter Mixer Machines Market
Food Processing Equipment
Edible Collagen Casing Market
Food Processing Equipment
Planetary Mixer Market
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Walk-In Refrigerators & Freezers Market
Food Processing Equipment
Pea Protein Processing Equipment Market
Food Processing Equipment
Kebab Machine Market
Food Processing Equipment
Semi-Auto Egg Tart Forming Machine Market
Food Processing Equipment
Yogurt Makers Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Food Processing Machinery Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Food Waste Shredder Market