
 Tonic Water Market | 2026-2036
Tonic Water Market Size, Share, and Industry Trends Forecast 2026-2036
Tonic Water Market Intelligence
A shift in buyer concentration, with consolidation in the hospitality industry and fragmentation in online retail, is realigning channel strategies. Fevertree Drinks PLC leverages its premium brand positioning to dominate the high-end mixer segment. The Coca-Cola Company sustains its market presence through the widespread distribution of its Schweppes brand. Meanwhile, craft producers like Fentimans Ltd. differentiate through unique botanical infusions and traditional production methods.
Tonic water is a carbonated soft drink defined by the inclusion of quinine, which imparts its characteristic bitter taste. Formulations typically contain a sweetener and may include various citrus or herbal flavorings for complexity. Its primary commercial purpose is as a mixer for alcoholic spirits, particularly gin. While Classic Tonic remains the volume leader, the Flavored Tonic and Premium Tonic categories are expanding rapidly. The sales channel mix is evolving as Online Retailers gain share from traditional Supermarkets, especially for specialty brands.
Food safety and labeling standards from regulators like the U.S. FDA and the European Food Safety Authority (EFSA) govern ingredient usage and marketing claims. In markets such as India, the FSSAI imposes specific requirements on quinine content and sugar levels in carbonated beverages. Producers must now decide whether to prioritize mass-market volume with standard formulations or capture higher margins in niche, premium segments.
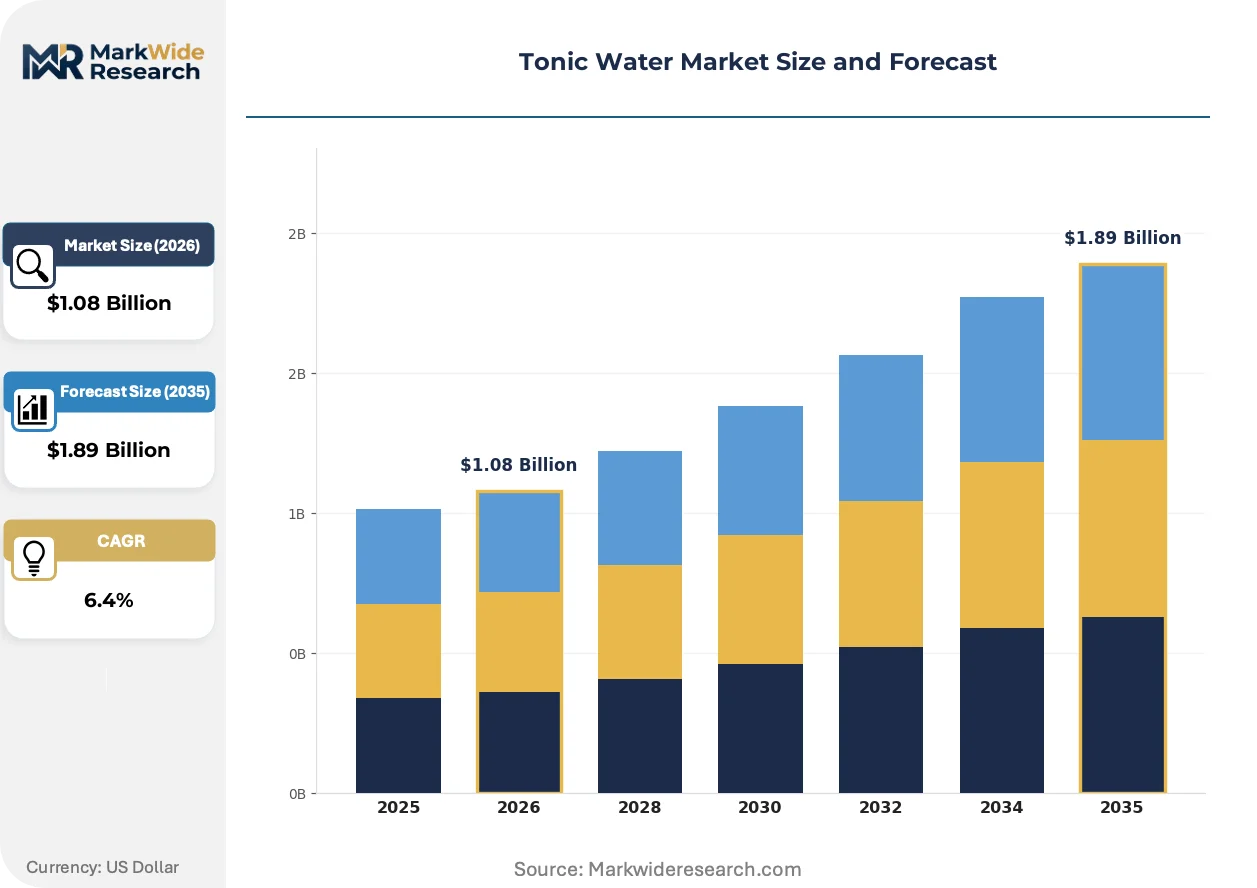
Market Dynamics
The central dynamic shaping the tonic water market is the consumer pivot towards health-conscious consumption, directly influencing product formulation. This shift compels producers to innovate with natural botanicals and low-sugar options to complement the premium spirits segment and expand occasions for use.
Growth Catalysts
- Premiumization of Spirits:The rising popularity of craft gin and premium cocktails in the hospitality sector creates a direct pull for sophisticated, high-quality mixers that can match the spirit's profile and price point.
- Expansion in Asia-Pacific:Growing disposable incomes and Western cultural influence in urban centers across countries like India and Japan are opening new consumer bases for tonic water, beyond its traditional European strongholds.
- Natural and Clean-Label Ingredients:Consumer demand for transparency and wellness pushes brands to adopt authentic botanicals and natural sweeteners, expanding the category's appeal to a broader health-aware demographic.
Market Restraints
- Quinine Supply Volatility:The supply of natural quinine, sourced from cinchona bark in regions like the Andean foothills, is subject to agricultural and geopolitical risks that can create raw material price instability.
- Competition from Other Mixers:A broadening array of carbonated beverages, including flavored seltzers and ginger ales, competes for the same consumption occasions, particularly outside of the core gin-and-tonic pairing.
- Sugar Taxation Policies:Government-imposed sugar taxes in markets such as the United Kingdom and Mexico increase production costs or force costly reformulation for classic tonic variants, impacting margins and pricing.
Strategic Opportunities
- Non-Alcoholic Cocktails:The growing sober-curious movement creates an opportunity for flavored and premium tonics to be marketed as standalone adult soft drinks or as key ingredients in complex non-alcoholic 'mocktails'.
- Direct-to-Consumer Channels:Craft and specialty brands can leverage online platforms and subscription services to bypass traditional retail gatekeepers, building direct relationships and community with niche consumer segments.
- Latin American Market Entry:With an established spirits culture but a less developed premium mixer category, countries like Brazil and Argentina present significant entry points for brands able to adapt to local flavor preferences.
Industry Challenges
- Distribution Complexity:Securing shelf space and managing logistics across fragmented channels, from large supermarkets to independent bars and online retailers, poses a significant operational hurdle for producers of all sizes.
- Navigating Global Food Standards:Adhering to divergent international regulations on quinine levels, sugar content, and labeling from bodies like the EFSA in Europe and FSSAI in India complicates global product rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tonic Water Market |
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Tonic, Mediterranean Tonic, Diet Tonic, Flavored Tonic, Premium Tonic Packaging Type: Glass Bottle, Aluminum Can, PET Bottle, Carton Pack, Tetra Pak Sales Channel: Supermarkets, Convenience Stores, Online Retailers, Bars & Restaurants, Liquor Stores End User: Households, Hospitality Industry, Event Organizers, Retail Chains, Food Services |
| Companies Covered | PepsiCo Inc, Q Mixers, Fevertree Drinks PLC, Carlsberg Group, Franklin & Sons Ltd, The Coca-Cola Company (Schweppes), Fentimans Ltd, East Imperial Beverage Corporation, Keurig Dr Pepper Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tonic Water Market Strategic Shifts & Innovations
Product innovation is accelerating as producers apply advanced flavor science to meet demand for unique botanical profiles. This evolution in formulation is amplified by the shift in how consumers discover and purchase mixers, driven by the growth of specialized online channels.
These sophisticated extraction methods, such as CO2 extraction, allow for the creation of complex, terroir-driven flavor profiles from a wide array of botanicals. Premium producers are rapidly adopting these techniques for product differentiation and to justify higher price points. As a result, formulation based on unique botanical infusions is overtaking reliance on simple citrus and quinine combinations in the high-margin segment.
The European Union's push for harmonized front-of-pack labeling, such as the Nutri-Score system, pressures beverage manufacturers on sugar and calorie content. This regulatory pressure directly impacts classic tonic formulations, which often receive unfavorable scores. Consequently, producers are accelerating development of low-sugar and zero-calorie alternatives to maintain consumer trust and market access.
Consumer purchasing behavior is shifting from loyalty to a single tonic brand. Enthusiasts now curate a 'mixer wardrobe', selecting specific tonic profiles to pair with different gins or other spirits. This fragments the market and benefits online retailers offering wider variety, a trend visible in mature gin markets like Spain and the UK.
Tonic Water Market Segmentation
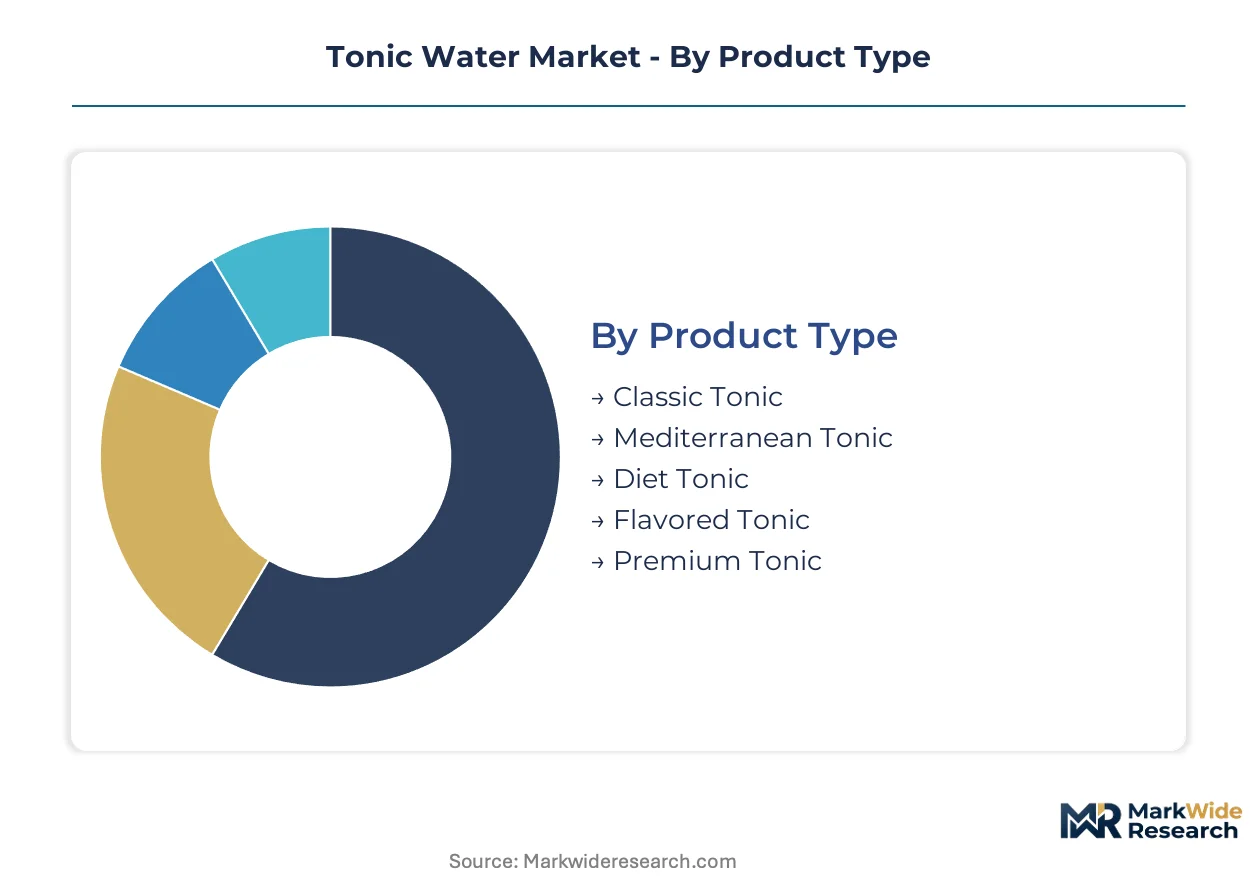
The tonic water market segments across various dimensions, reflecting diverse consumer preferences and operational demands. Understanding these classifications provides clarity on where product innovation and distribution strategies are most effective. This segmentation highlights the distinct characteristics driving consumption patterns across different market components.
Product Type:
Product formulation dictates consumer experience and market positioning, with specific ingredient profiles and taste characteristics defining each segment.
- Classic Tonic:This segment represents the traditional formulation, characterized by a distinct bitter quinine taste and often higher sugar content. Demand concentrates in established markets like the United Kingdom, remaining the foundational mixer for gin and tonic cocktails.
- Premium Tonic:These tonics feature refined botanical blends, often using natural sweeteners, designed to complement artisanal spirits. Demand is strong within the hospitality industry, where discerning consumers seek sophisticated flavor profiles for elevated drink experiences.
- Mediterranean Tonic:This variant typically incorporates herbal and citrus notes, such as rosemary or lemon thyme, offering a softer profile.
- Diet Tonic:Formulated with artificial or natural low-calorie sweeteners, this segment caters to health-conscious consumers seeking reduced sugar intake.
- Flavored Tonic:These products infuse various fruit, floral, or spice essences, expanding tonic water versatility.
Classic Tonic leads on scale; Premium Tonic leads on momentum.
Packaging Type:
The choice of packaging material impacts product preservation, consumer convenience, and environmental footprint.
- Glass Bottle:Valued for its inertness and premium aesthetic, glass packaging maintains product integrity and enhances brand perception, particularly in on-premise hospitality settings. Demand is concentrated in the premium segment, where visual appeal and perceived quality are paramount.
- Aluminum Can:Offering superior portability, rapid chilling, and recyclability, aluminum cans cater to convenience-driven consumption and outdoor events. Demand expands in markets with strong sustainability initiatives, such as Germany, due to high recycling rates.
- PET Bottle:Lightweight and shatter-resistant, PET bottles provide a cost-effective solution for larger volume consumption and mass distribution.
- Carton Pack:This packaging offers extended shelf life and a compact format, often used for multi-packs or specific retail environments.
- Tetra Pak:Known for aseptic processing, Tetra Pak is less common for carbonated beverages but offers unique shelf-stable advantages.
Glass Bottle maintains premium positioning, while Aluminum Can exhibits the steepest expansion trajectory.
Sales Channel:
Distribution strategies are shaped by consumer purchasing habits and specific requirements for product visibility and accessibility.
- Supermarkets:These large retail formats serve as the primary channel for mass-market tonic water, offering extensive product ranges and competitive pricing for household consumption. Volume demand remains high across European markets, ensuring broad consumer access.
- Online Retailers:E-commerce platforms facilitate direct-to-consumer sales, providing access to niche and specialty tonic brands. This channel gains share rapidly in the United Kingdom and Spain, driven by consumer desire for variety and convenience.
- Convenience Stores:Offering quick access for impulse purchases, convenience stores cater to immediate consumption needs, particularly for single-serve formats.
- Bars & Restaurants:The hospitality sector drives demand for premium tonic water as a mixer for cocktails and non-alcoholic beverages.
- Liquor Stores:Specializing in alcoholic beverages, liquor stores stock a curated selection of tonic waters to complement their spirits offerings.
Supermarkets capture the largest sales volume, while Online Retailers are gaining share at the highest rate.
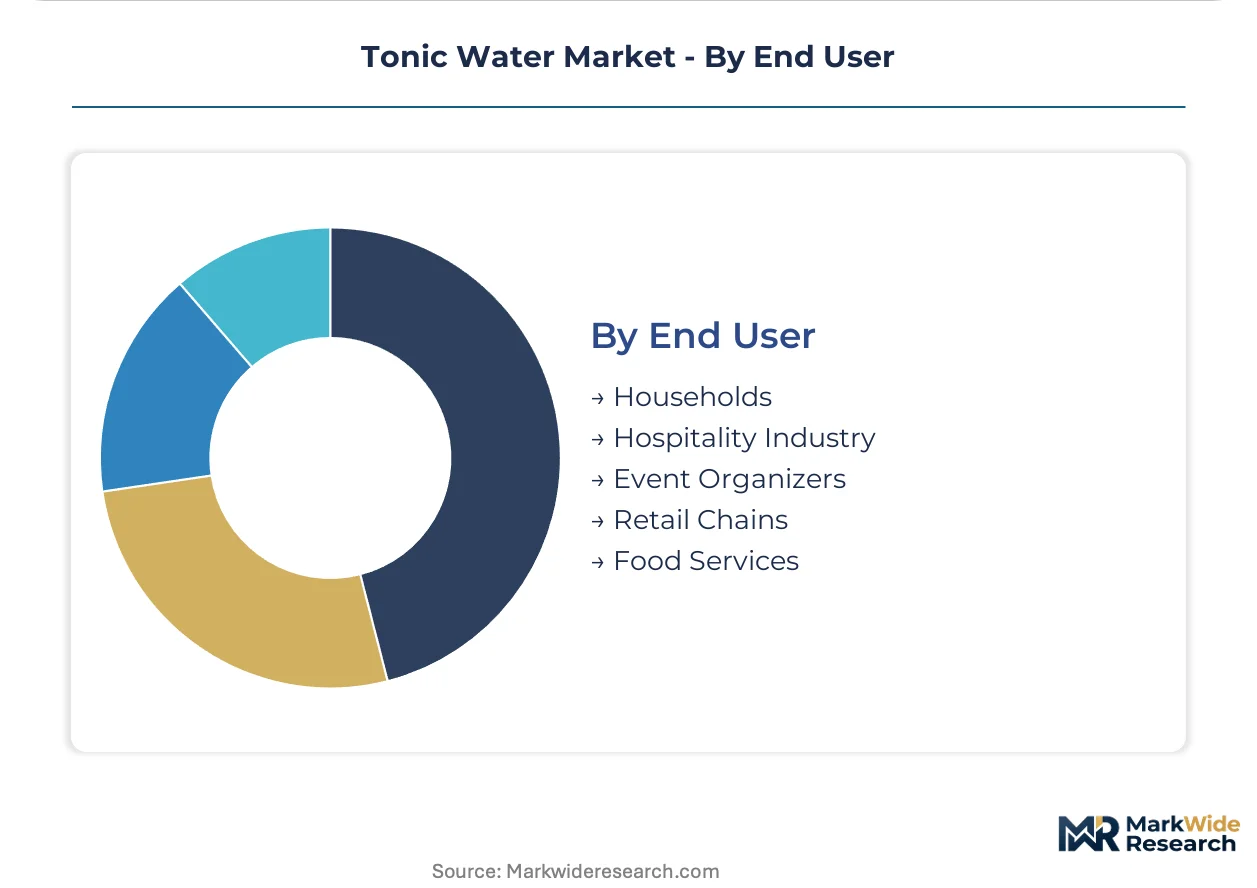
End User:
Distinct end-user groups drive demand for tonic water based on their specific consumption occasions, purchasing power, and preferences.
- Households:Individual consumers purchase tonic water for home consumption, ranging from casual mixers to standalone refreshing drinks. This segment values convenience and accessibility, with product choices influenced by brand recognition and price point.
- Hospitality Industry:This sector, encompassing bars, restaurants, and hotels, demands high-quality tonic water for crafting premium cocktails and mocktails. The industry prioritizes consistency, brand prestige, and tonic's ability to enhance spirit profiles.
- Event Organizers:Large-scale gatherings and festivals create temporary, high-volume demand for tonic water, often requiring efficient bulk supply.
- Retail Chains:These entities represent the distribution point for tonic water, purchasing from producers to resell to end consumers through their various outlets.
- Food Services:Caterers and institutional food providers use tonic water in diverse settings, from office canteens to airline services, for beverage options.
Households represent the broadest consumer base, and the Hospitality Industry provides the highest margin opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Highly skilled mixologists and hospitality professionals across European urban centers anchor the tonic water market's demand. These experts drive the premiumization trend, influencing consumer preferences for sophisticated mixers. Their expertise in cocktail crafting directly shapes product innovation and consumption patterns.
United Kingdom
Strong gin consumption patterns and a sophisticated cocktail culture drive demand for tonic water in the United Kingdom. Government-imposed sugar taxes, such as the Soft Drinks Industry Levy, compel producers to offer low-sugar alternatives. London's vibrant bar scene continually seeks new premium tonic brands and unique botanical profiles.
Spain
Established gin and tonic culture, deeply embedded in social traditions, sustains high per capita consumption of tonic water in Spain. The Spanish Agency for Food Safety and Nutrition (AESAN) enforces strict ingredient and labeling standards for beverages. Barcelona's craft cocktail movement fosters innovation in flavored tonic development.
India
Growing disposable incomes and increasing Western cultural influence in urban centers create new consumer bases for tonic water in India. The Food Safety and Standards Authority of India (FSSAI) regulates quinine content and sugar levels. Mumbai's burgeoning nightlife increasingly adopts premium tonic brands for sophisticated mixed drinks.
Japan
Western cultural influence and a strong focus on quality ingredients boost tonic water sales in Japan. The Ministry of Health, Labour and Welfare (MHLW) oversees food additive regulations, including quinine levels. Tokyo's discerning consumer base drives demand for unique botanical infusions and premium mixer experiences.
Brazil
An established spirits culture creates a significant entry point for premium tonic water brands in Brazil. The National Health Surveillance Agency (ANVISA) sets standards for food and beverage safety and labeling. São Paulo's dynamic culinary scene explores specialized tonic pairings for both local and international spirits.
Tonic Water Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the tonic water market, creating a dynamic competitive environment. The market structure exhibits a tiered consolidation, with large beverage corporations holding significant distribution advantages alongside agile niche brands. Three strategic archetypes define the landscape: global beverage giants leveraging scale, premium craft producers emphasizing unique formulations, and emerging regional players. Companies primarily engage in portfolio diversification and geographic expansion to capture market share and adapt to evolving consumer preferences.
Among global beverage giants, The Coca-Cola Company maintains widespread market presence through its established Schweppes brand, leveraging extensive distribution networks. Fevertree Drinks PLC, a UK-based public limited company, exemplifies the premium craft producer archetype, focusing on high-end mixer segments and sophisticated botanical blends. Fentimans Ltd, another UK-based entity, represents the traditional craft segment, differentiating through unique botanical infusions and time-honored production methods. These players collectively shape competitive dynamics by addressing different consumer segments, from mass-market volume to niche premium experiences.
| Leading Market Players |
|---|
| PepsiCo Inc |
| Q Mixers |
| Fevertree Drinks PLC |
| Carlsberg Group |
| Franklin & Sons Ltd |
| The Coca-Cola Company (Schweppes) |
| Fentimans Ltd |
| East Imperial Beverage Corporation |
| Keurig Dr Pepper Inc |
| Others |
Cost & Logistics Intelligence
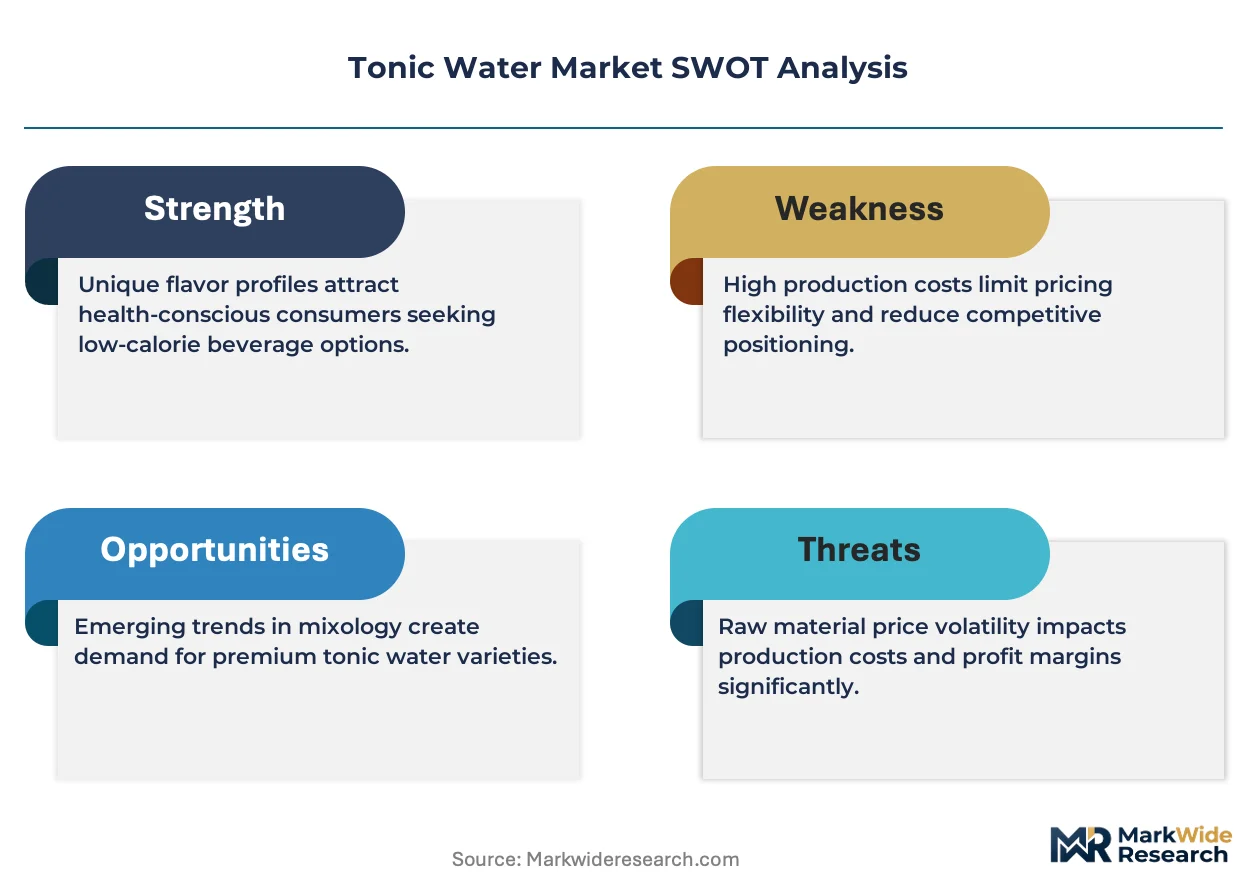
Publicly traded specialists and family-owned mid-caps characterize the tonic water market, influencing both supply behavior and pricing discipline. These ownership structures often prioritize long-term brand equity and quality consistency over short-term price concessions, impacting raw material sourcing and distribution strategies.
Pricing Analysis
The unbundled nature of premium tonic water as a standalone mixer drives its per-unit transactional pricing model. Price differentiation stems from brand premium and unique botanical sourcing, allowing companies to justify higher price points. Pricing pressure arises from government-imposed sugar taxation policies in markets like the United Kingdom, necessitating costly reformulations. Households exhibit higher price sensitivity compared to the hospitality industry, which prioritizes quality and brand alignment for cocktail crafting.
Supply Chain Analysis
Regional distribution centers form critical nodes, managing the flow of tonic water from production facilities to fragmented retail and hospitality channels. Geographic supply concentration exists in the Andean foothills for cinchona bark, while European hubs handle significant processing and bottling. The supply chain depends on natural quinine and various botanicals as core raw materials. Geopolitical instability in cinchona-producing regions presents a structural risk, causing raw material price instability. Distribution runs through a complex mix of large supermarkets, online retailers, and direct supply to bars and restaurants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tonic water market presents a geographic-arbitrage opportunity, leveraging varied regulatory landscapes and consumer maturity. European sugar taxation policies create cost differentials compared to emerging markets like India.
For Market Incumbents:
Anticipate sustained pressure from health-conscious consumption and sugar taxation policies. Diversify product portfolios into natural, low-sugar formulations to mitigate these regulatory shifts. Invest in R&D for novel botanical extraction methods to maintain premium positioning against emerging craft brands. Strengthen control over key distribution channels within the hospitality sector to defend market share.
For New Entrants and Emerging Players:
Sober-curious consumers represent an underserved buyer archetype, seeking sophisticated non-alcoholic options. Target the rapidly expanding mocktail segment with unique botanical infusions and premium packaging. Leverage direct-to-consumer online platforms to build brand communities and bypass traditional retail gatekeepers, particularly in markets like Brazil. Focus on regional flavor preferences to gain local market acceptance.
For Investors and Strategic Acquirers:
Valuations sit cheapest among regional craft producers with strong local brand loyalty but limited distribution. Long-term viability hinges on the sustained premiumization of the spirits market and the growth of non-alcoholic alternatives. Acquire agile, innovation-driven brands specializing in natural botanical infusions to capture niche segments. Watch for significant regulatory shifts in key markets like India, influencing product formulation and market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Low-Sugar | Addresses health-conscious consumer demand and mitigates risks from sugar taxation policies in the UK. |
| Direct-to-Consumer Channel Development | Builds brand loyalty and provides access to niche consumer segments for Fentimans Ltd. |
| Expansion into Latin American Markets | Leverages an established spirits culture and growing disposable incomes in Brazil. |
| Advanced Botanical Extraction Investment | Enables unique flavor profiles and product differentiation for premium brands like Fevertree Drinks PLC. |
| Strategic Partnerships with Spirit Brands | Secures preferred mixer status and enhances market visibility within the hospitality industry. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Interviews included beverage R&D directors, hospitality procurement managers, and flavor scientists across key markets. Secondary data drew from customs records, food safety authority reports like EFSA, and company financial filings. This approach ensured bottom-up and top-down triangulation for market sizing.
Historical reference periods anchored the forecast framework, projecting market trajectories across the analysis window. Segmentation dimensions modeled included product type, packaging format, sales channel, end user, and regional regulatory environments. Compound annual growth rates were derived from historical data and projected forward using econometric models. Key inputs included global gin consumption trends and anticipated sugar tax implementations.
Underlying measurement precision varies by segment; Classic Tonic and Supermarkets carry tighter precision than niche Flavored Tonic and Online Retailers. Forecasts reflect assumptions regarding consumer preferences and raw material availability. Quinine supply volatility and evolving food safety standards represent key risk factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Ready to Drink Margarita Market
Beverages
Bubble Food and Beverages Market
Beverages
Rose Floral Water Market
Beverages
Smoothies Market
Beverages
Fermented Foods and Beverages Market
Beverages
Cactus Water Market
Beverages
Wellness Water Market
Beverages
CBD-Infused Beverages Market
Beverages
China Soy Beverages Market
Beverages
NFC JUICE Market
Beverages
Fruit Juice Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
Hot Cocoa Mix Market
Beverages
Yerba Mate Market
Beverages
Europe Fruits and Vegetables Juice Market
Beverages
Bottled Deep Ocean Water Market