
 Europe Animal-Based Food and Beverage Market | 2026-2036
Europe Animal-Based Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Animal-Based Food and Beverage Market Foresight
REACH is rebalancing capital allocation across the Europe Animal-Based Food and Beverage value chain as chemical safety compliance costs reshape processor economics. Nestle SA leverages its pan-European dairy network to sustain formulation flexibility under evolving additive restrictions. Groupe Danone anchors its competitive position through specialized fermentation capabilities that navigate tightening environmental standards. Royal FrieslandCampina NV dominates cooperative milk sourcing across the Netherlands and Germany, extending farmer loyalty programs that buffer input volatility.
Europe Animal-Based Food and Beverage encompasses animal-derived edible products and drinks processed through slaughtering, milking, aquaculture harvesting, or egg collection, typically requiring cold-chain preservation below 4°C and compliance with microbiological safety thresholds under Regulation (EC) No 2073/2005. The category serves nutritional provisioning across retail, foodservice, and industrial manufacturing channels. Dairy commands the largest value pool within product type segmentation, reflecting entrenched per-capita consumption in Nordic and Alpine regions. Meat competes for shelf space through premiumization around protected designation of origin certifications. Online distribution channels are gaining velocity as refrigerated last-mile logistics mature across metropolitan zones.
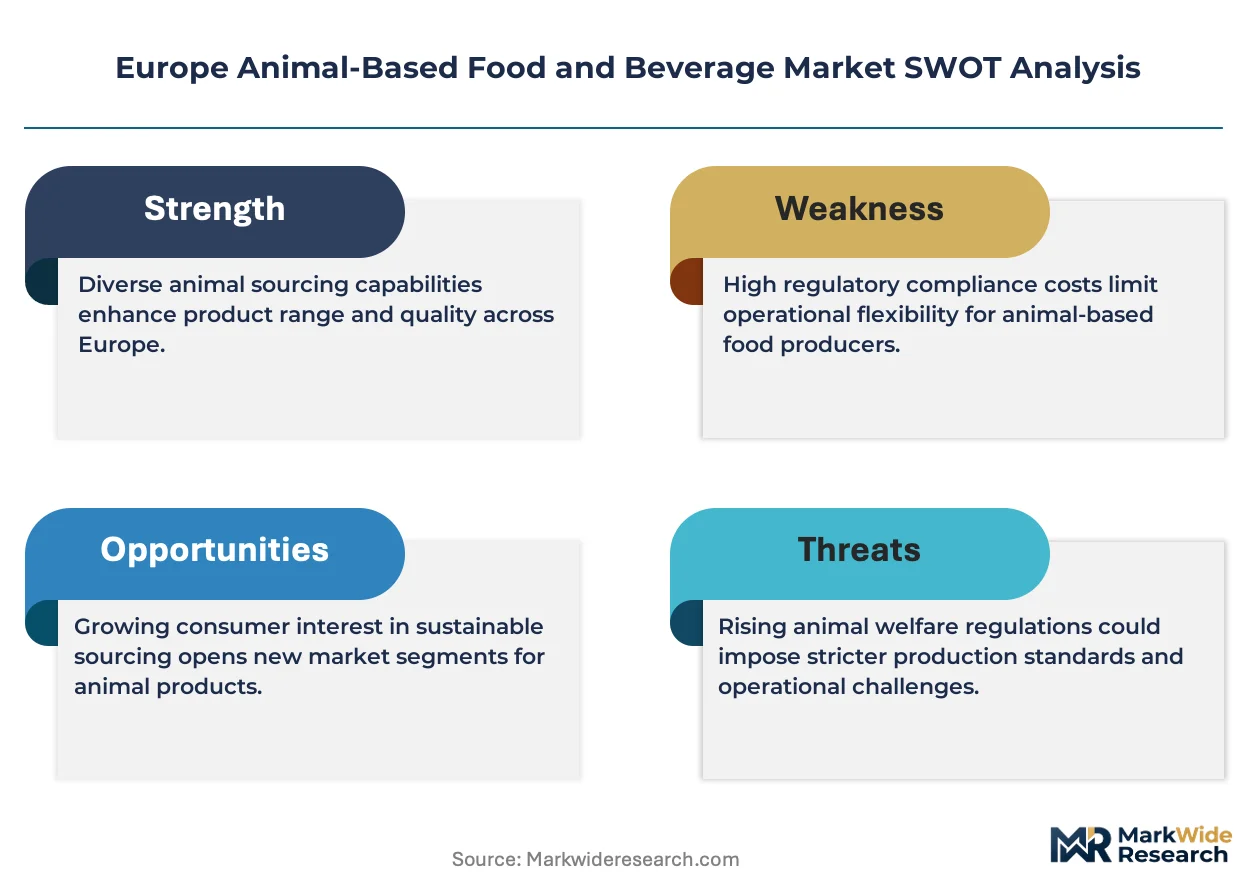
EMA, EFSA, and the EU Green Deal collectively govern animal welfare labeling, residue limits, and carbon-accounting disclosures that determine market access for producers and importers. EFSA's scientific opinions on antimicrobial resistance directly shape permitted veterinary practices, while EU Green Deal targets for methane reduction are pressuring feed formulation across member states. Stakeholders must monitor the interplay between national transposition timelines and Brussels-level enforcement consistency to anticipate compliance cost trajectories.
Market Dynamics
EU Green Deal methane reduction targets are forcing feed formulation changes across livestock operations while EFSA antimicrobial resistance opinions reshape veterinary protocols throughout member states.
Growth Catalysts
- Foodservice Premiumization:Western European operators expand high-value animal-protein menus as consumer willingness-to-pay for provenance-certified products strengthens across Germany, France, and Italy.
- Cold-Chain Logistics Maturation:Refrigerated last-mile networks now reach metropolitan zones previously excluded from fresh distribution, unlocking new addressable demand pools in secondary cities.
- REACH Chemical Compliance:Processors investing early in additive substitution and safety documentation capture preferential shelf placement as retailers preempt liability exposure.
Market Restraints
- Feed Input Volatility:Grain and protein meal prices swing with Black Sea supply disruptions, compressing processor margins and destabilizing long-term contract pricing.
- Cooperative Supply Concentration:Dutch and German dairy sourcing clusters around farmer-owned structures, limiting independent processor access to raw milk volumes during peak demand windows.
- Plant Protein Substitution:Fermentation-derived alternatives and precision-cultivated products capture flexitarian trial in Nordic urban centers, eroding category loyalty among younger demographics.
Strategic Opportunities
- Protected Designation Expansion:Meat processors leveraging PDO and PGI certifications command price premiums in Italian and Spanish retail channels where origin storytelling drives purchase decisions.
- Specialized Fermentation Capacity:Dairy operators with installed bioprocessing infrastructure can pivot toward enzymatic and cultured ingredient production as pharmaceutical and nutraceutical offtake grows.
- Carbon-Accounting Disclosure Mandates:Early compliance with EU Green Deal scope-three reporting requirements positions suppliers for preferential procurement by multinational food manufacturers facing scope-three pressure.
Industry Challenges
- Veterinary Antimicrobial Stewardship:EFSA-guided restrictions on prophylactic antibiotic use demand herd health management expertise that smaller livestock operations struggle to acquire or afford.
- Refrigerated Fleet Retrofit Requirements:F-Gas Regulation phase-down schedules force transport operators to replace or convert cooling units, straining capital allocation for logistics SMEs.
- Microbiological Testing Bottlenecks:Regulation (EC) No 2073/2005 compliance timelines stretch laboratory capacity during seasonal production peaks, delaying batch releases and compressing shelf-life windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Animal-Based Food and Beverage Market |
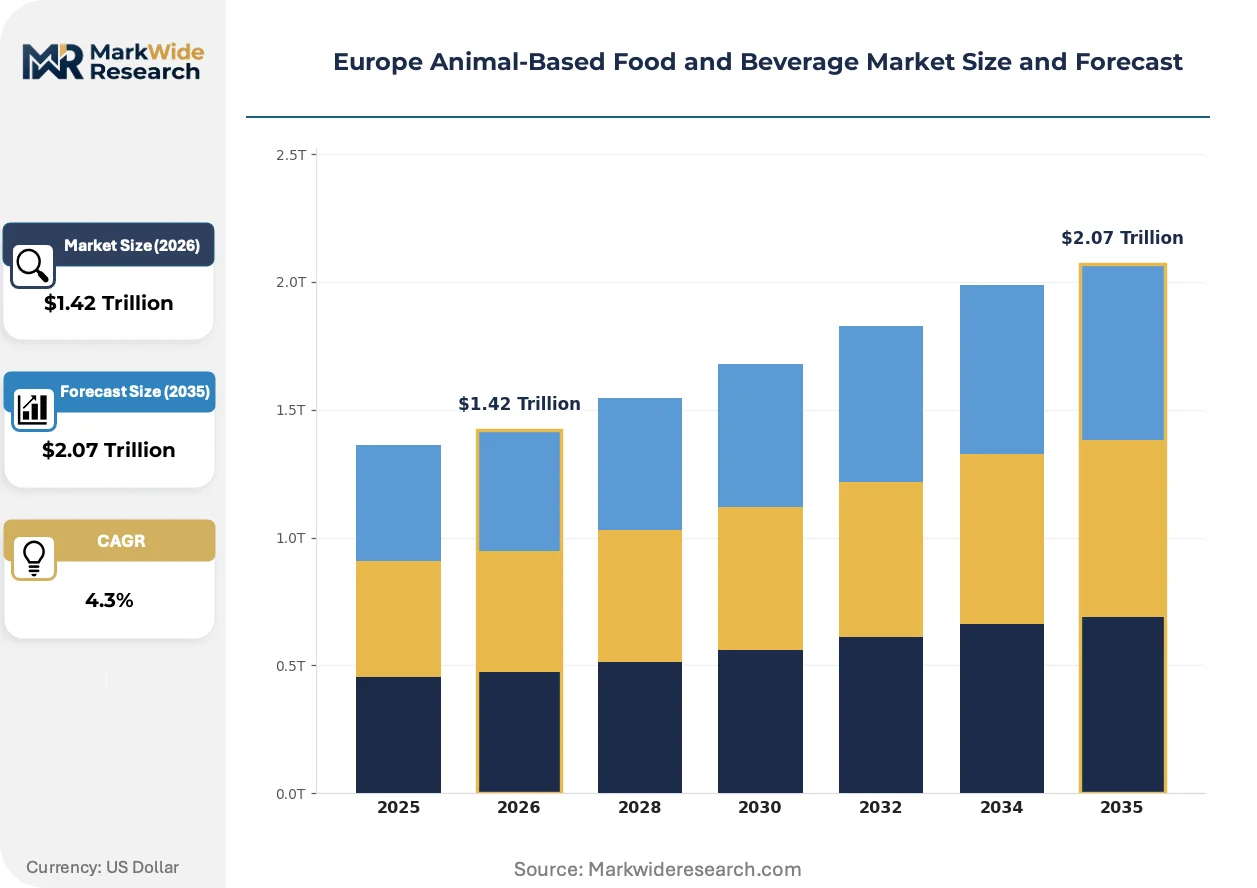
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.07 Trillion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dairy, Meat, Seafood, Eggs End User: Households, Restaurants, Retailers, Foodservice Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale Packaging Type: Flexible Packaging, Rigid Packaging, Vacuum Packaging, Others |
| Companies Covered | Nestle SA, Groupe Danone, Royal FrieslandCampina NV, Nomad Foods, Arla Foods Amba, Unilever PLC, Mars Holding GmbH, JBS SA, Tyson Foods Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Animal-Based Food and Beverage Market Shifts & Advancements
Processing technology and regulatory disclosure requirements are converging to reshape how animal-derived products move from farm to consumer across European supply chains.
Precision fermentation infrastructure is modularizing protein and fat production for hybrid dairy applications. Mid-sized dairy cooperatives in the Netherlands and Denmark are piloting these systems to reduce reliance on commodity milk powder economics. The technology is modularizing ingredient sourcing strategies, allowing processors to blend animal-derived and fermentation-derived components without full vertical integration into livestock operations.
EU Green Deal Farm to Fork Strategy mandates are tightening residue limits and carbon-footprint disclosure thresholds for imported animal feed and finished products. Processors must now document scope-three emissions across upstream grain and soy supply chains or face exclusion from public procurement tenders. German and French retail banners are responding fastest, delisting suppliers who miss interim reporting deadlines.
Foodservice procurement patterns favor shorter-contract, higher-flexibility arrangements as operators hedge against menu volatility and input cost swings. Broadline distributors are unbundling traditional full-service contracts into component sourcing agreements for proteins, dairy, and prepared items. This restructuring is most visible in UK and Irish foodservice markets where contract caterers and restaurant groups negotiate directly with cooperative processors for specified-origin volumes.
Europe Animal-Based Food and Beverage Market Segmentation
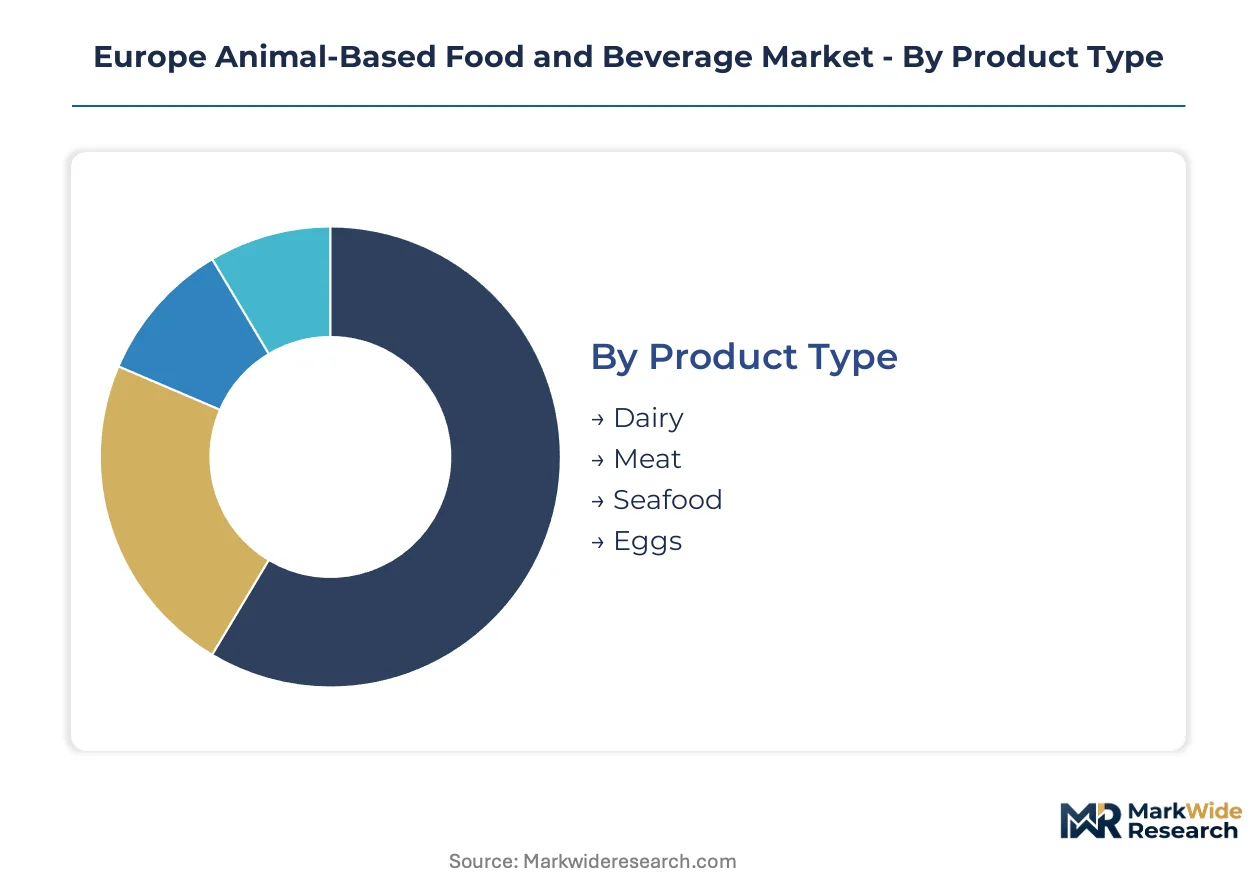
Segmentation in the Europe Animal-Based Food and Beverage Market reveals distinct operational logics across product, channel, and customer dimensions. Dairy and meat segments operate through fundamentally different cold-chain economics and regulatory exposure profiles. Understanding these structural boundaries enables targeted resource allocation across procurement, processing, and distribution investments.
Product Type:
Dairy and meat segments function as standalone value chains with dedicated processing infrastructure, while seafood and eggs embed more flexibly into multi-protein operations.
- Dairy:Fluid milk, cheese, yogurt, and butter products requiring fermentation infrastructure and sustained cold-chain preservation below 4°C. Demand concentrates in Germany, France, and the Netherlands where cooperative processing structures dominate volume flows and buffer farmer-processor price negotiations.
- Meat:Fresh, frozen, and processed pork, beef, and poultry products governed by slaughterhouse throughput economics and protected designation of origin certification premiums. Italian and Spanish retail channels absorb the highest-value provenance-certified volumes, with PDO and PGI storytelling commanding measurable price premiums.
- Seafood:Finfish and shellfish products harvested through wild catch or aquaculture operations, integrating into multi-protein retail and foodservice assortments with shorter shelf-life constraints than terrestrial proteins.
- Eggs:Shell eggs and processed egg products embedding into industrial manufacturing and retail private-label programs, with welfare labeling tiers differentiating pricing across German and Nordic markets.
Volume placements concentrate in Dairy; the faster expansion belongs to Meat as premiumization around origin certification accelerates category value capture.
End User:
Customer segmentation separates direct consumption from institutional procurement, with margin structures diverging sharply between contracted foodservice and spot retail purchasing.
- Households:Individual consumers purchasing through retail channels for at-home preparation, with purchasing patterns increasingly shifting toward online platforms and subscription-based dairy delivery in metropolitan Germany and France.
- Restaurants:Independent and chain foodservice operators sourcing specified-origin proteins and prepared dairy components for menu execution, negotiating shorter-contract, higher-flexibility arrangements to hedge input volatility.
- Retailers:Supermarket banners and specialty stores curating private-label and branded assortments, with German and French retail banners delisting suppliers who miss EU Green Deal interim carbon reporting deadlines.
- Foodservice:Contract caterers, institutional kitchens, and hospitality groups procuring at scale through broadline distributors now unbundling traditional full-service contracts into component sourcing agreements.
Margin stability favors Retailers; the steepest expansion trajectory sits with Restaurants as premium menu development accelerates across Western European urban centers.
Distribution Channel:
Channel segmentation tracks the maturation of refrigerated logistics, with last-mile cold-chain investments unlocking previously excluded demand pools.
- Online:Direct-to-consumer and platform-mediated sales requiring refrigerated last-mile fulfillment, gaining velocity as metropolitan zone coverage expands into secondary cities across the Netherlands and Germany.
- Supermarkets:Full-assortment retail banners dominating volume throughput, with shelf-space allocation increasingly contingent on REACH chemical compliance documentation and carbon-footprint disclosure completeness.
- Specialty Stores:Butcher counters, cheese mongers, and fishmongers emphasizing provenance storytelling and service differentiation, concentrated in Italian and Spanish urban retail corridors.
- Wholesale:Foodservice and retail redistribution intermediaries, with cooperative processors in the Netherlands and Germany extending direct relationships to large contract caterers and restaurant groups.
Supermarkets anchor current volume; Online channels are climbing the fastest as refrigerated logistics infrastructure reaches previously excluded metropolitan zones.
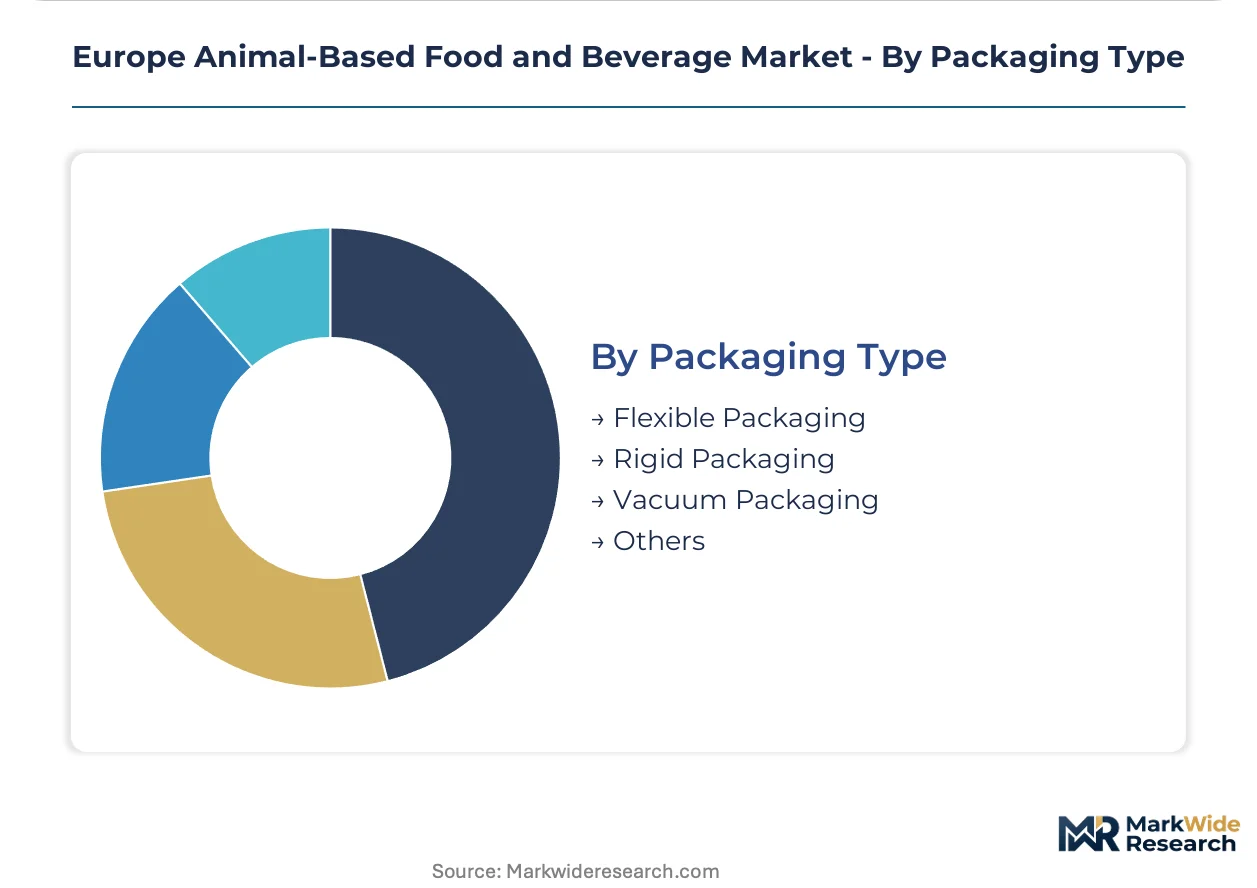
Packaging Type:
Packaging segmentation reflects the interplay between shelf-life extension, sustainability mandates, and regulatory compliance costs reshaping processor capital allocation.
- Flexible Packaging:Films, pouches, and bags offering cost efficiency and format versatility for processed meats and dairy portions, with F-Gas Regulation phase-down schedules forcing refrigeration-dependent transport packaging redesigns.
- Rigid Packaging:Bottles, cartons, and trays providing structural protection for fluid milk and fresh meat cuts, with EFSA microbiological safety thresholds under Regulation (EC) No 2073/2005 dictating material barrier specifications.
- Vacuum Packaging:Gas-flushed and evacuated formats extending shelf life for premium meat and seafood products, concentrated in retail channels where date-window extension reduces shrinkage costs.
- Others:Modified atmosphere packaging and active packaging systems incorporating oxygen scavengers or antimicrobial agents, piloted by mid-sized dairy cooperatives in Denmark for enzymatic ingredient applications.
Flexible Packaging holds the largest volume footprint; Vacuum Packaging is gaining share fastest as retailers prioritize shelf-life extension for premium protein categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benelux cooperative zones concentrate dairy processing infrastructure through tax-advantaged structures in the Netherlands and Belgium. German and French metropolitan corridors drive premium protein demand through foodservice density and retail banner consolidation.
Germany
Cooperative milk sourcing networks around Münsterland and Lower Saxony buffer farmer-processor price volatility through loyalty programs. EFSA antimicrobial resistance opinions reshape veterinary protocols across Bavarian livestock operations. Berlin and Hamburg foodservice operators negotiate directly with dairy cooperatives for specified-origin volumes.
France
Protected designation of origin certifications command measurable price premiums in Île-de-France and Auvergne-Rhône-Alpes retail channels. EU Green Deal Farm to Fork Strategy mandates tighten residue limits for imported feed grains through Atlantic port terminals. Lyon and Marseille specialty store corridors emphasize provenance storytelling for cheese and charcuterie assortments.
Netherlands
Randstad metropolitan cold-chain logistics unlock direct-to-consumer dairy delivery previously excluded from secondary cities. REACH chemical compliance documentation determines shelf-space allocation at Rotterdam and Amsterdam retail banners. Friesland and Gelderland cooperative structures dominate raw milk volume flows during peak demand windows.
Italy
PDO and PGI meat certifications accelerate value capture in Emilia-Romagna and Lombardy retail channels. F-Gas Regulation phase-down schedules force refrigerated fleet retrofits across Po Valley transport corridors. Milan and Bologna foodservice operators expand high-value animal-protein menus as consumer willingness-to-pay for provenance-certified products strengthens.
Spain
Aquaculture harvesting operations in Galicia and Andalusia integrate into multi-protein retail assortments with shorter shelf-life constraints. EMA animal welfare labeling requirements reshape packaging specifications for Madrid and Barcelona supermarket banners. Valencia and Catalonia specialty store networks concentrate service differentiation around fishmonger and butcher counter formats.
Europe Animal-Based Food and Beverage Market Competitive Landscape
Benelux cooperatives anchor one tier; Swiss and French diversified food groups hold portfolio breadth advantages. Market structure tilts toward cooperative ownership in dairy and consolidated multinational presence in processed proteins. Three archetypes dominate: farmer-owned cooperatives with captive raw milk supply, diversified nutrition conglomerates spanning multiple protein categories, and specialized meat processors leveraging origin certification premiums. Competitive moves concentrate on M&A for PDO/PGI portfolio expansion and cold-chain logistics partnerships for last-mile refrigerated fulfillment.
Within the cooperative tier, Royal FrieslandCampina NV and Arla Foods Amba exemplify farmer-owned structures that buffer input volatility through loyalty programs and direct sourcing relationships. Nestle SA and Groupe Danone occupy positions among diversified nutrition groups with pan-European dairy networks and fermentation infrastructure. These named entities represent archetypal competitive positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Nestle SA |
| Groupe Danone |
| Royal FrieslandCampina NV |
| Nomad Foods |
| Arla Foods Amba |
| Unilever PLC |
| Mars Holding GmbH |
| JBS SA |
| Tyson Foods Inc |
| Others |
Supply & Pricing Matrix
EU Green Deal methane reduction targets gate qualified supply and premium-tier pricing access by forcing feed formulation investments that only scaled cooperatives absorb without margin erosion. Processors lacking documented scope-three emissions compliance face exclusion from German and French retail procurement tenders, compressing their addressable demand pool to spot foodservice channels.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers: short-lead specified-origin volumes from FrieslandCampina and Arla command shelf-space premiums at Rotterdam and Hamburg retail banners, while spot inventory from independent traders clears at discounts through wholesale redistribution. Price differentiation hinges on PDO/PGI certification grade and cooperative membership status. Pricing pressure stems from Black Sea grain supply disruptions feeding into compound feed costs. Contract caterers exhibit highest price sensitivity; specialty store operators in Milan and Lyon show lowest sensitivity due to provenance storytelling requirements.
Supply Chain Analysis
Reverse-logistics flows for refrigerated returns and expired dairy batches concentrate processing waste valorization in Netherlands and Denmark biogas facilities. Raw material sourcing draws from German and Dutch cooperative milk pools, Spanish and Italian livestock operations, and Black Sea grain corridors. Supply chain risk centers on single-source vulnerability in cooperative raw milk concentration. Distribution runs through cooperative-processor direct relationships to retail banners, with last-mile cold-chain partnerships unlocking metropolitan zone penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where upstream feed sourcing control and downstream cold-chain captive capacity determine margin sustainability. Players pursuing backward integration into compound feed production buffer input volatility that destabilizes spot-market competitors.
For Market Incumbents: Deploy specialized fermentation infrastructure to pivot dairy processing assets toward enzymatic ingredient production as pharmaceutical offtake expands. Secure exclusive PDO/PGI certification portfolios in Italian and Spanish corridors before independent processors consolidate origin storytelling rights. Plant protein substitution in Nordic urban centers threatens category loyalty among younger demographics. For New Entrants and Emerging Players: Independent restaurant groups in secondary German and French metropolitan zones represent underserved buyer archetypes bypassed by cooperative direct-sales programs. White-space targets include subscription-based dairy delivery in Randstad satellite cities and direct-procurement platforms for contract caterers seeking specified-origin flexibility. Go-to-market angle: unbundled component sourcing agreements replacing traditional broadline distributor contracts. For Investors and Strategic Acquirers: EFSA antimicrobial resistance opinion publication is the leading indicator that veterinary protocol investments will separate acquirable mid-sized livestock operations from distressed sellers. Long-term viability favors processors with installed bioprocessing infrastructure and documented EU Green Deal compliance. Acquisition target archetype: mid-sized meat processors with dormant PDO/PGI applications and underutilized cold-chain assets. Signal to monitor: German retail banner delisting announcements for scope-three reporting failures.| Strategic Initiative | Industry Significance |
|---|---|
| PDO/PGI Certification Expansion | Italian and Spanish retail channels reward provenance storytelling with measurable shelf-space allocation premiums. |
| Specialized Fermentation Capacity Buildout | Danish and Dutch cooperatives pivot dairy assets toward pharmaceutical and nutraceutical ingredient markets. |
| Refrigerated Last-Mile Partnerships | Metropolitan zone penetration in Netherlands and Germany unlocks direct-to-consumer subscription demand pools. |
| Scope-Three Emissions Documentation | Early compliance positions suppliers for preferential procurement by multinational manufacturers facing disclosure pressure. |
| Feed Formulation R&D Investment | Methane reduction targets force additive substitution that cooperative structures absorb more efficiently than independents. |
Research Methodology
Independent corroboration across cooperative processor executives, retail category buyers, foodservice procurement directors, and veterinary compliance officers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through EFSA scientific opinion databases, EU Green Deal implementation timelines, REACH chemical compliance registries, and trade flow customs records. Bottom-up volume modeling triangulated against top-down macroeconomic consumption benchmarks.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, distribution channel, end-user category, and national regulatory cluster. CAGRs derive from fitted growth curves calibrated to historical consumption elasticities and policy implementation schedules. Forecast inputs include cooperative milk pricing data and refrigerated logistics infrastructure deployment timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement consistency and Black Sea grain supply stability. Forecasts reflect assumptions around national transposition timelines and laboratory capacity expansion for microbiological testing compliance. Practitioners should monitor EFSA antimicrobial resistance opinion updates and F-Gas Regulation phase-down schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Smoothies Market
Beverages
Spring Water Market
Beverages
Europe Coconut Water Market
Beverages
Crystal Boba Market
Beverages
Fusion Beverages Market
Beverages
Japan Energy Drink Market
Beverages
Probiotic Beverage Market
Beverages
Asia-Pacific Energy Bar Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
Fermented Drinks Market
Beverages
Growlers Market
Beverages
Global Bottled Water Market
Beverages
Chocolate Malt Drink Market
Beverages
Still Drinks Market
Beverages
South America Ready to Drink Beverages Market
Beverages
NFC JUICE Market