
 Low Calorie Treats Market | 2026-2036
Low Calorie Treats Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Treats Market Analytics
Pet specialty retail is repositioning shelf space toward functional nutrition formats. General Mills leverages its snack bar manufacturing infrastructure to serve co-manufacturing partners in the pet adjacent wellness space. Nestle anchors its portfolio through Purina's veterinary weight management lines, while Danone competes in human low-calorie formats that indirectly shape consumer taste expectations transferable to pet products.
Low calorie treats are formulated products delivering reduced energy density through controlled fat content, alternative carbohydrate sources, or bulking fiber additives, typically manufactured via extrusion or cold-pressing to preserve nutrient integrity while limiting caloric load per serving unit. Snack bars and smoothies lead product type development due to format versatility and portion control compatibility. Protein enrichments and high fiber ingredient types capture expanding margin pools as consumers prioritize satiety claims, while gluten-free positioning matures into a baseline expectation rather than a premium differentiator.
FDA Center for Veterinary Medicine guidelines and AAFCO model regulations shape permissible calorie claims and feeding direction labeling across the United States. State agriculture departments enforce feed control laws that affect product registration timelines and interstate distribution eligibility. Stakeholders must monitor evolving veterinary nutrition research on metabolizable energy calculation methods and anticipate how state-level enforcement harmonization will alter compliance costs.
Market Dynamics
Pet humanization has shifted from emotional narrative to structural purchasing mandate, compelling treat manufacturers to reformulate around metabolizable energy calculations while veterinary weight management protocols penetrate retail channels.
Growth Catalysts
- AAFCO Model Regulations:Standardized calorie claim definitions reduce interstate distribution friction for multi-state operators, compressing product registration timelines.
- Veterinary channel expansion:Prescription weight management protocols now extend into over-the-counter retail, blurring professional and consumer purchase boundaries.
- Urban household concentration:Dense metropolitan pet ownership correlates with apartment-living constraints that elevate portion-controlled treat formats.
Market Restraints
- Input cost volatility:Specialized protein isolates and novel carbohydrate sources face agricultural commodity price swings that compress formulation margins.
- Metabolizable energy calculation uncertainty:Veterinary nutrition research debates around Atwater factors versus modified energy coefficients create labeling liability exposure.
- Substitute category pressure:Fresh pet food and refrigerated meal formats capture treat occasions through functional overlap in weight management positioning.
Strategic Opportunities
- Veterinary telehealth integration:Remote consultation platforms create direct-to-consumer channels for prescription-aligned treat recommendations.
- Subscription model penetration:Auto-replenishment services for portion-controlled formats reduce customer acquisition costs while locking recurring revenue.
- State-level enforcement harmonization:Converging agriculture department feed control interpretations may reduce compliance fragmentation costs for national distributors.
Industry Challenges
- Veterinary nutritionist scarcity:Qualified formulators capable of metabolizable energy validation command premium compensation that strains mid-tier manufacturer budgets.
- Cold-pressing equipment capex:Nutrient-preserving manufacturing methods require specialized extrusion infrastructure with extended depreciation schedules.
- Label claim substantiation timelines:FDA Center for Veterinary Medicine review cycles for novel fiber additive safety data extend product development pipelines.
Report Scope
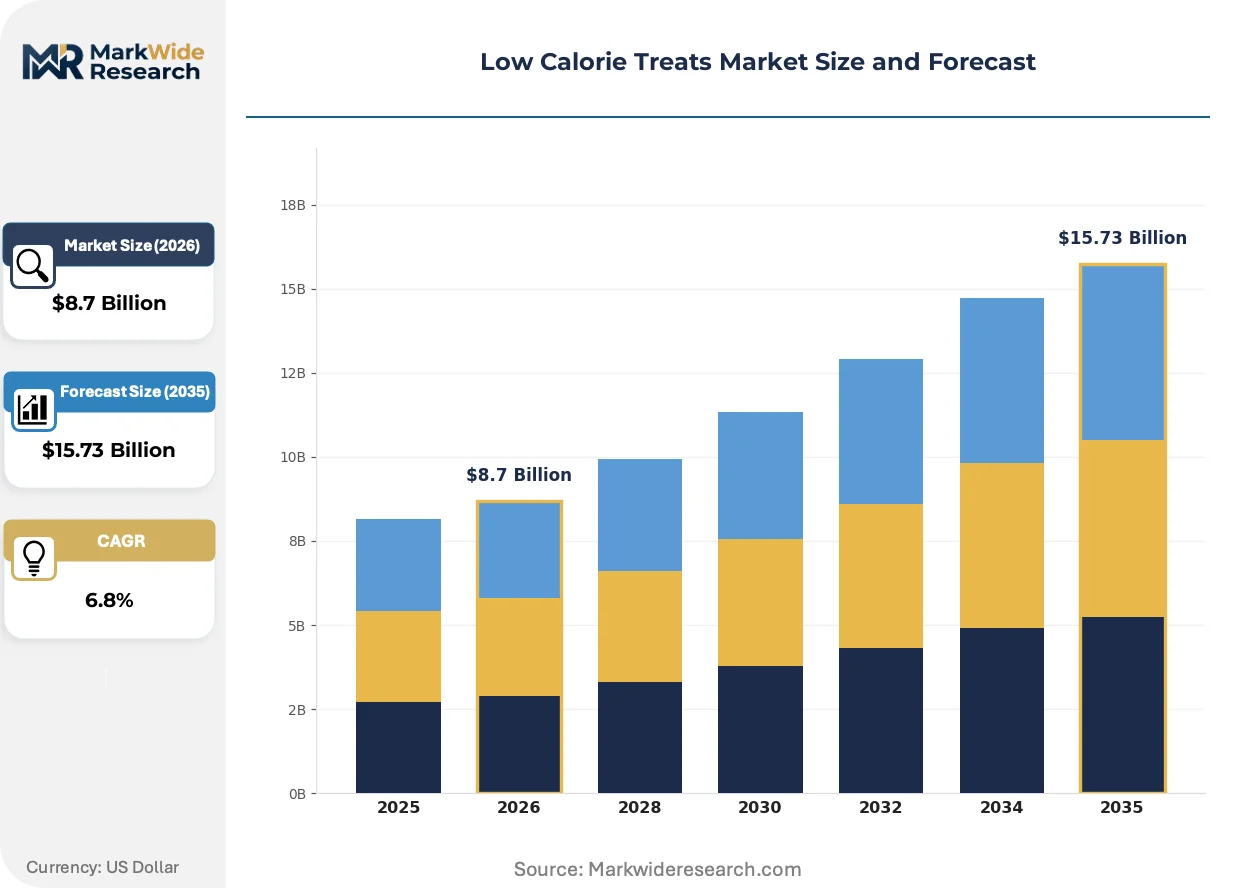
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Treats Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smoothies, Snack Bars, Cookies, Ice Cream Ingredient Type: Natural Sweeteners, High Fiber, Protein Enrichments, Gluten-Free Target Audience: Fitness Enthusiasts, Health-Conscious Consumers, Diabetics, Weight Watchers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Convenience Stores |
| Companies Covered | Archer Daniels Midland Company, Cargill, Conagra Brands, Danone, General Mills, The Hain Celestial Group, Ingredion, Mondelez International, Nestle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Treats Market Evolving Landscape
Formulation science and distribution architecture are converging to reshape how reduced-calorie pet nutrition reaches end consumers, with manufacturing precision and regulatory clarity emerging as decisive competitive variables.
Near-infrared spectroscopy is automating real-time fat and moisture analysis during extrusion processes, enabling continuous calibration of energy density without batch interruption. Mid-sized contract manufacturers in the pet wellness adjacent space are deploying these systems to serve co-manufacturing clients with tighter specification tolerances. This capability compression is automating quality assurance labor while reducing ingredient waste rates.
State agriculture departments are tightening feed control law enforcement around calorie disclosure accuracy, particularly in jurisdictions with active pet obesity public health campaigns. Manufacturers face expanded documentation requirements for metabolizable energy calculation methodologies. The veterinary weight management segment bears the highest compliance burden, with prescription-adjacent lines subject to enhanced substantiation protocols.
Specialty retailers are unbundling treat purchasing from bulk bag formats toward single-serve and trial-size positioning, reflecting compressed consumer commitment cycles. Urban pet specialty chains in dense metropolitan corridors lead this transition, replacing shelf-stable volume SKUs with refrigerated case proximity placements. This channel reconfiguration elevates turnover velocity for premium-positioned functional formats while pressuring traditional mass-market distribution economics.
Low Calorie Treats Market Segmentation
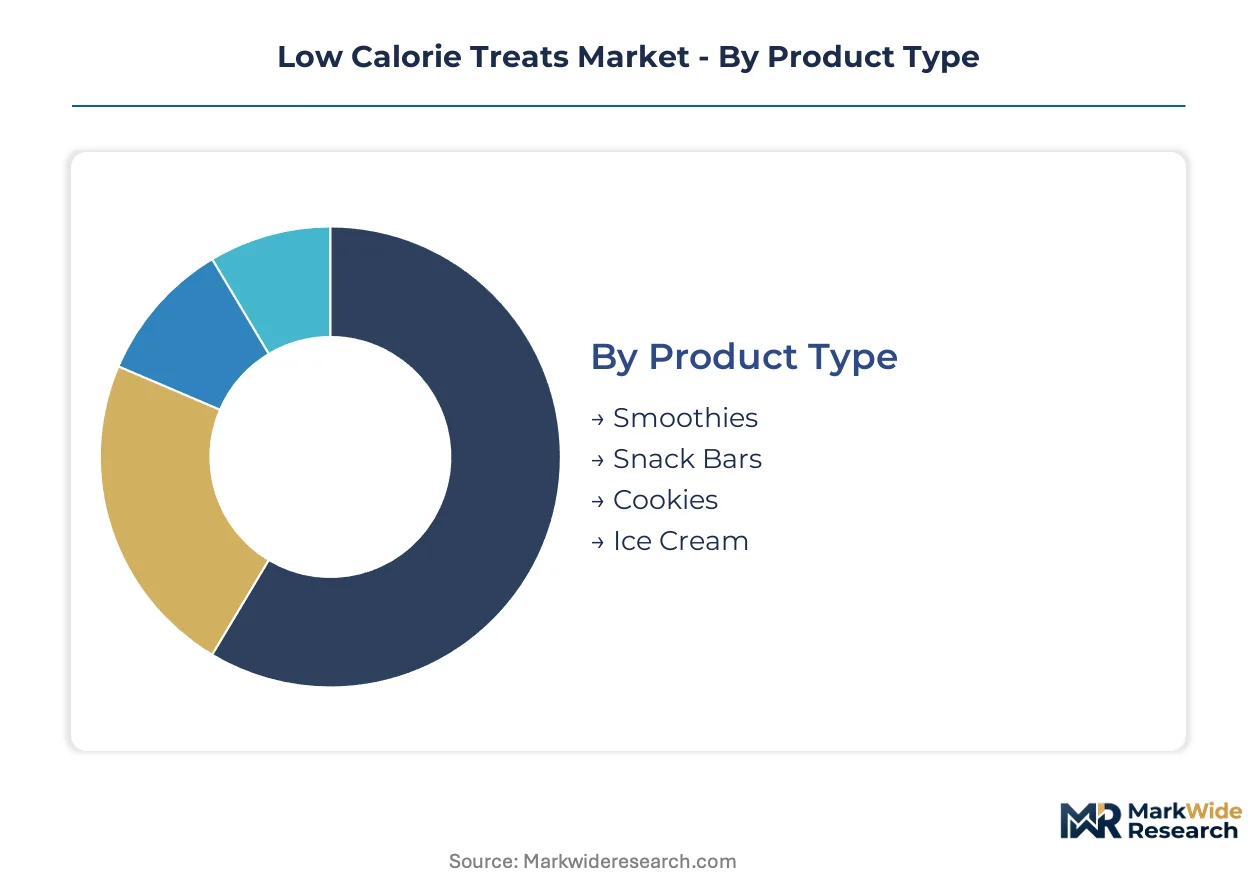
Low calorie treats manufacturers align formulation architecture with distinct consumption occasions and metabolic requirements. Segmentation clarity determines packaging formats, shelf placement strategies, and margin capture potential across competing retail channels.
Product Type:
Extrusion and cold-pressing technologies differentiate caloric density control across format geometries.
- Smoothies:Liquid formats achieve portion control through calibrated bottle sizing with controlled carbohydrate loads. Demand concentrates in urban convenience retail where grab-and-go consumption dominates morning and post-workout occasions.
- Snack Bars:Cold-pressed or extruded bar formats deliver protein-fiber matrices with precise metabolizable energy calculations. Weight Watchers and fitness enthusiasts in metropolitan United States households drive recurring subscription purchases for portion-controlled inventory.
- Cookies:Baked formats utilize alternative carbohydrate sources and bulking fibers to replicate traditional textures at reduced energy density.
- Ice Cream:Frozen dairy and plant-based formats employ air incorporation and sugar alcohol substitution to maintain mouthfeel with diminished caloric impact.
Snack bars lead on scale; smoothies lead on momentum.
Ingredient Type:
Raw material specifications determine functional claim substantiation and pricing tier placement.
- Natural Sweeteners:Stevia, monk fruit, and allulose formulations replace sucrose without glycemic impact. Diabetic consumers and ketogenic diet adherents in health food store channels prioritize these specifications despite input cost premiums.
- High Fiber:Soluble and insoluble fiber additives enhance satiety signaling and reduce net metabolizable energy. Protein Enrichments command expanding margin pools as consumers prioritize muscle preservation during caloric restriction protocols.
- Protein Enrichments:Whey isolates, plant concentrates, and collagen peptides elevate amino acid density per kilocalorie. Fitness enthusiasts seeking body composition optimization represent the core demand concentration for these formulations.
- Gluten-Free:Oat, almond, and coconut flour substitutions eliminate wheat proteins while maintaining structural integrity. This positioning has matured from premium differentiator to baseline expectation across mass-market distribution.
Protein enrichments lead on scale; high fiber leads on momentum.
Target Audience:
Metabolic goals and lifestyle constraints shape product development priorities and marketing architecture.
- Fitness Enthusiasts:Consumers prioritizing macronutrient timing and recovery nutrition. These buyers accept premium pricing for verified protein content and glycemic index certification.
- Health-Conscious Consumers:Broad demographic seeking general wellness optimization through cleaner label profiles. Supermarket channel placement and family-oriented packaging formats capture this volume base.
- Diabetics:Medically motivated buyers requiring glycemic control with validated glucose response data. These consumers concentrate in pharmacy-adjacent retail and specialized online platforms.
- Weight Watchers:Program-affiliated and independent calorie-counters utilizing portion-controlled formats. Urban apartment dwellers with limited storage space favor single-serve configurations.
Health-conscious consumers lead on scale; fitness enthusiasts lead on momentum.
Distribution Channel:
Channel economics determine packaging formats, promotional intensity, and margin retention.
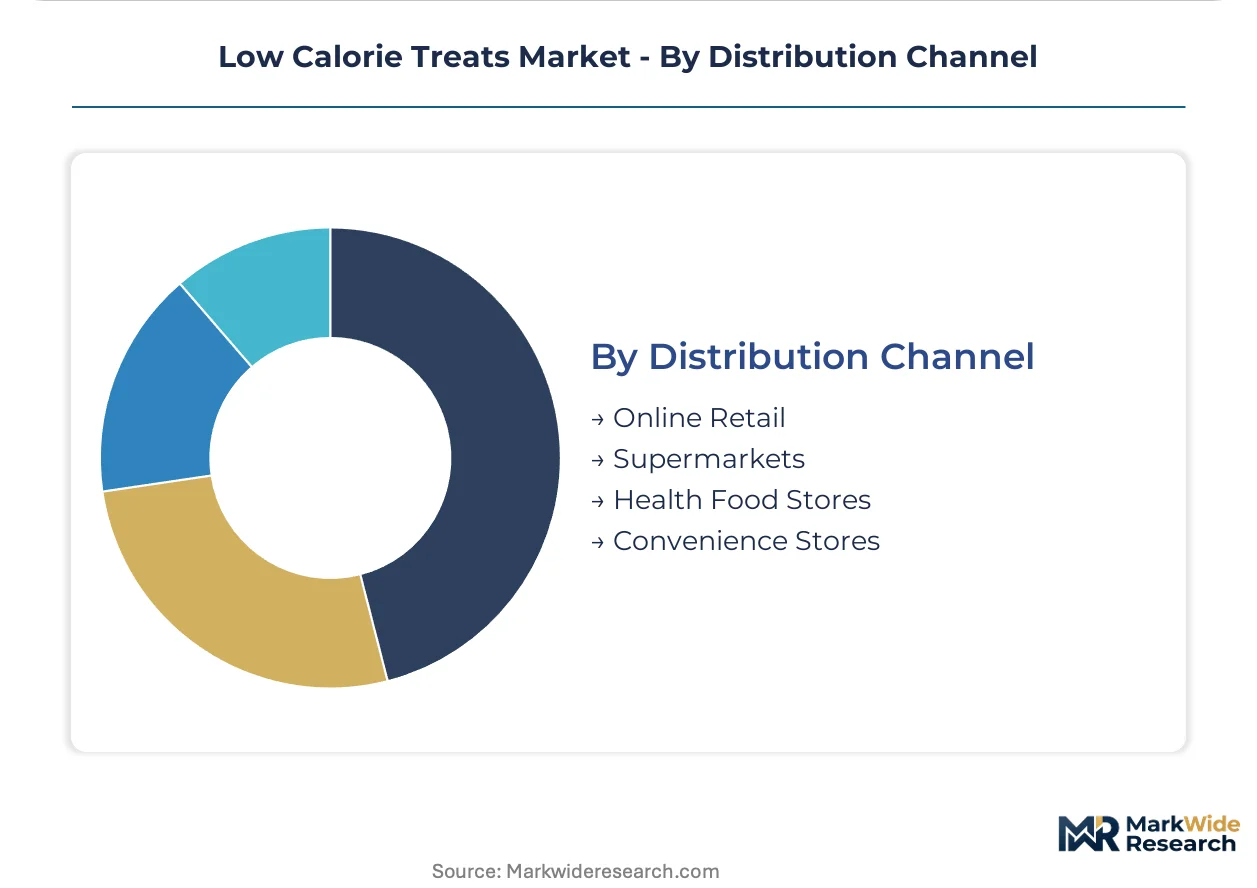
- Online Retail:Direct-to-consumer and marketplace platforms enable subscription mechanics and personalized recommendation algorithms. Auto-replenishment services for portion-controlled formats reduce customer acquisition costs while securing recurring revenue.
- Supermarkets:Mass-market penetration requires competitive unit economics and prominent shelf positioning. Health-conscious consumers drive volume through routine grocery consolidation shopping.
- Health Food Stores:Specialty retailers curate premium-positioned functional formats with enhanced ingredient transparency. These channels concentrate in metropolitan corridors with dense fitness-oriented populations.
- Convenience Stores:Impulse-oriented placement captures unplanned consumption with single-serve and trial-size positioning. Urban household concentration elevates turnover velocity for immediate-consumption formats.
Supermarkets lead on scale; online retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production to jurisdictions with streamlined pet food registration protocols, exploiting cost-of-compliance gaps between federal and state-level enforcement regimes. This arbitrage concentrates formulation capacity in regions with harmonized veterinary feed control laws.
United States
Urban pet-owning households in metropolitan corridors drive demand for portion-controlled treat formats. FDA Center for Veterinary Medicine guidelines and AAFCO model regulations establish calorie claim definitions that reduce interstate distribution friction. California and New York pet specialty chains lead the shift from bulk packaging toward single-serve refrigerated placements.
Germany
Health-conscious consumers prioritize functional nutrition claims for companion animals. EFSA guidelines on feed additives and the country's national veterinary feed control framework shape permissible ingredient declarations. Industrial clusters around Munich and Hamburg host contract manufacturers serving private-label pet wellness brands.
United Kingdom
Veterinary weight management protocols penetrate retail channels as pet humanization deepens. FSA and Defra feed regulations govern metabolizable energy labeling requirements. London and Southeast England concentrate specialty pet retail chains experimenting with subscription-based treat replenishment models.
Japan
Apartment-dwelling pet owners favor compact, calorie-controlled formats suited to limited storage spaces. MAFF and the national feed safety commission enforce strict additive approval processes. Tokyo-Osaka corridor retailers curate premium functional treat assortments targeting aging pet populations.
Brazil
Expanding middle-class pet ownership elevates demand for imported formulation expertise in weight management. ANVISA and the Ministry of Agriculture's feed control division regulate calorie disclosure accuracy. São Paulo industrial zones attract co-manufacturing investment serving Latin American private-label distributors.
Low Calorie Treats Market Competitive Landscape
Portfolio diversification dominates the current landscape as human food manufacturers leverage existing snack bar and extrusion infrastructure to enter pet-adjacent wellness categories. The vendor base separates into three tiers: multinational CPG conglomerates with captive R&D resources, mid-sized ingredient suppliers seeking downstream integration, and specialized contract manufacturers serving private-label demand. Two strategic archetypes predominate: firms exploiting human food manufacturing spillover capabilities, and veterinary nutrition specialists building prescription-aligned distribution. Competitive intensity concentrates on M&A activity targeting formulation expertise and capacity expansion in cold-pressing equipment.
Within the multinational tier, Nestle and General Mills exemplify CPG conglomerates repurposing human snack manufacturing infrastructure for pet wellness applications. Danone occupies a position bridging human low-calorie formats with taste expectations transferable to companion animal products. These three firms anchor the competitive structure through co-manufacturing partnerships and veterinary channel penetration strategies.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| Conagra Brands |
| Danone |
| General Mills |
| The Hain Celestial Group |
| Ingredion |
| Mondelez International |
| Nestle |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up contract manufacturers have consolidated cold-pressing and extrusion capacity across the United States Midwest, tightening supply discipline while anchoring pricing power through captive equipment pools. This ownership concentration feeds directly into tiered margin structures that separate veterinary prescription-adjacent lines from mass-market economy formats.
Pricing Analysis
Retailer markup layers stratify across premium, standard, and economy tiers based on metabolizable energy validation depth and AAFCO compliance certification. Price differentiation centers on veterinary nutritionist formulation oversight and cold-pressed manufacturing credentials. Pricing pressure stems from substitute category encroachment by fresh refrigerated meal formats. Veterinary channels demonstrate least price sensitivity; convenience store impulse buyers face greatest elasticity.
Supply Chain Analysis
Regional distribution centers in Iowa, Nebraska, and Kansas anchor hub-and-spoke patterns serving pet specialty chains and veterinary clinics nationwide. Manufacturing draws from specialized protein isolates sourced from United States dairy processing clusters and novel carbohydrate streams from Canadian pulse processing. Single-source vulnerability concentrates in veterinary nutritionist talent pools for metabolizable energy validation. Distribution runs through temperature-controlled logistics networks with refrigerated last-mile capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity as state agriculture departments tighten feed control enforcement around calorie disclosure accuracy. FDA Center for Veterinary Medicine guidelines on metabolizable energy calculations serve as the primary demand catalyst.
For Market Incumbents: Hedge against substitute category displacement by securing captive cold-pressing capacity in veterinary corridor states. Deepen backward integration into novel fiber additive supply chains before FDA review cycles extend. Reinforce channel control through exclusive veterinary telehealth platform partnerships. For New Entrants and Emerging Players: The gap between premium subscription-formatted snack bars and economy bulk cookies offers white-space entry through mid-tier single-serve positioning. Target urban apartment-dwelling weight watchers with refrigerated case placement in metropolitan pet specialty chains. Deploy direct-to-consumer sampling via veterinary telehealth referral networks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized contract manufacturers lacking in-house metabolizable energy validation capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch state-level enforcement harmonization progress as the inflection signal for national distribution scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Expansion | Prescription-adjacent positioning captures AAFCO-validated premium pricing tiers. |
| Cold-Pressing Capacity Addition | Nutrient-preserving infrastructure locks in metabolizable energy claim substantiation. |
| Subscription Model Penetration | Auto-replenishment mechanics reduce customer acquisition costs for portion-controlled formats. |
| Novel Fiber Additive Integration | Bulking fiber innovations satisfy FDA safety data requirements for reduced-calorie positioning. |
| State Registration Harmonization | Unified agriculture department interpretations compress multi-state product launch timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with veterinary nutritionists, pet specialty retail category managers, contract manufacturing operations directors, and state agriculture department feed control officers with secondary validation against FDA Center for Veterinary Medicine guidance documents, AAFCO model regulation updates, state feed control law databases, and veterinary nutrition research publications. Bottom-up SKU-level enumeration and top-down category sizing triangulated volume estimates.
Historical reference periods anchored the forecast window to established metabolizable energy calculation methodologies and AAFCO regulatory adoption curves. The analytical framework segmented by product type, ingredient category, target metabolic goal, and distribution channel across the projection horizon. CAGRs derived from elasticity-adjusted penetration curves incorporating veterinary protocol adoption rates and urban household concentration trends.
The model assumes a particular technology adoption path; alternative pathways for near-infrared spectroscopy real-time calibration would alter the outlook. Forecasts reflect documented assumptions around state enforcement harmonization timing and veterinary telehealth platform penetration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
Asia-Pacific Compound Chocolate Market
Confectionery
North America Chocolate Market
Confectionery
North America Chocolate Confectionery Market
Confectionery
Africa Compound Chocolate Market
Confectionery
Mints Market
Confectionery
Japan Chocolate Market
Confectionery
Infused Fruits Jellies Market
Confectionery
Gummy Market
Confectionery
Europe Dark Chocolate Market
Confectionery
Mooncake Market
Confectionery
Green Tea Chocolate Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Sugar-Free Sweets Market
Confectionery
United Arab Emirates Sugar Confectionery Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market