
 Kvass Market | 2026-2036
Kvass Market Size, Share, and Industry Trends Forecast 2026-2036
Kvass Market Analysis
Single-serve PET and aluminum can configurations are realigning how urban consumers purchase kvass away from bulk draft formats. Ochakovo Company leverages its Soviet-era brand equity to dominate Moscow's retail channels. Baltika Brewery anchors its kvass portfolio through backward integration into malt and rye supply chains. PepsiCo competes by extending its beverage distribution infrastructure into provincial Russian markets previously served only by local producers.
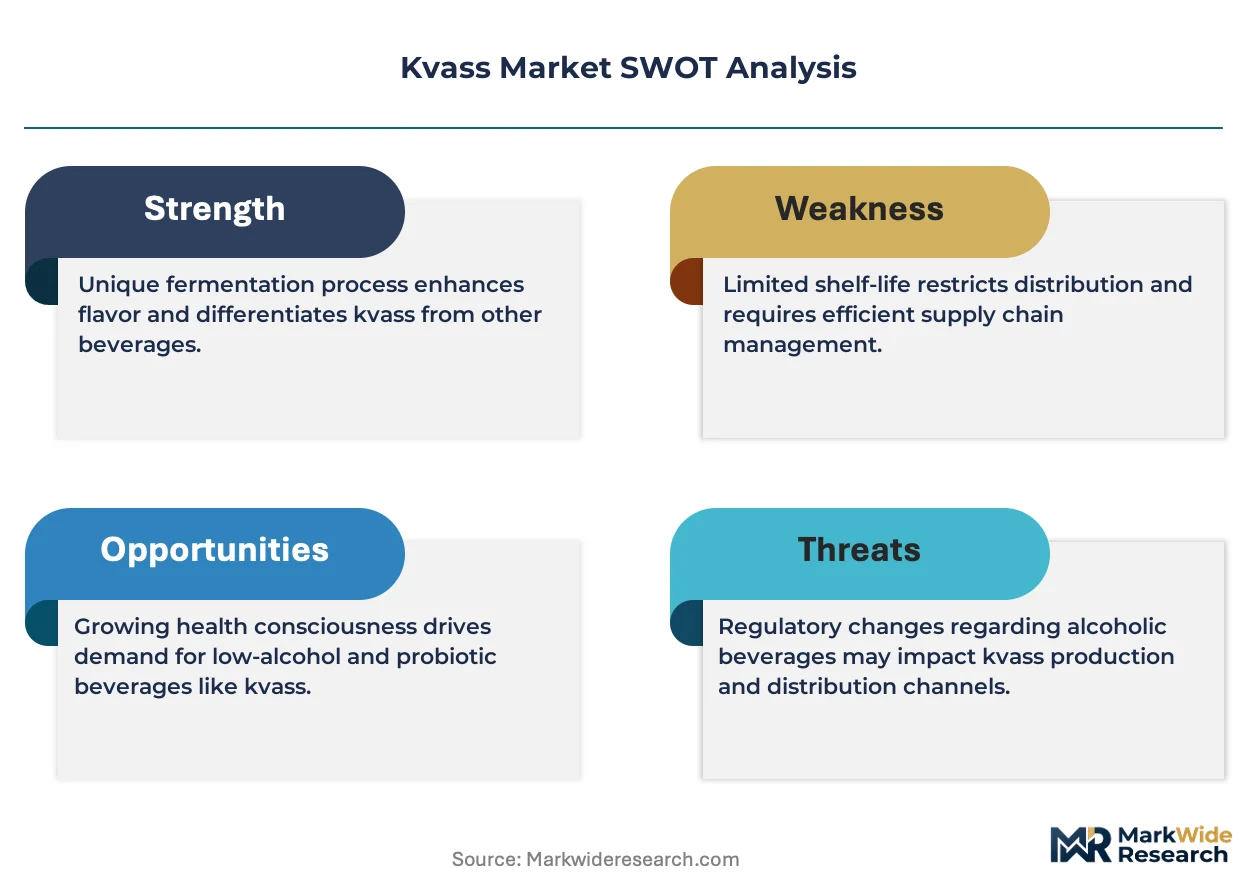
Kvass is a fermented cereal beverage produced from rye bread, malt, or flour through lactic acid and yeast fermentation, typically containing 0.5-1.5% alcohol by volume and valued for its digestive properties and refreshing taste. Traditional kvass maintains volume leadership across Eastern European retail shelves due to minimal ingredient costs and established consumer loyalty. Flavored kvass variants targeting young adults represent the fastest-growing product category as manufacturers experiment with fruit and herbal infusions. The health-conscious consumer segment commands premium pricing, particularly for organic-certified and reduced-sugar formulations distributed through supermarket chains.
Russia's Federal Service for Surveillance on Consumer Rights Protection and Human Wellbeing (Rospotrebnadzor) enforces TR TS 021/2011 technical regulations governing kvass production hygiene and labeling accuracy. The Eurasian Economic Commission's harmonized food safety standards facilitate cross-border trade between Russia, Belarus, and Kazakhstan while imposing uniform additive restrictions. Stakeholders must monitor evolving sugar taxation proposals across Eastern European jurisdictions and assess whether reformulated kvass recipes can maintain traditional taste profiles under tightened compositional limits.
Market Dynamics
Modern grocery retail expansion across Eastern Europe is compressing traditional draft kvass distribution, forcing producers to reconfigure packaging and shelf-life technologies for supermarket supply chains.
Growth Catalysts
- TR TS 021/2011 Compliance:Russia's harmonized food safety technical regulation reduces cross-border friction for kvass producers exporting to Belarus and Kazakhstan. Manufacturers achieving certification gain streamlined market access across the Eurasian Economic Union.
- Fermented Beverage Shelf Space:Supermarket chains in Moscow, Saint Petersburg, and Kyiv are expanding dedicated sections for functional drinks. Retailers recognize kvass as a high-margin category with established consumer recognition and repeat purchase frequency.
- Rye and Malt Supply Integration:Backward integration into cereal supply chains secures input cost stability for large-scale producers. Captive sourcing of black rye bread and malt extract insulates margins from agricultural commodity volatility.
Market Restraints
- Input Cost Concentration:Quality rye cultivation concentrates in Russia's Central Black Earth region and select Ukrainian oblasts. Weather-driven harvest variability directly impacts raw material pricing for fermentation substrates.
- Alcohol Content Ambiguity:Regulatory thresholds between non-alcoholic and low-alcoholic beverages create labeling complexity across jurisdictions. Producers face reformulation costs to maintain sub-0.5% ABV classifications in certain markets.
- Refrigerated Distribution Requirement:Unpasteurized traditional kvass demands cold-chain infrastructure unavailable in provincial Russian and Central Asian retail networks. Shelf-stable alternatives sacrifice taste authenticity and premium positioning.
Strategic Opportunities
- Organic Certification Pathway:EU Regulation 2018/848 equivalence recognition would unlock Western European distribution for certified Russian and Ukrainian producers. Premium positioning in German and Polish ethnic food channels commands significant price multiples.
- Functional Ingredient Convergence:Probiotic strain enhancement combined with adaptogenic herbal infusions targets wellness-oriented young adults. Product development pipelines are exploring schisandra, ginger, and sea buckthorn fortification.
- E-commerce Direct-to-Consumer:Ozon and Wildberries marketplace penetration enables regional producers to bypass Moscow-centric retail gatekeepers. Last-mile cold delivery partnerships overcome traditional distribution barriers to Siberian and Far Eastern consumers.
Industry Challenges
- Microbiological Consistency:Maintaining stable lactic acid bacteria and yeast populations across large-batch fermentation requires specialized biotechnology expertise. Talent scarcity in industrial fermentation science limits producer scale-up capabilities.
- Legacy Equipment Retrofit:Soviet-era production facilities require substantial capital investment for automated clean-in-place systems and aseptic filling lines. Financing availability constrains mid-tier producers' modernization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kvass Market |
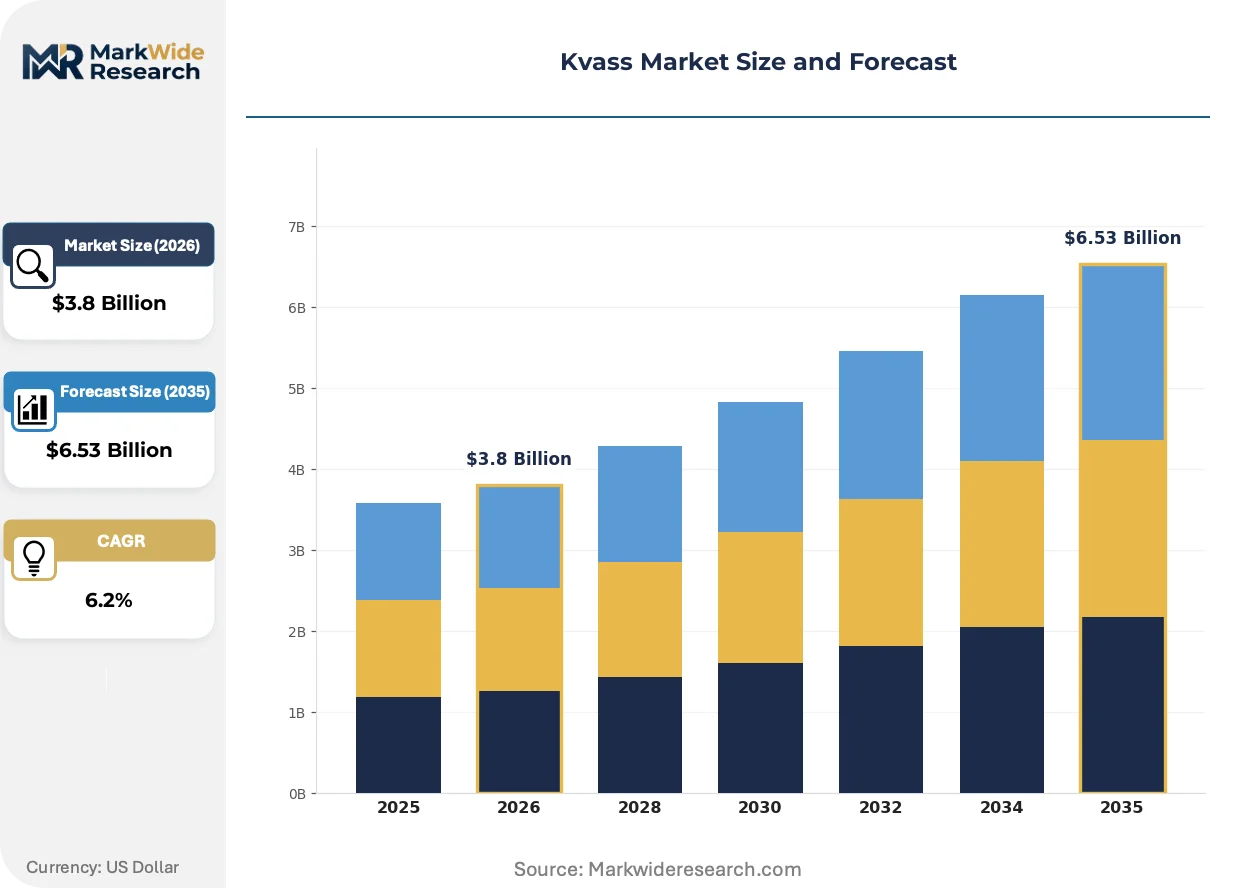
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Kvass, Flavored Kvass, Alcoholic Kvass, Non-Alcoholic Kvass Distribution Channel: Supermarkets, Online Retailers, Local Shops, Restaurants Consumer Segment: Health-Conscious Consumers, Traditionalists, Young Adults, Families Flavor Profile: Sweet, Sour, Herbal, Spicy |
| Companies Covered | Ochakovo Company, Gubernija AB, Carlsberg Group, Kvass Beverages LLC, Deka Company, The Coca-Cola Company, Bryanskpivo OAO, Baltika Brewery, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kvass Market Emerging Trajectories
Packaging technology and distribution channel evolution are redefining how kvass reaches consumers, compressing the gap between artisanal production values and industrial scale efficiency.
Aseptic cold-filling technology for PET bottles is unifying shelf stability with taste authenticity previously achievable only through refrigerated draft distribution. Urban Russian consumers aged 25-40 are adopting single-serve formats at accelerating rates. This packaging shift is enabling regional producers to access Moscow retail shelves without establishing capital-intensive local brewing facilities.
Russia's Rospotrebnadzor is tightening enforcement of TR TS 021/2011 additive disclosure requirements for flavored kvass variants. The regulatory pressure is forcing reformulation of fruit-infused product lines toward natural extract systems. Premium organic producers in Saint Petersburg and Krasnodar Krai are responding fastest, leveraging existing clean-label supply chain relationships.
Convenience-store channel expansion is displacing traditional street-side kvass barrels in Ukrainian and Russian cities. Young adult consumers in Kyiv, Kharkiv, and Yekaterinburg now purchase chilled single-serve cans during commuting hours. This behavioral shift concentrates demand toward branded packaged products and away from unbranded bulk dispensing.
Kvass Market Segmentation
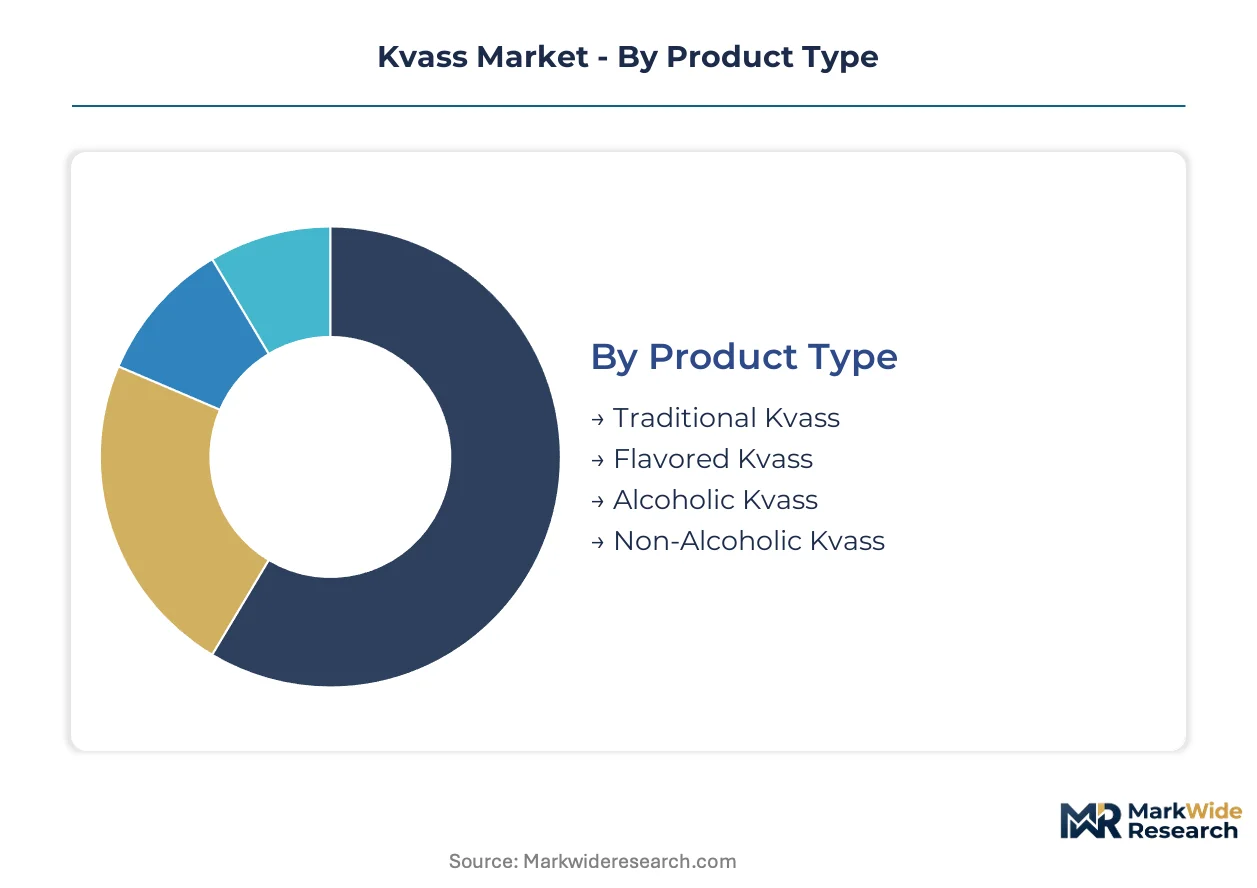
Kvass producers navigate distinct demand profiles across consumption occasions, with traditional fermented formats commanding shelf stability while innovative variants target health-positioned premiums. Segmentation reveals how packaging evolution and channel expansion are fragmenting what was historically a uniform bulk beverage category.
Product Type:
Standalone consumption dominates daily drinking occasions, while embedded applications in cooking and mixology remain underdeveloped commercial vectors.
- Traditional Kvass:Fermented rye bread base with 0.5-1.5% ABV maintains the category's volume anchor through minimal processing and established production protocols. Russian and Ukrainian households in Moscow, Saint Petersburg, and Kyiv sustain repeat purchase patterns for unflavored variants distributed through modern grocery channels.
- Flavored Kvass:Fruit and herbal infusions target young adult trial through differentiated taste profiles and premium single-serve packaging. Saint Petersburg producers are accelerating berry and ginger variant launches to capture convenience-store channel growth.
- Alcoholic Kvass:Higher ABV formulations (2-3%) occupy niche positioning in specialty retail and on-premise channels, requiring distinct licensing frameworks.
- Non-Alcoholic Kvass:Sub-0.5% ABV variants address regulatory thresholds in Kazakhstan and Belarus cross-border trade, sacrificing some fermentation depth for distribution compliance.
Volume placements concentrate in Traditional Kvass; the faster expansion belongs to Flavored Kvass.
Distribution Channel:
Cost tier stratification separates capital-intensive modern retail from low-fixed-cost traditional outlets, with digital intermediaries capturing margin from both.
- Supermarkets:Aseptic PET and aluminum can formats dominate shelf space allocation in Moscow and Kyiv chains, with Rospotrebnadzor-compliant labeling enabling Eurasian Economic Union cross-listing. Refrigerated section placement commands slotting fees that filter smaller producers toward alternative channels.
- Online Retailers:Ozon and Wildberries marketplace infrastructure enables direct-to-consumer penetration of Siberian and Far Eastern markets previously unreachable through conventional distribution. Cold-chain logistics partnerships overcome the traditional draft barrel's geographic limitations.
- Local Shops:Neighborhood proximity retail maintains draft kvass barrel presence in Russian provincial cities and Ukrainian towns, serving price-sensitive daily consumption.
- Restaurants:On-premise placement concentrates in ethnic cuisine establishments across Eastern European capitals, with limited penetration into mainstream foodservice.
Supermarkets capture the highest absolute volume; online retailers are climbing the fastest as logistics infrastructure matures.
Consumer Segment:
Application intensity varies from daily ritual consumption among heritage-oriented users to occasional functional beverage adoption among wellness seekers.
- Health-Conscious Consumers:Probiotic content and digestive health claims drive premium pricing for organic-certified and reduced-sugar formulations in supermarket chains.
- Traditionalists:Heritage-motivated drinkers in Russia and Ukraine sustain bulk draft purchases, resisting packaged format migration despite urban retail transformation.
- Young Adults:Convenience-oriented urban consumers aged 25-40 in Yekaterinburg and Kharkiv are adopting single-serve flavored variants for commuting consumption.
- Families:Multi-liter household purchases concentrate in suburban and provincial markets, prioritizing value positioning over functional claims.
Traditionalists retain the largest volume base; young adults are gaining share fastest through format innovation.
Flavor Profile:
Customer type differentiation separates mass-market sweetness from artisanal sour and botanical positioning, with regional taste preferences shaping formulation decisions.
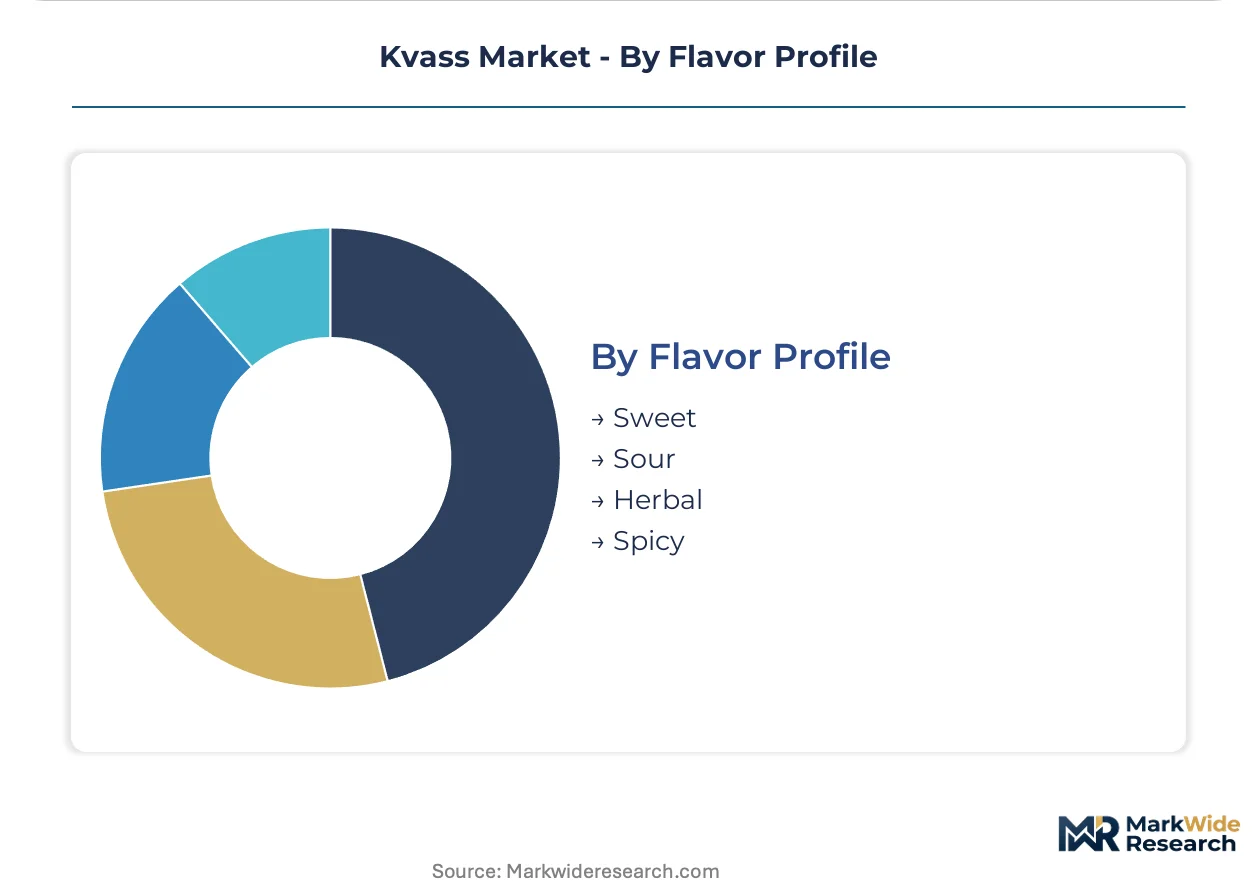
- Sweet:Sugar-forward profiles dominate mass-market packaged kvass in Russia, though reformulation pressures from proposed sugar taxation are forcing gradual reduction.
- Sour:Traditional fermentation intensity appeals to heritage consumers in Ukraine and Baltic ethnic communities, with shorter shelf life limiting distribution radius.
- Herbal:Mint, chamomile, and adaptogenic infusions target wellness-positioned young adults in premium supermarket tiers.
- Spicy:Ginger and pepper variants occupy niche positioning, with limited production scale outside experimental craft producers.
Sweet formulations hold the dominant volume position; herbal profiles are expanding most quickly through functional beverage convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia dominates kvass production capacity while Ukraine sustains comparable per-capita consumption rates. Cross-border trade flows concentrate through Belarus and Kazakhstan under Eurasian Economic Union harmonized standards. Western distribution remains limited to ethnic retail channels in Germany and Poland.
Russia
Moscow and Saint Petersburg drive packaged kvass demand through supermarket channel expansion. Rospotrebnadzor enforces TR TS 021/2011 technical regulations governing fermentation hygiene and additive disclosure. The Central Black Earth region anchors rye cultivation, with Voronezh and Tambov oblasts supplying malt extract to large-scale producers.
Ukraine
Kyiv and Kharkiv sustain daily consumption rituals through convenience-store format migration. The State Service of Ukraine on Food Safety and Consumer Protection monitors production facility compliance with national food safety standards. Lviv maintains artisanal production clusters where small-batch sour kvass commands premium positioning in specialty retail.
Belarus
Minsk channels re-export demand from Russian producers seeking Eurasian Economic Union tariff advantages. The Department for Sanitary and Epidemiological Surveillance enforces technical regulation alignment with Russian standards. Grodno and Brest regions develop indigenous production capacity to capture domestic market share from cross-border imports.
Kazakhstan
Almaty and Nur-Sultan concentrate urban demand for sub-0.5% ABV formulations compliant with local non-alcoholic beverage classifications. The Committee for Sanitary and Epidemiological Control of the Ministry of Health regulates import standards for Russian and Ukrainian producers. Shymkent and Karaganda emerge as regional distribution hubs for Central Asian market penetration.
Poland
Warsaw and Krakow host ethnic food retail channels serving Russian and Ukrainian diaspora communities. The Chief Sanitary Inspectorate applies EU food safety frameworks to imported fermented beverages. Poznan and Wrocław develop local craft production experimenting with Baltic-style formulations for domestic consumer trial.
Kvass Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the kvass category. The market structure consolidates around beverage multinationals leveraging distribution infrastructure alongside heritage producers defending regional brand equity. Strategic archetypes include Soviet-era legacy brewers, multinational beverage extenders, and regional malt-integrated specialists. Dominant competitive moves center on backward integration into rye supply chains and e-commerce marketplace penetration bypassing traditional retail gatekeepers.
Among Russia-based heritage producers, Ochakovo Company and Baltika Brewery exemplify the legacy brewer archetype with established Soviet-era brand recognition. PepsiCo represents the multinational extender model, applying beverage distribution infrastructure to provincial market penetration. These three anchors illustrate how scale advantages separate from authentic production heritage in competitive positioning.
| Leading Market Players |
|---|
| Ochakovo Company |
| Gubernija AB |
| Carlsberg Group |
| Kvass Beverages LLC |
| Deka Company |
| The Coca-Cola Company |
| Bryanskpivo OAO |
| Baltika Brewery |
| PepsiCo |
| Others |
Supply Flow & Price Mechanics
Organic-to-conventional certification divergence splits the Kvass Market into sharply divergent pricing strata, with EU Regulation 2018/848 equivalence commanding 40-60% premia in German and Polish ethnic channels while commodity rye-based formulations compete on input cost minimization through Central Black Earth sourcing.
Pricing Analysis
Margin tightening in traditional draft kvass reflects supermarket slotting fee escalation and refrigerated distribution cost absorption. Three-tier pricing structure across premium organic, standard packaged, and economy bulk levels separates health-conscious urban consumers from price-sensitive provincial households. Brand premiums for Soviet-era heritage labels persist in Moscow and Saint Petersburg despite private-label encroachment. Young adult convenience-store buyers exhibit lowest price sensitivity; family bulk purchasers in Siberian and Far Eastern regions drive hardest bargain negotiations.
Supply Chain Analysis
Regional distribution centers in Voronezh, Tambov, and Krasnodar Krai anchor hub-and-spoke patterns radiating toward Moscow retail gates and cross-border Eurasian Economic Union corridors. Rye cultivation concentrates in Russia's Central Black Earth region and select Ukrainian oblasts; malt extract production feeds from captive brewery integration. Single-source vulnerability to weather-driven harvest variability threatens input cost stability. Distribution runs through modern grocery chains displacing traditional street-side barrel networks, with Ozon and Wildberries marketplace infrastructure capturing last-mile margin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic cold-filling technology is displacing Soviet-era draft infrastructure, compressing shelf-life extension costs while enabling regional producer access to Moscow-centric retail channels previously blocked by capital barriers.
For Market Incumbents: Deploy backward integration into rye and malt supply chains to insulate margins from agricultural commodity volatility. Ochakovo Company and Baltika Brewery should accelerate automated clean-in-place system retrofit across legacy fermentation facilities to defend microbiological consistency against craft producer quality encroachment. Channel control through exclusive supermarket refrigerated section placement agreements blocks regional competitor shelf access.
For New Entrants and Emerging Players: E-commerce direct-to-consumer infrastructure offers the most penetrable wedge for bypassing Moscow retail gatekeepers. Target Siberian and Far Eastern consumers through Ozon and Wildberries cold-chain logistics partnerships previously unreachable through conventional distribution. Functional ingredient convergence—probiotic strain enhancement combined with schisandra or sea buckthorn fortification—captures wellness-oriented young adult trial in premium supermarket tiers.
For Investors and Strategic Acquirers: Re-rating potential sits with organic-certified producers given EU Regulation 2018/848 equivalence recognition catalyst unlocking Western European distribution. Long-term viability hinges on fermentation biotechnology talent acquisition and clean-label supply chain construction. Monitor Rospotrebnadzor sugar taxation enforcement as inflection indicator for reformulation cost exposure across sweet-profile dominant portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Filling Technology Adoption | Unifies shelf stability with taste authenticity for PET bottle distribution through Moscow supermarket chains. |
| Backward Integration into Rye Supply | Captive sourcing from Voronezh and Tambov oblasts insulates margins from Central Black Earth harvest variability. |
| E-Commerce Marketplace Penetration | Ozon and Wildberries partnerships overcome geographic barriers to Siberian and Far Eastern consumer segments. |
| Organic Certification Investment | EU Regulation 2018/848 equivalence unlocks premium ethnic channel positioning in German and Polish markets. |
| Functional Ingredient Convergence | Probiotic enhancement with adaptogenic herbal infusions targets wellness-oriented young adult convenience-store trial. |
Methodological Framework
Independent corroboration across Rospotrebnadzor regulatory filings, Eurasian Economic Commission trade databases, and Nielsen retail audit data underwrites the qualitative findings. Primary interviews with fermentation biotechnology directors, supermarket category buyers, and Ozon marketplace supply chain managers combined with secondary validation from customs records and SEC beverage segment disclosures. Bottom-up producer capacity assessments and top-down consumption modeling triangulate volume estimates.
Rate-of-change decomposition across product type, distribution channel, and consumer segment dimensions structures the analytical framework throughout the forecast period. CAGRs derive from segment-level growth rate blending against macroeconomic consumption elasticity assumptions. Industry-specific inputs include rye harvest yield projections and Rospotrebnadzor enforcement intensity scoring for additive disclosure compliance.
Several conditions sit outside the modeled scope, including potential TR TS 021/2011 regulatory amendments, sugar taxation implementation timelines, and geopolitical trade flow disruptions. Forecasts reflect documented assumptions regarding Eurasian Economic Union harmonization continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Botanical Infused Beverages Market
Beverages
Blenders Market
Beverages
Foaming Creamer Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Plant Based Beverages Market
Beverages
Baby Drinking Water Market
Beverages
Bottled Water Processing Market
Beverages
Canned Beverages Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Superfood Infused Beverages Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Europe Beverage Market
Beverages
Carbonate Drink Maker Market
Beverages
Plant Based Protein Beverages Market
Beverages
Bangladesh Energy Drinks Market