
 Europe Sugar Free Energy Drinks Market | 2026-2036
Europe Sugar Free Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sugar Free Energy Drinks Market Insights
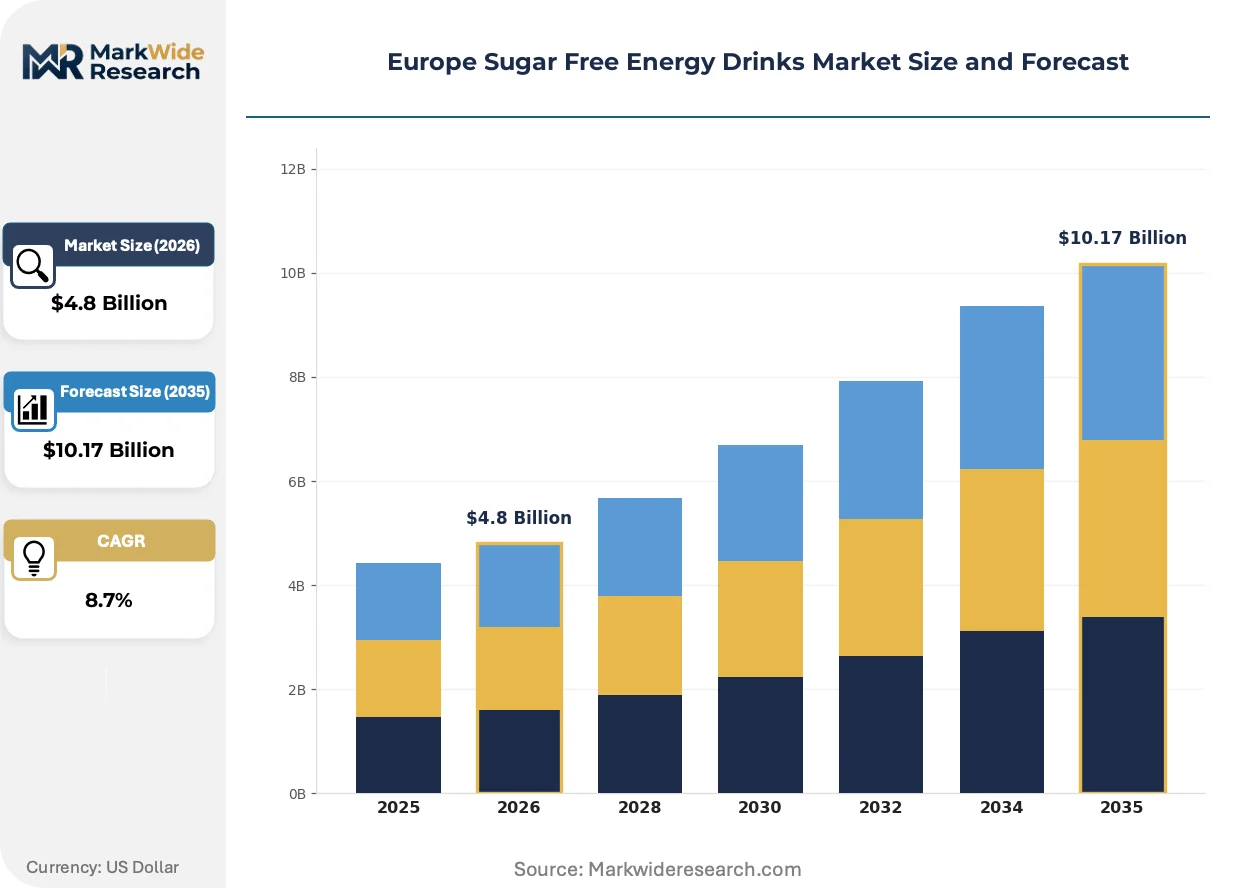
Premium functional-tier positioning is bifurcating the Europe sugar free energy drinks landscape into performance-certified and mass-market wellness segments. Red Bull GmbH leverages its Austrian heritage and event-sponsorship infrastructure to sustain brand authority across Central European convenience channels. PepsiCo, Inc. competes through extensive supermarket and hypermarket distribution networks spanning France, Spain, and Italy. Monster Beverage Corporation differentiates via gaming and esports partnerships that anchor loyalty among younger demographics.
Europe sugar free energy drinks are non-alcoholic, caffeinated beverages containing synthetic or natural non-nutritive sweeteners such as sucralose, steviol glycosides, or acesulfame potassium, formulated to deliver alertness without caloric load. They serve commercial purposes spanning athletic performance support, workplace productivity enhancement, and social consumption occasions where sugar avoidance is prioritized. Ready-to-drink formats dominate volume flows through supermarkets and convenience stores, while powdered variants capture margin pools in health stores and online channels serving committed fitness enthusiasts. Carbonated products retain the largest share of shelf space, though non-carbonated lines are gaining velocity among general consumers seeking cleaner-label alternatives.
The European Food Safety Authority sets maximum caffeine thresholds that constrain formulation latitude, while the EU Green Deal's packaging waste directives are forcing transitions toward recycled PET and aluminum can circularity. Nutri-Score front-of-pack labeling requirements in France and Belgium create competitive pressure to improve nutritional profiles beyond mere sugar elimination. Stakeholders must monitor evolving EFSA sweetener safety assessments and national deposit-return scheme expansions that will reshape cost structures and channel economics.
Market Dynamics
The EU's Nutri-Score labeling mandate and EFSA sugar reduction targets are compressing formulation cycles while fragmenting competitive positioning between performance-certified and mass-market wellness tiers across the continent.
Growth Catalysts
- Gym culture proliferation:Fitness enthusiasts represent the fastest-expanding end-user cohort as dedicated training facilities multiply across Germany, France, and Poland.
- EFSA regulatory clarity:Established maximum caffeine thresholds provide formulation certainty that accelerates new product development timelines.
- Steviol glycoside innovation:Natural sweetener advances are displacing synthetic alternatives in premium positioning strategies.
Market Restraints
- Aluminum can supply concentration:Packaging material dependence on limited European smelter capacity creates input cost volatility.
- Deposit-return scheme fragmentation:National variations in Germany, Belgium, and Nordic markets force redundant logistics infrastructure.
- Aspartame safety reassessment:Pending EFSA sweetener reviews introduce formulation uncertainty for legacy product lines.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania exhibit per-capita consumption gaps versus Western European benchmarks.
- Health store channel expansion:Powdered variants capture margin pools through specialized retail and direct-to-consumer platforms.
- EU Green Deal packaging mandates:Recycled PET transitions create first-mover advantages in circular economy positioning.
Industry Challenges
- Reformulation timeline compression:Accelerated EFSA compliance deadlines strain R&D resource allocation.
- Supply chain reconfiguration friction:Deposit-return scheme expansions force distributor relationship restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sugar Free Energy Drinks Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Powdered, Ready-to-Drink End User: Fitness Enthusiasts, Athletes, General Consumers, Students Flavor: Citrus, Berry, Tropical, Coffee Distribution Channel: Supermarkets, Online Stores, Health Stores, Convenience Stores |
| Companies Covered | The Coca-Cola Company, Carabao Group Public Company Limited, Monster Beverage Corporation, Grenade (UK) Limited, A.G. BARR P.L.C., Red Bull GmbH, Suntory Holdings Limited, Keurig Dr Pepper, Inc., PepsiCo, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sugar Free Energy Drinks Market Trends and Innovations
Formulation science and packaging engineering are converging to reshape product architecture, with regulatory pressure and consumption-pattern shifts compressing development cycles across the European landscape.
Natural sweetener blending technology is miniaturizing the functional gap between sugar-free and full-sugar sensory profiles. Beverage technologists in Germany and the Netherlands are deploying microencapsulation to mask steviol aftertaste in carbonated bases. This convergence is miniaturizing the premium-mass market price differential that previously separated performance-certified from wellness-tier positioning.
France and Belgium's Nutri-Score front-of-pack labeling requirements are forcing nutritional profile improvements beyond caloric reduction alone. Manufacturers must now optimize additive loads and micronutrient density to achieve favorable color-coded ratings. The mass-market wellness segment faces the steepest compliance investment as reformulation costs concentrate on high-volume SKUs.
Gaming and esports consumption occasions are displacing traditional nightlife and workplace consumption as primary demand anchors. Younger demographics in Spain and Italy are sourcing sugar-free energy drinks through specialized online channels rather than convenience retail. This behavioral pivot is fragmenting distributor relationships and compressing brand loyalty cycles across Southern European markets.
Europe Sugar Free Energy Drinks Market Segmentation
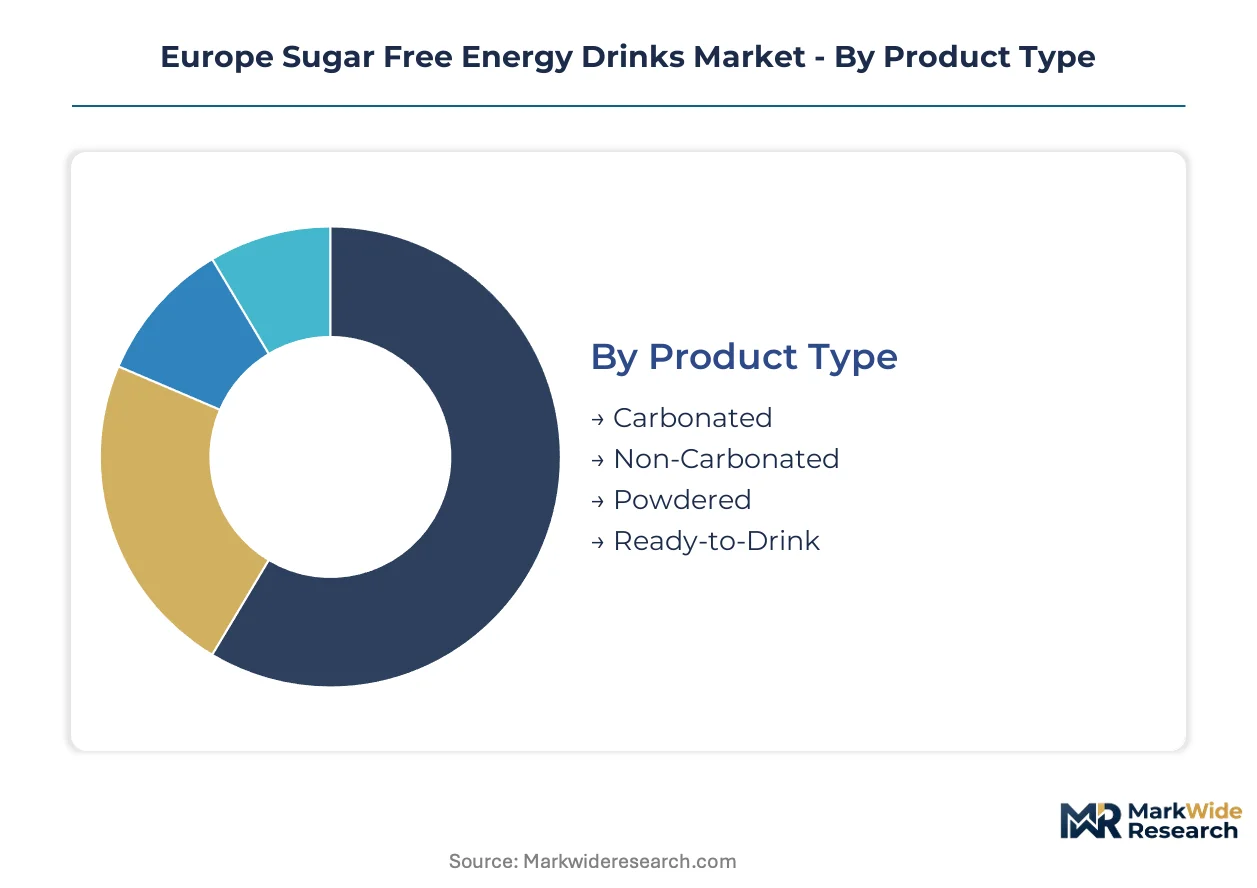
Europe sugar free energy drinks exhibit distinct demand patterns across formulation formats, user profiles, and channel structures. EFSA caffeine thresholds and national labeling mandates create divergent compliance burdens that reshape segment economics differently.
Product Type:
EFSA's maximum caffeine regulations and France's Nutri-Score labeling apply differential pressure across carbonated versus non-carbonated bases, altering reformulation investment priorities.
- Carbonated:Pressurized CO2 bases dominate German and Austrian convenience channel shelf space. EFSA caffeine caps constrain formulation latitude, forcing manufacturers to optimize sweetener blends rather than stimulant loads. Established volume favors carbonated; emerging adoption favors non-carbonated.
- Non-Carbonated:Still formulations gain velocity in Belgium and Netherlands health-conscious segments. Cleaner-label positioning attracts wellness-tier consumers seeking reduced additive profiles beyond mere sugar elimination. Steviol glycoside microencapsulation from Dutch beverage technologists masks aftertaste in these bases.
- Powdered:Dry concentrates capture margin pools through specialized health stores and direct-to-consumer platforms serving committed fitness enthusiasts in Poland and Romania.
- Ready-to-Drink:Single-serve liquid formats flow through supermarket and hypermarket networks across France, Spain, and Italy with extensive distribution coverage.
Carbonated SKUs absorb the bulk of reformulation compliance costs; powdered variants escape front-of-pack labeling scrutiny.
End User:
Gym culture proliferation across Germany, France, and Poland concentrates demand among performance-oriented cohorts willing to pay certification premiums.
- Fitness Enthusiasts:Dedicated training facility users represent the fastest-expanding cohort as membership rolls multiply across Central European markets. These consumers source through specialized channels and demand functional ingredient transparency.
- General Consumers:Mass-market wellness seekers in Belgium and Netherlands prioritize Nutri-Score ratings over performance claims, driving formulation changes toward micronutrient density improvements.
- Athletes:Competition-certified products face stricter contaminant testing requirements from national anti-doping authorities across EU member states.
- Students:Younger demographics in Spain and Italy source through gaming and esports specialized online channels rather than traditional convenience retail.
Athletes command price premiums for certification; students fragment loyalty cycles through digital-first purchasing.
Flavor:
Sensory profile preferences correlate with consumption occasion and channel format across distinct national markets.
- Citrus:Lemon-lime and orange variants dominate carbonated formats in German convenience channels, benefiting from established palate familiarity.
- Berry:Mixed berry profiles anchor wellness-tier positioning in French supermarkets where Nutri-Score visibility drives selection behavior.
- Tropical:Mango and passionfruit formulations attract younger demographics in Italian and Spanish markets through esports and gaming consumption occasions.
- Coffee:Caffeine-plus-coffee hybrid products capture workplace productivity segments in Netherlands and Belgium with extended-release energy positioning.
Citrus anchors established volume; tropical gains share fastest through digital-native distribution.
Distribution Channel:
National deposit-return scheme variations force redundant logistics infrastructure that reshapes channel economics differently across member states.
- Supermarkets:Hypermarket networks spanning France, Spain, and Italy provide PepsiCo with extensive shelf access for mass-market wellness tier placement.
- Convenience Stores:Central European petrol station and urban convenience channels sustain Red Bull's Austrian-heritage brand authority through event-sponsorship infrastructure.
- Online Stores:Gaming and esports specialized platforms fragment Southern European distributor relationships as younger demographics bypass traditional retail.
- Health Stores:Specialized retail and direct-to-consumer platforms capture powdered variant margin pools serving committed fitness enthusiasts in Poland and Romania.
Supermarkets concentrate volume; online stores climb the fastest through demographic behavioral pivots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Austria-based Red Bull GmbH ships sugar-free formulations across Central European convenience corridors into Germany, Poland, and Switzerland. Dutch beverage technologists export steviol glycoside microencapsulation expertise to Belgian and French reformulation labs. Nordic deposit-return logistics flow recycled aluminum from Swedish smelters into Danish and Norwegian retail channels.
Germany
Fitness enthusiasts drive per-capita consumption leadership as gym memberships multiply across Berlin and Munich metropolitan clusters. EFSA caffeine thresholds provide formulation certainty that accelerates new product development timelines for domestic bottlers. Bavaria's beverage technology cluster hosts steviol glycoside innovation labs serving Central European reformulation demand.
France
Nutri-Score front-of-pack labeling forces micronutrient density improvements beyond mere sugar elimination in Parisian supermarket chains. ANSM coordinates with EFSA on additive safety assessments that constrain flavoring agent selection. Île-de-France logistics hubs distribute wellness-tier products to Belgian and Luxembourg cross-border consumers.
Netherlands
Still-formulation adoption accelerates among health-conscious consumers seeking cleaner-label alternatives to carbonated legacy products. The Dutch national packaging waste directive enforces recycled PET transitions ahead of EU Green Deal baseline requirements. Rotterdam port infrastructure handles stevia extract imports from South American suppliers for regional sweetener processing.
Poland
Eastern European underpenetration creates expansion opportunity as per-capita consumption trails Western benchmarks by significant margins. National deposit-return scheme implementation forces distributor relationship restructuring across Warsaw and Kraków retail networks. Specialized health stores in Silesian urban centers capture powdered variant margin pools serving committed fitness enthusiasts.
Spain
Gaming and esports consumption occasions displace traditional nightlife demand among younger demographics in Madrid and Barcelona. Specialized online channels fragment distributor relationships as digital-native purchasing bypasses convenience retail. Tropical flavor formulations gain velocity through esports sponsorship platforms targeting Southern European youth segments.
Europe Sugar Free Energy Drinks Market Competitive Landscape
Listed leaders compete with private specialists across distribution channel access and event-sponsorship infrastructure. The market exhibits consolidated brand authority at the premium functional tier alongside fragmented wellness-tier competition from regional bottlers. Three archetypes dominate: heritage energy specialists with sponsorship ecosystems, diversified beverage conglomerates with supermarket scale, and fitness-focused niche formulators with health-store penetration. Competitive moves concentrate on portfolio diversification into natural sweetener lines and strategic partnerships with esports and gaming platforms.
Within the heritage specialist tier, Red Bull GmbH and Monster Beverage Corporation exemplify divergent positioning strategies. Red Bull's Austrian-heritage brand authority anchors Central European convenience channel presence through event-sponsorship infrastructure spanning music festivals and extreme sports. Monster occupies a position calibrated toward younger demographics via gaming and esports partnerships that fragment traditional retail loyalty cycles. Among diversified conglomerates, PepsiCo, Inc. represents supermarket and hypermarket scale across France, Italy, and Spain. The Coca-Cola Company sits within the same archetype with complementary distribution depth. Fitness-focused specialists include Grenade (UK) Limited, which exemplifies health-store channel penetration and performance-certified product architecture.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| Carabao Group Public Company Limited |
| Monster Beverage Corporation |
| Grenade (UK) Limited |
| A.G. BARR P.L.C. |
| Red Bull GmbH |
| Suntory Holdings Limited |
| Keurig Dr Pepper, Inc. |
| PepsiCo, Inc. |
| Others |
Pricing and Supply Chain Analysis
Sixty-day stevia extract inventory cycles from South American suppliers into Rotterdam anchor both input cost volatility and formulation pricing power for European bottlers. This lead-time exposure concentrates margin pressure on wellness-tier SKUs while insulating premium performance-certified lines.
Pricing Analysis
Fitness enthusiasts anchor a three-tier pricing structure across premium, standard, and economy levels in the European sugar free energy drinks market. Price differentiation stems from certification grade—EFSA compliance tiers versus Informed Sport certification—and volume scale through supermarket contracts versus convenience single-serve. Cost compression in mass-market wellness tiers is intensifying because Nutri-Score reformulation investments concentrate on high-volume SKUs. General consumers in Belgium and Netherlands exhibit highest price sensitivity, while performance-certified athletes accept premium positioning.
Supply Chain Analysis
Container availability fluctuations on the Santos-Rotterdam lane constrain stevia extract inbound flows to Dutch beverage technology clusters. Geographic supply concentration centers on Austria for Red Bull's Central European distribution, Germany for domestic bottling capacity, and Netherlands for sweetener processing infrastructure. Raw material dependencies rest on Brazilian stevia leaf, Chinese acesulfame potassium, and European aluminum smelter output. Single-source vulnerability in aluminum can supply from limited European smelter capacity threatens packaging continuity. Distribution runs through supermarket-hypermarket networks in France and Spain, convenience petrol stations in Germany and Austria, and specialized health stores in Poland and Romania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's sugar free energy drinks market sits in early-cycle expansion as gym culture penetration in Poland and Romania trails Western benchmarks by substantial margins, creating runway for per-capita consumption convergence.
For Market Incumbents: Shield premium positioning against wellness-tier commoditization by accelerating steviol glycoside microencapsulation R&D in Bavarian beverage technology clusters. Deepen backward integration into recycled PET supply through EU Green Deal packaging mandate compliance ahead of regulatory deadlines. Control event-sponsorship infrastructure against gaming and esports platform fragmentation threatening Central European convenience channel loyalty.
For New Entrants and Emerging Players: Health store channel under-service in Polish Silesian urban centers offers white-space entry for powdered variant specialists. Esports platform distribution gaps in Spanish and Italian markets enable digital-native brand building bypassing traditional retail gatekeepers. Pursue direct-to-consumer subscription models targeting committed fitness enthusiasts with transparent functional ingredient disclosure.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EFSA sweetener safety reassessments and national deposit-return scheme expansions will force consolidation among sub-scale regional bottlers. Target acquisition archetypes: fitness-focused niche formulators with health-store penetration and natural sweetener IP. Monitor EFSA aspartame review outcomes as inflection signal for legacy formulation obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Natural Sweetener Line Extension | Steviol glycoside innovation displaces synthetic alternatives in premium positioning strategies. |
| Esports Platform Partnership | Gaming consumption occasions fragment traditional retail loyalty cycles among Spanish and Italian youth. |
| Recycled PET Transition | EU Green Deal packaging mandates create first-mover advantages in circular economy positioning. |
| Eastern European Distribution Buildout | Poland and Romania per-capita consumption gaps versus Western benchmarks offer expansion runway. |
| Nutri-Score Optimization Investment | France and Belgium labeling requirements force micronutrient density improvements beyond sugar elimination. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA additive safety assessments, EU customs trade data, and national deposit-return scheme filings. Primary interviews engaged beverage technology R&D directors, supermarket category buyers in France and Germany, convenience channel sales heads, health store procurement managers in Poland, and fitness facility operators. Secondary validation drew from EFSA scientific opinions, EU Green Deal packaging directives, and beverage industry association reports. Bottom-up SKU-level volume estimates triangulated against top-down category spend analysis.
Segmentation dimensions modeled span product type—carbonated, non-carbonated, powdered, ready-to-drink—end user profile, flavor category, and distribution channel structure across the analysis window. CAGRs derived from trend extrapolation of per-capita consumption patterns, gym membership growth trajectories, and regulatory compliance timeline impacts. Forecast inputs incorporated EFSA caffeine threshold enforcement schedules and Nutri-Score adoption expansion across member states.
Underlying assumptions cover stable EFSA regulatory frameworks and continued gym culture proliferation, with deviation risk concentrated in pending aspartame safety reassessments and aluminum supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Fruit Juice Market
Beverages
Plant Based Protein Beverages Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Kvass Market
Beverages
Morocco Bottled Water Market
Beverages
Collagen Drinks Market
Beverages
Sparkling Soda Market
Beverages
Drinking Water Market
Beverages
Gluten Free Beverages Market
Beverages
Ready to Drink Premixes Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Sparkling Juice Drinks Market
Beverages
Crystal Boba Market
Beverages
Global Beverage Emulsion Market
Beverages
GCC Coconut Water Market
Beverages
United States Sports and Energy Drinks Market