
 Direct Piping Water Dispenser Market | 2026-2036
Direct Piping Water Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Piping Water Dispenser Market Insights
The gap between premium stainless-steel built-in models and basic plastic countertop units is expanding across procurement channels. Waterlogic Holdings Ltd. leverages its commercial leasing infrastructure to dominate office deployments in Western Europe. Culligan International Company anchors its position through captive service networks that handle filter replacement and sanitation compliance. Midea Group Co. Ltd. competes on manufacturing scale, shipping compressor-based units from Guangdong factories to Southeast Asian distributors.
A direct piping water dispenser connects to municipal plumbing through activated carbon, reverse osmosis, or ultrafiltration stages, delivering chilled or heated potable water without bottle storage. Wall-mounted dispensers lead in commercial offices where floor space commands premium rents, while built-in units capture the fastest growth in new construction across premium residential towers. Compressor-based cooling still occupies the majority of value pools due to higher unit economics, though thermoelectric variants are gaining share in educational institutions where noise thresholds matter.
NSF International standards and the EU Drinking Water Directive shape product certification requirements, with CE marking mandatory for European market access and FDA oversight governing materials in US-bound units. China's GB standards for water-contact materials and South Korea's KC certification for electrical safety create layered compliance burdens for multinational suppliers. Stakeholders must weigh filter replacement revenue streams against regulatory testing costs when selecting geographic expansion priorities.
Market Dynamics
Municipal infrastructure upgrades across East Asian metropolitan cores are compressing installation timelines for plumbed dispensing systems, while certification layering between electrical safety and water-contact material standards fragments supplier compliance roadmaps.
Growth Catalysts
- Commercial real estate densification:Seoul and Singapore office landlords are mandating bottle-free hydration infrastructure in Class-A lease specifications to reduce floor-space waste from storage rooms.
- GB standards harmonization:China's unified testing protocols for activated carbon and reverse osmosis membranes are accelerating domestic manufacturer scale-up in Guangdong province.
- MFDS quality tightening:South Korea's point-of-use device standards are forcing filtration upgrades that favor plumbed systems with integrated monitoring over standalone countertop units.
Market Restraints
- Stainless steel input volatility:Premium built-in model margins compress when nickel and chromium prices spike, forcing manufacturers to absorb costs or downgrade specifications.
- Filter supply concentration:Activated carbon block production clusters in Zhejiang and Jiangsu provinces, creating single-source risk for European and Southeast Asian assemblers.
- RO membrane import dependency:Thin-film composite production remains concentrated with US and Japanese specialty chemical suppliers, exposing non-integrated brands to tariff and shipping disruptions.
Strategic Opportunities
- Vietnam manufacturing migration:Labor cost arbitrage and EU-Vietnam free trade agreement benefits are drawing compressor assembly lines from Dongguan to Hai Phong industrial zones.
- Educational institution noise thresholds:Thermoelectric cooling modules are penetrating university and school procurement channels where compressor hum disrupts classroom environments.
- EU F-Gas Regulation phase-down:The hydrofluorocarbon quota system is accelerating R-290 propane adoption in compressor-based chillers, favoring suppliers with提前 certified hydrocarbon architectures.
Industry Challenges
- Multi-jurisdiction certification lag:Simultaneous KC electrical, GB material, and CE machinery compliance requires 14-18 month validation cycles that delay product launches.
- Legacy plumbing retrofit complexity:Pre-2000 commercial buildings in Seoul and Shanghai lack under-sink drainage and power access, requiring costly core drilling and permit amendments.
- Filter replacement revenue capture:Third-party compatible cartridge suppliers erode aftermarket income streams through cross-compatible form factors that bypass proprietary lock-in designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Piping Water Dispenser Market |
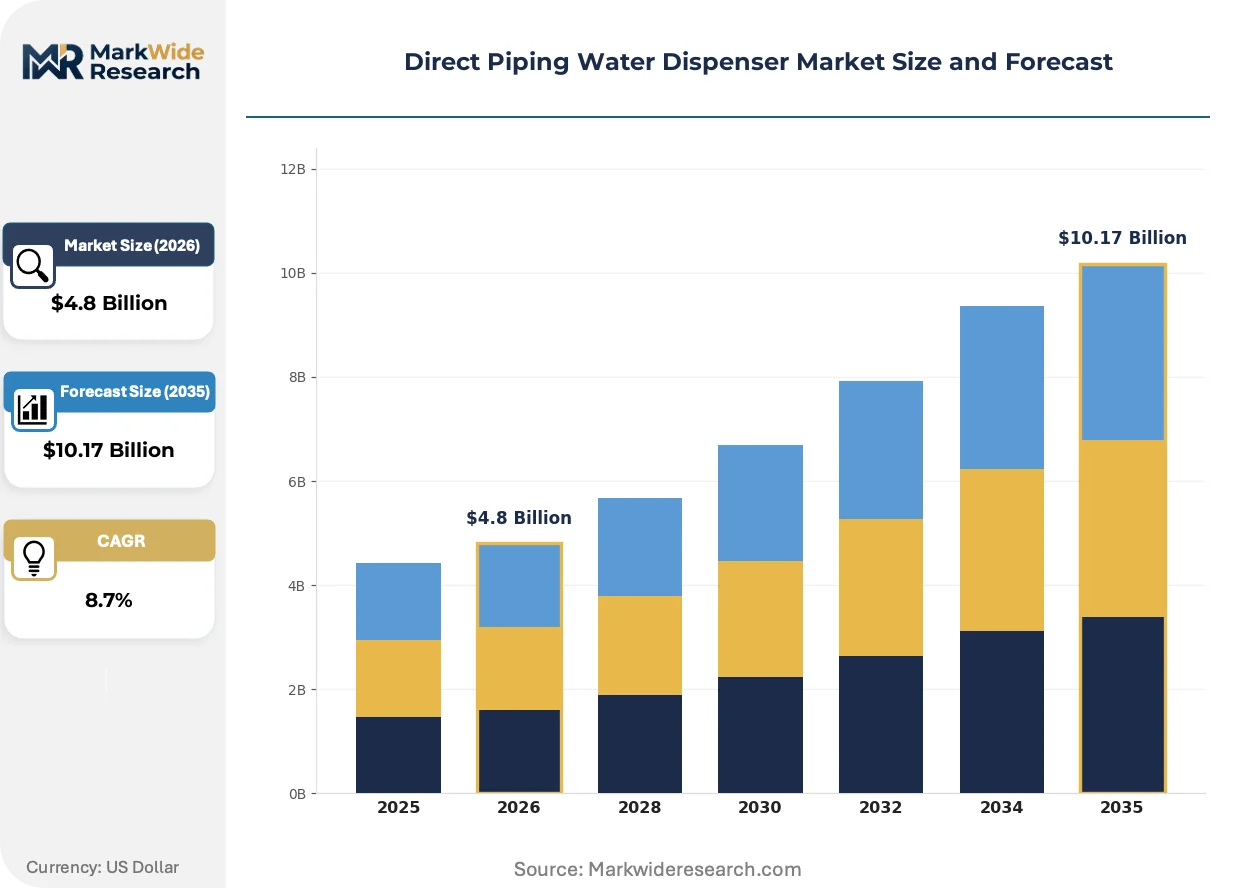
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Dispenser, Wall-Mounted Dispenser, Built-In Dispenser, Outdoor Dispenser End User: Residential Users, Commercial Offices, Educational Institutions, Healthcare Facilities Installation Type: Permanent Installation, Temporary Setup, Professional Installation, DIY Installation Cooling Technology: Compressor-Based Cooling, Thermoelectric Cooling, Air-Cooled System, Ice-Making Technology |
| Companies Covered | Waterlogic Holdings Ltd., Culligan International Company, Primo Water Corporation, Whirlpool Corporation, Honeywell International Inc., Midea Group Co. Ltd., A. O. Smith Corporation, Clover Co. Ltd., Brio Water Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Piping Water Dispenser Market Trends and Innovations
Filtration monitoring systems and refrigerant chemistry are converging to redefine equipment lifecycle economics, while procurement authority migrates from facilities managers to sustainability officers with distinct vendor evaluation criteria.
Ultraviolet-C LED sterilization modules are automating microbial compliance verification in high-traffic commercial installations. Airport lounges and hospital cafeterias in Singapore and Dubai are specifying these self-diagnosing units to eliminate manual sanitation logging. The technology is automating compliance documentation that previously required quarterly third-party water testing, compressing operating cost structures for multi-site operators.
The EU Drinking Water Directive's 2024 revision tightens point-of-use device material migration limits, mandating expanded testing for bisphenol-A and phthalate leaching from plastic reservoirs. German and French certification bodies are extending validation timelines by 30-40% as they implement new analytical protocols. Built-in stainless-steel tank configurations are capturing specification share from plastic-reservoir countertop models as specifiers preempt compliance risk.
Leasing structures with bundled filter service are displacing capital purchase models in Western European office markets. Copenhagen and Amsterdam facility managers now specify per-liter pricing contracts that transfer maintenance liability to equipment providers. This arrangement concentrates volume with vendors possessing captive technician networks, squeezing distributor-dependent competitors from premium commercial tenders.
Direct Piping Water Dispenser Market Segmentation
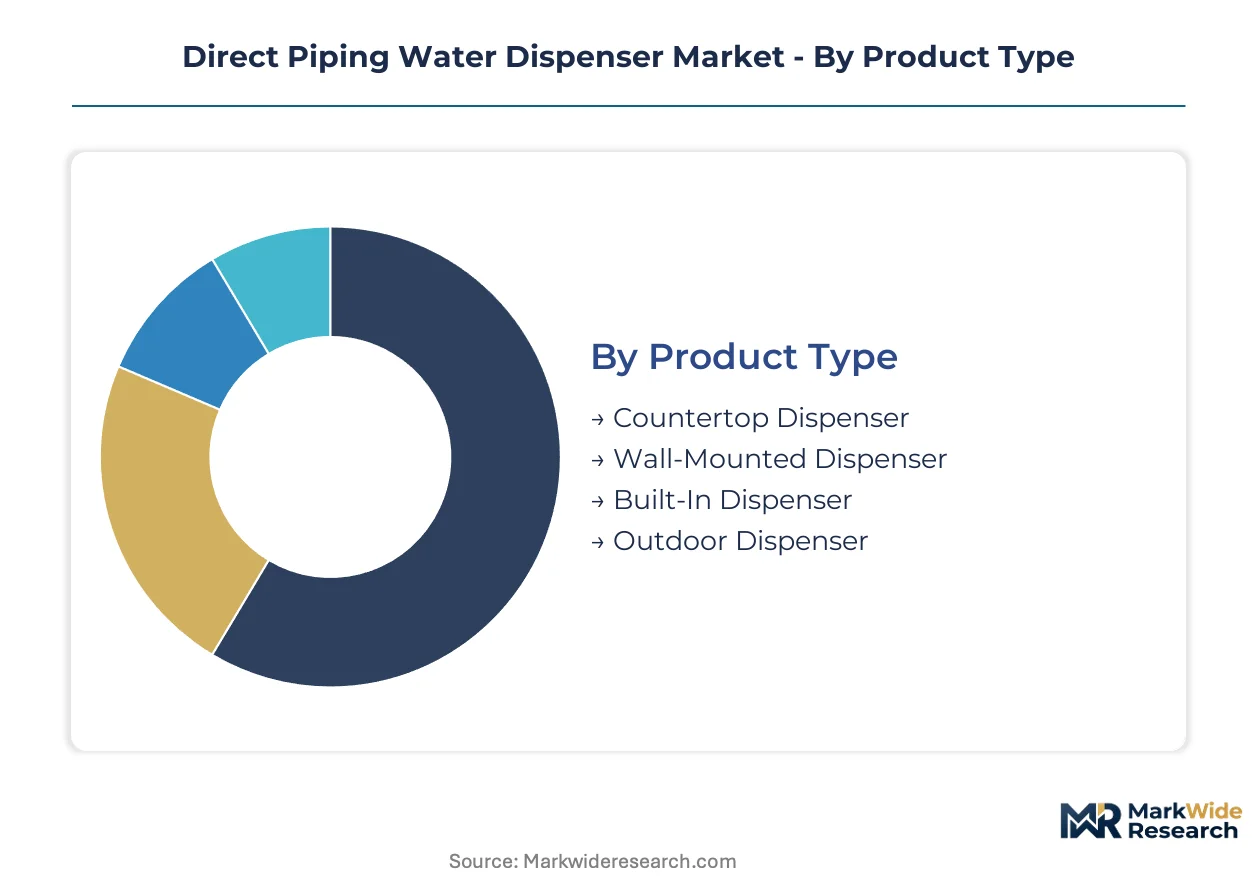
Segmentation in the direct piping water dispenser market reveals distinct procurement logics across installation contexts, cooling architectures, and user environments. Each dimension carries specific certification burdens and margin structures that shape supplier positioning.
Product Type:
Volume concentrates in basic countertop units, while premium value pools sit with built-in configurations for new construction.
- Countertop Dispenser:Plastic-reservoir units dominate residential procurement in China's tier-one cities and Southeast Asian apartment markets. Municipal water pressure compatibility and compact footprint drive selection for rental properties where permanent modification is restricted.
- Wall-Mounted Dispenser:Stainless-steel configurations lead commercial office specifications in Seoul and Singapore, where floor space premiums exceed USD 80 per square meter annually. Landlord lease mandates for bottle-free infrastructure accelerate replacement of legacy bottled units in Class-A towers.
- Built-In Dispenser:Integrated kitchen cabinetry units capture premium residential towers in Dubai and Riyadh, with GCC developers specifying these as standard amenities in luxury developments.
- Outdoor Dispenser:Weather-sealed variants serve hospitality pool decks and stadium concourses in subtropical climates, requiring IP65+ enclosures and UV-stabilized plastics.
Mature deployment sits with countertop dispensers. Newer deployment is concentrated in built-in dispensers.
End User:
Commercial offices generate recurring filter service revenue, while healthcare procurement prioritizes microbial compliance documentation.
- Residential Users:Individual household installations concentrate in Shanghai, Beijing, and Shenzhen high-rises with renovated plumbing infrastructure. Filter subscription models are displacing retail cartridge purchases as domestic brands deploy IoT-enabled reorder systems.
- Commercial Offices:Multi-tenant buildings in Amsterdam and Copenhagen specify per-liter leasing contracts that bundle equipment and maintenance. Copenhagen facility managers now mandate sustainability officer sign-off on hydration infrastructure selections.
- Educational Institutions:Thermoelectric cooling variants penetrate university procurement channels where compressor noise disrupts classroom environments. Seoul metropolitan school districts specify sub-40 decibel operation thresholds.
- Healthcare Facilities:UV-C LED sterilization modules automate compliance verification for hospital cafeterias and airport lounges in Singapore and Dubai, eliminating quarterly third-party water testing requirements.
Healthcare facilities deploy the most advanced filtration monitoring. Educational institutions are expanding most quickly as noise regulations tighten.
Installation Type:
Professional installation dominates commercial segments, while DIY channels serve cost-sensitive residential replacement cycles.
- Permanent Installation:Under-sink drainage and dedicated power circuits anchor commercial office deployments in Seoul and Shanghai new construction. Pre-2000 building retrofits require costly core drilling and permit amendments.
- Temporary Setup:Quick-connect variants serve event venues and construction site offices, with rental fleets operated by facility service providers in Western Europe.
- Professional Installation:Certified technician networks handle electrical safety compliance and pressure testing, with Waterlogic and Culligan leveraging captive service infrastructure to lock in multi-year contracts.
- DIY Installation:Push-fit plumbing connectors and pre-filtered faucet adapters expand mass-market penetration in China's e-commerce channels, though warranty terms often exclude self-installed units.
Professional installation anchors commercial revenue. DIY channels are gaining share fastest in residential e-commerce.
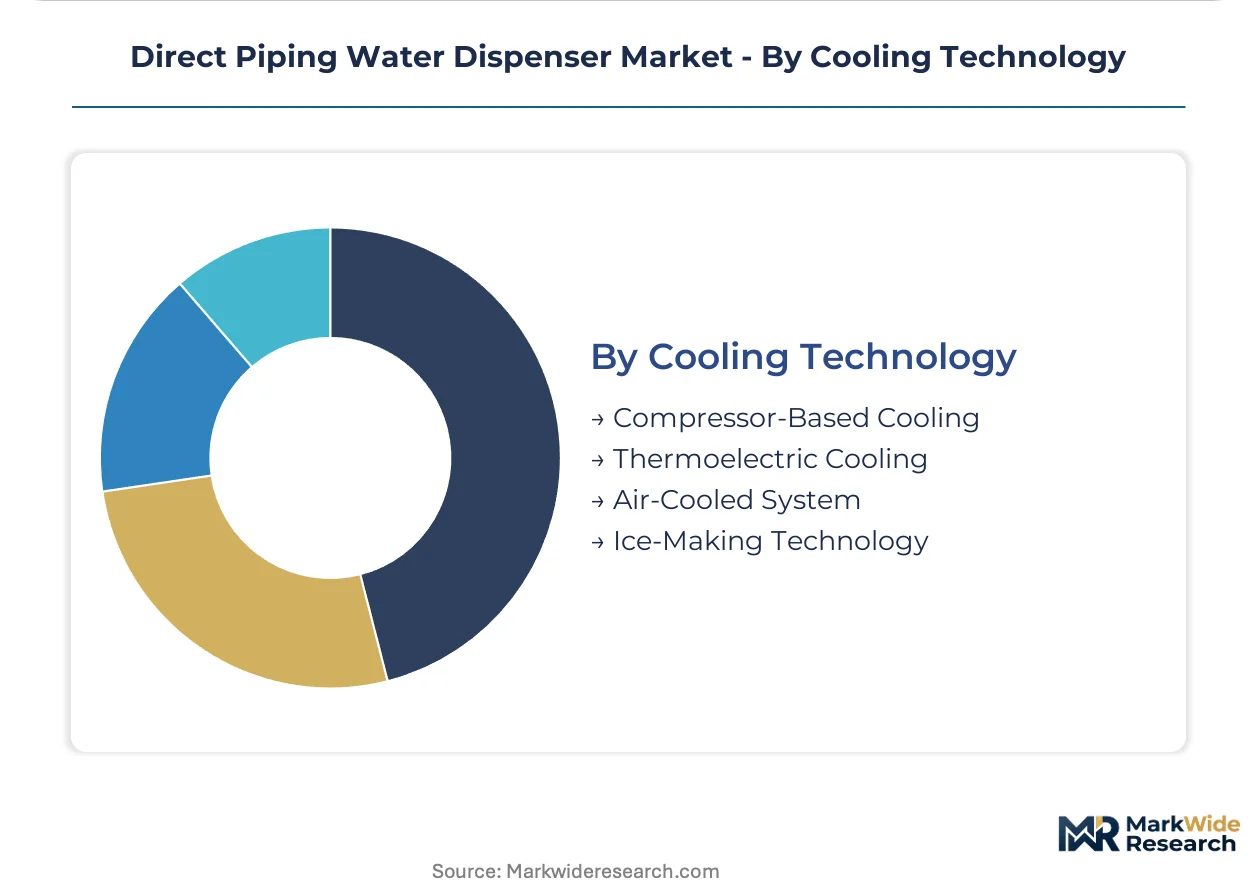
Cooling Technology:
Compressor-based systems retain value pool dominance, while thermoelectric architectures capture noise-sensitive niches.
- Compressor-Based Cooling:R-290 propane refrigerant adoption accelerates under EU F-Gas Regulation phase-down, favoring suppliers with提前 certified hydrocarbon architectures. Dongguan and Hai Phong assembly lines concentrate production for European export.
- Thermoelectric Cooling:Solid-state Peltier modules eliminate moving parts and compressor hum, penetrating university and school procurement where acoustic thresholds matter. Energy efficiency penalties limit deployment in high-usage commercial settings.
- Air-Cooled System:Passive convection designs serve low-traffic residential installations in temperate climates, avoiding refrigerant compliance entirely.
- Ice-Making Technology:Integrated cube production distinguishes premium built-in units for GCC hospitality and residential developments, with separate food-grade water circuits required.
Compressor-based cooling dominates installed base. Thermoelectric cooling is climbing the fastest as educational noise standards proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Class-A office towers are mandating bottle-free hydration infrastructure, compressing installation timelines for plumbed dispensing systems across East Asian metropolitan cores.
China
Shanghai, Beijing, and Shenzhen high-rises drive residential installations where renovated plumbing infrastructure supports direct-connection appliances. GB standards harmonization for activated carbon and reverse osmosis membranes accelerates domestic manufacturer scale-up in Guangdong province. Dongguan assembly lines ship compressor-based units to Southeast Asian distributors.
South Korea
Seoul metropolitan school districts specify sub-40 decibel operation thresholds, favoring thermoelectric cooling variants in educational procurement. MFDS quality tightening for point-of-use devices forces filtration upgrades that favor plumbed systems with integrated monitoring. Busan-Ulsan industrial corridors supply components for domestic assembly.
Singapore
Commercial office landlords mandate bottle-free hydration infrastructure in Class-A lease specifications to reduce floor-space waste from storage rooms. Airport lounges specify UV-C LED sterilization modules to eliminate quarterly third-party water testing. The city-state's position as a regional logistics hub channels European and Japanese component imports.
Germany
Copenhagen and Amsterdam facility managers specify per-liter leasing contracts that bundle equipment and maintenance, transferring liability to providers. EU F-Gas Regulation phase-down accelerates R-290 propane adoption in compressor-based chillers. German certification bodies extend validation timelines by 30-40% under tightened EU Drinking Water Directive material migration limits.
United Arab Emirates
Dubai and Riyadh luxury residential towers specify built-in dispensers as standard amenities in new construction developments. Hospital cafeterias automate microbial compliance verification through self-diagnosing UV-C LED units. GCC developers source premium stainless-steel configurations from European and East Asian suppliers.
Direct Piping Water Dispenser Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the direct piping water dispenser market. The vendor base stratifies between integrated manufacturers with captive filter production and assemblers dependent on third-party component sourcing. Three archetypes dominate: leasing infrastructure operators, manufacturing scale players, and service-network anchors. Consolidation pressure intensifies through M&A activity among regional distributors and backward integration into membrane production.
Within the leasing infrastructure tier, Waterlogic Holdings Ltd. and Culligan International Company exemplify asset-light models that prioritize captive technician networks over manufacturing ownership. Midea Group Co. Ltd. occupies a position among scale-driven fabricators with Guangdong-based production. These three anchors illustrate divergent strategic paths: service density, manufacturing throughput, and vertical control over aftermarket revenue streams.
| Leading Market Players |
|---|
| Waterlogic Holdings Ltd. |
| Culligan International Company |
| Primo Water Corporation |
| Whirlpool Corporation |
| Honeywell International Inc. |
| Midea Group Co. Ltd. |
| A. O. Smith Corporation |
| Clover Co. Ltd. |
| Brio Water Technology Inc. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between NSF/CE-marked premium stainless-steel units and basic plastic countertop alternatives manifests in both pricing power and supply chain configuration. Manufacturers serving Seoul Class-A office towers command filter-service bundling premiums, while Guangdong assemblers compete on volume throughput to Southeast Asian distributors.
Pricing Analysis
Per-liter throughput pricing anchors commercial leasing contracts in Copenhagen and Amsterdam, transferring maintenance liability to equipment providers. Price differentiation rests on certification tier (CE marking versus basic compliance) and captive technician network density. Cost compression in plastic countertop segments intensifies as domestic Chinese brands deploy IoT-enabled reorder systems. Residential DIY channels exhibit highest price sensitivity; healthcare facilities with microbial compliance mandates show lowest.
Supply Chain Analysis
Multi-jurisdiction certification gating fragments supplier compliance roadmaps across KC electrical, GB material, and CE machinery standards. Component sourcing concentrates in China, South Korea, and Japan, with thin-film composite membranes drawing from US and Japanese specialty chemical suppliers. Activated carbon block production clusters in Zhejiang and Jiangsu provinces create single-source vulnerability for European assemblers. Distribution runs through captive technician networks for commercial leasing operators and e-commerce platforms for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where filter replacement revenue streams and membrane production control determine long-term margin sustainability. Players are pursuing backward integration into RO membrane manufacturing to reduce import dependency.
For Market Incumbents: Cement multi-year leasing contracts through captive technician density in Western European commercial corridors. Invest in R-290 propane refrigerant certification ahead of EU F-Gas quota phase-down. Third-party compatible cartridge suppliers threaten aftermarket lock-in designs. For New Entrants and Emerging Players: Enter via thermoelectric cooling architectures for educational procurement channels in Seoul and Singapore where sub-40 decibel thresholds displace compressor units. Vietnam manufacturing migration offers labor cost arbitrage under EU-Vietnam free trade benefits. Target quick-connect rental fleet operators for event venue temporary setups. For Investors and Strategic Acquirers: Re-rating potential sits with integrated manufacturers possessing captive filter production given GB standards harmonization accelerating Guangdong scale-up. Long-term viability favors suppliers with certified hydrocarbon architectures and UV-C LED sterilization modules. Watch MFDS quality tightening enforcement as inflection indicator for plumbed system displacement of countertop units.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Production | Reduces thin-film composite import dependency from US and Japanese suppliers. |
| R-290 Propane Refrigerant Certification | Secures EU market access ahead of F-Gas Regulation hydrofluorocarbon quota phase-down. |
| UV-C LED Sterilization Module Deployment | Automates microbial compliance for Singapore airport lounges and Dubai hospital cafeterias. |
| Captive Technician Network Expansion | Locks in multi-year per-liter leasing contracts with Copenhagen and Amsterdam facility managers. |
| Vietnam Manufacturing Migration | Captures EU-Vietnam free trade agreement benefits for compressor assembly relocation from Dongguan. |
Research Methodology
Trade databases, regulatory filing repositories, and equipment certification registries formed the secondary backbone, supplemented by customs records and commercial real estate lease specification documents. Primary fieldwork encompassed facilities managers, aftermarket service technicians, procurement officers at educational institutions, and filtration component distributors. Bottom-up unit shipment analysis triangulated against top-down spending estimates across installation type and cooling technology segments.
Historical trendline analysis established baseline penetration rates for plumbed versus bottled systems across metropolitan cores. The projection framework modeled installation type, end-user environment, product configuration, and regional regulatory cluster dimensions. CAGRs derived from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated MFDS enforcement timelines and EU F-Gas quota phase-down schedules.
Revisions become necessary when municipal infrastructure upgrade timelines accelerate or stainless steel input volatility exceeds historical bands. Forecasts reflect assumptions around certification validation cycle durations and filter replacement frequency adherence. A model refresh is warranted upon material change in thin-film composite membrane tariff exposure or GB standards implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Packaged Cactus Water Market
Beverages
Double Valve Moka Pots Market
Beverages
Carbonate Drink Maker Market
Beverages
Adaptogenic Beverages Market
Beverages
India Sports Drinks Market
Beverages
Italy Bottled Water Market
Beverages
South America Mate Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Morocco Bottled Water Market
Beverages
Packaged Milkshake Market
Beverages
Canned Beverages Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Fruit Beverages Market
Beverages
Ginger Beer Market
Beverages
Middle East Energy Drinks Market