
 Yerba Mate Market | 2026-2036
Yerba Mate Market Size, Share, and Industry Trends Forecast 2026-2036
Yerba Mate Market Intelligence
Argentine yerba mate cooperatives is repositioning processing capacity toward organic certification to capture premium export demand. Guayaki Sustainable Rainforest Products Inc. leverages regenerative agriculture narratives to anchor shelf space in North American natural channel retailers. Establecimiento Las Marías dominates domestic Argentine distribution through vertically controlled milling and aging infrastructure. Molinos Río de la Plata SA extends brand recognition across Mercosur borders via co-manufacturing partnerships.
Yerba mate comprises dried leaves and stems of Ilex paraguariensis, typically containing 1-2% caffeine by dry weight and processed through sapeco thermal shock and secado drying stages to develop characteristic flavor biochemistry. The botanical serves as both a traditional stimulant beverage and an industrial input for functional drink formulations. Ready-to-drink formats now command the fastest expansion trajectory within product type segmentation, as convenience positioning offsets per-unit margin compression. Organic certification within the same dimension captures price premiums of roughly 40-60% above conventional grades, though supply constraints limit volume scaling. Distribution through specialty stores and health shops concentrates margin pools, while supermarket penetration drives awareness among trial-stage consumers.
Argentina's National Service for Agri-Food Health and Quality and Brazil's Ministry of Agriculture enforce divergent maximum moisture and foreign matter standards that fragment cross-border product specifications. The European Union's novel food classification for non-traditional extracts continues to gate certain concentrated formats from import channels. Stakeholders must monitor evolving pesticide maximum residue limits across destination markets and calibrate sourcing strategies between certified organic and conventional supply tiers.
Market Dynamics
Certification-driven bifurcation is fragmenting the yerba mate supply base into parallel organic and conventional tiers, forcing processors to duplicate aging infrastructure and quality systems while export buyers consolidate procurement around certified volumes.
Growth Catalysts
- EU Green Deal agricultural transition incentives:European import demand for regenerative-sourced botanicals is accelerating organic conversion rates among Argentine cooperatives seeking premium channel access.
- Functional beverage formulation expansion:North American energy drink manufacturers are incorporating yerba mate extracts as natural caffeine alternatives to synthetic anhydrous caffeine in clean-label portfolios.
- Brazil's southern states consumption base:Traditional chimarrão culture in Rio Grande do Sul and Santa Catarina anchors per-capita volume that subsidizes export-grade production scaling.
Market Restraints
- Input cost volatility in organic certification:Three-year conversion periods and inspector scarcity inflate organic yerba mate premiums beyond price elasticity thresholds for mass-market penetration.
- Supply concentration in Misiones province:Argentina's northeastern growing belt concentrates over seventy percent of exportable organic supply, exposing buyers to climate and labor disruption correlations.
- Technical limitation in extract standardization:Batch-to-batch variation in methylxanthine profiles complicates functional beverage formulation consistency and dosage labeling compliance.
Strategic Opportunities
- Underpenetrated United States specialty coffee channel:Third-wave cafés in Pacific Coast metropolitan clusters represent untapped on-premise trial conversion for traditional preparation formats.
- Regulatory tailwind from ANVISA functional food pathways:Brazil's expanded health claim authorization for botanical stimulants enables ready-to-drink positioning beyond conventional beverage categories.
- Technology convergence of flash pasteurization and aseptic cold filling:Extended shelf-life capabilities without thermal degradation are unlocking convenience retail distribution for unpreserved organic formulations.
Industry Challenges
- Specialized agronomic skill scarcity:Organic yerba mate cultivation requires integrated pest management expertise that outpaces regional agricultural extension capacity in Argentina's Misiones and Corrientes provinces.
- Certification timeline compression:Simultaneous pursuit of USDA Organic, EU Organic, and Fairtrade certifications creates audit scheduling conflicts that delay export readiness by six to eighteen months.
- Legacy drying infrastructure incompatibility:Traditional secado systems designed for volume throughput cannot achieve the moisture precision required for extract-grade raw material specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yerba Mate Market |
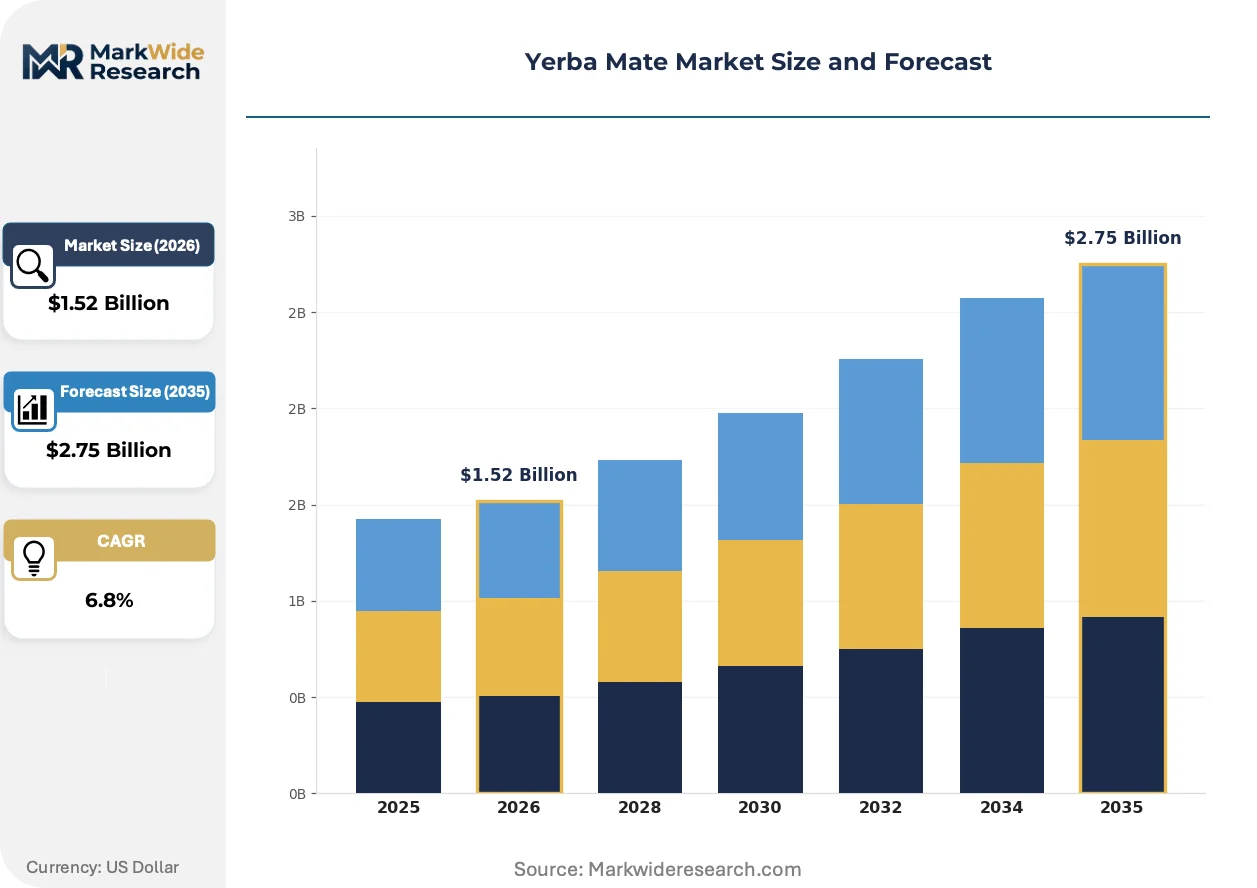
| Market Size in 2026 | $1.52 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Tea Bags, Instant Powder, Ready-to-Drink, Organic Flavor Profile: Traditional, Citrus, Mint, Herbal, Floral, Spiced Consumption Occasion: Morning Beverage, Afternoon Refreshment, Social Gatherings, Wellness Routine, Workout Supplement Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Food Service, Health Shops |
| Companies Covered | HREÑUK S.A., Guayaki Sustainable Rainforest Products Inc., Yerba Madre, Yuyo Drinks Ltd, HerboFlora, Molinos Río de la Plata SA, La Cachuera SA, Wisdom Natural Brands, Establecimiento Las Marías, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yerba Mate Market Strategic Shifts & Innovations
Processing technology convergence and regulatory classification evolution are restructuring competitive advantage around extract standardization capabilities and certification stacking efficiency rather than raw volume throughput.
Flash chromatography purification is unifying previously fragmented alkaloid and polyphenol isolation workflows into continuous processing lines. Functional ingredient manufacturers in Germany and the United States are adopting these systems at pilot scale to secure pharmaceutical-grade mate extracts. The technology is unifying quality benchmarks across cosmetic, nutraceutical, and beverage applications that previously operated under divergent purity specifications.
Argentina's National Service for Agri-Food Health and Quality revised phytosanitary export protocols now mandate lot-level DNA authentication for Ilex paraguariensis origin verification. This industrial consequence forces processors to segregate supply chains by genetic cultivar and geographic sub-zone from harvest through export documentation. Smallholder cooperatives in Misiones province face the most acute compliance burden as they retrofit traceability systems without centralized milling infrastructure.
Specialty retailers are consolidating shelf space allocation around multi-certification SKUs that stack organic, fair trade, and regenerative agriculture claims in single product presentations. This preference compression disadvantages conventional-grade producers while rewarding processors who invested early in integrated certification management systems. The behavioral shift is most visible in North American natural channel distribution where buyer concentration among three national distributors amplifies certification gatekeeping effects.
Yerba Mate Market Segmentation
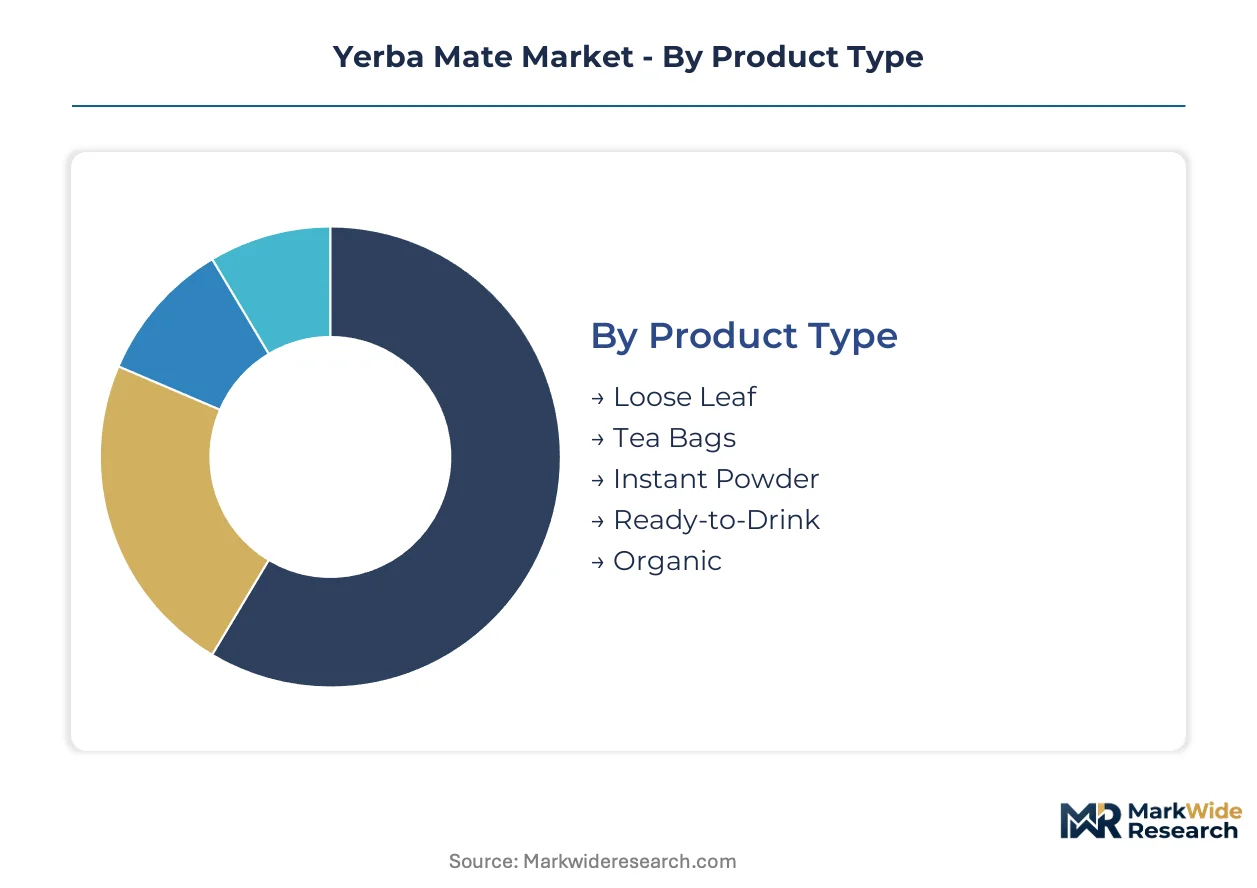
Yerba mate's commercial structure fragments across preparation format, sensory positioning, usage context, and channel access. Each dimension carries distinct margin profiles and certification requirements that reshape procurement priorities for processors and retailers.
Product Type:
Customization intensity spans from commodity bulk formats to precision-engineered extract grades requiring specialized drying protocols.
- Loose Leaf:Traditional dried leaf and stem cuts processed through sapeco thermal shock and secado aging stages. Argentine cooperatives in Misiones province anchor supply, with organic conversion rates accelerating under EU Green Deal import incentives.
- Ready-to-Drink:Aseptically filled beverages leveraging flash pasteurization to preserve methylxanthine stability without preservatives. North American functional beverage manufacturers are driving formulation partnerships that displace synthetic caffeine alternatives.
- Tea Bags:Standardized cut sizes for single-serve convenience, with filter material compatibility constraining leaf particle geometry.
- Instant Powder:Spray-dried or freeze-dried extracts targeting solubility performance in cold-water applications.
- Organic:Certified supply requiring three-year conversion periods and segregated processing infrastructure, commanding substantial premiums in specialty retail channels.
Most installed capacity flows through Loose Leaf. Expansion is steepest in Ready-to-Drink.
Flavor Profile:
Regional taste formation in Brazil's southern states contrasts with flavor innovation pipelines serving export trial conversion.
- Traditional:Unadulterated Ilex paraguariensis character developed through controlled aging of smoke-dried leaf. Rio Grande do Sul's chimarrão culture perpetuates per-capita consumption density that subsidizes export-grade production economics.
- Citrus:Lemon, grapefruit, and bergamot oil infusions targeting North American palate adaptation and summer consumption seasonality.
- Mint:Peppermint and spearmint blends positioned for digestive wellness claims in health shop distribution.
- Herbal:Botanical additions such as chamomile, lemongrass, or ginger extending functional positioning beyond stimulant categories.
- Floral:Rose, jasmine, and lavender infusions capturing premium shelf space in specialty coffee channel trial.
- Spiced:Cinnamon, clove, and cardamom formulations aligned with seasonal retail programming and warming consumption occasions.
Traditional formats absorb the majority of milling throughput. Citrus and mint variants are gaining share fastest in export markets.
Consumption Occasion:
Usage context determines packaging format, dosage communication, and channel placement strategy.
- Morning Beverage:Caffeine-forward positioning competing with coffee rituals, with Argentine and Brazilian households maintaining embedded preparation traditions.
- Afternoon Refreshment:Moderate-stimulation formats for workplace and educational settings, often in tea bag or ready-to-drink convenience packaging.
- Social Gatherings:Ceremonial gourd-and-bombilla preparation sustaining cultural practice in southern Brazil and Uruguay.
- Wellness Routine:Antioxidant and adaptogen claims driving integration into supplement-adjacent consumption patterns.
- Workout Supplement:Pre-training energy applications leveraging yerba mate's theobromine and theophylline profile for sustained release positioning.
Social and morning occasions dominate volume. Wellness and workout positioning are expanding most quickly in North American natural channel distribution.
Distribution Channel:
Channel selection constrains certification requirements, pricing architecture, and consumer education investment.
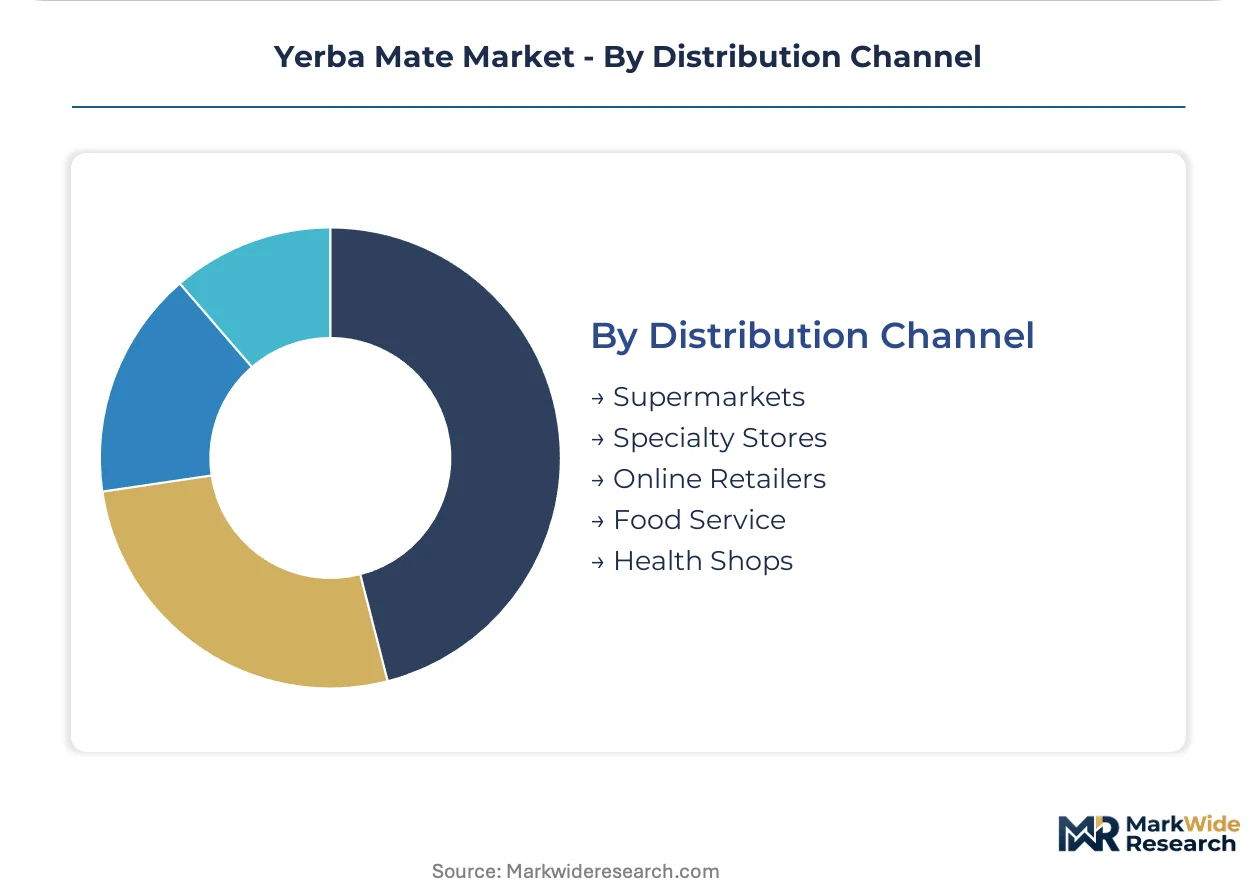
- Specialty Stores:Curated assortments emphasizing multi-certification SKUs stacking organic, fair trade, and regenerative claims. Buyer concentration among three national North American distributors amplifies certification gatekeeping effects.
- Supermarkets:Mass-market penetration driving awareness among trial-stage consumers, with conventional grades dominating price-competitive shelf sets.
- Online Retailers:Direct-to-consumer subscription models enabling origin storytelling and cultivar-specific merchandising.
- Food Service:Café and restaurant on-premise preparation requiring barista training investment and equipment compatibility.
- Health Shops:Margin-concentrated positioning for organic and functional formulations with pharmacist or nutritionist endorsement.
Specialty stores and supermarkets command the largest revenue pools. Online and food service channels are climbing the fastest as trial conversion infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping yerba mate production geography as processors migrate toward jurisdictions with streamlined phytosanitary protocols and organic certification reciprocity. Argentina's updated export standards and Brazil's ANVISA functional food pathways are creating divergent compliance cost structures that influence investment location decisions.
Argentina
Domestic consumption density in Buenos Aires and Córdoba provinces sustains volume throughput that subsidizes export-grade milling. The National Service for Agri-Food Health and Quality mandates lot-level DNA authentication for origin verification, forcing Misiones province cooperatives to retrofit traceability systems. Northeastern growing belts around Posadas and Oberá concentrate over seventy percent of certified organic supply.
Brazil
Rio Grande do Sul's chimarrão culture perpetuates per-capita consumption rates that anchor regional production economics. ANVISA's expanded health claim authorization for botanical stimulants enables ready-to-drink positioning beyond conventional beverage categories. Porto Alegre metropolitan clusters represent emerging formulation partnerships with North American functional beverage manufacturers.
United States
Third-wave café penetration in Pacific Coast metropolitan areas drives trial conversion for traditional preparation formats. FDA enforcement of novel food classifications gates concentrated extract imports from non-traditional suppliers. Los Angeles and San Francisco distribution hubs concentrate specialty retail buyer consolidation among national natural channel distributors.
Germany
EU Green Deal agricultural transition incentives accelerate import demand for regenerative-sourced botanicals. EFSA regulatory frameworks govern maximum residue limits for pesticide contaminants in herbal preparations. Hamburg and Bremen port infrastructure handles the majority of South American organic yerba mate transshipment into continental European markets.
Uruguay
Montevideo serves as a secondary export processing node with streamlined Mercosur transit documentation. The country's national agricultural regulator enforces moisture and foreign matter standards that align with Argentine protocols. Northern departments along the Brazilian border concentrate smallholder production integrated into cross-border cooperative milling arrangements.
Yerba Mate Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue certification-stacked premium positioning and functional extract supply contracts. Market structure exhibits moderate consolidation around vertically integrated Argentine and Brazilian processors with captive aging infrastructure. Three archetypes dominate: heritage cooperatives with organic conversion pipelines, multinational beverage conglomerates leveraging co-manufacturing partnerships, and North American mission-driven brands anchored in regenerative agriculture narratives. Capacity expansion and strategic co-manufacturing agreements constitute the dominant competitive moves as participants seek to bridge supply gaps between conventional and certified organic tiers.
Within the heritage cooperative archetype, Establecimiento Las Marías and Molinos Río de la Plata SA exemplify vertically integrated processors with domestic distribution control extending across Mercosur borders. Guayaki Sustainable Rainforest Products Inc. occupies a position representing North American mission-driven entrants leveraging regenerative agriculture narratives for natural channel shelf space. These three entities collectively illustrate the geographic and strategic bifurcation between Southern Cone production concentration and Northern Hemisphere brand building.
| Leading Market Players |
|---|
| HREÑUK S.A. |
| Guayaki Sustainable Rainforest Products Inc. |
| Yerba Madre |
| Yuyo Drinks Ltd |
| HerboFlora |
| Molinos Río de la Plata SA |
| La Cachuera SA |
| Wisdom Natural Brands |
| Establecimiento Las Marías |
| Others |
Cost & Logistics Intelligence
Specialized agronomic labor scarcity in Argentina's Misiones province amplifies wage differentials between conventional and certified organic cultivation tiers, compressing margins on standard grades while inflating premiums for multi-certification supply by 40-60%.
Pricing Analysis
Distributor margin stacking in North American natural channels absorbs substantial value before retail placement, compressing processor returns unless direct-to-specialty relationships bypass intermediary layers. Three-tier pricing structure across premium organic, standard conventional, and economy bulk grades reflects certification depth and aging infrastructure investment. Price differentiation hinges on organic certification status and Fairtrade compliance, with specialty retailers least price-sensitive due to mission-aligned consumer bases. Cost compression in conventional loose-leaf tiers is intensifying as Argentine cooperatives divert milling capacity toward certified export demand.
Supply Chain Analysis
Single-source vulnerability sits with Argentina's Misiones province, where over seventy percent of exportable organic supply concentrates in a narrow northeastern growing belt exposed to climate and labor disruption correlations. Raw material sourcing draws from Ilex paraguariensis cultivars in Argentina, Brazil's Rio Grande do Sul, and Paraguay's eastern departments, with methylxanthine profile variation complicating extract-grade standardization. Supply chain risk centers on regulatory restriction divergence between Argentina's SENASA and Brazil's Ministry of Agriculture moisture and foreign matter standards. Distribution runs through vertically controlled milling infrastructure in Posadas and Oberá before transshipment via Hamburg and Bremen to European buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Argentina's streamlined SENASA phytosanitary protocols and Brazil's ANVISA functional food authorization pathways, with regulatory compliance cost differentials reshaping investment location decisions.
For Market Incumbents: To counter certification-stacking demands from North American natural channel distributors, Establecimiento Las Marías and Molinos Río de la Plata SA should deepen backward integration into captive organic cultivation in Corrientes province while retrofitting legacy secado systems for extract-grade moisture precision. Channel control through direct specialty retailer relationships offers margin defense against intermediary consolidation. For New Entrants and Emerging Players: ANVISA's expanded health claim authorization for botanical stimulants in Brazil opens a window for ready-to-drink formulation partnerships targeting workout supplement positioning in North American functional beverage channels. White-space concentration exists in Pacific Coast third-wave café trial conversion for traditional gourd preparation formats, with subscription direct-to-consumer models enabling origin storytelling that bypasses distributor gatekeeping. For Investors and Strategic Acquirers: Functional beverage conglomerates seeking natural caffeine alternatives are the most active acquirer in this space, with mid-tier Argentine cooperatives holding organic conversion pipelines representing prime targets. Long-term viability over a five-to-ten-year horizon rests on extract standardization capabilities rather than raw volume throughput. The signal to watch is flash chromatography adoption rates among German and United States ingredient manufacturers, indicating pharmaceutical-grade mate extract demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Conversion | Captures EU Green Deal import incentives and 40-60% price premiums in specialty channels. |
| Flash Pasteurization Technology Adoption | Unlocks convenience retail distribution for unpreserved organic ready-to-drink formulations. |
| Extract Standardization Investment | Resolves batch-to-batch methylxanthine variation that complicates functional beverage compliance. |
| Direct-to-Specialty Channel Development | Bypasses three-distributor concentration in North American natural channel gatekeeping. |
| Regenerative Agriculture Repositioning | Secures shelf space through Guayaki-style narrative differentiation in mission-aligned retail. |
Research Approach
Bottom-up consumption occasion modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with Argentine cooperative managers, Brazilian chimarrão culture preservation associations, North American natural channel buyers, and German functional ingredient formulators with secondary validation from SENASA export documentation, ANVISA regulatory filings, and EU Green Deal agricultural transition incentive disclosures. Customs records from Hamburg and Bremen port authorities, alongside EFSA maximum residue limit enforcement data, anchor supply-side triangulation.
Input-output matrices map Ilex paraguariensis cultivation area, yield assumptions, and processing capacity utilization against consumption volume by preparation format across the analysis window. Segmentation dimensions span product type, flavor profile, consumption occasion, and distribution channel, with CAGRs derived from regression analysis of historic trade flows and elasticity-adjusted demand projections. Forecast inputs incorporate organic conversion timeline constraints and inspector availability bottlenecks specific to Argentine certification bodies.
Revisions become necessary when SENASA phytosanitary protocol amendments, ANVISA functional food pathway expansions, or EFSA novel food reclassifications materialize. Forecasts reflect documented assumptions about certification stacking efficiency and methylxanthine standardization technology diffusion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Europe Bottled Water Processing Market
Beverages
North America Sugar Free Energy Drinks Market
Beverages
North America Kombucha Market
Beverages
Chill Block Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market
Beverages
Caffeinated Beverage Market
Beverages
Premium Water Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Orange Juice Market
Beverages
Juice Concentrates Market
Beverages
Morocco Bottled Water Market
Beverages
Solid Beverages Market
Beverages
Popping Bobas Market
Beverages
Germany Probiotic Drinks Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
India Bottled Water Market