
 Organic Ice Cream Market | 2026-2036
Organic Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Ice Cream Market Analysis
Supermarket private-label programs is shifting toward organic frozen dessert placements as conventional ice cream aisles lose traffic to perimeter fresh departments. Ben & Jerry's leverages its parent company's sourcing infrastructure to secure certified organic dairy volumes at scale. Straus Family Creamery anchors Northern California supply through its vertically integrated organic dairy operation. Alden's Organic competes in the family-pack segment with conventional pricing parity on select stock-keeping units.
Organic ice cream denotes frozen dessert formulations produced from milk, cream, or plant-based alternatives bearing certified organic status for agricultural inputs and processing aids, with pasteurization and homogenization followed by batch or continuous freezing to achieve overrun levels between twenty and one hundred percent. Its primary commercial purpose centers on delivering indulgent frozen confectionery to consumers prioritizing reduced synthetic pesticide exposure and prohibited hormone or antibiotic residues in dairy supply chains. Non-dairy formulations now lead growth within product type segmentation as oat and coconut bases displace soy in clean-label positioning. Specialty stores capture disproportionate margin pools compared to supermarkets within distribution channel segmentation due to curated assortment and educated staff enabling premium price realization. Health-conscious consumers within consumer segment segmentation drive repeat purchase frequency through subscription and direct-to-home delivery adoption.
The USDA National Organic Program governs ingredient certification and labeling claims, while the FDA enforces frozen dessert identity standards and allergen declarations; state-level dairy inspection programs in Wisconsin and New York add supplementary processing facility oversight. The EU Organic Regulation cross-frames export market access for North American producers seeking shelf placement in German and French retail channels. Stakeholders must monitor evolving plant-based identity standard proposals and carbon labeling pilot programs that could reshape competitive positioning in premium frozen dessert aisles.
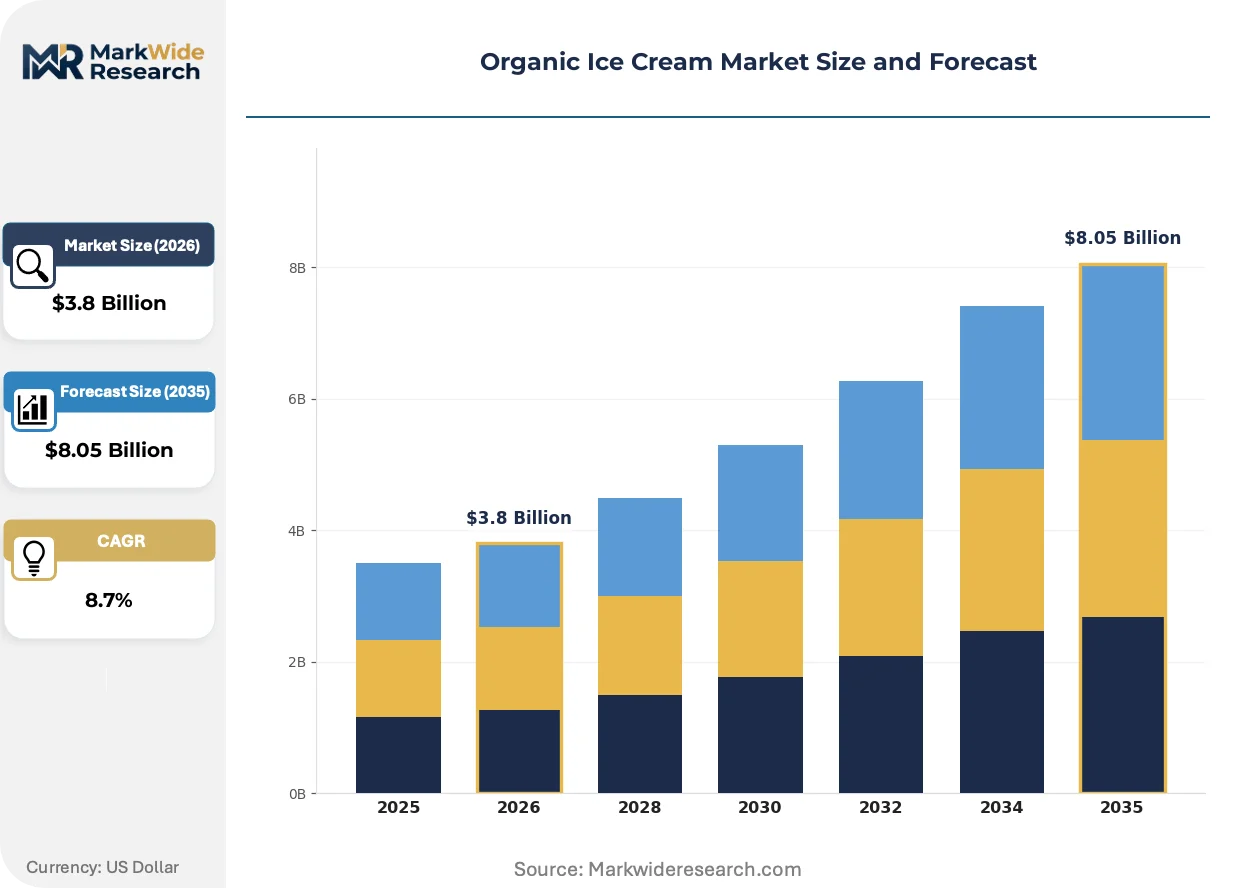
Market Dynamics
Clean-label certification requirements under the USDA National Organic Program are compressing ingredient sourcing flexibility while concentrating procurement power among vertically integrated dairy processors with captive organic milk supply.
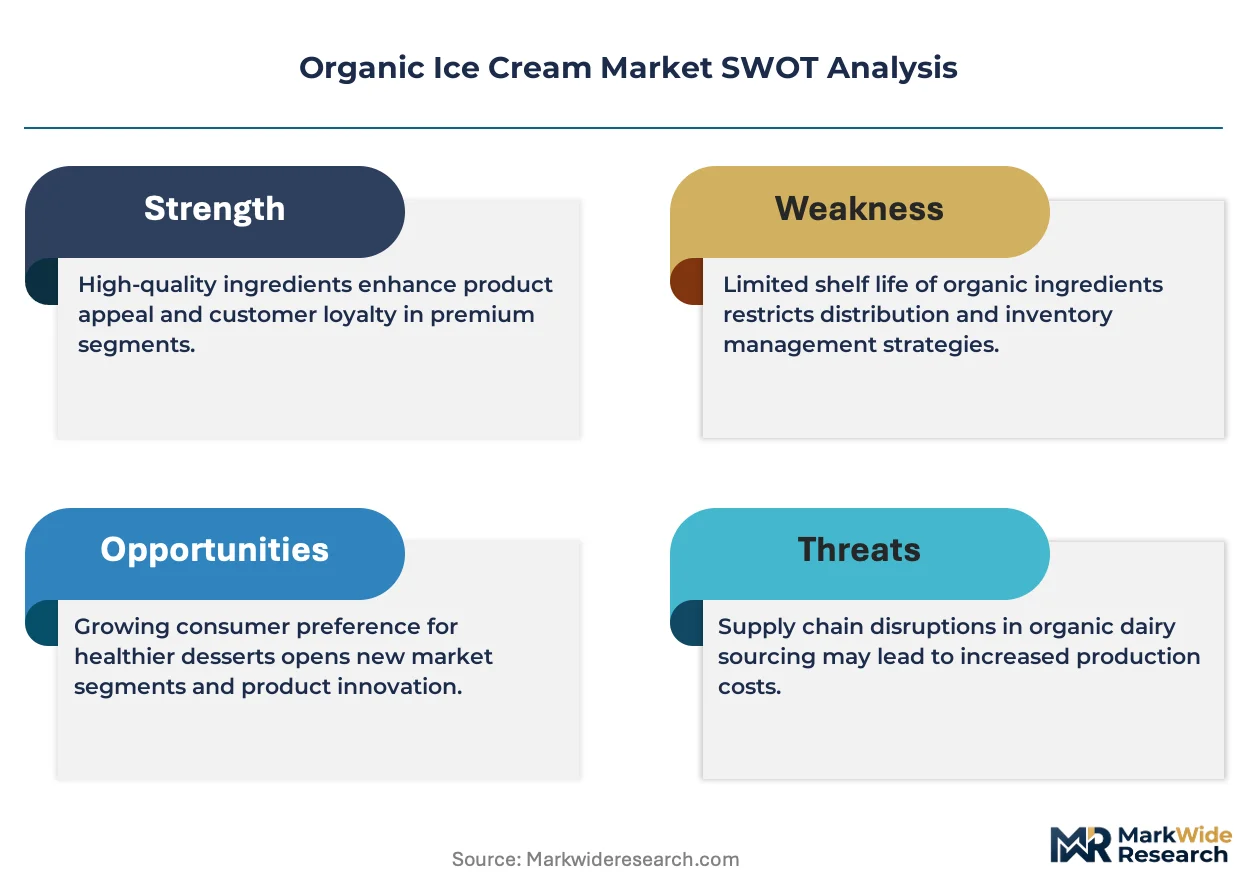
Growth Catalysts
- USDA National Organic Program enforcement:Tightened ingredient traceability mandates are disqualifying conventional suppliers and expanding addressable market for certified producers with compliant documentation systems.
- Oat base formulation advances:Improved fat and protein mimicry in plant-based alternatives is capturing lactose-intolerant consumers previously excluded from premium frozen dessert categories.
- California dairy belt concentration:Proximity of organic milk production to processing infrastructure reduces cold-chain logistics costs and enables fresher distribution to West Coast population centers.
Market Restraints
- Organic milk input cost volatility:Feed price fluctuations and herd transition timelines constrain margin predictability for processors dependent on spot market dairy purchases.
- Single-source supply concentration:Vermont's artisanal cluster and California's Central Valley dominate certified organic cream supply, creating geographic vulnerability to climate disruption.
- Clean-label technical ceiling:Prohibition of synthetic stabilizers limits shelf-life extension and complicates distribution to remote retail locations.
Strategic Opportunities
- Direct-to-home subscription channels:Refrigerated last-mile logistics investments by specialty retailers enable recurring revenue capture from health-conscious households.
- Carbon labeling pilot programs:Early adoption of farm-to-freezer emissions tracking differentiates premium positioning ahead of anticipated EU Green Deal alignment requirements.
- Specialty café channel expansion:Premium dessert shops with educated staff enable price realization unavailable in conventional supermarket environments.
Industry Challenges
- Organic certification timeline compression:Three-year land conversion requirements and documentation audits delay new supplier onboarding during demand surges.
- Legacy cold-chain infrastructure gaps:Temperature-controlled distribution networks optimized for conventional ice cream require retrofitting for organic product segregation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Ice Cream Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Non-Dairy, Gelato, Sorbet Ingredient Type: Milk-Based, Cream-Based, Sweetener, Flavoring Distribution Channel: Online, Supermarkets, Specialty Stores, Farmers Markets Consumer Segment: Health-Conscious Consumers, Families, Vegan Customers, Dessert Enthusiasts |
| Companies Covered | Ben & Jerry's, Häagen-Dazs, Three Twins Ice Cream, Blue Marble Ice Cream, Straus Family Creamery, Yeo Valley, Organic Meadow, Alden's Organic, Talenti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Ice Cream Market Emerging Trajectories
Formulation science and regulatory disclosure requirements are converging to redefine competitive advantage in premium frozen desserts, with transparency replacing flavor novelty as the primary purchase trigger.
Continuous freezing technology with precision overrun control is consolidating production economics for mid-scale organic processors. Batch freezer operators in Vermont and California are retrofitting equipment to achieve 40-80% overrun consistency previously available only to industrial continuous lines. This capability compression enables artisanal brands to compete for foodservice contracts requiring volume reliability without sacrificing label credentials.
The EU Organic Regulation's equivalence requirements for North American export access are reshaping documentation investments across California and Vermont processing facilities. German and French retail buyers now demand dual-certified supply chains with traceability systems interoperable with European organic databases. Producers targeting transatlantic placement are reconfiguring ingredient sourcing to exclude non-equivalent processing aids.
Subscription-based replenishment models are capturing repeat purchase frequency from health-conscious households with predictable consumption patterns. Direct-to-home delivery platforms displace conventional supermarket stocking decisions with algorithm-driven flavor curation. This channel shift concentrates most visibly in United States metropolitan corridors with established refrigerated logistics infrastructure and high organic food penetration rates.
Organic Ice Cream Market Segmentation
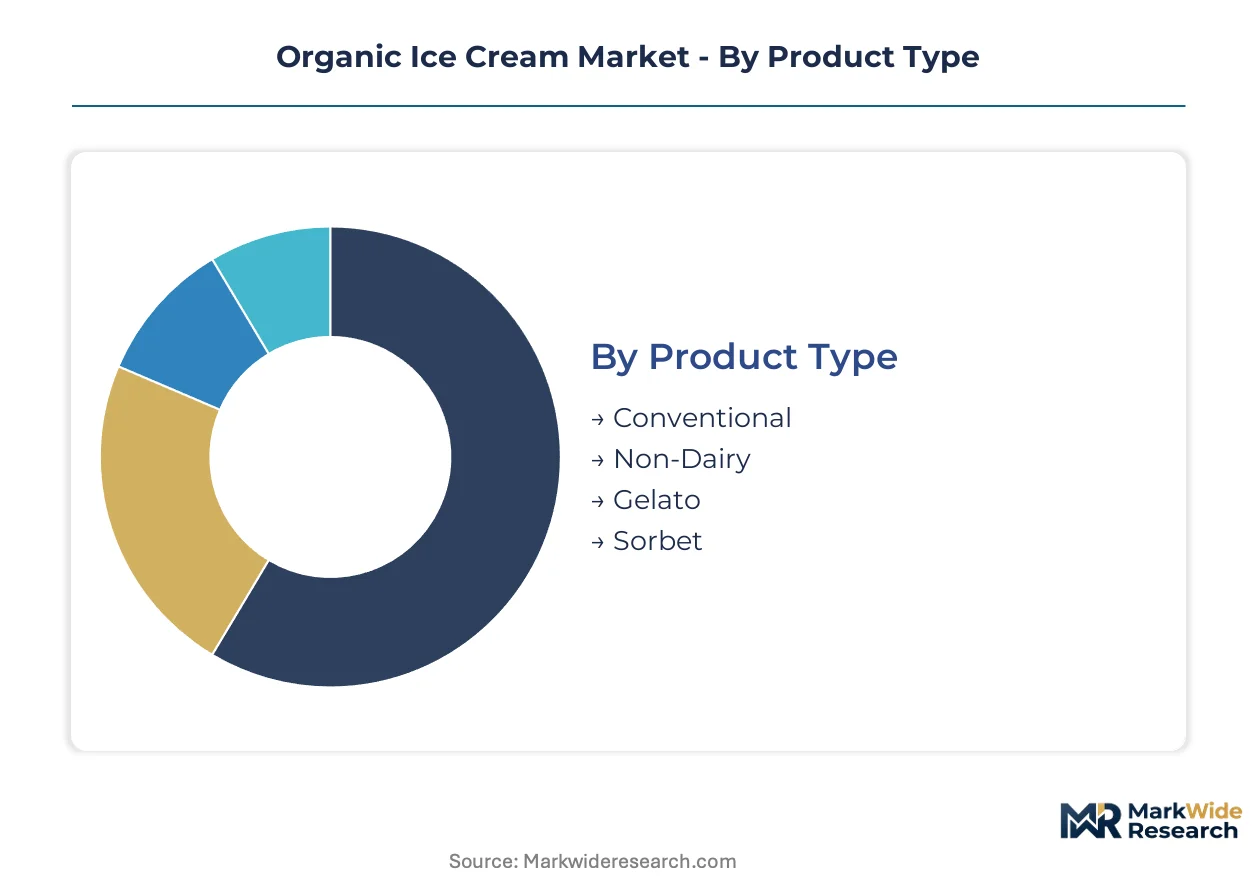
Organic ice cream segmentation reveals how formulation chemistry, procurement channel, and dietary identity intersect to create distinct margin pools. Clean-label certification requirements compress supplier flexibility differently across each dimension, concentrating competitive advantage among operators with compliant captive supply chains.
Product Type:
Supply concentration in California's Central Valley and Vermont's artisanal corridor favors processors with geographic proximity to certified organic cream sources.
- Conventional:Milk-fat formulations ranging 10-16% butterfat content with USDA National Organic Program certification for all agricultural inputs. Demand clusters in United States family households seeking familiar taste profiles with reduced synthetic pesticide exposure. Organic milk input cost volatility constrains margin predictability for processors dependent on spot market dairy purchases.
- Non-Dairy:Oat and coconut base formulations achieving improved fat and protein mimicry through enzymatic processing. Lactose-intolerant consumers in metropolitan corridors with established refrigerated logistics infrastructure drive adoption. Clean-label technical ceiling limits shelf-life extension and complicates distribution to remote retail locations.
- Gelato:Lower overrun formulations (20-35%) with denser texture and intensified flavor delivery.
- Sorbet:Fruit-puree based formulations without dairy content, targeting vegan and allergen-sensitive consumption occasions.
Today's leader: Conventional. Tomorrow's challenger: Non-Dairy.
Ingredient Type:
Cost tier stratification separates premium organic dairy inputs from commodity-grade alternatives, with certification grade determining price realization.
- Milk-Based:Fluid organic milk comprising 60-80% of finished product mass, sourced from herds under three-year land conversion protocols. California's dairy belt concentration reduces cold-chain logistics costs for West Coast processors. Single-source supply concentration creates geographic vulnerability to climate disruption.
- Cream-Based:Higher butterfat organic cream (36-40% fat content) enabling premium texture and mouthfeel differentiation.
- Sweetener:Organic cane sugar, tapioca syrup, and fruit juice concentrates replacing conventional corn syrup.
- Flavoring:Certified organic vanilla, cocoa, and fruit preparations with traceable origin documentation.
Ingredient procurement power concentrates among vertically integrated operators with captive organic milk supply.
Distribution Channel:
Margin structure varies dramatically by channel, with specialty stores capturing disproportionate pools through curated assortment and educated staff.
- Specialty Stores:Premium dessert shops and organic grocers with trained personnel enabling price realization unavailable in conventional supermarket environments. Subscription-based replenishment models capture repeat purchase frequency from health-conscious households with predictable consumption patterns.
- Supermarkets:Private-label programs shifting toward organic frozen dessert placements as conventional ice cream aisles lose traffic to perimeter fresh departments.
- Online:Direct-to-home delivery platforms displacing conventional stocking decisions with algorithm-driven flavor curation.
- Farmers Markets:Hyper-local procurement with minimal cold-chain infrastructure requirements.
Specialty stores command current premium realization. Online channels are gaining share fastest through refrigerated last-mile logistics investments.
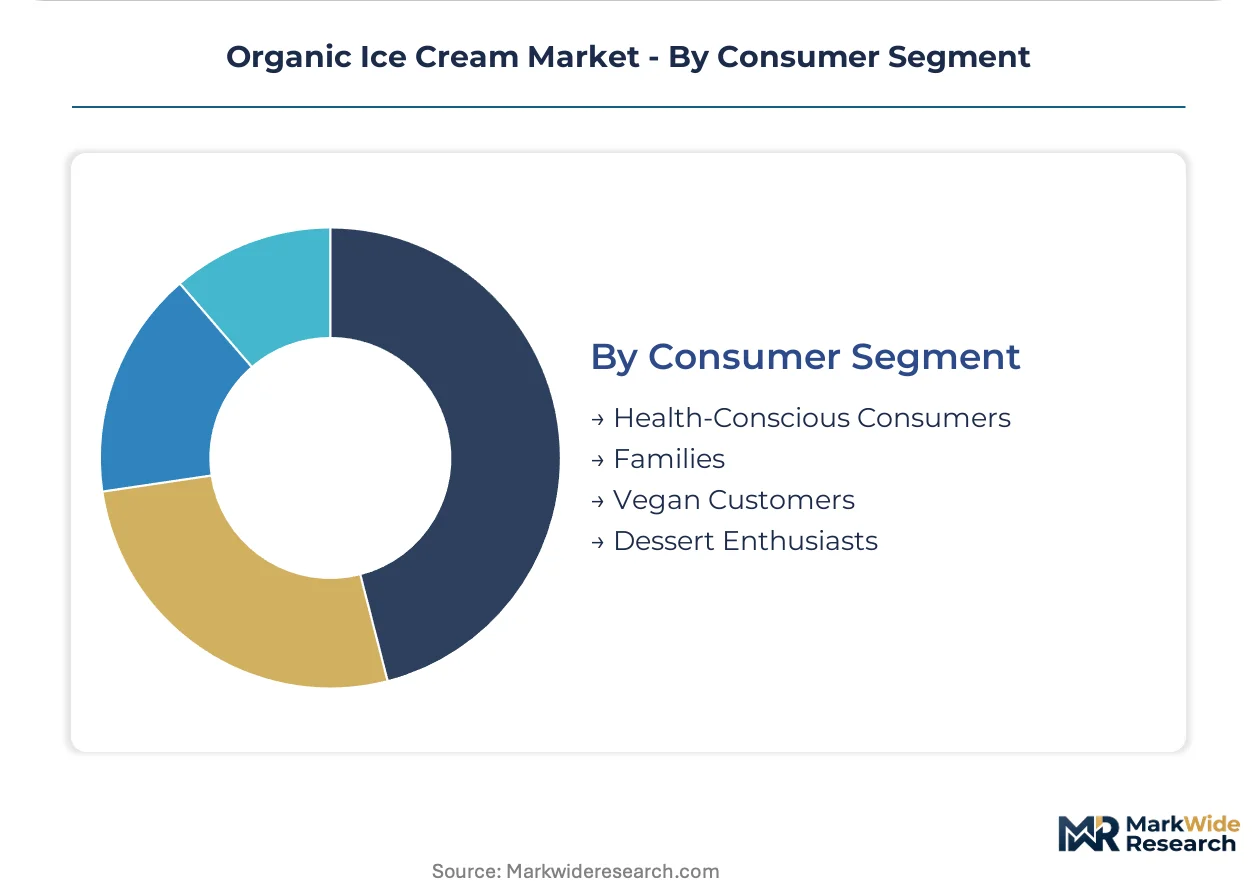
Consumer Segment:
Dietary identity and health motivation create distinct purchasing patterns with varying price elasticity and repeat frequency.
- Health-Conscious Consumers:Households prioritizing reduced synthetic pesticide exposure and prohibited hormone or antibiotic residues, with above-average willingness-to-pay for certified supply chain transparency. Direct-to-home subscription adoption concentrates visibly in United States metropolitan corridors with high organic food penetration rates.
- Families:Multi-person households purchasing family-pack formats with conventional pricing parity expectations.
- Vegan Customers:Plant-based formulation demand driven by ethical and digestive considerations.
- Dessert Enthusiasts:Flavor-forward purchasers seeking novel taste experiences within clean-label constraints.
Health-Conscious Consumers anchor current revenue concentration. Vegan Customers represent the steepest expansion trajectory as oat base formulation advances capture previously excluded lactose-intolerant demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as processors migrate toward jurisdictions with streamlined organic certification timelines and lower feed-input costs. California's dairy belt and Vermont's artisanal corridor anchor North American capacity, while European equivalence requirements redirect export-oriented investment toward dual-certified facilities.
United States
Health-conscious households in metropolitan corridors drive subscription-based replenishment adoption through direct-to-home delivery platforms. The USDA National Organic Program governs ingredient traceability mandates that disqualify conventional suppliers lacking compliant documentation systems. California's Central Valley concentrates organic milk production near processing infrastructure, reducing cold-chain logistics costs for West Coast distribution.
Germany
Retail buyers in Berlin and Hamburg demand dual-certified supply chains with traceability systems interoperable with European organic databases. The EU Organic Regulation's equivalence requirements reshape documentation investments for North American exporters seeking shelf placement. Bavarian processing facilities are reconfiguring ingredient sourcing to exclude non-equivalent processing aids for transatlantic market access.
France
Parisian specialty cafés capture disproportionate margin pools through curated organic dessert assortments and educated staff enabling premium price realization. The EU Green Deal's anticipated alignment requirements are accelerating carbon labeling pilot program adoption among export-oriented processors. Provençal artisanal clusters are retrofitting batch freezer equipment to achieve overrun consistency previously available only to industrial continuous lines.
Canada
Health Canada and the PMRA enforce supplementary processing facility oversight alongside federal organic standards in Ontario and Quebec dairy regions. Provincial inspection programs in British Columbia add layer compliance costs that favor vertically integrated operators with captive organic milk supply. Toronto and Vancouver metropolitan markets concentrate direct-to-home delivery adoption with established refrigerated logistics infrastructure.
United Kingdom
London's premium dessert shops command larger procurement shares than conventional foodservice channels through staff-enabled price realization. The Food Standards Agency coordinates with EU Organic Regulation equivalence protocols for post-Brexit trade continuity. Somerset and Cotswolds artisanal dairy clusters anchor production capacity with proximity to metropolitan demand centers.
Organic Ice Cream Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier operators capturing margin through clean-label certification while private-label programs compete on conventional pricing parity. Market structure concentrates procurement power among vertically integrated dairy processors with captive organic milk supply. Three archetypes dominate: multinational branded portfolios leveraging parent-company sourcing infrastructure, regional artisanal operators with geographic proximity to certified cream sources, and private-label specialists serving supermarket channel placement. Competitive moves center on direct-to-home subscription channel investment and carbon labeling early adoption for premium positioning.
Within the multinational branded tier, Ben & Jerry's exemplifies parent-company infrastructure leverage for certified organic dairy procurement at scale. Among regionally anchored artisanal operators, Straus Family Creamery occupies a position representing vertically integrated organic dairy production in Northern California supply chains. On the private-label competitive vector, Alden's Organic sits within the family-pack segment archetype pursuing conventional pricing parity on select stock-keeping units.
| Leading Market Players |
|---|
| Ben & Jerry's |
| Häagen-Dazs |
| Three Twins Ice Cream |
| Blue Marble Ice Cream |
| Straus Family Creamery |
| Yeo Valley |
| Organic Meadow |
| Alden's Organic |
| Talenti |
| Others |
Supply Flow & Price Mechanics
Organic milk feed costs transmit directly through California's Central Valley processors into three-tier pricing structure across premium, standard, and economy levels, with Vermont's artisanal cluster commanding spreads based on certification grade and captive supply control.
Pricing Analysis
Distributor margin compression in conventional supermarket channels is accelerating price erosion through family-pack segments where Alden's Organic pursues parity positioning. Specialty stores extract premium realization through educated staff and curated assortment, with health-conscious households showing lowest price sensitivity. Price differentiation rests on USDA National Organic Program certification tier and geographic proximity to production clusters. Cost compression in standard-tier formulations is intensifying because spot market organic milk purchases expose processors to feed price volatility.
Supply Chain Analysis
USDA National Organic Program qualification gates entry through three-year land conversion protocols and documentation audit requirements that favor incumbent processors with established compliance systems. Supply concentrates in the United States, Germany, and France, with raw material dependencies on certified organic milk, oat base formulations, and enzymatic processing aids. Single-source vulnerability runs through California's Central Valley and Vermont's dairy belt concentration. Distribution runs through temperature-controlled networks requiring retrofit for organic product segregation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge between the United States and Germany, where EU Organic Regulation equivalence requirements impose documentation investments that US-based exporters can leverage for premium positioning ahead of anticipated Green Deal alignment.
For Market Incumbents: Anticipate oat base formulation advances by securing enzymatic processing partnerships before technical ceilings stabilize competitive positions. Defend margin structures through backward integration into captive organic milk supply in California's dairy belt, insulating against spot market volatility that threatens processors dependent on external procurement. For New Entrants and Emerging Players: Capture direct-to-home subscription white space in United States metropolitan corridors with established refrigerated logistics infrastructure. Target vegan customer segments with improved fat and protein mimicry in plant-based alternatives, deploying algorithm-driven flavor curation as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Consolidation pressure builds where single-source supply concentration creates geographic vulnerability to climate disruption. Long-term viability favors vertically integrated operators with captive organic milk supply and dual-certified facilities for transatlantic access. Watch carbon labeling pilot program adoption as the inflection signal for premium positioning ahead of regulatory alignment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Algorithm-driven flavor curation displaces conventional supermarket stocking decisions in high-penetration corridors. |
| Backward Integration into Organic Dairy | Captive milk supply insulates margin predictability against feed price volatility in California's Central Valley. |
| Dual Certification Investment | EU Organic Regulation equivalence unlocks German and French retail placement for North American exporters. |
| Carbon Labeling Early Adoption | Farm-to-freezer emissions tracking differentiates premium positioning ahead of EU Green Deal requirements. |
| Specialty Café Channel Expansion | Educated staff at premium dessert shops enable price realization unavailable in conventional supermarket environments. |
Methodological Framework
Coverage spans North America and Western Europe, with primary inputs from each region combining interviews with organic dairy processors, specialty retail buyers, and supply chain logistics operators alongside secondary validation through USDA National Organic Program filings, EU Organic Regulation documentation, and refrigerated distribution infrastructure databases. Bottom-up volume modeling triangulates against top-down category spend analysis.
Granularity-level framing applies product type, distribution channel, and consumer segment dimensions at the country level across the analysis window, with ingredient type and regional production cluster modeled at sub-national resolution. CAGRs derive from historical trajectory analysis adjusted for regulatory enforcement intensity and channel shift velocity. Forecast inputs incorporate organic milk herd transition timelines and refrigerated last-mile logistics penetration rates.
Underlying measurement precision varies by segment; conventional and non-dairy product types carry tighter precision than emerging gelato and sorbet categories due to established reporting infrastructure. Forecasts reflect assumptions about USDA enforcement continuity and EU equivalence protocol stability. A model refresh is warranted upon material change in three-year land conversion protocol timelines or carbon labeling mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Non-GMO Food Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
Germany Organic Food Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
Organic Food and Beverages Market
Organic Food and Beverages
Canada Organic Food Market
Organic Food and Beverages
Organic Drinks Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
Organic Fast Food Market
Organic Food and Beverages
Scandinavia Organic Packaged Food and Beverages Market
Organic Food and Beverages
Global Organic Packaged Food Market