
 Morocco Bottled Water Market | 2026-2036
Morocco Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Bottled Water Market Foresight
Aftermarket service revenue from cooler rentals and bulk delivery contracts is reshaping profit pools away from single-serve retail. PepsiCo, Inc. leverages its nationwide distribution network to dominate modern trade channels. Les Eaux Minérales d'Oulmès SA anchors its position through deep well access in the Middle Atlas. Danone S.A. specializes in premium glass-bottled mineral water for restaurant accounts.
Bottled water comprises potable water sealed in containers for human consumption, typically sourced from protected springs or boreholes and treated through filtration, ozonation, or UV sterilization to meet microbiological safety thresholds. Still water holds the largest volume share across Moroccan retail shelves, though flavored water segments attract younger urban consumers seeking alternatives to sugary beverages. Plastic bottles command manufacturing scale advantages, while glass packaging captures premium positioning in hotel and restaurant channels.
Morocco's national food safety authority enforces mineral composition disclosure rules that determine spring water versus mineral water classification. The country's environmental ministry regulates single-use plastic reduction timelines that push producers toward recyclable PET innovations and alternative packaging formats. Stakeholders must weigh capital allocation between premium glass formats and scalable recycled-plastic infrastructure as regulatory pressure intensifies.
Market Dynamics
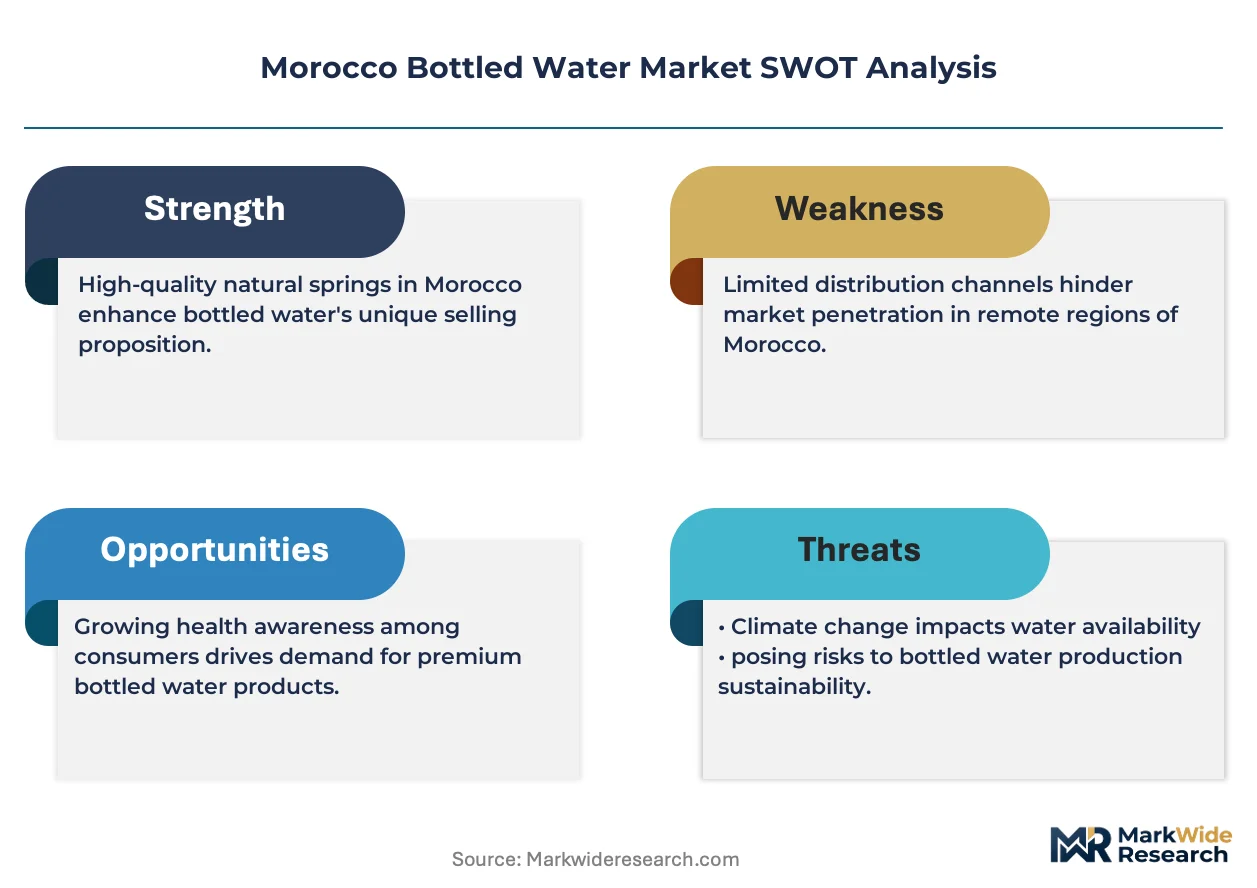
Mineral content disclosure mandates from Morocco's national food safety authority are forcing producers to reconfigure labeling infrastructure and sourcing certifications. This regulatory pressure intersects with tourism-driven hospitality procurement to reshape competitive positioning.
Growth Catalysts
- ONSSA mineral classification rules:Strict disclosure requirements create product differentiation opportunities for springs with distinctive mineral profiles. Producers leverage certified composition to command premium placement.
- Casablanca-Settat urban household concentration:Dense metropolitan populations sustain volume throughput for modern trade channels. Retail infrastructure expansion supports category penetration.
- UV-C LED sterilization systems:Advanced treatment technologies reduce chemical dependency while maintaining microbiological safety thresholds. Adoption accelerates among mid-scale bottlers seeking operational efficiency.
Market Restraints
- PET resin import dependency:Morocco lacks domestic polymer production capacity, exposing margins to currency fluctuation and shipping cost volatility. Packaging represents 35-45% of unit economics.
- Deep well access concentration:Protected aquifer rights cluster in Middle Atlas formations, limiting new entrant sourcing options. Incumbents control strategic borehole positions.
- Groundwater extraction permits:Environmental ministry allocation caps restrict production expansion timelines. Renewal processes introduce multi-year approval uncertainties.
Strategic Opportunities
- Rabat-Salé-Kénitra household penetration:Administrative capital corridor shows lower per-capita consumption than commercial hubs. Distribution network expansion captures latent demand.
- Hotel amenity programs:Branded glass format placement in riad and resort properties builds consumer recognition. Hospitality procurement contracts offer multi-year revenue visibility.
- Recycled-PET infrastructure investment:Ministry-mandated plastic reduction timelines incentivize domestic r-PET processing capacity. Early movers secure regulatory compliance advantages.
Industry Challenges
- Geological survey expertise scarcity:Qualified hydrogeologists capable of certifying new source viability command premium compensation. Talent pipelines remain underdeveloped.
- Cooler fleet maintenance networks:Bulk delivery service expansion requires technician density that lags in secondary cities. Aftermarket service quality inconsistency threatens contract renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Bottled Water Market |
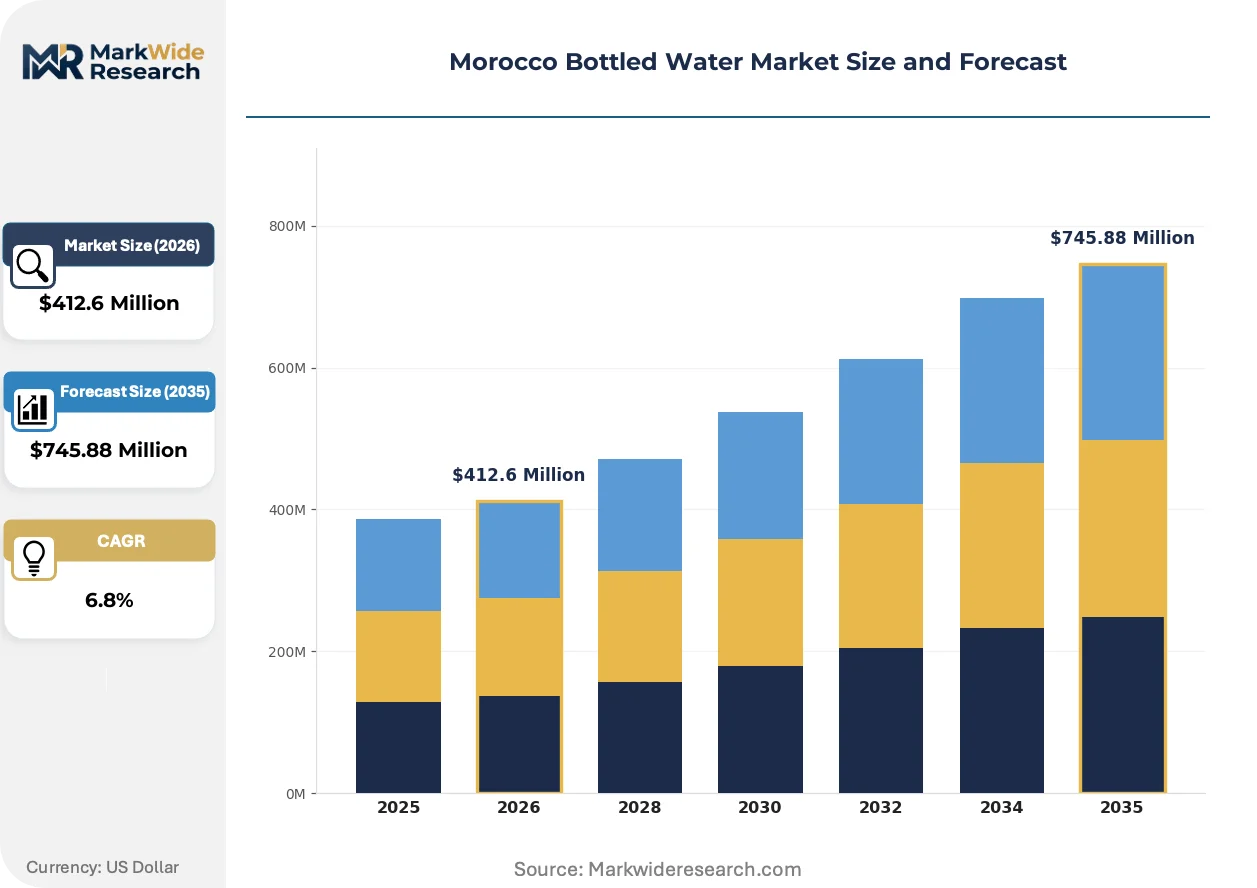
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Still Water, Sparkling Water, Flavored Water, Mineral Water Packaging Type: Plastic Bottles, Glass Bottles, Tetra Packs, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, HoReCa End User: Households, Offices, Fitness Centers, Restaurants |
| Companies Covered | PepsiCo, Inc., Sotherma SA, Les Eaux Minérales d'Oulmès SA, Water Mineral Chefchaouen Sarl, Lodep Sarl, Nestlé S.A., Danone S.A., Groupe des Brasseries du Maroc SA, The Coca-Cola Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Bottled Water Market Shifts & Advancements
Digital traceability systems and sustainable packaging formats are converging to transform how Moroccan producers demonstrate provenance and environmental accountability. These shifts respond to both regulatory pressure and hospitality buyer procurement criteria.
Blockchain-enabled source tracking is digitizing supply chain transparency for premium mineral water lines. Luxury hotel groups and export distributors now require batch-level provenance verification as a procurement condition. This technology is compressing information asymmetry between spring sources and end consumers, enabling price premiums for verified origins.
Morocco's environmental ministry has accelerated single-use plastic reduction timelines through enforceable production quotas. Bottlers must demonstrate r-PET incorporation percentages or face distribution restrictions. Glass format producers and domestic recycling infrastructure investors capture regulatory tailwinds as compliance deadlines approach.
Hospitality procurement teams are consolidating supplier relationships around full-service cooler rental and bulk delivery contracts. Traditional cash-and-carry retail purchasing loses share to subscription-based consumption models in Casablanca and Marrakesh corporate accounts. This pattern concentrates volume with distributors capable of integrated equipment service and logistics execution.
Morocco Bottled Water Market Segmentation
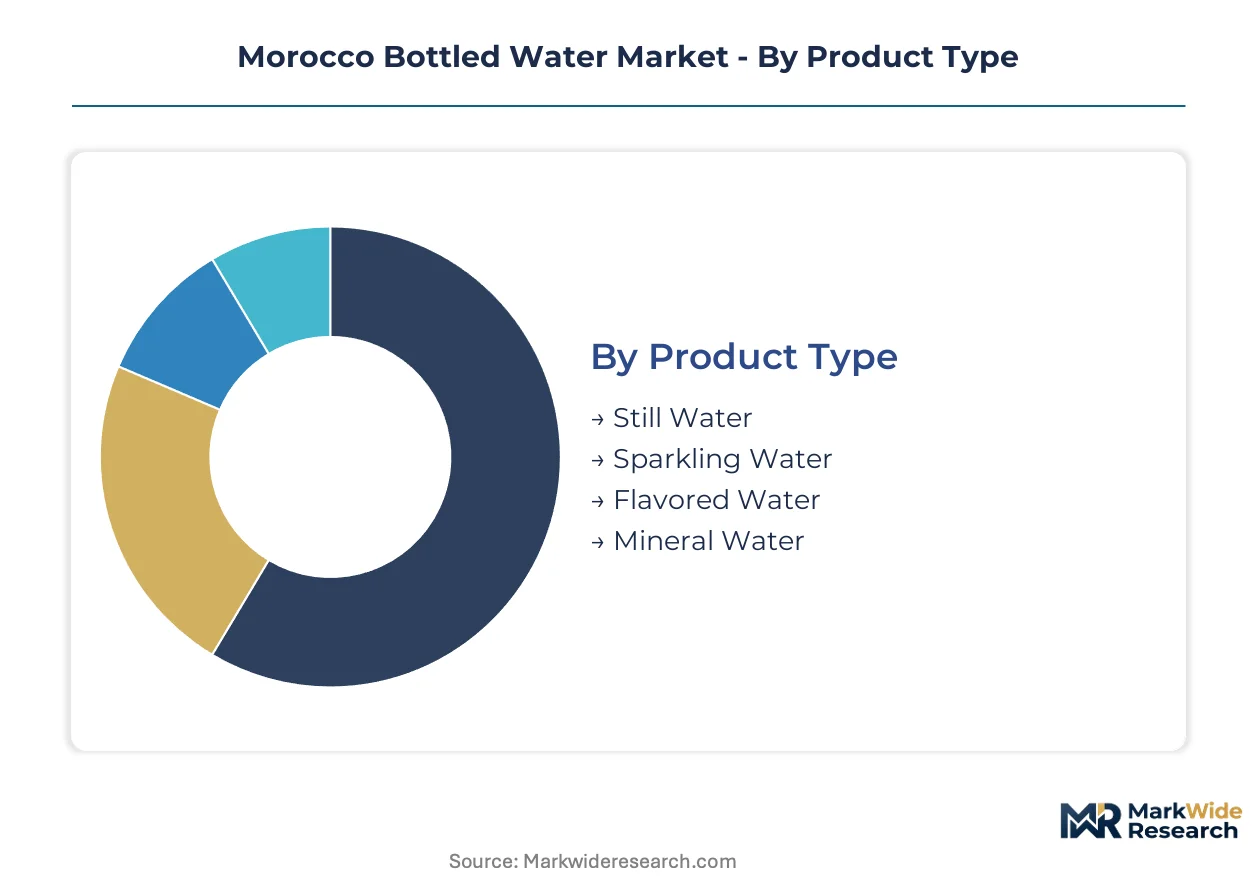
Morocco's bottled water market segments along four functional dimensions that determine sourcing strategy, packaging investment, and route-to-market economics. Each category reflects distinct consumption occasions and procurement patterns across Casablanca-Settat and Rabat-Salé-Kénitra demand clusters.
Product Type:
Still water dominates household pantry stock rotation, while carbonated and enhanced variants capture occasion-based consumption in hospitality and fitness settings.
- Still Water:Un carbonated potable water with neutral pH profiles fills bulk dispenser contracts and family-size retail purchases. Casablanca-Settat urban households sustain the highest per-capita throughput for daily hydration and cooking applications.
- Mineral Water:Naturally sourced water with certified mineral composition under ONSSA disclosure mandates commands premium shelf positioning. Deep well access in Middle Atlas formations limits supply-side expansion, concentrating provenance marketing among established bottlers.
- Sparkling Water:Carbonated variants target restaurant table service and mixer applications in Marrakesh hospitality venues.
- Flavored Water:Fruit-infused formulations attract younger consumers seeking alternatives to carbonated soft drinks in Rabat-Salé-Kénitra convenience channels.
Established volume favors still water; emerging adoption favors mineral water.
Packaging Type:
Format selection trades manufacturing scale against regulatory compliance timelines and hospitality buyer specifications.
- Plastic Bottles:PET containers deliver unit cost advantages at volume and dominate modern trade shelf space. Environmental ministry mandates for r-PET incorporation percentages are forcing producers toward domestic recycling infrastructure partnerships.
- Glass Bottles:Premium positioning in riad and resort properties builds brand recognition through amenity programs. Higher unit economics and breakage rates restrict distribution to urban hospitality clusters.
- Tetra Packs:Aseptic carton formats suit institutional catering and office pantry contracts with extended shelf stability.
- Pouches:Flexible single-serve packaging targets price-sensitive trial purchases in secondary city convenience stores.
Scale economics concentrate in plastic bottles; regulatory tailwinds favor glass bottles.
Distribution Channel:
Channel mix determines working capital intensity and customer acquisition cost structures across Morocco's retail landscape.
- Supermarkets:Hypermarket and supermarket chains in Casablanca-Settat anchor volume throughput with promotional calendar dependency. PepsiCo's nationwide distribution network dominates shelf placement and promotional frequency.
- HoReCa:Hotel, restaurant, and café procurement contracts offer multi-year revenue visibility through cooler rental and bulk delivery arrangements. Marrakesh tourism infrastructure expansion drives category penetration in this channel.
- Convenience Stores:Neighborhood proximity retail captures impulse purchases and single-serve consumption occasions.
- Online Retail:E-commerce platforms aggregate bulk household orders with delivery subscription models in administrative capital corridors.
Volume concentrates in supermarkets; margin expansion concentrates in HoReCa.
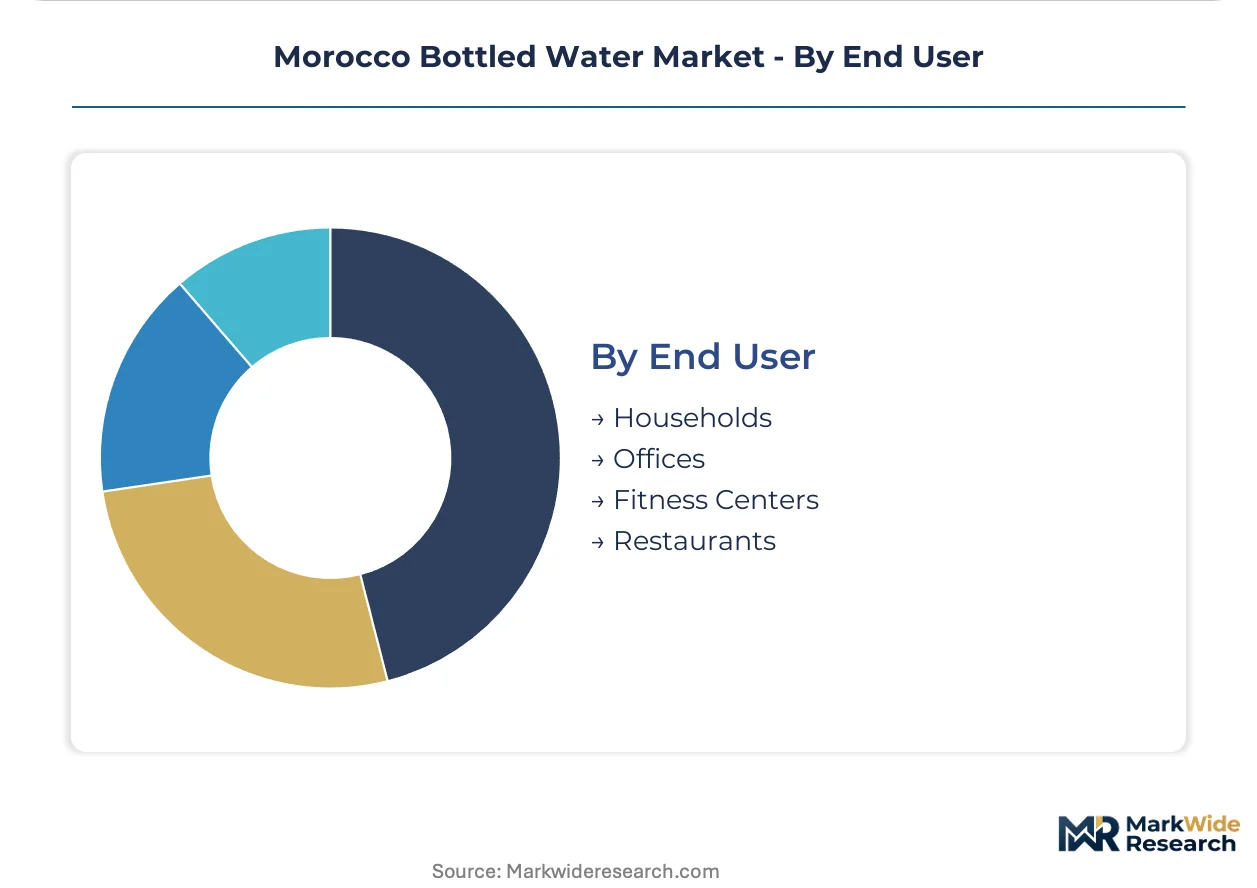
End User:
Final consumption context shapes volume scale, delivery frequency, and equipment service requirements.
- Households:Residential consumption in Casablanca-Settat and Rabat-Salé-Kénitra regions sustains baseline production planning. Family-size packaging and dispenser subscriptions dominate procurement patterns.
- Restaurants:Table service and kitchen preparation requirements in Marrakesh and Casablanca hospitality venues drive glass format demand. Branded amenity placement builds consumer recognition for premium lines.
- Offices:Corporate pantry and meeting room cooler contracts require technician density for fleet maintenance.
- Fitness Centers:Hydration stations and retail resale in gym facilities target health-conscious urban consumers.
Volume leadership sits with households; premium pricing power sits with restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Casablanca-Settat households consume bottled water for daily hydration and cooking, while Marrakesh hospitality venues drive premium glass-format demand through tourism procurement. This consumption-mix differential shapes regional investment priorities across Morocco's bottling infrastructure.
Casablanca-Settat
Urban household density sustains the highest per-capita throughput for family-size retail purchases and bulk dispenser contracts. ONSSA mineral classification rules force producers to reconfigure labeling infrastructure for modern trade shelf placement. PepsiCo leverages its nationwide distribution network to dominate hypermarket and supermarket chains across the metropolitan corridor.
Rabat-Salé-Kénitra
Administrative capital corridors show lower per-capita consumption than commercial hubs, creating latent demand for distribution network expansion. The environmental ministry's single-use plastic reduction timelines push producers toward domestic r-PET processing partnerships. E-commerce platforms aggregate bulk household orders with delivery subscription models in this corridor.
Marrakesh-Safi
Tourism infrastructure expansion drives category penetration through hotel, restaurant, and café procurement contracts. Hospitality buyers now require batch-level provenance verification as a procurement condition. Riad and resort properties concentrate glass-format demand for branded amenity programs.
Fès-Meknès
Secondary city convenience stores capture impulse purchases and single-serve consumption occasions in price-sensitive segments. Groundwater extraction permits from the environmental ministry restrict production expansion timelines with multi-year approval uncertainties. Flexible single-serve pouch packaging targets trial purchases in this sub-region.
Tanger-Tetouan-Al Hoceïma
Proximity to Mediterranean shipping corridors exposes PET resin import dependencies to currency fluctuation and shipping cost volatility. Deep well access concentration in Middle Atlas formations limits new entrant sourcing options. Incumbents control strategic borehole positions that anchor regional supply security.
Morocco Bottled Water Market Competitive Landscape
Capability concentration sits with established bottlers holding protected aquifer rights; scale advantage sits with multinational beverage conglomerates leveraging nationwide distribution networks. The market structures around three tiers: global beverage majors with integrated logistics, domestic incumbents with certified spring access, and regional specialists serving hospitality niches. Dominant competitive moves include cooler fleet expansion for subscription-based consumption models and r-PET infrastructure investment to secure regulatory compliance advantages.
Within the multinational tier, PepsiCo, Inc. and The Coca-Cola Company anchor scale-driven positions through modern trade channel dominance. Les Eaux Minérales d'Oulmès SA and Danone S.A. exemplify the premium-provenance archetype, with the former representing domestic spring-access incumbency and the latter occupying multinational mineral-water specialization. These three entities collectively illustrate how competitive positioning splits between distribution velocity and source-certified differentiation.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| Sotherma SA |
| Les Eaux Minérales d'Oulmès SA |
| Water Mineral Chefchaouen Sarl |
| Lodep Sarl |
| Nestlé S.A. |
| Danone S.A. |
| Groupe des Brasseries du Maroc SA |
| The Coca-Cola Company |
| Others |
Supply & Pricing Matrix
Underutilized r-PET processing capacity in Casablanca-Settat is forcing producers toward longer contract commitments to secure volume throughput, compressing spot-market flexibility and anchoring pricing power with integrated recyclers. This utilization dynamic tightens margin structures for mid-scale bottlers while rewarding early movers in domestic recycling infrastructure.
Pricing Analysis
Long-term cooler rental contracts dominate hospitality procurement in Marrakesh and Casablanca, locking in multi-year revenue visibility against transactional retail spot purchases. Price differentiation rests on mineral certification tier under ONSSA disclosure mandates and volume scale in family-size packaging. Cost compression in plastic bottle tiers is intensifying because PET resin import exposure amplifies currency-driven margin volatility. Price-sensitive household segments in Rabat-Salé-Kénitra absorb economy-tier pouch formats, while premium glass positioning in riad amenity programs commands insensitivity.
Supply Chain Analysis
Domestic bottling concentration sits with Les Eaux Minérales d'Oulmès SA and PepsiCo's licensed production facilities, with limited contract-manufacturing alternatives for mid-scale entrants. Raw material flows draw from Saudi Arabian and European PET resin suppliers, Middle Atlas spring source infrastructure, and imported UV-C LED sterilization equipment. Single-source vulnerability in deep well access concentrates supply risk with incumbent borehole rights holders. Distribution runs through modern trade hypermarket chains, HoReCa cooler fleet networks, and emerging e-commerce subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's bottled water market represents early-cycle expansion as tourism infrastructure buildout and household dispenser penetration in administrative corridors remain below saturation thresholds. The convergence of regulatory compliance timelines and hospitality procurement consolidation creates asymmetric returns for positioned players.
For Market Incumbents: Harden spring source certification moats through accelerated ONSSA mineral classification investment before extraction permit caps tighten. Deepen backward integration into r-PET processing capacity to capture regulatory compliance advantages as environmental ministry deadlines approach. Lock in multi-year HoReCa cooler fleet contracts in Marrakesh-Safi to preempt emerging distribution entrants. For New Entrants and Emerging Players: Mid-market household segments in Rabat-Salé-Kénitra represent the most penetrable entry point given lower per-capita consumption and underdeveloped e-commerce subscription density. Secondary city convenience channels in Fès-Meknès offer white-space for flexible pouch format trial positioning. Pursue direct-to-consumer bulk delivery models with technician partnerships to bypass entrenched modern trade shelf access barriers. For Investors and Strategic Acquirers: Capital is best deployed toward provenance-certified domestic bottlers with unencumbered Middle Atlas aquifer rights and established hospitality channel relationships. Long-term viability hinges on regulatory compliance positioning through the plastic reduction transition window. Watch for cooler fleet maintenance network density in secondary cities as an inflection signal for subscription model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic r-PET Processing Investment | ONSSA compliance deadlines reward early infrastructure commitment with distribution security. |
| HoReCa Cooler Fleet Expansion | Marrakesh tourism procurement contracts lock in multi-year revenue visibility against retail volatility. |
| Blockchain Provenance Verification | Luxury hotel buyers now mandate batch-level source tracking as non-negotiable procurement criteria. |
| Deep Well Access Acquisition | Environmental ministry permit caps concentrate strategic value in unencumbered Middle Atlas boreholes. |
| E-Commerce Subscription Launch | Rabat-Salé-Kénitra administrative corridors show latent demand for aggregated bulk household delivery. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ONSSA regulatory filings, environmental ministry permit databases, and hospitality procurement contract registries. The research program combined structured interviews with bottling plant operations directors, modern trade category buyers, riad procurement managers, and UV-C sterilization equipment distributors. Secondary validation drew from customs import records for PET resin, tourism board infrastructure investment disclosures, and national food safety authority mineral composition certifications. Bottom-up volume modeling triangulated against top-down category spend estimates across Casablanca-Settat and Rabat-Salé-Kénitra household clusters.
Forecast inputs incorporated product type segmentation across still, mineral, sparkling, and flavored variants; packaging format economics for PET, glass, and aseptic cartons; distribution channel working capital intensity; and end-user consumption occasion patterns. CAGRs were derived through regression analysis of historical volume trajectories against tourism arrival projections and urban household penetration curves. The analytical framework weighted groundwater extraction permit renewal timelines and r-PET infrastructure buildout schedules as supply-constraint variables.
Practitioners should monitor ONSSA enforcement intensity, cooler fleet maintenance quality scores in secondary cities, and hospitality buyer consolidation patterns for early signals of competitive repositioning. Forecasts embed assumptions around tourism recovery trajectory and environmental ministry plastic reduction timeline adherence. Quarterly review of extraction permit approval velocities and r-PET incorporation compliance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
GCC Bottled Water Market
Beverages
Hot Beverages Market
Beverages
North America Energy Drink Market
Beverages
Grab and Go Bottles Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
Nitro-Infused Cola Market
Beverages
Fermented Drinks Market
Beverages
Relaxation Beverages Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
Flavored Powder Drinks Market
Beverages
Sparkling Juice Drinks Market
Beverages
Saudi Arabia Retail Bubble Tea Kits Market
Beverages
Foaming Creamer Market
Beverages
Direct Piping Water Dispenser Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Bangladesh Energy Drinks Market