
 Sparkling Juice Drinks Market | 2026-2036
Sparkling Juice Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Sparkling Juice Drinks Market Insights
European fruit concentrate suppliers is decoupling from traditional still-juice supply chains as sparkling formats claim dedicated carbonation infrastructure. Ocean Spray leverages its cranberry sourcing networks to secure raw material advantage across North American production. PepsiCo anchors its position through captive bottling partnerships that reduce third-party dependency. S. Martinelli & Company differentiates via heritage apple varietals and premium glass packaging that commands shelf-space premiums in specialty retail.
Sparkling juice drinks combine filtered fruit or vegetable juice with carbonated water, typically containing 20-100% juice content and achieving 2.5-3.5 volumes of CO₂ saturation for effervescence; the category serves as a bridge between conventional soft drinks and premium functional beverages. Organic sparkling juice commands margin concentration as certification requirements limit supplier pools and justify price architecture above conventional alternatives. Cans are displacing glass in convenience channels due to lighter logistics profiles and expanded single-serve occasion capture, while tetra packs retain strength in European ambient retail.
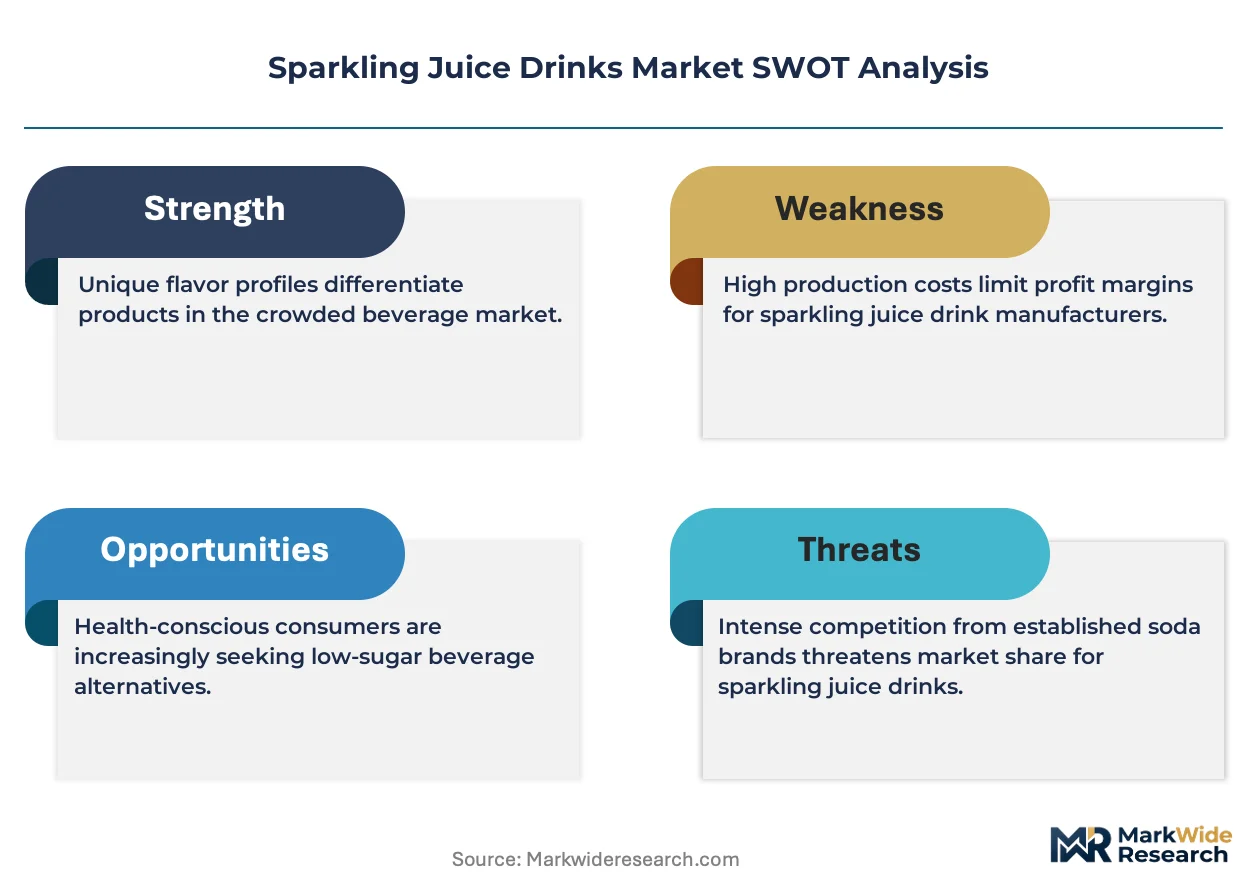
FDA governs juice percentage labeling and health claim substantiation in the United States, while EFSA sets purity benchmarks for EU-wide natural flavor declarations; both frameworks elevate compliance costs for cross-border entrants. The EU Green Deal packaging directives and emerging state-level bottle deposit expansions in California and New York are reshaping material selection timelines. Stakeholders must monitor evolving sugar taxation thresholds and carbon accounting disclosure requirements that threaten to recategorize sparkling juice positioning relative to zero-calorie alternatives.
Market Dynamics
Carbonation infrastructure specialization is fragmenting supply chains as sparkling formats demand dedicated CO₂ saturation systems distinct from still-juice processing lines. This equipment bifurcation is elevating capital requirements and reshaping supplier relationships across production networks.
Growth Catalysts
- EU Green Deal packaging directives:Reusable and recyclable material mandates are accelerating bottle-to-can transitions in European ambient retail, opening volume for aluminum suppliers.
- Functional beverage convergence:Sparkling juice formats with adaptogens and probiotics are capturing wellness-oriented consumers in premium supermarket channels.
- Millennial household formation:Health-conscious younger demographics in the United States are expanding per-capita consumption of organic-certified variants.
Market Restraints
- Concentrate supply concentration:European fruit concentrate suppliers control critical input streams, creating vulnerability for North American bottlers during harvest volatility.
- FDA juice percentage substantiation:Cross-border entrants face elevated compliance costs for natural claim verification in United States distribution.
- Zero-calorie substitution threat:Flavored sparkling waters with artificial sweeteners compete directly on price in convenience channels.
Strategic Opportunities
- State-level bottle deposit expansions:California and New York deposit systems are creating infrastructure for closed-loop packaging economics.
- Tetra pack ambient distribution:Shelf-stable formats enable European market penetration without cold-chain investment.
- Sugar taxation thresholds:Reduced-sugar sparkling juice positioning captures volume as beverage taxes expand across municipalities.
Industry Challenges
- Carbon accounting disclosure timelines:Emerging Scope 3 reporting requirements demand supply chain visibility that legacy ERP systems cannot deliver.
- CO₂ saturation technician scarcity:Specialized knowledge for 2.5-3.5 volume carbonation calibration is concentrated among aging workforce cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sparkling Juice Drinks Market |
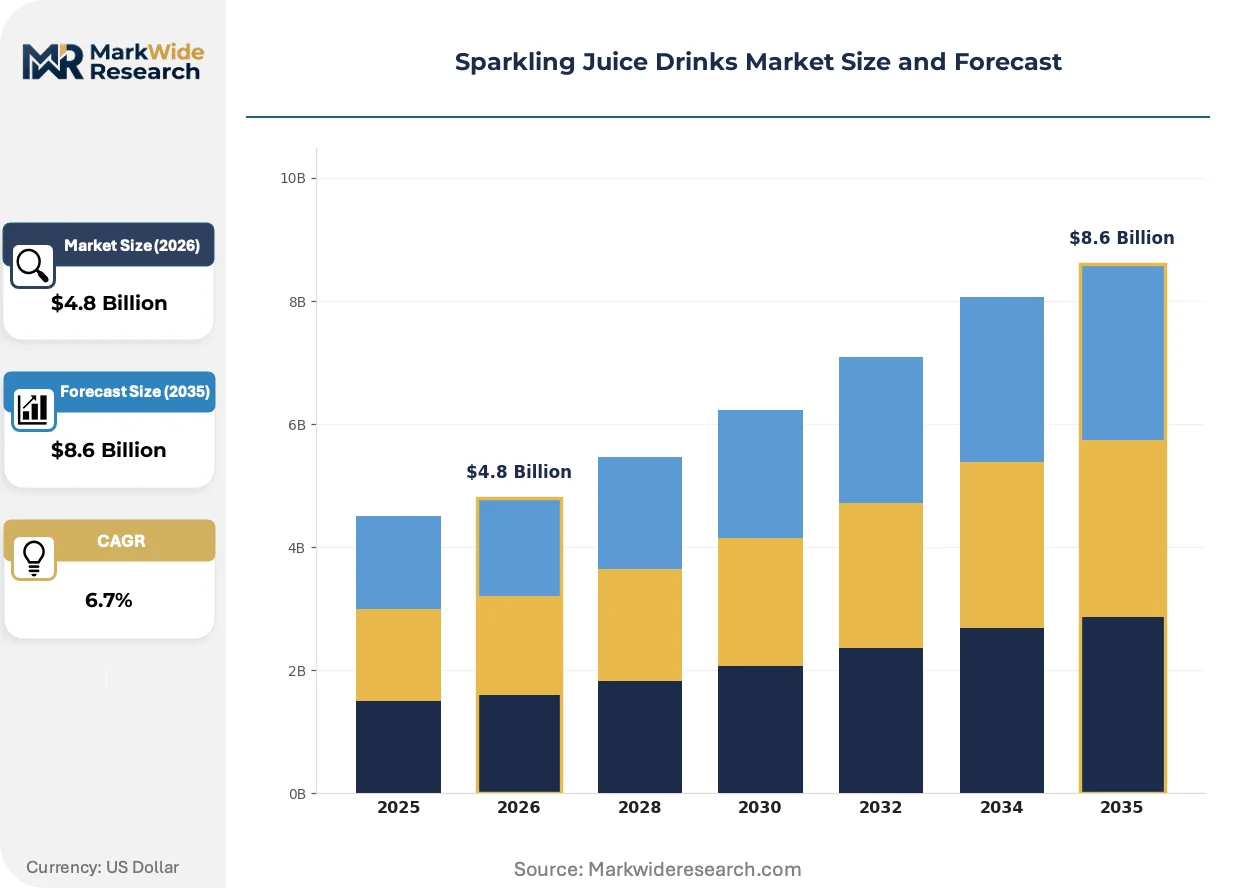
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Sparkling Juice, Vegetable Sparkling Juice, Mixed Sparkling Juice, Organic Sparkling Juice Flavor Profile: Citrus, Berry, Tropical, Herbal Packaging Type: Glass Bottles, Cans, Tetra Packs, PET Bottles Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Cafés |
| Companies Covered | Ocean Spray, Welch’s, Coca-Cola, Keurig Dr Pepper, AriZona Beverages, PepsiCo, S. Martinelli & Company, Knudsen & Sons, Nestle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sparkling Juice Drinks Market Trends and Innovations
Reformulation science and packaging engineering are converging to reshape competitive boundaries. Producers now balance effervescence stability against clean-label imperatives while logistics optimization drives material selection.
Aseptic cold-filling technology for carbonated beverages is electrifying production economics by eliminating thermal pasteurization energy costs. Mid-sized bottlers in Germany and Japan are retrofitting lines at accelerated pace. This process shift is compressing capital recovery timelines and enabling smaller-batch premium runs.
EFSA natural flavor purity benchmarks are tightening formulation specifications across EU-wide distribution. Manufacturers must document supply chain provenance for all volatile compounds. Organic-certified sparkling juice variants face the steepest compliance burden, with reformulation costs passed through specialty retail price architecture.
Millennial pantry replenishment patterns favor variety-pack trial formats over single-flavor commitments. E-commerce subscription channels in the United States are displacing conventional supermarket stock-up trips. This behavior concentrates demand volatility with direct-to-consumer fulfillment networks.
Sparkling Juice Drinks Market Segmentation
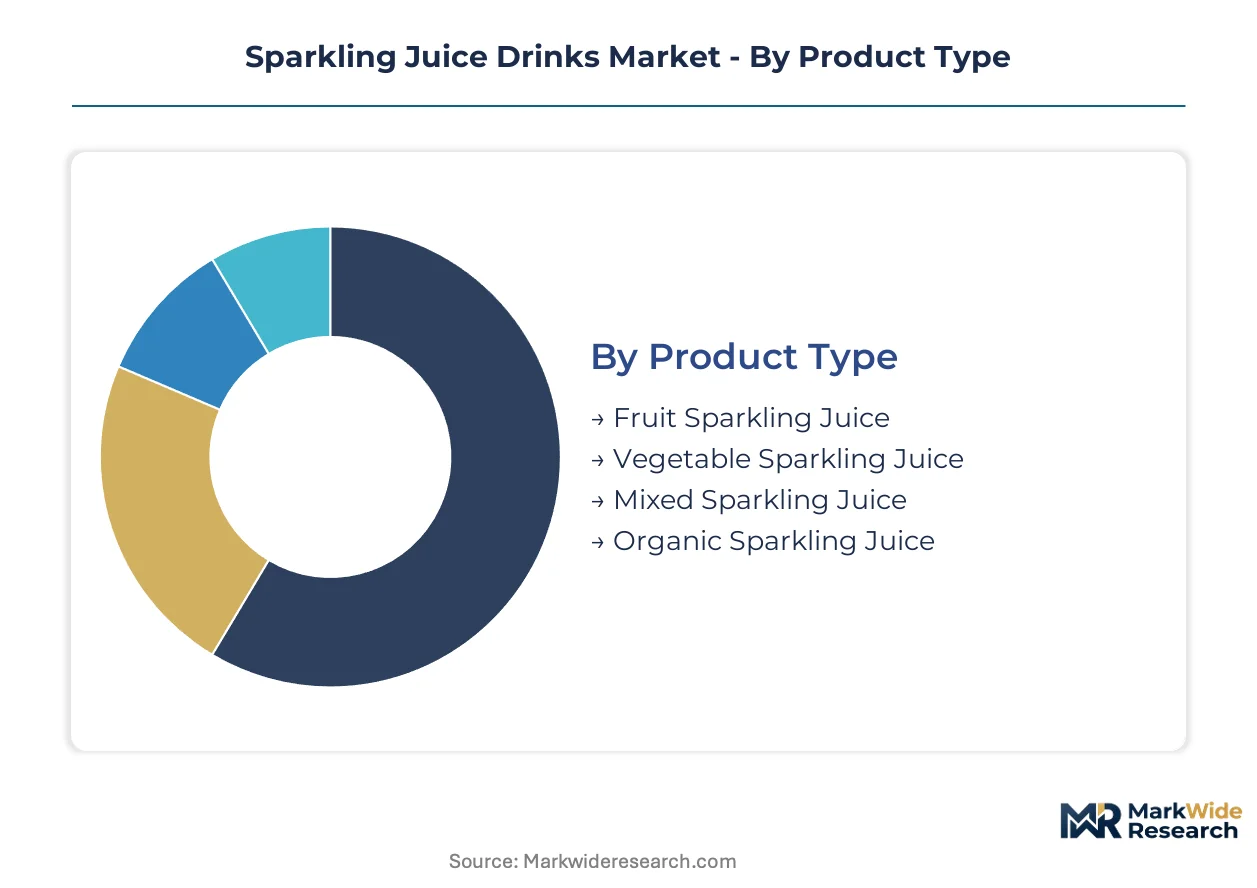
Segmentation in sparkling juice drinks reveals how certification burdens, packaging logistics, and channel economics partition commercial opportunity. Manufacturers configure production assets around specific segment combinations rather than serving the category uniformly.
Product Type:
Organic Sparkling Juice carries the heaviest certification load, requiring USDA Organic or EU Organic compliance for cross-border legitimacy, while conventional variants face lighter FDA juice percentage substantiation.
- Fruit Sparkling Juice:Formulations derive from filtered apple, grape, or citrus bases with 20-100% juice content and 2.5-3.5 volumes CO₂ saturation. Demand concentrates in United States premium supermarket channels where millennial household formation expands per-capita consumption of functional carbonated alternatives.
- Organic Sparkling Juice:Certification requirements limit supplier pools to audited orchards and processing facilities, justifying price architecture above conventional alternatives. German and Japanese health food stores capture the steepest volume growth as EFSA natural flavor purity benchmarks tighten formulation specifications.
- Vegetable Sparkling Juice:Carrot, beet, and tomato variants occupy niche positioning with lower absolute volumes.
- Mixed Sparkling Juice:Fruit-vegetable blends target wellness-oriented consumers seeking functional beverage convergence.
Fruit Sparkling Juice sits at the top of the volume ranking, with Organic Sparkling Juice climbing the fastest.
Flavor Profile:
Flavor selection drives raw material procurement geography, with citrus dependent on Mediterranean and Florida sourcing networks while berry concentrates rely on Pacific Northwest and Polish supply basins.
- Citrus:Lemon, lime, and orange variants dominate formulation portfolios due to year-round concentrate availability and established carbonation compatibility.
- Berry:Cranberry and blueberry sourcing networks in North America provide raw material advantage for integrated producers.
- Tropical:Mango, pineapple, and passionfruit formulations face higher concentrate supply concentration and harvest volatility exposure.
- Herbal:Botanical infusions command specialty retail shelf-space premiums with limited volume scale.
Citrus maintains the broadest geographic penetration, with Berry gaining share fastest in premium channels.
Packaging Type:
Material selection shapes logistics economics and regulatory exposure, with EU Green Deal packaging directives accelerating transitions away from single-use formats.
- Cans:Aluminum formats displace glass in convenience channels due to lighter logistics profiles and expanded single-serve occasion capture. California and New York deposit systems create infrastructure for closed-loop economics.
- Glass Bottles:Heritage producers command shelf-space premiums in specialty retail through premium packaging aesthetics. German and Japanese consumers sustain demand despite higher freight costs.
- Tetra Packs:Shelf-stable formats retain strength in European ambient retail without cold-chain investment.
- PET Bottles:Lightweight plastic faces regulatory pressure from emerging state-level bottle deposit expansions.
Cans lead volume growth trajectory, with Glass Bottles defending premium positioning.
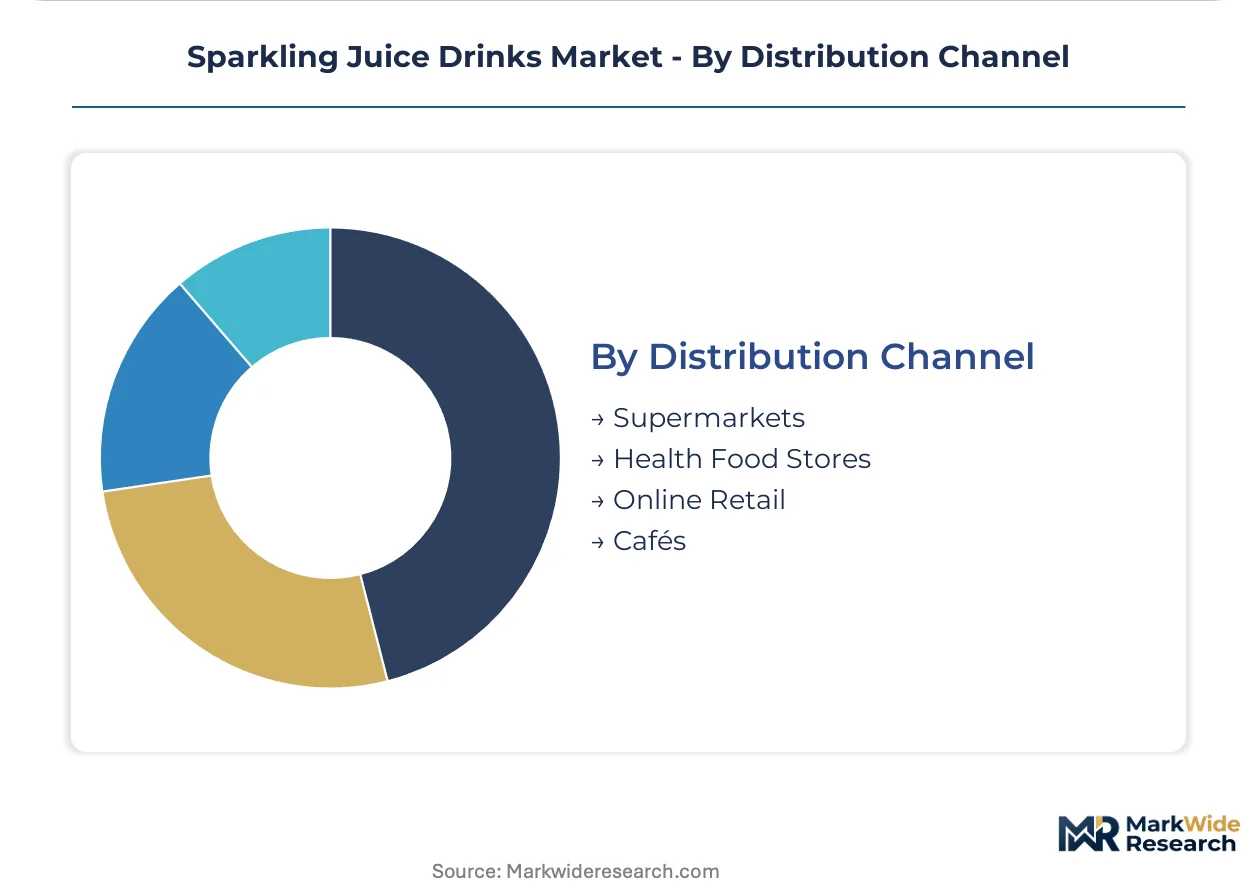
Distribution Channel:
Channel selection determines pricing architecture and consumer relationship depth, with direct-to-consumer fulfillment networks displacing conventional stock-up trips among younger demographics.
- Supermarkets:Premium chains in the United States, Germany, and Japan concentrate functional beverage demand. Health-conscious millennials drive organic variant expansion.
- Online Retail:E-commerce subscription channels capture pantry replenishment patterns favoring variety-pack trial formats.
- Health Food Stores:Specialty retailers absorb compliance cost pass-through for certified organic positioning.
- Cafés:On-premise consumption occasions support single-serve premium pricing.
Supermarkets anchor absolute volume, with Online Retail expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are reshaping production footprints as manufacturers relocate carbonation infrastructure toward jurisdictions with streamlined organic certification pathways. Compliance cost differentials between FDA and EFSA frameworks are accelerating cross-border facility investments.
United States
Millennial household formation in premium supermarket channels is expanding per-capita consumption of organic-certified variants. FDA juice percentage substantiation requirements elevate compliance costs for natural claim verification. California and New York state-level bottle deposit expansions are creating closed-loop packaging infrastructure for aluminum can economics.
Germany
Health food store networks absorb the steepest volume growth for EFSA-compliant organic positioning. EU Green Deal packaging directives accelerate bottle-to-can transitions in ambient retail channels. Bavarian bottling clusters are retrofitting aseptic cold-filling lines to compress capital recovery timelines for smaller-batch premium runs.
Japan
Functional beverage convergence with adaptogens and probiotics is capturing wellness-oriented consumers in Tokyo-Osaka premium channels. METI carbon accounting disclosure timelines demand supply chain visibility upgrades. Nagoya-area production facilities face CO₂ saturation technician scarcity as aging workforce cohorts concentrate specialized knowledge.
United Kingdom
E-commerce subscription channels are displacing conventional supermarket stock-up trips among younger demographics. EFSA natural flavor purity benchmarks apply post-Brexit through retained EU law alignment. London-Southeast logistics hubs concentrate direct-to-consumer fulfillment networks for variety-pack trial formats.
Canada
Health Canada labeling standards for natural claims are tightening formulation requirements parallel to FDA frameworks. Ontario and Quebec retail channels sustain demand for heritage glass packaging aesthetics despite higher freight costs. Pacific Northwest cross-border concentrate sourcing networks provide raw material advantage for integrated North American production.
Sparkling Juice Drinks Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue functional beverage convergence with adaptogen and probiotic infusions. The market structures around three maturity tiers: heritage juice houses with captive sourcing networks, multinational beverage conglomerates with captive bottling partnerships, and mid-sized organic specialists with audited supply chains. Dominant competitive moves include backward integration into fruit concentrate supply and strategic partnerships for carbonation infrastructure access.
Within the heritage producer tier, S. Martinelli & Company and Ocean Spray exemplify archetypes built on varietal-specific sourcing advantages. PepsiCo and Coca-Cola occupy positions as scale-driven multinationals leveraging captive bottling networks to reduce third-party dependency. Welch's represents the cooperative-structured competitor with integrated agricultural supply chains. These archetypes illustrate how certification burdens and packaging logistics partition commercial opportunity rather than uniform category service.
| Leading Market Players |
|---|
| Ocean Spray |
| Welch's |
| Coca-Cola |
| Keurig Dr Pepper |
| AriZona Beverages |
| PepsiCo |
| S. Martinelli & Company |
| Knudsen & Sons |
| Nestle |
| Others |
Pricing and Supply Chain Analysis
Aseptic cold-filling technology electrification is compressing capital recovery timelines for mid-sized German and Japanese bottlers while simultaneously fragmenting supplier relationships as carbonation infrastructure specialization demands dedicated CO₂ saturation systems distinct from legacy still-juice processing lines.
Pricing Analysis
Retailer markup layers in premium supermarket channels absorb compliance cost pass-through for EFSA-certified organic variants while direct-to-consumer subscription channels compress distributor margins through variety-pack trial formats. Three-tier pricing structure across premium organic, conventional functional, and economy private-label levels stratifies by certification grade and juice percentage substantiation. Price differentiation stems from USDA Organic audit costs and glass packaging aesthetics versus aluminum logistics efficiency. Pricing pressure intensifies in convenience channels as zero-calorie flavored sparkling waters compete on artificial sweetener cost structures. Health-conscious millennials in United States premium chains exhibit lowest price sensitivity while budget household segments in mass retail show highest elasticity.
Supply Chain Analysis
Freight cost differentials between aluminum can lightweighting and heritage glass bottle logistics are accelerating channel-specific material selection across North American and European distribution networks. Raw material procurement draws from Mediterranean citrus concentrate networks, Pacific Northwest cranberry sourcing basins, and Polish berry supply corridors. Carbonation equipment and CO₂ saturation calibration expertise hinge on aging technician cohorts concentrated in Bavarian and Nagoya-area production clusters. Single-source vulnerability concentrates in European fruit concentrate suppliers controlling critical input streams for North American bottlers during harvest volatility. Distribution runs through captive bottling partnerships for multinational scale players while mid-sized organic specialists rely on audited third-party co-packing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sparkling juice drinks function as a stable compounder anchored by health-conscious millennial pantry replenishment patterns that sustain recurring revenue through e-commerce subscription channels and premium supermarket loyalty programs.
For Market Incumbents: Acquire carbonation infrastructure assets in jurisdictions with streamlined organic certification pathways to reduce cross-border compliance cost differentials between FDA and EFSA frameworks. Secure captive fruit concentrate supply through backward integration into Mediterranean citrus and Pacific Northwest cranberry networks. Defend against zero-calorie substitution threats by expanding functional beverage convergence with adaptogen and probiotic infusions in premium channels.
For New Entrants and Emerging Players: Wellness-oriented convenience seekers in United States urban markets represent the most penetrable buyer archetype for reduced-sugar sparkling juice positioning ahead of expanding municipal beverage taxation. Target state-level bottle deposit expansion corridors in California and New York where closed-loop aluminum economics create infrastructure parity with established players. Launch through direct-to-consumer variety-pack subscriptions to capture trial behavior without conventional retail slotting fee barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized organic specialists with audited supply chains and aseptic cold-filling retrofit capabilities in German or Japanese production clusters. Long-term viability over the next decade rests on certification moat durability and carbon accounting disclosure readiness ahead of Scope 3 reporting mandates. Watch for inflection signals in sugar taxation threshold expansions that recategorize sparkling juice positioning relative to zero-calorie alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fruit Concentrate Supply | Ocean Spray's cranberry sourcing networks demonstrate raw material advantage capture across North American production corridors. |
| Aseptic Cold-Filling Line Retrofit | Bavarian bottling clusters compress capital recovery timelines while eliminating thermal pasteurization energy costs. |
| Direct-to-Consumer Subscription Launch | Variety-pack trial formats displace conventional supermarket stock-up trips among millennial pantry replenishment patterns. |
| Organic Certification Investment | USDA Organic and EU Organic compliance limits supplier pools to audited orchards justifying price architecture premiums. |
| Aluminum Can Channel Expansion | California and New York deposit systems create infrastructure for closed-loop packaging economics in convenience retail. |
Research Methodology
Bottom-up sparkling juice consumption modeling reconciled against top-down carbonation infrastructure and concentrate supply tracking forms the analytical core of this study. Primary interviews with brand managers at heritage juice houses, category buyers at United States premium supermarket chains, supply planners at captive bottling partnerships, and technical directors at aseptic filling equipment suppliers combined with secondary validation. Secondary sources include FDA juice percentage labeling filings, EFSA natural flavor purity benchmark documentation, EU Green Deal packaging directive compliance records, Nielsen retail audit data for functional beverage categories, and customs records for fruit concentrate trade flows.
Input-output matrices segment volume and value projections across product type, packaging material, distribution channel, and regional regulatory cluster throughout the forecast period. Modeled dimensions include organic versus conventional certification tier, aluminum can versus glass bottle versus tetra pack format, and premium supermarket versus online retail versus health food store channel. CAGRs derive from trend extrapolation of millennial household formation rates, organic certification expansion trajectories, and state-level bottle deposit adoption schedules. Industry-specific forecast inputs incorporate CO₂ saturation technician workforce demographics and aseptic cold-filling retrofit investment cycles.
Underlying measurement precision varies by segment; fruit sparkling juice and aluminum can packaging carry tighter precision than vegetable variants and tetra pack ambient formats due to established retail tracking infrastructure. Forecasts reflect assumptions regarding EFSA and FDA regulatory stability, harvest volatility in Mediterranean citrus and Pacific Northwest berry basins, and carbon accounting disclosure timeline adherence. A model refresh is warranted upon material change in sugar taxation threshold legislation or significant disruption to European fruit concentrate supplier networks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Yerba Mate Market
Beverages
Japan Energy Drink Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Bottled Deep Ocean Water Market
Beverages
China Soy Beverages Market
Beverages
Direct Piping Water Dispenser Market
Beverages
North America Yerba Mate Market
Beverages
Low Calorie RTD Beverages Market
Beverages
Commercial Sparkling Water Dispenser Market
Beverages
Morocco Bottled Water Market
Beverages
Detox Drinks Market
Beverages
Milk Tea Powder Market
Beverages
GCC Fruit Juice Market
Beverages
Beverage Multipacks Market
Beverages
North America Juices Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market