
 Europe Coconut Water Market | 2026-2036
Europe Coconut Water Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Coconut Water Market Intelligence
REACH is broadening the cost-of-entry calculus for coconut water brands importing into the European Union, forcing reformulation of packaging adhesives and label substrates. The Vita Coco Co. Inc. leverages its established retail network to sustain volume leadership across multiple EU member states. Green Coco Europe anchors its competitive position through specialized organic certification and cold-chain logistics expertise.
Coconut water is the clear liquid endosperm extracted from young green coconuts, typically containing electrolytes including potassium, sodium, and magnesium with a brix level of 4-6 degrees, serving primarily as a natural hydration beverage and sports drink alternative. Organic variants command premium shelf positioning and margin pools across European health stores and supermarkets. Tetra Pack formats dominate ambient distribution channels, while glass bottles capture higher price points in restaurant and specialty retail segments.
EMA food contact regulations, EFSA health claim protocols, and the EU Green Deal packaging directives collectively shape product formulation, label substantiation, and circular economy compliance for market participants. Brands must navigate divergent national implementations of EU-wide standards, particularly France's ANSM labeling requirements and Germany's KBA-adjacent transport regulations for refrigerated goods. Stakeholders should monitor upcoming revisions to the Packaging and Packaging Waste Regulation that will redefine recyclability thresholds.
Market Dynamics
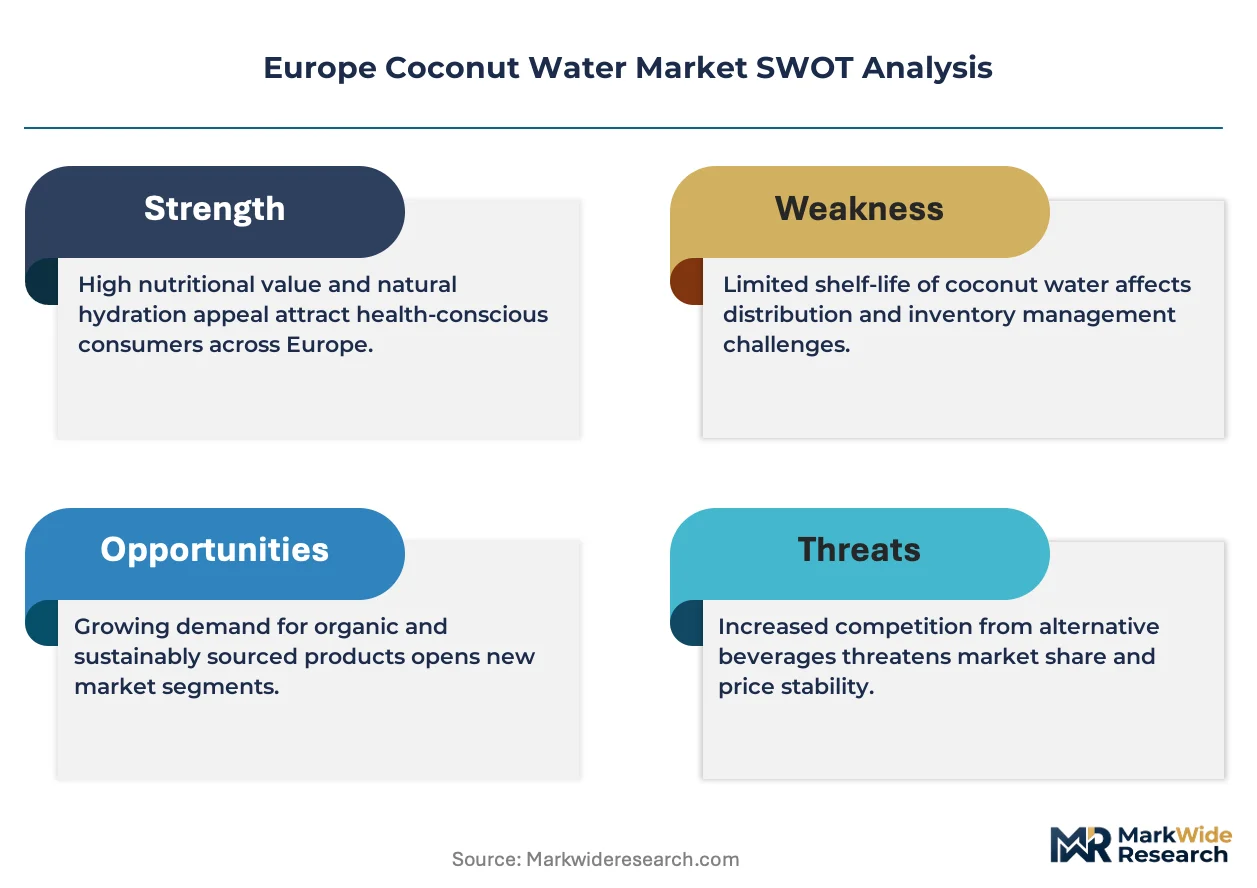
The EU Green Deal packaging directives are compressing margins and forcing rapid supply chain reconfiguration across European coconut water brands, with REACH compliance costs now embedded in import cost structures.
Growth Catalysts
- EU Green Deal packaging mandates:Brands accelerating adoption of recyclable Tetra Pack formats and bio-based plastics to meet circular economy targets ahead of enforcement timelines.
- German fitness culture:Health clubs and boutique gyms in Berlin and Munich expanding coconut water placement as post-workout hydration, driving volume through specialized sports retail.
- Cold-chain logistics advancement:Refrigerated transport networks across France and the Netherlands enabling wider distribution of raw, unpasteurized variants with extended shelf stability.
Market Restraints
- REACH chemical compliance:Reformulation of packaging adhesives and label substrates adds fixed cost layers for every EU import shipment, disproportionately burdening smaller traders.
- Southeast Asian supply concentration:Overreliance on Indonesian and Philippine coconut harvests exposes brands to climate-induced yield volatility and shipping cost spikes through the Suez corridor.
- Sports drink substitution:Established electrolyte beverages from PepsiCo and Coca-Cola maintain price anchoring and retail slotting dominance in mainstream supermarkets.
Strategic Opportunities
- Polish and Romanian retail expansion:Underserved Central European markets show rising health-conscious consumption with limited premium organic coconut water penetration.
- Foodservice channel development:High-end restaurants in Paris, London, and Amsterdam adopting coconut water as cocktail base and non-alcoholic pairing, extracting margin premiums unavailable in grocery.
- CSRD sustainability reporting:Early compliance with corporate sustainability disclosure requirements creates marketing differentiation and preferential listing with ESG-focused retail buyers.
Industry Challenges
- Organic certification timelines:EU organic label acquisition requires 12-18 month validation periods, delaying product launches and freezing working capital in inventory.
- Cold-chain capex intensity:Establishing refrigerated warehousing and last-mile delivery capabilities demands substantial upfront investment, particularly in Southern Europe where ambient distribution dominates.
- Multi-jurisdiction label compliance:Divergent ANSM requirements in France versus BfR interpretations in Germany force SKU proliferation and complicate pan-European marketing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Coconut Water Market |
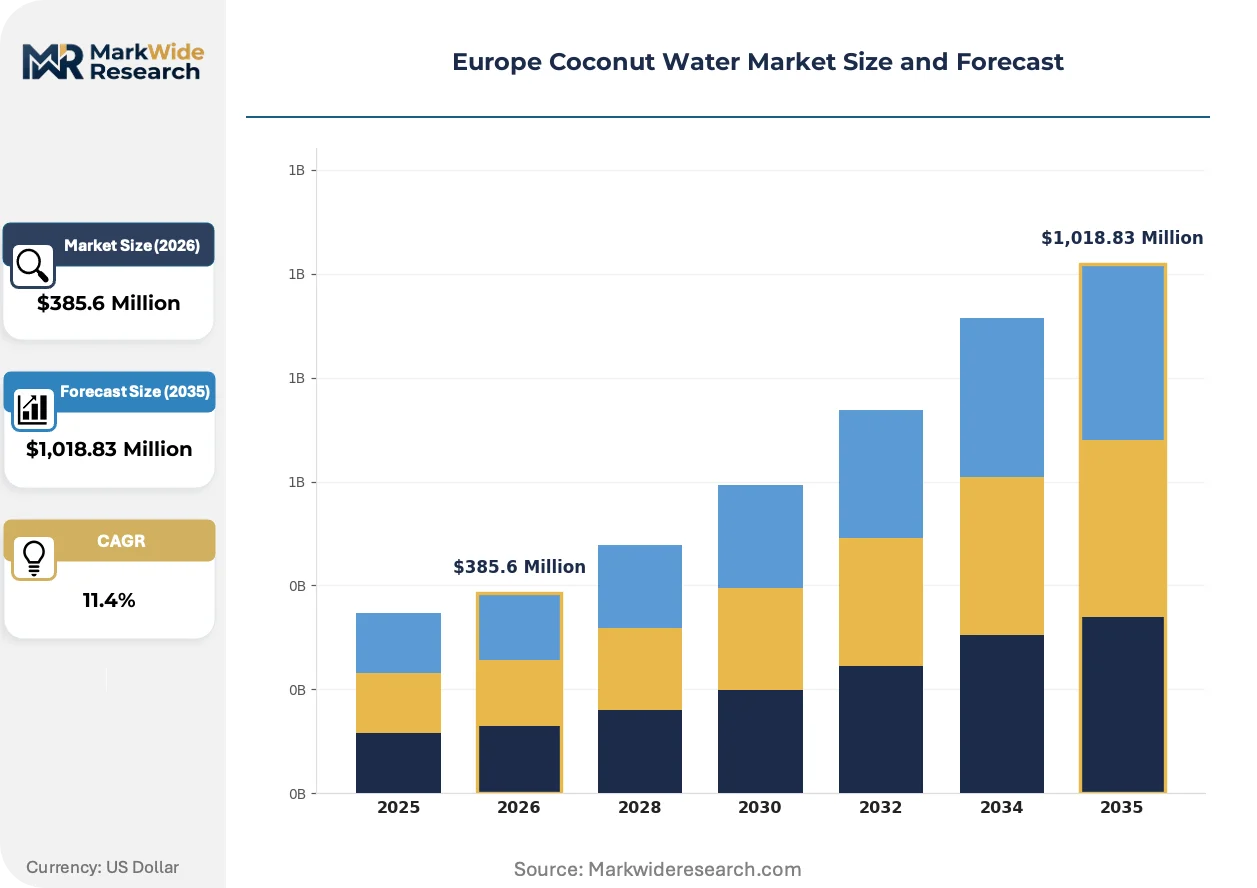
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,018.83 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Flavored, Plain, Sparkling Packaging Type: Tetra Pack, Glass Bottle, Canned, Pouch Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Stores End User: Health Enthusiasts, Athletes, General Consumers, Restaurants |
| Companies Covered | Harmless Harvest, GraceKennedy Ltd., The Vita Coco Co. Inc., Chi, Green Coco Europe, PepsiCo Inc., Goya Foods Inc., Helios Ingredients Ltd., The Coca-Cola Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Coconut Water Market Strategic Shifts & Innovations
Aseptic processing advances and bio-based material science are compressing the cost premium between ambient and chilled coconut water formats, while regulatory pressure on packaging recyclability accelerates format turnover.
HPP (high-pressure processing) technology is unifying food safety assurance with nutrient retention in premium coconut water segments. German and Dutch organic brands are adopting HPP at scale to eliminate thermal degradation while extending refrigerated shelf life. This technology is unifying previously separate supply chains for raw and pasteurized products, enabling single-source production flexibility.
REACH authorization requirements for food contact substances are tightening specification windows for packaging adhesives and barrier coatings. ECHA's 2024 updated candidate list is forcing reformulation cycles among Tetra Pack suppliers and independent canning operations. French brands face additional ANSM scrutiny on migration testing, creating compliance fragmentation even within harmonized EU frameworks.
Boutique fitness studios and direct-to-consumer subscription models are displacing traditional supermarket dominance in premium coconut water acquisition. London and Amsterdam urban consumers increasingly source through specialized health platforms and gym-affiliated retail, bypassing conventional grocery slotting fees. This channel rotation is most pronounced among 25-40 year old consumers in metropolitan UK and Benelux markets.
Europe Coconut Water Market Segmentation
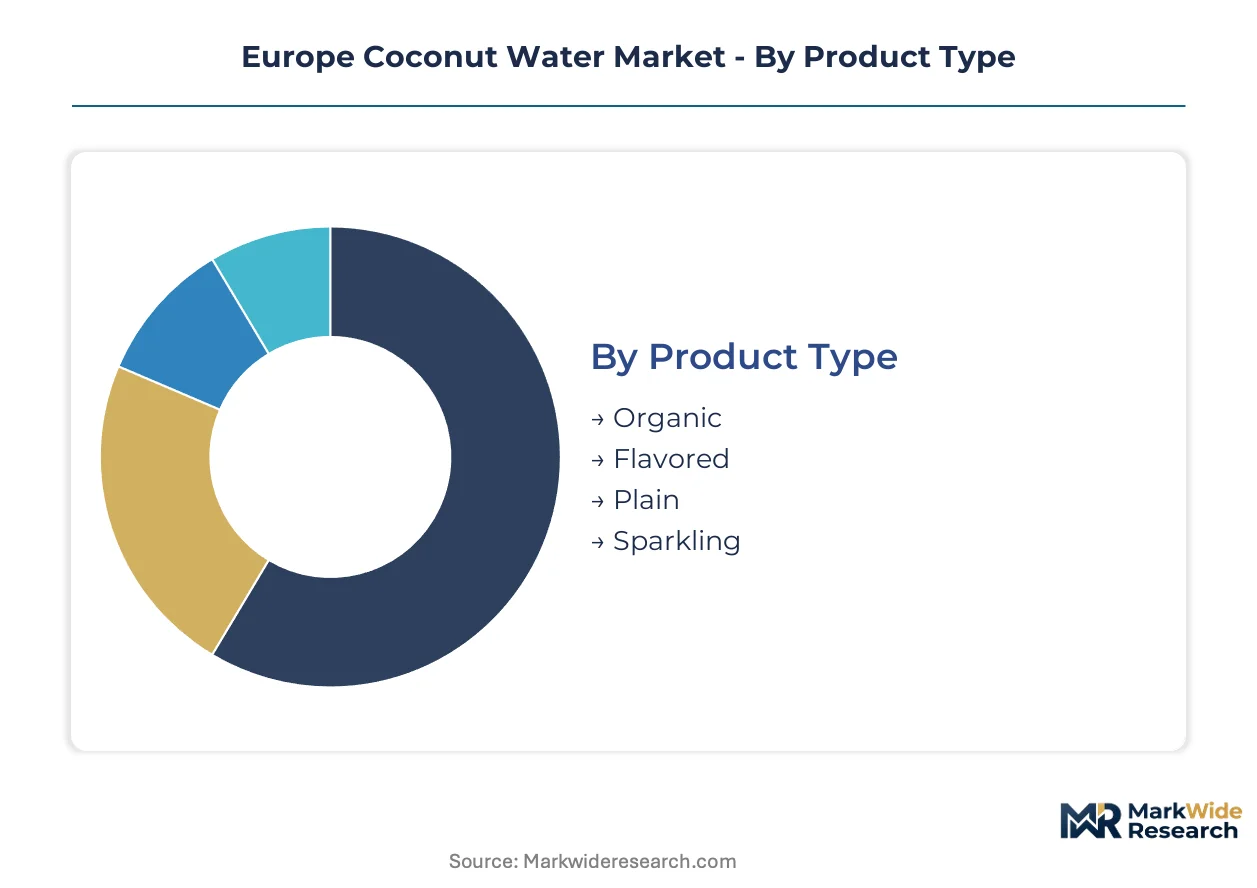
Segmentation in the Europe coconut water market reveals how health positioning, packaging technology, and channel access combine to create distinct margin pools. Understanding these divisions exposes where premium extraction succeeds and where volume commoditization threatens returns.
Product Type:
Integration depth varies sharply: plain and organic variants function as standalone hydration products with minimal processing, while flavored and sparkling formats embed coconut water into broader beverage systems competing with functional drinks and mixers.
- Organic:Certified production under EU organic regulations commands shelf space in German health stores and French bio-specialists. French consumers in Paris and Lyon drive disproportionate volume through ANSM-compliant labeling that signals purity. REACH-compliant packaging adhesives add fixed costs that filter out smaller traders.
- Plain:Unadulterated coconut water with 4-6 degrees brix serves as the category reference point for electrolyte content and taste neutrality. German fitness clubs in Berlin and Munich stock plain variants as post-workout standard, anchoring price expectations for the entire segment.
- Flavored:Infusions with tropical or botanical notes target younger demographics in UK urban centers through specialized health platforms.
- Sparkling:Carbonated formats compete in the non-alcoholic mixer category at Amsterdam and London bars seeking cocktail alternatives.
Volume placements concentrate in Plain; the faster expansion belongs to Organic.
Packaging Type:
Cost tier separation dominates: Tetra Pack and canned formats occupy economy and standard price bands, while glass bottles and pouches extract premiums through material differentiation and portion control.
- Tetra Pack:Aseptic cartons with bio-based barrier layers dominate ambient distribution across EU supermarkets. ECHA's updated candidate list forces reformulation cycles among suppliers, compressing margins for brands dependent on scale.
- Glass Bottle:Premium positioning in Paris, London, and Amsterdam restaurants extracts margins unavailable in grocery. Higher transport costs through KBA-adjacent German regulations limit geographic reach.
- Canned:Aluminum formats suit convenience store placement in Polish and Romanian retail expansion zones.
- Pouch:Flexible packaging targets on-the-go consumption in UK and Benelux direct-to-consumer subscription models.
Volume placements concentrate in Tetra Pack; the steepest expansion trajectory belongs to Glass Bottle.
Distribution Channel:
Customer type segmentation separates institutional buyers from individual consumers: supermarkets and health stores serve planned purchase behavior, while online retail and convenience stores capture impulse and replenishment occasions.
- Supermarkets:Shelf space allocation in Carrefour, REWE, and Tesco systems determines brand visibility for mass-market penetration. Slotting fee structures favor established players with refrigerated logistics capabilities.
- Health Stores:DM, Holland & Barrett, and independent bio-specialists curate premium organic assortments with trained staff recommendation. German and French consumers pay 30-40% premiums for cold-chain assured products.
- Online Retail:Direct-to-consumer platforms bypass conventional grocery fees in UK and Netherlands metropolitan markets.
- Convenience Stores:Grab-and-go placement targets commuter corridors in London and Amsterdam with smaller format SKUs.
Volume placements concentrate in Supermarkets; the fastest share gain belongs to Online Retail.
End User:
Application maturity separates established use cases from emerging adoption: athletes and health enthusiasts represent developed demand with clear functional expectations, while general consumers and restaurants show expanding but less defined usage patterns.
- Health Enthusiasts:Consumers prioritizing clean-label nutrition drive organic certification requirements and HPP technology adoption. German and French urban populations aged 25-40 source through specialized platforms with subscription loyalty.
- Athletes:Sports-specific hydration needs anchor potassium and sodium content marketing in Berlin and Munich boutique fitness studios. Post-workout placement competes directly with PepsiCo and Coca-Cola electrolyte beverages.
- General Consumers:Mainstream grocery shoppers in UK and Benelux purchase on promotion with limited brand loyalty.
- Restaurants:High-end foodservice in Paris, London, and Amsterdam adopts coconut water for cocktail bases and non-alcoholic pairings.
Volume placements concentrate in Health Enthusiasts; the most rapid expansion belongs to Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious consumers in Germany and France generate the bulk of European coconut water demand, while regulatory pressure from Brussels reshapes packaging standards across the continent. Cold-chain logistics networks now extend into Central Europe, unlocking new consumption clusters.
Germany
Berlin and Munich boutique fitness studios anchor post-workout coconut water placement, with health clubs driving volume through specialized sports retail channels. KBA-adjacent transport regulations govern refrigerated goods distribution, adding compliance layers for cross-border shipments. Bavaria's cold-chain infrastructure supports wider raw, unpasteurized variant availability.
France
Paris and Lyon consumers disproportionately favor organic-certified products through bio-specialist retailers, paying premiums for ANSM-compliant labeling. ANSM labeling requirements exceed baseline EU standards, forcing SKU-specific formulation for the French market. Île-de-France hosts the densest concentration of high-end restaurants adopting coconut water for cocktail bases.
United Kingdom
London and Amsterdam metropolitan consumers source increasingly through direct-to-consumer health platforms and gym-affiliated retail, bypassing conventional grocery slotting. EFSA health claim protocols shape permissible marketing language on electrolyte content. Southeast England logistics hubs enable rapid replenishment of subscription-based delivery models.
Netherlands
Amsterdam's foodservice sector leads non-alcoholic pairing innovation, with bars extracting margin premiums unavailable in grocery channels. REACH chemical compliance costs embed into import structures for Rotterdam-port arrivals. Randstad distribution networks facilitate Benelux-wide cold-chain coverage for premium chilled formats.
Poland
Warsaw and Krakow retail expansion shows rising health-conscious consumption with limited premium organic penetration, creating first-mover opportunities. EU Green Deal packaging directives apply equally despite later-stage market development. Central European warehousing investments reduce lead times for ambient Tetra Pack distribution.
Europe Coconut Water Market Key Industry Players
Southeast Asian producers anchor the supply-side tier; European specialists and North American brand-owners hold distribution and marketing positions. The vendor base separates into three strategic archetypes: vertically integrated plantation-to-shelf operators, brand licensors with outsourced manufacturing, and private-label suppliers serving supermarket chains. Competitive moves concentrate on organic certification acquisition and refrigerated logistics partnerships.
Within the brand-owner tier, The Vita Coco Co. Inc. and Harmless Harvest occupy positions exemplifying divergent channel strategies—mass retail penetration versus premium cold-chain specialization. Green Coco Europe anchors the European specialist archetype through organic certification focus. GraceKennedy Ltd. represents the plantation-origin integrated model. Chi sits within the challenger brand category targeting urban health platforms.
| Leading Market Players |
|---|
| Harmless Harvest |
| GraceKennedy Ltd. |
| The Vita Coco Co. Inc. |
| Chi |
| Green Coco Europe |
| PepsiCo Inc. |
| Goya Foods Inc. |
| Helios Ingredients Ltd. |
| The Coca-Cola Co. |
| Others |
Cost & Logistics Intelligence
Captive supply of Indonesian and Philippine coconut plantations anchors the supply position of premium European brands while simultaneously constraining their pricing power against ambient-format commodity competitors. REACH compliance costs and cold-chain logistics investments embed fixed cost layers that stratify pricing tiers across organic-certified and conventional variants.
Pricing Analysis
Volume placements concentrate in economy Tetra Pack tiers while margin extraction concentrates in organic glass bottle formats serving Paris and Amsterdam restaurants. Price differentiation hinges on EU organic certification grade and refrigerated delivery assurance, with German health store consumers paying substantial premiums for cold-chain integrity. Cost compression in ambient distribution channels is intensifying because ECHA-mandated packaging reformulation cycles compress supplier margins. Mainstream supermarket shoppers exhibit highest price sensitivity; boutique fitness studios and foodservice buyers show lowest sensitivity to per-unit pricing.
Supply Chain Analysis
Raw coconut supply rests on Indonesian, Philippine, and Sri Lankan harvest seasons with concentrated monsoon-dependent yield patterns. Aseptic carton barrier coatings, HPP processing equipment, and refrigerated transport containers constitute critical input dependencies. Single-source vulnerability in Southeast Asian plantation networks exposes brands to climate-induced supply shocks. Distribution runs through Rotterdam and Hamburg port hubs into specialized cold-chain networks serving Benelux and German retail clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization requirements and EU Green Deal packaging mandates construct a cost-of-compliance moat that filters out undercapitalized entrants while rewarding early-adopter incumbents with preferential retail listings.
For Market Incumbents: Deploy cold-chain logistics partnerships as the defensive anchor. Secure exclusive refrigerated slotting agreements with REWE and Carrefour systems before competitor capacity expansion. Accelerate organic certification acquisition to exploit 12-18 month validation delays facing challengers. Counter sports drink substitution threats from PepsiCo and Coca-Cola through boutique fitness studio exclusivity arrangements. For New Entrants and Emerging Players: Boutique fitness subscription platforms offer the most penetrable channel wedge for bypassing supermarket slotting fee barriers. Polish and Romanian retail expansion zones present white-space opportunities with limited premium organic penetration and rising health-conscious consumption. Foodservice cocktail-base positioning in Amsterdam and London bars enables margin extraction unavailable in grocery channels. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by North American brand-owners seeking European distribution infrastructure. Long-term viability favors vertically integrated plantation-to-shelf operators with captive supply and REACH-compliant packaging capabilities. Monitor ECHA candidate list revisions as the critical inflection signal for forced reformulation cycles and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Acquisition | EU organic label validation creates 12-18 month barriers that freeze competitor working capital. |
| Cold-Chain Logistics Partnership | Refrigerated transport agreements with KBA-compliant carriers secure German market access. |
| Bio-Based Packaging Transition | Tetra Pack barrier layer reformulation ahead of EU Green Deal enforcement timelines protects margin. |
| Foodservice Channel Development | Amsterdam and Paris restaurant placements extract premiums unavailable in conventional grocery. |
| Central European Retail Expansion | Polish and Romanian distribution builds first-mover position in underserved health-conscious markets. |
Research Approach
Independent corroboration across brand managers at coconut water importers, category buyers at German and French retailers, cold-chain logistics operators, and organic certification auditors underwrites the qualitative findings. Primary interviews with supply planners and channel sales heads combined with secondary validation from ECHA regulatory filings, EU customs trade data, and Nielsen retail audit records. Bottom-up volume triangulation against top-down value estimates anchored the market sizing framework.
Comparable historical periods spanning pre- and post-REACH implementation phases anchored the forecast window calibration. The analytical framework modeled volume and value outputs across product type, packaging format, distribution channel, and end-user segmentation dimensions throughout the projection horizon. CAGRs derived from weighted regression of import volume trends, organic certification growth curves, and refrigerated logistics capacity expansion. Industry-specific inputs included coconut harvest yield volatility indices and ECHA candidate list substance restriction timelines.
Several conditions sit outside the modeled scope, including abrupt climate shocks to Southeast Asian plantation regions, sudden REACH substance bans without transition periods, and currency dislocation in euro-zone import markets. Forecasts reflect documented assumptions about regulatory enforcement pacing and cold-chain infrastructure buildout rates. A small set of named triggers warrants ongoing watch: ECHA packaging adhesive authorization revisions, EU Green Deal recyclability threshold finalization, and KBA transport regulation amendments affecting cross-border refrigerated shipments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Sparkling Water Market
Beverages
Sports Drink Market
Beverages
US and Canada Tonic Water Market
Beverages
Japan Kombucha Market
Beverages
United States Soy Beverages Market
Beverages
Caffeinated Beverage Market
Beverages
Sports and Energy Drinks Market
Beverages
Chocolate Malt Drink Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
Commercial Sparkling Water Dispenser Market
Beverages
Recovery Drinks Market
Beverages
Hydrogen Water Bottle Market
Beverages
Rose Floral Water Market
Beverages
India Sports Drinks Market
Beverages
North America Dairy Beverages Market
Beverages
Fermented Drinks Market