
 Kids Food and Beverages Market | 2026-2036
Kids Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Food and Beverages Market Foresight
Multi-pack bundling of single-serve pouches and mini-bottles is consolidating buyer choice around convenience-driven pantry loading. The Hershey Company leverages its chocolate production infrastructure to dominate portion-controlled treat formats. Danone North America anchors its position through fermented dairy specialization for pediatric nutrition. Chobani competes with strained yogurt innovations designed for school lunch compatibility.
Kids food and beverages encompass nutrient-modified, portion-scaled, and sensory-optimized edible products formulated for consumers aged two to twelve, typically featuring reduced sodium profiles below 140mg per serving, fortified micronutrient matrices, and texture engineering for developing palates. Snacks and dairy command the dominant margin pools due to higher permissible price points and repeat purchase frequency. Pouch packaging across fruit and savory segments captures the fastest growth trajectory as parents prioritize mess-free portability. Online retail distribution is expanding fastest among channels, though supermarkets sustain the volume base through impulse-driven checkout placement.
FDA nutrition labeling mandates and USDA school meal standards jointly constrain permissible sugar thresholds and sodium ceilings in products targeting institutional channels. The EPA regulates pesticide residue tolerances in fruit-based offerings, directly affecting supplier qualification for organic-positioned lines. Stakeholders must monitor evolving state-level sugar tax proposals and school procurement localization trends to anticipate channel access shifts.
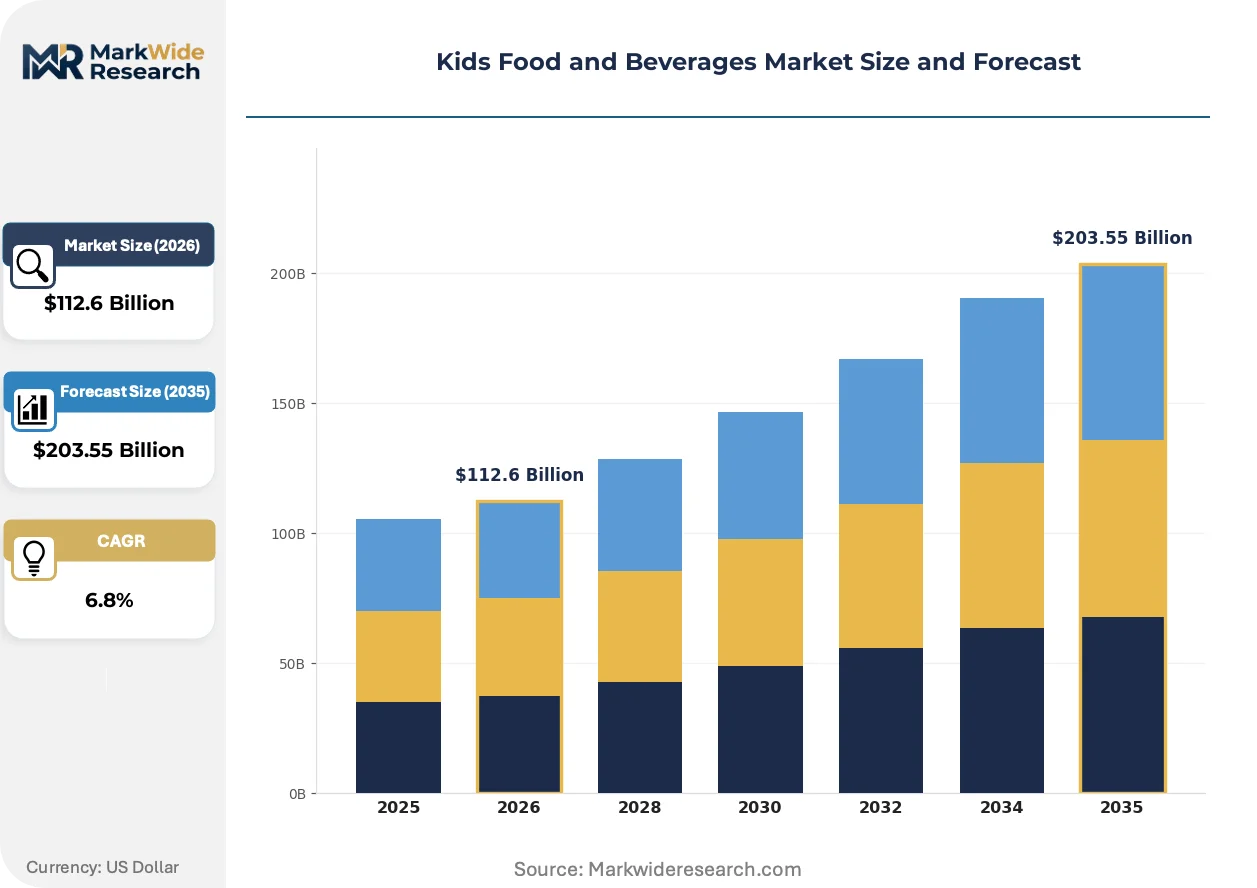
Market Dynamics
Dual-income household time compression is consolidating purchase decisions around portable, portion-controlled formats that minimize preparation friction while satisfying institutional nutrition standards.
Growth Catalysts
- FDA Nutrition Facts overhauls:Mandatory added-sugar disclosure is forcing reformulation across juice and cereal portfolios, creating first-mover advantages for brands with clean-label pipelines already in development.
- USDA school meal localization:District-level procurement autonomy is expanding addressable market for regional suppliers meeting sodium and whole-grain thresholds without national distribution scale.
- Pouch packaging chemistry advances:High-barrier film innovations extending ambient shelf life without preservatives are unlocking new savory and dairy applications previously limited to refrigeration.
Market Restraints
- Organic fruit concentrate supply:EPA pesticide tolerance enforcement has reduced qualified US orchard acreage by tightening residue standards for suppliers seeking organic certification.
- Single-serve format cost premiums:Miniaturized packaging runs carry 40-60% higher per-unit conversion costs versus bulk formats, compressing margins at price-sensitive retail tiers.
- Sugar tax jurisdictional fragmentation:State and municipal proposals in California, Colorado, and Washington create compliance patchwork that complicates national SKU rationalization.
Strategic Opportunities
- Subscription direct-to-pantry models:Auto-replenishment platforms bypass slotting fee barriers while capturing recurring revenue from time-constrained parent segments.
- Plant-based dairy hybridization:Pea-oat protein blends meeting USDA Child and Adult Care Food Program guidelines open institutional channel access previously blocked by allergen restrictions.
- Smart packaging integration:NFC-enabled pouches linking to gamified nutrition education are differentiating premium tiers in South Korean and Japanese test markets.
Industry Challenges
- Pediatric formulation expertise scarcity:Food science programs graduating fewer specialists in micronutrient bioavailability for developing metabolisms than industry replacement demand requires.
- Co-manufacturer qualification timelines:FDA preventive controls and supplier verification protocols extend new production partner onboarding to 18-24 months, constraining capacity scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Food and Beverages Market |
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Juices, Dairy, Cereal Flavor Profile: Fruit, Chocolate, Savory, Spicy Packaging Type: Pouches, Bottles, Boxes, Tubs Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops |
| Companies Covered | The Hershey Company, Lunchly, Danone North America, Lotus Bakeries, Kellanova, Chobani, Red Bull, Goodles, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Food and Beverages Market Shifts & Advancements
Reformulation science and packaging engineering are converging to resolve the historical trade-off between nutritional density and sensory acceptance in products targeting developing palates.
Aseptic filling technology is modularizing production economics for small-batch savory pouches. Regional dairy processors are adopting skid-mounted systems to enter adjacent fruit-vegetable categories without dedicated plant investment. This distributed manufacturing model is compressing minimum viable scale thresholds and enabling faster flavor iteration cycles against mass-market incumbents.
EFSA novel food ingredient approvals are accelerating European access to fermented fiber and microbiome-targeted additives. Manufacturers reformulating for reduced sugar are substituting these ingredients to maintain mouthfeel and satiety signaling previously delivered by sucrose. The regulatory pathway, while lengthier than GRAS self-determination, is creating defensible IP positions for early filers in pediatric gut-health positioning.
Pantry-loading behavior among suburban dual-income households is consolidating weekly purchase decisions into fewer, larger-format transactions. Club and online channels are capturing this shift through multi-week variety packs, displacing single-unit impulse purchases at conventional supermarket checkouts. This concentration is most pronounced in coastal metropolitan corridors where delivery density supports subscription economics.
Kids Food and Beverages Market Segmentation
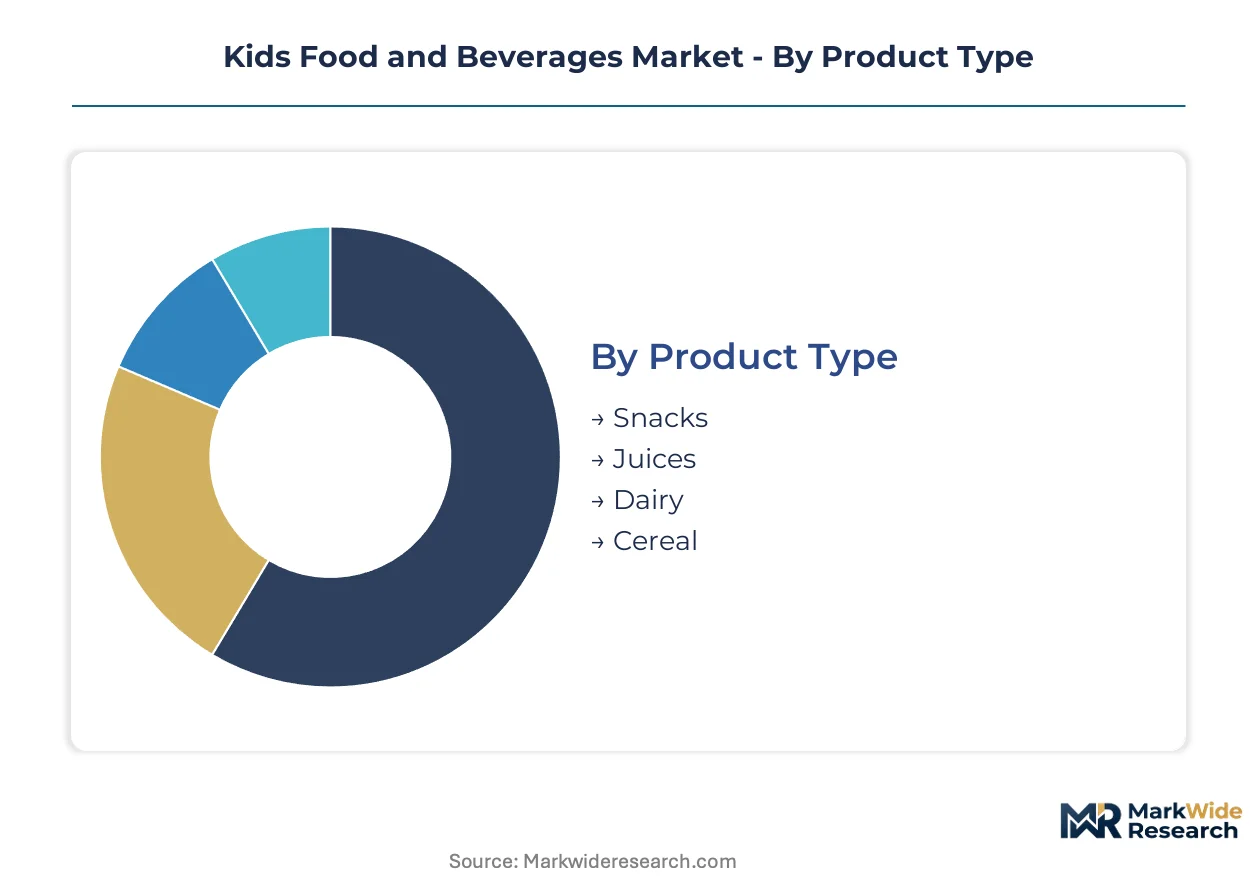
Segmentation in kids food and beverages reveals how reformulation pressures and packaging innovation create divergent margin profiles across product categories. Understanding these partitions exposes where dual-income households concentrate spending and where institutional procurement standards reshape supplier viability.
Product Type:
Upgrade cycles in this category track pediatric nutrition science advances and school meal program revisions that disqualify legacy formulations.
- Snacks:Portion-controlled formats featuring sub-140mg sodium profiles and whole-grain bases dominate preschool and early elementary procurement. Pouch packaging of fruit and savory varieties captures suburban pantry-loading behavior as parents prioritize mess-free portability for school lunch compatibility.
- Dairy:Fermented and strained yogurt innovations fortified with micronutrient matrices command premium price points through repeat purchase frequency. USDA Child and Adult Care Food Program compliance requirements drive reformulation of sugar-reduced lines to maintain mouthfeel without sucrose.
- Juices:Added-sugar disclosure mandates under FDA Nutrition Facts overhauls force clean-label pipeline development. EPA pesticide tolerance enforcement constrains organic fruit concentrate supply from qualified US orchard acreage.
- Cereal:Sodium ceilings and whole-grain thresholds in institutional channels compress margins for reformulation-heavy portfolios. District-level procurement autonomy expands addressable market for regional suppliers without national distribution scale.
Snacks sit at the top of the volume ranking, with dairy climbing the fastest.
Flavor Profile:
Cost tier differentiation separates premium sensory-engineered lines from economy formulations targeting price-sensitive retail tiers.
- Fruit:Natural and artificial flavor systems engineered for developing palates, with high-barrier film innovations extending ambient shelf life without preservatives in pouch applications.
- Chocolate:Portion-controlled treat formats leveraging existing production infrastructure, constrained by sugar tax proposals across California, Colorado, and Washington creating compliance patchwork.
- Savory:Aseptic filling technology modularization enables small-batch regional production without dedicated plant investment, compressing minimum viable scale thresholds.
- Spicy:Emerging acceptance in older pediatric demographics drives limited SKU experimentation, primarily through ethnic food specialty channels.
Fruit flavors anchor volume share, while savory applications expand most quickly through pouch packaging chemistry advances.
Packaging Type:
Customer type segmentation distinguishes convenience-driven subscription purchasers from impulse-driven supermarket shoppers.
- Pouches:High-barrier film technology unlocking savory and dairy applications previously limited to refrigeration, with NFC-enabled variants differentiating premium tiers in South Korean and Japanese test markets.
- Bottles:Mini-bottle formats carry 40-60% higher per-unit conversion costs versus bulk alternatives, compressing margins at price-sensitive retail tiers while serving on-the-go consumption.
- Boxes:Multi-pack bundling for pantry-loading behavior in club and online channels, displacing single-unit impulse purchases at conventional supermarket checkouts.
- Tubs:Larger-format yogurt and snack containers capturing weekly purchase consolidation among suburban dual-income households with refrigerator capacity.
Pouches lead volume growth trajectory, with bottles maintaining stable share through convenience store distribution.
Distribution Channel:
Maturity gradients separate established supermarket infrastructure from rapidly scaling digital fulfillment networks.
- Supermarkets:Checkout placement sustains impulse-driven volume base despite share erosion, with slotting fee barriers protecting incumbent positions.
- Online Retail:Auto-replenishment platforms bypass slotting fees while capturing recurring revenue from time-constrained parent segments, expanding fastest among all channels.
- Convenience Stores:Single-serve format concentration serves immediate consumption occasions, though limited refrigerated space constrains dairy assortment depth.
- Specialty Shops:Organic and allergen-free positioning attracts premium pricing, with localized procurement trends favoring regional supplier qualification.
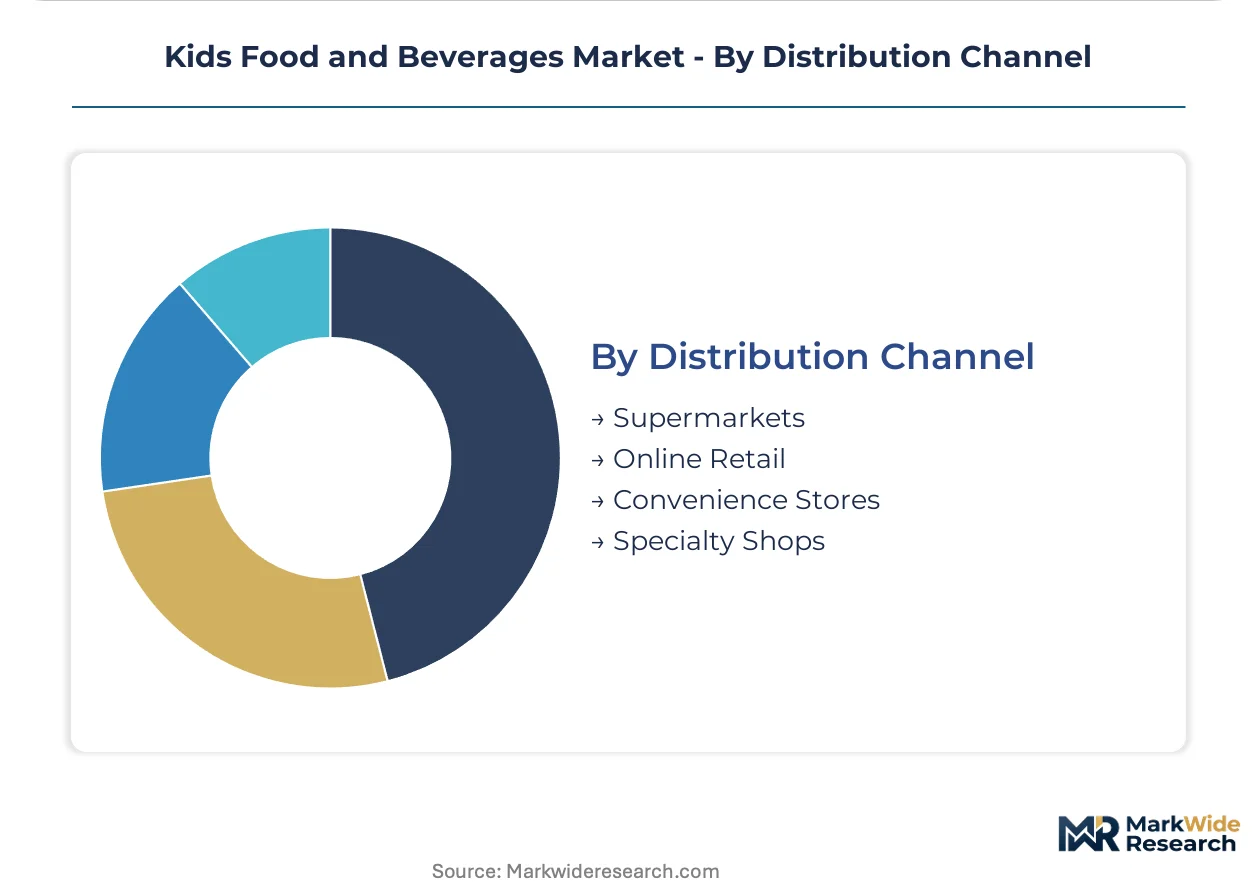
Supermarkets retain volume leadership, while online retail gains share fastest through subscription direct-to-pantry models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The kids food and beverages industry traces its modern origins to post-war United States food processing innovations, where mass-market cereal and juice concentrate technologies first scaled for pediatric consumption. Institutional procurement standards and dual-income household time compression subsequently drove geographic specialization around regulatory hubs and dairy processing clusters.
United States
Dual-income household density in coastal metropolitan corridors concentrates demand for portable, portion-controlled formats designed for school lunch compatibility. FDA Nutrition Facts labeling mandates for added sugars and USDA school meal sodium ceilings jointly constrain permissible formulations for institutional channel access. Chicago and Minneapolis-St. Paul anchor dairy processing infrastructure serving national distribution networks.
China
Urban middle-class expansion in tier-one cities generates premiumization demand for imported and domestically produced pediatric nutrition lines. SAMR food safety registration requirements and GB standards for infant formula create compliance barriers favoring established processors with in-house laboratory capabilities. Yangtze River Delta manufacturing clusters around Shanghai specialize in aseptic pouch filling technology for fruit and dairy applications.
Germany
Organic and clean-label positioning commands shelf space through retailer sustainability commitments and parental allergen avoidance preferences. EFSA novel food ingredient approvals accelerate European market access for fermented fiber additives in reduced-sugar reformulations. Bavaria and North Rhine-Westphalia host dairy cooperatives with integrated pediatric nutrition R&D facilities.
Japan
Declining birth rates intensify competition for per-capita spending on premium functional foods targeting developmental nutrition. METI standards for food for specified health uses (FOSHU) create a regulated pathway for micronutrient-fortified claims. Tokyo-Osaka corridor distribution networks prioritize convenience store penetration for single-serve format availability.
Brazil
Informal sector consumption and formal retail expansion create bifurcated demand for economy and premium pediatric snack tiers. ANVISA nutrition labeling regulations align with Mercosur harmonization efforts, simplifying cross-border formulation strategies. São Paulo state concentrates food processing capacity serving Southeast regional consumption clusters.
Kids Food and Beverages Market Competitive Landscape
The competitive structure tilts toward diversified food conglomerates with pediatric portfolio extensions rather than pure-play specialists. National brand recognition and supermarket slotting fee barriers protect incumbent positions against regional challengers. Two strategic archetypes dominate: chocolate and confectionery processors leveraging existing production infrastructure for portion-controlled treat formats, and dairy specialists anchoring positions through fermented and strained yogurt innovations. Competitive moves concentrate on reformulation pipeline development for clean-label compliance and pouch packaging capacity expansion for savory category entry.
Among North American market participants, The Hershey Company and Danone North America exemplify contrasting archetype strategies, while Chobani occupies a position within the strained yogurt specialization tier. The Hershey Company represents the confectionery infrastructure leverage model, Danone North America anchors the fermented dairy nutrition positioning, and Chobani exemplifies school lunch compatibility innovation. These three entities collectively illustrate how distinct production capabilities and distribution relationships shape competitive differentiation in institutional and retail channels.
| Leading Market Players |
|---|
| The Hershey Company |
| Lunchly |
| Danone North America |
| Lotus Bakeries |
| Kellanova |
| Chobani |
| Red Bull |
| Goodles |
| The Coca-Cola Company |
| Others |
Supply & Pricing Matrix
Dual-income suburban households consolidating weekly purchases into fewer transactions anchor pricing power with club and online channels, compressing margins for single-serve formats while rewarding multi-pack bundling economies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA-compliant organic-positioned lines from conventional reformulations and private-label alternatives. Price differentiation hinges on organic certification grade and pouch packaging technology tier. Cost compression in the single-serve segment is intensifying because miniaturized packaging runs carry higher per-unit conversion costs. Price-sensitive mass-market retail tiers face the greatest margin pressure, while premium subscription channels maintain pricing resilience.
Supply Chain Analysis
Single-source vulnerability sits with organic fruit concentrate supply from qualified US orchard acreage, where EPA pesticide tolerance enforcement has tightened residue standards. Manufacturing draws from dairy processing clusters in the United States, aseptic pouch filling capacity in China, and European fermented additive production. Tariff exposure on high-barrier film imports creates supply chain risk. Distribution runs through supermarket infrastructure sustaining volume base, with online retail expanding fastest through direct-to-pantry subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with dual-income household demand shifting toward clean-label, school-lunch-compatible premium specifications that command repeat purchase frequency.
For Market Incumbents: Deploy reformulation pipeline acceleration to outpace FDA added-sugar disclosure mandates and USDA sodium ceiling revisions. Deepen backward integration into organic fruit concentrate supply to offset EPA-qualified acreage constraints. Co-manufacturer qualification timelines extending to 18-24 months threaten capacity scaling, necessitating captive production investment or long-term partnership lock-ups with qualified aseptic filling operators. For New Entrants and Emerging Players: Launch via subscription direct-to-pantry models to bypass supermarket slotting fee barriers and capture recurring revenue from time-constrained parent segments. White-space concentration sits with plant-based dairy hybridization meeting USDA Child and Adult Care Food Program guidelines, opening institutional channel access previously blocked by allergen restrictions. Regional district-level procurement autonomy favors localized suppliers without national distribution scale. For Investors and Strategic Acquirers: Dairy conglomerates with pediatric portfolio extensions are the most active acquirer in this space, seeking fermented and strained yogurt specialization to complement existing infrastructure. Long-term viability centers on defensible IP positions in clean-label reformulation and high-barrier pouch packaging capacity. Signal to monitor: state-level sugar tax proposal advancement in California, Colorado, and Washington creating compliance patchwork that favors diversified national SKU portfolios over regional specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Pipeline | FDA added-sugar disclosure mandates force first-mover advantage for brands with compliant portfolios. |
| Pouch Packaging Capacity Expansion | High-barrier film technology unlocks savory and dairy applications previously limited to refrigeration. |
| Subscription Direct-to-Pantry Launch | Auto-replenishment platforms bypass slotting fees while capturing recurring revenue from suburban households. |
| Plant-Based Dairy Hybridization | Pea-oat protein blends meeting USDA guidelines open institutional channel access blocked by allergen restrictions. |
| Co-Manufacturer Qualification Acceleration | FDA preventive controls and supplier verification protocols compress new production partner onboarding timelines. |
Research Methodology
Coverage spans the United States, China, Germany, Japan, and Brazil, with primary inputs from each market combining interviews with brand managers, category buyers at retailers, channel sales heads, and supply planners with secondary validation. Data sources include Nielsen retail audit data, FDA filings, USDA school meal program documentation, EPA pesticide tolerance records, and customs trade records. Bottom-up segment modeling and top-down macroeconomic triangulation ensure cross-verified outputs.
Granularity-level modeling operates at product type, flavor profile, packaging format, and distribution channel dimensions, with additional segmentation by institutional versus retail procurement pathway. CAGRs derive from trend-line extrapolation against historical volume trajectories, adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporate dual-income household time-compression indices and school meal program revision schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sugar tax jurisdictional fragmentation and organic concentrate supply disruption scenarios. Projections reflect assumptions about regulatory enforcement consistency and pouch packaging chemistry advancement rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Anti-Spit Up Formula Market
Baby Food and Infant Formula
Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Canada Baby Food Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market
Baby Food and Infant Formula
Human Milk Oligosaccharides in Infant Formula Market
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market