
 Water Flavor Market | 2026-2036
Water Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Water Flavor Market Analytics
Premium natural positioning is unwinding conventional commodity dynamics across the Water Flavor Market. Nestlé leverages its bottled water heritage to anchor European shelf-space dominance in unsweetened variants. PepsiCo competes through R&D intensity on zero-calorie natural flavor systems. The Coca-Cola Company controls mainstream retail velocity with broad distribution infrastructure.
Water flavor denotes liquid or powdered formulations designed to impart taste to still or carbonated water without substantial caloric contribution, typically containing natural or nature-identical flavor compounds, acidulants, and non-nutritive sweeteners at concentrations below beverage thresholds. These products serve commercial purposes spanning consumer hydration enhancement, food service menu customization, and co-manufacturing inputs for branded bottled water extensions. Fruit Infusions occupy the largest margin pool as clean-label positioning justifies price premiums in supermarkets and specialty stores. Beverage Concentrates sustain the fastest volume trajectory among customer types as food service operators and health clubs seek cost-efficient bulk dispensing solutions. Flavor Enhancers in berry and tropical profiles specialize in capturing repeat purchase frequency through seasonal rotation strategies.
The FDA governs ingredient safety and labeling accuracy for water flavor products sold in the United States, while the EPA regulates source water quality standards that underpin product purity claims. The USDA Organic certification creates differentiated market access for brands meeting strict agricultural input requirements. Stakeholders must monitor evolving state-level sugar taxation proposals and shifting retailer shelf-reset policies that favor reduced-sugar assortments.
Market Dynamics
FDA nutrition labeling mandates for added sugars are compressing formulation timelines across the Water Flavor Market, forcing manufacturers to accelerate clean-label transitions before compliance deadlines.
Growth Catalysts
- Health Club Expansion:Fitness-oriented consumers are shifting from sugary sports drinks toward low-calorie flavored hydration, creating dedicated bulk dispensing demand.
- USDA Organic Certification:Premium natural positioning commands stronger consumer willingness to pay in United States supermarkets and specialty stores.
- Food Service Menu Customization:Beverage concentrates enable cost-efficient flavor rotation for restaurants and hospitality operators seeking differentiation.
Market Restraints
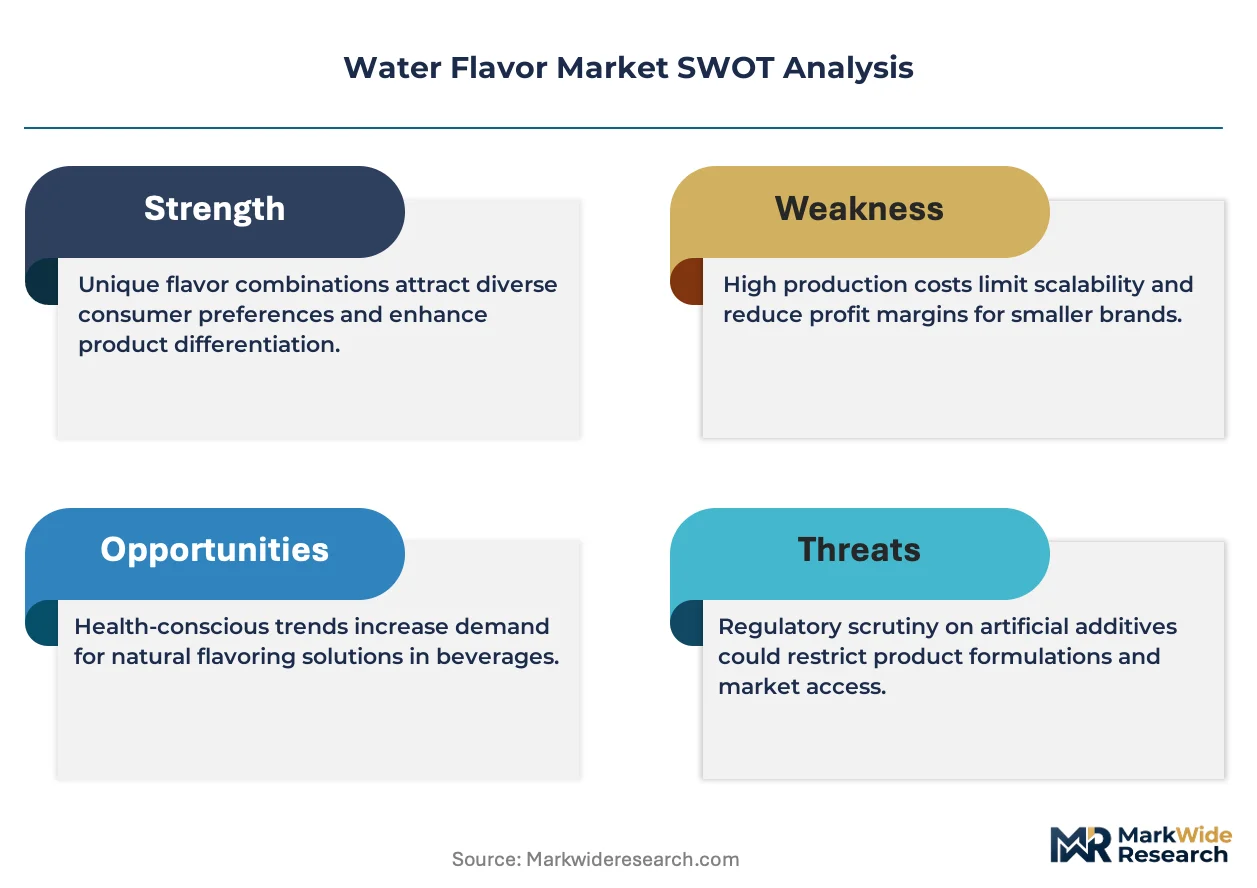
- Natural Flavor Input Volatility:Supply concentration for botanical extracts and nature-identical compounds creates margin pressure during harvest disruptions.
- EPA Source Water Standards:Purity claim verification requires costly testing infrastructure that disadvantages smaller regional entrants.
- Zero-Calorie Sweetener Substitution:Stevia and monk fruit face competition from emerging allulose formulations in adjacent beverage categories.
Strategic Opportunities
- Underpenetrated European Markets:Unsweetened variants show shelf-space gaps outside Nestlé's established strongholds in Germany and France.
- Co-Manufacturing Partnerships:Branded bottled water extensions seek external flavor system suppliers to accelerate line extensions without capex.
- State-Level Sugar Taxation:Proposed levies in California and New York would accelerate consumer migration from sugary alternatives to water flavor products.
Industry Challenges
- Flavor Chemist Talent Scarcity:Formulation expertise for stable natural flavor systems remains concentrated among a limited pool of specialists.
- Clean-Label Certification Timelines:USDA Organic and non-GMO verification processes extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Flavor Market |
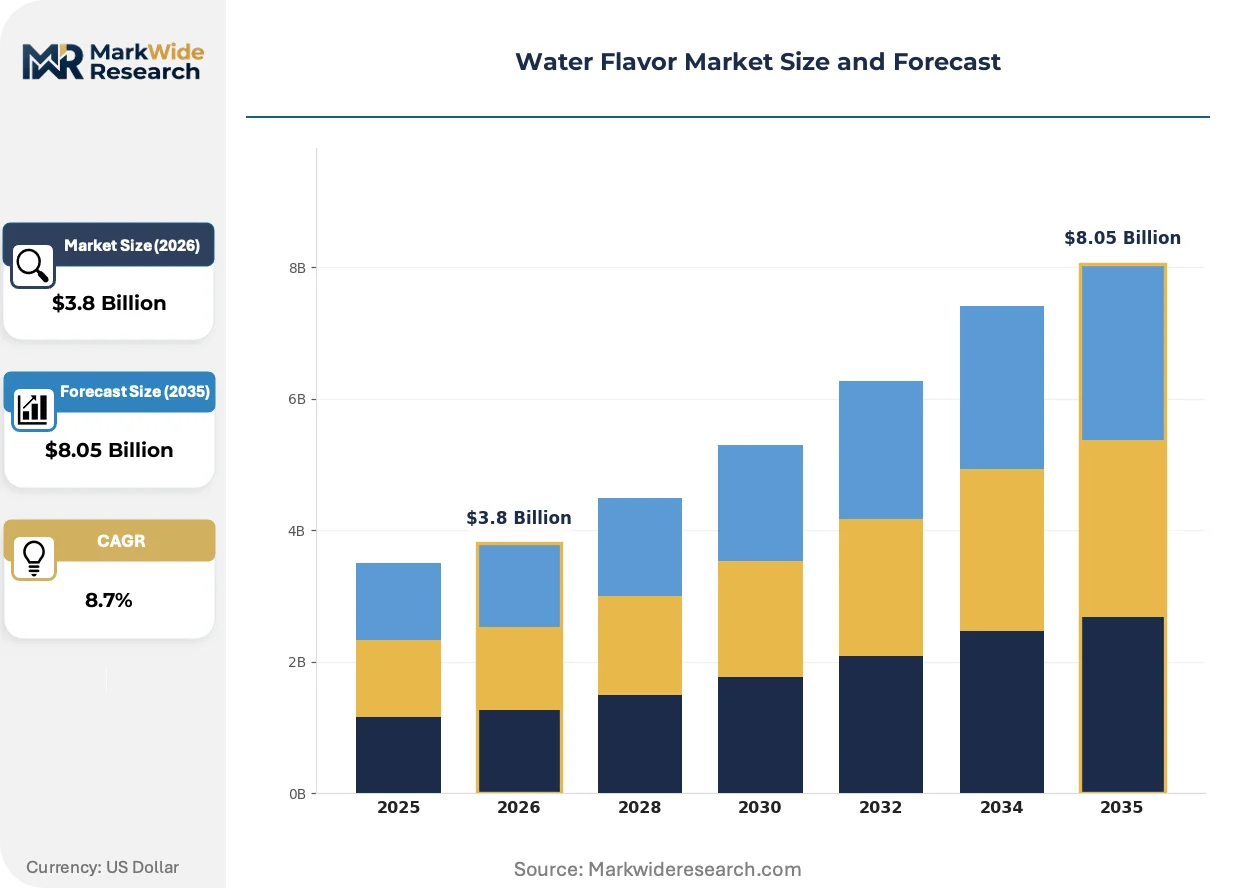
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Infusions, Herbal Extracts, Flavor Enhancers, Beverage Concentrates Customer Type: Retail Consumers, Food Service, Beverage Manufacturers, Health Clubs Flavor Profile: Citrus, Berry, Herbal, Tropical Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Vending Machines |
| Companies Covered | The Coca-Cola Company, PepsiCo, Nestlé, Keurig Dr Pepper, Danone, Hint, National Beverage Corp., Spindrift Beverage Co., Talking Rain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Flavor Market Evolving Landscape
Reformulation pressure is fragmenting competitive advantage away from scale economics toward speed-to-clean-label and proprietary natural extraction capabilities.
Enzymatic flavor extraction is fragmenting conventional solvent-based processing. Health clubs and premium bottled water co-manufacturers are adopting these systems to meet clean-label demands. The technology is fragmenting incumbent supply relationships by enabling smaller producers to match large-scale natural positioning.
REACH chemical registration requirements in Europe are tightening scrutiny on nature-identical flavor compounds. Manufacturers must document full supply chain substance volumes above one ton annually. Fruit infusion specialists targeting EU export markets are accelerating botanical sourcing transparency to maintain shelf access.
Subscription-based replenishment models are displacing traditional retail replenishment cycles for home-use flavor enhancers. Direct-to-consumer channels capture repeat purchase data that informs seasonal rotation strategies. This pattern concentrates in United States metropolitan markets where delivery density supports unit economics.
Water Flavor Market Segmentation
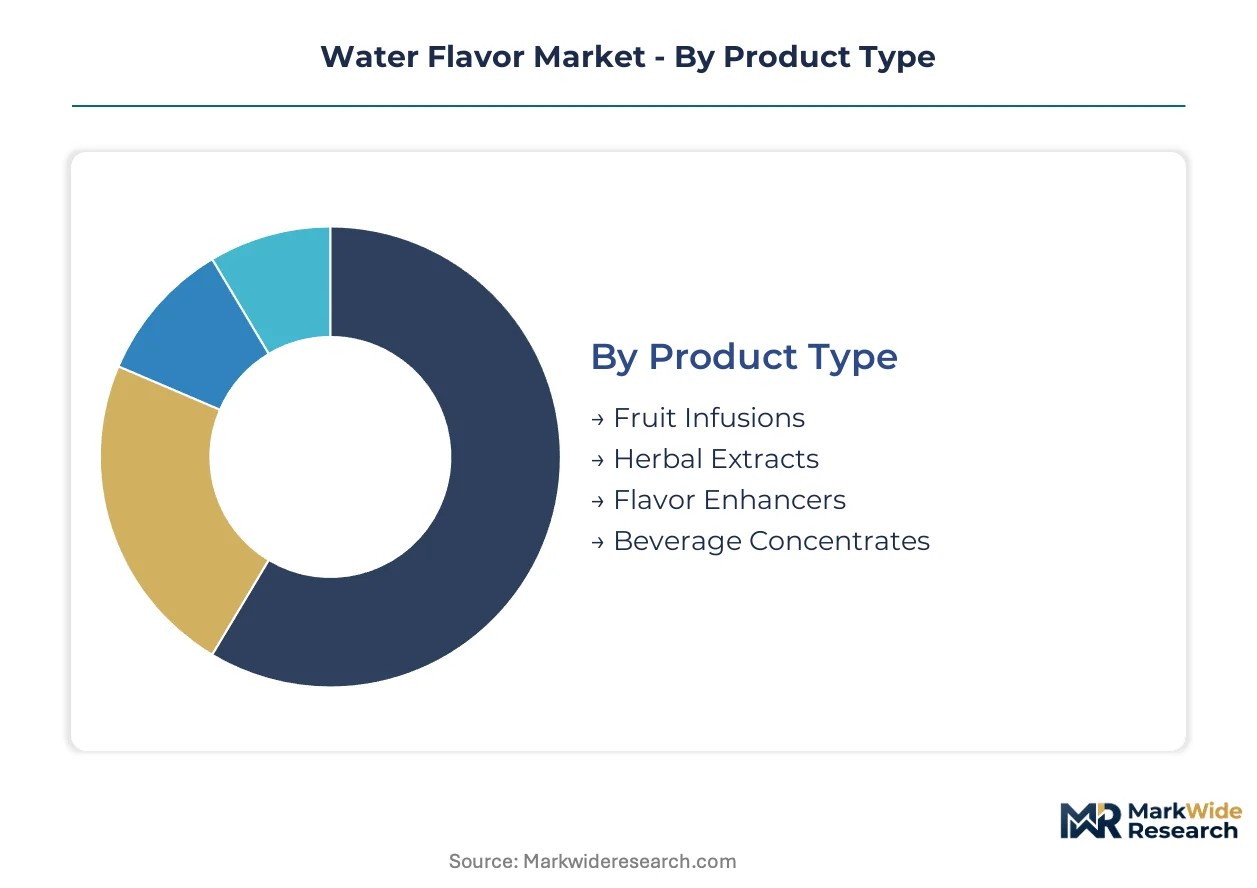
Water flavor segmentation reveals divergent margin structures across formulation types and channel economics. Product architecture and customer procurement patterns determine which segments sustain premium pricing versus commodity pressure.
Product Type:
Domestic production dominates Fruit Infusions and Flavor Enhancers, while Beverage Concentrates serve substantial export demand to food service operators across multiple continents.
- Fruit Infusions:Liquid formulations blending natural fruit essences with acidulants and non-nutritive sweeteners at sub-beverage concentrations. United States supermarkets and specialty stores concentrate demand, driven by clean-label positioning that justifies price premiums.
- Beverage Concentrates:High-potency liquid systems designed for dilution ratios exceeding 1:20, enabling cost-efficient bulk dispensing. Health clubs and European hospitality operators drive fastest expansion as they seek flavor rotation without inventory complexity.
- Herbal Extracts:Botanical-derived flavor systems incorporating chamomile, mint, and lavender compounds for functional positioning.
- Flavor Enhancers:Powdered or liquid additives emphasizing intensity over complexity, typically in single-serve formats.
Fruit Infusions holds the largest share; momentum sits with Beverage Concentrates.
Customer Type:
Procurement sophistication varies sharply—beverage manufacturers negotiate multi-year supply contracts while health clubs prioritize flexible dispensing solutions.
- Health Clubs:Fitness-oriented facilities deploying bulk dispensing systems for member hydration stations. United States metropolitan markets concentrate demand as operators shift from sugary sports drinks toward low-calorie alternatives.
- Food Service:Restaurants, hotels, and catering operations seeking menu differentiation through rotating flavor options. European hospitality chains drive export-led procurement for unsweetened variants.
- Retail Consumers:Individual purchasers through supermarkets and online channels, typically in single-serve or small-format packaging.
- Beverage Manufacturers:Co-manufacturing partners and branded bottled water extensions requiring external flavor system supply.
Retail Consumers maintains volume dominance; Health Clubs climbs fastest on fitness-sector expansion.
Flavor Profile:
Regional preference fragmentation shapes formulation portfolios—citrus dominates North American shelves while tropical profiles penetrate warmer climates.
- Citrus:Lemon, lime, and orange-based formulations leveraging high consumer familiarity and broad demographic acceptance.
- Berry:Strawberry, raspberry, and blueberry compounds capturing repeat purchase frequency through seasonal rotation strategies in United States specialty stores.
- Herbal:Botanical and floral notes targeting wellness-positioned consumers seeking functional hydration benefits.
- Tropical:Mango, pineapple, and coconut profiles specializing in summer-season velocity and warmer-climate penetration.
Citrus anchors volume; Berry gains share fastest on clean-label innovation.
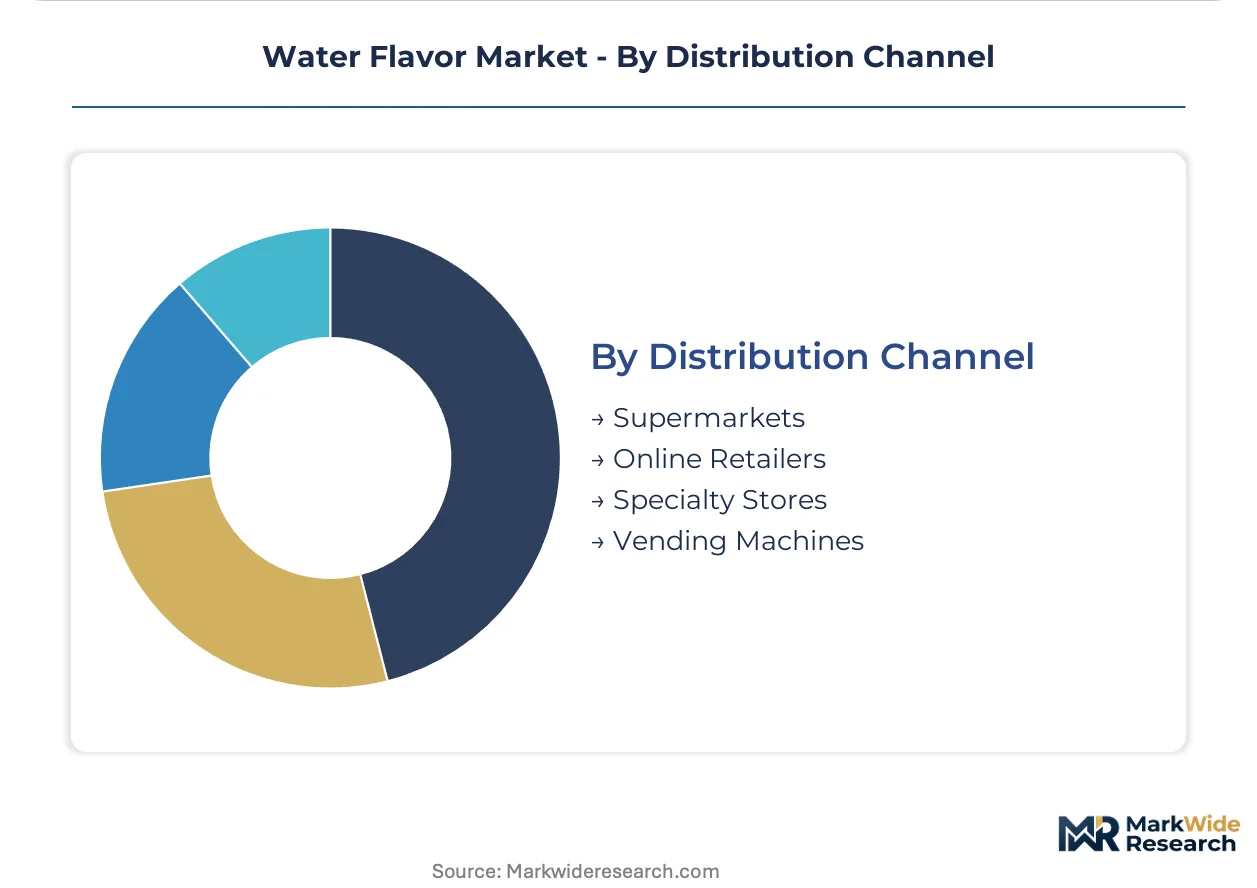
Distribution Channel:
Channel margin structures diverge—supermarkets extract slotting fees while online retail captures subscription-driven lifetime value.
- Supermarkets:Mass-market retail commanding broad shelf placement and promotional velocity. United States chains concentrate demand where premium natural positioning commands strongest willingness to pay.
- Online Retailers:Direct-to-consumer platforms enabling subscription replenishment models. Metropolitan United States markets drive steepest expansion as delivery density supports unit economics.
- Specialty Stores:Health-focused and gourmet retailers emphasizing curated assortment and educational merchandising.
- Vending Machines:Automated dispensing in workplaces, gyms, and transit locations for immediate consumption occasions.
Supermarkets retains the largest footprint; Online Retailers expands most quickly on subscription adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates among three distinct manufacturing clusters. The United States anchors premium natural positioning through FDA labeling mandates. Germany and France sustain European shelf-space dominance. China and India represent emerging production capacity for export-oriented concentrates.
United States
Health club bulk dispensing and subscription-based home replenishment drive metropolitan demand. FDA updated nutrition labeling requirements for added sugars compress manufacturer reformulation timelines. California and New York state-level sugar taxation proposals accelerate consumer migration from sugary alternatives toward low-calorie flavored hydration systems.
Germany
European hospitality chains and food service operators procure unsweetened variants for menu differentiation. REACH chemical registration requirements tighten scrutiny on nature-identical flavor compounds entering EU markets. Bavaria-based bottling facilities anchor Nestlé's regional shelf-space dominance in premium still water extensions.
France
Specialty retailers and gourmet channels emphasize curated flavor assortments with clean-label positioning. EFSA evaluates novel food applications for enzymatic extraction technologies. Paris and Lyon metropolitan clusters concentrate demand for botanical-derived herbal extracts targeting wellness-positioned consumers.
China
Domestic beverage manufacturers seek external flavor system suppliers for branded bottled water line extensions. SAMR enforces national food safety standards on additive concentrations and labeling accuracy. Yangtze River Delta production zones scale beverage concentrate capacity for food service export markets.
India
Urban fitness centers and corporate wellness programs deploy bulk dispensing infrastructure for member hydration. FSSAI regulates ingredient safety and maximum permissible additive levels in flavored water formulations. Maharashtra and Karnataka industrial corridors attract co-manufacturing partnerships from multinational beverage brands.
Water Flavor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Water Flavor Market. Consolidated multinational beverage conglomerates control distribution infrastructure and retail velocity. Mid-sized natural specialists occupy premium positioning through clean-label certification. Emerging enzymatic extraction technology providers enable smaller producers to match large-scale natural positioning. Dominant competitive moves include co-manufacturing partnerships for line extensions and accelerated USDA Organic certification timelines.
Within the multinational tier, The Coca-Cola Company and PepsiCo exemplify divergent strategic positioning—one leveraging broad retail infrastructure, the other competing through R&D intensity on zero-calorie natural flavor systems. Nestlé represents European heritage anchoring through bottled water brand extensions. These three players collectively illustrate how scale, technology investment, and regional brand equity create distinct competitive moats without overlapping positioning.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Nestlé |
| Keurig Dr Pepper |
| Danone |
| Hint |
| National Beverage Corp. |
| Spindrift Beverage Co. |
| Talking Rain |
| Others |
Value Network & Pricing Analysis
USDA Organic certification gates both supply qualification and price differentiation simultaneously in the Water Flavor Market, creating a dual barrier where botanical traceability requirements elevate input costs while commanding shelf-price premiums in United States supermarkets. This regulatory threshold compresses margins for uncertified producers while rewarding verified clean-label positioning with repeat purchase loyalty.
Pricing Analysis
FDA updated nutrition labeling mandates dictate the pricing tier structure across the Water Flavor Market, forcing reformulation investments that stratify manufacturers by compliance readiness. Three-tier pricing structure across premium organic, standard natural, and economy synthetic levels separates USDA-certified botanical extracts from nature-identical compounds and artificial flavor systems. Cost compression in the economy tier is intensifying because health club procurement teams negotiate volume contracts for bulk concentrates. Retail consumers demonstrate highest price sensitivity in single-serve formats, while food service operators accept premium positioning for menu differentiation.
Supply Chain Analysis
Botanical extract sourcing from Madagascar, India, and Turkey anchors supply vulnerability for natural flavor systems in the Water Flavor Market. Stevia leaf cultivation in Paraguay and monk fruit harvesting in southern China feed into nature-identical compound production. Single-source vulnerability concentrates in tropical fruit essence suppliers facing climate-driven harvest disruptions. Distribution runs through co-manufacturing partnerships with branded bottled water extensions, bypassing traditional retail slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity defines the Water Flavor Market as enzymatic extraction technology democratizes clean-label capabilities, enabling smaller producers to challenge incumbent scale advantages. Fitness-sector procurement decentralization and subscription-channel emergence create multiple entry points outside established retail gatekeeping.
For Market Incumbents: Consolidate formulation expertise through captive supply of botanical extraction capabilities, securing flavor chemist talent pools before scarcity intensifies. Accelerate USDA Organic certification pipelines to outpace compliance-driven competitor launches. Nestlé's European shelf-space dominance and PepsiCo's R&D intensity on zero-calorie systems illustrate divergent defensive moats worth extending. For New Entrants and Emerging Players: Lead with enzymatic extraction technology partnerships to match large-scale natural positioning without capital-intensive infrastructure. Target underpenetrated European markets outside Germany and France where unsweetened variants show shelf-space gaps. Deploy direct-to-consumer subscription models in United States metropolitan clusters where delivery density supports unit economics against incumbent retail velocity. For Investors and Strategic Acquirers: California and New York state-level sugar taxation proposals reshape the acquisition landscape, accelerating consumer migration toward low-calorie alternatives that validates water flavor platform investments. Prioritize mid-sized natural specialists with established clean-label certification and health club distribution relationships. Watch FDA enforcement patterns on added sugar disclosure as inflection indicators for reformulation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Technology Adoption | Enables smaller producers to match Nestlé's large-scale natural positioning without solvent-based infrastructure. |
| USDA Organic Certification Acceleration | Compresses launch timelines by 8-14 months while commanding price premiums in United States specialty retail. |
| Health Club Bulk Dispensing Partnerships | Captures fitness-sector procurement shifts away from sugary sports drinks toward low-calorie hydration systems. |
| Direct-to-Consumer Subscription Launch | Displaces traditional retail replenishment cycles through delivery-density economics in metropolitan markets. |
| European Co-Manufacturing Expansion | Addresses shelf-space gaps in unsweetened variants outside Nestlé's established German and French strongholds. |
Research Methodology
Cross-validation between primary interviews with formulation chemists, health club procurement directors, and specialty retail category buyers anchors the qualitative findings against secondary validation from FDA guidance documents, USDA Organic certification databases, and EPA source water quality filings. Bottom-up triangulation aggregates segment-level demand patterns while top-down analysis reconciles macroeconomic consumption trends across the projection horizon.
Sensitivity analysis frames the analytical approach, testing volume and value outputs against varying adoption rates for enzymatic extraction and shifting health club penetration curves. Segmentation dimensions span product type, customer procurement sophistication, flavor profile regional preferences, and distribution channel margin structures. CAGRs derive from fitted growth curves incorporating FDA compliance timeline impacts and state-level sugar taxation probability assessments.
Underlying assumptions cover steady botanical supply availability and health club membership expansion rates, with deviation risk concentrated in harvest disruption events and regulatory enforcement intensity variations. Practitioners should keep alternative scenarios live as FDA labeling compliance deadlines and European REACH registration requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Grape Juice Concentrate for Wine Making Market
Beverages
Europe Animal-Based Food and Beverage Market
Beverages
Mixers Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Electrolyte Mixes Market
Beverages
Vegetable Juice Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
India Sports Drinks Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
Water Bottle Market
Beverages
Fermented Foods and Beverages Market
Beverages
Plant Based Protein Beverages Market
Beverages
South America Energy Drink Market
Beverages
India Bottled Water Market
Beverages
Canned Beverages Market
Beverages
Beverage Multipacks Market