
 Smoothies Market | 2026-2036
Smoothies Market Size, Share, and Industry Trends Forecast 2026-2036
Smoothies Market Intelligence
At-home blending equipment sales is tilting toward commercial prepared formats as convenience-seeking consumers trade kitchen time for grab-and-go nutrition. Bolthouse Farms leverages its agricultural supply chain to anchor cost positions in retail bottled smoothies. PepsiCo, Inc. competes through multi-brand portfolio breadth spanning juice, dairy, and functional beverage aisles. Innocent Drinks differentiates via ethical sourcing narratives and transparent ingredient storytelling across European retail channels.
A smoothie is a blended beverage typically comprising fruit, vegetable, dairy or plant milk, ice, and optional functional additives such as protein isolates, fiber, or probiotics, processed through high-shear blending to achieve homogeneous texture without heat degradation of heat-labile vitamins. Its primary commercial purpose is delivering convenient, nutrient-dense refreshment aligned with wellness-oriented consumption patterns. Fruit-based formulations dominate volume due to established palatability and color appeal, while protein-enhanced variants capture disproportionate margin as athletic and aging demographics seek macronutrient fortification. Pouch packaging is gaining traction in on-the-go channels for portability and reduced material weight relative to bottles.
The FDA governs smoothie labeling under beverage regulations, requiring accurate serving-size declarations and allergen alerts that shape formulation and packaging communication strategies. The USDA Organic certification and EU Organic Regulation create tiered market access where certified products command shelf placement advantages in premium retail. The EU Green Deal packaging directives are accelerating shifts toward recyclable mono-material structures. Stakeholders must monitor evolving front-of-pack labeling schemes across jurisdictions, as these schemes increasingly influence consumer choice architecture and reformulation priorities.

Market Dynamics
Clean-label regulatory tightening across multiple jurisdictions is forcing simultaneous reformulation, supply chain requalification, and packaging redesign throughout the smoothie value chain.
Growth Catalysts
- EU Green Deal packaging directives:Mono-material recyclable structures are unlocking shelf placement in premium European retail channels committed to circular economy targets.
- Fitness center channel expansion:Post-workout nutrition habits are shifting toward ready-to-drink formats as gym chains build captive beverage retail into membership ecosystems.
- USDA Organic certification tier:Certified products command disproportionate margin capture in United States coastal metropolitan clusters where health-conscious consumers pay ingredient transparency premiums.
Market Restraints
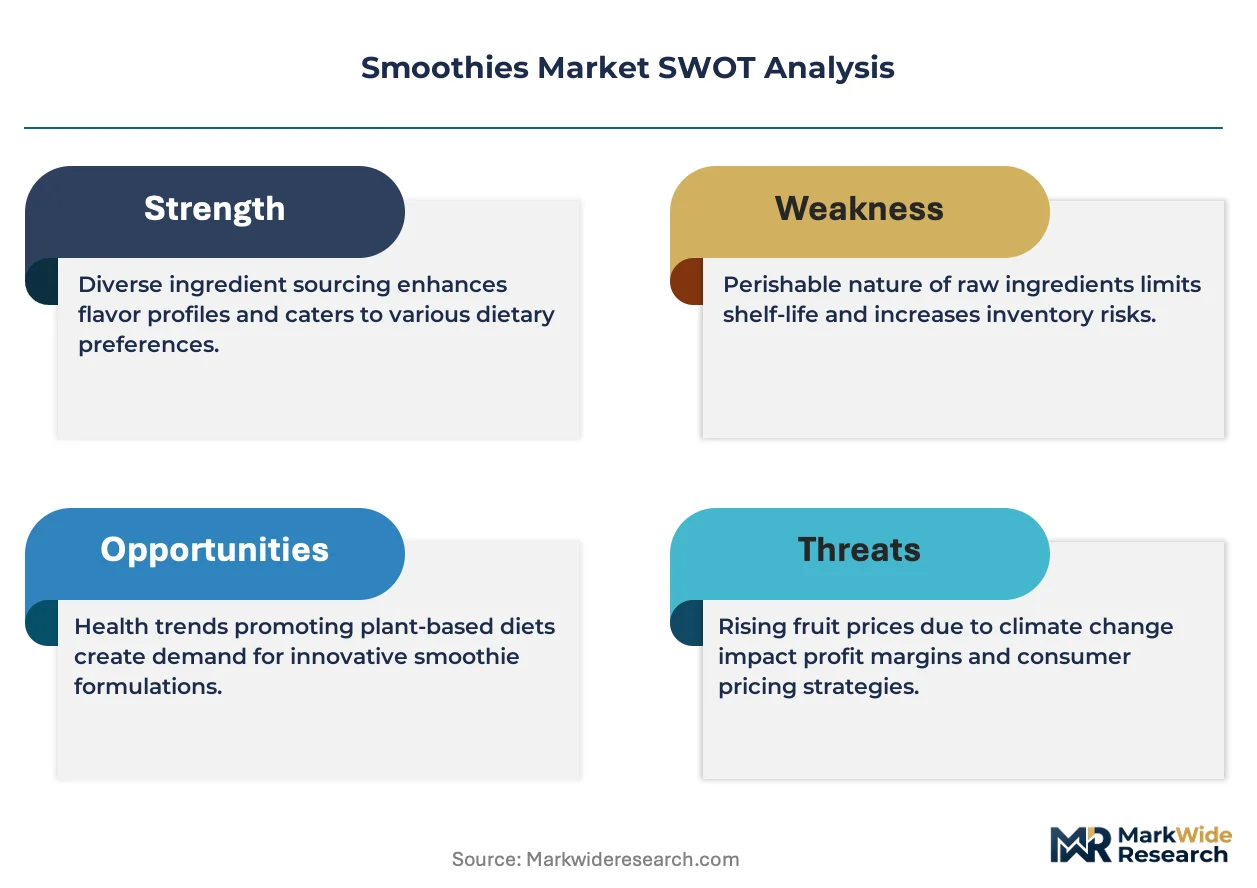
- Perishable ingredient volatility:Fresh fruit and vegetable input costs fluctuate with seasonal harvest yields and climate-driven supply interruptions.
- Refrigerated distribution concentration:Cold-chain logistics capacity constraints in secondary United States markets limit geographic expansion for chilled smoothie formats.
- High-pressure processing capex barriers:HPP equipment requirements for extended shelf-life without thermal degradation create capital intensity thresholds that favor scaled producers.
Strategic Opportunities
- Pouch packaging channel innovation:Reduced material weight and enhanced portability are opening on-the-go consumption occasions previously captured by bottled formats.
- Protein-enhanced aging demographic:Macronutrient fortification targeting consumers over fifty represents underpenetrated white space beyond athletic positioning.
- FDA front-of-pack labeling evolution:Pending disclosure schemes create first-mover advantage for brands with pre-positioned clean ingredient architectures.
Industry Challenges
- Reformulation timeline compression:Accelerated additive disclosure requirements in the European Union demand simultaneous R&D and regulatory submission cycles.
- Heat-labile vitamin retention:Maintaining probiotic and vitamin stability through high-shear blending without thermal degradation requires precise process engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoothies Market |
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $42.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit-Based, Vegetable-Based, Dairy-Based, Protein-Enhanced, Vegan Packaging Type: Bottles, Tetra Packs, Pouches, Jars, Cups Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops, Fitness Centers Customer Type: Health Enthusiasts, Working Professionals, Students, Athletes, Seniors |
| Companies Covered | Smoothie King, Bolthouse Farms, PepsiCo, Inc., Barfresh Food Group, Inc., Innocent Drinks, The Coca-Cola Company, Tropical Smoothie Café, Danone SA, Jamba Juice Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoothies Market Strategic Shifts & Innovations
Active reshaping in the smoothie category centers on three vectors: processing technology migration, regulatory disclosure evolution, and convenience-driven consumption pattern transformation.
High-pressure processing is migrating from niche organic lines to mainstream refrigerated smoothie portfolios. Mid-tier retailers in the United States are adopting HPP-equipped co-manufacturers to match shelf-life performance of national brands. This technology migration is compressing the shelf-life advantage previously held by thermally pasteurized competitors.
REACH chemical disclosure expansions and EU Green Deal packaging mandates are converging to reshape European formulation priorities. Manufacturers must now document additive provenance while simultaneously redesigning packaging structures for mono-material recyclability. German and French retail buyers are enforcing these requirements through procurement specifications that disqualify non-compliant suppliers.
Urban health-conscious consumers are substituting at-home blending with commercial prepared formats across United States coastal metropolitan clusters. This behavioral pivot concentrates volume in convenience retail and fitness channel outlets while eroding household appliance attachment rates. New York and Los Angeles metropolitan statistical areas exhibit the most pronounced channel shift velocity.
Smoothies Market Segmentation

Smoothie segmentation reveals how formulation, packaging, and channel choices align with distinct consumption occasions and wellness priorities. Understanding these divides exposes where margin concentrates and which customer migrations are reshaping volume distribution.
Product Type:
Use-case spectrum spans refreshment-driven fruit blends to functional protein fortification targeting specific physiological outcomes.
- Fruit-Based:Blends rely on banana, berry, and tropical fruit bases for natural sweetness and vibrant color appeal. Demand clusters in United States coastal metropolitan clusters where visual presentation drives social media sharing and repeat purchase.
- Protein-Enhanced:Formulations integrate whey, pea, or collagen isolates delivering 15-30g protein per serving for post-workout recovery. Athletes and aging demographics seeking sarcopenia prevention are concentrating orders in fitness center channels and specialty retail.
- Vegetable-Based:Green blends incorporating spinach, kale, and celery target consumers prioritizing micronutrient density over caloric load.
- Dairy-Based:Yogurt and kefir smoothies leverage probiotic positioning for digestive health claims.
- Vegan:Plant-milk formulations exclude all animal derivatives, appealing to ethical and allergen-sensitive consumers.
The dominant share belongs to Fruit-Based, while Protein-Enhanced is closing the gap fastest.
Packaging Type:
Cost tier separation runs from premium glass jars to economy pouch formats, with material choice directly shaping cold-chain requirements and shelf-life extension feasibility.
- Bottles:PET and HDPE containers dominate refrigerated retail sets, offering resealability and brand billboard space. United States supermarkets and convenience stores anchor volume, though material weight creates freight cost penalties versus flexible alternatives.
- Pouches:Flexible film structures reduce material weight by 60-70% versus rigid bottles, unlocking on-the-go consumption in commuter and fitness occasions. EU Green Deal packaging directives are accelerating mono-material recyclable pouch adoption in German and French retail channels.
- Tetra Packs:Aseptic carton technology enables ambient distribution, bypassing refrigerated logistics constraints.
- Jars:Glass containers signal premium positioning and support extended shelf-life through hot-fill processing.
- Cups:Single-serve formats target immediate consumption in foodservice and convenience settings.
Bottles retain volume leadership, though Pouches are expanding most quickly as sustainability procurement specifications tighten.
Distribution Channel:
Application context determines format specifications, with fitness centers demanding portable single-serve while supermarkets accommodate multi-pack purchasing.
- Supermarkets:Full-size refrigerated sets in United States coastal metropolitan clusters carry 20-40 SKU assortments, with placement fees and promotional calendars determining visibility. Clean-label positioning and USDA Organic certification command eye-level positioning and disproportionate margin capture.
- Fitness Centers:Gym chains are building captive beverage retail into membership ecosystems, with post-workout nutrition habits shifting toward ready-to-drink formats consumed immediately after training. This channel bypasses traditional retail slotting fees while capturing higher per-unit pricing.
- Convenience Stores:Grab-and-go cooler placement targets impulse refreshment occasions with smaller format SKUs.
- Online Retail:Direct-to-consumer and marketplace fulfillment requires shelf-stable or frozen formats viable through last-mile logistics.
- Specialty Shops:Independent health food retailers curate local and artisanal brands with transparent sourcing narratives.
Supermarkets hold the dominant share, while Fitness Centers are gaining share fastest through membership ecosystem integration.
Customer Type:
Volume concentrates among urban health-conscious consumers, though demographic expansion into aging populations is opening formulation white space.
- Health Enthusiasts:Early adopters of functional additives and superfood ingredients, this segment drives premium pricing acceptance and influences broader market trends through social proof. United States coastal metropolitan clusters exhibit highest per-capita consumption.
- Seniors:Consumers over fifty represent underpenetrated white space beyond athletic positioning, with protein-enhanced variants targeting sarcopenia prevention and bone health. Formulation requirements emphasize texture modification and reduced sugar load.
- Working Professionals:Time-constrained commuters prioritize convenience and meal replacement functionality.
- Students:Price-sensitive demand concentrates in value-tier formats and promotional purchasing.
- Athletes:Performance-oriented consumers prioritize macronutrient ratios and recovery timing.
Health Enthusiasts command the dominant share, while Seniors are climbing the fastest as aging demographics seek targeted nutrition solutions.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States consumers favor ready-to-drink protein-enhanced formats in fitness channels, while European buyers prioritize organic certification and recyclable packaging under EU Green Deal mandates.
United States
Urban health-conscious consumers in New York and Los Angeles metropolitan areas drive premium smoothie demand through convenience retail and gym chain ecosystems. FDA beverage labeling regulations govern serving-size declarations and allergen alerts that shape formulation strategies. Cold-chain logistics capacity constraints in secondary markets limit geographic expansion for chilled formats beyond coastal clusters.
Germany
German retail buyers enforce EU Green Deal packaging specifications that disqualify non-compliant suppliers from premium shelf placement. REACH chemical disclosure expansions demand additive provenance documentation alongside mono-material recyclable structure redesigns. Berlin and Munich metropolitan areas concentrate demand for transparent ingredient storytelling and ethical sourcing narratives.
United Kingdom
London and Southeast England anchor demand for plant-based and vegan smoothie formulations aligned with ethical consumption trends. UK organic certification schemes create tiered market access where certified products command visibility advantages in premium retail. Post-Brexit regulatory divergence from EU standards requires parallel compliance tracks for exporters serving continental markets.
France
French consumers prioritize micronutrient density in vegetable-based green blends incorporating spinach and kale. ANSM and DGCCRF enforcement of clean-label standards accelerates reformulation toward shorter ingredient lists. Paris and Île-de-France retail channels exhibit strongest adoption of pouch packaging formats for commuter consumption occasions.
Japan
Japanese consumers over fifty represent expanding demand for protein-enhanced variants targeting sarcopenia prevention and bone health. METI guidelines on functional food claims shape how manufacturers communicate macronutrient fortification benefits. Tokyo and Osaka metropolitan areas concentrate volume for premium positioning and texture-modified formulations.
Smoothies Market Key Industry Players
Capability concentration sits with mid-tier specialists possessing high-pressure processing expertise; scale advantage sits with diversified beverage conglomerates with refrigerated distribution networks. The vendor base separates into three archetypes: agricultural supply chain owners, multi-brand portfolio operators, and ethical sourcing storytellers. Dominant competitive moves include strategic partnerships with fitness center chains and portfolio diversification into functional additive categories.
Within the agricultural integration tier, Bolthouse Farms exemplifies supply chain ownership anchoring cost positions in retail bottled formats. PepsiCo, Inc. occupies a position among diversified conglomerates competing through multi-brand breadth spanning juice, dairy, and functional beverage aisles. Innocent Drinks represents the transparent sourcing archetype, leveraging ethical narratives across European retail channels where procurement specifications favor clean-label compliance.
| Leading Market Players |
|---|
| Smoothie King |
| Bolthouse Farms |
| PepsiCo, Inc. |
| Barfresh Food Group, Inc. |
| Innocent Drinks |
| The Coca-Cola Company |
| Tropical Smoothie Café |
| Danone SA |
| Jamba Juice Company |
| Others |
Cost & Logistics Intelligence
Perishable ingredient volatility determines both tier spreads and supply chain configuration, as seasonal harvest fluctuations and climate-driven interruptions compress margins across all pricing levels while forcing geographic diversification of fruit and vegetable sourcing.
Pricing Analysis
Contract structures favor long-term agricultural offtake agreements with banana, berry, and tropical fruit growers to hedge against spot market volatility. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified products from conventional formulations and value-tier private labels. Pricing pressure stems from cold-chain logistics cost inflation as refrigerated distribution capacity tightens in secondary United States markets. Students and price-sensitive commuters exhibit highest elasticity, while health enthusiasts in coastal metropolitan clusters accept substantial premiums for clean-label positioning.
Supply Chain Analysis
Tariff exposure between the United States and Mexico dominates raw material cost planning for avocado and tropical fruit inputs. Supply draws from California berry operations, Mexican banana plantations, and Brazilian açaí harvesting cooperatives. Single-source vulnerability concentrates in high-pressure processing equipment manufacturing, where German and Italian suppliers control critical HPP system production. Distribution runs through refrigerated third-party logistics networks anchored in coastal metropolitan cold-storage hubs, with ambient Tetra Pack formats bypassing these constraints through aseptic shelf-stable channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smoothie market sits at a post-pandemic wellness cyclical recovery driven by gym membership reactivation and fitness channel expansion. This cyclical positioning favors brands with pre-built refrigerated distribution infrastructure.
For Market Incumbents: Build captive channel moats through exclusive supply agreements with Planet Fitness and Equinox-tier gym chains that lock out competitor shelf placement. Bolthouse Farms and PepsiCo should deepen backward integration into organic berry cultivation to secure USDA Organic certification tier supply. High-pressure processing equipment scarcity threatens shelf-life parity with national brands.
For New Entrants and Emerging Players: Secondary United States markets beyond coastal metropolitan clusters offer underpenetrated white space where cold-chain logistics gaps have stalled incumbent expansion. Protein-enhanced formulations for sarcopenia prevention in consumers over fifty represent the most penetrable demographic segment beyond saturated athletic positioning. Direct-to-consumer frozen subscription models bypass retail slotting fee barriers entirely.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-tier specialists with HPP technical expertise and established fitness channel relationships. Long-term viability hinges on regulatory pre-positioning for FDA front-of-pack labeling evolution. Acquisition targets should demonstrate clean-label formulation archives and mono-material recyclable packaging redesign completion. Watch EU Green Deal packaging directive enforcement velocity as the inflection signal for European market access tiering.
| Strategic Initiative | Industry Significance |
|---|---|
| Fitness Center Exclusive Partnership | Captive beverage retail within gym membership ecosystems bypasses traditional slotting fees while capturing premium pricing. |
| USDA Organic Certification Investment | Certified products command eye-level placement and margin premiums in United States coastal metropolitan clusters. |
| Mono-Material Pouch Packaging Redesign | EU Green Deal compliance unlocks premium shelf placement in German and French retail procurement specifications. |
| High-Pressure Processing Capacity Addition | HPP equipment access compresses shelf-life gaps versus thermally pasteurized competitors in refrigerated sets. |
| Protein-Enhanced Aging Demographic Launch | Sarcopenia prevention positioning opens white space beyond saturated athletic consumer segments. |
Research Approach
Desk research of FDA beverage labeling guidance documents, EU Green Deal packaging directive texts, and Nielsen retail audit data preceded structured interviews with smoothie brand managers, refrigerated logistics operators, grocery category buyers, and high-pressure processing equipment manufacturers. Primary fieldwork captured formulation reformulation timelines, certification investment patterns, and channel placement fee structures. Secondary validation drew from USDA organic certification databases, trade customs records for fruit concentrate imports, and SEC filings of diversified beverage conglomerates. Bottom-up SKU-level volume builds were triangulated against top-down category spend estimates.
Assumptions held fixed include regulatory enforcement timelines for front-of-pack labeling schemes and EU packaging directive compliance deadlines, while variables included fitness center channel expansion velocity and perishable ingredient cost trajectories. The analytical framework modeled volume and value across product type, packaging format, distribution channel, and customer demographic dimensions over the projection horizon. CAGRs were derived from segment-level growth rate differential analysis applied to base-year market sizing. Forecast inputs incorporated high-pressure processing adoption curves and organic certification penetration rates by metropolitan statistical area.
Practitioners should monitor EU Green Deal enforcement stringency, FDA labeling rule finalization timing, and cold-chain logistics capacity additions for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Grape Juice Concentrate for Wine Making Market
Beverages
Fermented Drinks Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Coconut Milk Beverages Market
Beverages
Aloe Vera Drinks Market
Beverages
Hydrogen Water Bottle Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Oat Based Beverages Market
Beverages
Kvass Market
Beverages
Milk Tea Powder Market
Beverages
Gluten Free Beverages Market
Beverages
GCC Juice Market
Beverages
Germany Probiotic Drinks Market
Beverages
Ready to Drink Premixes Market
Beverages
Herb Infused Water Market
Beverages
Flavored Powder Drinks Market