
 US Acute Hospital Care Market | 2026-2036
US Acute Hospital Care Market Size, Share, and Industry Trends Forecast 2026-2036
US Acute Hospital Care Market Intelligence
Tax-exempt municipal bond financing for hospital construction is reconfiguring competitive entry barriers across metropolitan markets. HCA Healthcare leverages its scale to dominate capital-intensive surgical capacity in high-growth Sun Belt metros. Tenet Healthcare Corporation sustains geographic diversification across urban acute networks and ambulatory surgery centers. Mayo Clinic anchors premium tertiary and quaternary referral volumes through integrated physician-hospital alignment.
Acute hospital care encompasses emergency stabilization, invasive surgical intervention, intensive physiological monitoring, and advanced diagnostic imaging delivered in licensed inpatient facilities with 24-hour physician coverage and defined length-of-stay protocols. Structural demand is shifting toward outpatient and telemedicine delivery modes as reimbursement compression and minimally invasive techniques reduce traditional inpatient dependency. Surgical services and intensive care segments retain the deepest margin pools due to specialized staffing requirements and capital intensity, while diagnostic imaging faces price transparency pressures.
FDA oversight of medical devices, CMS conditions of participation, and state-level certificate-of-need laws collectively shape capital deployment timelines and service line expansion permissions. OSHA workplace safety mandates and HIPAA data privacy requirements add compliance layers that influence technology procurement and operational cost structures. Stakeholders must monitor how Medicare Advantage penetration and site-neutral payment policies redistribute volume between inpatient and alternative settings.
Market Dynamics
CMS site-neutral payment policies are compressing reimbursement differentials between inpatient and outpatient settings, redirecting capital deployment toward ambulatory surgical centers and micro-hospitals across Sun Belt metropolitan markets.
Growth Catalysts
- Medicare Advantage Penetration:CMS payment models reward coordinated care networks, pulling seniors toward managed acute services with bundled episode payments and reduced readmission incentives.
- Minimally Invasive Surgery Adoption:Laparoscopic and robotic-assisted techniques shorten length-of-stay protocols, expanding eligible procedure volumes and facility throughput capacity.
- Certificate-of-Need Reform:States including Texas and Florida have relaxed CON restrictions, enabling faster bed expansion and specialty service line entry in high-growth corridors.
Market Restraints
- Nurse Labor Scarcity:Registered nurse vacancy rates exceed 15% in intensive care units, forcing wage inflation and contract staffing dependency that erodes surgical margins.
- Medical Device Supply Concentration:Cardiac stent and orthopedic implant sourcing concentrates among three dominant manufacturers, exposing procurement to price volatility and allocation constraints.
- HIPAA Compliance Burden:Cybersecurity infrastructure upgrades and breach notification mandates divert capital from clinical capacity expansion into data protection systems.
Strategic Opportunities
- Rural Hospital Conversion Models:CMS Rural Emergency Hospital designation allows cost-reporting hospitals to eliminate inpatient beds while retaining emergency and observation services, preserving federal reimbursement eligibility.
- Tele-ICU Integration:Remote intensivist coverage extends critical care capacity to community hospitals without 24-hour onsite specialist staffing, addressing intensivist shortage in secondary markets.
- Value-Based Purchasing Alignment:Hospital-Acquired Condition Reduction Program incentives reward infection control and patient safety investments with Medicare payment adjustments.
Industry Challenges
- Electronic Health Record Interoperability:CMS Promoting Interoperability mandates require data exchange capabilities that strain legacy Cerner and Epic implementations at mid-size systems.
- Surgical Robot Capital Intensity:da Vinci system acquisition and maintenance contracts demand $2-3 million per unit plus disposable instrument commitments, concentrating advanced surgical capacity among well-capitalized networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Acute Hospital Care Market |
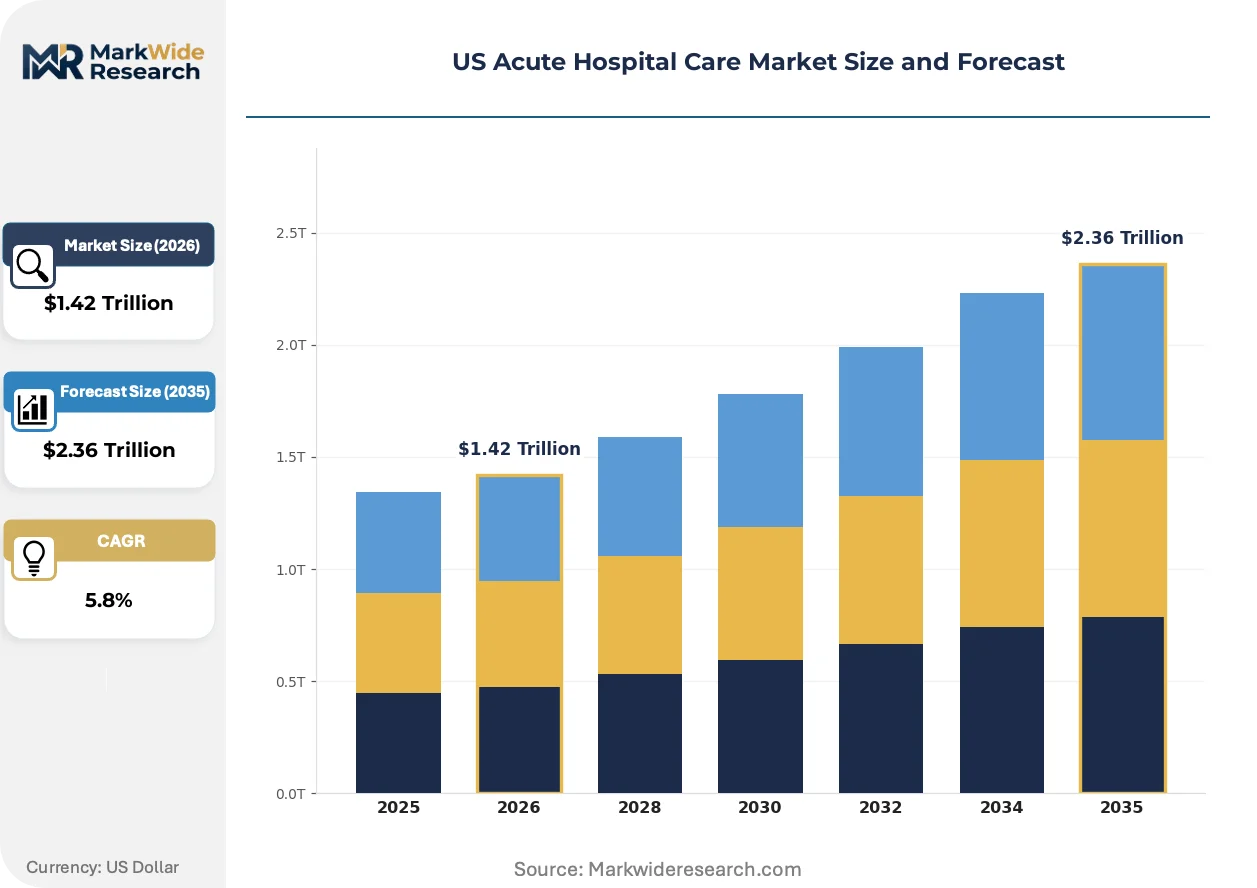
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.36 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency Services, Surgical Services, Intensive Care, Diagnostic Imaging End User: Patients, Healthcare Professionals, Insurance Providers, Rehabilitation Facilities Technology: Telehealth, Electronic Health Records, Wearable Devices, Robotic Surgery Delivery Mode: Inpatient Care, Outpatient Care, Home Healthcare, Telemedicine |
| Companies Covered | HCA Healthcare, Tenet Healthcare Corporation, Universal Health Services Inc., Community Health Systems, Inc., Ascension, Ardent Health Services, Lifepoint Health, Inc., Mayo Clinic, Cleveland Clinic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Acute Hospital Care Market Strategic Shifts & Innovations
Acute care delivery is fragmenting across settings as reimbursement compression and clinical automation compress traditional hospital economics, forcing incumbents to reconfigure physical footprints and workforce deployment models.
Same-day discharge protocols are collapsing the traditional 23-hour observation window for joint replacement and cardiac catheterization procedures. Orthopedic service lines at HCA and Tenet facilities now discharge 40% of total knee arthroplasty patients within eight hours, enabled by long-acting local anesthetics and wearable remote monitoring. This compression is eliminating overnight bed demand and reallocating nursing labor to preoperative optimization.
CMS site-neutral payment finalization is equalizing reimbursement rates for clinic-based and hospital-based services, stripping facility fees from off-campus provider-based departments. Cardiology and gastroenterology service lines face 60% payment reductions for procedures moved to hospital outpatient departments, accelerating divestiture of physician practices back to independent ambulatory settings. Texas and Florida markets show the fastest decoupling of physician alignment from hospital real estate.
Consumers are demanding price transparency before service selection, exploiting CMS hospital price disclosure mandates to compare shoppable services across systems. Elective procedure volumes at high-deductible health plan enrollees now concentrate at facilities publishing machine-readable charge data, bypassing academic medical centers with opaque pricing. Employer-sponsored plans in California and Texas are steering members toward transparently priced ambulatory surgery centers through reference-based benefit designs.
US Acute Hospital Care Market Segmentation
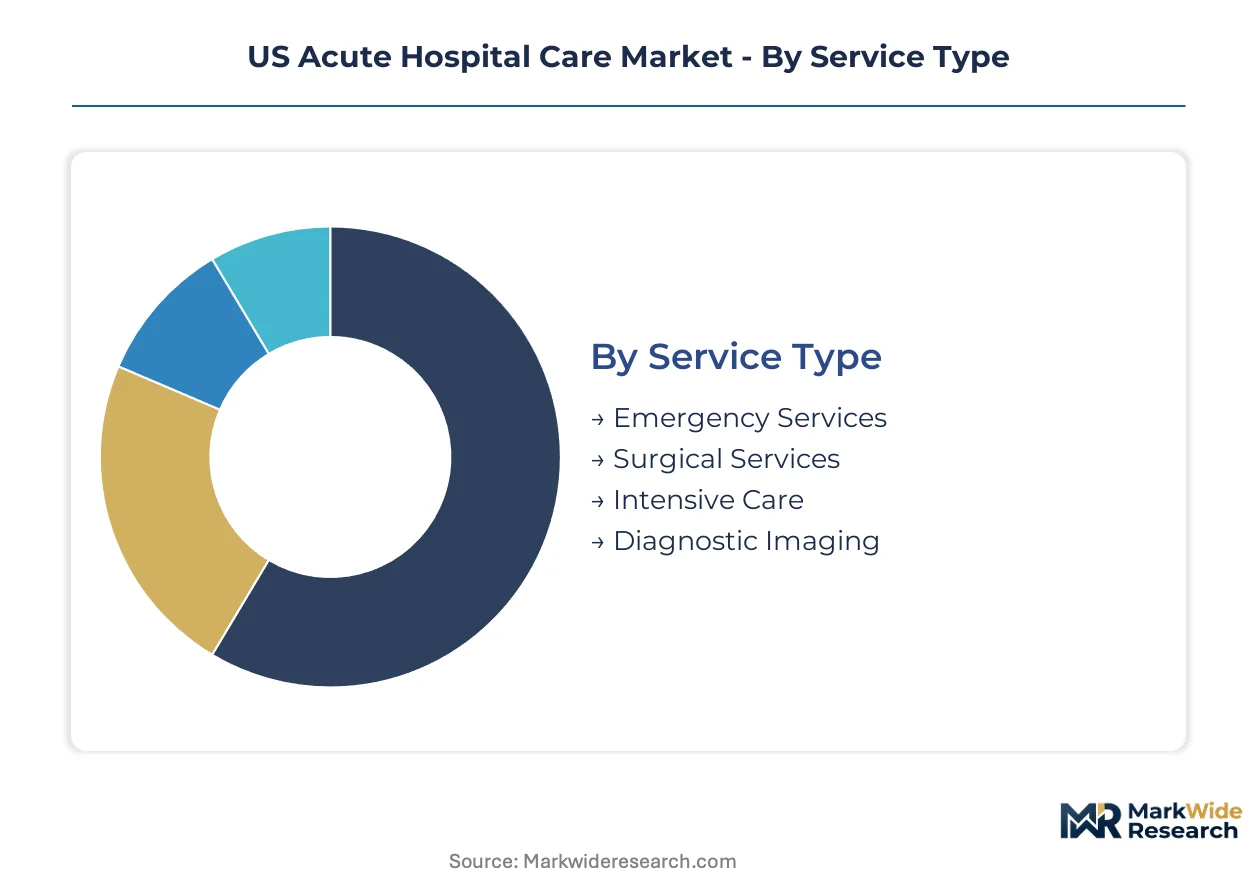
Segmentation reveals how acute care revenue pools concentrate across service intensity tiers and technology adoption curves. Distinct capital deployment patterns emerge when mapping patient flow against reimbursement modality and clinical infrastructure requirements.
Service Type:
Mature service lines retain margin dominance while emerging modalities reshape throughput economics.
- Surgical Services:Invasive procedures requiring anesthesia support and sterile operating infrastructure generate the deepest margin pools due to specialized staffing and device intensity. Demand concentrates in joint replacement and cardiac intervention volumes across Texas and Florida Sun Belt corridors, where CON relaxation permits faster specialty capacity expansion.
- Intensive Care:Continuous physiological monitoring and ventilator-dependent care delivered in specialized units with 24-hour intensivist coverage commands premium reimbursement. Nurse vacancy rates exceeding 15% in these units force wage inflation that erodes margins despite high acuity payments.
- Emergency Services:Stabilization and triage functions anchor hospital licensure and federal eligibility for CMS reimbursement.
- Diagnostic Imaging:Advanced radiology and interventional imaging face price transparency pressures from CMS hospital price disclosure mandates.
Surgical Services handles the majority of throughput; Intensive Care is expanding most quickly on share as aging demographics drive critical care demand.
End User:
Customer concentration patterns split between direct clinical decision-makers and financial intermediaries controlling access.
- Patients:Consumer-facing demand increasingly steers toward price-transparent facilities as high-deductible plan enrollment exposes individuals to out-of-pocket costs. California and Texas markets show the fastest shift toward shoppable service selection using CMS-mandated charge data.
- Healthcare Professionals:Physician preference drives technology procurement and referral pattern formation across service line economics.
- Insurance Providers:Medicare Advantage plans and commercial payers redirect volume through narrow networks and bundled payment structures.
- Rehabilitation Facilities:Post-acute settings capture step-down demand following inpatient stabilization and surgical recovery.
Patients command rising influence over site selection; Insurance Providers are gaining share fastest through network steerage and prior authorization requirements.
Technology:
Capital intensity separates established digital infrastructure from emerging automation platforms.
- Robotic Surgery:da Vinci and competing platforms enable minimally invasive techniques that compress length-of-stay and expand eligible procedure volumes. HCA and Tenet networks concentrate this capacity in high-growth metropolitan markets where disposable instrument commitments and maintenance contracts create switching costs.
- Electronic Health Records:Epic and Cerner implementations anchor clinical workflow and CMS interoperability mandates.
- Telehealth:Remote consultation platforms extend specialist reach into underserved geographies and post-discharge monitoring.
- Wearable Devices:Continuous physiological monitoring supports same-day discharge protocols and remote patient surveillance.
Electronic Health Records underpins operational continuity; Robotic Surgery is climbing the fastest on capital allocation priority.
Delivery Mode:
Site-neutral payment policies are collapsing traditional inpatient-outpatient reimbursement differentials.
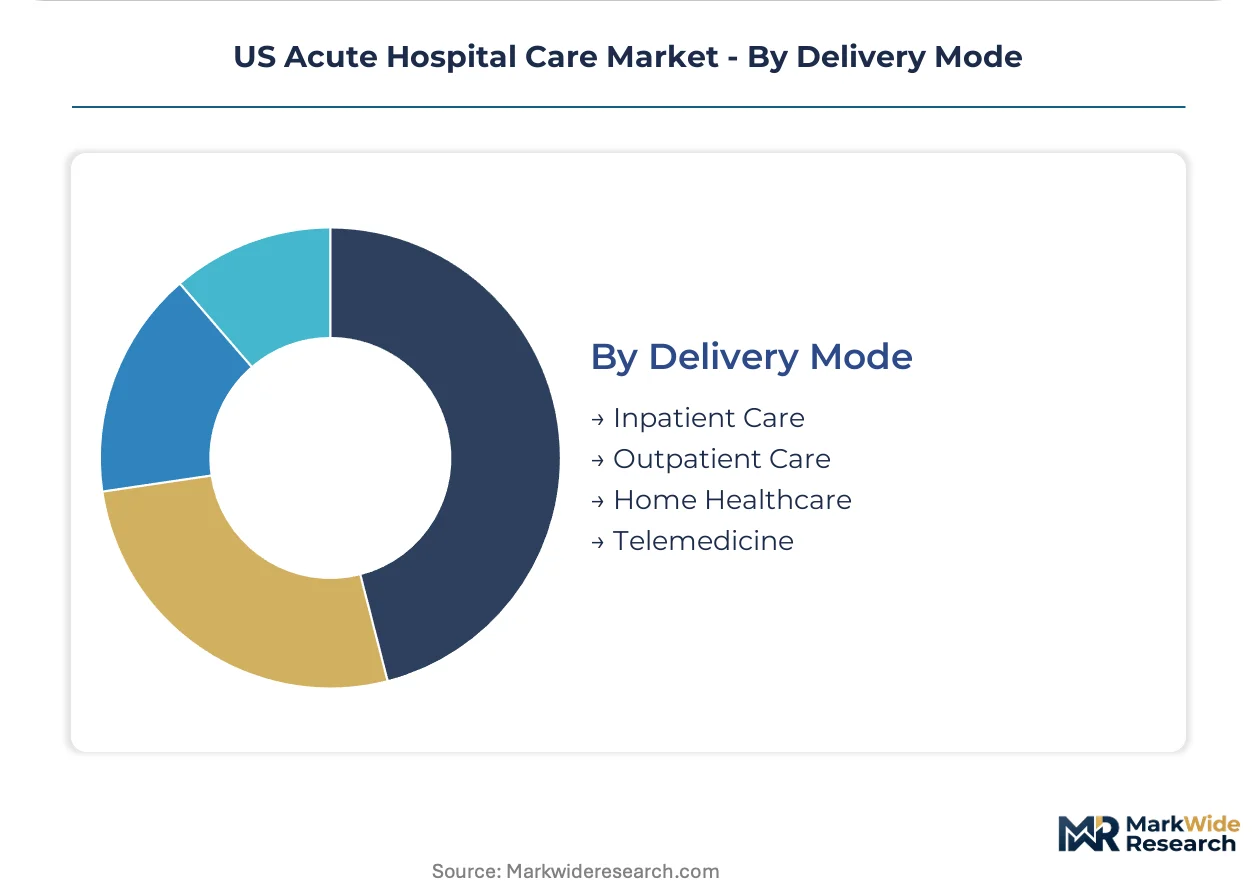
- Outpatient Care:Ambulatory surgical centers and micro-hospitals capture shifting volume as CMS equalizes payment rates between settings. Texas and Florida markets show the fastest decoupling of physician alignment from hospital real estate.
- Inpatient Care:Licensed 24-hour facilities with defined length-of-stay protocols retain dominance for high-acuity stabilization.
- Telemedicine:Remote delivery platforms expand access while facing state-level licensure and reimbursement parity constraints.
- Home Healthcare:Post-acute and chronic monitoring services extend institutional care into residential settings.
Inpatient Care retains the highest acuity concentration; Outpatient Care is gaining share fastest as reimbursement compression redirects capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interstate patient mobility patterns reveal stark regional imbalances in acute care capacity. High-growth Sun Belt states absorb inbound medical migration while legacy Northeast markets shed utilization to lower-cost ambulatory alternatives.
Texas
Metropolitan hospital construction in Dallas-Fort Worth and Houston outpaces national bed expansion rates by a factor of two. CMS Rural Emergency Hospital designations preserve federal reimbursement for converted critical access facilities in the Panhandle and West Texas. HCA Healthcare concentrates robotic surgical capacity in the Texas Medical Center corridor, capturing migration flows from neighboring states.
Florida
Medicare Advantage penetration among senior populations exceeds forty percent, redirecting acute volumes toward managed care networks with bundled episode structures. State-level certificate-of-need relaxation enables faster specialty service line entry in Orlando and Tampa Bay markets. Tenet Healthcare anchors ambulatory surgery center networks across the I-4 corridor, decoupling physician alignment from hospital real estate.
California
Price transparency mandates and reference-based employer benefit designs steer high-deductible plan enrollees toward shoppable ambulatory services. OSHA workplace safety mandates and HIPAA breach notification requirements strain capital deployment at mid-size systems in Los Angeles and San Diego. Mayo Clinic anchors premium tertiary referral volumes through integrated physician-hospital alignment in the Bay Area.
Arizona
Retiree population concentration drives demand for orthopedic and cardiac intervention volumes in Phoenix and Tucson metropolitan areas. State Medicaid expansion and dual-eligible integration programs reshape reimbursement economics for safety-net hospitals. Banner Health and HonorHealth systems compete for narrow-network inclusion with Medicare Advantage plans operating across the Colorado River corridor.
North Carolina
Research Triangle metropolitan growth attracts academic medical center expansion with quaternary service line development. FDA oversight of medical devices and clinical trial infrastructure concentrates procurement decisions in Durham and Chapel Hill. Atrium Health and Duke Health systems leverage integrated electronic health record platforms to capture regional referral volumes across the Piedmont corridor.
US Acute Hospital Care Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in device and technology supply. The US acute hospital market consolidates around multi-state networks with capital access for robotic surgical platforms and electronic health record infrastructure. Three archetypes dominate: scale-driven procedural consolidators, premium academic referral anchors, and ambulatory-focused divestiture specialists. Competitive maneuvering centers on geographic tuck-in acquisitions and site-neutral payment arbitrage between inpatient and outpatient settings.
Among publicly traded hospital operators, HCA Healthcare exemplifies the scale-driven procedural consolidator archetype through concentrated Sun Belt metropolitan presence. Tenet Healthcare Corporation occupies a diversified position spanning urban acute networks and ambulatory surgery center portfolios. Mayo Clinic anchors the premium academic referral tier through integrated physician alignment and destination quaternary care volumes.
| Leading Market Players |
|---|
| HCA Healthcare |
| Tenet Healthcare Corporation |
| Universal Health Services Inc. |
| Community Health Systems, Inc. |
| Ascension |
| Ardent Health Services |
| Lifepoint Health, Inc. |
| Mayo Clinic |
| Cleveland Clinic |
| Others |
Cost & Logistics Intelligence
Bed underutilization in legacy Northeast markets is forcing capital redeployment toward ambulatory assets, compressing inpatient pricing power while elevating procurement leverage for surgical devices and implantable supplies.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across cardiac stent and orthopedic implant procurement. Pricing stratifies across premium, standard, and economy tiers based on FDA device classification and volume commitment scale. Cost compression in standard-tier implants is intensifying because Medicare site-neutral policies strip facility fees from hospital outpatient departments. High-deductible plan enrollees exhibit highest price sensitivity, while integrated delivery networks with GPO contracts demonstrate lowest sensitivity due to bundled purchasing leverage.
Supply Chain Analysis
Extended payment terms from device manufacturers to hospital systems now stretch 90-120 days, straining working capital across mid-size networks. Supply concentrates in Ireland, Switzerland, and the USA for cardiac rhythm management devices and orthopedic implants. Procurement draws from nitinol, cobalt-chrome, and ultra-high molecular weight polyethylene feedstocks. Single-source vulnerability persists for da Vinci robotic surgical systems and specialized laparoscopic instruments. Distribution runs through group purchasing organizations and direct manufacturer contracts with IDNs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ambulatory surgical centers and tele-ICU platforms threaten traditional inpatient economics, forcing incumbents to defend procedural volume through site-neutral payment arbitrage and same-day discharge protocols.
For Market Incumbents: Harden robotic surgical capacity concentration in Texas and Florida Sun Belt corridors where CON relaxation permits faster specialty bed expansion. Consolidate physician alignment through employment models that capture referral volume before site-neutral payment equalization strips hospital outpatient department premiums. Defend against ambulatory surgery center divestiture by embedding wearable remote monitoring into joint replacement protocols.
For New Entrants and Emerging Players: Rural Emergency Hospital conversions in the Texas Panhandle and West Texas represent the most penetrable entry point for CMS-eligible emergency and observation services without full inpatient licensure burden. Micro-hospital formats in Florida I-4 corridor suburbs offer second white-space target with lower capital intensity than traditional acute facilities. Pursue narrow-network inclusion with Medicare Advantage plans as primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ambulatory surgery center networks with multi-specialty physician alignment and bundled episode contracts. Long-term viability over the next decade favors platforms with site-neutral payment arbitrage capability and robotic surgical density. Target acquisition archetype: regional ASC networks in CON-relaxed states with established GPO relationships. Watch Medicare Advantage penetration rates as inflection signal for volume migration timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Surgical Capacity Expansion | HCA and Tenet concentrate da Vinci systems in Dallas-Fort Worth and Houston to capture migration flows. |
| Rural Emergency Hospital Conversion | CMS designation preserves federal reimbursement for Panhandle facilities eliminating inpatient beds. |
| Tele-ICU Platform Integration | Remote intensivist coverage extends critical care capacity to community hospitals without 24-hour onsite staffing. |
| Medicare Advantage Narrow Network Inclusion | Banner Health and HonorHealth compete for plan contracts across Arizona's Colorado River corridor. |
| Same-Day Discharge Protocol Implementation | Long-acting local anesthetics and wearable monitoring enable 40% of knee arthroplasty patients to depart within eight hours. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital CFOs, GPO contracts managers, biomedical engineers, and Medicare Advantage plan medical directors. Secondary validation drew from CMS Medicare cost reports, FDA 510(k) device filings, hospital procurement databases, and state certificate-of-need regulatory filings. Bottom-up bed capacity and utilization modeling triangulated against top-down reimbursement flow analysis across the analysis window.
Calibration against historical capacity expansion patterns and Medicare payment rule finalizations anchored the projection framework. Segmentation dimensions modeled include service intensity tier, delivery mode, technology adoption curve, and metropolitan statistical area growth trajectory. CAGRs were derived from regression analysis of bed expansion rates against population migration flows and payer mix shifts. Forecast inputs incorporated CON regulatory status by state and site-neutral payment implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting tax-exempt municipal bond financing or Medicare reimbursement index adjustments would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Immunoassay CDMO Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
Michigan Urgent Care Center Market
Healthcare Services
Healthcare Cold Chain Logistics Market
Healthcare Services
Funeral and Cremation Services Market
Healthcare Services
Private Healthcare Market
Healthcare Services
US Retail Clinics Market
Healthcare Services
Pharmaceutical Contract Sales Organizations Market
Healthcare Services
Chronic Disease Management Service Market
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
Hair Transplant Services Market
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
Healthcare Staffing Market
Healthcare Services
US Value-Based Healthcare Service Market