
 Hospital Workforce Management Market | 2026-2036
Hospital Workforce Management Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Workforce Management Market Foresight
Joint Commission accreditation standards are redrawing competitive boundaries for vendors serving acute-care facilities. UKG Inc. leverages its unified HCM platform to anchor enterprise hospital contracts across North America. Oracle Corporation competes through cloud infrastructure depth that sustains real-time scheduling at scale. Workday Inc. differentiates via native analytics that positions workforce data alongside financial planning modules.
Hospital workforce management encompasses the digital systems and methodologies used to schedule clinical and non-clinical staff, track credentials, manage labor costs, and ensure regulatory compliance across healthcare delivery organizations. These platforms integrate time-clock hardware, predictive staffing algorithms, and bi-directional EHR interfaces to maintain optimal nurse-to-patient ratios while controlling overtime expenditure. Cloud-based services represent the fastest-expanding delivery model as health systems abandon legacy on-premise installations that demand dedicated IT maintenance. Staff Scheduling Software occupies the largest product-type share, though analytics solutions command the highest margins by converting workforce data into actionable operational intelligence. Regulatory Compliance applications are gaining share as CMS reimbursement rules tie payment accuracy to documented staffing levels.
FDA oversight of clinical decision-support functions embedded in scheduling platforms, combined with ONC interoperability mandates and OSHA workplace-safety recordkeeping requirements, shapes product development priorities for vendors targeting U.S. hospitals. State-level nurse staffing ratio laws in California and Massachusetts add further compliance complexity that drives demand for automated tracking. Stakeholders must monitor how emerging AI-driven scheduling tools navigate emerging liability frameworks before committing to platform migrations.
Market Dynamics
Cloud migration pressure from the ONC Cures Act Final Rule is forcing acute-care networks to replace legacy on-premise workforce systems with interoperable SaaS platforms that synchronize scheduling data across EHR environments.
Growth Catalysts
- Interoperability Mandates:The ONC Cures Act Final Rule compels hospitals to adopt systems that exchange workforce data bidirectionally with EHRs, accelerating procurement cycles for integrated platforms.
- Clinical Labor Shortages:Registered nurse vacancy rates exceeding critical thresholds in United States metropolitan markets drive automated scheduling adoption to optimize existing staff deployment.
- Predictive Algorithms:Machine learning models forecasting patient census patterns enable proactive shift adjustments that reduce premium labor expenditure in emergency departments.
Market Restraints
- Implementation Costs:Health systems face substantial capital requirements for data migration from legacy mainframe scheduling systems to cloud-native architectures.
- Vendor Concentration:Enterprise contract consolidation around three dominant platform providers limits pricing leverage for mid-sized hospital networks.
- Technical Debt:Decades-old COBOL-based workforce systems in veteran facilities resist API integration with modern analytics layers.
Strategic Opportunities
- Rural Health Networks:Critical Access Hospitals in underserved United States counties present untapped demand for lightweight, subscription-based scheduling tools.
- AI-Native Scheduling:Convergence of natural language processing with real-time census feeds enables conversational shift-swapping interfaces for nursing staff.
- OSHA Compliance Automation:Workplace safety recordkeeping requirements create attachable revenue streams for vendors bundling incident tracking with core workforce modules.
Industry Challenges
- Clinical Informatics Talent:Scarce specialists who bridge nursing workflows with system configuration command premium compensation that strains implementation budgets.
- Multi-Platform Integration:Synchronizing workforce data across disparate EHR instances following hospital mergers demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Workforce Management Market |
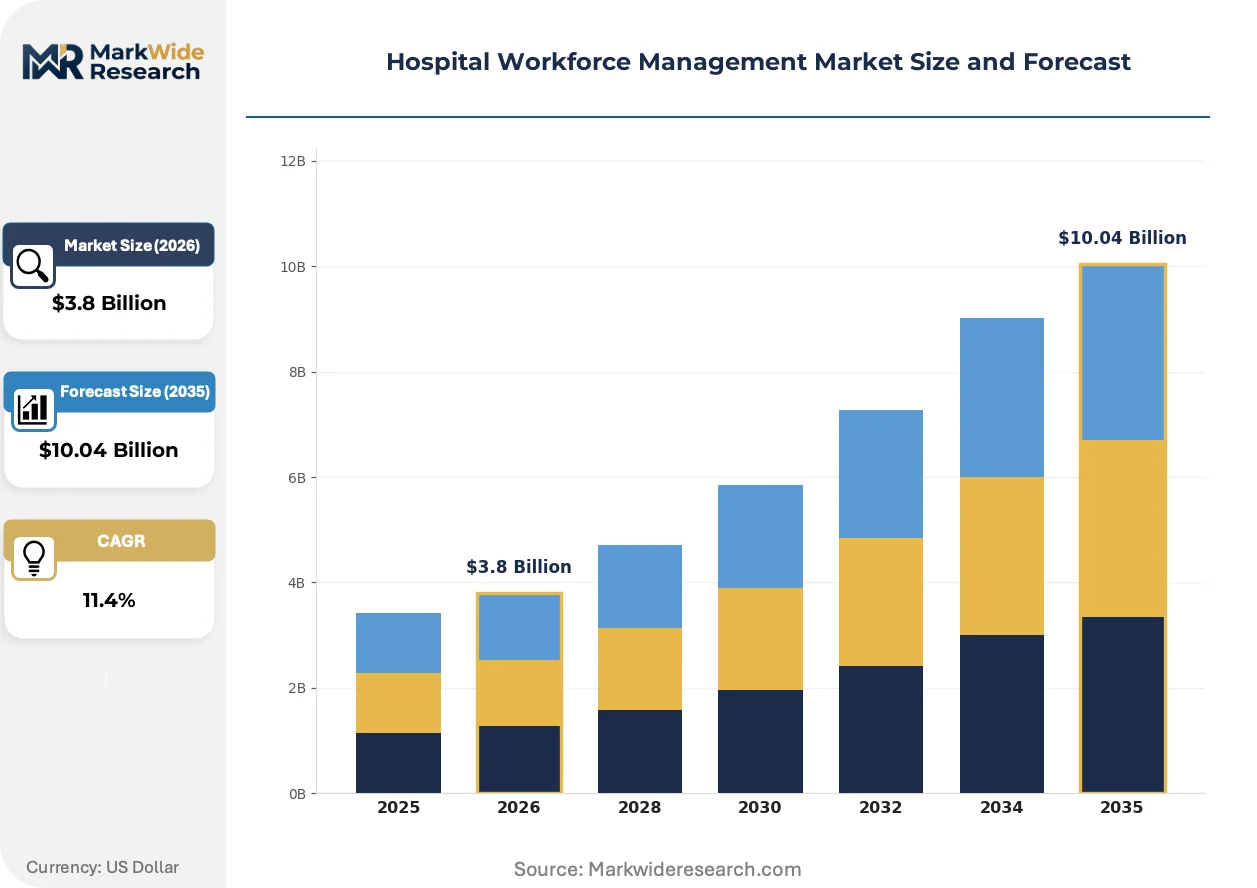
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Staff Scheduling Software, Employee Engagement Tools, Performance Management Systems, Analytics Solutions Application: Staffing Optimization, Regulatory Compliance, Data Reporting, Cost Management End User: Healthcare Providers, Clinical Administrators, HR Departments, Workforce Planners Delivery Model: On-Premise Solutions, Cloud-Based Services, Hybrid Systems, Mobile Applications |
| Companies Covered | UKG Inc., Workday Inc., Oracle Corporation, Infor, ADP Inc., ATOSS Software AG, IBM Corporation, McKesson Corporation, WorkForce Software LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Workforce Management Market Shifts & Advancements
Workforce technology is converging around ambient intelligence and edge computing, compressing decision latency from days to minutes while embedding compliance verification directly into clinical workflows.
Mobile-first shift management applications are miniaturizing complex scheduling logic into smartphone interfaces that nurses access at point-of-care. Large academic medical centers in California and Massachusetts have mandated these tools for all clinical staff. The technology is miniaturizing administrative overhead that previously required dedicated scheduling office personnel.
The FDA is scrutinizing clinical decision-support features embedded within scheduling algorithms that recommend nurse-to-patient ratios. This oversight is compelling vendors to segregate predictive staffing suggestions from automated assignment execution. United States health systems are responding by demanding audit trails that document human override of algorithmic recommendations.
Subscription pricing models are displacing perpetual license structures as hospital CFOs prioritize operational expenditure over capital deployment. Group purchasing organizations are consolidating vendor negotiations for member health systems. The United States market exhibits the most pronounced shift, with rural networks particularly receptive to all-inclusive per-employee-per-month arrangements.
Hospital Workforce Management Market Segmentation
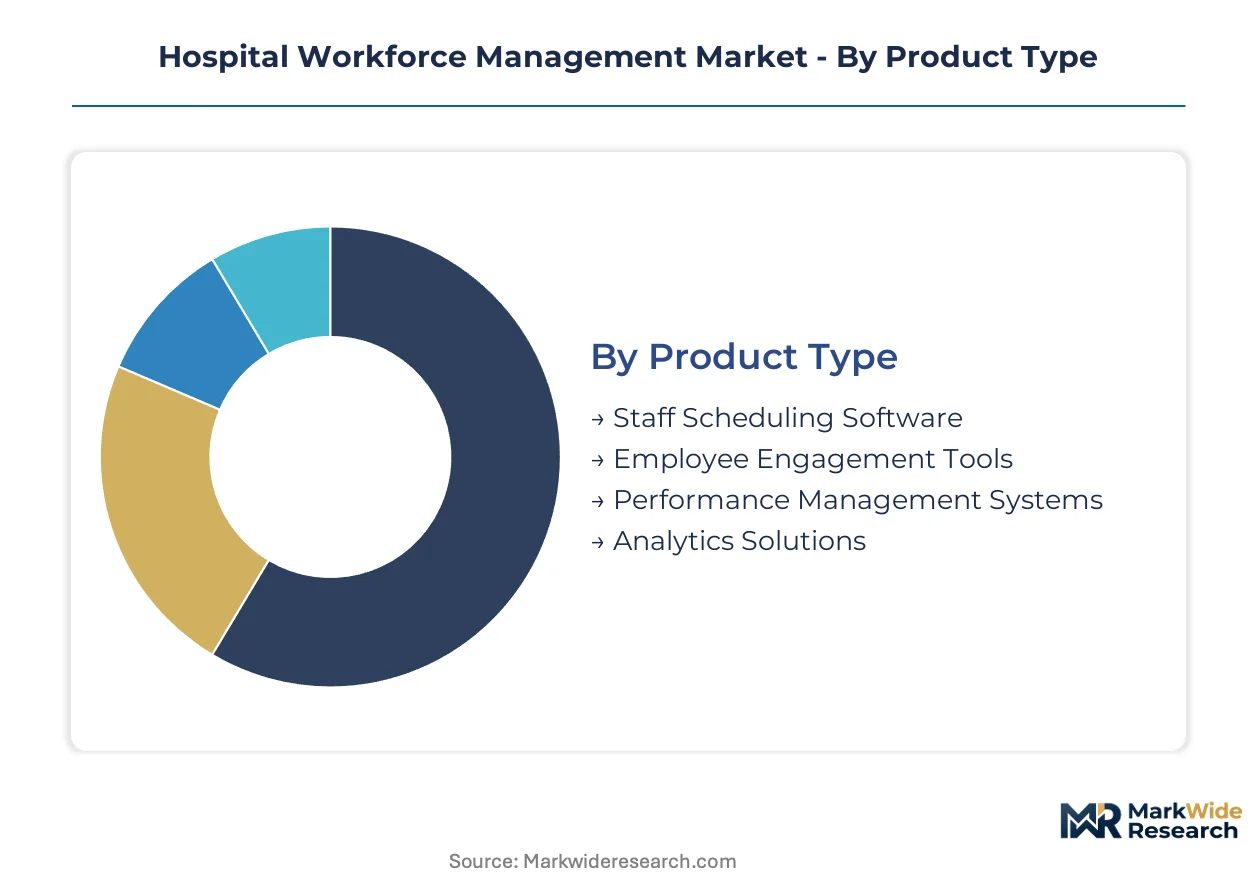
Hospital workforce management platforms serve distinct operational layers across clinical and administrative functions. Segmentation reveals how procurement priorities diverge between cost-conscious rural networks and enterprise health systems pursuing predictive capabilities.
Product Type:
Channel mix varies sharply: direct enterprise sales dominate analytics and performance systems, while scheduling software flows through group purchasing organizations and EHR-integrated marketplaces.
- Staff Scheduling Software:Core platforms automate shift allocation, credential verification, and nurse-to-patient ratio compliance through bidirectional EHR interfaces. Demand concentrates in United States metropolitan health systems facing Joint Commission audits and state-level staffing mandates. California and Massachusetts hospitals drive premium module adoption for automated ratio tracking.
- Analytics Solutions:Predictive engines transform historical census patterns, seasonal admission trends, and real-time acuity data into staffing forecasts. Academic medical centers and large integrated delivery networks in Texas and Florida prioritize these tools for emergency department optimization. Highest-margin segment due to consultative implementation and recurring insight subscriptions.
- Employee Engagement Tools:Mobile-first applications enabling shift swapping, self-scheduling, and burnout monitoring through sentiment analysis.
- Performance Management Systems:Credential tracking, competency assessments, and continuing education workflows for clinical staff.
Staff Scheduling Software dominates installed base. Analytics Solutions is where expansion concentrates.
Application:
Cost tier segmentation separates compliance-driven procurement from discretionary optimization spending, with regulatory applications commanding protected budgets during capital constraints.
- Regulatory Compliance:Automated documentation of staffing levels, credential status, and workplace safety incidents for CMS reimbursement accuracy and OSHA recordkeeping. Critical Access Hospitals in underserved United States counties prioritize lightweight compliance bundles over comprehensive suites. ONC interoperability mandates accelerate replacement of paper-based tracking.
- Staffing Optimization:Algorithmic shift matching against patient census forecasts, skill matrices, and union contract rules. Large hospital networks in Illinois and Ohio deploy these modules to reduce premium labor expenditure. Machine learning models now incorporate real-time admission, discharge, and transfer feeds.
- Cost Management:Overtime tracking, agency labor reduction, and productivity benchmarking against DRG-adjusted patient volumes.
- Data Reporting:Standardized dashboards for executive leadership, nursing management, and regulatory submission.
Regulatory Compliance commands priority budget allocation. Staffing Optimization is climbing the fastest as labor shortages intensify.
End User:
Volume concentration follows organizational scale: individual hospitals favor departmental solutions while multi-facility systems demand unified enterprise platforms.
- Healthcare Providers:Frontline clinical leadership including chief nursing officers and department directors requiring real-time visibility into unit-level staffing. Demand clusters in academic medical centers with complex rotation schedules and fellowship programs. These users prioritize mobile interfaces accessible at point-of-care.
- Workforce Planners:Specialized analysts forecasting multi-week staffing needs against projected census, seasonal patterns, and planned leave. Large United States health systems in Pennsylvania and North Carolina employ dedicated teams. Predictive algorithm adoption is steepest among this cohort.
- Clinical Administrators:Operations managers balancing patient flow, bed capacity, and staffing across service lines.
- HR Departments:Compensation, benefits, and enterprise-wide policy administration functions.
Healthcare Providers anchor transaction volume. Workforce Planners represent the steepest expansion trajectory as predictive tools mature.
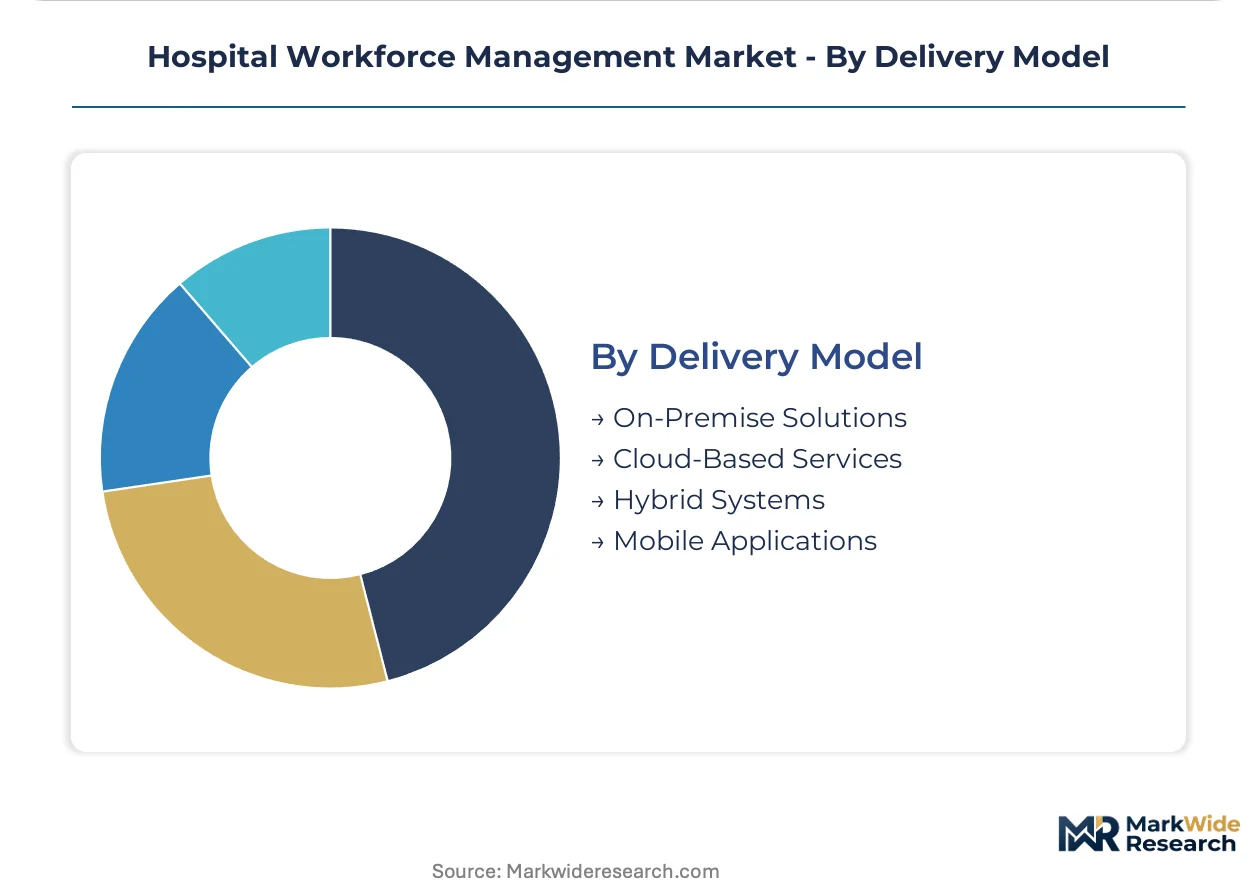
Delivery Model:
Customer type segmentation distinguishes legacy-dependent veteran facilities from cloud-native new construction and mobile-first ambulatory strategies.
- Cloud-Based Services:SaaS platforms with automatic updates, elastic scaling, and API-first architecture for EHR integration. United States health systems abandoning COBOL-based legacy systems drive replacement cycles. Subscription pricing aligns with CFO preferences for operational expenditure over capital deployment.
- Mobile Applications:Smartphone-native shift management with biometric authentication, geofenced clock-in, and conversational interfaces for shift swapping. California and Massachusetts academic centers have mandated universal clinical staff adoption. Natural language processing enables voice-activated schedule queries at bedside.
- On-Premise Solutions:Legacy installations requiring dedicated IT infrastructure and maintenance personnel.
- Hybrid Systems:Mixed deployments preserving sensitive credential data on-premise while leveraging cloud analytics.
On-Premise Solutions retain installed base concentration. Cloud-Based Services is gaining share fastest as ONC mandates accelerate migration timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal interoperability mandates in the United States are accelerating procurement cycles for cloud-native workforce platforms. Hospital networks in Germany and the United Kingdom are following with national digitization programs. Japan's aging clinical workforce is intensifying automation demand across acute-care facilities.
United States
Registered nurse vacancy rates exceeding critical thresholds in metropolitan markets drive automated scheduling adoption. The ONC Cures Act Final Rule compels bidirectional workforce data exchange with EHR systems. California and Massachusetts health systems lead premium module procurement for state-mandated nurse-to-patient ratio tracking.
Germany
Hospital consolidation into large integrated networks creates demand for unified workforce platforms across multi-site operations. The country's national digital health strategy prioritizes interoperable hospital information systems. Academic medical centers in Bavaria and North Rhine-Westphalia are deploying predictive staffing algorithms for emergency department optimization.
United Kingdom
NHS workforce pressures following pandemic-era staff attrition are accelerating technology procurement for roster optimization. National Health Service England's digital transformation mandates require cloud-based workforce systems by 2025. London and Greater Manchester hospital trusts are piloting AI-native scheduling tools with conversational interfaces for nursing staff.
Japan
Aging clinical workforce demographics and declining nursing school enrollment intensify automation imperatives for acute-care facilities. The Ministry of Health, Labour and Welfare's work-style reform legislation limits overtime hours for medical personnel. Tokyo and Osaka metropolitan hospital networks are investing in mobile-first shift management to reduce administrative burden on point-of-care staff.
Canada
Provincial health authority consolidation is driving enterprise workforce platform standardization across hospital networks. Health Canada interoperability guidelines align with ONC Cures Act principles for cross-border data exchange readiness. Ontario and Quebec health systems are replacing legacy COBOL-based scheduling installations with cloud-native architectures.
Hospital Workforce Management Market Competitive Landscape
Listed leaders compete with private specialists across platform depth and vertical integration. Enterprise software conglomerates anchor the upper tier through unified HCM suites that bundle workforce modules with broader enterprise applications. Mid-market specialists occupy a distinct tier through purpose-built healthcare scheduling tools with faster implementation cycles. Competitive moves concentrate on API-first architecture development and strategic partnerships with EHR vendors to secure bidirectional data exchange capabilities.
Within the enterprise conglomerate tier, UKG Inc., Oracle Corporation, and Workday Inc. exemplify divergent competitive positioning. UKG Inc. anchors its market presence through unified human capital management platforms that integrate workforce scheduling with broader HR functions. Oracle Corporation occupies a position defined by cloud infrastructure depth that sustains real-time scheduling at scale across multi-facility networks. Workday Inc. represents the native analytics archetype, positioning workforce data alongside financial planning modules for health system CFOs. These three entities collectively illustrate how platform breadth, infrastructure scale, and analytical sophistication serve as alternative vectors for enterprise hospital contract capture.
| Leading Market Players |
|---|
| UKG Inc. |
| Workday Inc. |
| Oracle Corporation |
| Infor |
| ADP Inc. |
| ATOSS Software AG |
| IBM Corporation |
| McKesson Corporation |
| WorkForce Software LLC |
| Others |
Supply & Pricing Matrix
Per-employee-per-month subscription contracts lock in multi-year supply access for hospital networks while insulating CFOs from capital expenditure volatility. This SaaS structure concentrates pricing power with cloud-native vendors who bundle EHR interoperability modules into base tiers.
Pricing Analysis
Certification level (ONC-2015 Edition Cures Act Update) creates the primary spread between premium analytics suites and basic scheduling modules. Pricing stratifies across enterprise, mid-market, and critical access tiers based on API integration depth and predictive algorithm inclusion. Cost compression in the mid-market tier intensifies because group purchasing organizations consolidate vendor negotiations for member health systems. Critical Access Hospitals exhibit highest price sensitivity due to constrained IT budgets, while academic medical centers prioritize functionality over cost.
Supply Chain Analysis
Just-in-time deployment models dominate as health systems abandon legacy COBOL installations for elastic cloud infrastructure that scales with census fluctuations. Software development concentrates in the United States, Ireland, and India, with implementation services drawing from domestic clinical informatics specialists. Supply chain risk centers on single-source vulnerability for EHR-integrated modules that require vendor-specific API certifications. Distribution runs through direct enterprise sales for analytics platforms and group purchasing organization channels for core scheduling tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital workforce management sits at a platform-economics inflection where ONC interoperability mandates are consolidating procurement around API-first vendors who control data exchange standards.
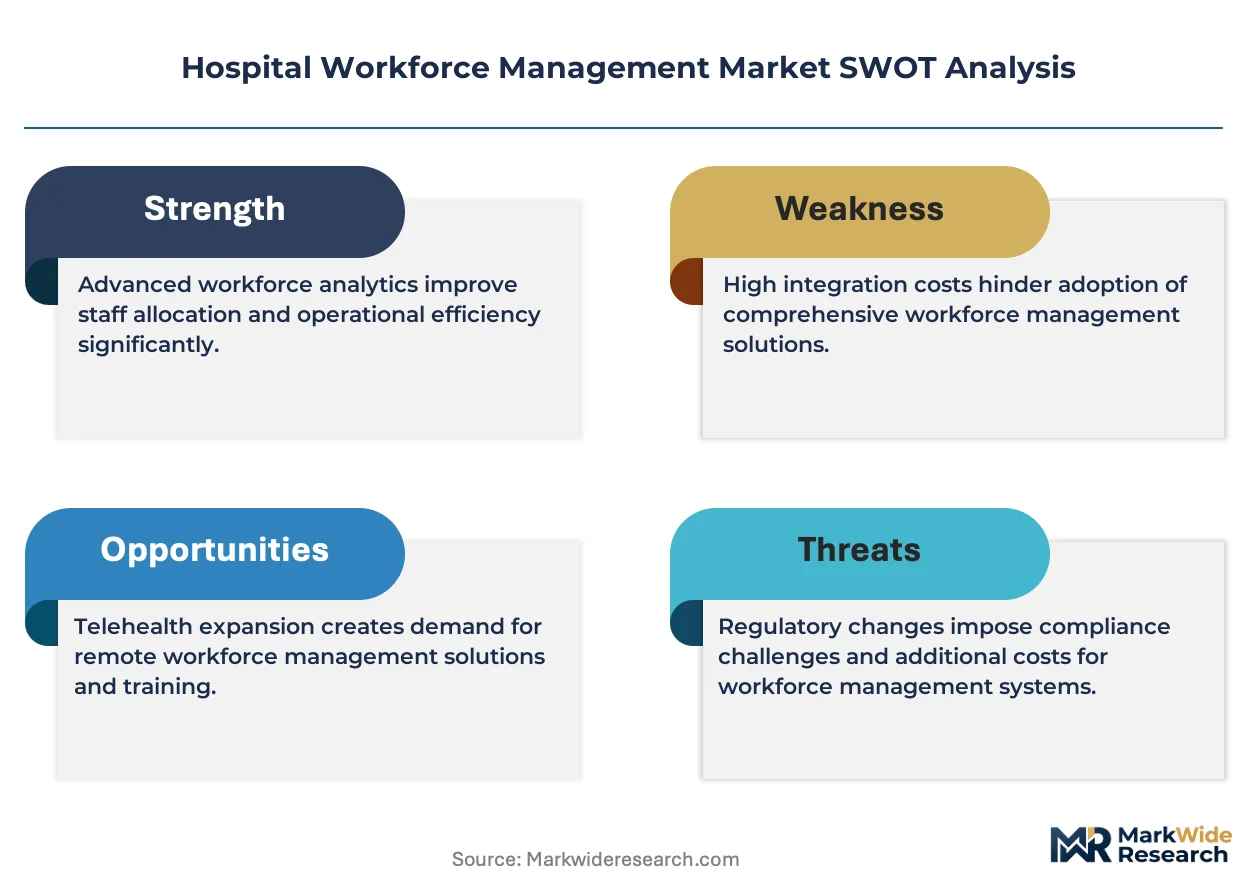
For Market Incumbents: Compound platform stickiness by embedding predictive staffing algorithms deeper into clinical workflows that resist disintermediation. Defend against cloud-native challengers through backward integration into EHR data pipelines that accelerate bidirectional synchronization. Prioritize certification investment in ONC-2015 Edition Cures Act Update compliance to maintain eligibility for federal health system contracts. For New Entrants and Emerging Players: Lead with lightweight mobile-first scheduling tools targeting Critical Access Hospitals in underserved United States counties where enterprise suites prove cost-prohibitive. Capture white-space in OSHA compliance automation by bundling incident tracking with core workforce modules. Pursue go-to-market partnerships with regional group purchasing organizations that aggregate procurement for rural network members. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertical specialists with proven EHR integration capabilities over horizontal HCM platforms. Long-term viability hinges on AI-native scheduling tools that navigate emerging FDA liability frameworks for clinical decision-support functions. Watch for inflection when state-level nurse staffing ratio laws expand beyond California and Massachusetts to trigger automated tracking mandates.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Development | ONC Cures Act mandates require bidirectional EHR data exchange that legacy systems cannot support. |
| AI-Native Scheduling Platform Launch | FDA scrutiny of algorithmic nurse-to-patient recommendations demands segregated suggestion-execution workflows. |
| Strategic EHR Vendor Partnership | Epic and Cerner integration certifications gate access to large United States health system procurement. |
| Acquisition of Clinical Informatics Specialist | Scarce talent bridging nursing workflows with system configuration commands premium compensation and implementation risk. |
| Rural Health Network Expansion | Critical Access Hospitals in underserved counties present untapped demand for subscription-based lightweight tools. |
Research Methodology
A spread of perspectives from chief nursing officers, health system CFOs, clinical informatics specialists, and group purchasing organization contract managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with workforce technology procurement committees and secondary validation against hospital procurement databases, CMS Medicare cost report filings, and ONC interoperability certification records. Bottom-up sizing of installed base and top-down cross-check against health system IT expenditure benchmarks ensured triangulation integrity.
Segmentation dimensions modeled include delivery model, organization scale, application priority, and regional regulatory cluster across the projection horizon. CAGRs were derived from trend extrapolation of replacement cycles for legacy COBOL systems and adoption curves for predictive analytics modules. Forecast inputs incorporated registered nurse vacancy rate trajectories and state-level staffing mandate expansion probabilities.
Forecasts assume regulatory continuity in ONC Cures Act implementation and OSHA recordkeeping requirements; material policy shifts would require re-modeling of procurement timeline assumptions. Revision becomes warranted when FDA guidance on clinical decision-support liability crosses enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Professional Spa Services Market
Healthcare Services
Tissue Banking Market
Healthcare Services
US Sterilization Services Market
Healthcare Services
US Acute Hospital Care Market
Healthcare Services
Immunoassay CDMO Market
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
Canada Senior Living Market
Healthcare Services
Medical Case Management Services Market
Healthcare Services
Healthcare Staffing Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Chronic Disease Management Service Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Direct-To-Patient Healthcare Logistics Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
Medical Devices and Equipment Logistics Market