
 Biopharmaceutical Third Party Logistics (3PL) Market | 2026-2036
Biopharmaceutical Third Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Biopharmaceutical Third Party Logistics (3PL) Market Intelligence
Direct-to-patient distribution channels is narrowing as biopharmaceutical manufacturers consolidate logistics partnerships around validated cold chain networks. FedEx sustains dominance in time-critical biologics transport through its temperature-controlled express infrastructure spanning six continents. DHL International GmbH differentiates via pharmaceutical-certified warehousing and dedicated healthcare compliance teams embedded in regional hubs. KUEHNE + NAGEL anchors European biologics distribution with specialized reefers and active thermal packaging systems certified for cell therapy payloads.
Biopharmaceutical Third Party Logistics (3PL) encompasses outsourced supply chain management for temperature-sensitive biological products, requiring continuous cold chain maintenance between minus 80 degrees Celsius and plus 25 degrees Celsius depending on payload stability profiles. The discipline integrates real-time environmental monitoring, validated packaging, and regulatory documentation to prevent thermal excursions that compromise product efficacy. Warehousing and cold chain management together command the deepest margin pools as pharmaceutical companies outsource capital-intensive infrastructure rather than build in-house capabilities. Transportation segments face margin compression from fuel volatility, though air freight retains premium pricing for clinical trial materials requiring rapid global deployment. IoT solutions and data analytics represent the fastest-growing technology layer as shippers demand predictive visibility into shipment integrity.
FDA enforcement of the Drug Supply Chain Security Act, EMA's Falsified Medicines Directive, and WHO Good Distribution Practice standards collectively mandate serialized track-and-trace systems for all pharmaceutical logistics providers. These frameworks compel 3PL operators to invest in blockchain-enabled verification platforms and temperature logging infrastructure as baseline market access requirements. Stakeholders must monitor evolving cell therapy logistics protocols where chain-of-identity documentation now rivals physical cold chain integrity as a compliance threshold.
Market Dynamics
Cell and gene therapy commercialization is compressing logistics timelines and forcing 3PL operators to reconfigure infrastructure around patient-specific chain-of-identity protocols rather than bulk pharmaceutical distribution models.
Growth Catalysts
- FDA Drug Supply Chain Security Act serialization mandates:Track-and-trace requirements compel pharmaceutical manufacturers to outsource compliance-capable logistics infrastructure rather than build proprietary systems.
- Cell therapy cold chain protocols:Cryogenic transport requirements between minus 150 and minus 196 degrees Celsius for CAR-T and gene-modified cell products create specialized demand for validated ultra-low temperature infrastructure.
- German biotech cluster concentration:Heidelberg, Munich, and Berlin anchor European cell therapy manufacturing, concentrating demand for pharmaceutical-certified warehousing and dedicated healthcare compliance teams within a 500-kilometer radius.
Market Restraints
- Jet fuel price volatility:Air freight constitutes the dominant mode for clinical trial materials and temperature-critical biologics, exposing margins to energy market fluctuations without contractual pass-through mechanisms.
- Active thermal packaging capex concentration:Phase change materials and electric refrigeration units for cell therapy payloads require specialized manufacturing capacity concentrated among three European and North American suppliers.
- EMA Falsified Medicines Directive verification delays:Serialized authentication infrastructure deployment has created bottlenecks at customs checkpoints, extending cross-border transit times for temperature-sensitive shipments.
Strategic Opportunities
- Direct-to-patient distribution models:Home infusion and decentralized clinical trial administration channels bypass traditional hospital pharmacy receiving, requiring last-mile cold chain capabilities that incumbent parcel networks underserve.
- WHO Good Distribution Practice harmonization:Emerging market regulators in Southeast Asia and Latin America are adopting WHO standards, creating certification pathway opportunities for 3PL operators with existing EU or US compliance infrastructure.
- Blockchain-IoT convergence:Distributed ledger verification combined with real-time temperature logging enables autonomous compliance documentation, reducing manual audit overhead for multi-modal pharmaceutical shipments.
Industry Challenges
- Qualified Person certification scarcity:EMA mandates require named individuals with pharmaceutical logistics expertise to sign off on GDP compliance, creating recruitment bottlenecks as cell therapy volumes expand.
- Legacy warehouse management system integration:Pharmaceutical serialization data streams require API connectivity with customer ERP platforms, forcing mid-tier 3PL operators into expensive middleware development or platform replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopharmaceutical Third Party Logistics (3PL) Market |
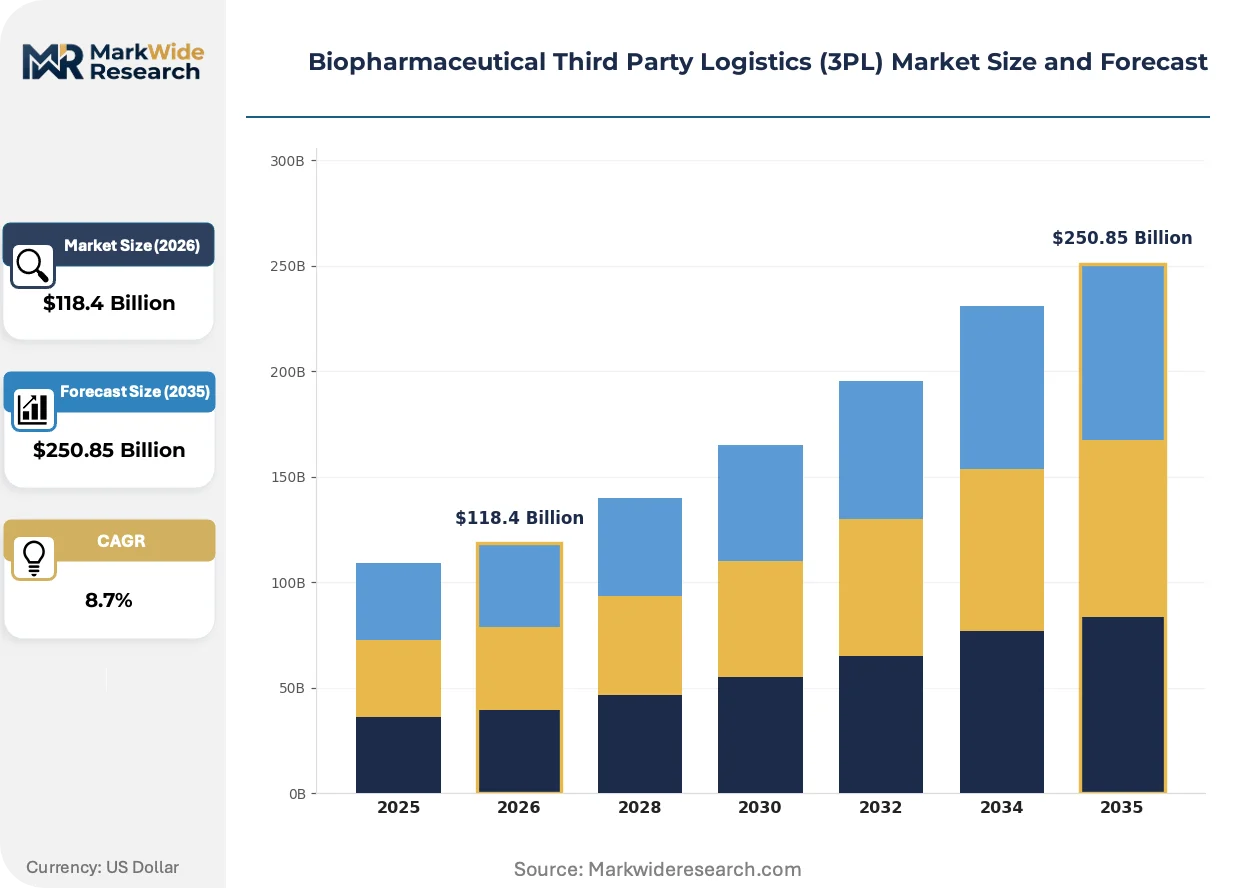
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $250.85 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Transportation, Packaging, Distribution End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Hospitals Technology: IoT Solutions, Cold Chain Management, Automation, Data Analytics Delivery Mode: Road Transport, Air Freight, Rail Transport, Sea Freight |
| Companies Covered | FedEx, DHL International GmbH, United Parcel Service (UPS), KUEHNE + NAGEL, DB Schenker, AmerisourceBergen Corporation, SF Express, CEVA Logistics, Kerry Logistics Network Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopharmaceutical Third Party Logistics (3PL) Market Strategic Shifts & Innovations
Digitization of supply chain verification is compressing compliance timelines and enabling predictive intervention before thermal excursions compromise product integrity. Three developments dominate current investment patterns.
Digital twin platforms are replicating physical cold chain infrastructure in software environments to simulate failure scenarios and optimize packaging configurations. Cell therapy manufacturers in Germany and Switzerland are deploying these systems for regulatory submission support. The technology is virtualizing traditional qualification protocols that previously required physical shipment testing.
EMA's strengthened Annex 1 manufacturing guidelines are extending environmental monitoring requirements into logistics operations, compelling 3PL operators to install continuous particle counting and microbial detection in pharmaceutical warehousing. This regulatory tightening most affects sterile injectable distribution, where German and Dutch hubs are retrofitting classified cleanroom storage zones to maintain manufacturing-grade conditions through final delivery.
Consolidation of biopharmaceutical manufacturing into single-source sites is elongating distribution distances and intensifying contingency planning requirements. Manufacturers are now mandating dual-qualified 3PL relationships with geographically separated backup facilities rather than sole-source contracts. This pattern concentrates most visibly in Belgium and Ireland, where clustered biologics production sites serve European patient populations through centralized distribution models that amplify single-point-of-failure risk.
Biopharmaceutical Third Party Logistics (3PL) Market Segmentation
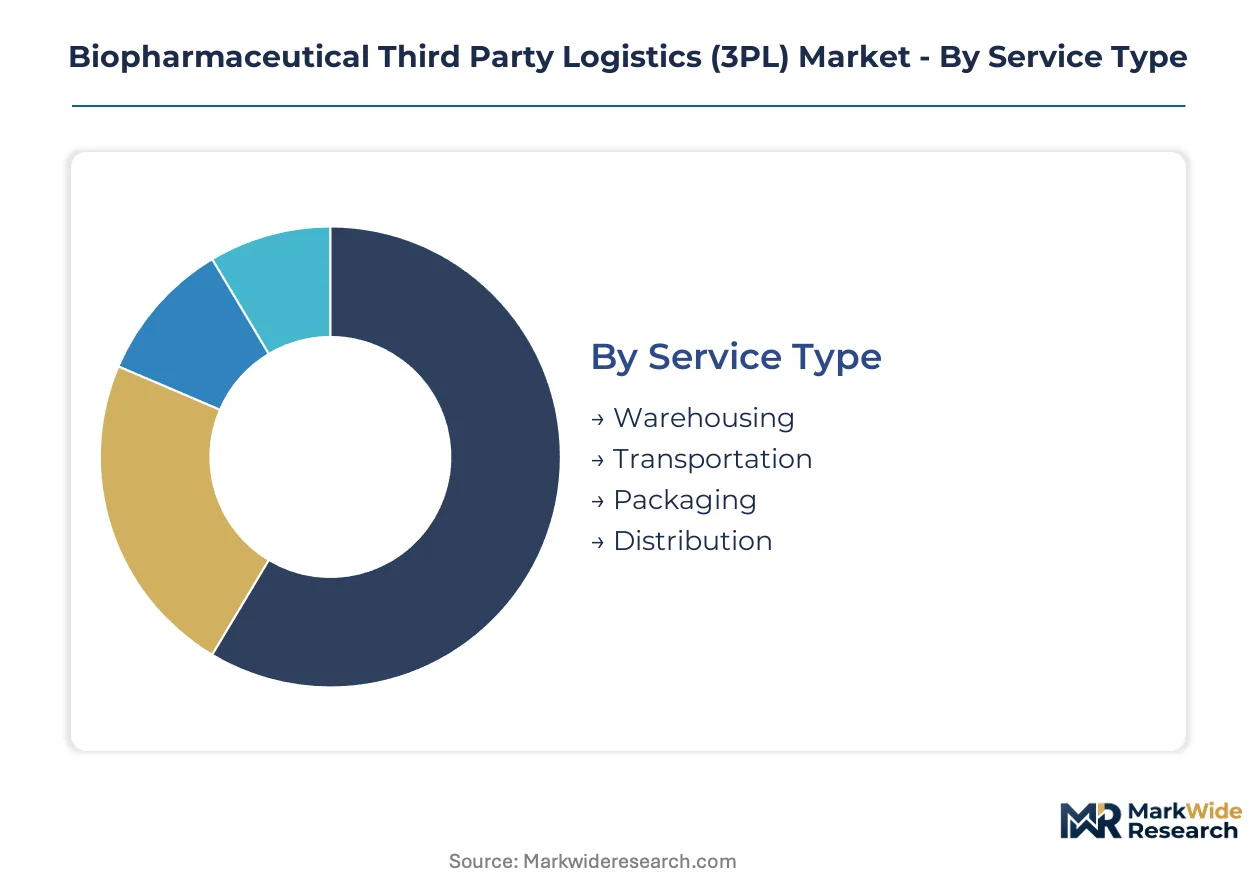
Biopharmaceutical 3PL segmentation reflects divergent capital intensity and regulatory burden across service layers. Temperature-sensitive biologics demand specialized infrastructure that reshapes vendor selection criteria and contract structures.
Service Type:
After-sales service intensity varies dramatically, with warehousing commanding embedded compliance teams and 24/7 environmental monitoring versus transactional transportation brokerage.
- Warehousing:Pharmaceutical-certified facilities maintain continuous temperature mapping between minus 80 and plus 25 degrees Celsius with redundant backup systems. German biotech clusters in Heidelberg and Munich concentrate demand for GDP-compliant storage with Qualified Person oversight.
- Transportation:Time-critical biologics movement requires validated cold chain equipment with real-time GPS tracking and automated excursion alerts. Air freight dominates clinical trial materials and cell therapy payloads where transit speed outweighs cost.
- Packaging:Active thermal systems using phase change materials or electric refrigeration protect ultra-low temperature payloads. Three European and North American suppliers control specialized manufacturing capacity for minus 150 degree Celsius cell therapy containers.
- Distribution:Last-mile capabilities integrate with hospital pharmacy systems and emerging direct-to-patient channels for home infusion therapies. EMA serialization mandates require blockchain-enabled verification at every handoff point.
Warehousing holds the largest share; momentum sits with distribution as decentralized clinical trial models expand.
End User:
Customer scale determines contract structure, with large pharmaceutical manufacturers demanding dedicated infrastructure versus shared-service models for mid-tier biotechnology firms.
- Pharmaceutical Companies:Multinational manufacturers outsource entire distribution networks to achieve FDA and EMA compliance without capital deployment. Serialization mandates compel partnership with 3PL operators possessing validated track-and-trace infrastructure.
- Biotechnology Firms:Cell and gene therapy developers require cryogenic logistics expertise that traditional pharmaceutical distribution lacks. CAR-T manufacturers in Germany and Switzerland drive fastest adoption of ultra-low temperature chain-of-identity protocols.
- Research Institutions:Academic medical centers and contract research organizations need flexible clinical trial logistics with rapid protocol adaptation. Demand concentrates in Boston and Basel corridor institutions.
- Hospitals:Receiving pharmacy operations require validated cold storage with immediate temperature verification upon delivery. EMA Annex 1 guidelines now extend cleanroom-grade environmental monitoring into hospital storage zones.
Pharmaceutical companies dominate contract value; biotechnology firms are climbing the fastest as cell therapy commercialization accelerates.
Technology:
Technology layers differentiate margin capture, with predictive analytics commanding premium pricing versus commoditized sensor hardware.
- IoT Solutions:Connected devices stream temperature, humidity, shock, and light exposure data to centralized monitoring platforms. Real-time alerts enable intervention before thermal excursions compromise product integrity.
- Cold Chain Management:Integrated systems coordinate packaging selection, route optimization, and contingency planning for temperature-sensitive shipments. German operators lead deployment of digital twin platforms for regulatory submission support.
- Automation:Robotic picking and automated storage retrieval systems minimize human contact in pharmaceutical warehousing. EMA strengthened guidelines drive investment in continuous particle counting and microbial detection.
- Data Analytics:Predictive algorithms identify failure patterns and optimize packaging configurations before physical testing. Blockchain-IoT convergence enables autonomous compliance documentation reducing manual audit overhead.
Cold chain management anchors current spending; data analytics shows steepest expansion trajectory as predictive capabilities mature.
Delivery Mode:
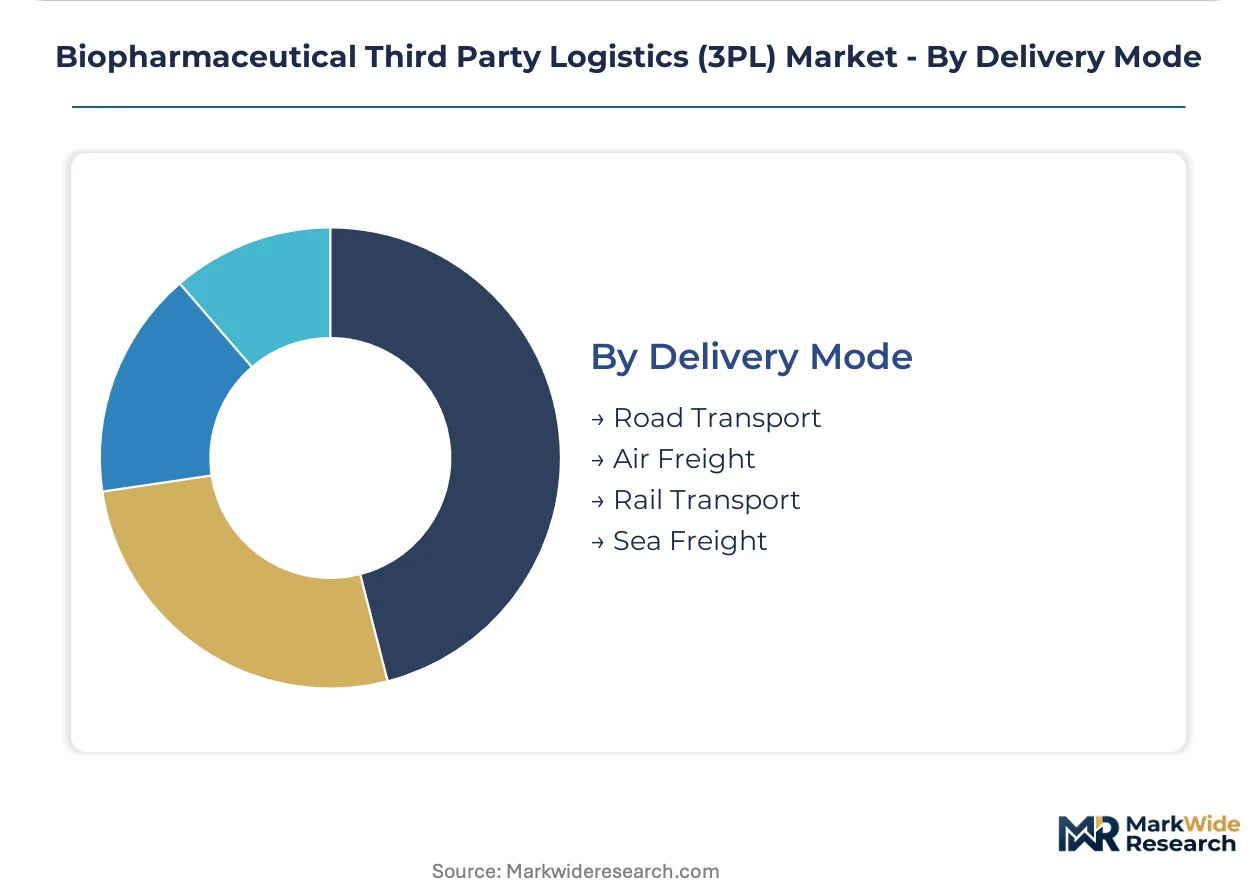
Modal selection reflects speed-cost tradeoffs with clinical trial materials and cell therapies requiring air freight despite fuel volatility exposure.
- Road Transport:Refrigerated trucking serves regional distribution networks within 500-kilometer radii of manufacturing clusters. European pharmaceutical corridors between Belgium, the Netherlands, and Germany rely on validated reefer fleets with continuous monitoring.
- Air Freight:Express networks dominate intercontinental biologics movement with temperature-controlled containers and priority handling. Jet fuel price volatility compresses margins without contractual pass-through mechanisms.
- Rail Transport:Dedicated pharmaceutical rail services offer intermediate speed with lower carbon intensity for bulk non-urgent shipments. Limited specialized infrastructure constrains adoption outside European core networks.
- Sea Freight:Ocean containers with active refrigeration serve cost-sensitive bulk pharmaceutical movements with extended lead times. Temperature stability requirements and piracy risk limit applicability for high-value biologics.
Air freight commands premium pricing; road transport gains share fastest as manufacturing regionalization shortens distribution distances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German 3PL operators extract pricing premiums of 15-20% above North American peers for cell therapy logistics, reflecting specialized cryogenic infrastructure concentration and EMA Qualified Person certification scarcity. This asymmetry widens as FDA serialization mandates force US manufacturers toward European compliance architectures.
United States
FDA Drug Supply Chain Security Act enforcement compels pharmaceutical manufacturers to outsource track-and-trace infrastructure rather than build proprietary systems. The Greater Boston corridor anchors cell therapy manufacturing clusters where cryogenic logistics demand concentrates around CAR-T commercialization sites. FedEx and UPS maintain temperature-controlled express networks serving decentralized clinical trial distribution models.
Germany
EMA Falsified Medicines Directive verification requirements create compliance bottlenecks at customs checkpoints, extending cross-border transit times for temperature-sensitive shipments. Heidelberg, Munich, and Berlin biotech clusters concentrate demand for pharmaceutical-certified warehousing within a 500-kilometer radius. KUEHNE + NAGEL and DB Schenker anchor specialized reefer infrastructure serving European cell therapy manufacturers.
Switzerland
Swissmedic pharmaceutical regulations align with EMA standards while maintaining distinct national serialization requirements. Basel anchors Novartis and Roche manufacturing sites driving demand for GDP-compliant distribution with continuous environmental monitoring. Digital twin platforms for regulatory submission support are deploying fastest among Swiss cell therapy developers.
China
NMPA Good Distribution Practice harmonization with WHO standards accelerates cross-border pharmaceutical logistics certification. Yangtze River Delta biotech clusters in Shanghai and Suzhou concentrate domestic cell therapy manufacturing demand. SF Express is expanding temperature-controlled pharmaceutical networks to capture outbound biologics distribution from NMPA-registered facilities.
India
CDSCO pharmaceutical export regulations mandate cold chain documentation for temperature-sensitive biologics shipments to regulated markets. Hyderabad and Bengaluru vaccine manufacturing clusters drive demand for validated air freight infrastructure with real-time temperature logging. Domestic 3PL operators are investing in WHO Good Distribution Practice certification to access European and US pharmaceutical supply chains.
Biopharmaceutical Third Party Logistics (3PL) Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in packaging and monitoring technology. The market structure consolidates around three global express networks with pharmaceutical-certified infrastructure, while regional operators compete on EMA compliance specialization and last-mile density. Two strategic archetypes dominate: integrated logistics platforms with six-continent cold chain networks, and regional specialists with embedded Qualified Person teams and GDP-certified warehousing. Competitive moves concentrate on M&A for cryogenic packaging capabilities and strategic partnerships for cell therapy chain-of-identity protocols.
Among integrated platform operators, FedEx, DHL International GmbH, and United Parcel Service occupy positions as archetypal infrastructure owners with pharmaceutical-certified express networks spanning multiple continents. These entities represent the scale-driven tier where temperature-controlled air freight and validated warehousing combine to serve multinational pharmaceutical manufacturers. Regional specialists including KUEHNE + NAGEL and DB Schenker exemplify the European compliance-focused archetype, anchoring GDP-certified operations within German biotech clusters. The competitive dynamic pits global reach against regulatory specialization, with EMA Qualified Person certification scarcity creating defensive moats for European operators.
| Leading Market Players |
|---|
| FedEx |
| DHL International GmbH |
| United Parcel Service (UPS) |
| KUEHNE + NAGEL |
| DB Schenker |
| AmerisourceBergen Corporation |
| SF Express |
| CEVA Logistics |
| Kerry Logistics Network Limited |
| Others |
Cost & Logistics Intelligence
Heidelberg's cryogenic logistics cluster anchors European cell therapy pricing power through EMA Qualified Person certification scarcity and specialized minus 196 degrees Celsius infrastructure concentration. German 3PL operators extract 15-20% premiums over North American peers as FDA serialization mandates force US manufacturers toward European compliance architectures.
Pricing Analysis
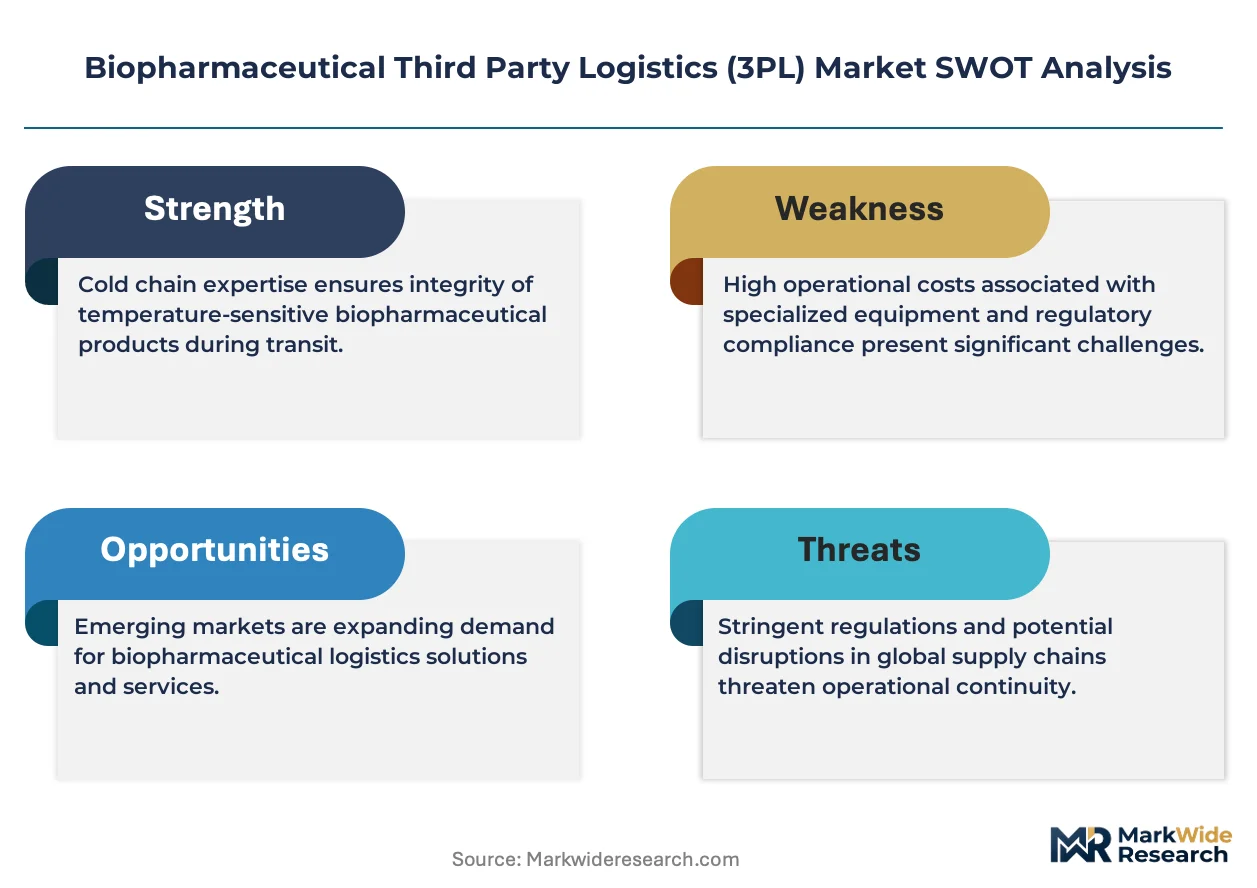
The customization-premium spread separates standard pharmaceutical warehousing from cell therapy chain-of-identity protocols requiring patient-specific documentation and cryogenic handling. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with GDP-compliant cold chain services commanding highest tiers and generic freight brokerage occupying lowest. Cost compression in air freight tiers is intensifying because jet fuel volatility lacks contractual pass-through mechanisms. Biotechnology firms show highest price sensitivity due to clinical-stage cash constraints, while multinational pharmaceutical manufacturers prioritize compliance assurance over rate negotiation.
Supply Chain Analysis
Contract manufacturing concentration for active thermal packaging rests with three European and North American suppliers controlling phase change materials and electric refrigeration units for ultra-low temperature payloads. Geographic supply concentrates in Germany, Switzerland, and Belgium where biotech clusters anchor GDP-certified warehousing infrastructure. Raw material dependencies include specialized refrigerants, validated temperature loggers, and serialized authentication hardware. Single-source vulnerability pervades cryogenic container manufacturing where qualification timelines deter supplier switching. Distribution runs through hub-and-spoke models with regional cold chain facilities feeding last-mile hospital pharmacy and emerging direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell therapy commercialization cycles favor logistics operators with established cryogenic infrastructure as biopharmaceutical manufacturing investment recovers from post-pandemic normalization.
For Market Incumbents: Insulate margin position through backward integration into active thermal packaging manufacturing and captive Qualified Person certification programs. Capacity addition in Swiss and German biotech corridors defends against regional specialists encroaching on multinational accounts. EMA Annex 1 guideline tightening threatens operators lacking cleanroom-grade warehousing retrofit capabilities. For New Entrants and Emerging Players: Pursue direct-to-patient distribution white space where incumbent parcel networks underserve home infusion cold chain requirements. Southeast Asia and Latin America present most penetrable geographies as WHO Good Distribution Practice harmonization creates certification pathway opportunities. Partner with cell therapy developers for chain-of-identity protocol co-development rather than competing on transportation rates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform integrators with blockchain-IoT convergence capabilities over component hardware suppliers. Long-term viability hinges on autonomous compliance documentation reducing manual audit overhead. Acquisition target archetype: regional specialists with embedded EMA compliance teams and GDP-certified warehousing in underserved biotech corridors. Monitor NMPA Good Distribution Practice harmonization progress as inflection indicator for Chinese market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Packaging Capability Acquisition | Secures minus 196 degrees Celsius handling credentials required for CAR-T commercialization. |
| Blockchain-IoT Platform Integration | Enables autonomous EMA serialization compliance reducing manual documentation overhead. |
| Direct-to-Patient Channel Development | Captures decentralized clinical trial and home infusion logistics growth. |
| EMA Qualified Person Certification Investment | Creates defensive moat against regulatory capacity constraints in European biotech clusters. |
| Digital Twin Platform Deployment | Virtualizes cold chain qualification protocols accelerating cell therapy regulatory submissions. |
Research Approach
Initial hypotheses were tested against primary input from supply chain directors at cell therapy manufacturers, EMA regulatory affairs leads, hospital pharmacy procurement managers, and cold chain operations specialists and refined through secondary validation. FDA Drug Supply Chain Security Act filings, EMA GDP inspection reports, ClinicalTrials.gov logistics protocol disclosures, and WHO Good Distribution Practice certification databases anchored secondary research. Bottom-up service provider capacity modeling and top-down pharmaceutical outsourcing spend analysis triangulated market sizing.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning service type, end user archetype, technology layer, and delivery mode plus regional regulatory cluster differentiation. CAGRs derived from logistic curve adoption modeling for cell therapy commercialization and pharmaceutical outsourcing penetration rates. Jet fuel price volatility scenarios and EMA serialization mandate implementation timelines informed sensitivity bounds.
Sensitivities concentrate around cell therapy approval velocity, cryogenic infrastructure capacity expansion rates, and cross-border customs verification delays. Forecasts reflect documented assumptions regarding biopharmaceutical manufacturing regionalization trends and regulatory harmonization progress. Quarterly review of NMPA certification alignment, EMA Annex 1 guideline enforcement intensity, and active thermal packaging supplier capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
Primary Care Physicians Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Global Retirement Home Services Market
Healthcare Services
US Sterilization Services Market
Healthcare Services
Global Medical Affairs Outsourcing Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
Sterilization Services Market
Healthcare Services
Funeral Goods and Services Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
US Post-Acute Care (PAC) Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
US Long Term Care Market
Healthcare Services
Hospital Outsourcing Market
Healthcare Services
Medical Recruitment Market