
 UK Pharmaceutical Logistics Market | 2026-2036
UK Pharmaceutical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
UK Pharmaceutical Logistics Market Insights
UK cold storage infrastructure is repositioning around biologics handling requirements. DHL Supply Chain leverages its Heathrow pharmaceutical hub to anchor temperature-controlled throughput for international vaccine flows. Kuehne + Nagel sustains specialized GDP-certified warehousing capacity across the Midlands, competing for contracts with domestic biotech manufacturers. UPS Healthcare differentiates through real-time chain-of-custody tracking, extending its service layer beyond pure transport into compliance documentation.
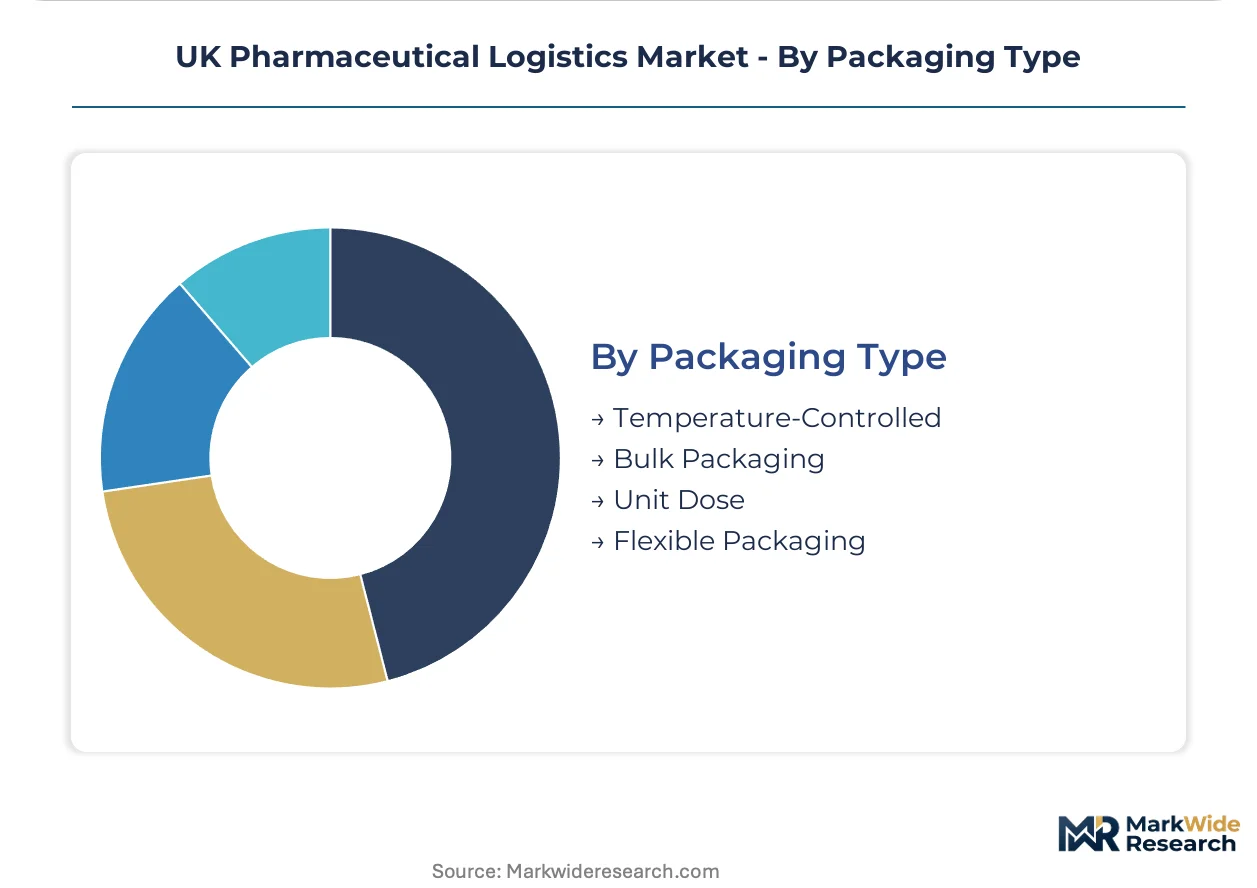
Pharmaceutical logistics encompasses the temperature-controlled movement, storage, and distribution of medicinal products under Good Distribution Practice standards requiring validated cold chain maintenance between two and eight degrees Celsius for most biologics. The discipline ensures therapeutic efficacy from manufacturer through to hospital, pharmacy, or patient administration point. Cold chain services command premium positioning within the service type dimension because biologics and cell therapies degrade irreversibly outside narrow thermal bands. Last-mile delivery to hospitals represents the fastest-growing delivery mode segment as NHS trusts adopt direct-to-site replenishment to reduce inventory carrying costs. Temperature-controlled packaging dominates the packaging type category, with flexible packaging formats gaining traction for clinical trial shipments requiring variable dose configurations.
The Medicines and Healthcare products Regulatory Agency enforces GDP compliance through unannounced inspections, while the Human Medicines Regulations 2012 establish legal frameworks for wholesale distribution licensing. Health and Safety Executive protocols govern occupational exposure during hazardous pharmaceutical handling, shaping warehouse design and staff certification requirements. Stakeholders must monitor MHRA guidance evolution on post-Brexit recognition of EU manufacturing and distribution sites, as regulatory divergence would force parallel qualification pathways and duplicate inventory positioning.
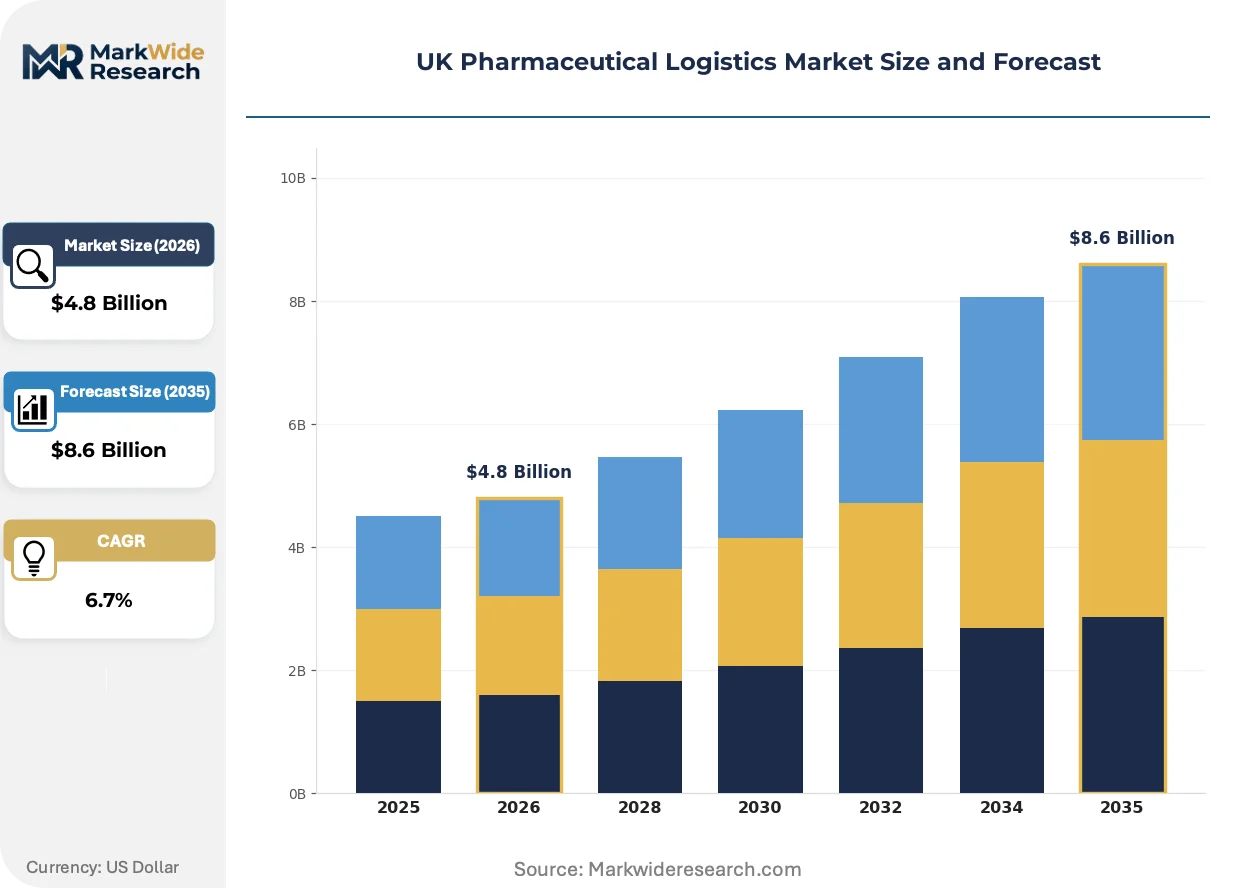
Market Dynamics
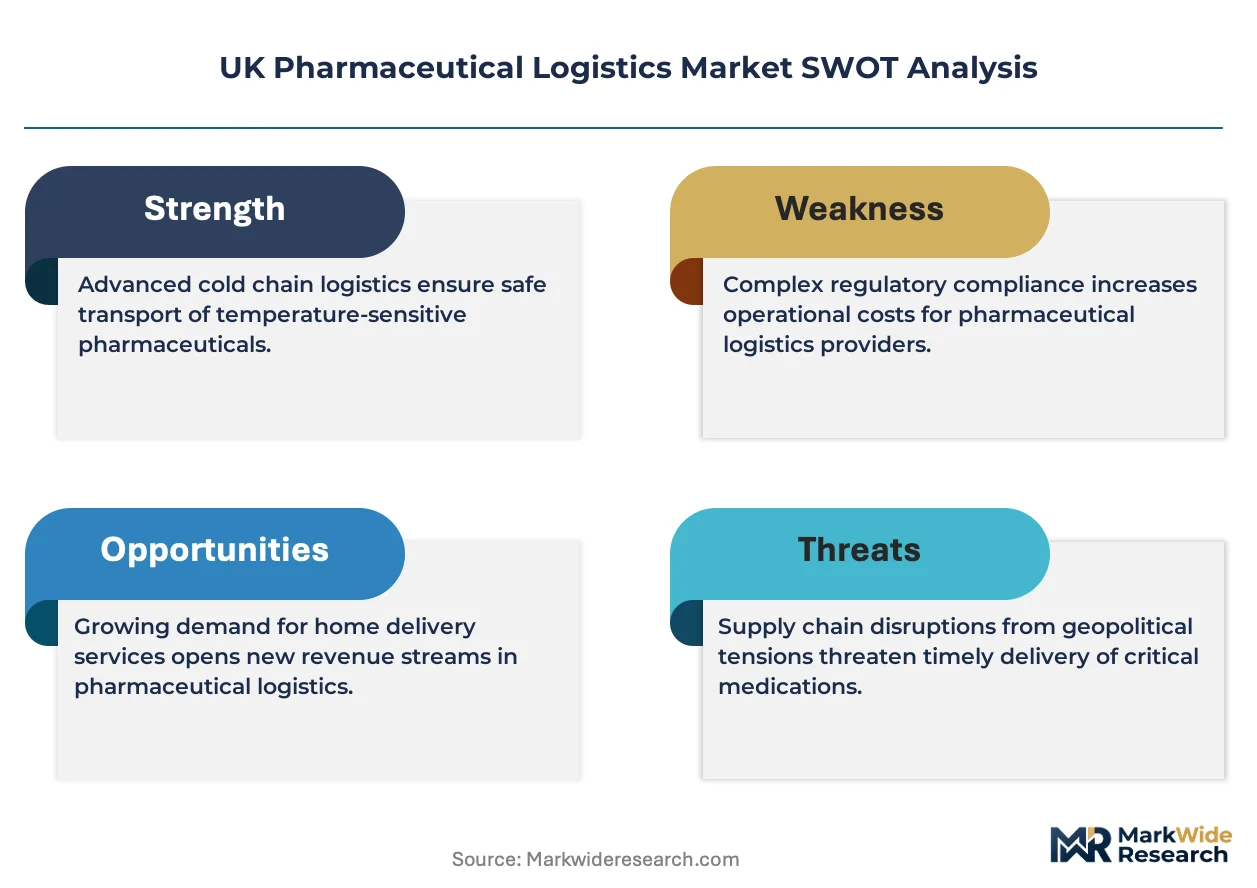
Biologics proliferation across NHS hospital networks is forcing wholesale cold chain infrastructure reinvestment, as temperature excursions now trigger automatic batch destruction under tightened MHRA enforcement protocols.
Growth Catalysts
- Human Medicines Regulations 2012:Mandatory wholesale distribution licensing creates compliance barriers that consolidate qualified logistics capacity around GDP-certified operators serving NHS trusts.
- Cell therapy manufacturing:Domestic biotech production clusters in Oxford-Cambridge corridor generate specialized cryogenic transport demand requiring validated minus eighty degrees Celsius handling protocols.
- Heathrow pharmaceutical corridor:Concentration of temperature-controlled air freight capacity near the airport anchors international vaccine distribution flows through UK gateway operations.
Market Restraints
- Dry ice supply volatility:Carbon dioxide capture plant outages disrupt cryogenic packaging availability for clinical trial shipments requiring sustained sub-zero thermal protection.
- Midlands warehousing concentration:GDP-certified cold storage capacity clusters around Birmingham-Leicester axis, creating single-region exposure for national biologics distribution resilience.
- Post-Brexit regulatory friction:MHRA non-recognition of EU qualified person certifications forces duplicate batch release testing for continental-sourced products.
Strategic Opportunities
- NHS direct-to-site replenishment:Hospital trust adoption of vendor-managed inventory models opens last-mile logistics contracts bypassing traditional wholesale distribution tiers.
- Real-time chain-of-custody tracking:Integration of IoT temperature loggers with blockchain documentation creates premium service differentiation for high-value gene therapy shipments.
- Scottish biotech corridor:Emerging cell therapy manufacturing in Glasgow-Edinburgh cluster lacks proximate GDP-certified cold storage, creating greenfield facility development potential.
Industry Challenges
- Qualified person shortage:GDP-mandated responsible pharmacologist certification bottlenecks constrain warehouse staffing for time-sensitive biologics release operations.
- Legacy WMS integration:Hospital ERP systems require custom API development to accept automated cold chain documentation, delaying direct-to-site service rollout timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Pharmaceutical Logistics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Transportation, Distribution, Cold Chain End User: Pharmaceutical Producers, Wholesalers, Retail Pharmacies, Hospitals Delivery Mode: Direct Shipping, Cross-Docking, Last-Mile Delivery, E-commerce Packaging Type: Temperature-Controlled, Bulk Packaging, Unit Dose, Flexible Packaging |
| Companies Covered | DHL Supply Chain, Kuehne + Nagel, UPS Healthcare, XPO Logistics, DB Schenker, FedEx Supply Chain, Life Couriers UK, Cencora, Inc., Lineage Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Pharmaceutical Logistics Market Trends and Innovations
Cold chain digitization is compressing temperature excursion response windows while regulatory divergence post-Brexit forces parallel qualification investments across UK-EU distribution pathways.
Passive thermal packaging systems incorporating phase-change materials are absorbing validation complexity for clinical trial logistics. Biotech sponsors adopt these formats to reduce dry ice dependency for international investigator site shipments. The technology is absorbing documentation burden from logistics providers by embedding calibrated temperature loggers with automatic cloud upload.
MHRA guidance evolution on post-Brexit recognition of EU manufacturing sites creates qualification pathway uncertainty. Wholesale distributors must maintain parallel inventory positioning against potential regulatory divergence scenarios. Temperature-controlled warehousing operators near Channel ports face highest compliance adaptation exposure.
Hospital pharmacy procurement is consolidating replenishment authority at NHS trust level rather than individual site purchasing. National framework agreements displace fragmented supplier relationships across acute care networks. Greater London trusts demonstrate fastest adoption of centralized vendor-managed inventory contracts.
UK Pharmaceutical Logistics Market Segmentation
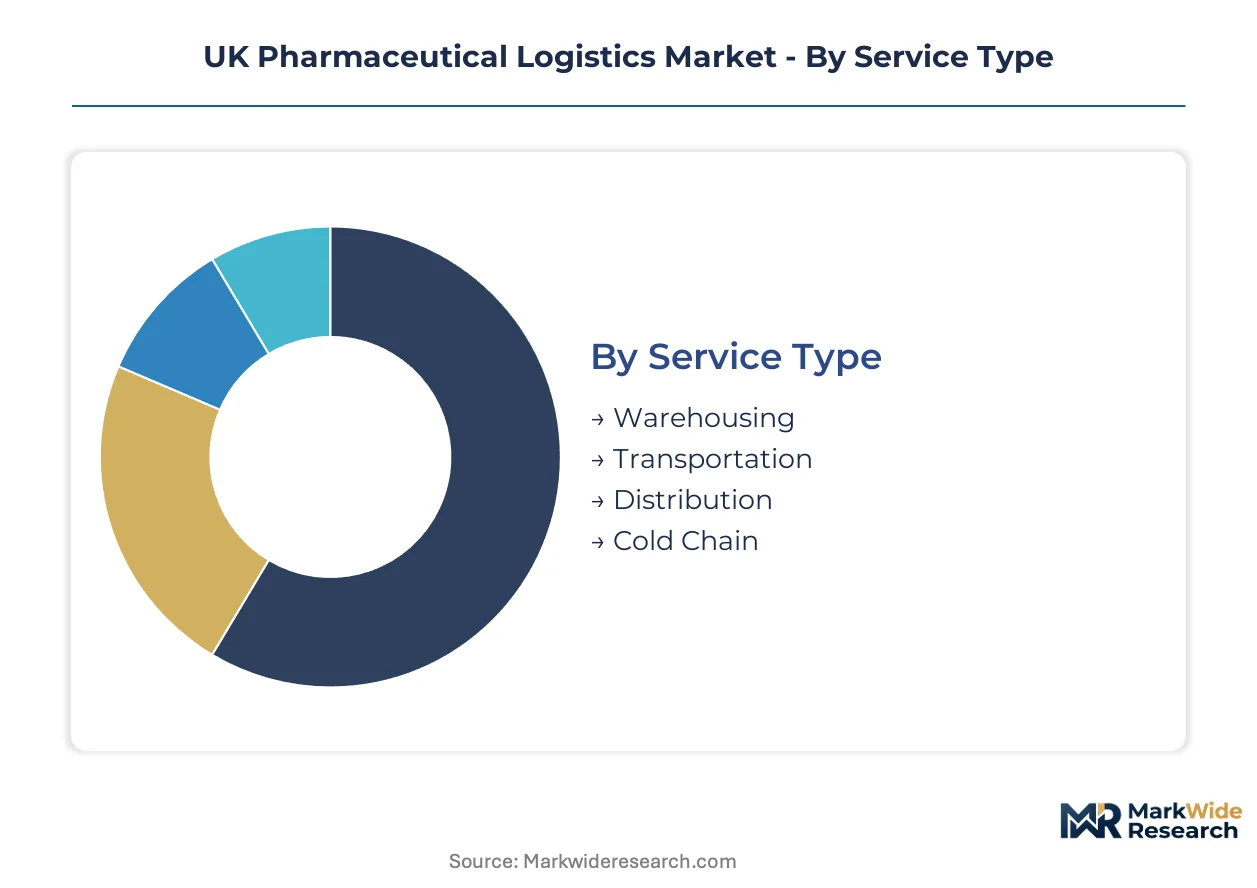
UK pharmaceutical logistics segmentation reflects the tension between GDP compliance mandates and NHS procurement centralization. Service differentiation now hinges on temperature validation capabilities rather than pure transport speed.
Service Type:
Buyer differentiation in this category tracks capital intensity and regulatory certification depth.
- Cold Chain:Validated two-to-eight degrees Celsius handling with continuous temperature monitoring and automated excursion alerting. NHS hospital networks concentrate demand here as biologics procurement expands across acute care trusts, with MHRA GDP enforcement tightening batch destruction protocols for thermal breaches.
- Warehousing:GDP-certified ambient and refrigerated storage with qualified person oversight for batch release operations. The Midlands corridor around Birmingham-Leicester anchors national capacity, though single-region concentration creates resilience vulnerabilities for UK-wide distribution.
- Transportation:Temperature-controlled vehicle fleets with real-time GPS tracking and chain-of-custody documentation.
- Distribution:Multi-node hub operations linking manufacturers to wholesale and hospital endpoints.
Cold Chain leads volumes today; Warehousing is gaining share fastest as inventory positioning complexity rises post-Brexit.
End User:
Procurement authority concentration distinguishes buyers across this dimension.
- Hospitals:NHS trust-level purchasing with vendor-managed inventory contracts and direct-to-site replenishment requirements. Greater London acute care networks demonstrate fastest adoption of centralized frameworks, displacing fragmented site-level supplier relationships.
- Pharmaceutical Producers:Domestic biotech manufacturers in the Oxford-Cambridge corridor generating cryogenic transport demand for cell therapy clinical trials.
- Wholesalers:Licensed distributors serving as intermediaries between manufacturers and pharmacy endpoints.
- Retail Pharmacies:Community pharmacy chains with consolidated ordering patterns and standardized delivery windows.
Hospitals dominate current throughput; Pharmaceutical Producers are expanding most quickly on cell therapy manufacturing growth.
Delivery Mode:
Speed requirements and documentation burden separate buyers in this category.
- Last-Mile Delivery:Direct hospital site replenishment with validated handoff protocols and electronic proof-of-delivery. NHS trusts adopt this mode to reduce inventory carrying costs, though legacy ERP integration delays rollout timelines.
- Direct Shipping:Manufacturer-to-hospital bypass of wholesale tiers for high-value biologics.
- Cross-Docking:Minimal-inventory transfer operations at Heathrow-area hubs for international vaccine flows.
- E-commerce:Patient-direct shipment models with specialized packaging for home administration.
Last-Mile Delivery commands premium positioning today; Direct Shipping is climbing the fastest on biologics value concentration.
Packaging Type:
Validation complexity and shipment scale differentiate buyer needs here.
- Temperature-Controlled:Insulated shippers with phase-change materials or active cooling systems maintaining validated thermal bands. Dry ice supply volatility constrains cryogenic options for clinical trial shipments requiring sustained sub-zero protection.
- Flexible Packaging:Variable-dose configurations for investigator site shipments with embedded IoT loggers and automatic cloud documentation upload.
- Bulk Packaging:Pallet-level thermal protection for wholesale distribution with standardized handling protocols.
- Unit Dose:Individual patient-level packaging with tamper-evident seals and dosing instruction integration.
Temperature-Controlled leads current deployment; Flexible Packaging is gaining share fastest on clinical trial logistics expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands Europe's densest pharmaceutical logistics network while the United Kingdom concentrates specialized biologics handling around a single air freight gateway. France and the Netherlands anchor continental distribution resilience through divergent regulatory postures toward cross-border qualification.
Germany
Domestic biotech manufacturing in the Rhine-Main and Munich clusters generates sustained cold chain demand for cell therapy exports. The country's national pharmaceutical regulator enforces GDP compliance through the regional competent authorities of the Länder, creating decentralized inspection intensity. Frankfurt Airport anchors continental vaccine transshipment with dedicated pharmaceutical handling terminals operated by temperature-certified ground handlers.
United Kingdom
NHS trust procurement centralization drives last-mile logistics contracts toward vendor-managed inventory models. The Medicines and Healthcare products Regulatory Agency tightened GDP guidelines for cold chain validation following post-Brexit regulatory autonomy. The Heathrow pharmaceutical corridor concentrates temperature-controlled air freight capacity where DHL Supply Chain and Kuehne + Nagel maintain GDP-certified hubs for international biologics flows.
France
Paris-region hospital networks expand direct-to-site replenishment for temperature-sensitive oncology biologics. ANSM maintains mutual recognition pathways with EMA qualified person certifications, reducing duplicate batch release friction for continental-sourced products. The Île-de-France logistics basin clusters pharmaceutical distribution around Roissy-Charles de Gaulle with specialized cold storage infrastructure for clinical trial exports.
Netherlands
Rotterdam and Amsterdam ports anchor sea-air pharmaceutical transshipment for Asian-manufactured APIs entering European distribution. The country's national pharmaceutical regulator enforces GDP through the Health and Youth Care Inspectorate with unannounced warehouse inspections. The Randstad logistics corridor maintains surplus cold storage capacity serving as contingency positioning for UK-bound shipments facing Channel crossing disruption.
Switzerland
Basel-centered pharmaceutical manufacturing generates high-value biologics requiring validated cryogenic transport for global clinical trials. Swissmedic maintains autonomous GDP enforcement while preserving bilateral recognition agreements with EU qualified person frameworks. The Zurich logistics cluster specializes in gene therapy shipment handling with dedicated minus eighty degrees Celsius packaging validation facilities.
UK Pharmaceutical Logistics Market Competitive Landscape
UK-based operators anchor the domestic last-mile tier; continental European specialists hold gateway and international forwarding positions. The market structures around three tiers: integrated global forwarders with Heathrow pharmaceutical hubs, regional cold chain specialists serving NHS trusts, and niche clinical trial couriers handling investigator site logistics. Consolidation pressure concentrates among mid-scale operators lacking GDP certification depth. Dominant competitive moves include strategic partnerships with biotech manufacturers for dedicated capacity and technology licensing for real-time chain-of-custody documentation.
Within the integrated global tier, DHL Supply Chain and Kuehne + Nagel occupy positions exemplifying capital-intensive cold chain infrastructure deployment. UPS Healthcare represents the technology-differentiated archetype with tracking and compliance documentation capabilities. These three entities anchor the competitive structure while smaller specialists including Life Couriers UK and Lineage Logistics occupy niche segments requiring specialized handling protocols.
| Leading Market Players |
|---|
| DHL Supply Chain |
| Kuehne + Nagel |
| UPS Healthcare |
| XPO Logistics |
| DB Schenker |
| FedEx Supply Chain |
| Life Couriers UK |
| Cencora, Inc. |
| Lineage Logistics |
| Others |
Pricing and Supply Chain Analysis
Captive warehousing investments by NHS trusts are reshaping how pharmaceutical logistics providers anchor both supply position and pricing power. Vertical integration into temperature-controlled storage reduces third-party dependency while compressing margin capture for wholesale distributors serving Greater London hospital networks.
Pricing Analysis
Capacity additions in the Midlands corridor are reshaping price floors across GDP-certified warehousing tiers. Three-tier pricing structure across premium cold chain, standard ambient, and economy bulk distribution segments reflects certification depth and thermal validation rigor. Cost compression in economy tiers is intensifying because NHS procurement centralization aggregates volume leverage at trust level. Hospital pharmacy buyers demonstrate highest price sensitivity for ambient storage, while cell therapy manufacturers accept premium positioning for validated minus eighty degrees Celsius handling.
Supply Chain Analysis
Dual-sourcing requirements mandated by MHRA GDP guidelines force wholesalers to qualify redundant cold storage providers across separate geographic nodes. Supply concentrates in the United Kingdom and Ireland for pharmaceutical distribution, with API manufacturing drawing from India and China. Carbon dioxide capture infrastructure, qualified person labor pools, and temperature-controlled vehicle fleets constitute critical input dependencies. Single-region warehousing concentration around Birmingham-Leicester creates vulnerability exposure for national biologics resilience. Distribution runs through Heathrow pharmaceutical hubs linking international vaccine flows to NHS hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical logistics margin expansion rests on automation-driven cost compression in warehouse operations and premium-tier pricing capture for gene therapy handling. NHS trust procurement consolidation rewards operators with GDP certification depth and real-time tracking capabilities.
For Market Incumbents: Hedge against qualified person shortages by embedding automated batch release documentation and cross-training pharmacy technicians for GDP oversight. Invest in IoT temperature logger integration to differentiate from competitors lacking real-time chain-of-custody capabilities. Defensive positioning requires Midlands capacity expansion to reduce single-region exposure for national distribution contracts. For New Entrants and Emerging Players: Begin with Scottish biotech corridor cold storage development where GDP-certified capacity scarcity creates white-space opportunity. Target cell therapy manufacturers in Glasgow-Edinburgh cluster requiring proximate minus eighty degrees Celsius handling. Go-to-market positioning should emphasize flexible packaging with embedded cloud documentation for clinical trial logistics. For Investors and Strategic Acquirers: Roll-up economics work for regional cold chain specialists because NHS procurement centralization favors scaled operators with multi-node GDP certification. Five-to-ten year viability hinges on regulatory divergence adaptation capacity. Acquisition targets should demonstrate Heathrow corridor access or Scottish biotech proximity. Watch MHRA guidance evolution on EU qualified person recognition as inflection indicator for parallel inventory positioning requirements.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | MHRA enforcement tightening creates compliance barrier consolidating market share around certified operators. |
| Real-Time Tracking Integration | IoT logger deployment with blockchain documentation differentiates service tier for gene therapy shipments. |
| Heathrow Hub Expansion | Air freight corridor concentration anchors international vaccine distribution flows through UK gateway. |
| Scottish Cold Storage Development | Glasgow-Edinburgh biotech cluster lacks proximate GDP-certified capacity creating greenfield opportunity. |
| Automated Batch Release Systems | Qualified person shortage mitigation through pharmacy technician cross-training reduces labor constraint exposure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture pharmaceutical logistics dynamics. Primary engagement with cold chain operations directors, NHS trust procurement managers, MHRA regulatory affairs leads, and biotech supply chain heads informed operational constraints. Secondary validation drew from MHRA inspection reports, NHS procurement framework disclosures, ClinicalTrials.gov logistics protocols, and Heathrow cargo throughput statistics. Bottom-up service provider capacity modeling and top-down NHS pharmaceutical expenditure analysis enabled triangulation.
Historical reference periods anchored volume and value projections across the analysis window. Segmentation modeling incorporated service type, end user procurement authority, delivery mode speed requirements, and packaging validation complexity dimensions. CAGRs derived from regression analysis against NHS biologics procurement expansion and cell therapy manufacturing growth trajectories. Forecast inputs included MHRA GDP enforcement intensity and post-Brexit regulatory divergence scenarios.
Caveats apply where dry ice supply volatility, qualified person certification bottlenecks, or MHRA guidance evolution on EU site recognition could materially shift the outlook. Deviation in NHS procurement centralization pace or Heathrow air freight capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
IVD Contract Manufacturing Services Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Vaccine Logistics Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Blood Bank Market
Healthcare Services
US Value-Based Healthcare Service Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Global Medical Affairs Outsourcing Market
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
United States Senior Living Market
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
US Care Services Market
Healthcare Services
US Retail Clinics Market
Healthcare Services
Funeral and Cremation Services Market