
 Pharmaceutical Contract Sales Organizations Market | 2026-2036
Pharmaceutical Contract Sales Organizations Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Contract Sales Organizations Market Intelligence
Market Context
The capital-intensity divergence between full-service CSOs and boutique specialists is unwinding as mid-tier players invest in digital infrastructure to match enterprise-scale capabilities. IQVIA leverages its real-world evidence platforms to anchor integrated commercialization contracts across oncology and rare disease portfolios. EVERSANA differentiates through its patient-services overlay, while Syneos Health competes by controlling clinical-to-commercial continuity with embedded medical affairs teams.
Technical Definition and Segment Structure
Pharmaceutical Contract Sales Organizations are outsourced commercial entities that deploy trained sales representatives, medical science liaisons, and digital engagement specialists to promote prescription and non-prescription therapies to healthcare providers, with field teams typically carrying portfolios of 3-8 products segmented by therapeutic area and physician prescribing volume. The service type dimension shows integrated services capturing margin pools as clients consolidate vendors, while telemarketing faces compression from digital-native HCP engagement platforms. Engagement models reveal performance-based contracts gaining share against fee-for-service structures as pharmaceutical companies demand outcome-linked compensation tied to prescription volume or market access milestones.
Regulatory Environment and Outlook
FDA oversight of promotional materials through the Office of Prescription Drug Promotion shapes CSO training protocols and content approval workflows, while HIPAA constraints on physician data usage limit targeting precision for field sales deployment. The EU AI Act and GDPR impose additional compliance layers on European CSO operations deploying algorithmic HCP segmentation. Stakeholders must monitor how FDA guidance on artificial intelligence in drug promotion reshapes representative training investments and vendor qualification criteria.
Market Dynamics
Biotech pipeline maturation is compressing commercialization timelines, forcing CSOs to pre-build specialized sales infrastructure before FDA approval rather than scaling reactively post-launch.
Growth Catalysts
- Specialty launch density:Oncology and rare disease portfolios require physician access capabilities that in-house teams cannot build economically. Outsourced deployment accelerates time-to-first-prescription.
- IRA price negotiation timelines:US pharmaceutical manufacturers face compressed revenue windows for selected drugs, intensifying pressure to maximize launch-year market penetration through flexible CSO partnerships.
- Real-world evidence integration:IQVIA's data assets and similar platforms enable outcome-linked contracting structures that align CSO compensation with actual prescription velocity rather than activity metrics.
Market Restraints
- Representative compensation inflation:Experienced oncology and rare disease sales talent commands premium wages that compress CSO margins, particularly in the United States where specialized expertise concentrates.
- Data access fragmentation:HIPAA constraints and state-level privacy laws restrict physician targeting precision, degrading field deployment efficiency versus European markets with more permissive HCP data frameworks.
- Digital-native platform substitution:Veeva Systems' engagement platforms and similar tools enable direct-to-physician digital detailing that bypasses traditional representative-led models for certain therapeutic categories.
Strategic Opportunities
- EU AI Act compliance services:Algorithmic HCP segmentation faces new regulatory layers across European operations, creating demand for CSOs with embedded compliance infrastructure and trained data governance personnel.
- Patient services integration:EVERSANA's overlay model demonstrates white space for CSOs that bundle hub services, prior authorization support, and adherence programs with core sales deployment.
- Japan's specialty pharma expansion:PMDA's accelerated approval pathways for regenerative medicines and gene therapies are generating demand for localized medical affairs and commercial capabilities that global manufacturers lack in-house.
Industry Challenges
- Medical science liaison scarcity:The convergence of clinical and commercial functions requires MSLs with doctoral credentials who can engage academic medical centers; recruitment pipelines for this hybrid profile remain underdeveloped.
- Multi-vendor integration complexity:Pharmaceutical clients increasingly unbundle services across specialized providers, forcing CSOs to interoperate with separate data analytics, patient services, and digital engagement vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Contract Sales Organizations Market |
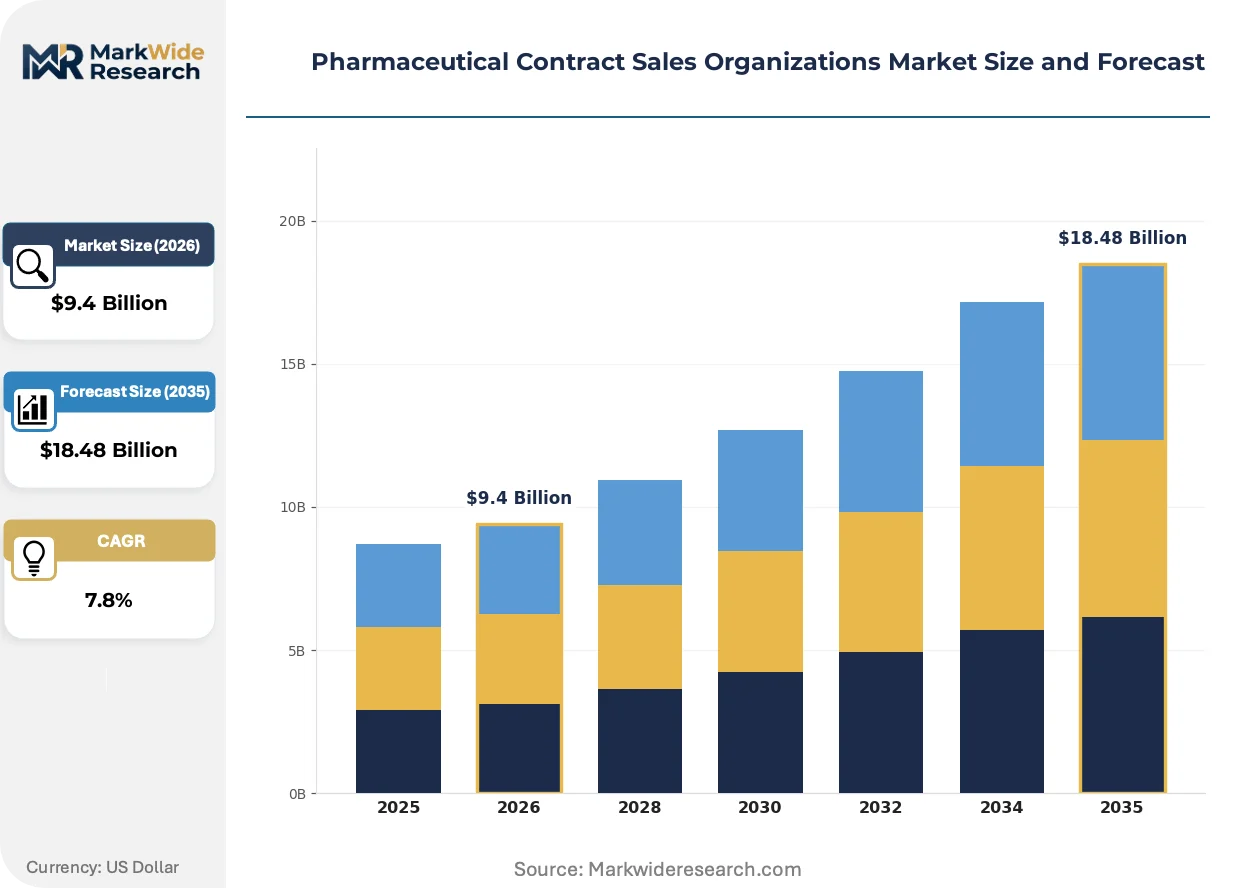
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $18.48 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Field Sales, Telemarketing, Medical Liaison, Integrated Services End User: Pharmaceutical Companies, Biotech Firms, Generic Manufacturers, Specialty Pharmacies Product Type: Branded Drugs, Generic Drugs, OTC Products, Specialty Medications Engagement Model: Fee-for-Service, Performance-Based, Hybrid, Exclusivity Agreements |
| Companies Covered | Axxelus, ICON Plc, IQVIA, EVERSANA, Ashfield Medcomms, Syneos Health, EPS Corporation, Amplity Health, CMIC HOLDINGS Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Contract Sales Organizations Market Strategic Shifts & Innovations
Artificial intelligence is restructuring how CSOs train representatives, target physicians, and measure engagement effectiveness, compressing the gap between data insight and field execution.
AI-powered conversation intelligence is supplanting traditional ride-along coaching and post-call self-reporting in representative development. Syneos Health and similar organizations deploy natural language processing to analyze recorded HCP interactions, identify effective messaging patterns, and personalize training curricula at scale. This capability is compressing new representative time-to-productivity from months to weeks while reducing field manager overhead.
REACH and RoHS compliance requirements in Europe are extending into CSO operational infrastructure as pharmaceutical clients demand environmental accountability across their outsourced supply chains. Contract terms increasingly specify sustainable fleet management, paperless detailing systems, and carbon-neutral event execution. German and French operations face the tightest constraints, with sustainability scoring now weighted in vendor selection criteria alongside traditional capability metrics.
Pharmaceutical procurement departments are consolidating vendor rosters from multi-CSO arrangements toward single integrated partners with clinical-to-commercial continuity. This behavior concentrates contract value with full-service providers while marginalizing boutique telemarketing specialists. The United States exhibits the most pronounced consolidation, where specialty launch complexity rewards vendors controlling embedded medical affairs, regulatory strategy, and patient services alongside core sales deployment.
Pharmaceutical Contract Sales Organizations Market Segmentation
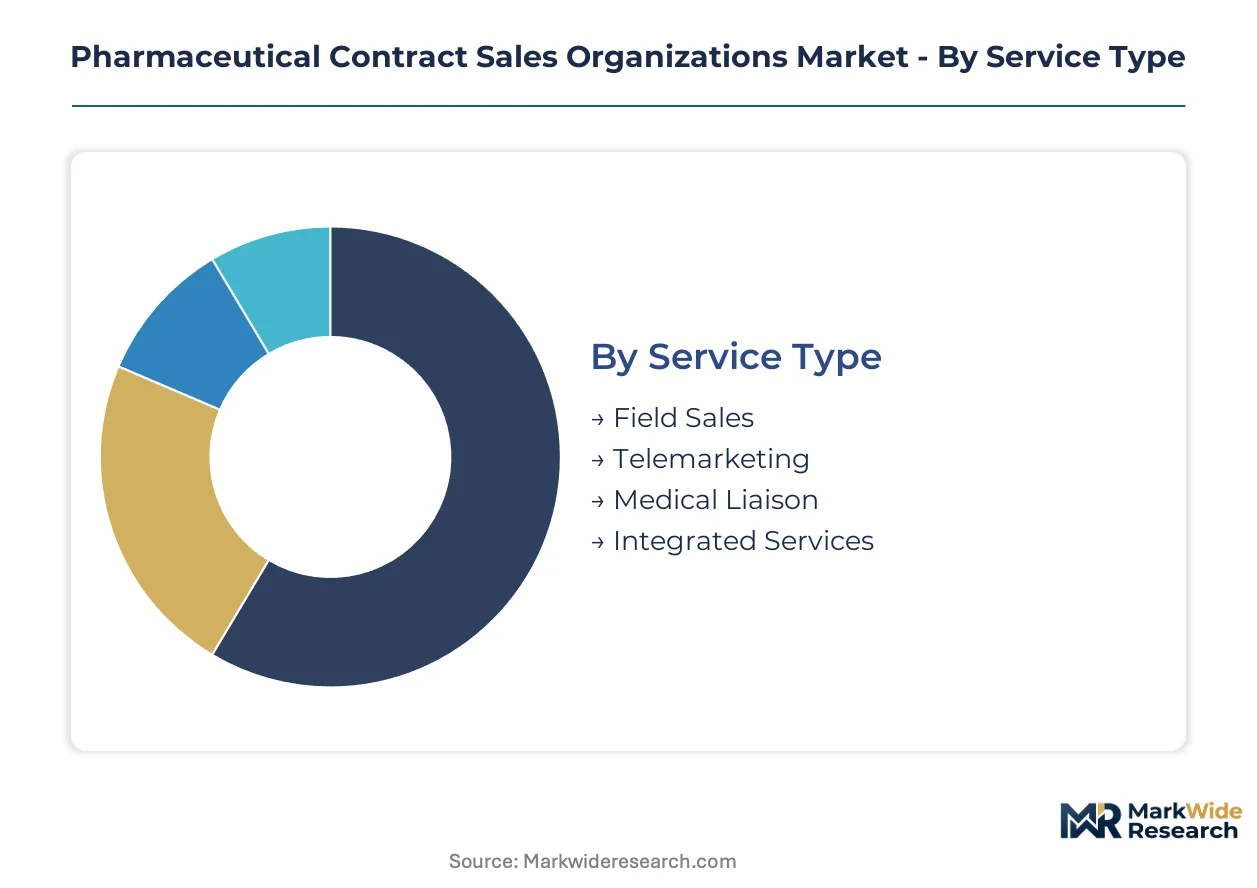
CSO segmentation reveals how vendor capabilities align with client commercialization strategies. Service configurations and engagement structures determine which organizations can capture specialty launch contracts versus commodity detailing work.
Service Type:
Domestic US operations concentrate field sales and medical liaison deployment, while telemarketing and integrated services increasingly serve export-led biotech clients launching across multiple markets.
- Field Sales:Representative teams conduct in-person physician detailing across hospitals, clinics, and academic medical centers. Demand clusters in the United States for oncology and rare disease launches where specialized access to high-volume prescribers commands premium pricing.
- Integrated Services:Bundled offerings combine sales deployment with medical affairs, patient services, and real-world evidence capabilities. Biotech firms expanding from US bases into European and Japanese markets favor these arrangements for clinical-to-commercial continuity.
- Telemarketing:Remote detailing via phone and video platforms targets primary care physicians and established therapeutic categories.
- Medical Liaison:Doctoral-credentialed MSLs engage academic investigators and key opinion leaders in scientific exchange.
Integrated services holds the largest share; momentum sits with medical liaison as clinical-commercial convergence accelerates.
End User:
Cost tier separation distinguishes enterprise pharmaceutical manufacturers with full outsourcing budgets from emerging biotech firms purchasing modular capabilities.
- Pharmaceutical Companies:Large manufacturers deploy CSOs for portfolio optimization, geographic expansion, and therapeutic area entry where in-house infrastructure proves uneconomical. US-based organizations dominate this segment with consolidated vendor rosters.
- Biotech Firms:Pipeline-stage companies lacking commercial infrastructure represent the steepest expansion trajectory as FDA approvals for cell therapies and gene treatments multiply.
- Generic Manufacturers:Price-competitive players utilize CSOs for volume-driven primary care detailing.
- Specialty Pharmacies:Hub service providers and limited distribution networks require coordinated patient access support.
Pharmaceutical companies retain the dominant position; biotech firms are climbing the fastest as capital flows into pre-commercial assets.
Product Type:
Application complexity separates high-touch specialty medications requiring MSL engagement from standardized generic and OTC portfolios.
- Specialty Medications:Oncology, rare disease, and cell therapy products demand sophisticated physician access, reimbursement navigation, and patient support services. US academic medical centers and European reference hospitals concentrate demand for these high-value launches.
- Branded Drugs:Established prescription therapies in competitive categories require differentiated messaging and formulary access capabilities.
- Generic Drugs:Commoditized portfolios prioritize cost-efficient coverage and volume-based deployment.
- OTC Products:Consumer-facing health products utilize CSOs for pharmacy channel management and retail education.
Specialty medications command premium engagement terms; generic drugs face margin compression from digital substitution.
Engagement Model:
Customer risk tolerance separates conservative fee-for-service arrangements from outcome-linked partnerships.
- Performance-Based:Contracts tie CSO compensation to prescription volume, market access milestones, or revenue targets. US pharmaceutical procurement departments favor these structures for specialty launches with measurable launch-year metrics.
- Fee-for-Service:Fixed pricing for defined activities retains popularity among generic manufacturers and established therapeutic categories with predictable deployment patterns.
- Hybrid:Blended structures combine guaranteed minimums with upside participation based on outcomes.
- Exclusivity Agreements:Dedicated CSO teams serve single clients with embedded operational integration.
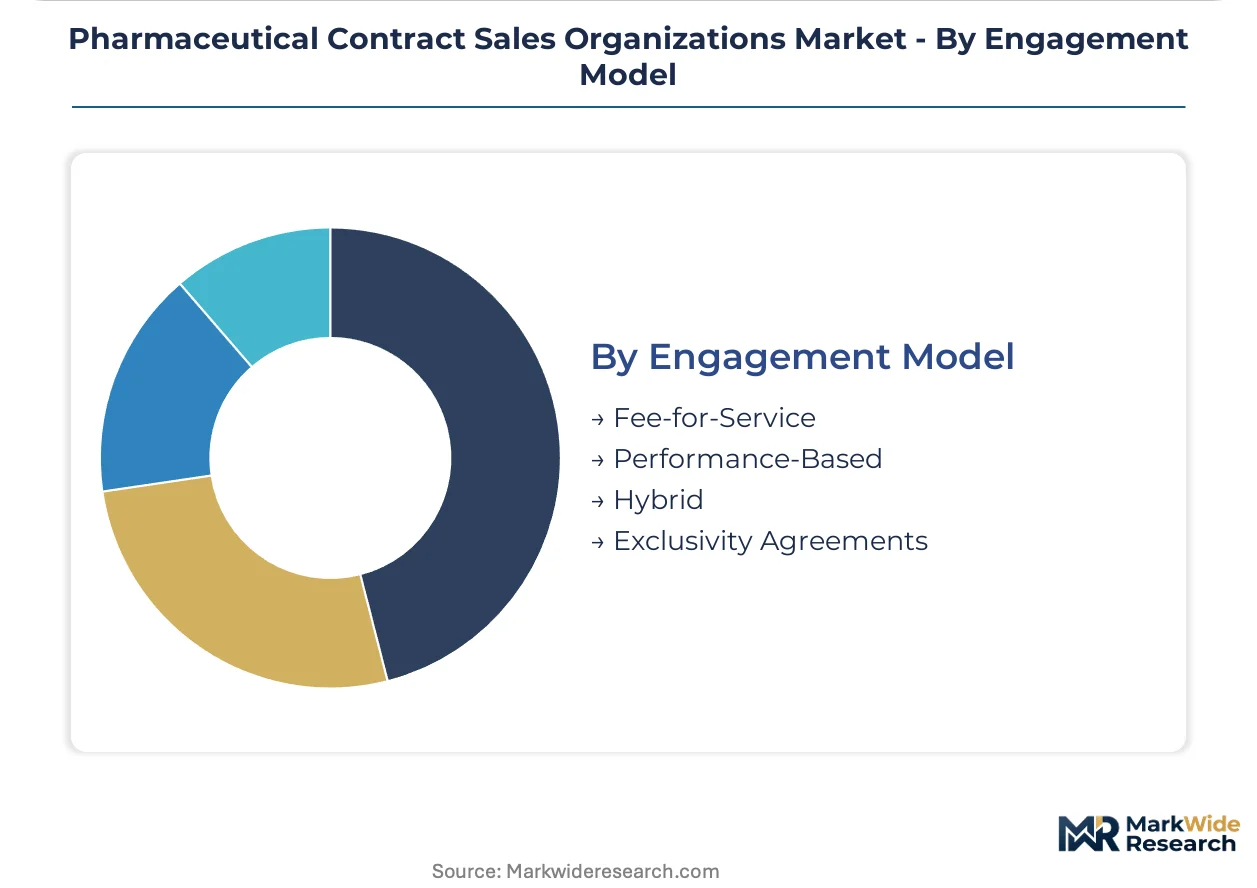
Performance-based contracting gains share fastest; fee-for-service retains volume leadership in commoditized segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds European benchmarks by substantial margins, while Japanese CSO contracts command premiums for localized medical affairs capabilities that global vendors struggle to replicate.
United States
Specialty medication launches in oncology and rare disease drive CSO deployment density, with academic medical centers in Boston, New York, and San Francisco requiring embedded MSL teams. The FDA's Office of Prescription Drug Promotion mandates rigorous representative training protocols that inflate operational costs. The Research Triangle Park corridor in North Carolina concentrates contract research and commercialization infrastructure where IQVIA and Syneos Health anchor integrated service delivery.
Germany
REACH and RoHS compliance requirements extend into CSO operational contracts, with pharmaceutical procurement departments weighting sustainability scoring alongside capability metrics. The EU AI Act imposes algorithmic governance layers on HCP segmentation tools that vendors must embed. The Rhine-Ruhr metropolitan region hosts dense pharmaceutical manufacturing that generates parallel demand for medical liaison and field sales deployment.
Japan
PMDA accelerated approval pathways for regenerative medicines and gene therapies compress commercialization timelines, forcing pre-built sales infrastructure before regulatory clearance. METI industrial policy supports domestic biotech scale-up that outpaces in-house commercial capabilities. The Kanto region around Tokyo concentrates both pharmaceutical headquarters and specialized CSO operations serving global manufacturers lacking localized expertise.
United Kingdom
NHS formulary access complexity demands CSOs with integrated market access capabilities that bridge pricing negotiation and physician engagement. The MHRA post-Brexit regulatory autonomy creates divergence from EU promotional guidelines that vendors must navigate. The London-Oxford-Cambridge golden triangle anchors biotech pipeline activity that feeds contract commercialization demand.
India
CDSCO regulatory harmonization with ICH standards elevates clinical trial activity that precedes commercialization outsourcing. The PLI scheme for pharmaceuticals incentivizes domestic manufacturing scale that will eventually require aligned sales infrastructure. Hyderabad and Bangalore clusters concentrate both API production and emerging biotech development that drives CSO market entry.
Pharmaceutical Contract Sales Organizations Market Key Industry Players
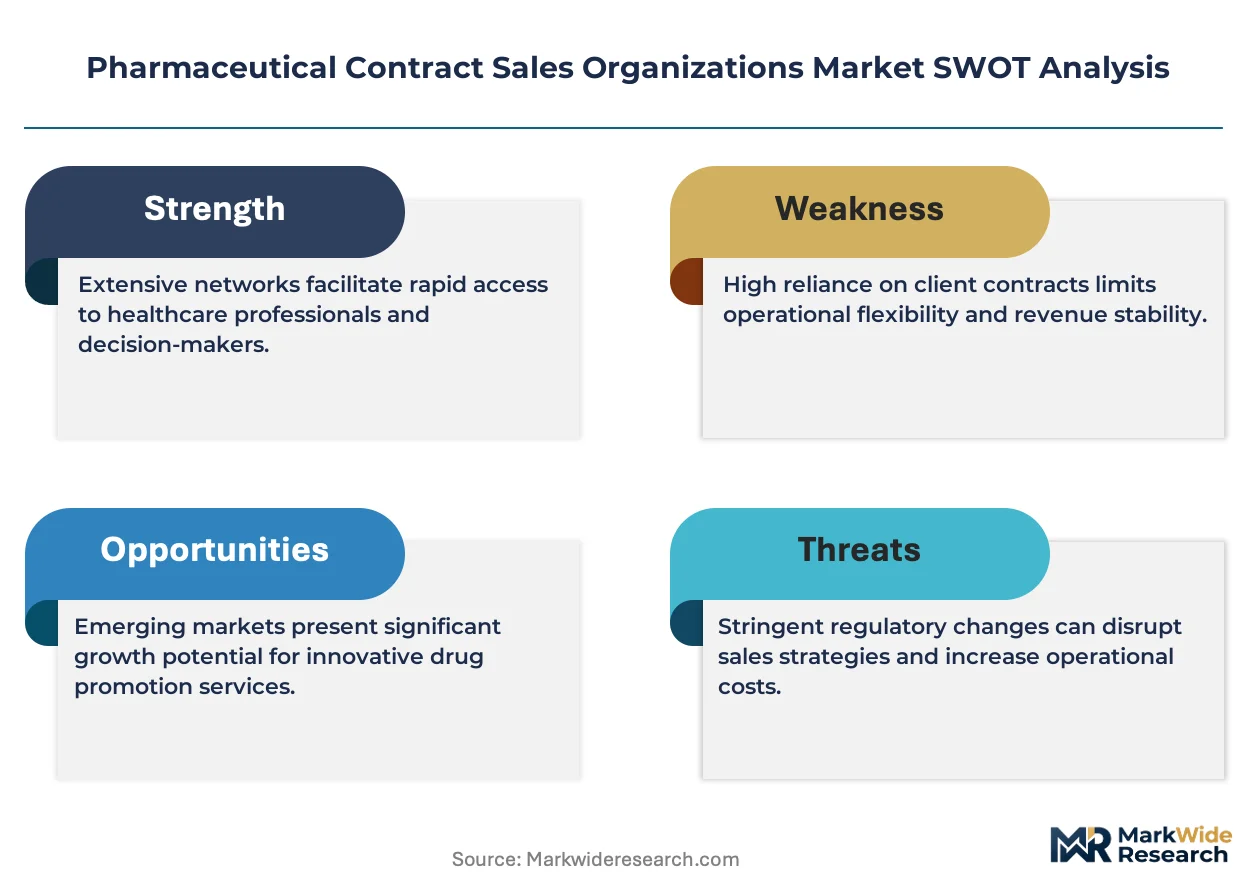
Technology leadership and cost leadership are held by different player archetypes, with integrated data-analytics platforms commanding premium positioning against modular telemarketing specialists. The vendor base concentrates around full-service providers capable of clinical-to-commercial continuity, while boutique telemarketing operations face margin compression from digital-native substitutes. Three archetypes dominate: data-anchored integrators, patient-services bundlers, and embedded medical affairs specialists. Consolidation pressure intensifies as pharmaceutical procurement departments narrow vendor rosters, and performance-based contracting structures favor scale players with balance sheet capacity to absorb outcome risk.
Within the data-anchored integrator tier, IQVIA exemplifies real-world evidence platform leverage that anchors outcome-linked contracts, while Syneos Health occupies a position emphasizing clinical-to-commercial embedded teams. EVERSANA represents the patient-services bundling archetype through hub and adherence program integration. Among Asia-Pacific specialists, CMIC HOLDINGS Co., Ltd. anchors localized Japanese commercialization capabilities that global vendors struggle to replicate.
| Leading Market Players |
|---|
| Axxelus |
| ICON Plc |
| IQVIA |
| EVERSANA |
| Ashfield Medcomms |
| Syneos Health |
| EPS Corporation |
| Amplity Health |
| CMIC HOLDINGS Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Scale economies in integrated service delivery concentrate pricing power among full-service CSOs with embedded medical affairs and patient services capabilities, compressing margins for modular telemarketing specialists while elevating price floors for specialty launch deployment. Field infrastructure utilization rates across the United States and Japanese markets directly determine per-representative cost structures, with pre-built oncology and rare disease teams commanding substantial premiums over reactive scaling models.
Pricing Analysis
The customization-premium spread separates configured-to-order integrated service contracts from standardized field sales arrangements, with three-tier pricing structure across premium, standard, and economy levels reflecting therapeutic complexity and MSL embedding. Price differentiation hinges on therapeutic area certification depth and geographic coverage density, with oncology-specialized teams in the United States extracting maximum premiums. Cost compression in telemarketing tiers is intensifying because Veeva Systems' digital engagement platforms enable direct-to-physician detailing that bypasses traditional representative models. Generic manufacturers exhibit highest price sensitivity, while biotech firms launching cell therapies demonstrate lowest sensitivity due to compressed commercialization timelines.
Supply Chain Analysis
The United States anchors representative talent pools and medical liaison credentialing infrastructure, while Japan and Germany concentrate localized regulatory compliance capabilities that global vendors struggle to replicate. Human capital inputs draw from doctoral-credentialed MSL pipelines, specialized oncology sales veterans, and digital engagement technologists, with training content sourcing from FDA Office of Prescription Drug Promotion guidelines and EU AI Act compliance frameworks. Single-source vulnerability concentrates in experienced rare disease sales talent, where recruitment pipelines remain underdeveloped relative to demand acceleration. Distribution runs through pharmaceutical procurement departments consolidating vendor rosters toward integrated partners with clinical-to-commercial continuity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CSO incumbents face substitution defense against digital-native HCP engagement platforms that displace traditional representative-led detailing for established therapeutic categories, requiring capability evolution to justify premium positioning.
For Market Incumbents: Secure MSL talent pipelines through academic medical center partnerships and embedded fellowship programs before competitor recruitment intensifies. Secure patient services integration capabilities through hub service acquisitions or exclusive prior authorization technology licensing, as EVERSANA's overlay model demonstrates defensible bundling that pure-play sales vendors cannot replicate. Vertical integration into real-world evidence platforms mirrors IQVIA's data-anchored positioning that anchors outcome-linked contracts.
For New Entrants and Emerging Players: Algorithmic HCP segmentation compliance services represent the most penetrable white space, as EU AI Act implementation creates immediate demand for trained data governance personnel that established CSOs lack. Japan's regenerative medicine commercialization gap offers geographic entry with PMDA accelerated approval pathways generating demand for localized medical affairs capabilities. A go-to-market angle emphasizing pre-built sales infrastructure before FDA approval compresses time-to-first-prescription for biotech clients facing IRA price negotiation timelines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among data-anchored integrators with real-world evidence platform lock-in that enables outcome-linked contracting structures. Long-term viability over the coming decade favors full-service providers with clinical-to-commercial continuity as pharmaceutical procurement departments narrow vendor rosters. Acquisition targets should demonstrate embedded medical affairs, patient services overlay, or Japanese localization capabilities. The signal to watch is FDA guidance on artificial intelligence in drug promotion, which would reshape representative training investments and vendor qualification criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Patient Services Integration | Bundling hub services with core sales deployment mirrors EVERSANA's defensible market position. |
| EU AI Act Compliance Infrastructure | Embedded algorithmic governance capabilities capture regulatory-driven demand from European biotech launches. |
| Japanese Localization Investment | PMDA accelerated approval pathways for gene therapies generate premium commercialization contracts. |
| Real-World Evidence Platform Development | Data assets anchor outcome-linked contracts that align CSO compensation with prescription velocity. |
| MSL Talent Pipeline Securement | Doctoral-credentialed medical science liaison scarcity constrains specialty launch capacity expansion. |
Research Approach
Cross-validation between primary interviews with commercial operations executives, regulatory affairs leads, formulary directors, and payer access specialists anchors the qualitative findings against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up triangulation aggregates individual contract values and deployment metrics, while top-down verification cross-checks aggregate market sizing against pharmaceutical R&D expenditure patterns and commercialization outsourcing ratios.
Sensitivity analysis across therapeutic area concentration, regulatory approval velocity, and digital substitution rates shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include service type configuration, engagement model structure, end-user scale tier, product complexity classification, and regional regulatory cluster. CAGRs were derived from regression analysis of historical outsourcing penetration against biotech pipeline maturation timelines, with inputs including IRA price negotiation implementation pace and FDA digital promotional guidance evolution.
Forecasts assume regulatory continuity in FDA promotional oversight, EU AI Act algorithmic governance, and PMDA accelerated approval frameworks; material policy shifts would require re-modeling. Specific risk factors that could revise projections include HIPAA constraint relaxation altering physician targeting precision, digital-native platform substitution acceleration, and MSL talent pipeline expansion that alleviates specialty launch capacity bottlenecks. Recalibration cycles align with material shifts in biotech FDA approval velocity, pharmaceutical procurement consolidation patterns, and regulatory guidance on artificial intelligence deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Global Sperm Bank Market
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
Retail Clinics Market
Healthcare Services
Private Healthcare Market
Healthcare Services
Global Urgent Care Center Market
Healthcare Services
Global Infusion Pharmacy Management Market
Healthcare Services
Medical Spa Market
Healthcare Services
Long Term Care Market
Healthcare Services
Medical Recruitment Market
Healthcare Services
Immunoassay CDMO Market
Healthcare Services
Regulatory Affairs Outsourcing Market
Healthcare Services
Tissue Banking Market